
 E-Bike Lithium-Ion Battery Market | 2026-2036
E-Bike Lithium-Ion Battery Market Size, Share, and Industry Trends Forecast 2026-2036
E-Bike Lithium-Ion Battery Market Insights
China's cell manufacturing base is tilting toward dedicated e-bike lines as European assemblers seek supply security. Samsung SDI leverages its cylindrical cell expertise to dominate premium e-bike OEM contracts. LG Energy Solution anchors its position through direct partnerships with major European frame manufacturers. Panasonic Corporation specializes in nickel-cobalt-aluminum cathode formulations for extended cycle life in fleet applications.
E-bike lithium-ion batteries store electrochemical energy in layered oxide cathodes paired with graphite anodes, delivering nominal voltages between 36V and 48V for pedal-assist propulsion. The cells undergo formation cycling, electrolyte filling, and aging protocols before module assembly to ensure thermal stability under vibration loads. Cylindrical formats currently occupy the highest volume tier due to mature automation and consistent quality, while pouch architectures are gaining traction in frame-integrated designs where packaging flexibility commands premium positioning. Delivery services represent the fastest-growing end-user channel as logistics operators replace combustion vans with cargo e-bikes for urban zones.
China's SAMR enforces GB/T standards for cell safety and transportation testing that determine market access for both domestic producers and importers. The EU's F-Gas Regulation and CE marking requirements under the Machinery Directive shape battery management system specifications and thermal runaway containment protocols for European market entry. Stakeholders must monitor evolving recycling mandates under the EU Battery Regulation and China's dual carbon goals, as compliance investments will separate qualified suppliers from margin-pressured competitors.
Market Dynamics
Urban logistics operators are forcing capacity upgrades across cell chemistries as last-mile delivery fleets abandon combustion vans for cargo e-bikes, compressing development cycles and straining certification bandwidth.
Growth Catalysts
- GB/T safety standards:China's SAMR enforcement of stricter cell testing protocols is filtering out marginal suppliers and consolidating procurement toward certified pack assemblers with verified thermal runaway containment.
- Stuttgart-Munich manufacturing corridor:Germany's bicycle production clusters are anchoring European demand for frame-integrated battery architectures with localized module assembly requirements.
- Nickel-cobalt-aluminum cathodes:Extended cycle life formulations are displacing standard NMC blends in fleet applications where daily deep cycling exceeds residential usage intensity.
Market Restraints
- Lithium carbonate volatility:Raw material price swings are compressing pack margins and forcing OEMs into long-term offtake contracts with Chinese refiners.
- Cylindrical cell supply concentration:Automated production lines for 18650 and 21700 formats cluster in East Asian manufacturing hubs, creating single-source vulnerability for European assemblers.
- EU Battery Regulation recycling mandates:Compliance investments in end-of-life collection infrastructure are raising effective production costs for smaller pack producers without scale economics.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:Domestic manufacturing incentives are opening import-substitution pathways for e-bike pack producers targeting South Asian micromobility markets.
- Solid-state electrolyte convergence:Sulfide-based ceramic separators paired with silicon anodes promise energy density breakthroughs for premium cargo platforms.
- Direct-to-fleet channel expansion:Bypassing traditional bicycle OEMs to supply integrated powertrain solutions to logistics operators is capturing margin previously allocated to frame manufacturers.
Industry Challenges
- Battery management system firmware certification:CE marking under the EU Machinery Directive requires extensive electromagnetic compatibility testing that extends product launch timelines.
- Thermal propagation engineering talent:Cell-to-pack design expertise for preventing cascade failure remains concentrated among a limited pool of specialists with automotive EV experience.
- Legacy fleet retrofit compatibility:Swappable pack standards vary across early-generation cargo bike platforms, complicating aftermarket service strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Bike Lithium-Ion Battery Market |
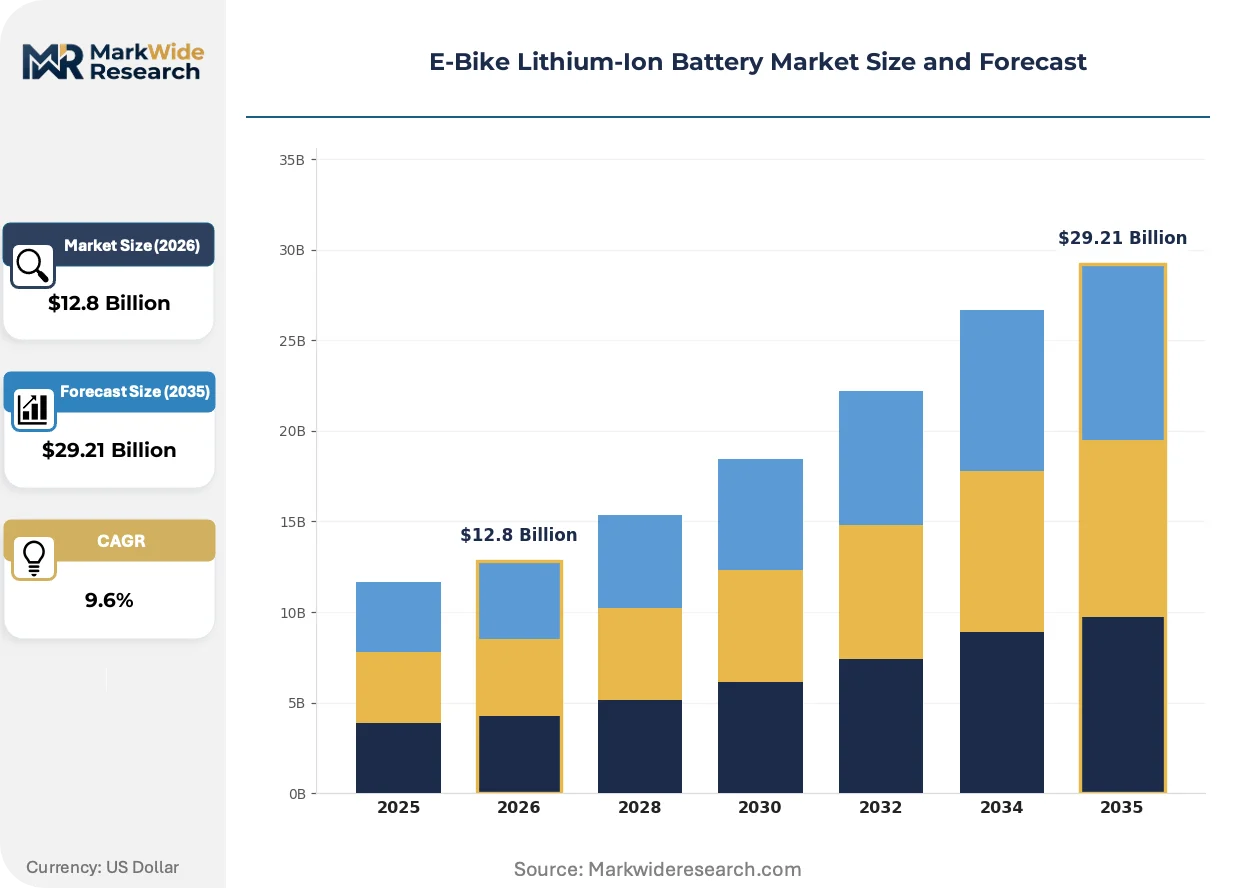
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $29.21 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Cylindrical, Prismatic, Pouch, Custom End User: Personal Use, Delivery Services, Rental Services, Fleet Operators Capacity: 250Wh, 500Wh, 750Wh, 1000Wh Integration Level: Modular, Built-in, Removable, Hybrid |
| Companies Covered | Samsung SDI, LG Energy Solution, Panasonic Corporation, BYD, BMZ Group, A123 Systems, EVE Energy, CATL, Amperex Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Bike Lithium-Ion Battery Market Trends and Innovations
Intelligent battery management systems are digitizing every layer of pack performance monitoring, from cell-level voltage telemetry to predictive degradation modeling, compressing the gap between hardware and software value capture.
Smart BMS platforms with cloud-connected state-of-health algorithms are digitizing fleet operator oversight of distributed e-bike assets. Logistics coordinators in Amsterdam and Copenhagen are adopting these systems to optimize swap-station scheduling. The technology is digitizing maintenance workflows previously handled through manual inspection intervals.
The EU F-Gas Regulation is tightening containment requirements for thermal management systems using fluorinated refrigerants. Pack producers must redesign liquid-cooling loops to accommodate alternative heat transfer fluids. Premium cargo e-bike segments in Germany and the Netherlands are absorbing these engineering costs faster than price-sensitive commuter categories.
Subscription-based battery service models are displacing outright pack purchases among commercial fleet operators. Third-party energy-as-a-service providers in Paris and Barcelona are assuming capital burden and degradation risk. Urban delivery cooperatives are the earliest adoptees, trading ownership complexity for predictable per-kilometer operating costs.
E-Bike Lithium-Ion Battery Market Segmentation
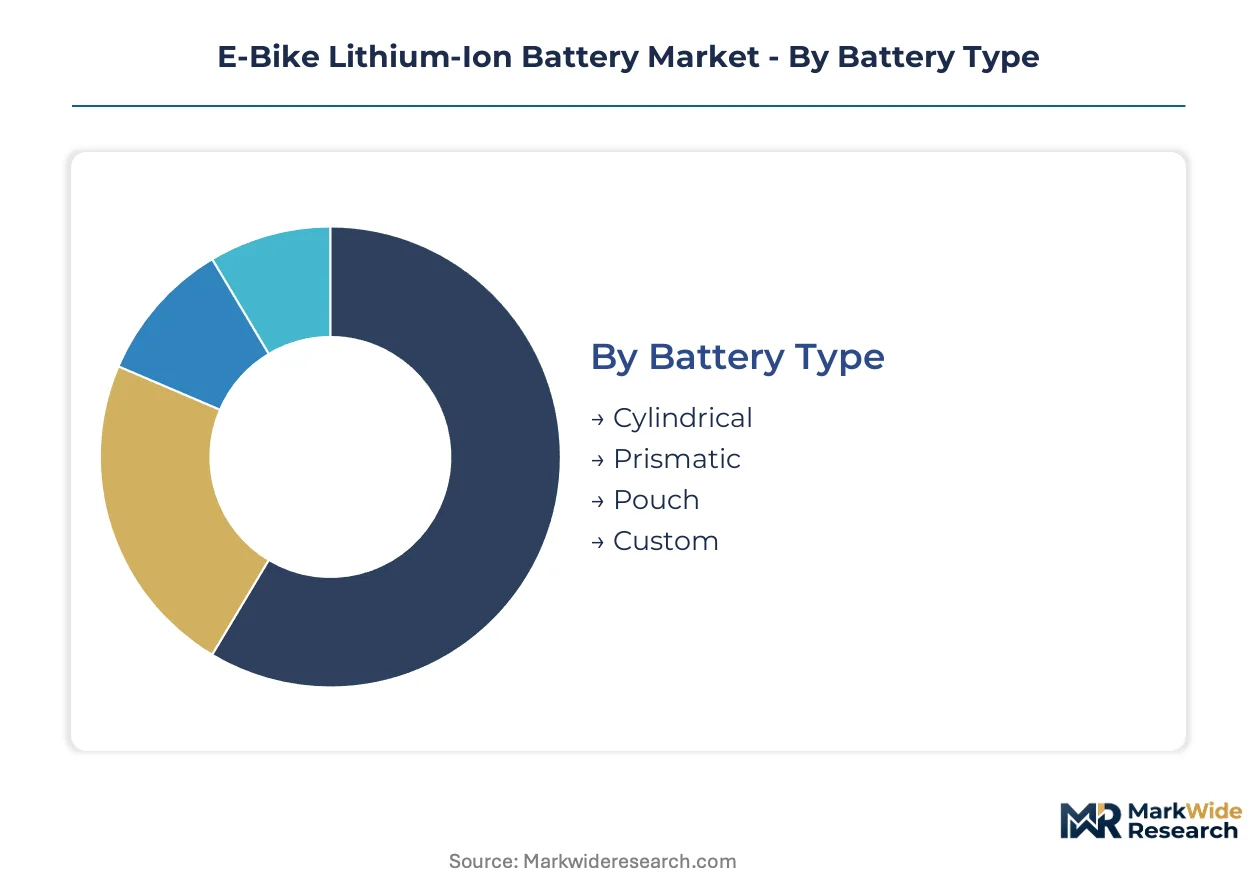
E-bike battery procurement splits across four critical dimensions: cell geometry shapes manufacturing economics, end-use intensity dictates cycle life requirements, energy density determines range architecture, and integration design frames serviceability models. Each axis carries distinct margin profiles and certification burdens.
Battery Type:
Cell geometry spans from mature cylindrical automation to emerging pouch flexibility, with each format commanding different tooling investments and thermal management approaches.
- Cylindrical:18650 and 21700 formats leverage decades of automotive-scale automation, delivering consistent quality at high throughput. Demand concentrates in Germany's frame-integrated commuter segment where suppliers prioritize proven supply chains over packaging innovation.
- Pouch:Aluminum-laminated flat cells enable frame-integrated architectures with minimal dead volume. Amsterdam's cargo bike assemblers are specifying pouch formats for their ability to conform to irregular downtube geometries, though thermal runaway containment requires more complex engineering.
- Prismatic:Hard-cased rectangular cells offer intermediate density and structural rigidity. Chinese pack producers favor prismatic formats for domestic fleet contracts where serviceability outweighs weight minimization.
- Custom:Bespoke cell arrangements address niche applications including recumbent trikes and adaptive cycles. Low volume constrains automation economics.
Established volume favors cylindrical; emerging adoption favors pouch.
End User:
Usage intensity creates a spectrum from occasional residential charging to continuous commercial cycling, with warranty terms and cycle life specifications diverging accordingly.
- Delivery Services:Urban logistics operators deploy cargo e-bikes for 12-16 hour daily duty cycles. Paris-based last-mile fleets are driving demand for 1000Wh+ packs with rapid-swap compatibility.
- Personal Use:Commuter and recreational riders typically charge overnight with moderate weekly mileage. Stuttgart's bicycle OEMs specify 500Wh as the standard configuration for this segment.
- Fleet Operators:Corporate and municipal pooled vehicle programs require centralized asset management. Copenhagen's municipal bike share contracts mandate cloud-connected BMS for remote diagnostics.
- Rental Services:Tourism and short-term hire operators prioritize vandal resistance and standardized charging interfaces. Barcelona's beachfront rental networks specify IP67-rated enclosures.
Delivery services are expanding most quickly; personal use retains the largest installed base.
Capacity:
Energy storage tiers align with range anxiety thresholds and regulatory classifications across European type-approval frameworks.
- 500Wh:The reference specification for EU-compliant pedelecs balances weight and range. Munich's premium commuter OEMs treat this as their volume anchor.
- 750Wh:Extended-range configurations address hilly terrain and cargo loads. E-cargo bike producers in the Netherlands specify this tier for suburban delivery routes.
- 250Wh:Minimalist packs serve lightweight urban folders and regulatory-limited speed pedelec categories. Asian micromobility markets favor this entry point.
- 1000Wh:High-capacity architectures enable all-day commercial operation without mid-route charging. German logistics operators are piloting this tier for inter-city courier services.
500Wh dominates unit economics; 1000Wh shows the steepest expansion trajectory.
Integration Level:
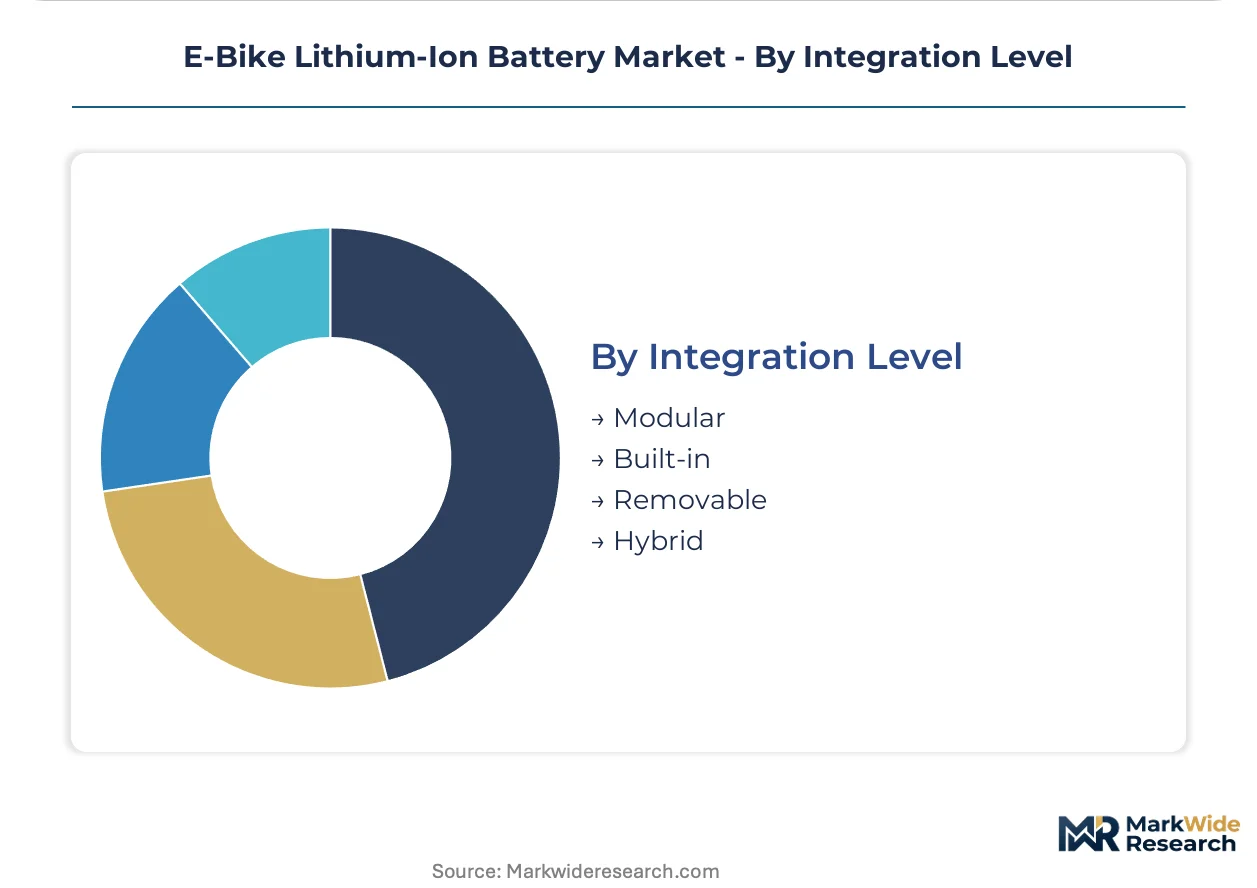
Pack accessibility determines service model economics and frame design constraints, with tradeoffs between theft resistance and field replaceability.
- Removable:Key-locked battery docking enables indoor charging and theft deterrence. Residential users across European cities mandate this flexibility.
- Built-in:Permanent frame integration minimizes connector wear and aesthetic disruption. Premium road e-bike producers favor this approach.
- Modular:Standardized cell modules permit capacity scaling and field servicing. Fleet operators in Barcelona specify modular architectures to minimize downtime.
- Hybrid:Semi-integrated designs balance service access with structural packaging. Emerging formats for step-through urban frames.
Removable configurations command the highest unit volumes; built-in designs capture premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Antwerp port complex channels cylindrical cell imports into European assembly plants, while China's Yangtze River Delta manufacturing belt feeds domestic e-bike production and export demand.
China
Domestic e-bike fleets in Hangzhou and Chengdu exceed twenty million units, creating massive replacement battery demand. SAMR's GB/T 36972 safety standards mandate nail penetration and overcharge testing for all market entrants. Shenzhen's Bao'an district hosts concentrated pack assembly operations serving both domestic brands and export OEMs.
Germany
Stuttgart-Munich corridor manufacturers specify frame-integrated pouch cells for premium cargo platforms. KBA type-approval requirements under EU Regulation 168/2013 govern motor power and battery voltage thresholds. Bosch's Reutlingen engineering center anchors development of modular battery architectures for fleet operators.
Netherlands
Amsterdam's delivery cooperatives operate the densest cargo e-bike fleet per capita in Europe, driving rapid-swap infrastructure investment. The F-Gas Regulation restricts fluorinated refrigerants in liquid-cooled battery thermal management systems. Eindhoven's high-tech campus incubates solid-state electrolyte ventures targeting next-generation energy density.
United States
Seattle and San Francisco micromobility programs subsidize e-bike purchases for low-income commuters. NHTSA classifies pedal-assist vehicles under 750W as bicycles, exempting them from automotive safety standards. Brooklyn's last-mile logistics startups are trialing 1000Wh packs for inter-borough courier services.
India
Bengaluru and Delhi-NCR last-mile delivery fleets are converting from two-stroke mopeds to lithium-powered e-bikes. The PLI scheme for advanced chemistry cells offers production-linked incentives to domestic manufacturers. Tamil Nadu's Sriperumbudur industrial zone is attracting pack assembly investments from Korean cell suppliers.
E-Bike Lithium-Ion Battery Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in cell chemistry and thermal management. The vendor base organizes into three tiers: multinational cell producers with automotive-scale automation, regional pack assemblers serving bicycle OEMs, and emerging solid-state technology ventures. Strategic moves concentrate on backward integration into cathode material refining and geographic diversification of cell production to mitigate single-source risk.
Among East Asian cell manufacturers, Samsung SDI and LG Energy Solution exemplify the premium-tier archetype through cylindrical format expertise, while Panasonic Corporation occupies a distinct position in nickel-cobalt-aluminum cathode formulations. These three anchors represent divergent technical specializations within the high-reliability segment.
| Leading Market Players |
|---|
| Samsung SDI |
| LG Energy Solution |
| Panasonic Corporation |
| BYD |
| BMZ Group |
| A123 Systems |
| EVE Energy |
| CATL |
| Amperex Technology |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in China's Yangtze River Delta cell manufacturing belt is compressing pack margins and forcing European assemblers into long-term offtake contracts that lock in volume but sacrifice pricing flexibility. This utilization dynamic feeds directly into how procurement teams negotiate tiered supply agreements across the 36V to 48V nominal voltage spectrum.
Pricing Analysis
The EU Battery Regulation dictates the pricing tier structure across the e-bike battery market, separating premium-certified packs with verified recycling pathways from standard-tier products lacking end-of-life documentation. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by GB/T 36972 certification status and thermal runaway containment engineering depth. Pricing pressure stems from lithium carbonate volatility forcing Chinese refiners to index cell contracts to spot metal markets. Delivery services exhibit the highest price sensitivity due to thin per-route margins, while premium road e-bike OEMs absorb cost premiums for frame-integrated pouch architectures.
Supply Chain Analysis
CATL and BYD hold the dominant contract-manufacturing capacity for prismatic and blade-format cells feeding e-bike pack assembly, with Samsung SDI and LG Energy Solution anchoring cylindrical production for premium European OEMs. Geographic supply concentration centers on China, South Korea, and Japan, with each hub specializing in distinct cathode chemistries and automation formats. Raw material dependencies draw from Indonesian nickel processing, Chilean lithium brine operations, and Chinese graphite anode production. Single-source vulnerability concentrates in East Asian cylindrical cell lines, where 18650 and 21700 automation clusters lack geographic redundancy. Distribution runs through Rotterdam-Antwerp port channels into Stuttgart-Munich assembly corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across fleet-operator battery service models, as logistics coordinators seek alternatives to OEM-captive supply chains that bundle pack procurement with frame purchases.
For Market Incumbents: Harden thermal propagation engineering capabilities through recruitment of automotive EV specialists with cell-to-pack design experience, as cascade failure prevention becomes the decisive certification differentiator under tightening GB/T and CE marking protocols. Deepen backward integration into cathode material refining to offset lithium carbonate volatility and secure margin control over nickel-cobalt-aluminum formulations. For New Entrants and Emerging Players: Build out direct-to-fleet channel infrastructure in Amsterdam and Copenhagen, where delivery cooperatives already pilot subscription-based battery service models that displace outright pack purchases. India's PLI scheme for advanced chemistry cells offers the most penetrable geography, with Tamil Nadu's Sriperumbudur industrial zone attracting Korean cell suppliers seeking import-substitution partnerships. Target municipal bike share contracts mandating cloud-connected BMS for remote diagnostics. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across solid-state electrolyte ventures, as sulfide-based ceramic separator development reaches pilot-scale validation. Long-term viability favors pack assemblers with demonstrated EU Battery Regulation compliance infrastructure and established collection networks for end-of-life cells. The signal to watch is KBA type-approval timeline compression, indicating which engineering centers can accelerate product launch cycles under Machinery Directive electromagnetic compatibility requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Refining | Captures margin from nickel-cobalt-aluminum formulations and insulates against lithium carbonate spot volatility. |
| Direct-to-Fleet Channel Expansion | Bypasses frame OEMs to supply integrated powertrain solutions to Paris and Barcelona logistics operators. |
| Solid-State Electrolyte Pilot Scale-Up | Eindhoven ventures target energy density breakthroughs for German inter-city cargo platforms. |
| GB/T 36972 Certification Investment | SAMR enforcement filters marginal suppliers and consolidates procurement toward verified pack assemblers. |
| Cloud-Connected BMS Platform Launch | Amsterdam fleet coordinators adopt predictive degradation modeling to optimize swap-station scheduling. |
Research Methodology
Desk research of trade customs data, SEC filings from listed cell manufacturers, and EU regulatory databases preceded structured interviews with pack assembly plant managers, procurement leads at Stuttgart bicycle OEMs, thermal management engineering directors, and fleet operations coordinators in Amsterdam and Copenhagen. Primary fieldwork validated secondary findings on GB/T certification timelines and CE marking test protocols. Bottom-up cell shipment data triangulated against top-down e-bike production estimates from Germany's KBA and China's bicycle association.
Assumptions held fixed include current EU Battery Regulation recycling mandate timelines and SAMR enforcement intensity of GB/T standards, while lithium carbonate price trajectories and solid-state electrolyte commercialization pace were varied across sensitivity bands. The analytical framework modeled cell geometry, end-use intensity, energy density tier, and integration level across the projection horizon. CAGRs derived from segment-level volume builds incorporating replacement cycle assumptions for Hangzhou's domestic fleet and European cargo bike penetration. Industry-specific inputs included KBA type-approval throughput rates and F-Gas Regulation containment cost engineering.
Stress conditions across lithium carbonate spot volatility, cylindrical cell supply disruption, and EU recycling mandate acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these bounded assumptions and acknowledge that solid-state electrolyte breakthroughs or abrupt SAMR enforcement shifts could revise trajectory. Quarterly review of GB/T certification backlog data and Rotterdam-Antwerp import volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Solar Powered Electric Vehicle Market
Electric Vehicles
Automotive Coolant Distribution Manifold for EV Battery Market
Electric Vehicles
Europe Solar E-Bike Market
Electric Vehicles
Electric Vehicle Regenerative Braking System Market
Electric Vehicles
Scooter Market
Electric Vehicles
Automotive EV HUB Market
Electric Vehicles
Off-Highway Electric Machine Battery Pack Systems Market
Electric Vehicles
Germany Solar E-Bike Market
Electric Vehicles
Neighbourhood Electric Vehicle Market
Electric Vehicles
E-Rickshaw Market
Electric Vehicles
Electric Vehicle Helmet Market
Electric Vehicles
E-Bike Smart Systems Market
Electric Vehicles
US Automotive High Performance Electric Vehicle Market
Electric Vehicles
Electric Vehicle (EV) Battery Housing Market
Electric Vehicles
Busbar for EV Market
Electric Vehicles
Solar Electric Car Market