
 Embedded System for Electric Vehicle Market | 2026-2036
Embedded System for Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Embedded System for Electric Vehicle Market Analysis
Automotive-grade ASIL-D certification is rotating through the supply chain as the baseline specification for new EV platform bids. Tata Elxsi leverages its India-Europe delivery model to anchor validation services for European OEM embedded programs. KPIT Technologies sustains deep specialization in powertrain control software, while Luxoft competes on digital cockpit integration for premium EV brands.
An embedded system for electric vehicle denotes a dedicated computing subsystem with real-time operating constraints, typically integrating microcontrollers running at 40-200 MHz, sensor fusion arrays, and ISO 26262-compliant fault management to govern propulsion, energy distribution, and driver interaction. The application dimension shows Battery Management Systems commanding the largest current revenue pool due to cell monitoring complexity, while Advanced Driver Assistance Systems represents the fastest structural expansion as Level 2+ autonomy penetrates mid-range EV trims. Within the technology split, Vehicle-to-Everything (V2X) connectivity solutions remain nascent but carry disproportionate margin potential as infrastructure deployment accelerates.
The EU Green Deal and REACH chemical compliance frameworks shape embedded hardware material selection and software lifecycle documentation for any supplier accessing European EV production. In the United States, NHTSA FMVSS standards and EPA certification protocols dictate functional safety thresholds for battery control modules and thermal management algorithms. Stakeholders must monitor how functional safety standards harmonize across jurisdictions, as divergence in ASIL interpretation between ECE and FMVSS pathways would fragment validation costs for multi-region platform programs.
Market Dynamics
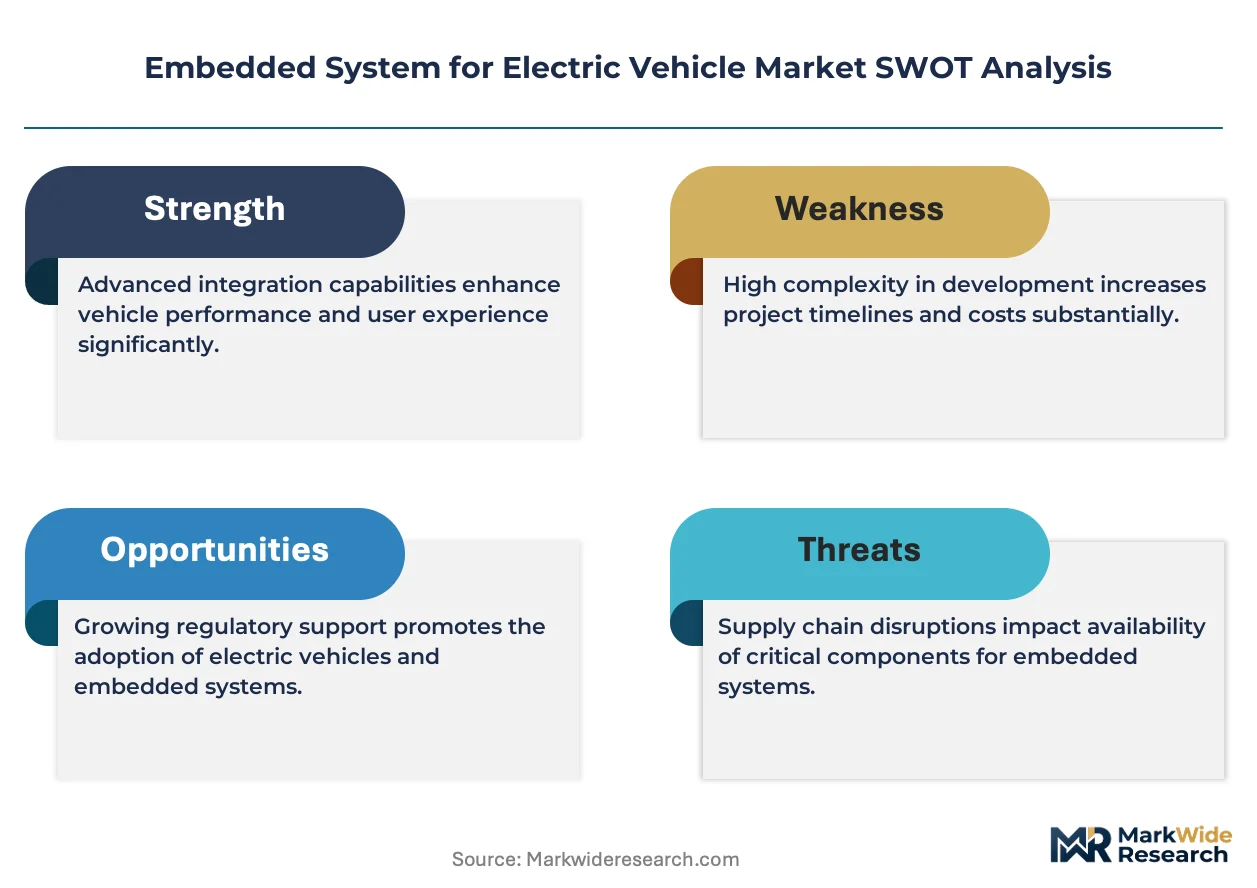
ASIL-D certification mandates from Germany's KBA are cascading through Tier-1 supplier contracts, forcing embedded architecture redesigns before platform bids can proceed. This safety-grade ratchet is compressing development timelines and redistributing engineering capacity toward validation services.
Growth Catalysts
- EU Green Deal embedded emissions standards:Software traceability requirements for automotive Tier-1 suppliers are expanding contract scopes for documentation and lifecycle management services.
- Battery Management Systems:Cell monitoring complexity in high-voltage architectures is absorbing disproportionate engineering resources and validation cycles.
- Level 2+ autonomy penetration:Mid-range EV trims are integrating sensor fusion arrays that demand real-time operating systems with deterministic fault response.
Market Restraints
- Automotive-grade microcontroller supply:40-200 MHz processor availability remains concentrated among foundries in Taiwan and South Korea, exposing programs to allocation risk.
- ISO 26262 compliance timeline:ASIL-D validation cycles extend platform development by 14-18 months, delaying revenue recognition for embedded suppliers.
- Silicon carbide module cost:Wide-bandgap power electronics for traction inverters carry 3-4x cost premiums over silicon IGBTs, constraining adoption in economy EV segments.
Strategic Opportunities
- Vehicle-to-Everything connectivity:V2X infrastructure deployment in Germany, France, and the Netherlands is opening embedded modules with disproportionate margin structures.
- Digital cockpit integration:Premium EV brands are consolidating infotainment, instrument cluster, and head-up display compute onto single domain controllers.
- India-Europe delivery models:Validation engineering arbitrage is enabling Tier-1 suppliers to compress ASIL-D documentation costs while maintaining KBA homologation compliance.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262-certified architects command 40-60% salary premiums, constraining program scaling for mid-size embedded suppliers.
- Multi-region certification divergence:ECE and FMVSS pathway differences in ASIL interpretation are fragmenting validation costs for shared EV platforms.
- Legacy powertrain code migration:Internal combustion engine control algorithms require complete re-architecture for electric motor torque vectoring, consuming engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embedded System for Electric Vehicle Market |
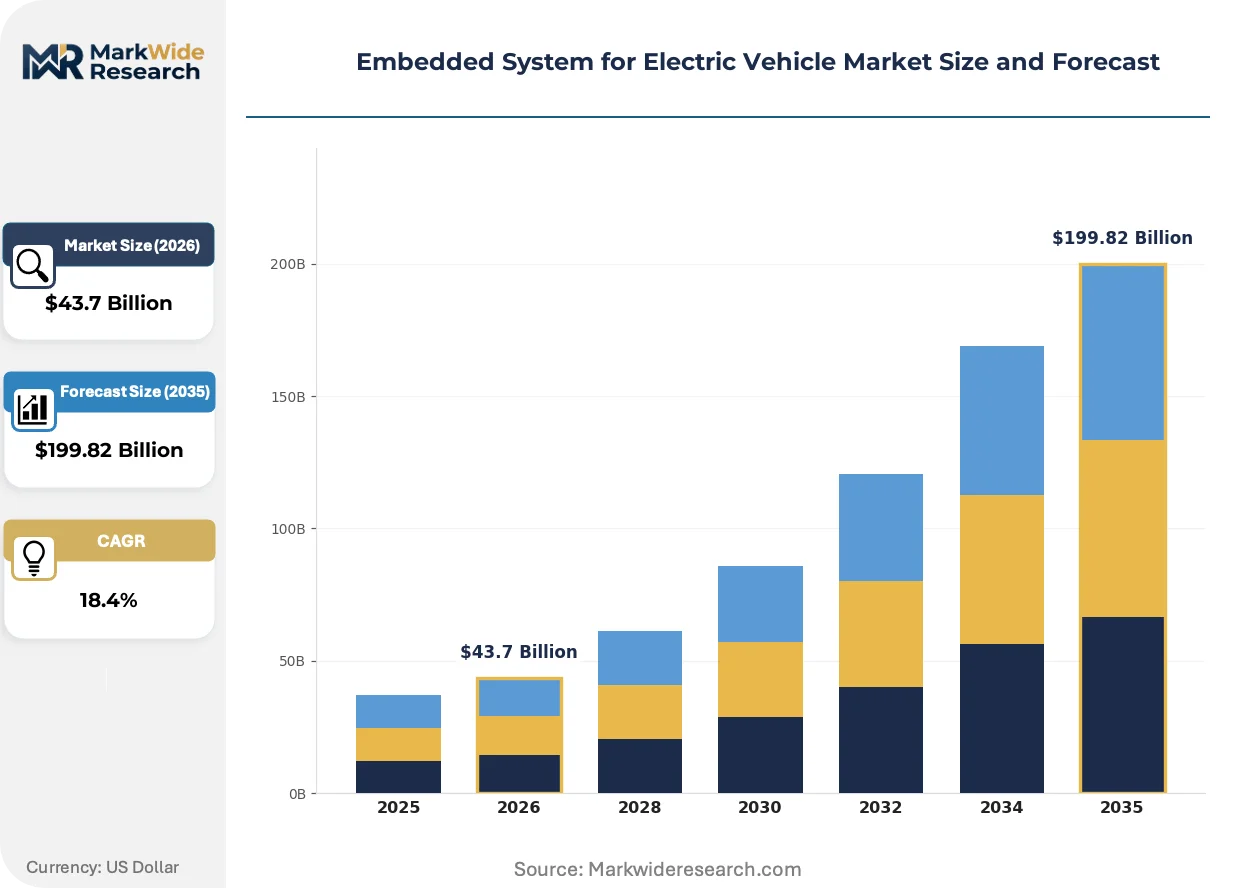
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $199.82 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
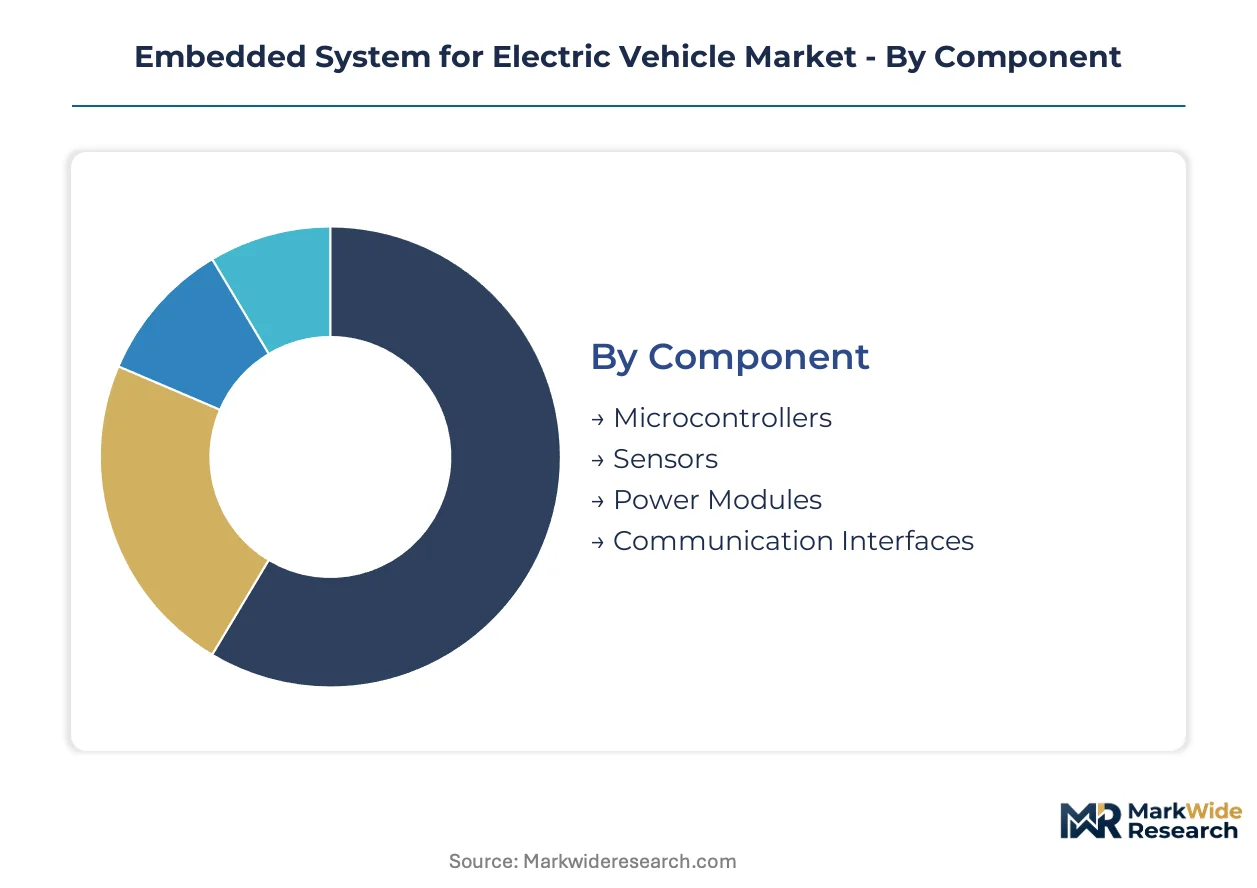
| Segmentation | Component: Microcontrollers, Sensors, Power Modules, Communication Interfaces Technology: Control Systems, Power Management, Connectivity Solutions, Vehicle-to-Everything (V2X) Application: Battery Management Systems, Infotainment Systems, Advanced Driver Assistance Systems, Telematics Use Case: Fleet Management, Smart Charging, Autonomous Driving, Maintenance Monitoring |
| Companies Covered | Wipro, Tata Elxsi, DXC Technology, Infosys, KPIT Technologies, Luxoft, Capgemini Engineering, Intellias, EPAM Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embedded System for Electric Vehicle Market Emerging Trajectories
Domain-centralized compute architectures are displacing distributed ECU networks across EV platforms. This consolidation is redrawing supplier boundaries and compressing middleware layers into fewer, more powerful system-on-chip designs.
Software-defined vehicle architectures are decomposing hardware-software coupling in embedded systems. Tesla and BYD are deploying over-the-air updatable powertrain controllers that separate application logic from base software. This decomposition is enabling subscription revenue models for performance unlocks and reducing recall costs through remote fault remediation.
REACH chemical compliance frameworks from ECHA are restricting solder materials and flame-retardant substrates in embedded hardware destined for European EV production. Suppliers must document full material declarations across semiconductor packaging and PCB laminates. Battery control module manufacturers are responding by qualifying halogen-free substrates and lead-free ball grid arrays ahead of 2026 enforcement windows.
Fleet operators and mobility providers are compressing procurement cycles for embedded subsystems, shifting from component sourcing to integrated platform contracts. Tier-1 suppliers now compete on total cost of ownership guarantees rather than unit pricing. This pattern is most visible in Germany, where commercial EV fleet mandates from the KBA are aggregating demand around validated embedded stacks with 10-year lifecycle commitments.
Embedded System for Electric Vehicle Market Segmentation
Segmentation in the embedded system for electric vehicle market exposes how hardware-software coupling varies across powertrain, cockpit, and autonomy domains. Suppliers configure validation cycles and certification paths differently depending on which segment anchors their platform bid.
Component:
Microcontrollers face substitution pressure from domain-consolidated system-on-chip designs that absorb discrete processing functions into fewer silicon dies.
- Microcontrollers:These 40-200 MHz processors execute deterministic control loops for motor management and battery cell balancing. Demand concentrates in Germany where KBA homologation rules mandate ASIL-D fault tolerance architectures, compressing supplier qualification timelines.
- Sensors:Current, voltage, and temperature sensing arrays feed real-time data streams into battery management algorithms. Fleet operators in the Netherlands specify automotive-grade Hall-effect and shunt-based designs for commercial EV procurement, prioritizing calibration stability over unit cost.
- Power Modules:Silicon carbide and silicon IGBT packages switch traction inverter loads with efficiency targets set by OEM thermal budgets.
- Communication Interfaces:CAN FD, Ethernet, and LIN transceivers bridge domain controllers across zonal architectures.
Microcontrollers retain volume leadership; Sensors hold the steepest expansion curve.
Technology:
Cost tier stratification separates validated automotive-grade stacks from economy EV controller designs that accept lower ASIL ratings.
- Control Systems:Real-time operating systems with deterministic scheduling govern torque vectoring and regenerative braking. Premium passenger EVs from Tesla and BYD deploy these as over-the-air updatable platforms, decoupling application logic from base software to enable subscription revenue models.
- Power Management:DC-DC converters and onboard charger controllers regulate high-voltage distribution with efficiency thresholds. France's commercial fleet electrification mandates are absorbing engineering capacity for bidirectional charging-capable designs that support vehicle-to-grid integration.
- Connectivity Solutions:Cellular and Wi-Fi modules enable remote diagnostics and software updates across distributed fleets.
- Vehicle-to-Everything (V2X):C-V2X and DSRC radios exchange safety-critical messages with infrastructure and other vehicles. Infrastructure deployment in Germany, France, and the Netherlands is opening embedded modules with disproportionate margin structures relative to production volumes.
Control Systems anchor current revenue concentration; V2X climbs the fastest as roadside unit deployment accelerates.
Application:
Application maturity diverges sharply between established battery monitoring functions and emerging autonomy compute demands.
- Battery Management Systems:Cell monitoring integrated circuits and state-of-charge estimation algorithms protect high-voltage pack integrity. The EU Green Deal's embedded emissions standards are expanding contract scopes for lifecycle documentation and traceability services across Tier-1 supplier programs.
- Advanced Driver Assistance Systems:Sensor fusion arrays process camera, radar, and lidar inputs for Level 2+ autonomy features. Mid-range EV trims in Germany are integrating these systems as standard equipment, forcing real-time operating system suppliers to compress deterministic fault response latencies.
- Infotainment Systems:Digital cockpit domain controllers consolidate instrument cluster, head-up display, and entertainment compute onto single silicon platforms.
- Telematics:Location tracking and usage-based insurance modules transmit encrypted vehicle data to fleet operators and mobility providers.
Battery Management Systems command the largest revenue pool; Advanced Driver Assistance Systems gain share fastest as autonomy penetrates mass-market trims.
Use Case:
Customer type fragmentation separates fleet procurement patterns from individual owner integration requirements.
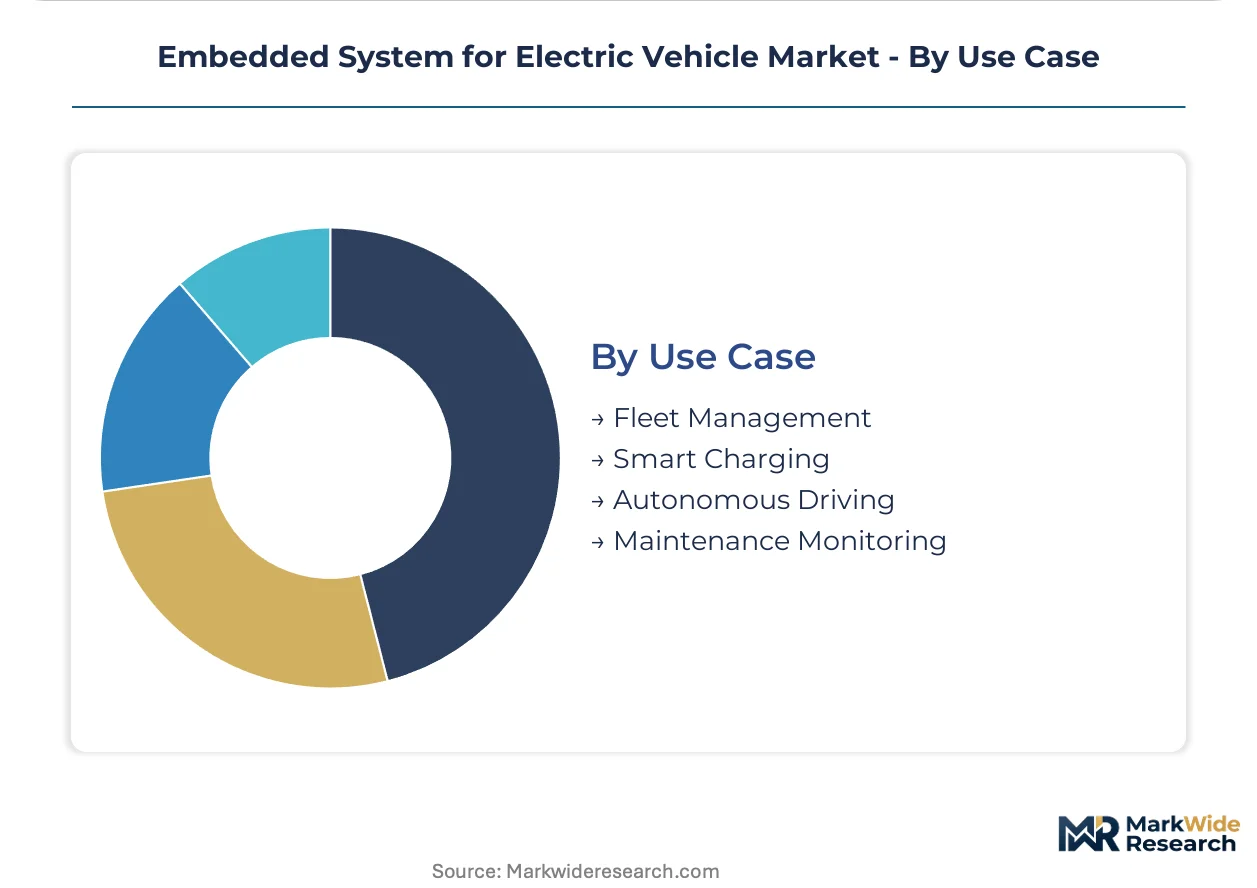
- Fleet Management:Centralized monitoring platforms track vehicle health, route efficiency, and driver behavior across commercial EV deployments. Germany's KBA mandates for commercial fleet electrification are aggregating demand around validated embedded stacks with decade-long lifecycle commitments.
- Autonomous Driving:Redundant compute architectures execute path planning and collision avoidance with fail-operational guarantees. Validation cycles for these systems extend platform development timelines, delaying revenue recognition for embedded suppliers pursuing ASIL-D certification.
- Smart Charging:Load balancing algorithms coordinate grid interaction and renewable energy absorption for residential and depot installations.
- Maintenance Monitoring:Predictive algorithms flag component degradation before failure, reducing unscheduled downtime for commercial operators.
Fleet Management dominates current contract value; Autonomous Driving carries the steepest capability investment requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor foundries in Taiwan and South Korea control the automotive-grade microcontroller supply that feeds embedded system production for electric vehicles. Tier-1 suppliers locate validation engineering and software development centers near OEM headquarters in Germany, the United States, and China to compress ASIL-D certification timelines. Regulatory divergence between ECE and FMVSS pathways fragments compliance costs for multi-region platform programs.
United States
NHTSA FMVSS standards and EPA certification protocols dictate functional safety thresholds for battery control modules and thermal management algorithms. The Inflation Reduction Act's domestic content requirements are reshaping procurement patterns for embedded hardware in EV assembly. Detroit-area engineering clusters concentrate powertrain control software development for legacy OEM electrification programs.
Germany
KBA homologation rules mandate validated embedded control systems for powertrain safety, compressing supplier qualification timelines. The EU Green Deal's embedded emissions standards tighten software traceability requirements for automotive Tier-1 suppliers. Stuttgart and Munich anchor validation service delivery for premium passenger EV platforms from domestic and international OEMs.
China
MIIT regulations govern cybersecurity and data localization requirements for connected vehicle embedded systems. Dual carbon goals accelerate fleet electrification mandates that absorb embedded controller capacity for commercial vehicle production. Shenzhen and Shanghai host integrated development centers where domestic OEMs co-locate with Tier-1 software partners.
India
PLI scheme incentives for automotive and advanced chemistry cell manufacturing are expanding embedded system demand for domestic EV production. BIS standards for automotive electronics compliance create certification pathways for export-oriented suppliers. Bangalore and Pune delivery centers execute India-Europe validation arbitrage for European OEM embedded programs.
South Korea
MFDS-equivalent automotive safety regulations align with international functional safety frameworks while maintaining domestic certification requirements. Battery manufacturer vertical integration into BMS development concentrates embedded engineering talent around Seoul and Ulsan. Domestic OEMs and Tier-1 suppliers co-develop silicon carbide power module controllers for next-generation traction inverters.
Embedded System for Electric Vehicle Market Vendor Landscape
Concentration sits with engineering services specialists that anchor ASIL-D validation programs for European and North American OEMs. The vendor base stratifies across three tiers: premium consulting firms commanding platform architecture roles, mid-size specialists dominating powertrain control software, and regional delivery centers capturing documentation and lifecycle management services. Competitive moves center on geographic arbitrage strategies and domain-specific capability acquisitions.
Within the engineering services tier, Tata Elxsi, KPIT Technologies, and Luxoft occupy positions that exemplify distinct specialization vectors. Tata Elxsi leverages its India-Europe delivery model to anchor validation services. KPIT Technologies sustains deep specialization in powertrain control software. Luxoft competes on digital cockpit integration for premium EV brands. These three represent how geographic footprint and domain focus determine competitive positioning in embedded system procurement cycles.
| Leading Market Players |
|---|
| Wipro |
| Tata Elxsi |
| DXC Technology |
| Infosys |
| KPIT Technologies |
| Luxoft |
| Capgemini Engineering |
| Intellias |
| EPAM Systems |
| Others |
Supply Flow & Price Mechanics
Automotive-grade microcontroller foundry utilization rates in Taiwan and South Korea establish price floors for embedded controllers, compressing margins for Tier-1 suppliers while concentrating procurement leverage among OEMs with volume guarantees. This scale asymmetry forces mid-size embedded suppliers toward validation service arbitrage to defend position.
Pricing Analysis
EU Green Deal embedded emissions standards dictate the pricing tier structure across European EV procurement. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified stacks from lower-grade alternatives. Cost compression in economy EV segments is intensifying because silicon carbide module premiums constrain traction inverter adoption. Fleet operators in Germany demonstrate lowest price sensitivity due to decade-long lifecycle commitments, while aftermarket replacement buyers face acute cost pressure.
Supply Chain Analysis
Taiwan Strait transit risks expose automotive-grade microcontroller supply to geopolitical disruption, threatening 40-200 MHz processor allocation for embedded system production. Manufacturing concentrates in Taiwan, South Korea, and China, with raw material dependencies spanning silicon wafers, rare earth packaging materials, and halogen-free substrate laminates. Single-source vulnerability around TSMC automotive node capacity feeds allocation risk into Tier-1 supplier programs. Distribution runs through OEM-direct contracts and Tier-1 system integrators, bypassing traditional component distributors for high-complexity modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The embedded system for electric vehicle market tracks a cyclical recovery anchored to OEM platform refresh cycles and regulatory compliance deadlines. ASIL-D certification backlogs and silicon carbide adoption curves create predictable demand waves for engineering services.
For Market Incumbents: Shield core powertrain control software franchises through captive validation engineering capacity in India and Eastern Europe. Incumbents must secure ASIL-D certified architect talent pools before salary premiums render program scaling uneconomical. Backward integration into silicon carbide module qualification accelerates traction inverter platform bids.
For New Entrants and Emerging Players: V2X connectivity deployment gaps in secondary European markets offer white-space entry where incumbents under-serve roadside unit integration demands. New entrants should target Netherlands and Belgium commercial fleet procurement, where KBA-aligned homologation requirements remain less saturated than German programs. A validation-services-first go-to-market angle bypasses capital-intensive silicon design barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors engineering services specialists with India-Europe delivery footprints and established OEM relationships. Long-term viability hinges on software-defined vehicle architecture transition, where application-base software separation creates recurring revenue potential. Watch ASIL-D certification timeline compression as the inflection signal for validation service demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | KBA homologation requirements in Germany mandate validated fault management architectures for powertrain safety. |
| India-Europe Delivery Model Expansion | Bangalore and Pune centers compress documentation costs while maintaining EU Green Deal traceability compliance. |
| Silicon Carbide Module Qualification | Wide-bandgap power electronics adoption enables next-generation traction inverter efficiency targets. |
| V2X Infrastructure Partnership | Germany, France, and Netherlands roadside unit deployment opens embedded modules with superior margin structures. |
| Software-Defined Vehicle Platform Development | Over-the-air updatable controllers separate application logic to enable subscription revenue models. |
Methodological Framework
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this study. Conversations with Tier-1 supplier procurement leads, OEM platform engineers, functional safety architects, and KBA homologation specialists informed demand-side dynamics. Secondary sources include EU Green Deal implementation documents, KBA technical bulletins, EPA certification protocols, and semiconductor foundry capacity disclosures. Bottom-up segment sizing triangulates against top-down OEM production forecasts.
Sensitivity analysis around silicon carbide adoption rates and ASIL-D certification timeline assumptions shapes the projection framework. Segmentation dimensions span component type, technology tier, application domain, and regional regulatory cluster across the modeling period. CAGRs derive from installed base evolution and content-per-vehicle trajectories, with specific inputs including battery pack size distributions and autonomy feature penetration curves.
Forecasts assume regulatory continuity in EU Green Deal enforcement and KBA homologation pathways; material policy shifts would require re-modeling. Semiconductor supply allocation disruptions or REACH chemical compliance deadline accelerations represent specific revision triggers. Practitioners should keep alternative scenarios live as foundry capacity expansion and functional safety engineer supply dynamics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Panoramic Sunroof Market
Electric Vehicles
ASEAN EV Battery Pack Market
Electric Vehicles
Middle East and Africa Electric Vehicle Thermal Management System Market
Electric Vehicles
Asia-Pacific Electric Bus Battery Pack Market
Electric Vehicles
Europe Wireless Electric Vehicle Charging Market
Electric Vehicles
Europe Electric Scooter Market
Electric Vehicles
Lawn Mower Battery Market
Electric Vehicles
Europe Automotive High Performance Electric Vehicle Market
Electric Vehicles
Mexico Electric Car Market
Electric Vehicles
North America Electric Vehicle Thermal Management System Market
Electric Vehicles
India Hybrid Electric Vehicle Battery Market
Electric Vehicles
Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle Battery Enclosure Market
Electric Vehicles
Electric Vehicle Testing, Inspection, and Certification Market
Electric Vehicles
Global Electric Scooter Lift and Carrier Market
Electric Vehicles
Europe Electric Vehicle Power Inverter Market