
 US Electric Vehicle Market | 2026-2036
US Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
US Electric Vehicle Market Intelligence
Federal Motor Vehicle Safety Standards (FMVSS) compliance is reorganizing the competitive landscape for electric vehicle manufacturers entering the US. Tesla dominates the high-end BEV segment through its proprietary charging infrastructure. Ford leverages its established truck leadership with the F-150 Lightning. General Motors competes across a wide spectrum with its Chevrolet and Cadillac brands, aiming for volume.
An electric vehicle utilizes one or more electric motors for propulsion, powered by a high-voltage rechargeable battery pack. Key components include the battery management system for thermal control, an inverter to convert DC to AC power, and an on-board charger. Battery Electric Vehicles (BEVs) command the largest share of the market, significantly outpacing plug-in hybrids. While private consumers are the primary end-user base, adoption by fleet operators and ride-sharing companies is accelerating rapidly.
The US market is shaped by regulations from the Environmental Protection Agency (EPA) concerning emissions and the National Highway Traffic Safety Administration (NHTSA) on vehicle safety. The Inflation Reduction Act (IRA) directly influences consumer and commercial purchasing decisions through substantial tax credits tied to domestic sourcing. Future competitiveness will hinge on securing domestic battery supply chains and navigating the build-out of a standardized public charging network.
Market Dynamics
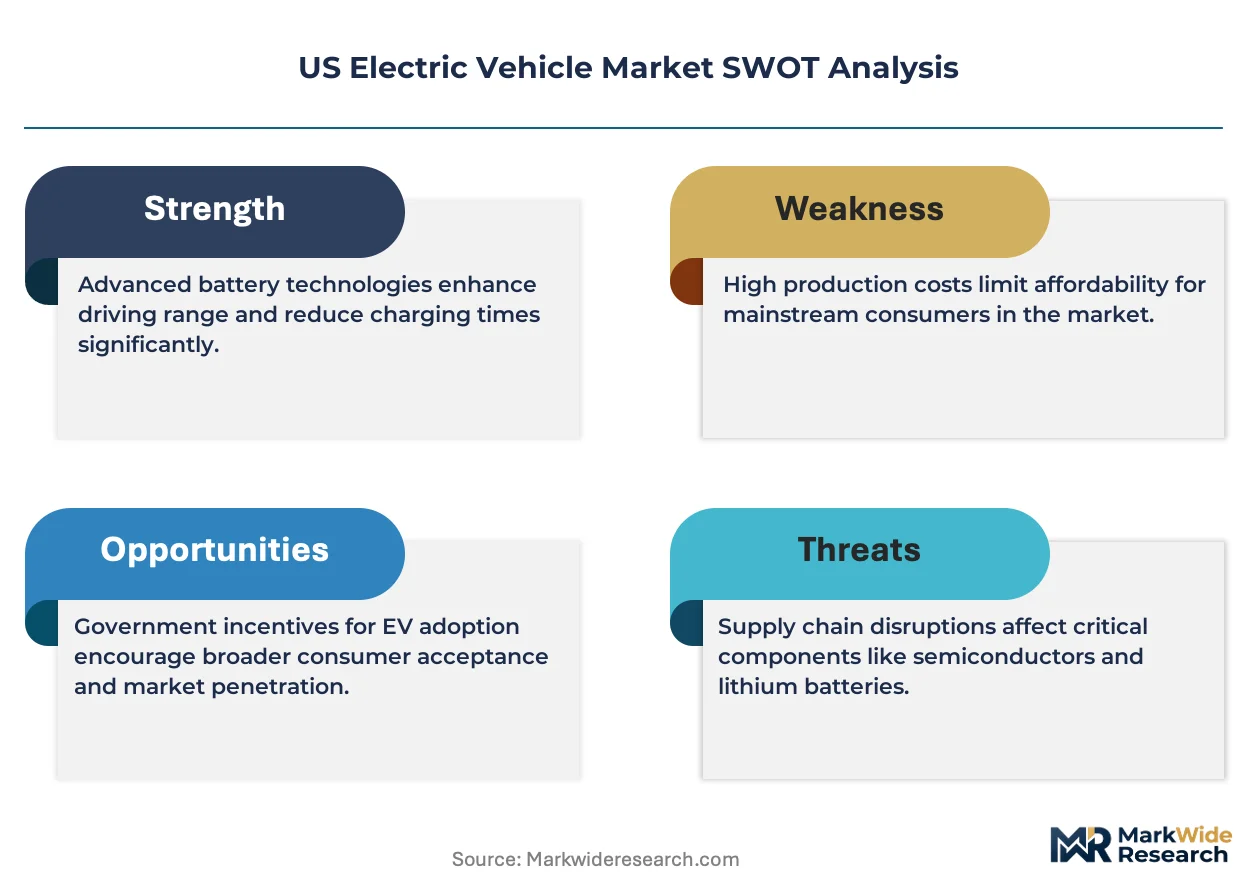
The US electric vehicle market's structure is fundamentally shaped by the Inflation Reduction Act (IRA), which ties lucrative consumer and commercial tax credits to strict domestic assembly and battery component sourcing requirements, forcing a rapid onshoring of the supply chain.
Growth Catalysts
- Federal Tax Incentives:The Inflation Reduction Act provides substantial tax credits for new and used electric vehicles, directly lowering the acquisition cost for consumers and accelerating adoption among commercial fleet operators seeking to reduce operational expenses.
- State-Level Mandates:Regulations in states like California, which mandate a transition to zero-emission vehicle sales, create a large, concentrated, and predictable demand base that pulls significant investment in charging infrastructure and manufacturing.
- Total Cost of Ownership:For high-utilization applications such as ride-sharing and last-mile delivery, the lower fuel and maintenance costs of BEVs create a compelling economic advantage over traditional internal combustion engine vehicles.
Market Restraints
- Battery Supply Chain Constraints:Heavy reliance on foreign-sourced critical minerals and battery components creates significant friction with IRA domestic content requirements, jeopardizing tax credit eligibility for many models and creating supply volatility.
- Charging Infrastructure Gaps:While dense in some urban corridors, the public charging network remains underdeveloped in many rural and multi-family housing areas, causing range anxiety and creating a barrier for potential buyers without home charging access.
- Grid Capacity Limitations:Rapid, geographically concentrated growth in EV adoption places significant strain on local electrical distribution grids, requiring substantial and costly upgrades to support increased demand, particularly from fleet depot charging.
Strategic Opportunities
- Vehicle-to-Grid Technology:The development and deployment of bidirectional charging capabilities present an opportunity for EV owners and fleet operators to participate in energy markets, providing grid stabilization services and creating new revenue streams.
- Medium and Heavy-Duty Truck Electrification:Targeting the commercial truck segment offers a significant opportunity, as these vehicles have predictable routes, high fuel consumption, and can benefit from centralized depot charging, maximizing total cost of ownership savings.
- Battery Second-Life Applications:Establishing a secondary market for retired EV battery packs for use in stationary energy storage systems addresses end-of-life concerns and creates value from a depreciating asset.
Industry Challenges
- Technician Skill Gaps:A widespread shortage of automotive technicians trained in high-voltage battery systems and EV-specific diagnostics creates service bottlenecks, increases repair costs, and hinders the post-sale customer experience.
- Permitting and Siting Delays:The build-out of public fast-charging stations is frequently hampered by lengthy and complex local permitting processes, zoning regulations, and utility interconnection studies, slowing network expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Electric Vehicle Market |
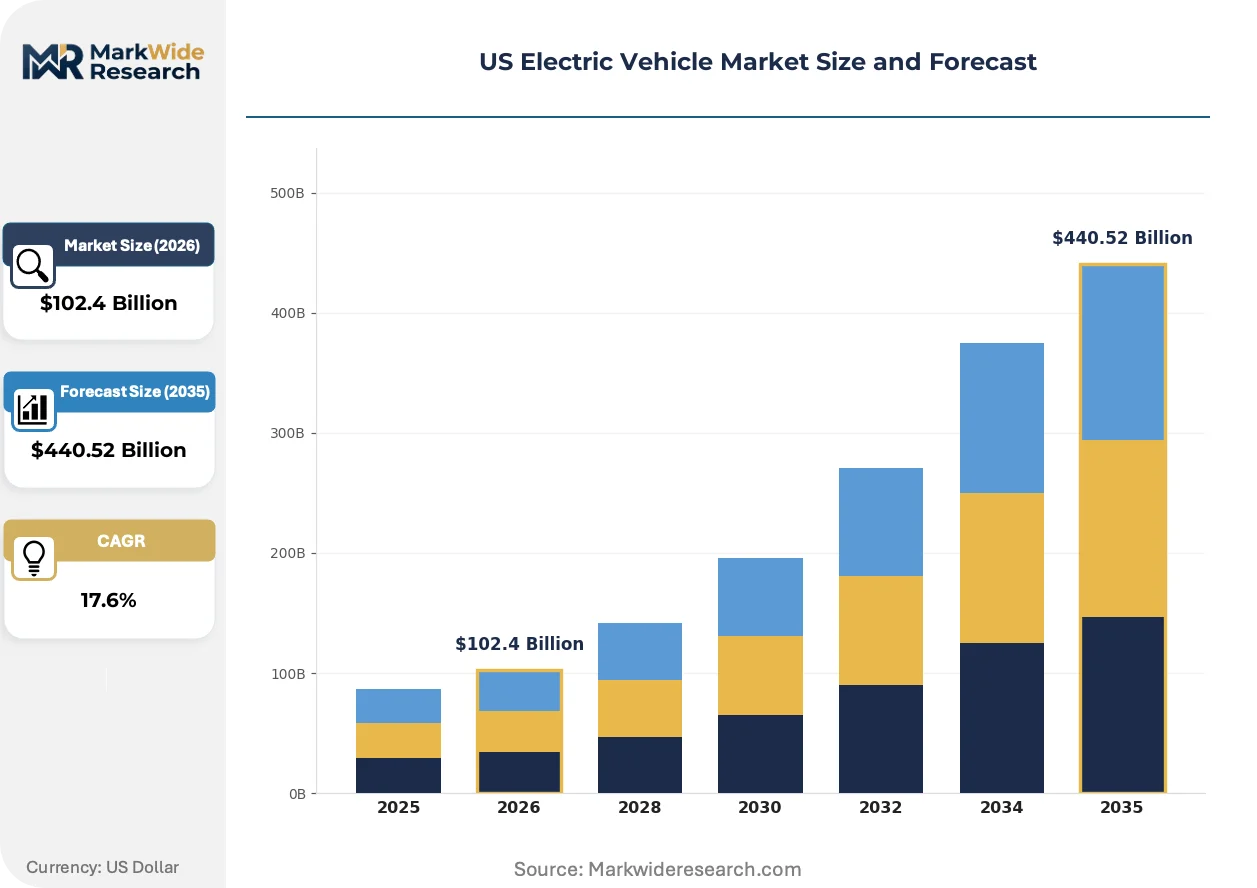
| Market Size in 2026 | $102.4 Billion |
| Market Size in 2035 | $440.52 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Battery Electric Vehicles, Plug-in Hybrid Vehicles, Fuel Cell Electric Vehicles, Neighborhood Electric Vehicles Propulsion: Electric Motor, Hybrid Drive, Hydrogen Fuel Cell, Regenerative Braking System End User: Fleet Operators, Ride-Sharing Companies, Government Agencies, Private Consumers Distribution Channel: Direct Sales, Dealerships, Online Platforms, Leasing Companies |
| Companies Covered | Volkswagen, Hyundai, Tesla, Chevrolet, Cadillac, General Motors, BMW, Audi, Ford, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Electric Vehicle Market Strategic Shifts & Innovations
The market is shifting from a focus on early adopters to addressing the pragmatic needs of mass-market consumers and commercial fleets. This pivot drives innovation toward lower-cost battery chemistries, more resilient charging solutions, and software-defined vehicle architectures.
Lithium Iron Phosphate (LFP) battery chemistry provides a lower-cost, cobalt-free alternative for vehicle batteries. Automakers are rapidly adopting LFP for standard-range and entry-level models to make them more price-competitive. The technology's improved thermal stability and longer cycle life is supplanting traditional Nickel Manganese Cobalt (NMC) formulations in segments where extreme energy density is not the primary requirement, such as commercial delivery vans.
New vehicle emissions standards from the Environmental Protection Agency (EPA) are accelerating the transition to electric powertrains. These regulations set progressively stricter limits on fleet-wide average emissions, creating a strong compliance incentive for manufacturers to increase their BEV sales mix. The light-duty truck and SUV segments, which represent a large portion of US auto sales and manufacturer profits, are most directly impacted by this regulatory pressure.
A behavioral shift toward simplified vehicle access models is challenging traditional ownership norms. Subscription services that bundle the vehicle, insurance, maintenance, and public charging into a single monthly fee are gaining traction, particularly in dense urban centers. This trend, most visible in markets like California and Florida, caters to consumers who prioritize flexibility and predictable costs over the long-term commitment of a loan or lease.
US Electric Vehicle Market Segmentation
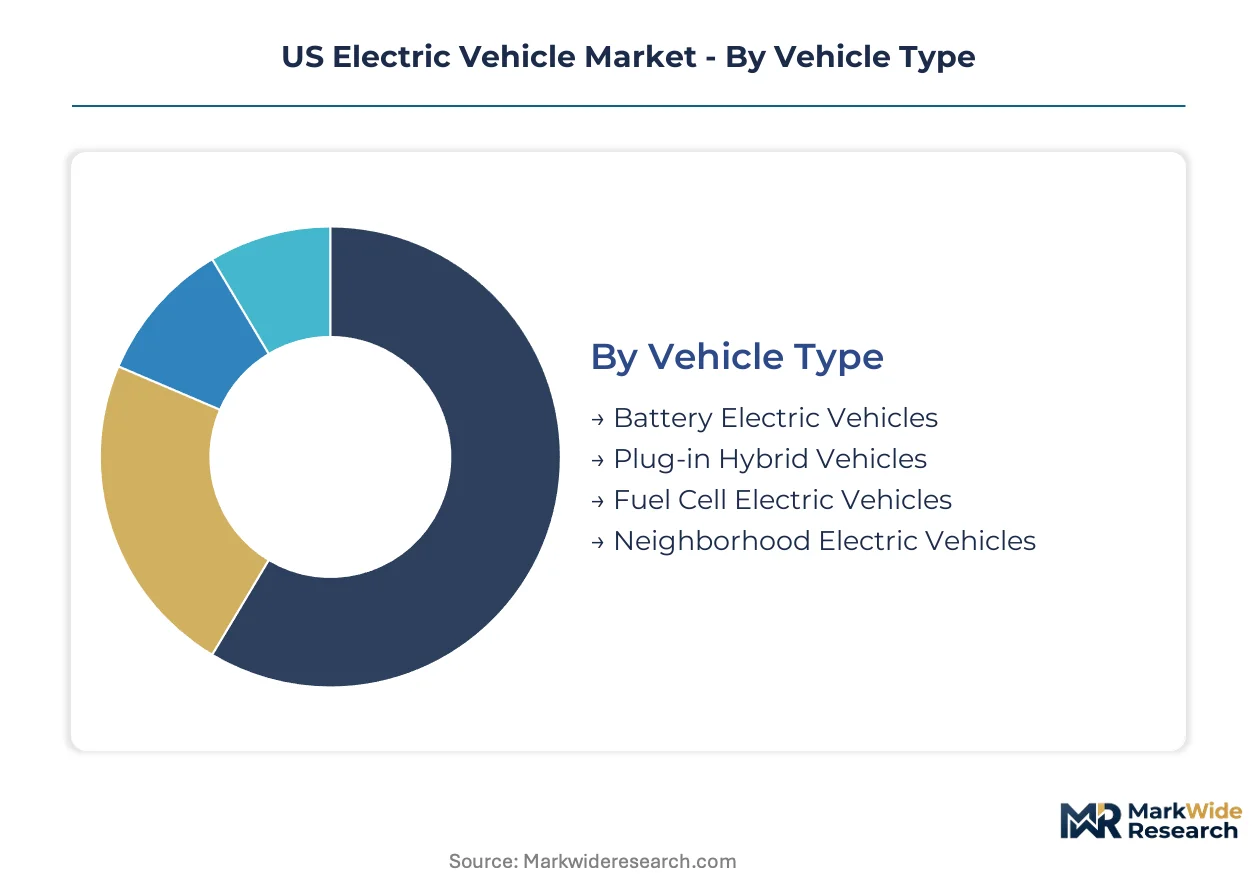
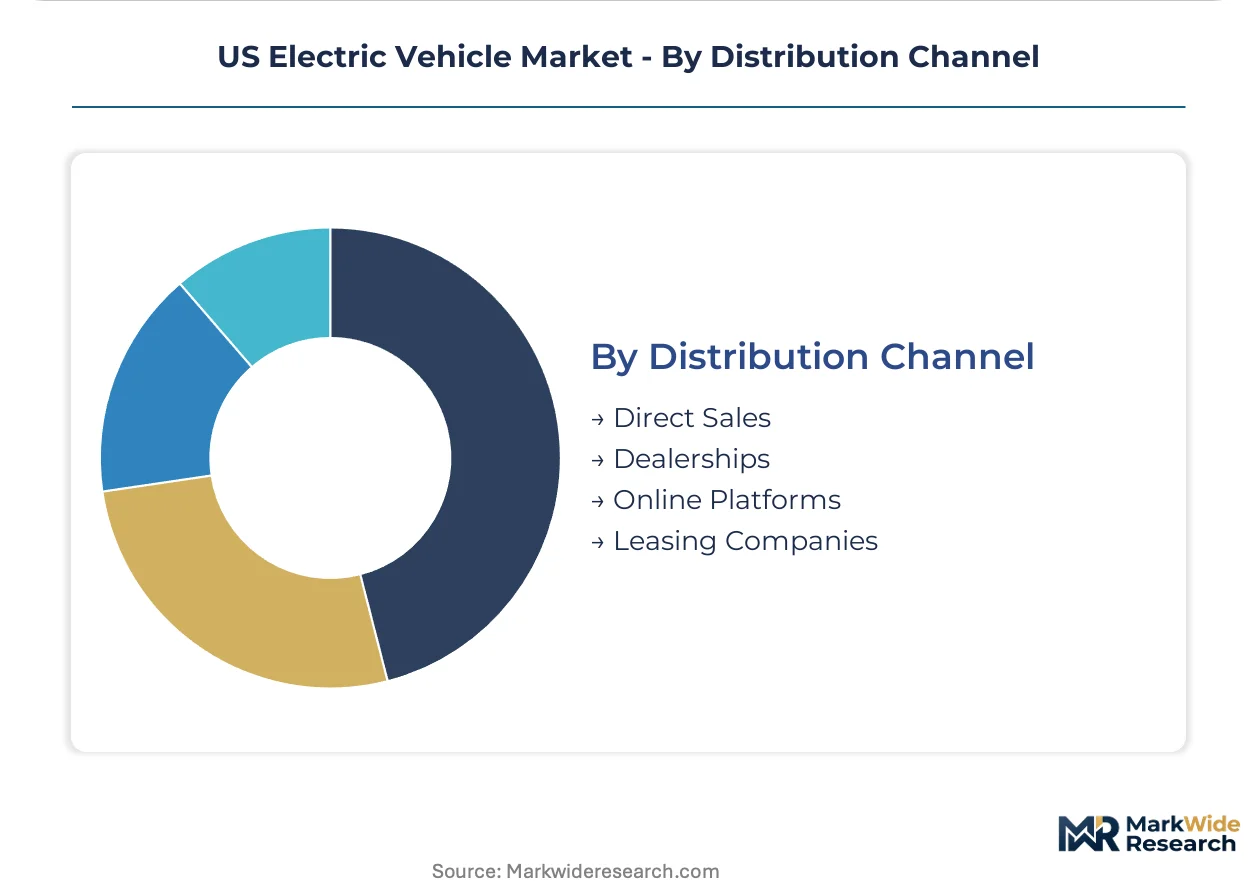
The US electric vehicle market structures itself across distinct categories, reflecting the diverse technological advancements and varied consumer demands. Understanding these segments is crucial for manufacturers and policymakers aiming to strategically address specific market needs and regulatory pressures.
Vehicle Type:
The competitive dynamics within vehicle types are largely defined by the substitution pressure exerted by established internal combustion engine vehicles and the emerging alternatives.
- Battery Electric Vehicles:These vehicles utilize only electric motors, drawing power from a large, high-voltage battery pack for propulsion. They command the largest share of the US market, driven by significant federal tax credits and state-level mandates in California.
- Plug-in Hybrid Vehicles:These vehicles combine an electric motor with an internal combustion engine, offering limited electric-only range. They appeal to US consumers seeking flexibility and extended range without full reliance on charging infrastructure.
- Fuel Cell Electric Vehicles:These vehicles generate electricity from hydrogen and oxygen, emitting only water vapor. Toyota and Hyundai offer limited models in specific US regions.
- Neighborhood Electric Vehicles:These low-speed, street-legal vehicles are designed for short-distance travel, typically within master-planned US communities.
Battery Electric Vehicles retain volume leadership; Fuel Cell Electric Vehicles hold the steepest expansion curve.
Propulsion:
Propulsion technologies are differentiated by their application suitability across various vehicle platforms and operational requirements.
- Electric Motor:This component converts electrical energy into mechanical energy for propulsion, offering instant torque and high efficiency. It forms the core propulsion system for all battery electric vehicles, with demand concentrated in urban delivery fleets.
- Regenerative Braking System:This system recovers kinetic energy during deceleration, converting it back into electrical energy to recharge the battery. It enhances vehicle efficiency and extends range across all EV types, particularly beneficial in stop-and-go US city traffic.
- Hybrid Drive:This system combines an electric motor with a gasoline engine, optimizing fuel efficiency. It provides flexibility for consumers in the US seeking reduced emissions without range anxiety.
- Hydrogen Fuel Cell:This technology generates electricity through an electrochemical reaction between hydrogen and oxygen. It offers rapid refueling, primarily for specialized applications in California.
The efficiency and reliability of Electric Motor systems drive widespread adoption, while Hydrogen Fuel Cell technologies are gaining traction for specialized uses.
End User:
Customer types exhibit distinct purchasing behaviors and operational priorities, influencing vehicle design and service offerings.
- Private Consumers:These individuals purchase EVs for personal use, driven by environmental concerns, lower operating costs, and technological appeal. They represent the largest end-user base in the US, with purchasing decisions heavily influenced by home charging availability and state incentives.
- Fleet Operators:These commercial entities deploy EVs for business operations, including delivery, service, and corporate transportation. They show accelerating adoption in the US, driven by total cost of ownership savings and federal incentives from the Inflation Reduction Act.
- Ride-Sharing Companies:These businesses utilize EVs to provide on-demand transportation services in urban centers. They benefit from reduced operational costs and enhanced brand image.
- Government Agencies:Federal, state, and local government bodies acquire EVs for official use, aligning with sustainability goals and emissions reduction mandates.
Private consumers represent the largest segment by volume, with fleet operators showing rapid expansion.
Distribution Channel:
The maturity of distribution channels impacts market access and consumer engagement strategies for electric vehicles.
- Dealerships:This traditional automotive retail model offers sales, financing, and after-sales service through franchised locations. They remain the primary distribution channel for most established automakers in the US, leveraging existing sales networks and service infrastructure.
- Direct Sales:Manufacturers sell vehicles directly to consumers, often online or through brand-owned stores, bypassing traditional dealerships. This model is gaining traction in the US market, particularly with new EV entrants like Tesla, offering a streamlined purchasing experience.
- Online Platforms:These digital channels facilitate vehicle discovery, configuration, and purchase, sometimes in conjunction with physical showrooms. They offer convenience and broader reach for US consumers.
- Leasing Companies:These entities provide vehicles for a fixed period and mileage, appealing to consumers seeking lower upfront costs and flexibility. They offer an alternative access model for US EV adoption.
Dealerships maintain broad market reach, while direct sales models are reshaping consumer purchasing experiences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The build-out of a standardized public charging network underwrites the diverse regional adoption patterns for electric vehicles across the United States. State-level mandates and federal incentives significantly influence localized market growth. These dynamics create distinct EV ecosystems from coast to coast.
California
Strong consumer demand for zero-emission vehicles drives the California EV market. State-level mandates from the California Air Resources Board (CARB) accelerate the transition to electric powertrains. The Silicon Valley region and Los Angeles metropolitan area concentrate significant investment in charging infrastructure and EV manufacturing facilities.
Texas
Commercial fleet operators in Texas are rapidly electrifying their vehicle portfolios, seeking operational cost reductions. Federal tax credits from the Inflation Reduction Act (IRA) incentivize this commercial shift. Austin and Houston are becoming hubs for EV charging development and fleet depot electrification projects.
Northeast Corridor
Dense urban centers along the Northeast Corridor exhibit strong demand for electric delivery vans and ride-sharing services. State-level incentives in New York and Massachusetts support public charging network expansion. Boston and New York City are experiencing rapid growth in electric last-mile delivery fleets and public transit electrification.
Michigan
Michigan's automotive manufacturing legacy positions it for significant electric vehicle production. The Inflation Reduction Act (IRA) encourages domestic battery and vehicle assembly within the state. Detroit remains the epicenter for EV research, development, and advanced manufacturing, attracting substantial automotive industry investment.
US Electric Vehicle Market Key Industry Players
Listed leaders compete with private specialists across technological innovation and market reach within the US electric vehicle sector. The market exhibits a tiered structure, with established automotive giants alongside agile pure-play EV manufacturers. Strategic archetypes include volume-focused legacy automakers leveraging existing distribution, premium segment innovators emphasizing direct sales, and niche commercial vehicle specialists. Companies primarily engage in aggressive capacity expansion and strategic partnerships to secure critical battery supply chains and expand charging infrastructure.
Among the established automotive groups, General Motors Company and Ford Motor Company exemplify the strategy of electrifying broad vehicle portfolios, from mass-market cars to heavy-duty trucks, leveraging their extensive dealership networks and manufacturing scale. Tesla, Inc. represents the direct-to-consumer model, focusing on high-performance Battery Electric Vehicles and developing a proprietary charging infrastructure that differentiates its premium offerings. These three players collectively anchor significant segments of the US EV market through diverse product offerings, distinct go-to-market approaches, and substantial investment in domestic production capabilities.
| Leading Market Players |
|---|
| Volkswagen |
| Hyundai |
| Tesla |
| Chevrolet |
| Cadillac |
| General Motors |
| BMW |
| Audi |
| Ford |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements for critical battery minerals lock in both supply access and price visibility for US electric vehicle manufacturers. This structure mitigates commodity price volatility for key inputs like lithium and cobalt.
Pricing Analysis
Volume-based pricing structures influence electric vehicle acquisition costs for US buyers. Pricing stratifies across premium, standard, and economy tiers, differentiated by battery range and advanced driver-assistance features. Cost compression in the entry-level segment is intensifying due to competition and LFP battery adoption. Commercial fleet operators exhibit high price sensitivity, prioritizing total cost of ownership, while private consumers often prioritize brand and technology.
Supply Chain Analysis
Geopolitical chokepoints in Southeast Asia and Africa underwrite the US electric vehicle supply chain's vulnerability. Supply concentrates heavily in China for battery cells and processing of critical minerals like lithium and nickel. Regulatory restrictions from the Inflation Reduction Act (IRA) create a structural risk by mandating domestic sourcing for tax credit eligibility. Distribution runs through both traditional dealership networks and direct-to-consumer models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US electric vehicle market functions as a substitution defense against internal combustion engine vehicles. Incumbents must navigate the threat of range anxiety and high upfront costs for consumers.
For Market Incumbents: Fortify domestic battery supply chains through direct investments in US mining and processing facilities. Expand public charging infrastructure partnerships to alleviate range anxiety and improve customer experience. This counters the threat from foreign-sourced components and supports broad market adoption. Vertical integration into battery manufacturing serves as a key lever for cost control.
For New Entrants and Emerging Players: Lead with differentiated technology in niche segments, such as medium and heavy-duty commercial trucks. Target underserved urban delivery fleets and last-mile logistics operations, which are highly sensitive to total cost of ownership. A direct-to-consumer sales model with integrated charging solutions offers a compelling go-to-market angle. This strategy addresses the high capital requirements of mass-market competition.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized battery technology firms and charging network developers with proprietary intellectual property. Long-term viability depends on securing access to critical raw materials and establishing robust domestic manufacturing capabilities. Acquirers should target companies that enhance vertical integration or offer scalable software-defined vehicle platforms. The signal to watch is the sustained reduction in battery pack costs across the analysis window.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures long-term access to essential raw materials and stabilizes production costs for US manufacturers. |
| Charging Infrastructure Partnership | Expands public access to charging, reducing range anxiety for US electric vehicle consumers. |
| Platform Standardization | Reduces development costs and accelerates new model introductions across diverse vehicle segments. |
| Software-Defined Vehicle Investment | Enhances vehicle functionality and enables new revenue streams through over-the-air updates for owners. |
| Geographic Manufacturing Footprint | Leverages federal incentives like the Inflation Reduction Act to build domestic production capacity. |
Research Approach
A standing panel of automotive procurement leads, fleet managers, charging infrastructure developers, and regulatory compliance officers provided ongoing calibration. This primary research, combining in-depth interviews with industry stakeholders, was validated against extensive secondary data from NHTSA reports, EPA emissions data, and state EV registration databases. Bottom-up market sizing was triangulated with top-down industry forecasts.
Outputs were cross-referenced against external benchmarks and historical market trends for consistency across the analysis window. The analytical framework modeled market segments by vehicle type, propulsion, end user, distribution channel, and battery chemistry. Compound annual growth rates were derived from multi-factor regression, incorporating projected charging station deployment rates and critical raw material costs.
Forecasts assume regulatory continuity in US federal and state regimes; material policy shifts would require re-modeling. Battery supply chain volatility or grid capacity limitations are key risk factors. Revision becomes warranted when federal incentives or critical mineral availability significantly shift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Mobility Market
Electric Vehicles
E-Bike Smart Systems Market
Electric Vehicles
EV PTC Heaters Market
Electric Vehicles
Electric Vehicle Thermal Management Market
Electric Vehicles
United Kingdom Electric Vehicle (EV) Market
Electric Vehicles
UK Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Commercial Vehicle Electric Propulsion System Market
Electric Vehicles
Hybrid E-Scooter Market
Electric Vehicles
Electric All-Terrain Vehicle (ATV) Market
Electric Vehicles
Middle East and Africa Electric Vehicle Thermal Management System Market
Electric Vehicles
Russia Electric Cars Market
Electric Vehicles
China Electric Truck Market
Electric Vehicles
Electric Tuk-Tuks Market
Electric Vehicles
Fuel-Cell Electric Vehicle Insulation Market
Electric Vehicles
APAC E-Bikes Market
Electric Vehicles
Electric Vehicle Electronic Expansion Valve (EXV) Market