
 Mexico Mining Market | 2026-2036
Mexico Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Mining Market Intelligence
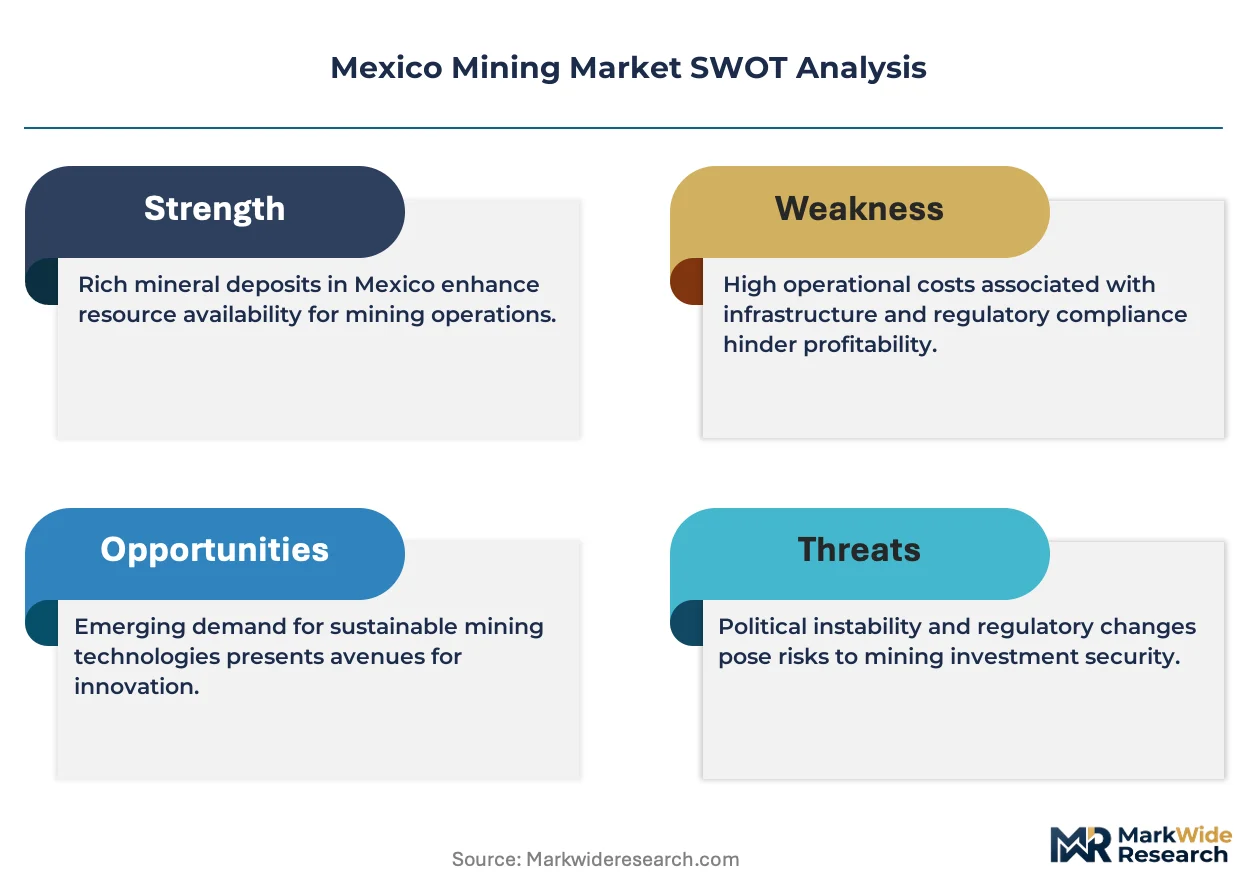
The PROFEPA Clean Industry certification program is bifurcating the competitive landscape in Mexico's mining sector. This voluntary environmental standard signals operational excellence and separates operators based on their commitment to sustainable practices. Santacruz Silver Mining leverages its operational experience in established silver-producing regions within Mexico. Discovery Silver specializes in developing large-scale silver projects, focusing on resource definition and engineering to attract investment.
Mexico's mining industry involves the exploration, extraction, and processing of metallic and non-metallic minerals from the earth. Key activities include geological surveying and the mechanical or chemical separation of valuable minerals like silver and gold from ore. Silver and Gold extraction remain the most valuable product segments, defining the country's historic mining identity. While traditional underground mining persists, large-scale open-pit operations for copper and zinc are gaining economic significance due to their efficiency.
The Secretaría de Economía grants mining concessions, while SEMARNAT and PROFEPA enforce environmental protection laws. These regulations dictate operational permits, water usage rights, and mandatory land reclamation standards for all mining projects in the country. Future investment viability will hinge on navigating community relations and securing social licenses to operate alongside formal government approvals.
Market Dynamics
The central force shaping Mexico's mining sector is the growing tension between federal economic objectives, which favor extraction, and stricter environmental and social governance standards demanded by regulators like SEMARNAT and local communities. This conflict defines investment risk and operational strategy.
Growth Catalysts
- Construction Sector Demand:Rising infrastructure and residential construction projects across Mexico are elevating the domestic requirement for industrial minerals such as aggregates, limestone, and gypsum, supporting quarrying operations.
- Clean Technology Mandates:Increasingly stringent environmental laws from SEMARNAT are compelling mining operators to invest in cleaner extraction and water treatment technologies, which in turn boosts efficiency and resource recovery rates.
- Precious Metal Safe Haven:Continued global economic uncertainty sustains demand for gold and silver as safe-haven assets, reinforcing the economic viability of exploration and production activities in historic mining states like Zacatecas and Durango.
Market Restraints
- Regulatory Ambiguity:Unpredictable timelines and shifting criteria for the granting of mining concessions by the Secretaría de Economía create significant uncertainty for long-term capital investment and project planning.
- Water Access Conflicts:In arid states like Sonora and Chihuahua, competition for scarce water resources between mining operations and other users creates significant social and legal hurdles, often involving CONAGUA regulations.
- Community Opposition:Organized resistance from local and indigenous communities, particularly in southern states like Oaxaca, can halt or indefinitely delay projects, highlighting the risk of operating without a secured social license.
Strategic Opportunities
- Critical Mineral Exploration:Growing global demand for battery and energy transition metals presents an opportunity to diversify beyond precious metals by exploring and developing Mexico's untapped lithium and copper deposits.
- Tailings Reprocessing:The application of modern metallurgical technologies to reprocess historical mine tailings offers a low-impact opportunity to recover valuable minerals from waste materials at legacy sites across the country.
- Supply Chain Formalization:Initiatives to formalize and integrate small-scale and artisanal miners into the legal supply chain can unlock new sources of ore while improving safety standards and reducing environmental impact.
Industry Challenges
- Insecurity and Extortion:Mining operations, particularly in states like Guerrero and Michoacán, face significant operational disruptions and increased security costs due to the activities of organized criminal groups.
- Deficient Infrastructure:The remote location of many prospective mining sites requires substantial capital expenditure on basic infrastructure such as roads and power, inflating project development costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Mining Market |
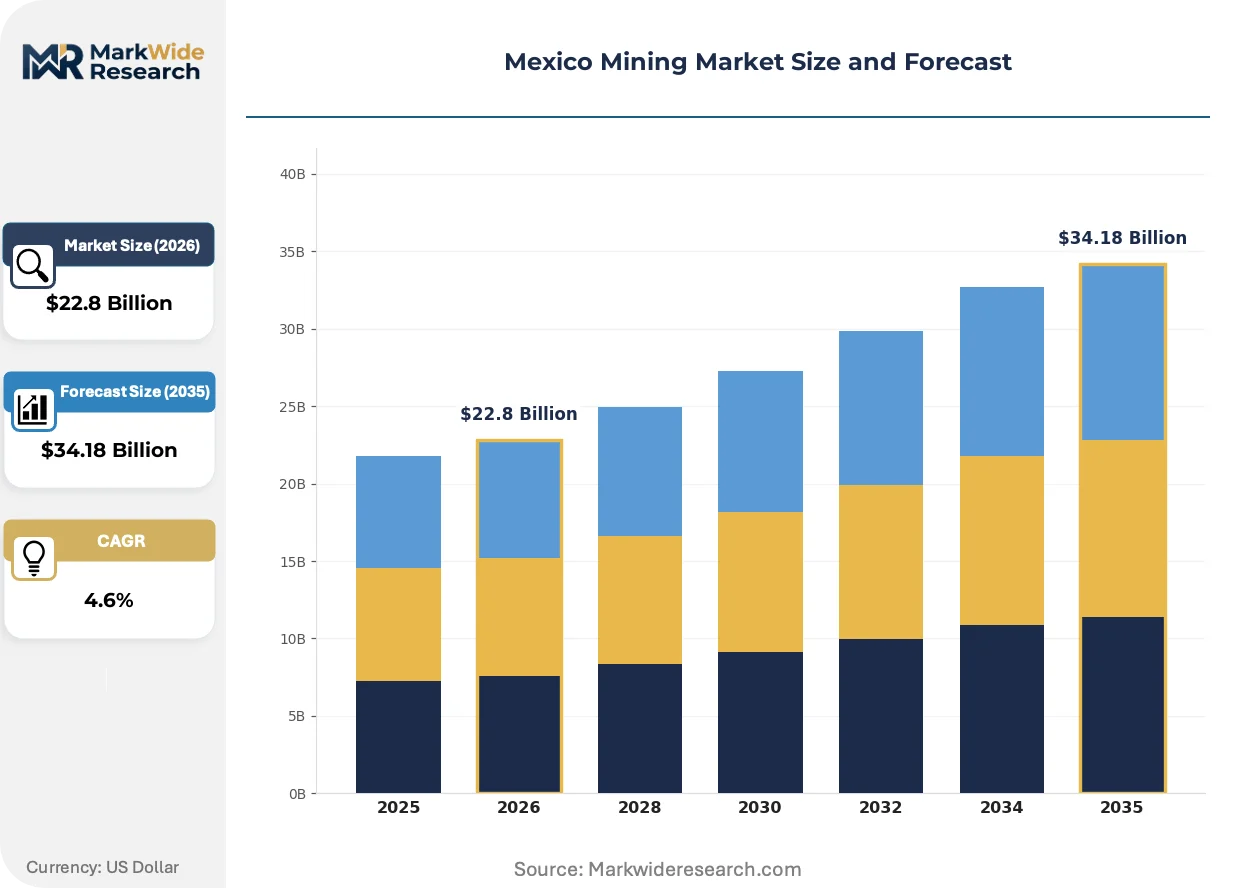
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $34.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gold, Silver, Copper, Zinc Extraction Method: Open-Pit, Underground, Placer, Mountaintop Removal End User: Metals Industry, Manufacturing, Construction, Energy Technology: Automated Mining, Drone Surveying, Reclamation Techniques, Processing Innovations |
| Companies Covered | Discovery Silver, Lundin Gold, Heliostar Metals, G Mining Ventures, Graphite One, Santacruz Silver Mining, Rio2, Altona Rare Earths, Ucore Rare Metals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Mining Market Strategic Shifts & Innovations
A recalibration toward sustainability and operational efficiency defines Mexico's mining industry. This shift is driven by regulatory pressure from PROFEPA and the economic need to optimize extraction in a complex environment, altering how projects are planned and executed.
Digital twin technology allows for the creation of virtual models of mine sites for advanced simulation. Large-scale open-pit copper and zinc operations are the primary adopters, seeking to optimize blast patterns and fleet management. The use of such data-intensive platforms is bifurcating the sector between sophisticated, high-yield producers and smaller operators reliant on traditional methods.
PROFEPA's "Industria Limpia" (Clean Industry) voluntary certification program is gaining influence as a de facto standard for environmental excellence. Obtaining this certification signals superior operational management and helps secure a social license to operate, easing negotiations with communities and investors. The standard most affects large, publicly-traded mining companies that require demonstrable ESG credentials to access international capital markets.
Community engagement is evolving from a preliminary checkbox to a continuous requirement for project viability, constituting a social license. This disrupts the model where a federal SEMARNAT permit was sufficient for a project to proceed. The imperative for deep community partnerships is most visible in states like Sonora and Zacatecas, where water and land use are contentious.
Mexico Mining Market Segmentation
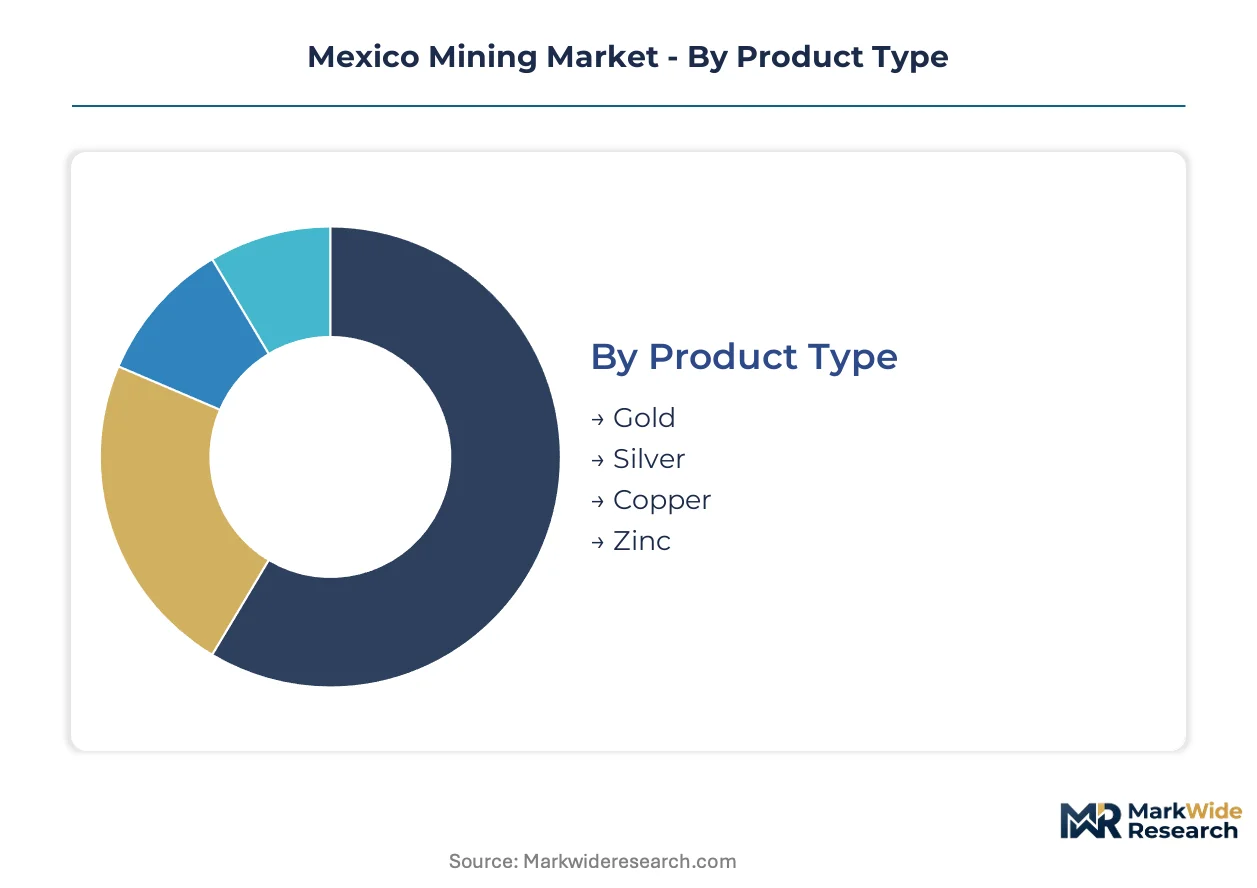
The Mexico Mining Market's segmentation reveals distinct operational and commercial landscapes across various mineral types and extraction methods. Understanding these divisions is crucial for investors and operators to pinpoint areas of high value and strategic growth. This analysis dissects the market into key product types, extraction methodologies, end-user industries, and technological applications.
Product Type:
Margin pools for precious metals define this category's commercial structure within the Mexican mining sector.
- Gold:This precious metal is primarily extracted from ore bodies through cyanide leaching or gravity concentration methods. Demand for gold remains robust due to its status as a global safe-haven asset, reinforcing exploration and production activities in states like Zacatecas and Durango.
- Silver:Silver is often found in polymetallic deposits and is recovered through flotation or leaching processes. Sustained global economic uncertainty drives its demand as a safe-haven investment, underpinning the economic viability of operations in established silver-producing regions.
- Copper:Copper is a base metal extracted from porphyry deposits through open-pit mining and solvent extraction-electrowinning (SX-EW) or flotation.
- Zinc:Zinc is typically mined from sulfide deposits, often alongside lead and silver, and processed using flotation to produce concentrates.
The dominant share belongs to Gold, while Silver is closing the gap fastest.
Extraction Method:
Cost efficiency and environmental impact dictate the predominant extraction methods in Mexico's mining industry.
- Open-Pit:This large-scale surface mining technique involves removing overburden to access mineral deposits near the surface. Open-pit operations for copper and zinc are gaining economic significance in Mexico due to their high efficiency and capacity to process large volumes of lower-grade ore.
- Underground:Underground mining involves creating tunnels and shafts to access deeper mineral veins, commonly used for high-grade precious metal deposits. Traditional underground methods remain critical for silver and gold extraction, particularly in geologically complex formations.
- Placer:Placer mining recovers heavy minerals from alluvial or glacial deposits using gravity-based separation methods, often for gold.
- Mountaintop Removal:This surface mining technique involves removing the top of a mountain to expose coal seams or other mineral deposits.
This segment is defined by operational scale, with Open-Pit exhibiting the most rapid expansion.
End User:
The application of extracted minerals across various industries shapes demand patterns and market stability.
- Construction:This sector utilizes industrial minerals like aggregates, limestone, and gypsum for infrastructure and residential projects. Rising construction activity across Mexico elevates domestic requirements, supporting quarrying operations and mineral producers.
- Metals Industry:This segment encompasses the smelting, refining, and fabrication of metallic minerals into semi-finished and finished products. Mexico's extensive silver and gold production directly feeds this industry for further processing and value addition.
- Manufacturing:Manufacturing industries consume various minerals as raw materials for producing goods, including automotive components and electronics.
- Energy:The energy sector uses minerals such as uranium for nuclear power and copper for electrical infrastructure and renewable energy technologies.
Construction drives the majority of demand, while Metals Industry shows significant growth potential.
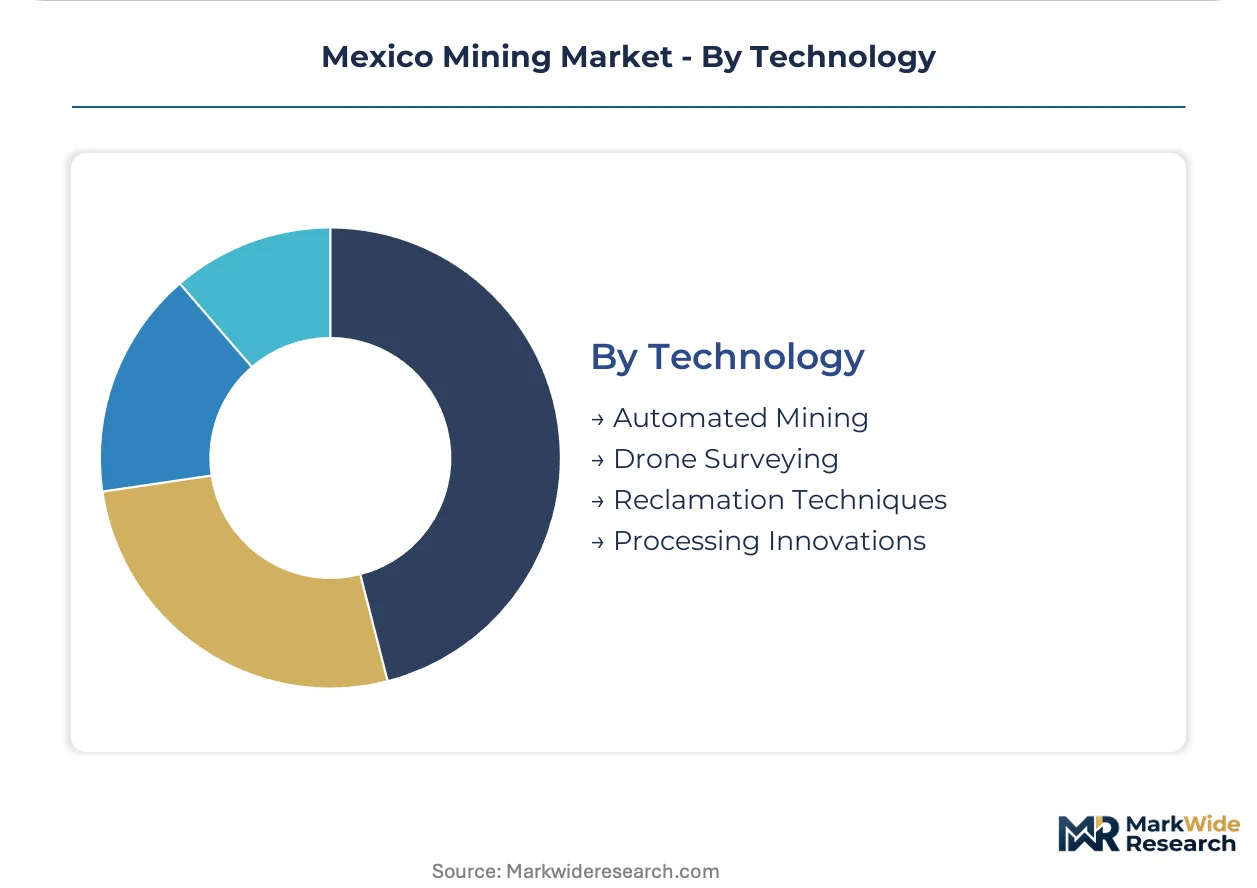
Technology:
Innovation in mining technology is driven by the need for operational efficiency and environmental compliance.
- Automated Mining:This involves deploying autonomous vehicles, remote-controlled equipment, and digital twin technology for mine planning and execution. Large-scale open-pit copper and zinc operations are primary adopters, optimizing blast patterns and fleet management for enhanced productivity.
- Processing Innovations:These advancements focus on improving mineral recovery rates and reducing environmental impact through cleaner extraction and water treatment technologies. Reprocessing historical mine tailings with modern metallurgical techniques offers a low-impact opportunity to recover valuable minerals.
- Drone Surveying:Drones provide aerial mapping and data collection for geological surveying, volumetric measurements, and environmental monitoring at mine sites.
- Reclamation Techniques:These methods involve restoring mined land to its original or an ecologically viable state, adhering to mandatory land reclamation standards set by SEMARNAT.
Efficiency gains are largely concentrated in Automated Mining, with Processing Innovations offering new operational paradigms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's extensive port infrastructure along both coasts underwrites its role in mineral exports, connecting producers to global markets. This strategic advantage supports the country's diverse mining operations. Regional variations in geology and regulatory enforcement shape local market dynamics.
Sonora
Sonora's economy benefits from strong demand for industrial minerals and base metals like copper and zinc. SEMARNAT regulations increasingly push for water treatment technologies in the arid region, boosting efficiency. The Hermosillo area concentrates major mining hubs, attracting significant foreign investment for large-scale operations.
Zacatecas
Zacatecas remains a crucial center for gold and silver production, driven by sustained safe-haven demand. The Secretaría de Economía manages mining concessions, influencing long-term project viability. Historic mining districts like Fresnillo continue to yield substantial precious metal output from both traditional and modern operations.
Durango
Durango's mining sector sees robust activity in gold and silver extraction, reinforcing its historic identity. PROFEPA's Clean Industry certification program encourages sustainable practices among operators. The state capital, Durango City, serves as a logistical base for numerous precious metal mining ventures and exploration efforts.
Oaxaca
Oaxaca experiences significant community opposition to new mining projects, impacting investment viability. Securing a social license to operate is paramount, often surpassing formal government approvals for project continuity. Southern states frequently face organized resistance from local and indigenous communities over land and water use.
Chihuahua
Chihuahua faces intense competition for scarce water resources, particularly from mining operations and agricultural users. CONAGUA regulations govern water usage rights, creating social and legal hurdles for expansion. The northern region contains various polymetallic deposits, vital for industrial supply chains and future critical mineral exploration.
Mexico Mining Market Key Industry Players
Listed leaders compete with private specialists across operational scale and technological adoption in Mexico's mining sector. The industry bifurcates between sophisticated, high-yield producers and smaller, often traditional operators. Strategic archetypes include large-scale precious metal producers, industrial mineral suppliers, and exploration juniors. Operators pursue strategic partnerships and invest in cleaner extraction technologies to enhance efficiency and compliance.
Specialists in silver development and extraction include Santacruz Silver Mining and Discovery Silver. Santacruz Silver Mining leverages its extensive operational experience in established silver-producing regions within Mexico, focusing on optimizing existing assets. Discovery Silver, conversely, focuses on developing large-scale silver projects, emphasizing resource definition and engineering to attract significant investment. These entities represent distinct approaches to silver asset development, reflecting different stages of project maturity and operational focus within the competitive Mexican mining market.
| Leading Market Players |
|---|
| Discovery Silver |
| Lundin Gold |
| Heliostar Metals |
| G Mining Ventures |
| Graphite One |
| Santacruz Silver Mining |
| Rio2 |
| Altona Rare Earths |
| Ucore Rare Metals |
| Others |
Cost & Logistics Intelligence
PROFEPA's Clean Industry certification program gates supply qualification and influences price differentiation within Mexico's mining sector. This voluntary standard impacts how operators secure long-term contracts and access premium market segments, intertwining regulatory compliance with commercial strategy.
Pricing Analysis
Volume-based contracts and long-term offtake agreements define Mexico's mining pricing model, particularly for industrial minerals and base metals. Price differentiation stems from the quality grade of extracted ore and the PROFEPA Clean Industry certification status of the producer. Pricing softness stems from global commodity price volatility, particularly for precious metals. Large industrial consumers in the construction sector exhibit high price sensitivity, while specialized buyers in the metals industry show less sensitivity for high-purity silver and gold.
Supply Chain Analysis
Just-in-time inventory strategies dominate for industrial minerals like aggregates, while precious metals often involve strategic stockpiling to manage market fluctuations. The supply chain sources critical inputs like explosives and heavy machinery parts from international suppliers. Geographic supply concentration centers on states like Sonora, Zacatecas, and Durango, which are key production hubs. Logistics chokepoints due to deficient infrastructure in remote mining regions present a structural supply chain risk. Distribution runs through direct sales to industrial end-users or through commodity exchanges for precious metals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mexico Mining Market faces a critical shortage of advanced environmental engineering expertise, creating a capability gap across the sector. This scarcity impacts project development timelines and operational efficiency.
For Market Incumbents: Compound operational efficiencies by investing in digital twin technology for large-scale open-pit operations. Secure long-term community partnerships and prioritize social licenses to mitigate the growing threat of local opposition. Leverage PROFEPA Clean Industry certification as a lever for regulatory compliance and market differentiation against emerging environmental mandates from SEMARNAT.
For New Entrants and Emerging Players: PROFEPA's Clean Industry certification offers a fast-track for new entrants to gain social license and differentiate operations. Target critical mineral exploration for untapped lithium and copper deposits to align with global energy transition demand. Reprocessing legacy tailings sites presents a low-impact white-space opportunity. Focus go-to-market strategies on sustainable extraction technologies and formalized partnerships with small-scale artisanal miners.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across critical mineral exploration projects, driven by infrastructure development costs. Long-term viability hinges on navigating social license and regulatory complexity within Mexico's diverse regions. Seek acquisition targets among mid-cap operators with established community relations, strong environmental governance, and PROFEPA certifications. Sustained investment in water treatment technologies across arid regions serves as a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Water Treatment Technologies | SEMARNAT regulations compel mining operators to invest in cleaner water treatment technologies. |
| Formalize Artisanal Mining Partnerships | Integrating small-scale miners can unlock new ore sources and improve safety standards. |
| Develop Critical Mineral Deposits | Diversifying beyond precious metals addresses global demand for battery metals. |
| Reprocess Legacy Tailings Sites | Recovering valuable minerals from waste materials offers low-impact resource recovery. |
| Implement Digital Twin Systems | Automated mining systems optimize blast patterns and fleet management for copper operations. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and extensive secondary research. Primary research involved discussions with mining executives, environmental regulators (SEMARNAT, PROFEPA), community leaders, and investment analysts. Bottom-up market sizing from production data and top-down validation from economic indicators ensured robust estimates.
The forecasting window spans the projection horizon, integrating a multi-dimensional analytical framework. Segmentation dimensions modeled include product type, extraction method, end-user industry, technology, and regional production hubs across Mexico. Compound Annual Growth Rates were derived from historical data trends and future project pipelines. Global commodity prices and Mexican construction sector growth served as key forecast inputs.
Underlying assumptions cover stable regulatory enforcement and consistent mineral demand, with deviation risk concentrated in geopolitical shifts and community opposition. Forecasts reflect these assumptions, considering the dynamic nature of the mining sector. Revision becomes warranted when new mining legislation or significant changes in global commodity prices cross predefined thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
India Colored Gemstones Market
Metals & Minerals
Zinc Sulphate Market
Metals & Minerals
Saudi Arabia and GCC Ferrosilicon Market
Metals & Minerals
Gemstones Market
Metals & Minerals
Global Nickel Hydroxide Market
Metals & Minerals
Diamond Market
Metals & Minerals
Zinc Citrate Market
Metals & Minerals
Flake Graphite Market
Metals & Minerals
Zinc Sulfate Market
Metals & Minerals
Gregoryite Market
Metals & Minerals
Global Lithium Market
Metals & Minerals
Chromite Market
Metals & Minerals
Precious Metals E-Waste Recovery Market
Metals & Minerals
Global Mining Metals Market
Metals & Minerals
Coalingite Market
Metals & Minerals
Bauxite Market