
 Rare Earth Elements Market | 2026-2036
Rare Earth Elements Market Size, Share, and Industry Trends Forecast 2026-2036
Rare Earth Elements Market Intelligence
Battery-grade purity specifications for rare earth oxides is redrawing supplier hierarchies in downstream magnet manufacturing. Lynas Rare Earths Ltd leverages its Malaysian processing facility to sustain non-Chinese heavy rare earth output. MP Materials anchors domestic U.S. supply through its Mountain Pass mining and expanding Fort Worth magnet facility. China Rare Earth Group Resources Technology Co., Ltd. dominates integrated extraction-to-oxide refining across Inner Mongolia and Jiangxi provinces.
Rare earth elements comprise fifteen lanthanide metals plus scandium and yttrium, typically occurring at concentrations below 0.1% in bastnäsite and monazite ores and requiring solvent extraction or ion exchange to achieve 99.9% purity. Their primary commercial purpose centers on generating strong permanent magnetic fields, catalytic surface activity, and optical phosphorescence across industrial systems. Neodymium and dysprosium command premium positioning within magnet applications where coercivity and thermal stability determine performance thresholds. Catalyst-grade lanthanum and cerium occupy mature volume positions in petroleum refining and glass polishing, carrying thinner margin structures than magnet materials. The electronics and automotive end-user segments concentrate value capture, with defense and renewable energy procurement channels tightening qualification requirements.
China's Ministry of Industry and Information Technology governs production quotas and export licensing, while the EU Critical Raw Materials Act imposes domestic processing targets and strategic stockpile obligations on member states. The U.S. Department of Defense and Department of Energy coordinate offtake agreements and loan guarantees to accelerate Western rare earth separation capacity. Stakeholders must track how export control expansions and carbon-border adjustments alter feedstock economics for magnet and catalyst supply chains.
Market Dynamics
Magnet-grade rare earth supply chains are fragmenting as export licensing systems and carbon-border adjustments force end-users to qualify alternative processing sources outside traditional concentration zones.
Growth Catalysts
- EV Powertrain Demand:Permanent magnet synchronous motors in electric vehicle drivetrains consume neodymium-iron-boron alloys at volumes that outpace catalyst-grade applications, pulling separation capacity toward magnet feedstock specifications.
- EU Critical Raw Materials Act:Domestic processing targets and strategic stockpile obligations are redirecting European offtake toward non-Chinese oxide suppliers, creating qualified demand pools for emerging Western refiners.
- Defense Procurement Channels:U.S. Department of Defense loan guarantees for heavy rare earth separation are underwriting capacity expansion that commercial markets alone cannot finance.
Market Restraints
- Feedstock Concentration:Bastnäsite and monazite ore bodies amenable to solvent extraction concentrate in specific geologic formations, limiting viable mine development to a handful of jurisdictions.
- Processing Cost Structure:Ion exchange and solvent extraction circuits require sulfuric acid and organic reagents at scales where energy price volatility directly compresses oxide refining margins.
- Substitution Threat:Ferrite magnets and switched reluctance motor designs are capturing cost-sensitive automotive applications where thermal performance requirements permit reduced magnetic field strength.
Strategic Opportunities
- Australian Heavy Rare Earth Expansion:Dysprosium and terbium deposits in Western Australia remain underdeveloped relative to light rare earth reserves, presenting first-mover advantages for integrated mine-to-magnet projects.
- Recycling Infrastructure:End-of-life hard disk drives and wind turbine generators constitute an emerging feedstock channel that bypasses mining entirely, with hydrometallurgical recovery yields now exceeding 90 percent for neodymium.
- Japan-METI Stockpiling Mandate:Japanese government procurement of strategic rare earth reserves is creating guaranteed offtake for qualified non-Chinese suppliers, de-risking greenfield refinery investments.
Industry Challenges
- Separations Chemistry Expertise Gap:Solvent extraction circuit design and rare earth liquor purification require specialized metallurgical skills concentrated in a small cohort of practitioners, constraining workforce scaling for new facilities.
- Environmental Permitting Timelines:Radioactive thorium and uranium co-occurrence in monazite ores triggers extended licensing reviews under national radiation safety frameworks, stretching project development cycles.
- Magnet Manufacturer Qualification:Automotive Tier 1 suppliers impose 24-to-36-month validation protocols for new oxide sources, locking out nascent refiners from premium contract volumes regardless of technical compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rare Earth Elements Market |
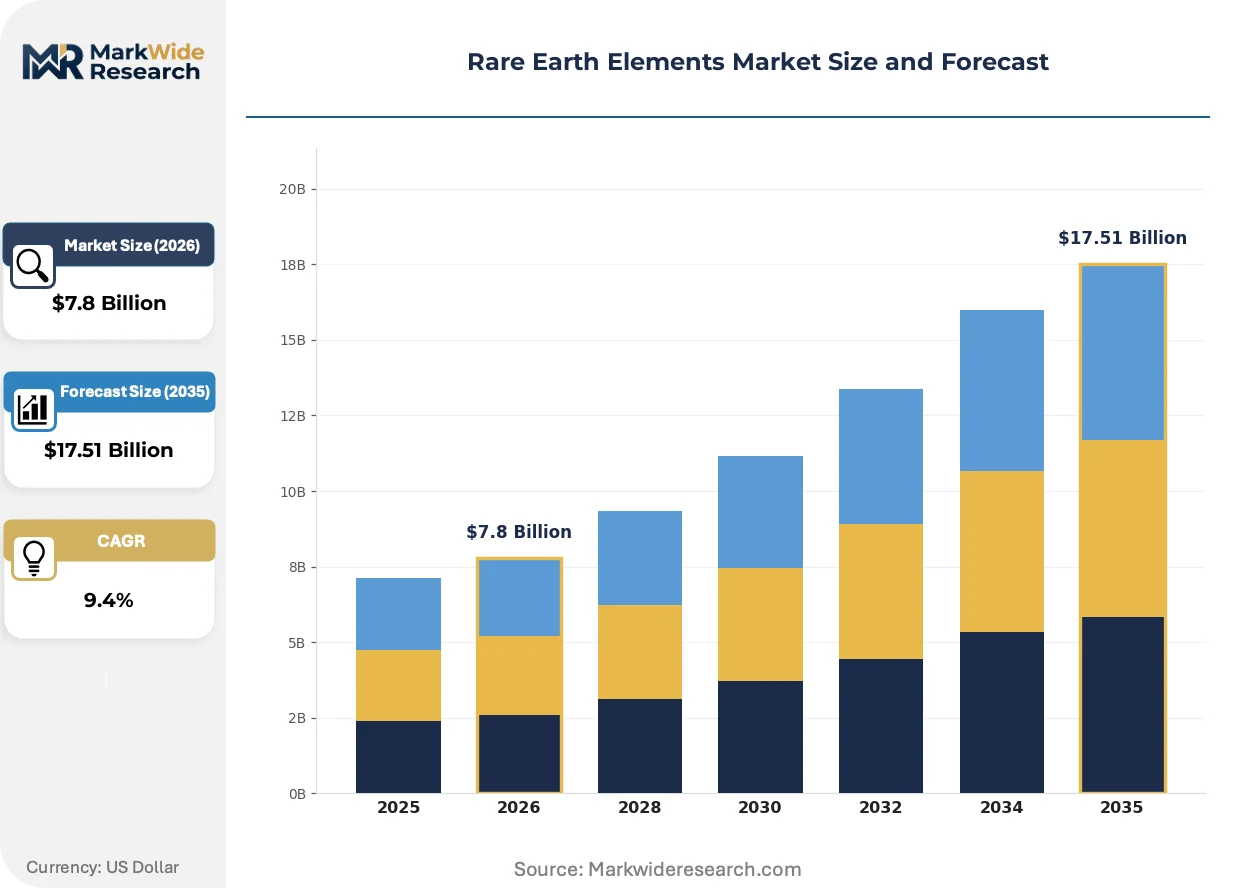
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $17.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neodymium, Dysprosium, Lanthanum, Cerium Application: Magnets, Catalysts, Phosphors, Glasses End User: Electronics, Automotive Industry, Defense, Renewable Energy Distribution Channel: Direct Sales, Distributors, Online Retail, Exporters |
| Companies Covered | China Rare Earth Group Resources Technology Co., Ltd., Lynas Rare Earths Ltd, MP Materials, Shenghe Resources Holding Co., Ltd., Iluka Resources Limited, China Northern Rare Earth Group High-Tech Co., Ltd., Arafura Resources Ltd, Australian Strategic Materials Ltd., Avalon Advanced Materials Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rare Earth Elements Market Strategic Shifts & Innovations
Processing technology and procurement specifications are diverging as end-users impose traceability requirements that legacy supply chains cannot satisfy without capital-intensive retrofit.
Bifurcation between heavy and light rare earth processing flows is accelerating as ion-adsorption clay deposits in southern China face depletion while bastnäsite operations in Mountain Pass and Mount Weld expand. Automotive magnet manufacturers are now specifying separate supply chain documentation for dysprosium versus neodymium origins. This divergence is bifurcating the merchant market into distinct heavy rare earth and light rare earth trading channels with non-overlapping price discovery mechanisms.
REACH authorization requirements for process chemicals are compelling European refiners to substitute traditional extractants with bio-based alternatives that maintain separation factors above 99.5 percent purity. The industrial consequence is elevated capital intensity for new EU-based facilities relative to legacy Asian operations. Catalyst-grade lanthanum and cerium producers are responding by consolidating solvent extraction trains to amortize compliance costs across higher throughput volumes.
Automotive OEMs are now mandating chain-of-custody certification from mine to magnet alloy, displacing spot-market oxide purchasing that obscures geographic origin. Tier 1 motor suppliers are consolidating qualified supplier lists to three-to-five approved refiners per element, compressing the viable vendor base. This concentration is most visible in German and South Korean electric vehicle supply chains, where battery and drivetrain procurement teams have merged rare earth qualification under unified sustainability audit protocols.
Rare Earth Elements Market Segmentation
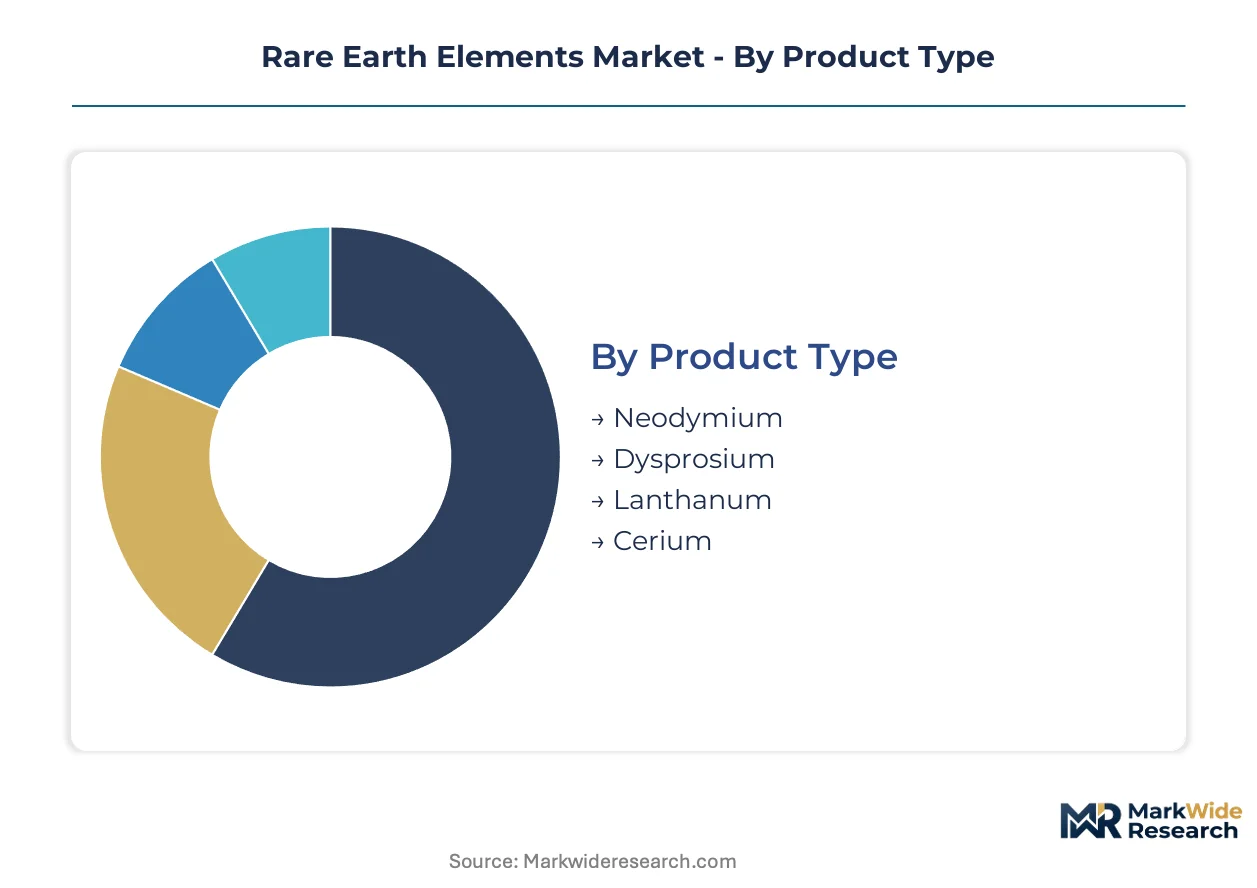
Rare earth element procurement patterns diverge sharply across product grades and end-use specifications, with magnet-grade oxides commanding qualification protocols that catalyst-grade materials bypass entirely. Segmentation reveals how automotive and defense procurement channels are consolidating supplier bases while electronics and renewable energy offtake retains more fragmented sourcing.
Product Type:
Domestic consumption patterns concentrate on light rare earths in China and the United States, while heavy rare earth trade flows remain overwhelmingly export-dependent from Chinese ion-adsorption clay operations to Japanese and European magnet manufacturers.
- Neodymium:Magnet-grade neodymium oxide specifies 99.5% purity with controlled praseodymium co-content for neodymium-iron-boron alloy production. German and South Korean automotive Tier 1 suppliers now mandate dual-source qualification outside China for this segment, driven by EU Critical Raw Materials Act domestic processing targets.
- Dysprosium:Heavy rare earth additions to sintered magnets enhance coercivity at elevated operating temperatures, with specifications requiring 0.5-12% dysprosium content depending on motor thermal load profiles. Japanese METI stockpiling mandates are absorbing Western Australian heavy rare earth pilot output before commercial magnet qualification completes.
- Lanthanum:Fluid catalytic cracking catalysts in petroleum refining consume lanthanum at mature volume scales with thinner margin structures than magnet materials.
- Cerium:Glass polishing and automotive catalytic converters represent established cerium applications with price discovery tied to light rare earth concentrate economics.
Neodymium holds the largest share; momentum sits with dysprosium as thermal stability requirements intensify in electric powertrain designs.
Application:
Cost tier stratification separates premium magnet alloys from commodity catalyst and glass formulations, with phosphor-grade materials occupying an intermediate position tied to display technology refresh cycles.
- Magnets:Neodymium-iron-boron and samarium-cobalt permanent magnets generate strong static magnetic fields for synchronous motors, generators, and magnetic resonance imaging systems. U.S. Department of Defense loan guarantees are underwriting heavy rare earth separation capacity specifically for this application tier.
- Catalysts:Lanthanum and cerium oxides drive petroleum refining fluid catalytic cracking and automotive exhaust emission control, with procurement volumes scaling with refinery throughput rather than technology substitution.
- Phosphors:Europium and terbium activated compounds produce red and green emission in LED and compact fluorescent lighting, facing demand pressure from quantum dot display technology displacement.
- Glasses:Cerium oxide polishing compounds and neodymium-doped laser glass serve specialized optical manufacturing with batch-scale procurement patterns distinct from continuous catalyst consumption.
Magnets command the steepest expansion trajectory; catalysts provide volume stability against technology disruption risks.
End User:
Customer type determines qualification intensity, with defense and automotive channels imposing 24-to-36-month validation protocols that electronics and renewable energy procurement has only recently begun adopting.
- Electronics:Hard disk drive voice coil motors, smartphone vibration mechanisms, and acoustic transducers consume neodymium-iron-boron alloys at specifications below automotive thermal thresholds. Japanese and Taiwanese contract manufacturers are consolidating qualified oxide supplier lists to three-to-five approved refiners per element.
- Automotive Industry:Permanent magnet synchronous motors in electric vehicle drivetrains specify separated heavy rare earth documentation with chain-of-custody certification from mine to magnet alloy. German OEM sustainability audit protocols have merged battery and drivetrain rare earth qualification under unified standards.
- Defense:Precision-guided munitions, radar systems, and satellite attitude control motors require ITAR-compliant rare earth supply chains with domestic U.S. or allied-nation provenance.
- Renewable Energy:Direct-drive wind turbine generators utilize multiple tons of neodymium-dysprosium-terbium alloys per unit, with end-of-life recovery infrastructure now exceeding 90% hydrometallurgical yields for neodymium.
Automotive Industry captures the fastest-growing demand pool; Defense maintains tightest supply chain security requirements.
Distribution Channel:
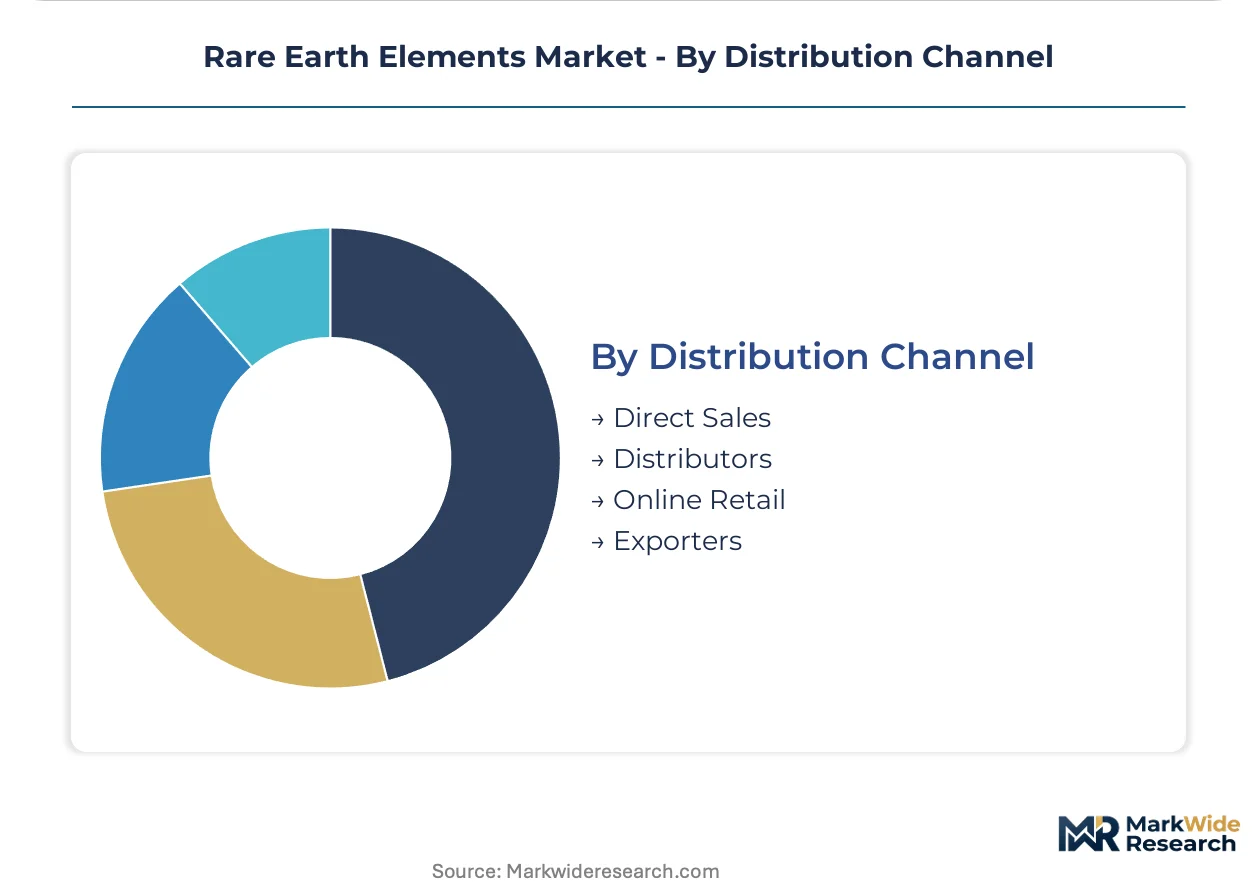
Supply concentration varies dramatically by channel, with direct sales relationships capturing magnet-grade volumes while distributors and exporters handle catalyst-grade commodity flows.
- Direct Sales:Long-term offtake agreements between integrated miners and magnet alloy producers dominate neodymium and dysprosium procurement, with pricing indexed to oxide purity specifications and delivery reliability metrics rather than spot market indices.
- Distributors:Merchant market trading of lanthanum and cerium oxides serves smaller catalyst manufacturers and glass polishers unable to meet minimum volume thresholds for direct refinery contracts.
- Online Retail:Specialty rare earth compounds and research-grade materials reach academic and industrial R&D laboratories through chemical supply house digital platforms.
- Exporters:China's Ministry of Industry and Information Technology export licensing system governs outbound rare earth shipments, with quota allocations favoring value-added magnet alloys over raw oxide exports.
Direct Sales holds the largest share; momentum sits with Exporters as Western separation capacity attempts to replicate Chinese integrated supply chain economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extraction and refining capacity concentrates in jurisdictions with permissive mining codes and established chemical processing infrastructure. China's Ministry of Industry and Information Technology governs production quotas across Inner Mongolia and Jiangxi. Western governments are underwriting alternative supply chains through defense procurement channels and strategic stockpile mandates.
China
Permanent magnet manufacturers in Ningbo and Shenzhen consume neodymium-iron-boron alloys at volumes exceeding domestic mine output. MIIT export licensing quotas favor value-added magnet alloys over raw oxide shipments. Bayan Obo in Inner Mongolia anchors light rare earth concentrate production, while ion-adsorption clay operations in southern Jiangxi province face depletion pressures.
United States
Defense contractors in California and Arizona require ITAR-compliant heavy rare earth supply chains for precision-guided munitions and satellite systems. The Department of Defense coordinates loan guarantees for domestic separation capacity expansion. Mountain Pass in California sustains bastnäsite mining, with Fort Worth, Texas hosting emerging magnet alloy fabrication.
Australia
Dysprosium and terbium deposits in Western Australia remain underdeveloped relative to light rare earth reserves at Mount Weld. The national critical minerals strategy prioritizes integrated mine-to-magnet project financing. Perth-based engineering firms are designing solvent extraction circuits for heavy rare earth pilot plants targeting Japanese offtake agreements.
Japan
Automotive Tier 1 suppliers in Nagoya and Tokyo impose 24-to-36-month validation protocols for new oxide sources. METI stockpiling mandates absorb Western Australian heavy rare earth output before commercial magnet qualification completes. The Kanto region concentrates magnet alloy producers serving Toyota and Honda electric powertrain programs.
Germany
BMW and Volkswagen procurement teams in Munich and Wolfsburg have merged battery and drivetrain rare earth qualification under unified sustainability audit protocols. The EU Critical Raw Materials Act imposes domestic processing targets and strategic stockpile obligations. Saxony-Anhalt is emerging as a candidate location for rare earth separation capacity serving Central European magnet manufacturers.
Rare Earth Elements Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the rare earth value chain. State-backed Chinese integrators command extraction-to-oxide refining economics through consolidated quota allocations. Western developers concentrate on magnet-grade separation and heavy rare earth recovery where defense procurement premiums offset higher processing costs. Competitive positioning hinges on securing qualified offtake from automotive Tier 1 suppliers and defense contractors rather than merchant market oxide trading. Capacity expansion and strategic partnerships dominate competitive moves, with greenfield projects requiring 5-to-7-year development timelines.
Among state-integrated Chinese producers, China Rare Earth Group Resources Technology Co., Ltd. and China Northern Rare Earth Group High-Tech Co., Ltd. exemplify the quota-controlled extraction archetype. Lynas Rare Earths Ltd and MP Materials occupy positions as Western-aligned refiners with qualified non-Chinese oxide output. Shenghe Resources Holding Co., Ltd. represents the trading-and-processing intermediary model bridging Chinese concentrate with international magnet alloy producers.
| Leading Market Players |
|---|
| China Rare Earth Group Resources Technology Co., Ltd. |
| Lynas Rare Earths Ltd |
| MP Materials |
| Shenghe Resources Holding Co., Ltd. |
| Iluka Resources Limited |
| China Northern Rare Earth Group High-Tech Co., Ltd. |
| Arafura Resources Ltd |
| Australian Strategic Materials Ltd. |
| Avalon Advanced Materials Inc. |
| Others |
Cost & Logistics Intelligence
Bayan Obo's light rare earth concentrate output anchors global scale economies that depress oxide price floors below Western separation costs. This capacity-utilization advantage concentrates pricing power in Chinese integrated refiners while forcing non-Chinese producers to seek defense procurement premiums to offset higher unit economics.
Pricing Analysis
MIIT export licensing dictates the pricing tier structure across magnet-grade and catalyst-grade oxide markets. Three-tier pricing structure across premium, standard, and economy levels separates ITAR-compliant defense offtake from automotive qualification-grade material and merchant-market catalyst flows. Pricing pressure stems from Japanese METI stockpiling absorption of Western Australian heavy rare earth pilot output before commercial magnet qualification completes. Catalyst manufacturers exhibit highest price sensitivity due to mature volume scales with thinner margin structures than magnet materials.
Supply Chain Analysis
Solvent extraction circuit expertise concentration in Inner Mongolia and Jiangxi provinces underwrites global rare earth oxide supply. Bastnäsite mining in California and Western Australia draws from sulfuric acid and organic reagent feedstocks whose energy-price volatility compresses refining margins. Single-source vulnerability concentrates in Chinese ion-adsorption clay depletion zones facing heavy rare earth output decline. Distribution runs through direct long-term offtake agreements between integrated miners and magnet alloy producers rather than spot-market trading.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rare earth elements sit in early-cycle expansion as permanent magnet synchronous motor penetration in electric vehicle drivetrains pulls separation capacity toward magnet feedstock specifications faster than Western refinery construction timelines.
For Market Incumbents: Compound qualification advantages by locking automotive Tier 1 suppliers into 24-to-36-month validation protocols that freeze out nascent refiners. Expand heavy rare earth separation capacity in Australia under Japanese METI stockpiling mandates before commercial magnet qualification completes. Vertical integration into Fort Worth magnet alloy fabrication secures defense procurement premiums against Chinese integrated cost structures. For New Entrants and Emerging Players: Recycling infrastructure gaps in end-of-life wind turbine generator recovery present white-space entry points that bypass mining entirely. Western Australian dysprosium and terbium deposits remain underdeveloped relative to light rare earth reserves, offering first-mover positioning for integrated mine-to-magnet projects. Hydrometallurgical recovery yields exceeding 90 percent for neodymium provide technical differentiation against virgin oxide competitors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among qualified non-Chinese oxide suppliers with locked automotive offtake agreements. Five-to-ten year viability favors Western-aligned refiners with defense procurement channels underwriting capacity expansion that commercial markets alone cannot finance. Monitor EU Critical Raw Materials Act domestic processing target compliance as inflection indicator for European offtake redirection.| Strategic Initiative | Industry Significance |
|---|---|
| Heavy Rare Earth Separation Capacity Expansion | Western Australian dysprosium output absorbs Japanese METI stockpiling mandates before commercial qualification. |
| Magnet Alloy Fabrication Integration | Fort Worth facility anchors domestic U.S. supply chain for ITAR-compliant defense procurement channels. |
| End-of-Life Recycling Infrastructure | Wind turbine generator recovery yields exceed 90 percent hydrometallurgical neodymium extraction. |
| Automotive Tier 1 Supplier Qualification | German OEM sustainability audit protocols merge battery and drivetrain rare earth certification under unified standards. |
| Defense Procurement Channel Lock-In | U.S. Department of Energy loan guarantees underwrite Western separation capacity expansion. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with magnet alloy producers, automotive Tier 1 procurement directors, defense contractor supply chain managers, and solvent extraction metallurgists. Secondary validation drew from MIIT production quota disclosures, EU Critical Raw Materials Act implementation guidance, U.S. Department of Defense offtake agreement announcements, and customs trade data. Bottom-up oxide volume modeling triangulated against top-down end-use demand aggregation from electric vehicle powertrain and wind turbine generator deployment.
Across the analysis window, forecasts segmented by magnet-grade versus catalyst-grade purity specifications, heavy versus light rare earth element categories, and defense-automotive-electronics end-user channels. CAGRs derived from regression analysis of permanent magnet synchronous motor adoption curves and renewable energy direct-drive generator deployment. Ion-adsorption clay depletion rates in southern China and bastnäsite expansion timelines at Mountain Pass and Mount Weld anchored supply-side constraints.
Forecasts assume regulatory continuity in MIIT export licensing and EU Critical Raw Materials Act domestic processing targets; material policy shifts would require re-modeling of trade flow redirection scenarios. Practitioners should keep alternative scenarios live as Japanese METI stockpiling mandate renewal terms and U.S. Department of Energy loan guarantee allocation priorities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Beryllium Hydroxide Market
Metals & Minerals
Prefab Iron Market
Metals & Minerals
Global Magnesium Oxide Market
Metals & Minerals
Metal and Metal Ores Market
Metals & Minerals
Steel Powder Market
Metals & Minerals
Cobalt Sulphate Market
Metals & Minerals
Andalusite Market
Metals & Minerals
Cobalt Nitrate Market
Metals & Minerals
Frac Sand Market
Metals & Minerals
Colored Gemstones Market
Metals & Minerals
US Coated Steel Market
Metals & Minerals
Rare Earth Elements Recycling Market
Metals & Minerals
Recycled Scrap Metal Market
Metals & Minerals
Middle-East and Africa Sodium Sulfide Market
Metals & Minerals
Pyroxenite Market
Metals & Minerals
Chromium Mining Market