
 European EV Battery Systems Market | 2026-2036
European EV Battery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
European EV Battery Systems Market Insights
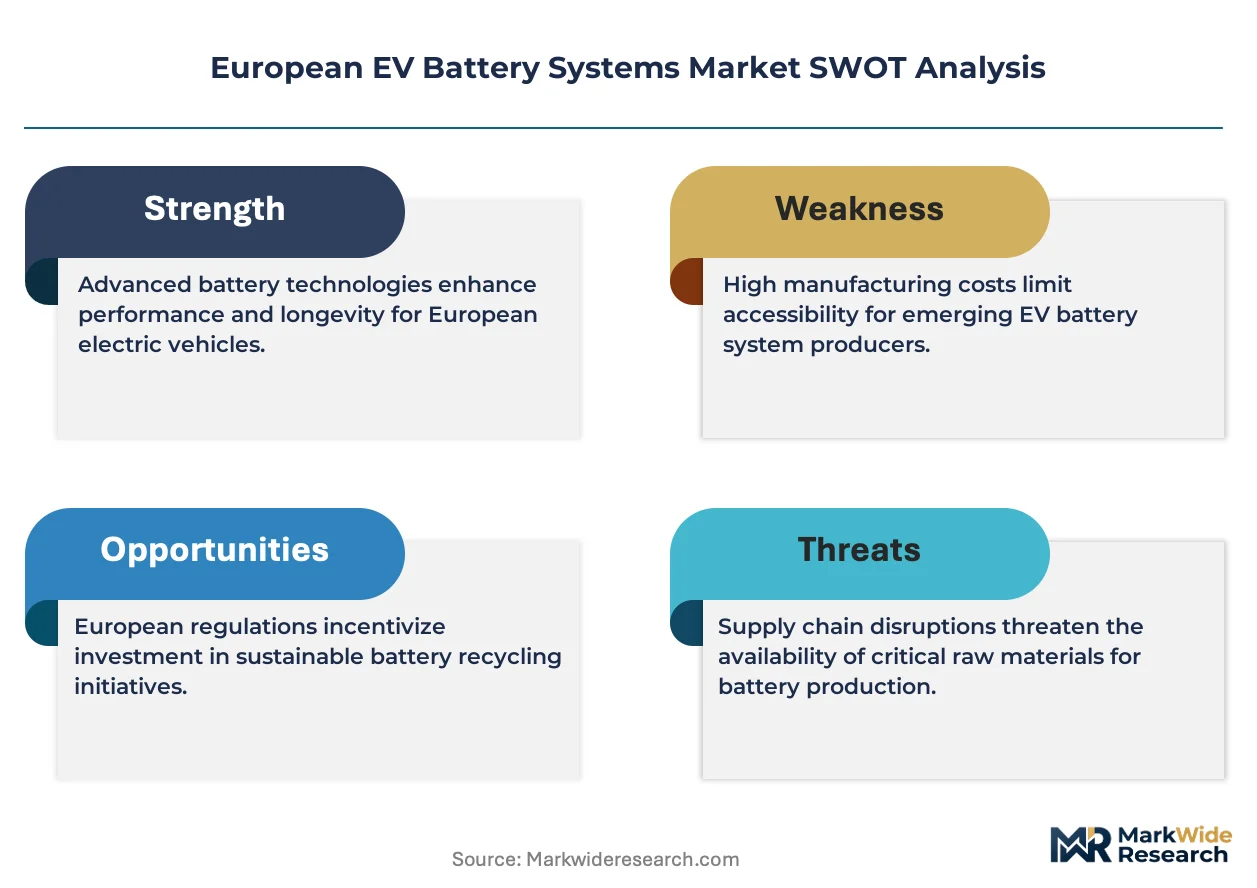
Automotive-grade cell certification is bifurcating the competitive landscape into qualified suppliers and aspirants. Northvolt leverages its Swedish gigafactory and renewable energy integration to anchor European sovereign supply. CATL sustains cost leadership through scale manufacturing in Hungary, while Samsung SDI differentiates via high-nickel chemistry specialization for premium German OEM platforms.
European EV battery systems encompass electrochemical energy storage modules engineered to deliver sustained voltage output, thermal stability across operational ranges, and cycle durability exceeding thousands of charge events. These systems integrate cell arrays, battery management electronics, and thermal regulation hardware to power electric drivetrains in passenger and commercial vehicles. Lithium-ion configurations currently dominate installed capacity, though solid-state architectures represent the fastest-growing technology segment as energy density thresholds advance. Fast charging infrastructure and battery management systems command concentrated R&D investment, while thermal management solutions protect margin pools as vehicle platforms migrate to 800-volt architectures.
The EU Battery Regulation, REACH chemical standards, and CE marking requirements collectively mandate carbon footprint disclosure, recycled material minimums, and supply chain due diligence across European manufacturing. EMA and national regulators in Germany, France, and Sweden enforce these frameworks through conformity assessment procedures that gate market access. Stakeholders must monitor evolving delegated acts under the EU Battery Regulation that will set binding performance criteria and recycling efficiency thresholds before the decade concludes.
Market Dynamics
Automotive-grade cell qualification under the EU Battery Regulation is concentrating procurement authority among certified suppliers while excluding uncertified aspirants from premium OEM platforms.
Growth Catalysts
- EU Battery Regulation recycled content mandates:Binding quotas for recovered lithium, cobalt, and nickel create guaranteed offtake for circular economy infrastructure investments across European manufacturing hubs.
- 800-volt platform proliferation:German luxury OEMs are engineering next-generation drivetrains around high-voltage architectures that demand advanced thermal management and silicon carbide power electronics integration.
- Gigafactory clustering in Hungary and Sweden:Concentrated capital deployment near renewable energy sources and automotive engineering centers shortens logistics loops and accelerates qualification timelines.
Market Restraints
- Refined lithium and nickel sulfate price volatility:Battery-grade chemical feedstock costs fluctuate with Indonesian nickel processing capacity and Chilean lithium brine expansion schedules, compressing cell producer margins.
- Single-source dependency for separator membranes:Korean and Japanese suppliers control the majority of ceramic-coated polyethylene separator production, creating supply vulnerability for European cell assembly.
- Solid-state electrolyte manufacturing scale limits:Sulfide and oxide ceramic electrolyte production remains constrained by dry-room infrastructure requirements and defect-rate challenges in continuous processing.
Strategic Opportunities
- Polish and Czech battery component ecosystems:Underdeveloped cathode active material and cell housing supply bases in Central European manufacturing corridors offer first-mover positioning for qualified suppliers.
- Second-life stationary storage applications:Retired automotive packs with diminished cycle performance retain residual capacity for grid balancing and industrial backup power, extending value extraction.
- CE marking and carbon footprint declaration services:Regulatory compliance complexity under delegated acts creates specialized advisory and verification revenue streams for technical consultancies.
Industry Challenges
- Electrochemical engineering talent scarcity:European universities produce insufficient doctoral-level specialists in solid-state ionics and battery interface science to staff expanding R&D centers.
- Automotive SPICE and ISO 26262 functional safety certification:Battery management system software qualification timelines extend 18-24 months, delaying platform integration and revenue recognition.
- Legacy 400-volt fleet interoperability:Mixed-voltage charging infrastructure creates customer confusion and stranded asset risk for early EV adopters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | European EV Battery Systems Market |
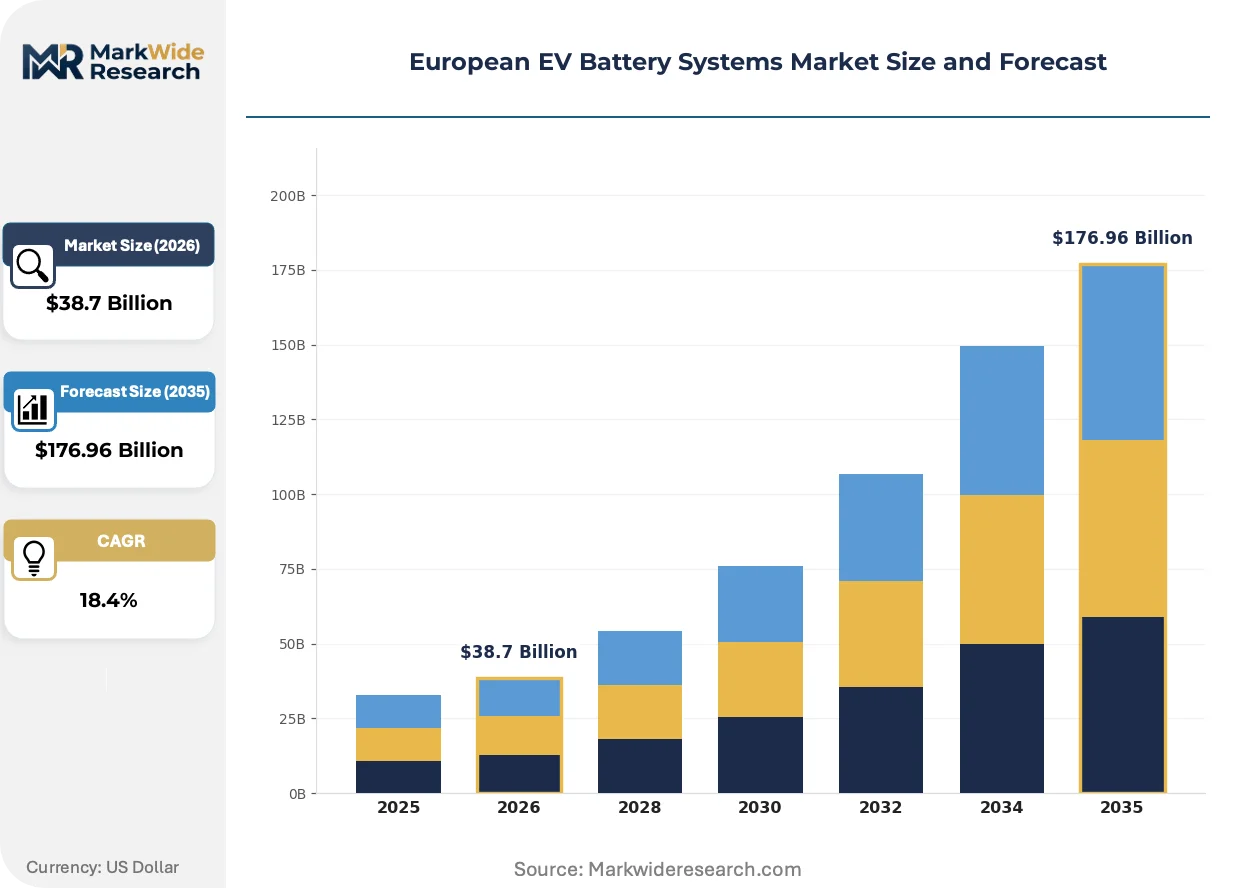
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $176.96 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Solid-State, Nickel-Metal Hydride, Lead-Acid End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, E-Bikes Technology: Fast Charging, Wireless Charging, Battery Management Systems, Thermal Management Installation: Manufacturing Facility, Aftermarket, Home Charging, Public Charging |
| Companies Covered | LG Energy Solution, Northvolt, CATL, Samsung SDI, Panasonic Holdings Corporation, BYD Company, Saft Groupe SA, Robert Bosch GmbH, Continental AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
European EV Battery Systems Market Trends and Innovations
Cell chemistry and system architecture are converging around energy density thresholds that enable platform simplification while regulatory pressure accelerates supply chain transparency requirements.
Silicon-dominant anode formulations are decomposing the graphite supply chain by replacing carbonaceous intercalation hosts with alloy-based lithium storage that delivers higher specific capacity. European cell producers are piloting silicon oxide and pre-lithiated silicon composites in premium cylindrical formats. This substitution is compressing incumbent graphite mining and spheronization investments while opening anode binder and electrolyte additive specialization.
Delegated acts under the EU Battery Regulation are mandating carbon footprint declarations and recycled content verification through third-party conformity assessment bodies. Cell producers must document lifecycle emissions from mining through manufacturing to qualify for CE marking and preferential procurement status. German and Swedish OEMs are responding by embedding supply chain due diligence into supplier qualification scorecards.
Fleet operators and energy utilities are consolidating procurement authority through long-term offtake agreements that bundle cell supply with second-life management and recycling services. This unbundles traditional component sales from lifecycle value capture and displaces spot-market purchasing in commercial vehicle and stationary storage applications. The shift is most visible in Nordic markets where municipal bus electrification and wind-storage hybrid projects dominate demand.
European EV Battery Systems Market Segmentation
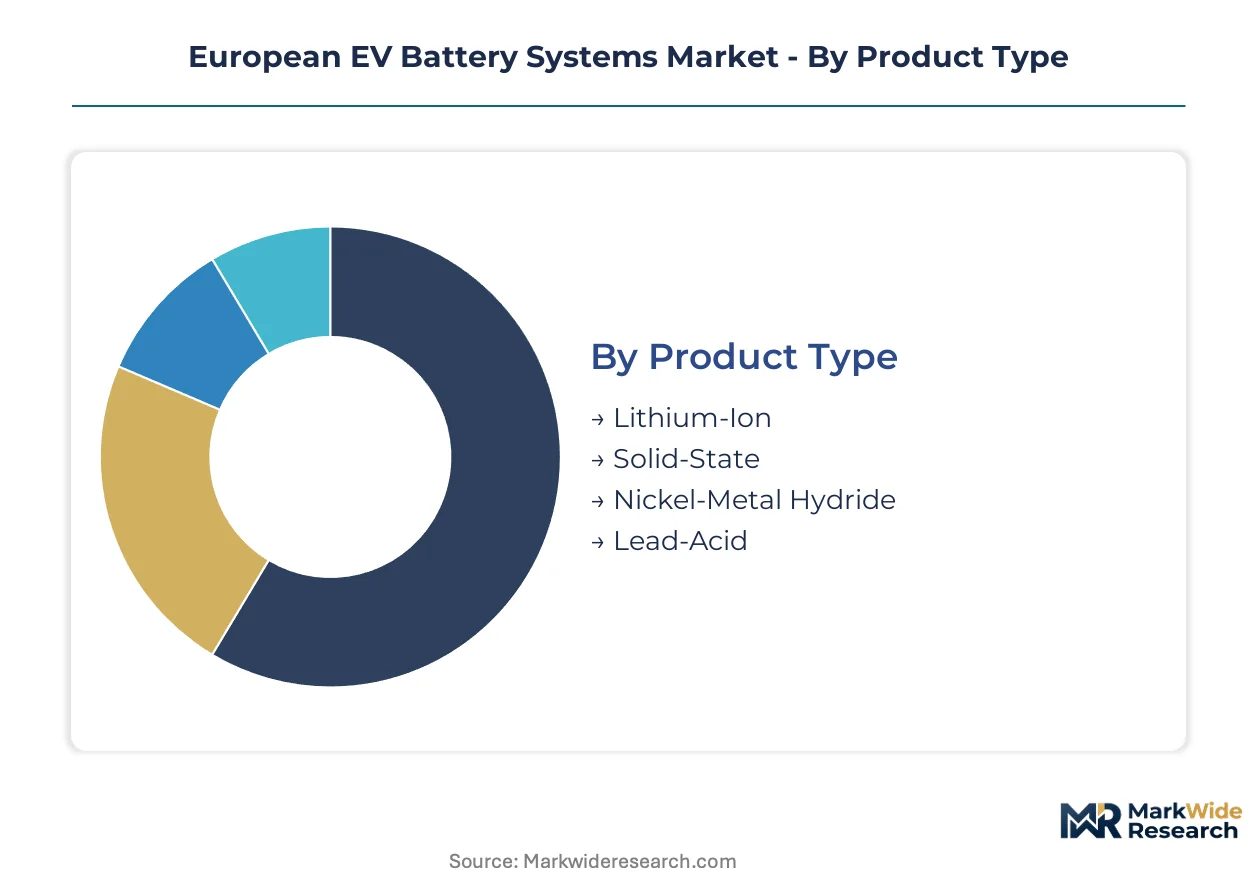
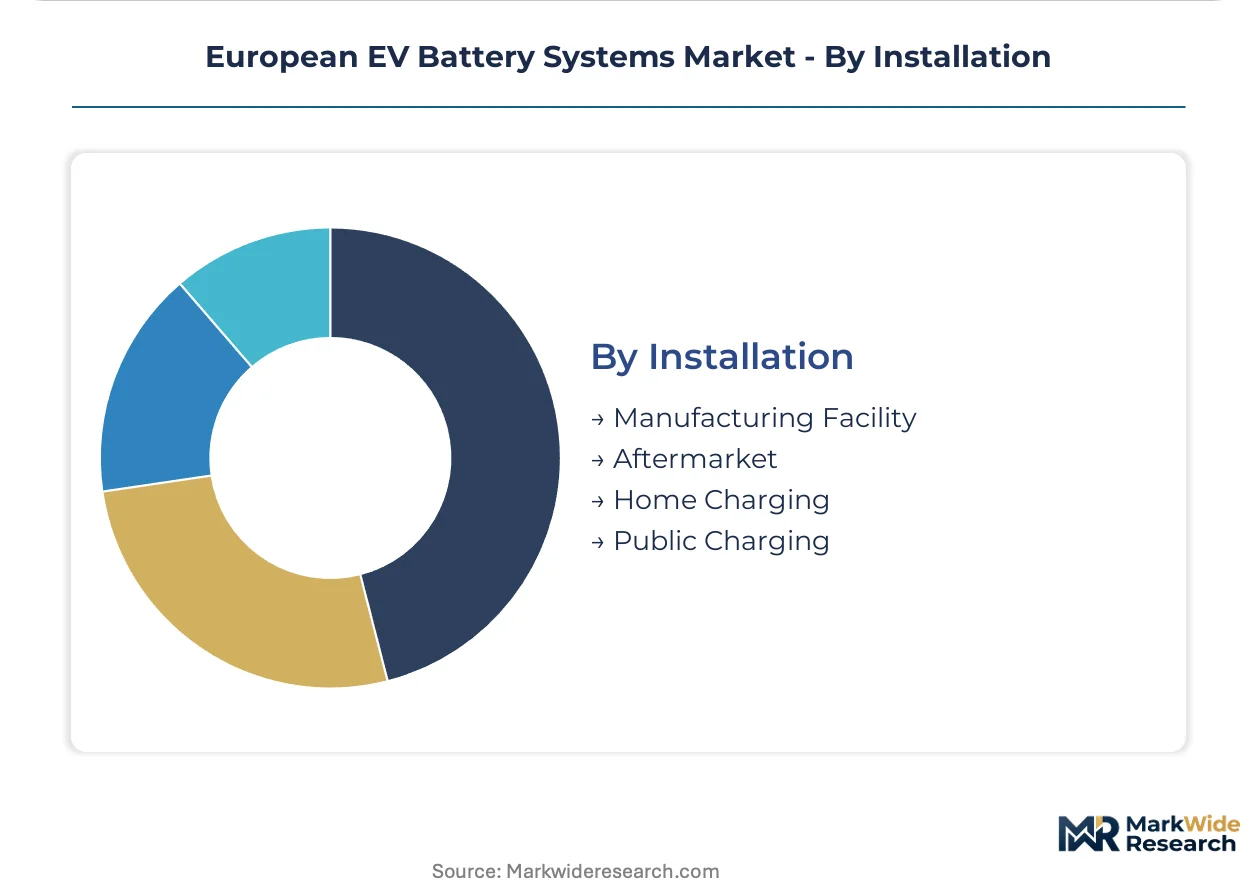
Segmentation in the European EV battery systems market reveals how regulatory mandates and platform electrification are concentrating procurement across specific chemistries and installation channels. Understanding these divisions exposes where substitution pressures and margin compression intersect with sovereign supply requirements.
Product Type:
Solid-state architectures pose the most acute substitution threat to incumbent lithium-ion formats as energy density thresholds advance and OEMs qualify next-generation platforms.
- Lithium-Ion:NMC and LFP configurations dominate installed capacity across German and Swedish OEM platforms, with cell-to-pack architectures reducing housing mass and simplifying thermal regulation. Demand concentrates in premium SUVs and sedans where 800-volt architectures require sustained voltage output and cycle durability exceeding thousands of charge events.
- Solid-State:Sulfide and oxide ceramic electrolyte designs deliver higher specific capacity and improved safety margins, though manufacturing scale remains constrained by dry-room infrastructure requirements. Pilot production lines in Germany and France are accelerating qualification timelines for luxury German OEM drivetrains.
- Nickel-Metal Hydride:Legacy chemistry retains niche presence in hybrid auxiliary power units and commercial vehicle starter applications where cost sensitivity outweighs energy density requirements.
- Lead-Acid:Constrained to low-voltage auxiliary systems and aftermarket replacement in legacy commercial fleets, facing displacement by lithium-ion as total cost of ownership equations shift.
Lithium-ion retains volume leadership; solid-state holds the steepest expansion curve.
End User:
Cost tier stratification separates premium passenger platforms from price-sensitive two-wheeler segments, with commercial vehicles occupying a mid-tier procurement position.
- Passenger Vehicles:German luxury OEMs anchor demand for high-nickel cylindrical formats and advanced battery management systems, with 800-volt platform proliferation driving thermal management specialization.
- Commercial Vehicles:Municipal bus electrification across Nordic markets and last-mile delivery van fleets in the Netherlands and Belgium are consolidating procurement through bundled cell supply and second-life management agreements.
- Two-Wheelers:Urban mobility schemes in Paris and Milan are standardizing swappable battery formats for scooter sharing, compressing margins through volume aggregation.
- E-Bikes:Bosch and Brose motor systems dominate integration, with battery packs sized for 400-500 watt-hour capacities and IP67 environmental sealing requirements.
Passenger vehicles command revenue concentration; commercial vehicles are climbing fastest in procurement volume.
Technology:
Application differentiation separates onboard power electronics from infrastructure-dependent charging modalities, with thermal management protecting margin pools across all voltage architectures.
- Fast Charging:Silicon carbide power electronics and liquid-cooled cable assemblies enable 350kW peak rates, with German OEMs engineering thermal derating algorithms to protect cell longevity during sustained high-current events.
- Battery Management Systems:ASIL-D functional safety certification under ISO 26262 extends software qualification timelines to 18-24 months, gating platform integration for uncertified suppliers.
- Thermal Management:Chiller-based and direct refrigerant systems protect cell arrays across operational temperature ranges, with demand intensifying as platforms migrate to 800-volt architectures.
- Wireless Charging:Inductive pad systems remain pilot-scale for fleet depot applications, with efficiency losses and alignment tolerances limiting passenger vehicle adoption.
Battery management systems anchor installed base value; fast charging infrastructure is expanding most quickly in capital deployment.
Installation:
Supply concentration in manufacturing facility integration contrasts with fragmented aftermarket and residential charging channels.
- Manufacturing Facility:Cell-to-pack and cell-to-chassis integration at Hungarian and Swedish gigafactories shortens logistics loops and accelerates qualification timelines for German OEM platforms.
- Public Charging:Ionity and Fastned networks are standardizing 800-volt compatible hardware across German autobahn corridors and Nordic highway infrastructure.
- Aftermarket:Replacement pack availability remains constrained by proprietary battery management system software locks and warranty voiding provisions.
- Home Charging:AC wallbox installations dominate residential segments, with smart grid integration requirements varying across German, French, and Italian utility territories.
Manufacturing facility integration retains value concentration; public charging infrastructure is gaining share fastest in deployment velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across the European EV battery systems market. Fleet operators in Southern Europe prioritize total cost of ownership, while German luxury OEMs absorb premium pricing for certified supply. Nordic markets balance sustainability premiums with scale procurement.
Germany
Bavarian and Baden-Württemberg OEMs anchor demand for high-nickel cylindrical formats and 800-volt platform integration. The KBA enforces type approval and battery safety certification under UN ECE R100. Cell-to-pack manufacturing concentrates in Lower Saxony near Volkswagen's Salzgitter engineering center.
Sweden
Northvolt's gigafactory in Skellefteå drives sovereign supply requirements for premium Scandinavian OEM platforms. The Swedish Chemicals Agency implements REACH compliance and carbon footprint verification under delegated EU Battery Regulation acts. Västerbotten County clusters renewable energy integration with dry-room cell assembly infrastructure.
Hungary
CATL's Debrecen facility and Samsung SDI's Goed investment position the country as the primary Asian cell manufacturing gateway into Europe. Hungarian investment promotion agencies coordinate state aid approvals under EU General Block Exemption Regulation. The Eastern region hosts cathode precursor chemical processing and module assembly corridors.
Poland
Underdeveloped cathode active material supply creates first-mover positioning for qualified component suppliers entering Central European manufacturing corridors. The Polish Office of Competition and Consumer Protection monitors state aid compliance for battery sector investments. Lower Silesia and Greater Poland voivodeships attract housing and thermal management component fabrication.
France
Automotive electrification mandates under the French Climate and Resilience Law accelerate demand for certified cell supply. ANSM and environmental regulators enforce chemical safety and end-of-life battery traceability requirements. The Hauts-de-France region hosts pilot solid-state electrolyte production lines for luxury OEM qualification programs.
European EV Battery Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European EV battery systems market. The vendor base separates into three tiers: Asian scale manufacturers with established European production, European sovereign suppliers leveraging renewable energy integration, and diversified industrial conglomerates with automotive electronics heritage. Consolidation pressure intensifies as automotive-grade cell qualification under EU Battery Regulation gates market access. Dominant competitive moves include gigafactory capacity expansion in Hungary and Sweden, and strategic partnerships binding cell supply with second-life management services.
Among Asian scale manufacturers, LG Energy Solution and CATL exemplify the cost-leadership archetype through Hungarian manufacturing footprints. Northvolt occupies a distinct position as the European sovereign supply anchor. Panasonic Holdings Corporation represents the diversified technology-licensing tier with established automotive customer relationships.
| Leading Market Players |
|---|
| LG Energy Solution |
| Northvolt |
| CATL |
| Samsung SDI |
| Panasonic Holdings Corporation |
| BYD Company |
| Saft Groupe SA |
| Robert Bosch GmbH |
| Continental AG |
| Others |
Pricing and Supply Chain Analysis
Ninety-day cathode active material lead times from South Korean precursor plants concentrate procurement leverage among qualified cell producers, compressing margin capture for uncertified aspirants while amplifying pricing power for Northvolt and CATL's Hungarian operations under long-term offtake structures.
Pricing Analysis
Second-life battery management and recycling service bundling drives lifetime value expansion beyond cell hardware sales. Contract-based long-term offtake agreements dominate, with pricing stratifying across automotive-grade certification tiers, volume scale commitments, and carbon footprint declaration status. Cost compression in LFP cylindrical formats intensifies as CATL scales Debrecen output, while German luxury OEMs absorb premium pricing for high-nickel certified supply. Municipal fleet operators exhibit acute price sensitivity; sovereign supply seekers show elasticity.
Supply Chain Analysis
Ceramic-coated polyethylene separator supply from South Korean and Japanese manufacturers creates single-source vulnerability for European cell assembly. China, South Korea, and Indonesia anchor refined lithium hydroxide and nickel sulfate feedstock, with Indonesian processing capacity expansion schedules feeding volatility. Tariff exposure on Chinese graphite anode materials is intensifying. Distribution runs through Hungarian and Swedish gigafactory direct integration with German OEM platform engineering centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European EV battery systems sit in early-cycle expansion as 800-volt platform proliferation accelerates OEM procurement timelines and sovereign supply mandates concentrate demand among qualified producers.
For Market Incumbents: Fortify automotive-grade cell certification under EU Battery Regulation delegated acts to exclude uncertified competitors from premium German OEM platforms. Accelerate dry-room infrastructure expansion in Sweden and Hungary to capture solid-state pilot production scale. Vertical integration into cathode active material precursor processing defends margin position against Korean and Japanese separator membrane supply constraints.
For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Germany and France opens procurement access for Polish and Czech component ecosystem suppliers. Polish cathode housing fabrication and Czech thermal management hardware production represent penetrable white-space corridors. Target municipal bus electrification tenders in Nordic markets with bundled cell supply and second-life management service offerings.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because EU Battery Regulation enforcement gates market access and concentrates procurement authority among certified suppliers. Acquisition targets center on solid-state electrolyte pilot producers with German OEM qualification relationships and carbon footprint verification service providers. Monitor delegated act implementation timelines as inflection signals for preferential procurement status shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Automotive-Grade Cell Certification Investment | EU Battery Regulation compliance gates CE marking access for German OEM supply contracts. |
| Gigafactory Capacity Expansion | Hungarian and Swedish manufacturing footprints shorten logistics loops to European automotive engineering centers. |
| Second-Life Battery Management Service Launch | Stationary storage applications extend value extraction from retired automotive packs in Nordic wind-storage hybrids. |
| Solid-State Electrolyte Pilot Production Scale-Up | Sulfide and oxide ceramic manufacturing advances energy density thresholds for luxury German OEM platforms. |
| Carbon Footprint Declaration Service Development | Third-party conformity assessment creates specialized advisory revenue under delegated EU Battery Regulation acts. |
Research Methodology
Desk research of EU regulatory filings, automotive production databases, and cathode chemical trade data preceded structured interviews with OEM platform engineers, Tier 1 battery procurement directors, gigafactory operations managers, and notified body certification specialists. Primary fieldwork captured qualification timeline dynamics, certification cost structures, and solid-state manufacturing scale constraints. Secondary validation drew from ECHA REACH substance registrations, KBA type approval documentation, and IHS Markit vehicle electrification forecasts. Bottom-up cell capacity buildouts and top-down OEM procurement projections were triangulated.
Variance decomposition across chemistry format, vehicle class, and installation channel shaped the analytical framework throughout the projection horizon. Segmentation dimensions modeled encompass lithium-ion and solid-state product architectures, passenger and commercial vehicle end-use applications, fast charging and thermal management technology tiers, and manufacturing facility versus aftermarket installation channels. CAGRs were derived from production capacity ramp schedules correlated with OEM platform launch timelines and regulatory mandate phase-in dates. Forecast inputs incorporated dry-room infrastructure buildout pace and separator membrane supply availability.
Underlying assumptions cover sustained EU Battery Regulation enforcement, continued German luxury OEM 800-volt platform commitments, and Indonesian nickel processing capacity expansion, with deviation risk concentrated in solid-state electrolyte defect-rate improvements and lithium brine extraction license delays. Practitioners should keep alternative scenarios live as delegated act implementation timelines and Chinese graphite export restriction policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Europe Electric Vehicle Battery Market
EV Batteries
Canada Electric Vehicle Battery Manufacturing Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Market
EV Batteries
Spain Rechargeable Battery Market
EV Batteries
Electric Vehicle Traction Batteries Market
EV Batteries
South America Electric Vehicle VRLA Batteries Market
EV Batteries
Electric Vehicle Battery Thermal Management Systems Market
EV Batteries
North America Electric Vehicle VRLA Batteries Market
EV Batteries
Middle-East Electric Vehicle Battery Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Market
EV Batteries
North America Electric Vehicle Battery Anode Market
EV Batteries
United States Electric Vehicle Battery Anode Market
EV Batteries
Thermal Interface Material for EV Battery Market
EV Batteries
EV Battery Heating System Market
EV Batteries
Asia-Pacific Electric Vehicle Solid State Battery Market