
 South America Electric Vehicle Battery Manufacturing Equipment Market | 2026-2036
South America Electric Vehicle Battery Manufacturing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
South America Electric Vehicle Battery Manufacturing Equipment Market Insights
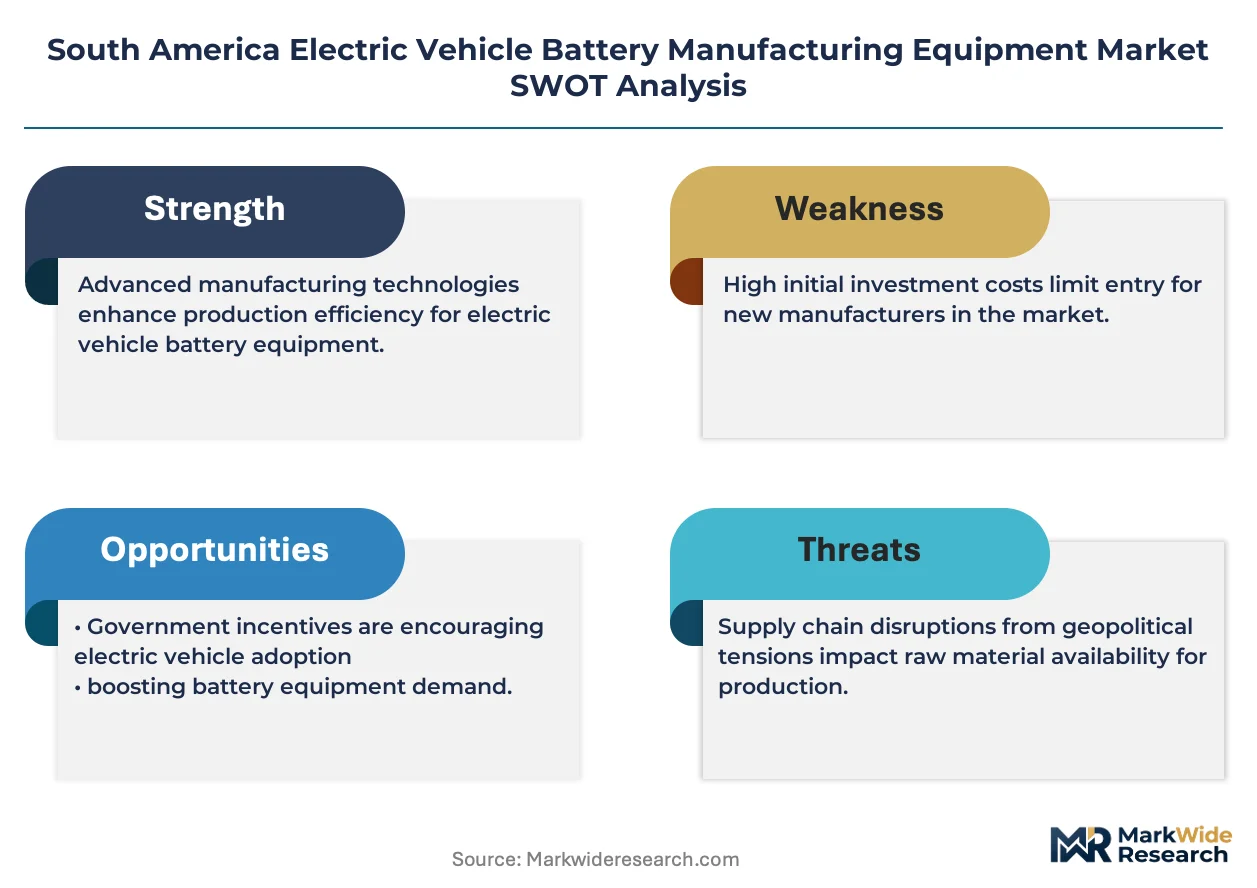
High-precision automation tiers are rotating toward South American EV battery factories as OEMs demand equipment capable of sub-10-micron electrode alignment. Schuler AG leverages its press-line heritage to dominate heavy-gauge cell housing fabrication. Xiamen Tmax Battery Equipments Limited anchors the mid-market with modular cell assembler platforms optimized for regional voltage standards. Hitachi High-Tech Corporation differentiates through in-house vision systems that sustain yield rates under variable plant conditions.
South America electric vehicle battery manufacturing equipment encompasses machinery for electrode coating, cell stacking, electrolyte filling, formation cycling, and module assembly, with formation testers typically operating at voltage ranges between 3.0V and 4.5V per cell to validate lithium-ion electrochemical performance. Cell Assemblers capture the dominant margin pool because stack precision directly determines cycle life and thermal stability in finished packs. Module Production Lines represent the fastest-growing segment as Brazilian and Argentine factories prioritize localized pack integration over imported finished modules. Filling Machines retain structural importance despite slower growth, since electrolyte dosing accuracy remains a yield-critical bottleneck across all chemistry platforms.
ANVISA certification requirements for industrial equipment safety and Brazil's INMETRO efficiency labeling rules shape import compliance costs and local assembly incentives. Argentina's Secretariat of Mining coordinates lithium supply chain policies that indirectly govern equipment placement near Salta-Jujuy processing corridors. Stakeholders must monitor how Chile's environmental permitting timelines for cathode plants redistribute equipment demand northward along the Andean lithium triangle.
Market Dynamics
Brazilian OEMs are consolidating cathode active material sourcing through captive partnerships, redirecting equipment procurement toward integrated coating and calendaring lines that match imported cell specifications.
Growth Catalysts
- INMETRO efficiency mandates:Brazil's labeling rules for industrial machinery accelerate replacement of legacy formation testers with energy-recovery cycling systems.
- Lithium hydroxide conversion corridors:Argentine processing investments in Salta-Jujuy concentrate demand for high-temperature sintering equipment near feedstock sources.
- Cell-to-pack architectures:Structural battery designs eliminate module assembly steps, compressing equipment footprints and reducing factory CAPEX per GWh.
Market Restraints
- Electrolyte salt supply concentration:LiPF6 precursor dependence on Chinese chemical processors exposes Argentine and Brazilian factories to freight cost volatility and customs delays.
- ANVISA equipment certification timelines:Safety validation protocols for high-voltage formation systems extend import clearance by four to eight months, freezing project schedules.
- Dry electrode technical immaturity:Binder-free coating processes remain below commercial yield thresholds, locking regional factories into solvent-based wet coating CAPEX.
Strategic Opportunities
- Colombian assembly greenfield sites:Bogotá's free trade zone incentives and Pacific port access position the country for Korean and Japanese equipment vendor entry.
- Solid-state pilot line demand:Sulfide electrolyte handling requirements create first-mover openings for hermetic glovebox and thin-film deposition specialists.
- Second-life battery disassembly equipment:Brazilian energy storage integrators seek automated module dismantling systems to recover cells from end-of-life automotive packs.
Industry Challenges
- Automation engineering skill scarcity:Regional technical institutes produce insufficient mechatronics graduates to program and maintain vision-guided stacking robots at scale.
- Multi-chemistry line reconfiguration:Brazilian contract manufacturers face downtime losses when switching equipment between LFP and NMC cell formats for different OEM customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Electric Vehicle Battery Manufacturing Equipment Market |
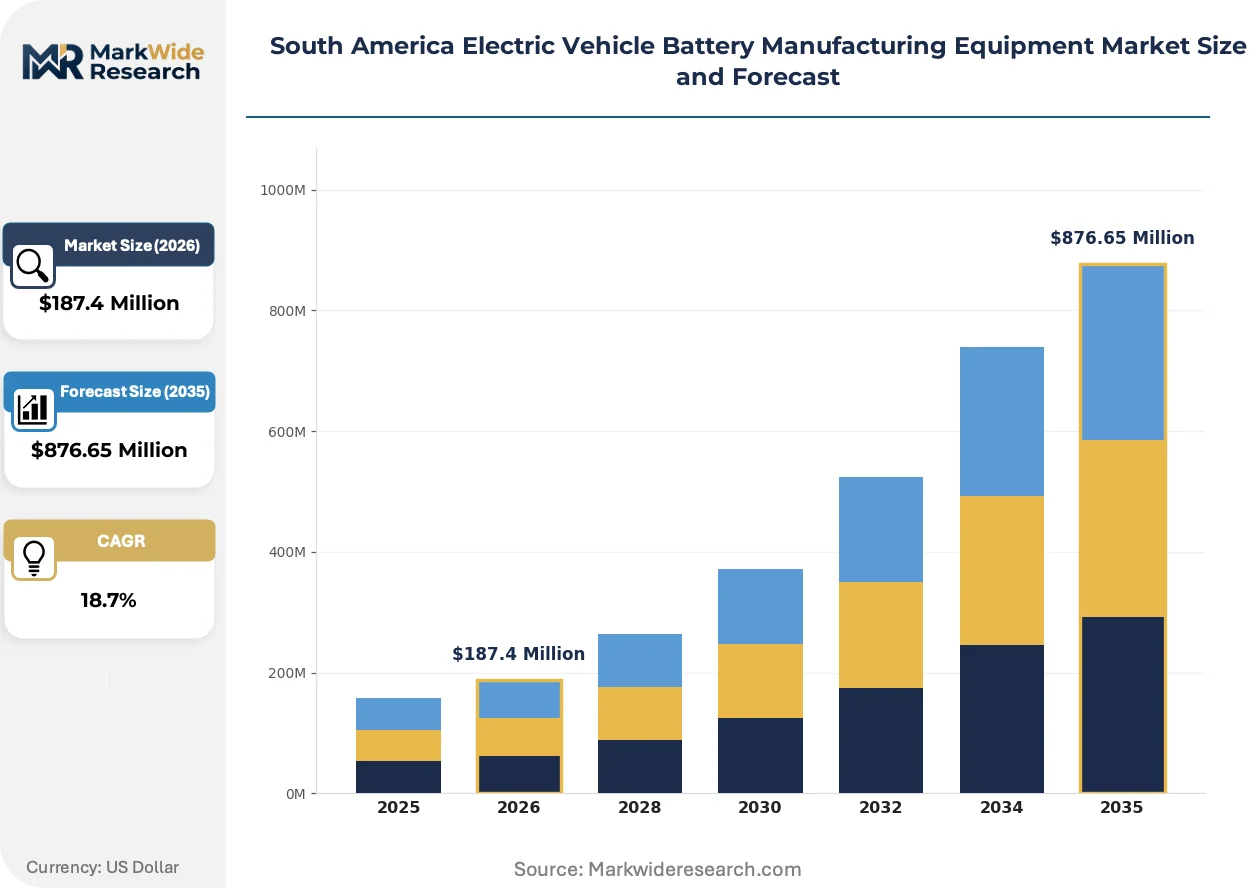
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cell Assemblers, Battery Testers, Filling Machines, Module Production Lines Technology: Lithium-ion, Solid State, Nickel-Metal Hydride, Lead Acid End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Research Institutions Application: Electric Vehicles, Energy Storage Systems, Consumer Electronics, Others |
| Companies Covered | Duerr AG, Schuler AG, Hitachi Ltd., Xiamen Tmax Battery Equipments Limited, ACEY New Energy Technology, Hitachi High-Tech Corporation, Dürr Group, Lead Intelligent Equipment, Panasonic Corporation, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Electric Vehicle Battery Manufacturing Equipment Market Trends and Innovations
Equipment architectures are converging around platform designs that accommodate chemistry transitions without full line replacement, reflecting uncertainty in cathode material procurement strategies.
High-speed laser notching systems for electrode tab formation are fragmenting the mechanical die-cutting installed base. Brazilian cell producers are piloting fiber laser platforms that eliminate tool wear and enable real-time edge quality feedback. The shift is compressing maintenance staffing ratios while raising capital intensity per electrode line.
ANVISA's updated industrial electrical safety protocols now mandate arc fault detection on formation circuits above 60VDC. Equipment vendors are integrating insulated-gate bipolar transistor protection modules that trip within 2 milliseconds of fault detection. Argentine factories in the Puna region face the steepest compliance costs due to remote service access limitations.
Fleet operators and energy storage developers in São Paulo and Buenos Aires are unbundling equipment procurement from turnkey EPC contracts. Direct purchasing of formation testers and electrolyte fillers through distributor channels is displacing integrator-mediated sourcing. The pattern concentrates price pressure on mid-tier European and Asian equipment exporters while favoring regional technical service partnerships.
South America Electric Vehicle Battery Manufacturing Equipment Market Segmentation
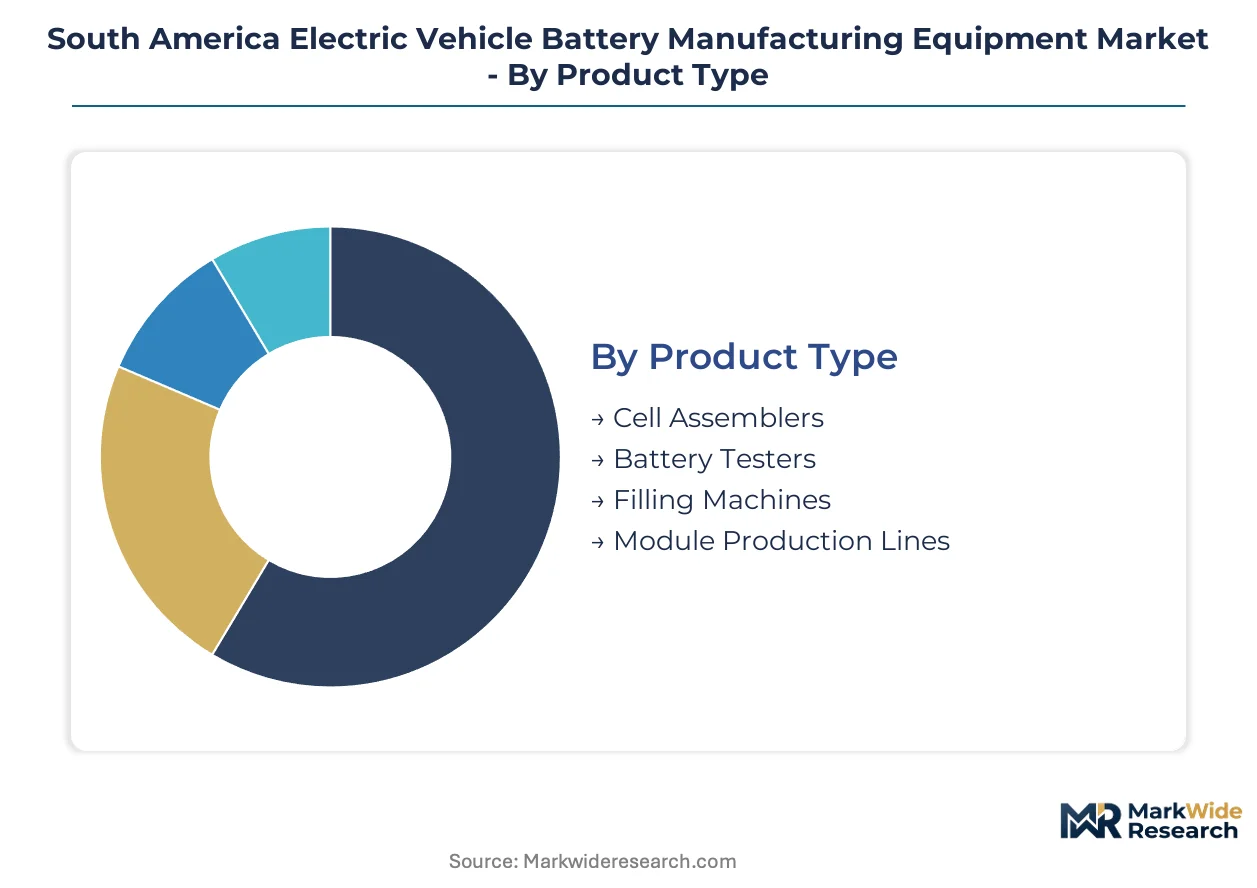
Equipment procurement patterns across South America diverge sharply between Brazilian OEMs building captive cell capacity and Argentine lithium processors seeking modular pilot lines. Segmentation reveals how cathode chemistry uncertainty and regulatory fragmentation reshape capital allocation priorities.
Product Type:
Brazilian factories concentrate demand on integrated coating-to-formation lines, while Argentine Puna corridor investments favor standalone cell assembly equipment for lithium hydroxide integration.
- Cell Assemblers:Stacking and winding systems achieve electrode alignment precision below 10 microns, critical for cycle life in NMC cells. Brazilian OEMs in São Paulo state deploy these at scale for LFP-NMC flexible lines, though ANVISA certification delays extend commissioning schedules. Cell Assemblers hold the largest share; momentum sits with Module Production Lines.
- Module Production Lines:Automated welding and thermal interface material dispensing systems enable localized pack integration, displacing imported finished modules. Argentine Salta-Jujuy processors prioritize these for grid-storage off-take contracts tied to lithium hydroxide supply.
- Battery Testers:Formation cycling systems with energy recovery operate at 3.0V to 4.5V per cell, validating electrochemical performance under INMETRO efficiency mandates.
- Filling Machines:Hermetic electrolyte dosing equipment maintains yield-critical precision across LFP, NMC, and emerging sodium-ion chemistries.
Cell Assemblers hold the largest share; momentum sits with Module Production Lines.
Technology:
Cost tiers stratify around cathode material procurement risk, with dry electrode immaturity locking regional factories into wet coating CAPEX for lithium-ion platforms.
- Lithium-ion:Dominant wet coating and calendaring infrastructure supports LFP and NMC formats, with Brazilian contract manufacturers absorbing downtime losses during chemistry switches. Argentine lithium carbonate and hydroxide conversion corridors anchor feedstock-adjacent cell production.
- Solid State:Sulfide electrolyte handling demands hermetic glovebox and thin-film deposition equipment, creating first-mover openings for specialized vendors in Colombian greenfield sites. Solid State is gaining share fastest; established volume remains with Lithium-ion.
- Nickel-Metal Hydride:Legacy hybrid vehicle tooling persists in Brazilian aftermarket refurbishment operations.
- Lead Acid:Stationary energy storage and industrial forklift applications sustain limited regional demand for formation and assembly equipment.
Lithium-ion dominates installed capacity; Solid State is gaining share fastest.
End User:
Procurement authority is shifting from integrator-mediated EPC contracts toward direct equipment purchasing through distributor channels.
- OEMs:Brazilian automakers consolidate cathode active material sourcing through captive partnerships, redirecting equipment procurement toward integrated coating lines matching imported cell specifications. OEMs command the largest procurement volumes; Aftermarket Providers show steepest expansion trajectory.
- Tier-1 Suppliers:Contract manufacturers face automation engineering skill scarcity when programming vision-guided stacking robots for multi-OEM programs.
- Aftermarket Providers:São Paulo and Buenos Aires fleet operators seek automated module dismantling systems for second-life battery recovery, unbundling procurement from turnkey contracts.
- Research Institutions:Argentine and Chilean universities pilot solid-state and sodium-ion lines with government mining secretariat coordination.
OEMs command the largest procurement volumes; Aftermarket Providers show steepest expansion trajectory.
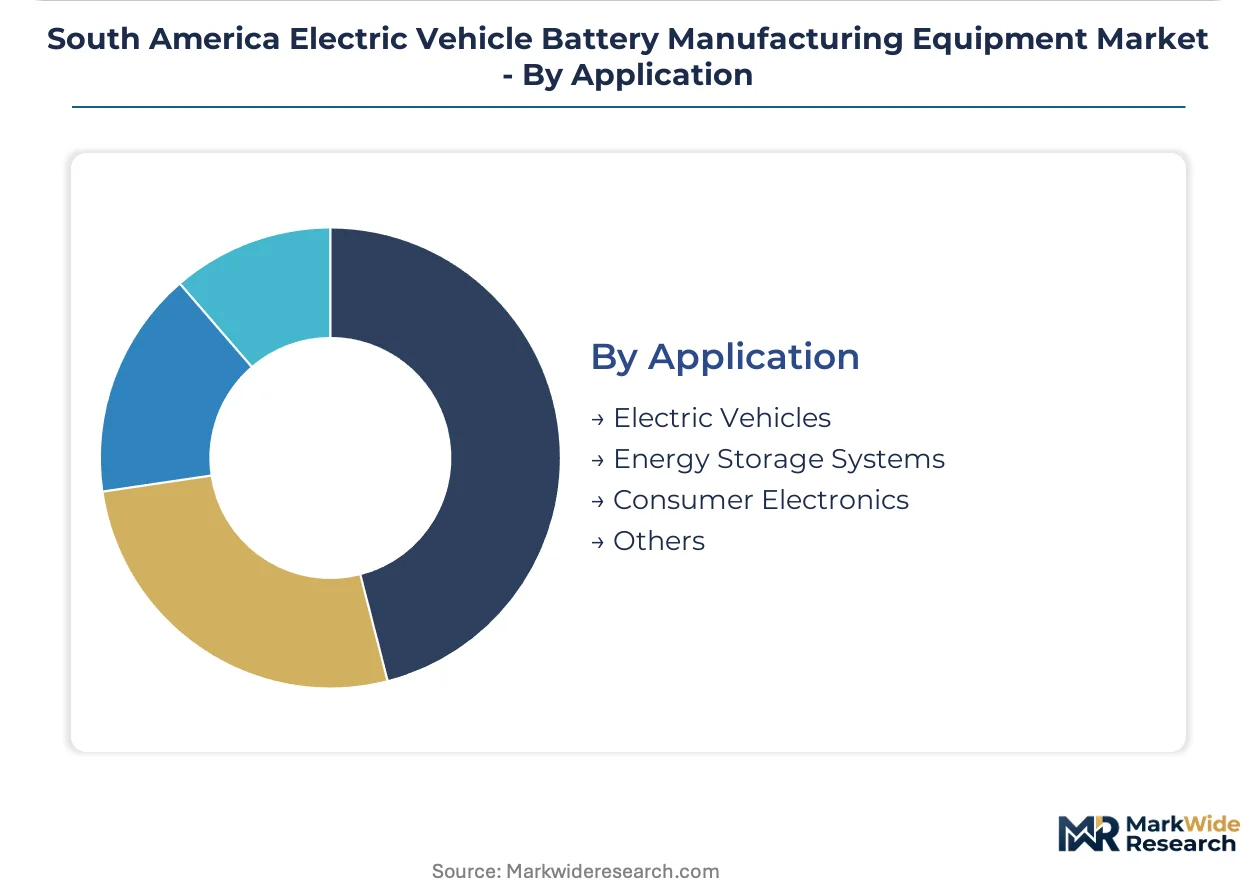
Application:
Demand concentration follows lithium supply chain geography, with Salta-Jujuy processing corridors anchoring energy storage equipment placement.
- Electric Vehicles:Brazilian OEM assembly lines drive formation tester and cell stacker demand, with cell-to-pack architectures compressing factory footprints and reducing CAPEX per GWh. Electric Vehicles anchor the largest application share; Energy Storage Systems are climbing fastest.
- Energy Storage Systems:Grid-scale integrators in Buenos Aires and Santiago procure module production lines for lithium iron phosphate packs, leveraging Argentine lithium hydroxide conversion capacity.
- Consumer Electronics:Limited regional demand for cylindrical cell equipment serves Brazilian electronics assemblers.
- Others:Industrial forklift and marine propulsion applications sustain niche formation and module welding equipment requirements.
Electric Vehicles anchor the largest application share; Energy Storage Systems are climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentine lithium hydroxide corridors and Brazilian OEM assembly lines concentrate equipment demand across distinct supply chain nodes. ANVISA certification protocols and mining secretariat policies reshape capital placement timelines in each jurisdiction.
Brazil
São Paulo state OEMs deploy integrated coating-to-formation lines for LFP-NMC flexible manufacturing. ANVISA industrial electrical safety mandates extend formation system commissioning by four to eight months. Campinas and São Bernardo do Campo clusters anchor cell-to-pack architecture adoption, compressing factory footprints per GWh.
Argentina
Salta-Jujuy lithium hydroxide conversion investments concentrate demand for high-temperature sintering and standalone cell assembly equipment. The Secretariat of Mining coordinates supply chain policies governing equipment placement near Puna region processing corridors. Argentine universities pilot solid-state lines with government mining secretariat backing.
Chile
Environmental permitting timelines for cathode plants redistribute equipment demand northward along the Andean lithium triangle. Santiago grid-scale integrators procure module production lines for lithium iron phosphate packs. Antofagasta region cathode active material projects face permitting delays that freeze equipment procurement schedules.
Colombia
Bogotá free trade zone incentives and Pacific port access position the country for Korean and Japanese equipment vendor entry. Colombian assembly greenfield sites attract modular cell assembler platforms optimized for regional voltage standards. Medellín technical institutes struggle to produce sufficient mechatronics graduates for vision-guided stacking robot maintenance.
Mexico
Nuevo León and Bajío region automotive suppliers evaluate second-life battery disassembly equipment for end-of-life pack recovery. Mexico City energy storage developers unbundle procurement from turnkey EPC contracts, sourcing formation testers through distributor channels. Northern border states face electrolyte salt freight volatility from Chinese chemical processor dependence.
South America Electric Vehicle Battery Manufacturing Equipment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the South American EV battery equipment market. German press-line and coating specialists occupy premium-tier positions demanding sub-10-micron precision. Chinese modular platform vendors anchor mid-market segments with regional voltage optimization. Japanese vision system providers differentiate through yield-rate sustainability under variable plant conditions. Consolidation pressure favors strategic partnerships over pure M&A, while geographic expansion into Colombian greenfield sites accelerates among Asian vendors.
Within the German engineering tier, Schuler AG and Dürr Group exemplify heavy-gauge fabrication and integrated coating line heritage. Among Asia-Pacific platform specialists, Xiamen Tmax Battery Equipments Limited occupies a position aligned with mid-market modularity. Hitachi High-Tech Corporation sits within the precision automation archetype, representing Japanese vision system differentiation. These three anchors illustrate how geographic origin and corporate structure map to distinct competitive positioning without overlapping segment claims.
| Leading Market Players |
|---|
| Duerr AG |
| Schuler AG |
| Hitachi Ltd. |
| Xiamen Tmax Battery Equipments Limited |
| ACEY New Energy Technology |
| Hitachi High-Tech Corporation |
| Dürr Group |
| Lead Intelligent Equipment |
| Panasonic Corporation |
| Others |
Pricing and Supply Chain Analysis
Four-to-eight-month ANVISA certification lead times for high-voltage formation systems concentrate pricing power with German and Japanese vendors who maintain pre-certified product portfolios, while Brazilian OEMs absorb expedited delivery premiums to offset frozen project schedules. This lead-time asymmetry rewards incumbent equipment suppliers with established compliance infrastructure and penalizes mid-tier Asian entrants seeking market penetration through price competition.
Pricing Analysis
ANVISA industrial electrical safety mandates dictate the pricing tier structure across the South American EV battery equipment market. Three-tier pricing structure across premium, standard, and economy levels separates Schuler AG and Hitachi High-Tech Corporation at the certification-intensive top tier from Xiamen Tmax Battery Equipments Limited in the modular mid-market. Cost compression in the mid-tier is intensifying because Brazilian contract manufacturers unbundle procurement from turnkey EPC contracts and source directly through distributor channels. Tier-1 suppliers exhibit the highest price sensitivity due to thin margins on multi-OEM programs, while research institutions show the lowest sensitivity given government mining secretariat backing for pilot lines.
Supply Chain Analysis
Shanghai-to-Santos maritime chokepoint transit underwrites equipment delivery scheduling across the South American EV battery manufacturing landscape. Supply concentrates in China, Germany, and Japan for precision coating lines, formation testers, and vision-guided stacking systems respectively. Raw material dependencies span lithium hydroxide from Argentine Salta-Jujuy corridors, electrolyte salt precursors from Chinese chemical processors, and insulated-gate bipolar transistor modules from Japanese semiconductor fabricators. Single-source vulnerability around LiPF6 precursor supply exposes Brazilian and Argentine factories to freight cost volatility and customs delays. Distribution runs through Campinas and São Bernardo do Campo technical service partnerships rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazilian OEM consolidation of cathode active material sourcing through captive partnerships has shifted procurement authority toward direct equipment purchasing, fragmenting buyer power across contract manufacturers, aftermarket providers, and research institutions. This buyer-base fragmentation rewards vendors with flexible service architectures over those locked into rigid EPC-mediated distribution.
For Market Incumbents: Compound technical service density in the Puna region to defend against ANVISA certification delays that freeze competitor project schedules. Deepen backward integration into vision system calibration and arc fault detection module production to capture margin pools currently leaking to Japanese semiconductor suppliers. Prioritize capacity addition in Colombian greenfield sites before Korean and Japanese vendors establish beachheads through Bogotá free trade zone incentives.
For New Entrants and Emerging Players: Differentiate on solid-state pilot line equipment for sulfide electrolyte handling, where hermetic glovebox and thin-film deposition specialization commands scarcity premiums. Target Colombian assembly greenfield sites as the most penetrable geography given Pacific port access and underdeveloped local technical service infrastructure. Pursue research institution partnerships with Argentine and Chilean universities as a go-to-market angle to secure government mining secretariat coordination for sodium-ion and solid-state pilot installations.
For Investors and Strategic Acquirers: Carve-out targets emerge from European automotive press-line specialists seeking to monetize non-core battery equipment divisions amid EV platform consolidation. Long-term viability in this market hinges on chemistry-agnostic equipment architectures that accommodate LFP-NMC transitions without full line replacement. Watch dry electrode technical maturity as the critical inflection indicator that would unlock binder-free coating CAPEX and displace solvent-based wet coating incumbents.
| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Pre-Certification Investment | Pre-certified formation systems bypass four-to-eight-month import clearance delays that freeze Brazilian OEM project schedules. |
| Argentine Lithium Corridor Proximity | Equipment placement near Salta-Jujuy hydroxide conversion sites captures feedstock-adjacent cell assembly demand. |
| Colombian Free Trade Zone Entry | Bogotá incentives and Pacific port access enable Korean and Japanese vendor expansion before incumbent consolidation. |
| Solid-State Pilot Line Development | Hermetic glovebox specialization for sulfide electrolyte handling commands first-mover premiums in emerging chemistry platforms. |
| Second-Life Disassembly Automation | Automated module dismantling systems serve São Paulo and Buenos Aires fleet operators recovering cells from end-of-life automotive packs. |
Research Methodology
A spread of perspectives from OEM platform engineers, Tier-1 supplier procurement leads, ANVISA certification consultants, and aftermarket service heads converged on the working assumptions driving equipment demand forecasts. Primary interviews with Brazilian plant managers and Argentine mining secretariat officials combined with secondary validation from SEC filings of listed equipment vendors, Brazilian customs import records for industrial machinery, and INMETRO efficiency labeling databases. Bottom-up triangulation across cell assembler unit economics and top-down reconciliation against lithium hydroxide conversion capacity announcements anchored the analytical framework.
Product type, technology chemistry, end-user procurement authority, and application segment dimensions structured the forecast model across the analysis window. CAGRs derived from equipment procurement pipeline analysis weighted by ANVISA certification timeline probabilities and lithium supply chain investment announcements. Cell-to-pack architecture adoption rates and dry electrode technical maturity thresholds served as industry-specific forecast sensitivity inputs.
Material uncertainties — regulatory timeline slippage, cathode chemistry switching costs, and electrolyte salt supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions around INMETRO mandate enforcement consistency and Argentine mining secretariat policy continuity. Practitioners should keep alternative scenarios live as dry electrode yield thresholds and solid-state pilot line scale-up timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Global Battery Technology Market
Battery Infrastructure
Battery Tray Market
Battery Infrastructure
Substation Battery Market
Battery Infrastructure
New Energy Battery Structural Parts Market
Battery Infrastructure
EV Battery Sealant Market
Battery Infrastructure
United Kingdom Electric Vehicle Battery Separator Market
Battery Infrastructure
Lithium-Ion Battery Housing Cases Market
Battery Infrastructure
Middle East and Africa Electric Vehicle Battery Separator Market
Battery Infrastructure
Europe Electric Vehicle Battery Separator Market
Battery Infrastructure
Germany Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
North America Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Raw Materials Market
Battery Infrastructure
Global Automotive 48 Volt Battery System Market
Battery Infrastructure
North America Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Italy Electric Vehicle Battery Separator Market
Battery Infrastructure
Automotive Battery Plate Market