
 Dew Point Thermometer Market | 2026-2036
Dew Point Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Dew Point Thermometer Market Outlook
REACH compliance is expanding the cost-of-entry calculus for dew point thermometer manufacturers selling into European industrial markets. Vaisala Corporation leverages its optical technology portfolio to sustain premium positioning in semiconductor cleanroom applications. Michell Instruments anchors British demand through specialized chilled-mirror systems for natural gas processing. E+E Elektronik GmbH competes on capacitive sensor miniaturization for building automation channels.
A dew point thermometer measures the temperature at which air becomes saturated with water vapor and condensation forms, typically employing chilled-mirror, capacitive polymer, or optical absorption methods achieving accuracies within ±0.1°C. These instruments prevent corrosion in compressed air systems, protect pharmaceutical stability, and ensure semiconductor yield by monitoring moisture levels in controlled environments. Digital portable units lead volume sales for field service technicians, while fixed installations with semiconductor sensors command higher margins in continuous industrial monitoring. Capacitive technology occupies the broadest application base across HVAC and weather monitoring, whereas optical chilled-mirror systems dominate calibration laboratories demanding traceable humidity standards.
The EPA mandates periodic verification of moisture analyzers in stack gas monitoring, compelling utility operators toward NIST-traceable dew point instrumentation. ISO 17025 accreditation requirements shape laboratory procurement specifications across testing facilities in North America and Europe. Stakeholders must weigh sensor drift rates against total cost of ownership as regulatory stringency tightens verification intervals for critical humidity measurements.
Market Dynamics
Semiconductor fabrication expansion in East Asia and tightening EPA emissions verification mandates are compressing procurement cycles for NIST-traceable dew point instrumentation across industrial and laboratory channels.
Growth Catalysts
- EPA stack gas monitoring mandates:Utility operators must upgrade to traceable humidity analyzers, forcing replacement of aging capacitive sensors with chilled-mirror reference standards.
- East Asian semiconductor buildouts:Taiwan, South Korea, and Japan fabs require continuous optical dew point monitoring to protect yield in sub-7nm lithography environments.
- Pharmaceutical cold chain expansion:Stability testing protocols under ICH Q1A guidelines demand calibrated humidity verification for biologics storage and distribution.
Market Restraints
- Platinum resistance thermometer cost volatility:Chilled-mirror systems depend on precision Pt100 elements, exposing manufacturers to precious metal price swings.
- Optical component supply concentration:Laser diode and interference filter fabrication concentrates in German and Japanese specialty optics houses, creating single-source vulnerability.
- Capacitive polymer accuracy ceiling:Polymer sensors drift beyond ±2°C at sub-zero dew points, limiting their deployment in natural gas dehydration and cryogenic applications.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO's tightened GMP inspections for export-oriented facilities create demand for ISO 17025-calibrated portable dew point meters.
- Green hydrogen electrolysis:PEM stack humidity control requires ultra-dry gas monitoring, opening a new application segment for optical chilled-mirror systems.
- Wireless sensor convergence:LoRaWAN-enabled dew point transmitters are penetrating building automation channels previously served by wired BACnet installations.
Industry Challenges
- Metrology technician scarcity:Chilled-mirror maintenance and NIST-traceable calibration require specialized humidity metrology skills that outpace vocational training output.
- Legacy system integration friction:Modern digital outputs from smart dew point transmitters conflict with 4-20mA analog infrastructure in decades-old compressed air plants.
- ISO 17025 accreditation timelines:Laboratory certification for humidity calibration labs stretches 12-18 months, delaying market entry for regional service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dew Point Thermometer Market |
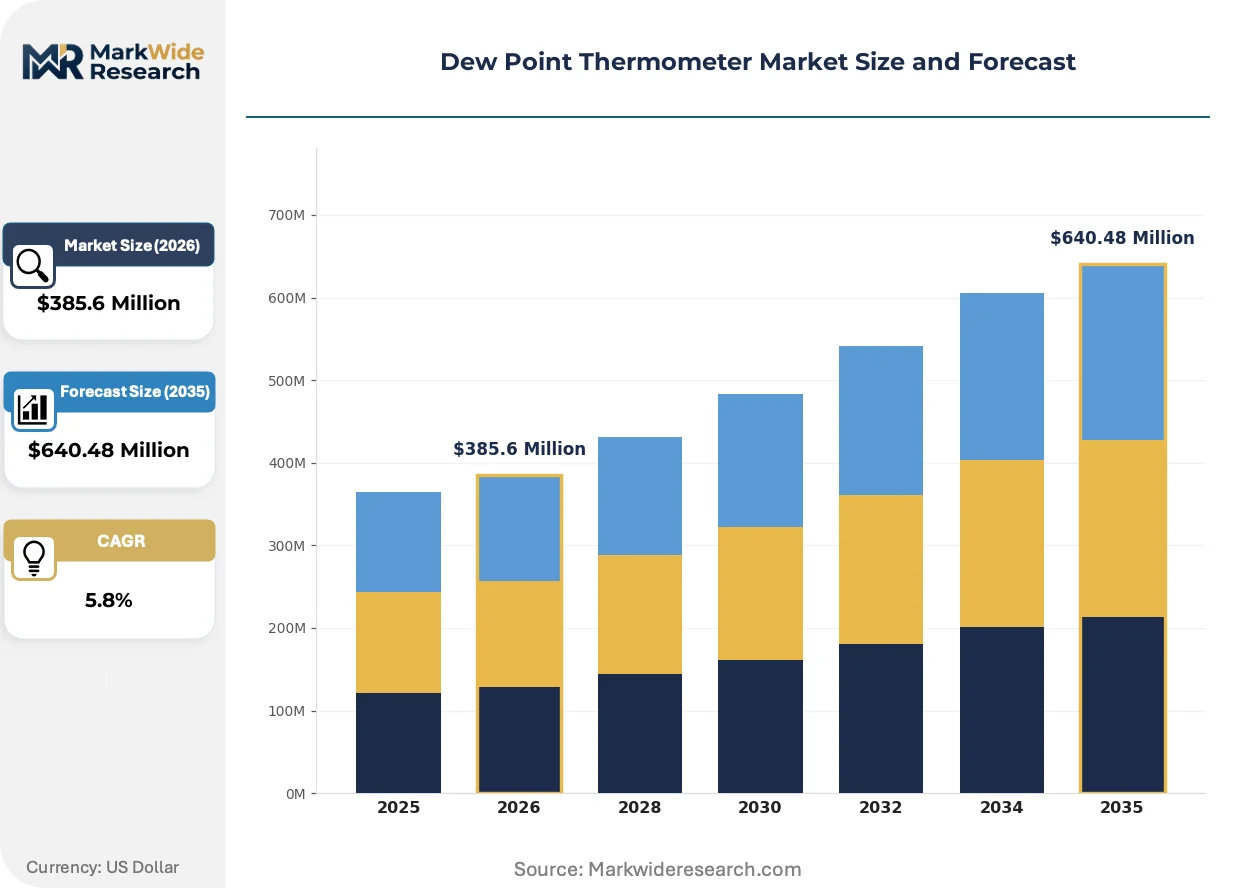
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Fixed, Analog, Digital Technology: Capacitive, Resistive, Optical, Semiconductor End User: Aerospace, HVAC, Automotive, Industrial Application: Weather Monitoring, Refrigeration, Agriculture, Laboratory |
| Companies Covered | Elcometer Limited, Panametrics, Vaisala Corporation, Alpha Moisture Systems, Shaw Moisture Meters, Michell Instruments, E+E Elektronik GmbH, COSA Xentaur, Edgetech Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dew Point Thermometer Market Strategic Shifts
Optical sensing architectures and wireless connectivity protocols are reconfiguring how dew point instrumentation deploys across distributed industrial environments.
Chilled-mirror systems are integrating microprocessor-controlled Peltier cooling with automatic surface reflectance detection, eliminating operator intervention for condensation onset determination. Semiconductor fabs in Taiwan and South Korea are adopting these self-calibrating units to reduce cleanroom personnel traffic. The technology is integrating reference-grade accuracy into continuous process monitoring roles previously served by less precise capacitive alternatives.
REACH compliance is expanding documentation requirements for polymer sensor materials used in European industrial markets. Manufacturers must now submit full substance dossiers for hygroscopic dielectric coatings, adding 6-9 months to product launch timelines. Pharmaceutical cleanroom operators in Germany and Switzerland are responding by specifying optical chilled-mirror systems that bypass polymer-based sensor restrictions entirely.
Compressed air service technicians are abandoning ownership models in favor of rental-with-calibration subscriptions for portable dew point meters. Equipment lessors in the US and Germany now bundle NIST-traceable recertification into monthly rates, capturing maintenance revenue that previously leaked to third-party metrology labs. This pattern concentrates most visible in automotive painting facilities where quarterly verification is mandatory under EPA NESHAP standards.
Dew Point Thermometer Market Segmentation
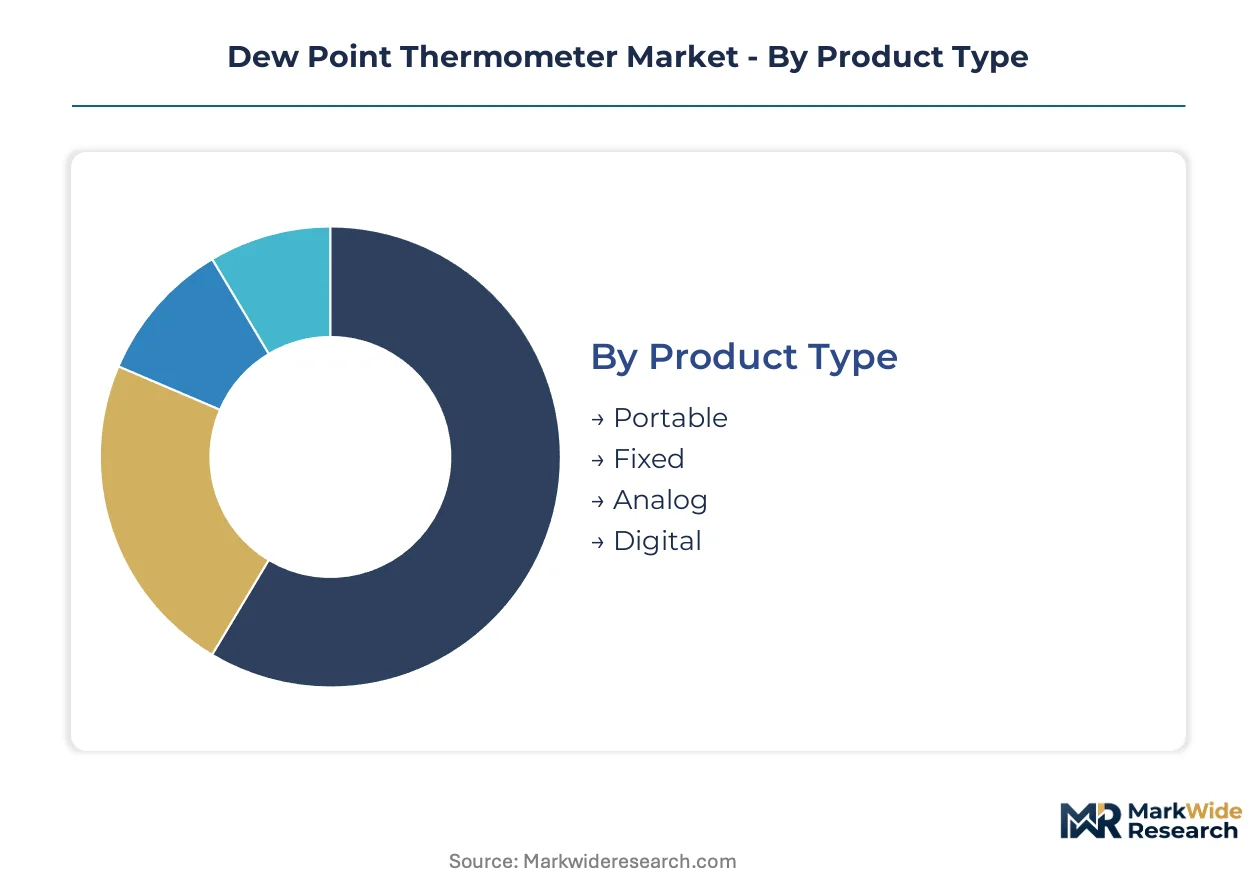
Dew point instrumentation fragments across four structural axes that determine procurement economics and vendor positioning. Product form factor dictates calibration frequency and total cost of ownership. Sensing technology separates premium reference-grade installations from mass-market HVAC deployments.
Product Type:
Fixed installations demand the heaviest upfront capital outlay for integration, distributed sensing networks, and continuous monitoring infrastructure. Portable units require lower initial investment but impose recurring calibration costs that compound over operational life.
- Portable:Battery-powered handheld units with interchangeable probe heads serve field service technicians in compressed air audits and spot-check validation. Automotive painting facilities in Michigan and South Carolina lease these under subscription models bundling NIST-traceable recertification to satisfy EPA NESHAP quarterly verification mandates.
- Fixed:Panel-mounted transmitters with semiconductor sensor elements integrate into SCADA architectures for continuous process monitoring. Taiwan and South Korea semiconductor fabs specify these for sub-7nm lithography environments where moisture excursions destroy wafer yields.
- Analog:Legacy 4-20mA output devices persist in decades-old compressed air plants where digital infrastructure retrofit costs outweigh replacement benefits.
- Digital:Smart transmitters with Modbus and Ethernet-IP outputs enable predictive maintenance algorithms in greenfield industrial facilities.
Most installed capacity flows through Fixed systems. Expansion is steepest in Digital.
Technology:
Optical chilled-mirror systems command the widest margin spreads due to precision optics and platinum sensor dependency. Capacitive polymer sensors dominate unit volume through cost-engineered designs for building automation.
- Capacitive:Polymer dielectric sensors measuring humidity-induced capacitance changes offer the lowest per-unit cost and broadest HVAC penetration. REACH compliance documentation requirements for hygroscopic coatings now extend European launch timelines by 6-9 months, pushing pharmaceutical cleanroom operators toward alternative technologies.
- Optical:Chilled-mirror systems detecting condensation onset through reflectance measurement achieve ±0.1°C accuracy for calibration laboratory traceability. German and Swiss pharmaceutical manufacturers specify these to bypass polymer sensor restrictions entirely while maintaining ISO 17025 accreditation.
- Resistive:Bulk polymer resistance sensors serve cost-constrained weather monitoring stations with moderate accuracy requirements.
- Semiconductor:Integrated CMOS humidity elements enable miniaturization for wireless IoT sensor nodes in building automation retrofits.
Capacitive technology carries the largest installed base. Optical systems are gaining share fastest in regulated industrial applications.
End User:
Aerospace and semiconductor industrial users absorb the highest per-site instrumentation spend due to mission-critical moisture control and stringent certification requirements. HVAC contractors optimize for procurement simplicity and interoperability.
- Aerospace:Aircraft environmental control system testing and fuel tank inerting applications demand explosion-proof portable units with FAA-compliant calibration chains.
- HVAC:Building commissioning and energy audit technicians favor wireless-enabled portable meters for duct traverse measurements without scaffolding.
- Automotive:Paint booth humidity control and compressed air quality verification drive fleet purchases across assembly plant metrology departments.
- Industrial:Natural gas processing, petrochemical dehydration, and cryogenic air separation plants specify chilled-mirror reference standards for custody transfer measurement integrity.
Industrial facilities deploy the most instruments per site. Aerospace represents the steepest expansion trajectory for high-accuracy portable systems.
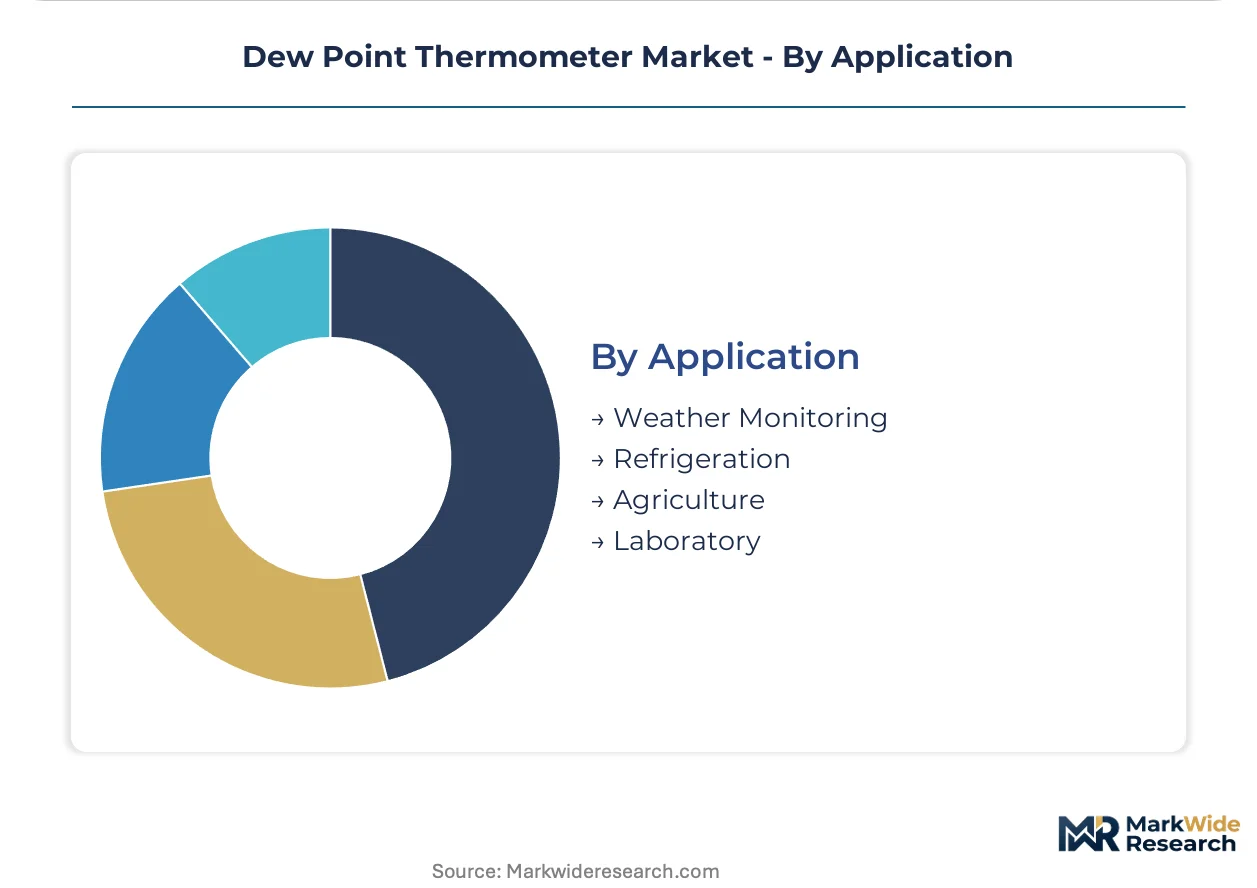
Application:
Laboratory and weather monitoring applications split between reference-grade investment and distributed low-cost sensing. Agriculture and refrigeration occupy intermediate positions with growing precision requirements.
- Weather Monitoring:National meteorological services operate capacitive sensor networks with solar-powered telemetry for synoptic observation grids.
- Refrigeration:Cold chain logistics operators deploy portable dew point meters to verify container desiccant performance during pharmaceutical distribution under ICH Q1A stability protocols.
- Agriculture:Controlled environment agriculture facilities monitor leaf condensation risk to prevent fungal pressure in high-value greenhouse operations.
- Laboratory:ISO 17025 calibration laboratories maintain optical chilled-mirror references as national humidity standards with direct NIST traceability.
Laboratory applications concentrate the highest value per instrument. Weather Monitoring deploys the greatest unit volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finnish optical sensing specialists anchor the premium instrumentation tier, while German metrology engineers sustain calibration laboratory density across Central Europe. Taiwanese semiconductor process engineers drive the steepest procurement acceleration for continuous monitoring infrastructure.
United States
EPA stack gas verification mandates and pharmaceutical cold chain expansion absorb the highest per-capita instrumentation spend. Utility operators under EPA NESHAP standards replace aging capacitive sensors with chilled-mirror reference systems. Automotive painting clusters in Michigan and South Carolina lease portable units under subscription models bundling NIST-traceable recertification.
Germany
Pharmaceutical cleanroom operators and natural gas processing facilities sustain European demand for precision dew point instrumentation. REACH compliance documentation requirements for polymer sensor materials push German manufacturers toward optical chilled-mirror alternatives. Bavarian calibration laboratories anchor ISO 17025 accreditation chains serving Central European industrial markets.
China
Semiconductor fabrication buildouts and green hydrogen electrolysis projects compress procurement cycles for ultra-dry gas monitoring systems. MIIT industrial upgrading guidelines emphasize traceable humidity measurement in advanced manufacturing zones. Yangtze River Delta fabs deploy continuous optical dew point monitoring to protect yield in sub-7nm lithography environments.
Japan
Specialty optics houses concentrate laser diode and interference filter fabrication, creating supply-side vulnerability for chilled-mirror system manufacturers. METI technology roadmaps prioritize domestic humidity metrology capability for semiconductor equipment supply chains. Kyushu-based sensor component fabricators serve both domestic instrument makers and Taiwanese fab operators.
South Korea
Memory and logic semiconductor producers drive the fastest adoption of self-calibrating chilled-mirror systems with automatic surface reflectance detection. MFDS pharmaceutical GMP inspections for export-oriented biologics facilities expand calibrated portable meter procurement. Seoul Capital Area cleanroom engineering firms specify continuous monitoring infrastructure to minimize personnel traffic in sub-7nm production environments.
Dew Point Thermometer Market Competitive Environment
The competitive structure tilts toward technology-differentiated specialists rather than scale-driven conglomerates. Finnish and British optical sensing houses occupy the premium reference-grade tier, while German and Austrian capacitive sensor manufacturers compete on miniaturization and building automation channels. Two dominant competitive moves define current positioning: backward integration into precision optics fabrication to secure laser diode supply, and strategic partnerships with semiconductor equipment OEMs for cleanroom-integrated monitoring systems.
Within the premium optical tier, Vaisala Corporation and Michell Instruments exemplify Nordic and British engineering heritage in chilled-mirror reference standards. E+E Elektronik GmbH occupies a distinct position on the capacitive miniaturization vector for HVAC and building automation applications. These three anchors represent divergent technology bets—optical precision versus polymer cost-engineering—that split procurement decisions between regulated industrial environments and mass-market commercial installations.
| Leading Market Players |
|---|
| Elcometer Limited |
| Panametrics |
| Vaisala Corporation |
| Alpha Moisture Systems |
| Shaw Moisture Meters |
| Michell Instruments |
| E+E Elektronik GmbH |
| COSA Xentaur |
| Edgetech Instruments |
| Others |
Value Chain & Pricing Dynamics
EPA NESHAP quarterly verification mandates for automotive painting facilities are compressing procurement cycles toward bundled rental-with-calibration subscriptions, forcing equipment lessors to internalize metrology service costs and reshape pricing architectures around lifetime ownership economics rather than upfront hardware margins.
Pricing Analysis
Bundled service subscriptions versus unbundled equipment sales split procurement economics across end-user segments. Three-tier pricing structure across premium optical chilled-mirror, standard capacitive fixed-installation, and economy portable polymer sensor levels stratifies buyers by certification stringency. Price differentiation hinges on NIST-traceability grade and REACH compliance documentation depth. Cost compression in mid-tier capacitive systems is intensifying because polymer sensor manufacturers absorb extended substance dossier preparation timelines. HVAC contractors exhibit highest price sensitivity; semiconductor fabs and pharmaceutical cleanrooms show lowest.
Supply Chain Analysis
Refurbishment flows for platinum resistance thermometer elements and precision optical components create secondary supply channels that extend instrument lifecycle value. Laser diode and interference filter fabrication concentrates in Japan and Germany, while chilled-mirror assembly draws from Finnish and British engineering houses. Raw material dependencies span platinum group metals, specialty optical glass, and hygroscopic polymer substrates. Single-source vulnerability in German and Japanese specialty optics houses threatens chilled-mirror system output. Distribution runs through authorized metrology service partners with captive calibration laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance documentation burdens in Europe against EPA verification mandates in the US create a geographic-arbitrage opportunity for manufacturers to optimize production location and service bundling models based on regulatory cost differentials.
For Market Incumbents: Extend calibration laboratory accreditation chains into India and Southeast Asia before CDSCO and ASEAN pharmaceutical regulators tighten GMP inspection protocols. Defend position by backward integration into laser diode fabrication to neutralize Japanese and German optics supply concentration. Prioritize semiconductor equipment OEM partnerships for cleanroom-integrated monitoring system lock-in. For New Entrants and Emerging Players: Green hydrogen electrolysis operators represent an underserved buyer archetype with unmet ultra-dry gas monitoring requirements and limited incumbent relationship depth. Penetrate PEM stack humidity control applications with portable optical chilled-mirror units before fixed-installation infrastructure standardizes. Deploy direct technical sales teams at electrolyzer pilot projects rather than channel distribution. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier capacitive sensor manufacturers possessing REACH-compliant polymer formulations and scalable building automation channel access. Long-term viability favors targets with captive metrology service revenue streams and ISO 17025 laboratory density. Monitor EPA enforcement intensity and semiconductor fab buildout announcements as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Optics | Secures laser diode supply against Japanese and German specialty house concentration risk. |
| Calibration Laboratory Network Expansion | Captures recurring service revenue from EPA NESHAP and CDSCO verification mandates. |
| Semiconductor Equipment OEM Partnership | Locks in continuous monitoring infrastructure specifications for sub-7nm lithography environments. |
| Wireless IoT Sensor Platform Launch | Penetrates building automation retrofits previously served by wired BACnet installations. |
| Green Hydrogen Application Development | Opens ultra-dry gas monitoring segment for PEM electrolysis humidity control requirements. |
Study Parameters
Multiple input streams — primary interviews with metrology laboratory directors, semiconductor process engineers, and pharmaceutical quality assurance managers; secondary validation through EPA enforcement databases, ISO 17025 accreditation registries, and SEC filings from precision instrument manufacturers; plus customs and trade flow data — were reconciled through bottom-up and top-down triangulation.
Historical shipment patterns were cross-referenced against expert panel assessments of procurement cycle compression and regulatory enforcement trajectories. The analytical framework modeled technology type, product form factor, end-user industry, and geographic regulatory cluster across the projection horizon. CAGRs were derived from segment-level unit economics and replacement cycle dynamics, incorporating platinum price volatility and REACH compliance timeline assumptions specific to polymer sensor material documentation.
Underlying measurement precision varies by segment; optical chilled-mirror reference standards carry tighter precision than capacitive polymer field units. Forecasts reflect assumptions about EPA enforcement continuity, semiconductor capital expenditure patterns, and metrology technician training pipeline output. Practitioners should monitor CDSCO inspection protocol updates, green hydrogen project announcements, and laser diode supply allocation decisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Sensor Based Sorting System Market
Sensors and Controls
Asia-Pacific Current Transducer Market
Sensors and Controls
Italy Digital Thermometer Market
Sensors and Controls
Smart Parking Sensor Market
Sensors and Controls
Global Thermocouple Temperature Sensors Market
Sensors and Controls
Yaw Rate Sensors Market
Sensors and Controls
In-Display Fingerprint Sensors Market
Sensors and Controls
Middle East and Africa Wearable Sensors Market
Sensors and Controls
Piezoelectric Materials Market
Sensors and Controls
Gimbal Market
Sensors and Controls
Global Ultra Low Power MEMS Sensors Market
Sensors and Controls
Ingestible Sensor Market
Sensors and Controls
Global Temperature Sensors Market
Sensors and Controls
Battery Free Sensor Market
Sensors and Controls
High-Voltage Isolation and Leakage Sensor Components Market
Sensors and Controls
Thermal Scanners Market