
 Piezoresistive Pressure Sensor Market | 2026-2036
Piezoresistive Pressure Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Piezoresistive Pressure Sensor Market Outlook
The EU Green Deal's industrial emissions monitoring mandates are shifting demand toward piezoresistive sensors with extended calibration intervals and lower drift coefficients. Bosch leverages captive MEMS fabrication in Reutlingen to sustain cost leadership across automotive absolute pressure lines. Sensata Technologies anchors North American aerospace aftermarket channels through FAA-certified repair station networks. TE Connectivity competes in industrial process control with ceramic-cell platforms rated for corrosive media.
A piezoresistive pressure sensor measures applied pressure through resistance changes in a strain-sensitive diaphragm, typically fabricated from single-crystal silicon with boron-doped piezoresistors patterned via photolithography and etched using deep reactive ion etching to achieve full-scale outputs of 50-300 mV. The device converts mechanical stress into electrical signals for closed-loop control in fluid systems, combustion chambers, and medical infusion pumps. Silicon technology dominates volume production due to mature foundry compatibility, while MEMS architectures capture the fastest expansion as wafer-level vacuum encapsulation cuts unit costs for consumer and wearable segments. Gauge sensors lead in automotive tire pressure and industrial pneumatics, whereas differential configurations command premium positioning in HVAC airflow management and cleanroom pressurization.
The EPA's methane emissions rules for oil and gas infrastructure mandate continuous pressure monitoring at compressor stations, directly expanding sensor replacement cycles. REACH restrictions on lead-based solders force manufacturers toward gold-tin eutectic die-attach processes that alter thermal compensation algorithms. China's GB standards for intelligent manufacturing require digital output protocols over legacy analog 4-20 mA loops. Stakeholders must evaluate whether to develop native IO-Link interfaces or license stack solutions from established fieldbus consortia.
Market Dynamics
Automotive electrification programs in Germany and Japan are compressing sensor qualification timelines while elevating precision requirements for battery thermal management systems. MEMS miniaturization and silicon-on-insulator processes are simultaneously reducing die sizes and improving signal stability, forcing incumbent suppliers to retool fabrication lines or surrender volume segments to captive foundry operations.
Growth Catalysts
- EU Green Deal industrial emissions mandates:Continuous monitoring requirements at manufacturing facilities extend replacement cycles for sensors with lower drift coefficients and extended calibration intervals.
- Silicon-on-insulator wafer processes:Advanced MEMS architectures achieve full-scale outputs of 50-300 mV through deep reactive ion etching, cutting unit costs for consumer and wearable segments.
- East Asian manufacturing clusters:South Korea's semiconductor foundry corridors and China's Yangtze River Delta sensor production zones concentrate demand for wafer-level vacuum encapsulation capacity.
Market Restraints
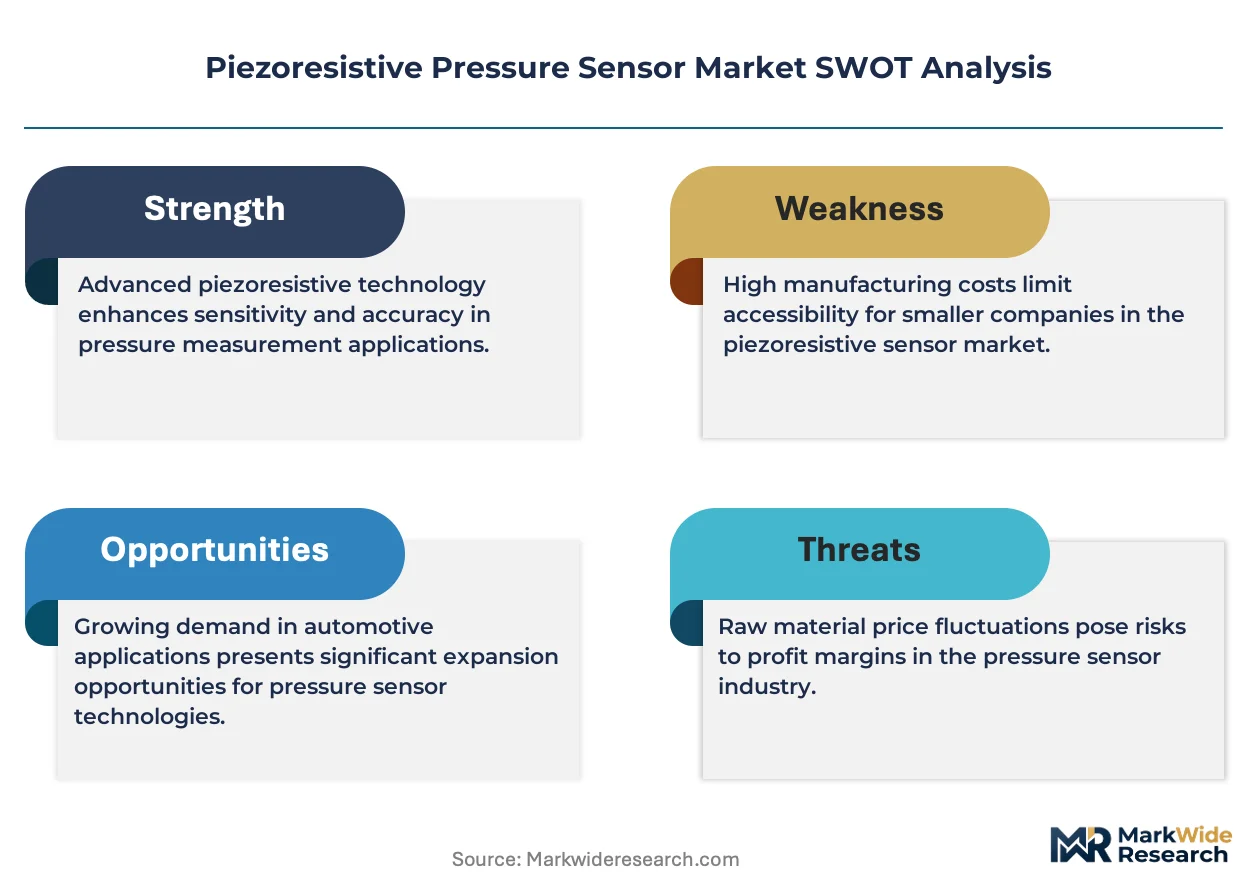
- REACH restrictions on lead-based solders:Manufacturers must migrate toward gold-tin eutectic die-attach processes that alter thermal compensation algorithms and raise material input costs.
- Supply concentration in MEMS foundries:Taiwan and South Korea control critical wafer-level vacuum encapsulation capacity, creating chokepoints for European and North American sensor designers.
- Signal drift in ceramic-cell platforms:Corrosive media applications in industrial process control expose limitations in TE Connectivity's ceramic-cell architectures compared to silicon alternatives.
Strategic Opportunities
- China's GB standards for intelligent manufacturing:Mandatory digital output protocols over legacy analog 4-20 mA loops create first-mover advantage for native IO-Link interface developers.
- EPA methane emissions rules for oil and gas infrastructure:Continuous pressure monitoring mandates at compressor stations accelerate replacement cycles for absolute pressure sensor lines.
- Silicon photonics convergence with MEMS pressure sensing:Hybrid architectures enable optical readout of mechanical deformation, eliminating electromagnetic interference in aerospace applications.
Industry Challenges
- Deep reactive ion etching process control:Achieving consistent diaphragm thickness across 200mm and 300mm wafers requires specialized plasma physics expertise that concentrates in German and Japanese equipment suppliers.
- FAA certification timelines for aerospace aftermarket channels:Sensata Technologies and competitors face 18-24 month qualification periods for repair station network expansions, compressing revenue recognition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Piezoresistive Pressure Sensor Market |
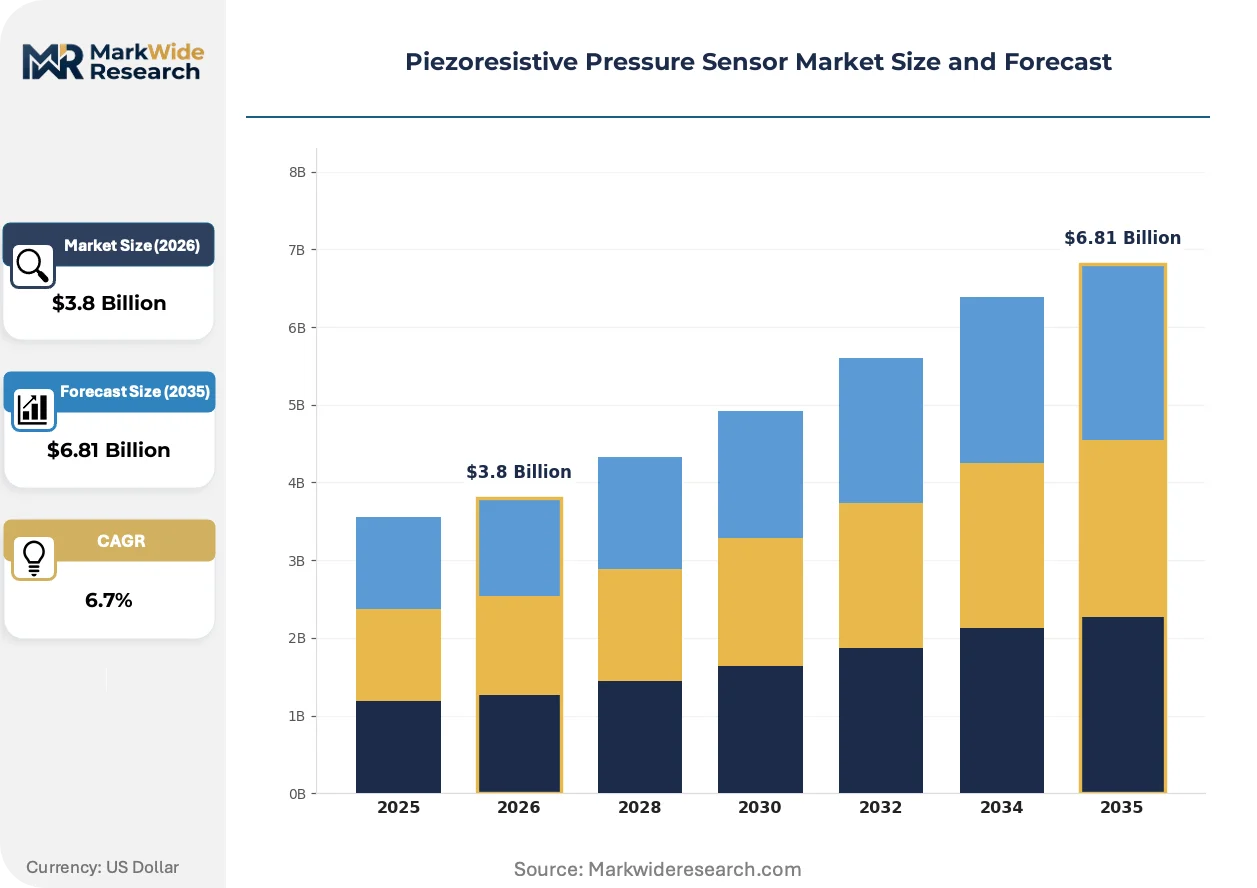
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absolute, Gauge, Differential, Multidimensional Technology: Silicon, Ceramic, Thin Film, MEMS End User: Aerospace, Automotive, Healthcare, Industrial Application: Fluid Monitoring, Structural Health, Process Control, HVAC |
| Companies Covered | Sensata Technologies, STMicroelectronics, Honeywell International Inc., Kistler, Bosch, TE Connectivity, NXP Semiconductors, Merit Sensor, Amphenol Advanced Sensors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Piezoresistive Pressure Sensor Market Strategic Shifts
Wafer-level vacuum encapsulation is compressing cost structures while enabling new form factors for wearable and implantable applications. Three concurrent developments are restructuring competitive positioning across automotive, industrial, and medical segments.
Silicon photonics integration with piezoresistive sensing elements is decentralizing signal conditioning architecture away from centralized ASICs toward distributed optical interrogation systems. Medical infusion pump manufacturers in Switzerland and Germany are piloting fiber-coupled sensors that eliminate electrical connections in sterile fluid paths. This architecture collapses electromagnetic shielding requirements and enables sub-millimeter catheter-compatible form factors previously unreachable with wire-bonded silicon dies.
The EPA's methane emissions regulations for oil and gas infrastructure mandate continuous pressure monitoring at compressor stations and wellhead assemblies, forcing sensor suppliers to certify products for hazardous area classifications. North American exploration operators are consolidating procurement around suppliers offering integrated temperature-pressure transmitters with HART protocol compatibility. This regulatory pressure is displacing legacy mechanical gauges in upstream applications where digital telemetry enables remote leak detection.
Automotive OEMs are unbundling sensor procurement from Tier 1 module contracts, establishing direct qualification relationships with MEMS foundries and ceramic substrate suppliers. Battery thermal management programs in Stuttgart and Toyota City now specify absolute pressure sensors with ASIL-D functional safety ratings independently of HVAC module sourcing. This disintermediation compresses margin pools for integrated subsystem suppliers while rewarding bare-die and packaged sensor specialists with design-in authority.
Piezoresistive Pressure Sensor Market Segmentation
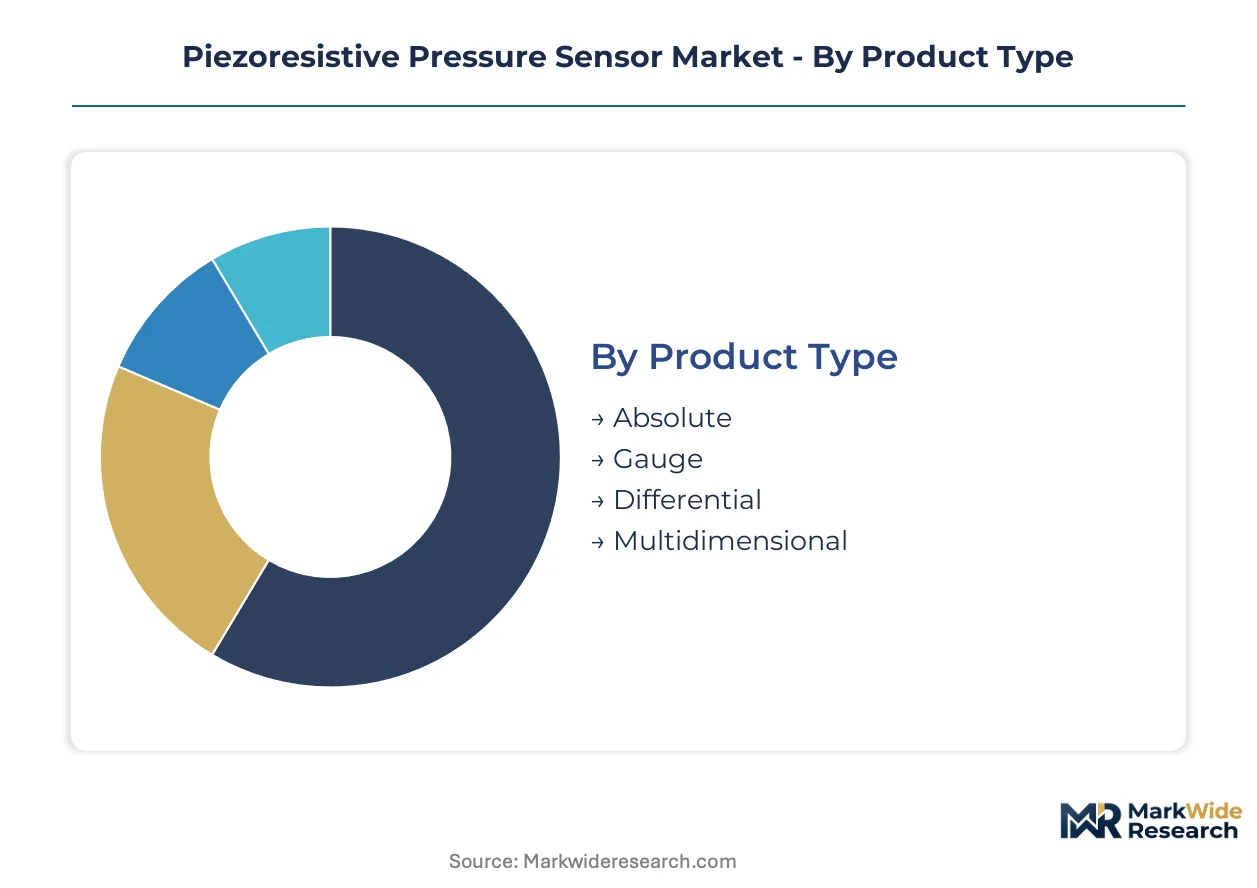
Piezoresistive pressure sensor procurement splits across incompatible certification regimes, forcing suppliers to maintain parallel qualification tracks. Automotive ASIL-D ratings, aerospace FAA DER approvals, and medical ISO 13485 compliance create segment-specific entry barriers that reshape competitive boundaries.
Product Type:
Absolute pressure sensors demand ASIL-D functional safety certification for battery thermal management in electrified vehicles, while differential configurations require ISO 17025 calibration traceability for cleanroom HVAC applications.
- Absolute:Measures pressure relative to vacuum reference. Stuttgart and Toyota City battery programs specify these for thermal runaway detection, compressing qualification timelines to 18 months.
- Gauge:References ambient atmospheric pressure. Tire pressure monitoring systems in Germany and Japan anchor volume demand, though margin pressure intensifies from unbundled OEM procurement.
- Differential:Captures pressure variance between two ports. Cleanroom pressurization in South Korean semiconductor fabs and Swiss pharmaceutical manufacturing commands premium positioning through ISO 14644 compliance requirements.
- Multidimensional:Integrates pressure with temperature or flow sensing. Emerging in aerospace health monitoring where FAA DER approval cycles extend 24-36 months.
Leading the category by volume: Gauge. Growing fastest: Differential.
Technology:
Silicon dominates unit economics through foundry compatibility, while MEMS architectures capture steepest expansion trajectories as wafer-level encapsulation cuts costs.
- Silicon:Single-crystal substrates with boron-doped piezoresistors achieve 50-300 mV outputs. Reutlingen and Yangtze River Delta foundries concentrate supply, though 200mm wafer transitions strain etching consistency.
- MEMS:Deep reactive ion etched diaphragms with vacuum encapsulation. South Korean foundry corridors and Taiwan packaging houses control critical capacity, creating chokepoints for European designers.
- Ceramic:Alumina or zirconia cells rated for corrosive media. Industrial process control applications in Germany's chemical belt expose signal drift limitations versus silicon alternatives.
- Thin Film:Sputtered metal strain elements on stainless steel. Oil and gas compressor stations under EPA methane rules favor these for hazardous area classifications.
Volume leader: Silicon. Fastest expansion: MEMS.
End User:
Automotive unbundling shifts procurement authority toward bare-die specialists, while healthcare's sterile fluid path requirements favor optical interrogation architectures.
- Automotive:Battery thermal management and tire pressure systems. Direct OEM-foundry relationships in Germany and Japan disintermediate Tier 1 module suppliers.
- Industrial:Process control and emissions monitoring. EU Green Deal mandates extend replacement cycles for low-drift sensors in manufacturing facilities.
- Aerospace:Flight control and engine monitoring. FAA-certified repair station networks require 18-24 month qualification periods, compressing revenue recognition.
- Healthcare:Infusion pumps and catheter-compatible sensors. Swiss and German manufacturers pilot fiber-coupled designs eliminating electrical connections in sterile paths.
Dominant by volume: Automotive. Steepest trajectory: Healthcare.
Application:
Fluid monitoring spans incompatible regulatory domains from FDA-regulated medical devices to EPA-mandated methane detection, fragmenting supplier specialization.
- Fluid Monitoring:Medical infusion and hydraulic systems. Fiber-coupled sensors in Switzerland enable sub-millimeter catheter form factors through optical readout.
- Process Control:Chemical and petrochemical operations. REACH restrictions on lead-based solders force gold-tin eutectic migration, altering thermal compensation.
- HVAC:Airflow management and cleanroom pressurization. China's GB standards mandate digital IO-Link protocols over legacy 4-20 mA loops.
- Structural Health:Civil infrastructure and aircraft monitoring. Distributed optical interrogation eliminates electromagnetic interference in aerospace applications.
Volume concentration: Process Control. Fastest climb: HVAC.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reutlingen anchors European sensor fabrication through captive MEMS operations serving Stuttgart automotive programs. Germany's electrification mandates and Japan's battery thermal management specifications concentrate procurement authority in these manufacturing corridors.
Germany
Stuttgart OEMs specify ASIL-D absolute pressure sensors for battery thermal management independent of HVAC module sourcing. The EU Green Deal's industrial emissions monitoring extends replacement cycles for low-drift sensors in manufacturing facilities. Reutlingen's foundry corridor concentrates captive MEMS fabrication serving automotive electrification timelines compressed to eighteen months.
Japan
Toyota City battery programs demand high-precision sensors for thermal runaway detection in electrified vehicle platforms. METI's carbon neutrality roadmaps accelerate foundry investments in silicon-on-insulator processes. Nagoya's industrial corridor houses specialized plasma physics expertise for deep reactive ion etching consistency across 300mm wafer transitions.
China
Yangtze River Delta sensor production zones concentrate wafer-level vacuum encapsulation capacity for consumer and wearable segments. GB standards for intelligent manufacturing mandate digital IO-Link protocols over legacy analog loops. Shanghai's foundry corridors face chokepoint risks as Taiwan and South Korea control critical packaging capacity.
South Korea
Seoul Capital Area semiconductor foundries supply deep reactive ion etched diaphragms for MEMS architectures. The country's emissions trading scheme tightens monitoring requirements at manufacturing facilities. Busan-Ulsan's packaging houses control vacuum encapsulation capacity creating supply concentration for European sensor designers.
United States
EPA methane emissions rules for oil and gas infrastructure mandate continuous pressure monitoring at compressor stations. North American exploration operators consolidate procurement around integrated temperature-pressure transmitters. Houston's energy corridor drives hazardous area certification demand for thin film sensors in upstream applications.
Piezoresistive Pressure Sensor Market Competitive Environment
The competitive structure tilts toward diversified industrial conglomerates with captive MEMS fabrication capabilities. Bosch and STMicroelectronics anchor volume supply through in-house foundry operations, while specialized sensor houses compete on certification depth. Three archetypes dominate: integrated semiconductor conglomerates with automotive safety ratings, diversified connectivity suppliers with ceramic-cell platforms, and MEMS-focused specialists with medical-grade sterile fluid path designs. Consolidation pressures intensify through direct OEM-foundry relationships disintermediating Tier 1 module suppliers, and qualification timeline compression forcing portfolio rationalization toward highest-margin certification tracks.
Among diversified industrial technology providers, Sensata Technologies, TE Connectivity, and Honeywell International Inc. occupy positions spanning automotive, aerospace, and industrial process control segments. Sensata Technologies exemplifies the aerospace aftermarket archetype through FAA-certified repair station networks requiring eighteen to twenty-four month qualification periods. TE Connectivity represents industrial process control positioning with ceramic-cell platforms rated for corrosive media applications. Honeywell International Inc. anchors the diversified conglomerate model with presence across multiple certification regimes from ASIL-D automotive to hazardous area oil and gas classifications. Bosch and STMicroelectronics sit within the captive foundry tier, leveraging Reutlingen and European corridor fabrication for cost leadership in high-volume automotive absolute pressure lines.
| Leading Market Players |
|---|
| Sensata Technologies |
| STMicroelectronics |
| Honeywell International Inc. |
| Kistler |
| Bosch |
| TE Connectivity |
| NXP Semiconductors |
| Merit Sensor |
| Amphenol Advanced Sensors |
| Others |
Value Chain & Pricing Dynamics
Wafer-level vacuum encapsulation is compressing unit economics while simultaneously concentrating fabrication capacity in East Asian foundry corridors. This process transition rewards captive MEMS operations with cost leadership while forcing European and North American designers into dependency relationships for critical packaging capacity.
Pricing Analysis
ASIL-D functional safety certification anchors value-based pricing premiums for battery thermal management applications. Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade certification levels separates premium positioning from commodity segments. Cost compression in gauge pressure sensors for tire pressure monitoring intensifies as automotive OEMs unbundle procurement from Tier 1 module contracts. Tier 1 module suppliers exhibit highest price sensitivity due to margin pool compression, while medical device manufacturers demonstrate lowest sensitivity given sterile fluid path requirements.
Supply Chain Analysis
China's GB standards for intelligent manufacturing and South Korea's emissions trading scheme are reshaping sourcing patterns toward domestic-content-compliant suppliers. Taiwan, South Korea, and China concentrate critical deep reactive ion etching capacity and vacuum encapsulation infrastructure. Raw material flows draw from single-crystal silicon ingots, boron dopant chemicals, and gold-tin eutectic die-attach materials. Single-source vulnerability in 300mm SOI wafer supply creates chokepoint exposure for European sensor designers. Distribution runs through direct OEM-foundry relationships disintermediating traditional module supplier channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where REACH restrictions on lead-based solders and EPA methane emissions rules create regulatory moats that protect qualified incumbents from uncertified competitors.
For Market Incumbents: Deploy captive MEMS fabrication capacity in Reutlingen or Yangtze River Delta corridors to defend against emerging foundry specialists. Consolidate certification depth across ASIL-D automotive and FAA aerospace ratings to exploit eighteen-month qualification timeline compression that disadvantages new entrants lacking repair station network infrastructure. For New Entrants and Emerging Players: Launch via native IO-Link interface development targeting China's GB standards-mandated digital protocol transition. White-space concentrates in fiber-coupled medical sensors for Swiss and German infusion pump manufacturers seeking sub-millimeter catheter-compatible form factors through optical interrogation architectures. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified industrial conglomerates seeking captive MEMS fabrication capabilities. Long-term viability favors targets with in-house deep reactive ion etching expertise and existing ASIL-D or FAA certification portfolios. Watch for EPA enforcement intensity around methane monitoring mandates as inflection indicator for absolute pressure sensor replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive MEMS Foundry Investment | Reutlingen and Yangtze River Delta corridors enable cost leadership in automotive absolute pressure lines. |
| Native IO-Link Interface Development | China's GB standards mandate creates first-mover advantage over legacy analog 4-20 mA competitors. |
| FAA-Certified Repair Station Expansion | Eighteen-month qualification timelines compress revenue recognition windows for aerospace aftermarket channels. |
| Silicon Photonics Integration | Hybrid architectures enable optical readout eliminating electromagnetic interference in medical sterile fluid paths. |
| Gold-Tin Eutectic Process Migration | REACH restrictions on lead-based solders force thermal compensation algorithm recalibration across product lines. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with MEMS foundry operations managers, automotive Tier 1 procurement directors, FAA DER certification specialists, and hospital biomedical engineers combined with secondary validation from EPA enforcement databases, EU ECHA substance restriction registers, and China MIIT standardization announcements. Bottom-up sensor shipment triangulation against top-down automotive production and industrial emissions monitoring installation data established volume baselines.
Data-stream reconciliation across foundry capacity utilization rates, OEM platform sensor content specifications, and regulatory compliance installation mandates shaped the analytical framework. Segmentation dimensions modeled include pressure reference type, fabrication technology, end-use certification regime, and regional regulatory cluster. CAGRs derived from slope-interpolation of disclosed foundry expansion timelines and OEM electrification program procurement schedules. MEMS miniaturization adoption curves and silicon-on-insulator process yield improvements served as industry-specific forecast inputs across the projection horizon.
EPA enforcement intensity variations, REACH substance restriction scope expansions, and Taiwan Strait logistics disruptions are the dominant revision risks for forecast trajectories. Forecasts reflect documented assumptions on qualification timeline compression rates and foundry capacity expansion completion schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Anti-Collision Sensor Market
Sensors and Controls
Global Solid State Lidar Sensor Market
Sensors and Controls
Submarine Sensor Market
Sensors and Controls
Condition Monitoring Equipment Market
Sensors and Controls
Room Pressure Monitor Market
Sensors and Controls
Micro-Electro Mechanical Systems Market
Sensors and Controls
Capacitive Tactile Sensor Market
Sensors and Controls
Parking Sensors Market
Sensors and Controls
Exhaust Sensors for Automotive Market
Sensors and Controls
Pressure Sensor Market
Sensors and Controls
Magnetic Sensor Market
Sensors and Controls
Nanopositioning Piezo Actuator Market
Sensors and Controls
Micropump Market
Sensors and Controls
Global Load Cell Market
Sensors and Controls
Germany Digital Thermometer Market
Sensors and Controls
On-Board Magnetic Sensors Market