
 Artificial Intelligence (AI) Sensor Market | 2026-2036
Artificial Intelligence (AI) Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence (AI) Sensor Market Analytics
The EU AI Act is expanding compliance obligations for high-risk AI systems, directly elevating sensor traceability and data governance requirements across automotive and healthcare supply chains. Robert Bosch GmbH leverages its MEMS fabrication depth in Reutlingen to sustain captive supply advantages for pressure and inertial AI sensors. Sony Corporation anchors global image sensor capacity through its Kumamoto and Nagasaki fabs, dominating CMOS supply for computer vision workloads. STMicroelectronics competes through its vertically integrated 8-inch MEMS lines in Agrate and Catania, positioning itself for industrial automation demand.
Artificial Intelligence (AI) Sensors are transducer systems that convert physical stimuli—light, pressure, temperature, motion—into digital signals processed by embedded neural networks or edge AI accelerators, typically operating at sub-10 milliwatt power budgets and sub-100 microsecond inference latencies for real-time decision loops. Their primary purpose is to enable autonomous perception in machines without cloud dependency. Image sensors command the largest revenue pool today due to camera proliferation across autonomous vehicles and smart home security, while deep learning-enabled sensor fusion architectures represent the fastest-growing technology segment as OEMs consolidate multi-modal inputs. Pressure sensors remain a mature, high-volume category with thinning margins, whereas wearable device applications concentrate margin pools in compact, ultra-low-power temperature and biometric variants.
The FDA's evolving software-as-medical-device framework and the EU AI Act's conformity assessment requirements are forcing sensor manufacturers to document algorithmic performance, data drift, and post-market surveillance protocols before market access. China's NMPA and MIIT are synchronizing GB standards for AI-enabled automotive sensors with cybersecurity and functional safety mandates. ISO/IEC 23053 on AI system trustworthiness is emerging as a cross-border benchmark that procurement teams now embed in supplier qualification. Stakeholders must decide whether to build in-house edge AI inference stacks or rely on fabless partnerships as regulatory validation costs escalate.
Market Dynamics
Sensor-integrated edge AI architectures are compressing cloud dependency across automotive and industrial automation, forcing component suppliers to restructure around sub-10 milliwatt power envelopes and deterministic inference latency guarantees.
Growth Catalysts
- EU AI Act conformity mandates:High-risk AI system classification is accelerating procurement of traceable, validated sensor modules for autonomous vehicle perception stacks.
- MEMS fabrication scale-up:China's Yangtze River Delta manufacturing cluster is expanding captive 8-inch wafer capacity for pressure and inertial AI sensor variants.
- Level 3+ autonomous driving:Automotive OEM procurement of LiDAR and image sensor fusion systems is intensifying in Germany, Japan, and the United States.
Market Restraints
- Advanced node wafer costs:CMOS image sensor production at 22nm and below faces escalating foundry pricing from TSMC and Samsung captive allocation priorities.
- Single-source LiDAR component risk:Indium gallium arsenide photodetectors and specialized optical assemblies concentrate among limited German and Israeli suppliers.
- Inference thermal density limits:Edge AI accelerators embedded in sensor packages face hard physical constraints on dissipation in automotive underhood and wearable form factors.
Strategic Opportunities
- India industrial automation penetration:PLI scheme incentives for electronics manufacturing are drawing sensor packaging investments toward Gujarat and Tamil Nadu corridors.
- Neuromorphic sensing convergence:Event-based vision chips paired with spiking neural network accelerators are opening ultra-low-latency application spaces in robotics and drone navigation.
- FDA software-as-medical-device pathway:Streamlined premarket review for AI-enabled diagnostic sensors is expanding addressable market for continuous glucose and cardiac monitoring wearables.
Industry Challenges
- Edge AI firmware validation:ISO/IEC 23053 trustworthiness documentation and post-market surveillance protocols are extending product development cycles by 12-18 months for medical and automotive certifications.
- Multi-modal sensor fusion integration:Legacy industrial control systems lack standardized interfaces for synchronizing heterogeneous AI sensor outputs, forcing costly gateway middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence (AI) Sensor Market |
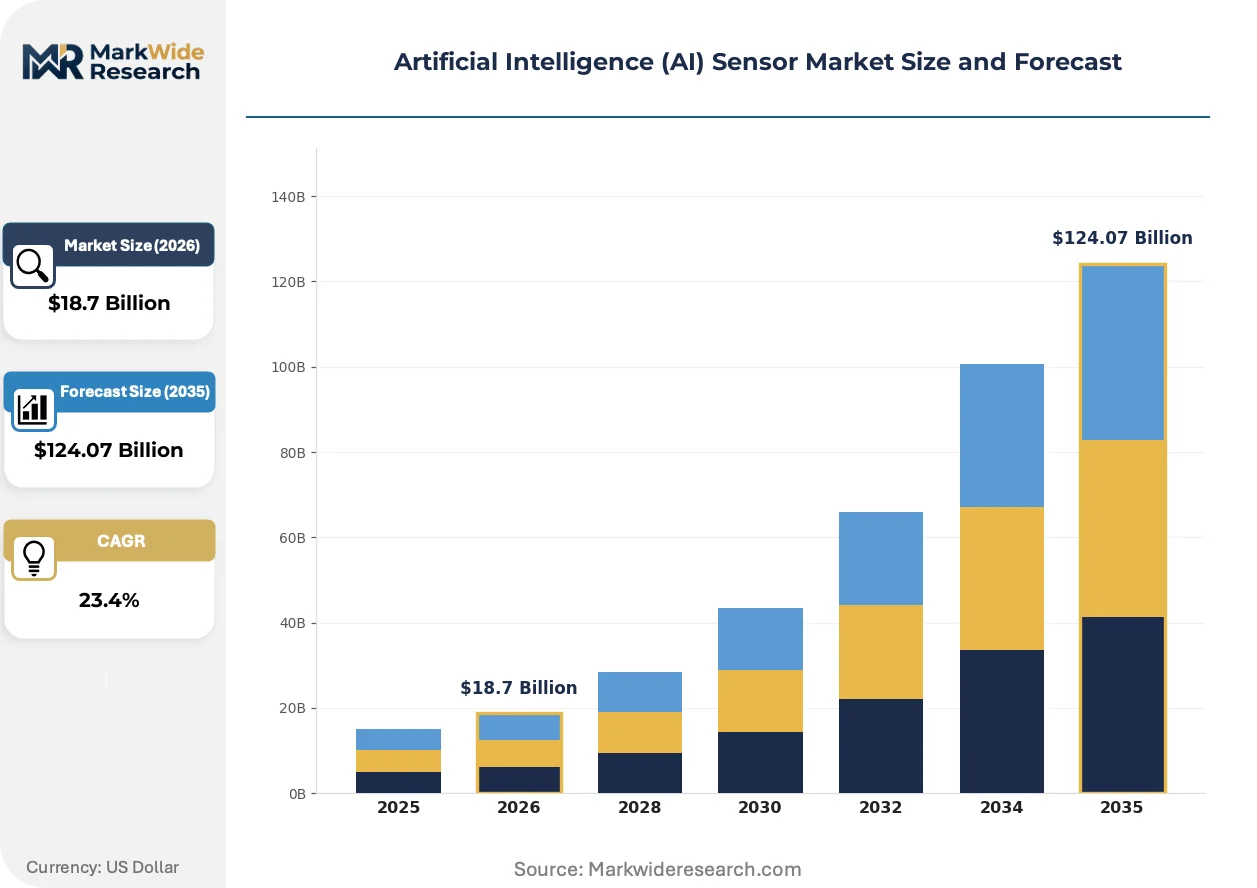
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $124.07 Billion |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Image Sensors, Infrared Sensors, Pressure Sensors, Temperature Sensors Technology: Machine Learning, Deep Learning, Computer Vision, Natural Language Processing End User: Automotive, Industrial, Healthcare, Consumer Electronics Application: Smart Homes, Autonomous Vehicles, Industrial Automation, Wearable Devices |
| Companies Covered | Sony Corporation, Robert Bosch GmbH, STMicroelectronics, Teledyne Technologies Incorporated, Sensata Technologies, Sensirion AG, Infineon Technologies, Keyence Corporation, Baidu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence (AI) Sensor Market Evolving Landscape
Silicon photonics and advanced packaging are collapsing the boundary between sensing and computation, enabling new form factors that embed neural inference directly at the pixel or MEMS element level.
Event-based vision sensors are absorbing frame-based image capture in robotics and autonomous navigation applications. These bio-inspired devices output asynchronous pixel-level brightness changes rather than full frames. Automotive Tier 1s in Germany and Japan are qualifying them for pedestrian detection at 10,000 frames-per-second equivalent temporal resolution. The technology is absorbing market share from conventional CMOS in motion-critical perception workloads.
The EU AI Act's risk-based classification system is mandating algorithmic transparency and data governance documentation for high-risk sensor-integrated systems. Manufacturers must now maintain version-controlled training datasets and drift monitoring protocols across product lifecycles. Medical device and automotive sensor suppliers are restructuring quality management systems to satisfy notified body expectations.
Buyers are consolidating procurement around vertically integrated sensor suppliers capable of delivering validated edge AI software stacks alongside hardware. Tier 1 automotive electronics purchasers in Stuttgart and Nagoya are reducing approved vendor lists from fifteen to five qualified partners. This concentration is most visible in LiDAR and 4D imaging radar categories where hardware-software co-validation costs exceed smaller competitors' capital access.
Artificial Intelligence (AI) Sensor Market Segmentation
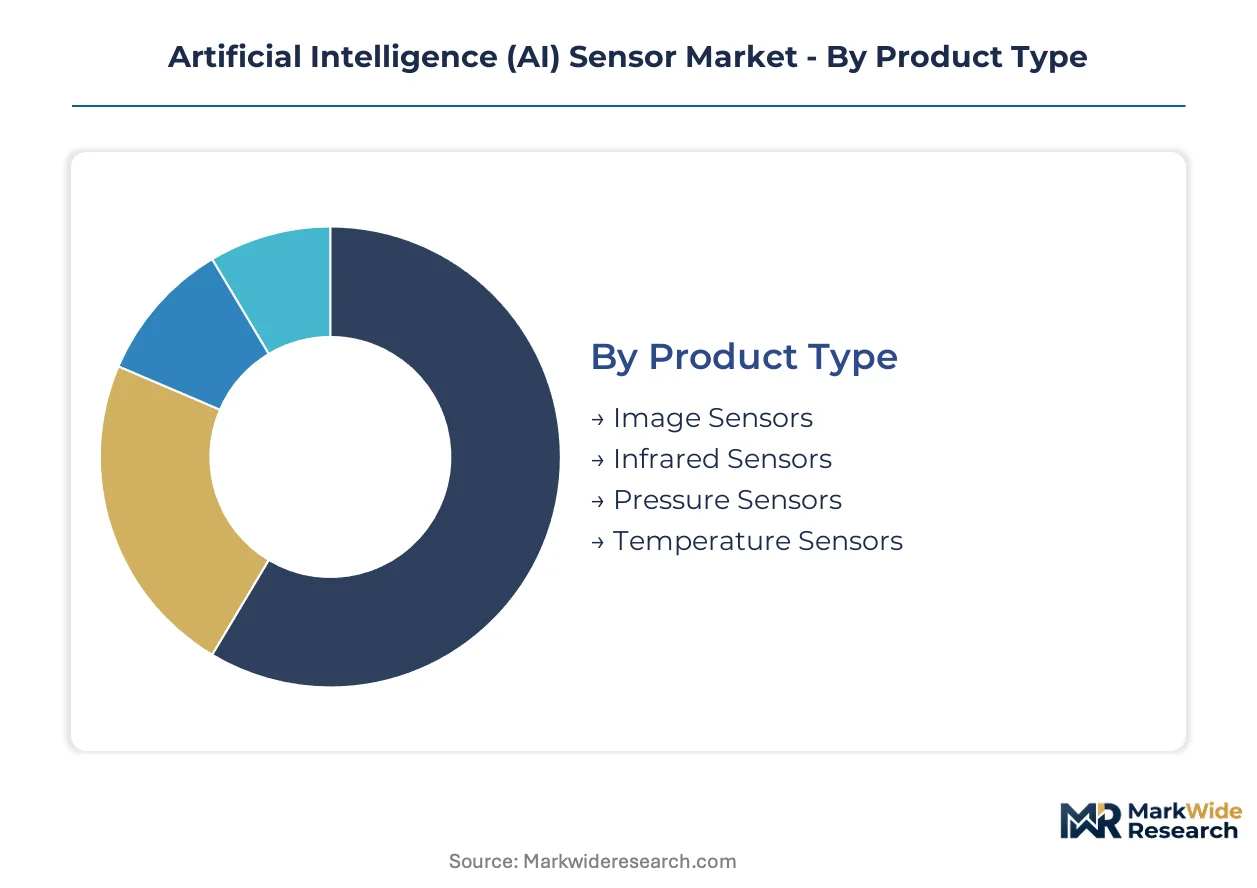
AI sensor procurement decisions hinge on matching inference latency, power budgets, and validation rigor to specific deployment environments. Segmentation reveals where hardware-software co-design investments concentrate and which combinations face regulatory bottlenecks.
Product Type:
Customization intensity spans from commoditized pressure variants to highly application-specific image sensor architectures.
- Image Sensors:CMOS architectures with embedded neural processing units operate at sub-100 microsecond latencies for real-time computer vision. Automotive OEMs in Germany and Japan dominate procurement for Level 3+ autonomous driving perception stacks, constrained by EU AI Act conformity documentation requirements.
- Pressure Sensors:MEMS-based transducers with analog-to-digital conversion and edge inference capability target industrial process control and automotive powertrain monitoring. China's Yangtze River Delta foundries are scaling 8-inch wafer capacity for high-volume, thinner-margin variants serving domestic EV manufacturers.
- Infrared Sensors:Thermal imaging arrays with on-chip AI classification enable night vision and industrial predictive maintenance.
- Temperature Sensors:Ultra-low-power biometric variants integrate into wearable form factors for continuous health monitoring under FDA software-as-medical-device pathways.
Leading the category by volume: Pressure Sensors. Growing fastest: Image Sensors.
Technology:
Algorithmic sophistication correlates directly with validation burden and customer willingness to pay for deterministic performance guarantees.
- Deep Learning:Multi-layer neural networks deployed on sensor-embedded accelerators enable complex pattern recognition in unstructured environments. Automotive Tier 1s in Stuttgart and Nagoya are consolidating procurement around suppliers offering hardware-software co-validated stacks, reducing approved vendor lists from fifteen to five partners.
- Computer Vision:Convolutional neural network architectures process pixel-level data for object detection and tracking. Event-based vision chips paired with spiking neural network accelerators are displacing frame-based capture in robotics and drone navigation applications requiring 10,000 frames-per-second equivalent resolution.
- Machine Learning:Traditional statistical learning methods on resource-constrained edge devices target predictive maintenance and anomaly detection.
- Natural Language Processing:Audio sensor fusion with semantic understanding enables voice-controlled industrial interfaces and smart home systems.
Highest validation costs attach to Deep Learning. Steepest expansion trajectory: Computer Vision.
End User:
Regulatory intensity and procurement scale separate capital-intensive verticals from high-volume consumer applications.
- Automotive:LiDAR and 4D imaging radar procurement concentrates among German, Japanese, and US OEMs pursuing Level 3+ autonomy. EU AI Act high-risk system classification mandates algorithmic transparency and post-market surveillance protocols, extending development cycles by 12-18 months.
- Healthcare:Continuous glucose and cardiac monitoring wearables leverage FDA streamlined premarket review for AI-enabled diagnostic sensors. Suppliers must document training dataset version control and drift monitoring across product lifecycles.
- Industrial:Smart factory deployments require multi-modal sensor fusion with legacy control system integration, forcing costly gateway middleware development.
- Consumer Electronics:Smart home security and voice assistants drive high-volume, price-sensitive demand for compact, low-power AI sensor modules.
Dominant procurement scale: Automotive. Tightest regulatory constraints: Healthcare.
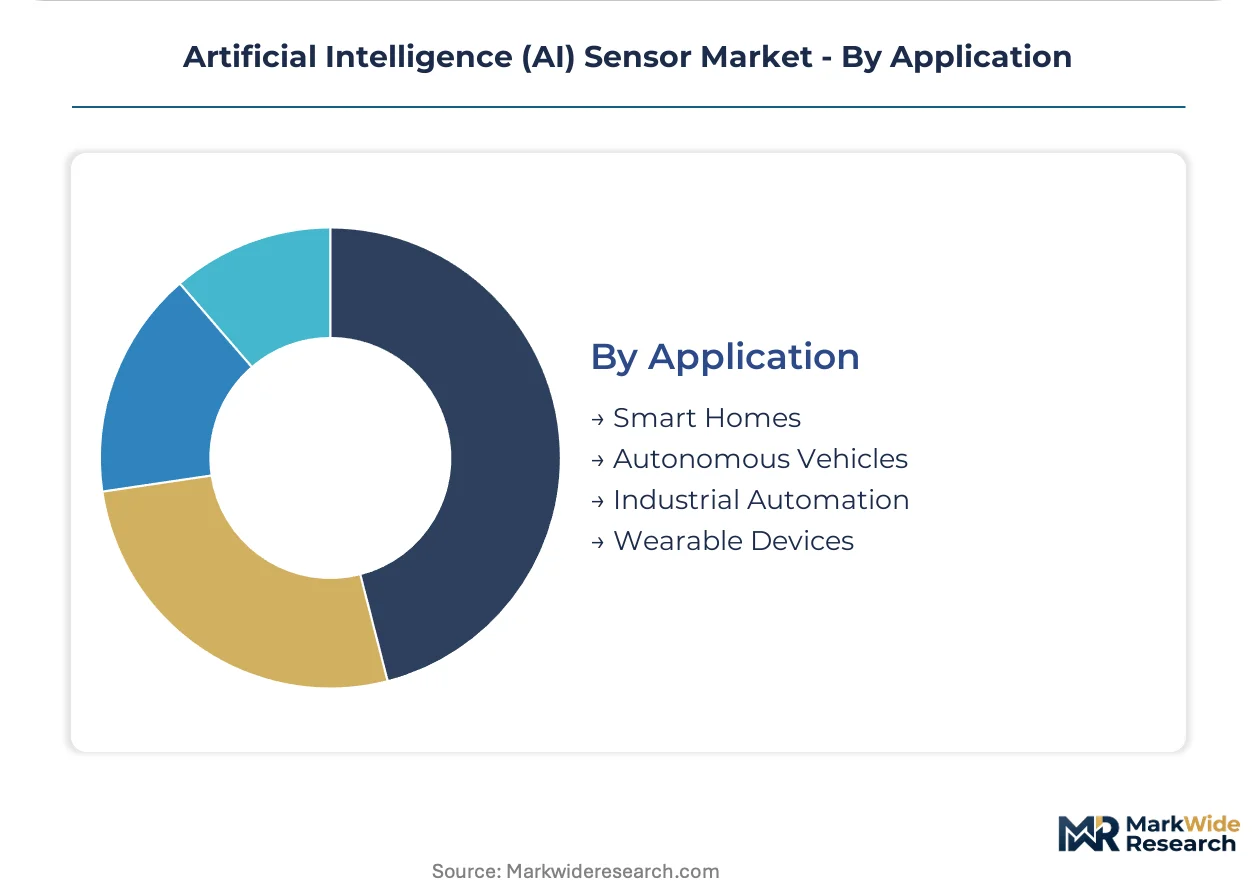
Application:
Latency requirements and safety criticality determine whether cloud-dependent or fully edge-native architectures prevail.
- Autonomous Vehicles:Multi-sensor fusion systems combining LiDAR, image, and radar inputs operate under deterministic latency guarantees for safety-critical decision loops. Indium gallium arsenide photodetector supply concentrates among limited German and Israeli sources, creating single-source vulnerability.
- Industrial Automation:Predictive maintenance and quality inspection deployments absorb event-based vision and pressure sensor arrays. India's PLI scheme incentives are drawing sensor packaging investments toward Gujarat and Tamil Nadu corridors.
- Smart Homes:Security cameras and environmental monitors prioritize cost-optimized edge inference over cloud connectivity.
- Wearable Devices:Compact temperature and biometric sensors target ultra-low-power operation with thermal density constraints limiting accelerator integration.
Highest safety certification burden: Autonomous Vehicles. Fastest geographic expansion: Industrial Automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta manufacturing cluster anchors AI sensor fabrication capacity, with domestic foundries scaling MEMS and CMOS production for edge computing workloads across automotive and industrial verticals.
United States
FDA software-as-medical-device pathways accelerate procurement of AI-enabled diagnostic sensors for continuous glucose and cardiac monitoring wearables. NHTSA guidelines for autonomous vehicle perception systems mandate deterministic latency guarantees for LiDAR and image sensor fusion stacks. Detroit and Austin corridors concentrate automotive Tier 1 electronics integration facilities serving domestic OEMs.
Germany
EU AI Act high-risk system classification extends development cycles for automotive perception sensors by 12-18 months through algorithmic transparency requirements. KBA type-approval processes now embed ISO/IEC 23053 trustworthiness documentation for Level 3+ autonomous driving components. Stuttgart and Munich industrial zones host captive MEMS fabrication and LiDAR assembly operations.
China
NMPA and MIIT synchronization of GB standards with cybersecurity mandates reshapes procurement criteria for AI-enabled automotive sensors. Domestic EV manufacturers in the Yangtze River Delta absorb high-volume pressure and inertial sensor output from expanded 8-inch wafer capacity. Shanghai and Suzhou fabs prioritize edge AI accelerators for smart factory deployments.
Japan
METI industrial automation incentives concentrate demand for multi-modal sensor fusion in Nagoya and Osaka manufacturing corridors. PMDA regulatory convergence with FDA software-as-medical-device frameworks opens wearable health monitoring applications for temperature and biometric variants. Kumamoto and Nagasaki production centers sustain CMOS image sensor supply for computer vision workloads.
India
PLI scheme electronics manufacturing incentives draw sensor packaging investments toward Gujarat and Tamil Nadu corridors for industrial automation penetration. CEA power sector mandates accelerate deployment of predictive maintenance sensor arrays in thermal and renewable generation facilities. Bangalore and Hyderabad technology clusters incubate edge AI firmware development for resource-constrained deployments.
Artificial Intelligence (AI) Sensor Market Competitive Landscape
The competitive structure tilts toward vertically integrated semiconductor conglomerates with captive MEMS and CMOS fabrication depth. Tier 1 automotive electronics purchasers in Stuttgart and Nagoya consolidate approved vendor lists from fifteen to five qualified partners, concentrating procurement around suppliers delivering hardware-software co-validated stacks. Two strategic archetypes dominate: diversified electronics conglomerates with in-house foundry capacity, and specialized sensor designers relying on fabless partnerships. Competitive moves center on backward integration into MEMS wafer production and strategic partnerships for algorithmic validation services.
Among diversified electronics conglomerates, Sony Corporation and Robert Bosch GmbH exemplify the vertically integrated archetype through captive supply advantages in image and pressure sensing categories. STMicroelectronics occupies a position within the European semiconductor tier, representing the vertically integrated model through dedicated MEMS production lines. These three anchors illustrate how fabrication depth determines competitive positioning as regulatory validation costs escalate and procurement concentration intensifies across automotive and healthcare supply chains.
| Leading Market Players |
|---|
| Sony Corporation |
| Robert Bosch GmbH |
| STMicroelectronics |
| Teledyne Technologies Incorporated |
| Sensata Technologies |
| Sensirion AG |
| Infineon Technologies |
| Keyence Corporation |
| Baidu |
| Others |
Value Network & Pricing Analysis
Automotive Tier 1 electronics purchasers in Stuttgart and Nagoya are consolidating approved vendor lists from fifteen to five qualified partners, forcing a value-based pricing model where hardware-software co-validation bundles command substantial premiums over commodity sensor modules.
Pricing Analysis
Outcome-based pricing anchored to deterministic latency guarantees and EU AI Act conformity documentation separates premium sensor-integrated stacks from standard MEMS variants. Price differentiation rests on certification grade—ISO/IEC 23053 trustworthiness tier versus basic CE marking—and captive foundry access for guaranteed supply allocation. Cost compression in high-volume pressure sensor categories is intensifying because China's Yangtze River Delta foundries are expanding 8-inch wafer capacity for domestic EV manufacturers. Automotive OEMs exhibit lowest price sensitivity for LiDAR fusion systems, while consumer electronics buyers drive aggressive negotiation on compact biometric modules.
Supply Chain Analysis
China's local-content mandates under MIIT cybersecurity guidelines are reshaping sourcing patterns for AI-enabled automotive sensors, compelling foreign suppliers to establish domestic packaging partnerships. Geographic supply concentration centers on China for MEMS fabrication, Japan for CMOS image sensors, and Germany for LiDAR optical assemblies. Raw material dependencies include indium gallium arsenide photodetectors, specialized optical glass substrates, and advanced node silicon wafers. Single-source vulnerability concentrates in InGaAs photodetector supply among limited German and Israeli sources. Distribution runs through direct OEM contracts for automotive qualification, with industrial automation channels utilizing specialized sensor distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in AI sensors has become a vertical-integration race where captive MEMS fabrication and algorithmic validation capabilities determine procurement access at major automotive and healthcare OEMs.
For Market Incumbents: Lock in long-term foundry allocation agreements with TSMC and domestic Yangtze River Delta fabs before capacity constraints tighten further. Deepen backward integration into specialized optical component supply to mitigate single-source InGaAs photodetector risk from German and Israeli suppliers. Prioritize ISO/IEC 23053 certification investment to maintain position on consolidated Tier 1 vendor lists. For New Entrants and Emerging Players: Direct-to-industrial-automation channels through India's PLI scheme electronics corridors offer lower qualification barriers than automotive Tier 1 supply. Target predictive maintenance and smart factory deployments in Gujarat and Tamil Nadu where legacy control system integration gaps create middleware partnership opportunities. Pursue fabless partnerships with established MEMS foundries to bypass capital-intensive fabrication entry costs. For Investors and Strategic Acquirers: The window for entry favors vertically integrated mid-cap specialists with captive 8-inch MEMS lines and existing automotive qualification footprints. Acquisition candidates showing algorithmic validation service revenue streams and EU AI Act conformity documentation capabilities present strongest long-term viability. Watch for FDA software-as-medical-device premarket submission volumes as inflection indicator for wearable health monitoring segment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Wafer Production | Captive 8-inch capacity in Reutlingen or Agrate insulates Bosch and STMicroelectronics from foundry pricing volatility. |
| Hardware-Software Co-Validation Partnership | Joint algorithmic performance documentation with notified bodies accelerates EU AI Act conformity for automotive Tier 1s. |
| Geographic Manufacturing Footprint Expansion | PLI scheme packaging investments in Gujarat and Tamil Nadu corridors capture India's industrial automation procurement growth. |
| Regulatory Certification Fast-Track Program | FDA software-as-medical-device pathway exploitation opens continuous glucose monitoring wearable addressable market. |
| Event-Based Vision Technology Licensing | Spiking neural network accelerator pairings with bio-inspired sensors displace frame-based CMOS in robotics navigation. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with MEMS fabrication executives, automotive Tier 1 procurement officers, biomedical engineers at hospital purchasing committees, and edge AI firmware developers. FDA 510(k) submissions, EU notified body conformity documentation, NMPA GB standard filings, and MIIT cybersecurity compliance records provided secondary validation. Bottom-up sensor shipment modeling and top-down OEM procurement budget analysis were triangulated against foundry capacity announcements.
Granularity-level modeling disaggregated volume and value outputs across product type, technology architecture, end-user vertical, and application latency requirement throughout the forecast period. Deep learning-enabled sensor fusion, computer vision inference stacks, machine learning predictive maintenance, and natural language processing audio interfaces were modeled separately. CAGRs were derived from segment-specific adoption curves calibrated to regulatory mandate timelines and OEM platform rollout schedules. Indium gallium arsenide supply constraints and EU AI Act implementation phasing served as industry-specific forecast sensitivity inputs.
Inputs from automotive Tier 1 procurement databases and foundry capacity utilization reports were available through the study window; gaps in real-time edge AI firmware performance benchmarking introduce uncertainty bands around inference latency claims. Forecasts reflect documented assumptions regarding Level 3+ autonomous driving adoption trajectories and FDA software-as-medical-device review streamlining. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Middle East and Africa Occupancy Sensors Market
Sensors and Controls
Acoustic Sensors Market
Sensors and Controls
Motion Control Encoders Market
Sensors and Controls
Vacuum Pressure Sensors Market
Sensors and Controls
Connected Sensors Market
Sensors and Controls
Calibrator Market
Sensors and Controls
Global MEMS and Sensors Market
Sensors and Controls
Capacitive Proximity Sensor Market
Sensors and Controls
Thermal Scanners Market
Sensors and Controls
Global Multi-Turn Potentiometer Market
Sensors and Controls
Predictive Touch Market
Sensors and Controls
Photodiode Sensors Market
Sensors and Controls
Differential Pressure Sensor Market
Sensors and Controls
Mexico Smart Ventilation Fans Market
Sensors and Controls
Accelerometer and Gyroscope Market
Sensors and Controls
US Distributed Acoustic Sensing Market