
 Battery Maintenance Service Market | 2026-2036
Battery Maintenance Service Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Maintenance Service Market Insights
China is fragmenting the competitive landscape for battery maintenance services as domestic cell manufacturing scales strain aftermarket capacity. Johnson Controls International leverages its building automation footprint to bundle thermal management with cell monitoring contracts. EnerSys anchors North American industrial demand through its motive power service network. GS Yuasa competes on deep specialization in lead-acid regeneration for Asian forklift fleets.
Battery maintenance service encompasses diagnostic testing, electrolyte analysis, cell balancing, thermal regulation, and capacity restoration performed on electrochemical storage systems to sustain rated performance and defer capital replacement. Preventive services dominate contract value as scheduled impedance testing and temperature mapping extend cycle life in critical infrastructure applications. Lithium-ion maintenance is the fastest-expanding technology segment, driven by thermal runaway prevention protocols and state-of-health algorithms that require specialized technician training. Small and medium scale capacity tiers concentrate margin pools where distributed energy storage and commercial EV fleets generate recurring service revenue.
The EPA governs spent battery handling and recycling thresholds under RCRASubtitle C, while OSHA mandates arc flash and confined space protocols for technician safety in battery rooms. IEEE 1188 and 1635 standards establish float voltage and specific gravity baselines that service providers must document for warranty compliance. Stakeholders should track how NHTSA's emerging EV battery safety rules extend maintenance disclosure requirements to second-life automotive packs.
Market Dynamics
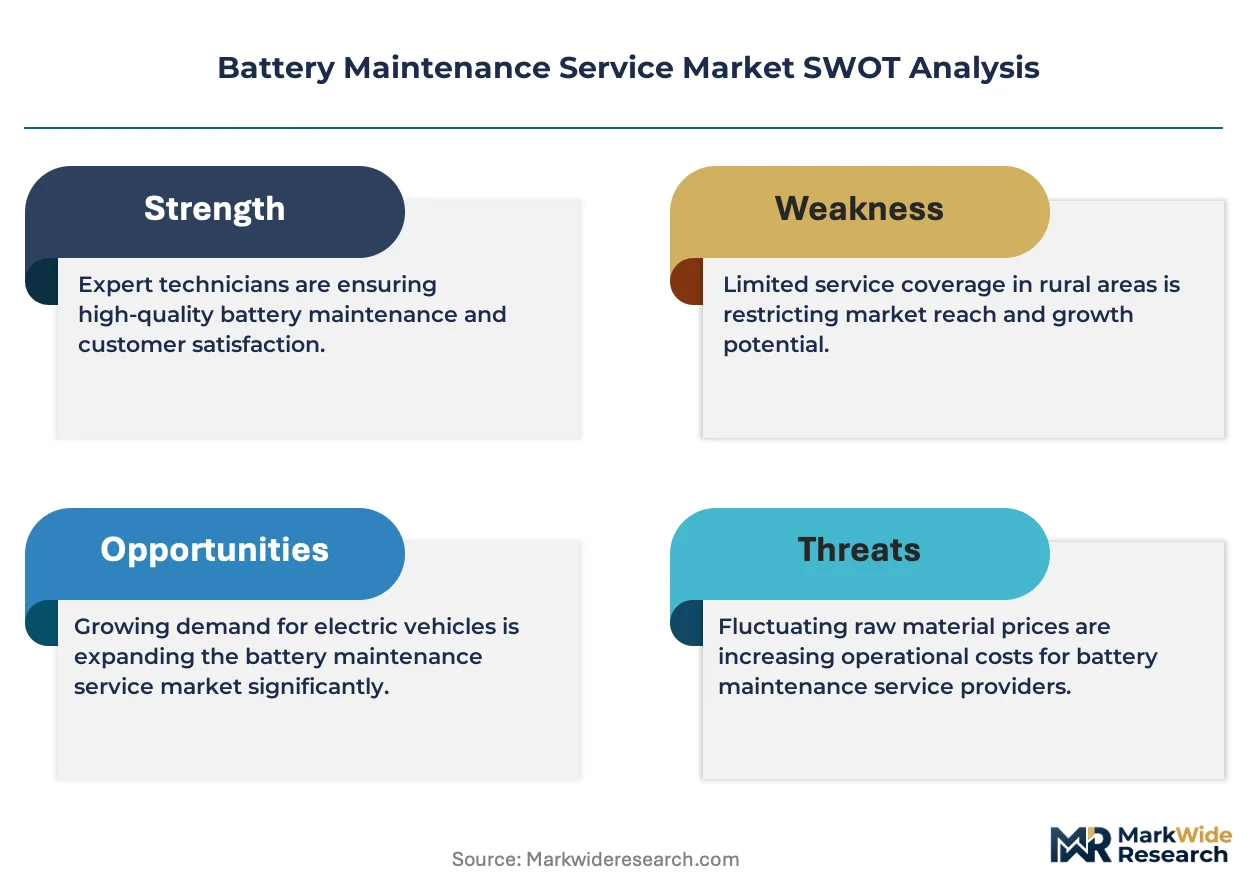
The Battery Maintenance Service Market is being fundamentally restructured by the EPA's tightening hazardous waste rules under RCRA Subtitle C, which extend service lifecycles and mandate specialized disposal protocols for lithium-ion systems across critical infrastructure.
Growth Catalysts
- RCRA Subtitle C Compliance:The EPA's spent battery handling thresholds force data center operators into preventive maintenance contracts to defer costly disposal and replacement cycles.
- Lithium-ion Thermal Runaway Prevention:State-of-health algorithms and impedance testing protocols create recurring revenue streams for technicians certified in electrochemical diagnostics.
- Germany Grid Stabilization Demand:Industrial battery parks require specialized electrolyte monitoring and capacity testing regimes that anchor long-term service agreements.
Market Restraints
- Lithium Carbonate Price Volatility:Raw material cost swings compress margins on cell replacement services bundled with maintenance contracts.
- China Aftermarket Capacity Strain:Domestic cell manufacturing scale overwhelms qualified service technician supply, fragmenting quality standards.
- Lead-acid Substitution Pressure:Forklift fleet electrification displaces regeneration-specialized providers dependent on mature lead-acid chemistry.
Strategic Opportunities
- Second-life EV Pack Servicing:NHTSA's emerging battery safety disclosure rules create compliance-driven demand for automotive pack refurbishment and resale certification.
- Commercial EV Fleet Electrification:Distributed charging infrastructure generates recurring thermal management and cell balancing contracts outside traditional industrial channels.
- IEEE 1635 Standardization:Float voltage documentation mandates open warranty-compliant service slots for independent providers against OEM captive networks.
Industry Challenges
- Arc Flash Certification Bottlenecks:OSHA confined space protocols create technician training backlogs that limit service capacity expansion in battery room environments.
- Legacy System Integration Complexity:State-of-health algorithms must interface with heterogeneous BMS architectures across multiple cell generations and OEM platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Maintenance Service Market |
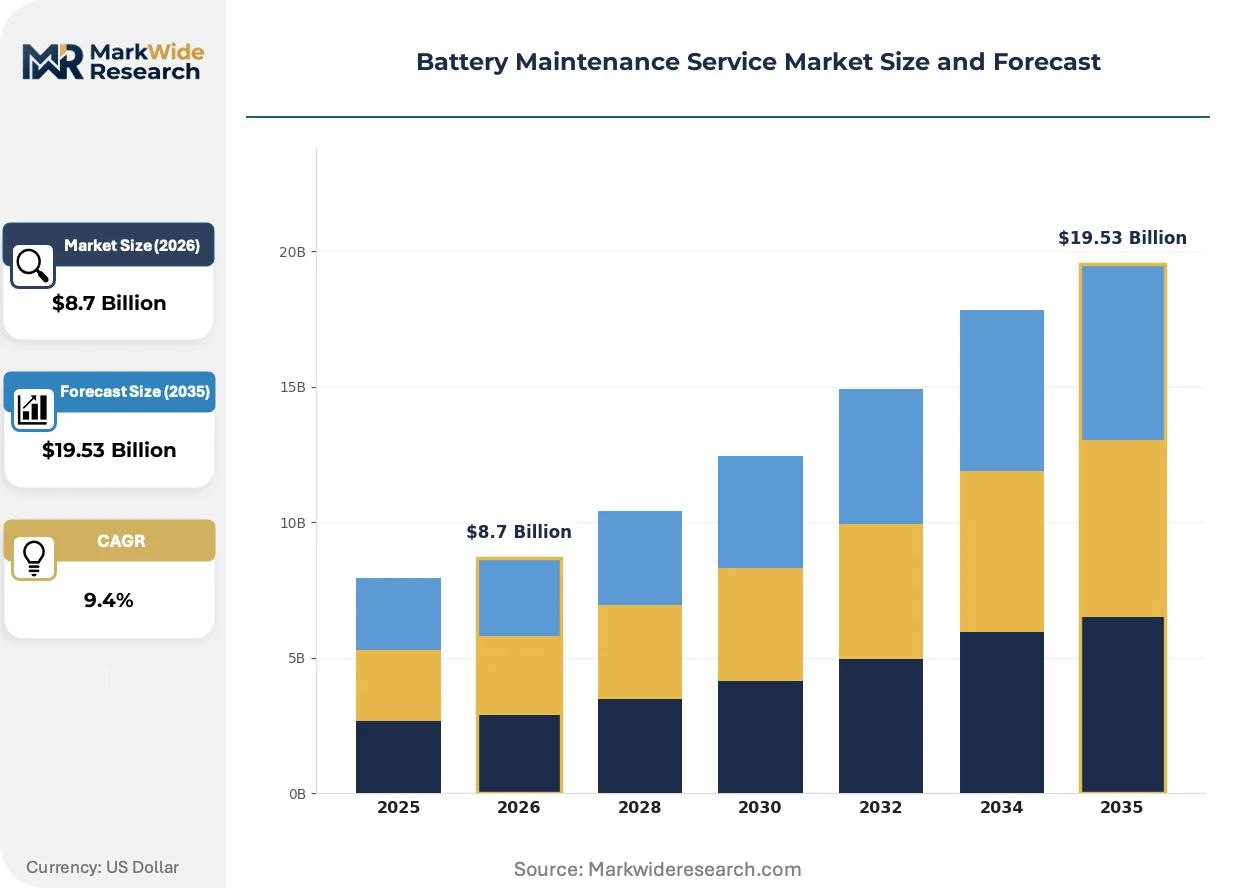
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: On-Site Maintenance, Preventive Services, Emergency Repairs, Monitoring Services End User: Industrial Facilities, Automotive OEMs, Telecommunications, Electric Utilities Technology: Lead-Acid, Lithium-Ion, Nickel-Cadmium, Flow Batteries Capacity: Small Scale, Medium Scale, Large Scale, Utility-Scale |
| Companies Covered | Johnson Controls International, A123 Systems, GS Yuasa, EnerSys, Exide Technologies, AAA Battery, Batteries Plus, AutoZone, Battery Solutions LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Maintenance Service Market Trends and Innovations
Diagnostic and thermal management technologies are converging with predictive analytics platforms, reshaping how service providers structure recurring revenue and technician deployment models across electrochemical storage assets.
Impedance spectroscopy hardware is hybridizing with cloud-based degradation modeling to enable remote state-of-health monitoring. Data center operators in Virginia and Texas are deploying these systems at scale to reduce on-site technician visits. The technology is hybridizing preventive and corrective maintenance into continuous optimization contracts that compress traditional service intervals.
The EU's F-Gas Regulation is phasing down fluorinated greenhouse gases used in battery thermal management systems. Industrial battery park operators in Germany must retrofit cooling infrastructure or face operating restrictions. Cell balancing service providers are responding by certifying technicians in CO2-based and water-glycol alternative cooling architectures.
Facility managers are unbundling after-sales service from original equipment procurement, driving direct contracting with specialized maintenance firms. This pattern displaces OEM captive service networks in North American data center verticals. The shift is most visible in hyperscale deployments where procurement teams negotiate multi-site thermal management agreements independent of cell supply contracts.
Battery Maintenance Service Market Segmentation
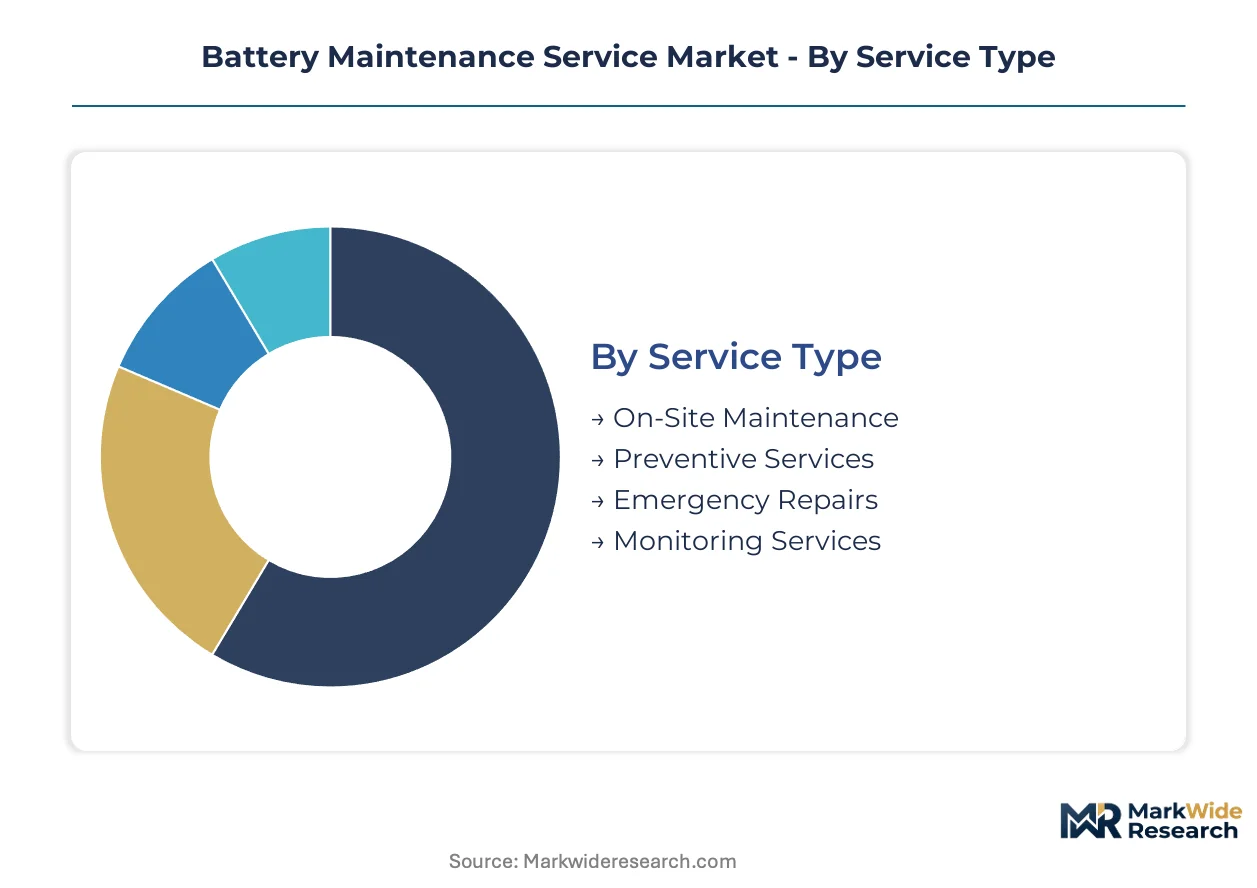
Battery maintenance contracts vary sharply in margin structure and technician deployment intensity across service modalities and end-use applications. Service providers calibrate pricing and resource allocation differently for scheduled preventive regimes versus reactive emergency dispatches, creating distinct competitive arenas within the same technical discipline.
Service Type:
After-sales-service intensity peaks in recurring preventive contracts that embed continuous monitoring and scheduled technician visits, while emergency repair models concentrate margin in sparse, high-value dispatches.
- Preventive Services:Scheduled impedance testing, electrolyte analysis, and thermal mapping protocols extend cycle life in critical infrastructure. Data center operators in Virginia and Texas deploy these contracts at scale to defer capital replacement under EPA RCRA Subtitle C compliance pressure.
- On-Site Maintenance:Physical technician deployment for cell balancing, capacity restoration, and hardware replacement. German industrial battery parks anchor demand for specialized electrolyte monitoring regimes that require certified personnel on facility premises.
- Monitoring Services:Remote state-of-health tracking via impedance spectroscopy and cloud-based degradation modeling.
- Emergency Repairs:Reactive thermal runaway response and corrective interventions following BMS fault alerts.
By volume, Preventive Services leads. By growth pace, Monitoring Services is ahead.
End User:
Cost tier segmentation separates capital-intensive utility contracts from distributed commercial deployments with diverging procurement authority structures.
- Industrial Facilities:Manufacturing plants and warehouse operations with motive power fleets and backup power systems. Forklift electrification in North American distribution centers generates recurring thermal management contracts outside traditional OEM channels.
- Telecommunications:Cell tower backup systems and edge computing infrastructure requiring high-availability power assurance. Tower operators prioritize float voltage documentation under IEEE 1635 warranty compliance mandates.
- Electric Utilities:Grid stabilization battery parks and substation backup systems with utility-scale service agreements.
- Automotive OEMs:Second-life EV pack refurbishment and resale certification driven by emerging NHTSA safety disclosure requirements.
Industrial Facilities dominates contract count. Electric Utilities commands the highest per-site service value.
Technology:
Application maturity determines whether maintenance protocols emphasize regeneration chemistry or thermal runaway prevention systems.
- Lithium-Ion:State-of-health algorithms and thermal management protocols for electrochemical storage with elevated fire risk profiles. The chemistry demands specialized technician training in arc flash and confined space protocols per OSHA mandates.
- Lead-Acid:Established regeneration and electrolyte restoration techniques for mature industrial fleets. Asian forklift markets sustain demand for deep specialization in capacity recovery chemistry.
- Nickel-Cadmium:Niche aviation and railway applications with specific gravity baselines under IEEE 1188 documentation standards.
- Flow Batteries:Vanadium and zinc-bromine systems requiring membrane maintenance and electrolyte rebalancing in grid storage configurations.
Lead-Acid retains the largest installed base. Lithium-Ion is expanding most quickly as fleet electrification accelerates.
Capacity:
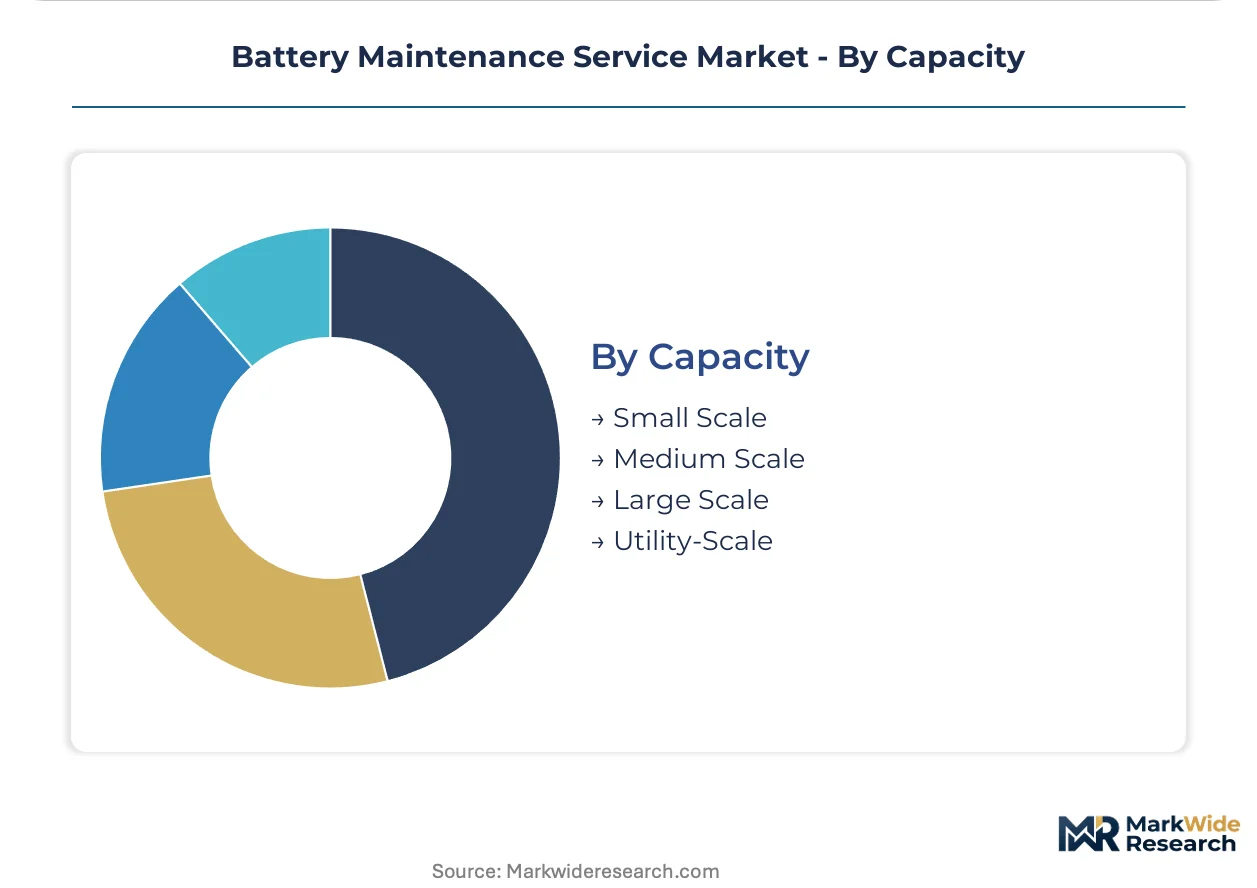
Margin pools concentrate in small and medium tiers where distributed energy storage and commercial EV fleets generate recurring revenue without utility-scale procurement complexity.
- Small Scale:Commercial EV charging infrastructure and building-level backup systems. Distributed deployments in Texas and California generate thermal management contracts with standardized service intervals.
- Medium Scale:Industrial battery parks and data center UPS systems with multi-cell architectures requiring cell balancing expertise. German grid stabilization facilities anchor specialized electrolyte monitoring demand in this tier.
- Large Scale:Regional storage installations with dedicated maintenance crews and captive service agreements.
- Utility-Scale:Transmission-connected battery parks with OEM-integrated long-term service contracts and minimal independent provider penetration.
Medium Scale captures the densest service provider margins. Small Scale is gaining share fastest as commercial fleet electrification disperses demand geographically.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technician certification bottlenecks and hazardous waste regulations concentrate service capacity in jurisdictions with mature industrial safety frameworks. Germany, the United States, China, Japan, and India each anchor distinct demand patterns shaped by local energy infrastructure and enforcement regimes.
Germany
Industrial battery parks for grid stabilization drive specialized electrolyte monitoring and capacity testing regimes. The EU F-Gas Regulation phases down fluorinated greenhouse gases in thermal management systems, forcing cooling infrastructure retrofits. Bavaria and North Rhine-Westphalia host dense clusters of utility-scale storage facilities where CO2-based cooling certification commands premium service rates.
United States
Data center operators in Virginia and Texas deploy impedance spectroscopy systems at scale to reduce on-site technician visits. EPA RCRA Subtitle C governs spent lithium-ion handling thresholds, extending preventive maintenance contract durations. Northern Virginia's hyperscale corridor unbundles thermal management agreements from OEM captive networks.
China
Domestic cell manufacturing scale strains qualified service technician supply, fragmenting quality standards across aftermarket capacity. MIIT oversees electrochemical storage safety protocols for industrial installations. The Yangtze River Delta and Pearl River Delta concentrate battery park construction where electrolyte monitoring expertise remains scarce relative to production growth.
Japan
Deep specialization in lead-acid regeneration sustains service demand from mature forklift fleets and railway backup systems. METI sets technical standards for state-of-health algorithms in grid-connected installations. The Kansai region around Osaka anchors industrial battery maintenance networks serving manufacturing plant motive power requirements.
India
Commercial fleet electrification disperses small-scale thermal management contracts across distributed charging infrastructure. CEA mandates safety documentation for battery energy storage systems above specified capacity thresholds. Maharashtra and Karnataka concentrate data center UPS maintenance demand where IEEE 1635 float voltage compliance creates warranty-linked service slots.
Battery Maintenance Service Market Competitive Landscape
Building automation integrators and industrial motive power networks split the market between bundled facility services and specialized electrochemical maintenance. The structure tilts toward consolidation in North American data center verticals while fragmenting across China's strained technician supply. Three archetypes dominate: OEM-captive service divisions, independent thermal management specialists, and diversified industrial asset maintenance platforms. Geographic expansion and technician certification partnerships constitute the primary competitive vectors.
Within the diversified industrial platform tier, Johnson Controls International and EnerSys exemplify contrasting scale strategies. Johnson Controls leverages building automation footprints to bundle thermal management with cell monitoring contracts across facility portfolios. EnerSys anchors North American industrial demand through its motive power service network. GS Yuasa occupies a position as a chemistry-specialist archetype, competing on deep lead-acid regeneration expertise for Asian forklift fleet operators.
| Leading Market Players |
|---|
| Johnson Controls International |
| A123 Systems |
| GS Yuasa |
| EnerSys |
| Exide Technologies |
| AAA Battery |
| Batteries Plus |
| AutoZone |
| Battery Solutions LLC |
| Others |
Pricing and Supply Chain Analysis
China's domestic cell manufacturing scale concentrates upstream lithium carbonate and electrolyte supply, anchoring margin pools in downstream preventive maintenance contracts where EPA RCRA Subtitle C compliance extends service lifecycles and defers costly replacement cycles for data center operators.
Pricing Analysis
EPA RCRA Subtitle C dictates the pricing tier structure across the battery maintenance service market. Three-tier pricing structure across premium, standard, and economy levels separates OEM-captive networks with full thermal management bundling from independent providers with IEEE 1635 warranty documentation and economy-tier commodity testers lacking arc flash certification. Cost compression in economy-tier cell replacement services is intensifying because lithium carbonate price volatility compresses margins on bundled maintenance contracts. Data center operators in hyperscale deployments exhibit lowest price sensitivity, while distributed commercial EV fleet managers drive hardest bargain on standardized thermal management intervals.
Supply Chain Analysis
Export controls on impedance spectroscopy hardware and state-of-health algorithm IP limit flows from US and European equipment vendors to Chinese service providers. Supply concentrates in China for lithium-ion cells, South Korea for advanced BMS components, and Germany for industrial-grade electrolyte monitoring instrumentation. Technician training infrastructure draws from IEEE 1188 documentation standards, OSHA confined space certification programs, and vendor-specific thermal runaway response protocols. Single-source vulnerability runs through China's qualified technician supply relative to its battery park construction pace. Distribution runs through OEM-captive service divisions, independent thermal management specialists, and diversified industrial asset maintenance platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement is shifting toward unbundled after-sales service contracts as hyperscale data center operators consolidate buying power across multi-site thermal management agreements independent of cell supply.
For Market Incumbents: Insulate recurring revenue streams by deepening technician certification partnerships in CO2-based cooling architectures before EU F-Gas Regulation retrofit deadlines strand legacy fluorinated gas service capacity. Lock in long-term cell monitoring contracts with Virginia and Texas data center clusters where impedance spectroscopy deployment reduces competitor access. Vertical integration into cloud-based degradation modeling platforms defends against independent providers exploiting IEEE 1635 documentation mandates. For New Entrants and Emerging Players: Build out white-space presence in second-life EV pack servicing where NHTSA safety disclosure rules create compliance-driven demand without entrenched OEM-captive networks. Penetrate India's distributed commercial fleet electrification corridor where CEA mandates generate warranty-linked service slots for IEEE 1635 float voltage documentation. Lead with CO2-based cooling certification as differentiated entry credential against fluorinated gas incumbents facing EU retrofit pressure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed diversified industrial platforms holding fragmented technician networks across North American motive power verticals. Five-to-ten year viability hinges on lithium-ion thermal runaway prevention protocols displacing lead-acid regeneration chemistry in forklift fleet electrification. Watch for NHTSA finalizing EV battery safety disclosure rules as inflection signal for second-life pack refurbishment certification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Partnerships | CO2-based cooling credentials capture EU F-Gas Regulation retrofit contracts in German industrial battery parks. |
| Impedance Spectroscopy Platform Integration | Remote state-of-health monitoring compresses service intervals for Virginia hyperscale data center operators. |
| Second-Life EV Pack Servicing Buildout | NHTSA safety disclosure compliance creates resale certification revenue outside OEM-captive networks. |
| Geographic Expansion into India | CEA-mandated documentation slots open warranty-compliant service opportunities in Maharashtra data centers. |
| Backward Integration into Cloud Analytics | In-house degradation modeling platforms defend margin against IEEE 1635-enabled independent providers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA enforcement databases, IEEE standards documentation, and EU regulatory filings. Interviews with data center facility managers, battery maintenance technicians, OEM service directors, and industrial procurement leads informed service contract structure and pricing dynamics. Secondary validation drew from OSHA certification records, NHTSA docket filings, and customs data on impedance spectroscopy equipment imports. Bottom-up technician deployment models and top-down contract value estimates triangulated market sizing.
Forecast inputs include service modality mix shifts, technology substitution rates, and regulatory compliance cost pass-through across the projection horizon. Segmentation dimensions encompass service type, end-user vertical, battery chemistry, and capacity tier with regional regulatory cluster overlays. CAGRs derive from technician supply constraints, RCRA Subtitle C enforcement intensity, and lithium-ion fleet penetration curves. Industry-specific inputs incorporate F-Gas Regulation phase-down schedules and NHTSA rulemaking timelines.
Practitioners should monitor lithium carbonate price volatility, EPA enforcement variance across states, and China technician training throughput for early signals. Forecasts reflect assumptions on regulatory compliance cost trajectories and technology substitution pace. Material shifts in NHTSA final rule timing or EU F-Gas Regulation acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
New Energy Battery Structural Parts Market
Battery Infrastructure
United Kingdom Electric Vehicle Battery Separator Market
Battery Infrastructure
Lithium-Ion Battery Housing Cases Market
Battery Infrastructure
China Electric Vehicle Battery Electrolyte Market
Battery Infrastructure
India Electric Vehicle Battery Separator Market
Battery Infrastructure
Electric Vehicle Battery Swapping Market
Battery Infrastructure
Smart Battery Swap Station Market
Battery Infrastructure
Germany Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery-As-A-Service Market
Battery Infrastructure
Substation Battery Market
Battery Infrastructure
Advance Battery Technologies Market
Battery Infrastructure
North America Electric Vehicle Battery Electrolyte Market
Battery Infrastructure
China Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Solar Containers Market
Battery Infrastructure
Carbon Battery Bank Market
Battery Infrastructure
North America Electric Vehicle Battery Separator Market