
 Electric Vehicle Showroom Charger Market | 2026-2036
Electric Vehicle Showroom Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Showroom Charger Market Insights
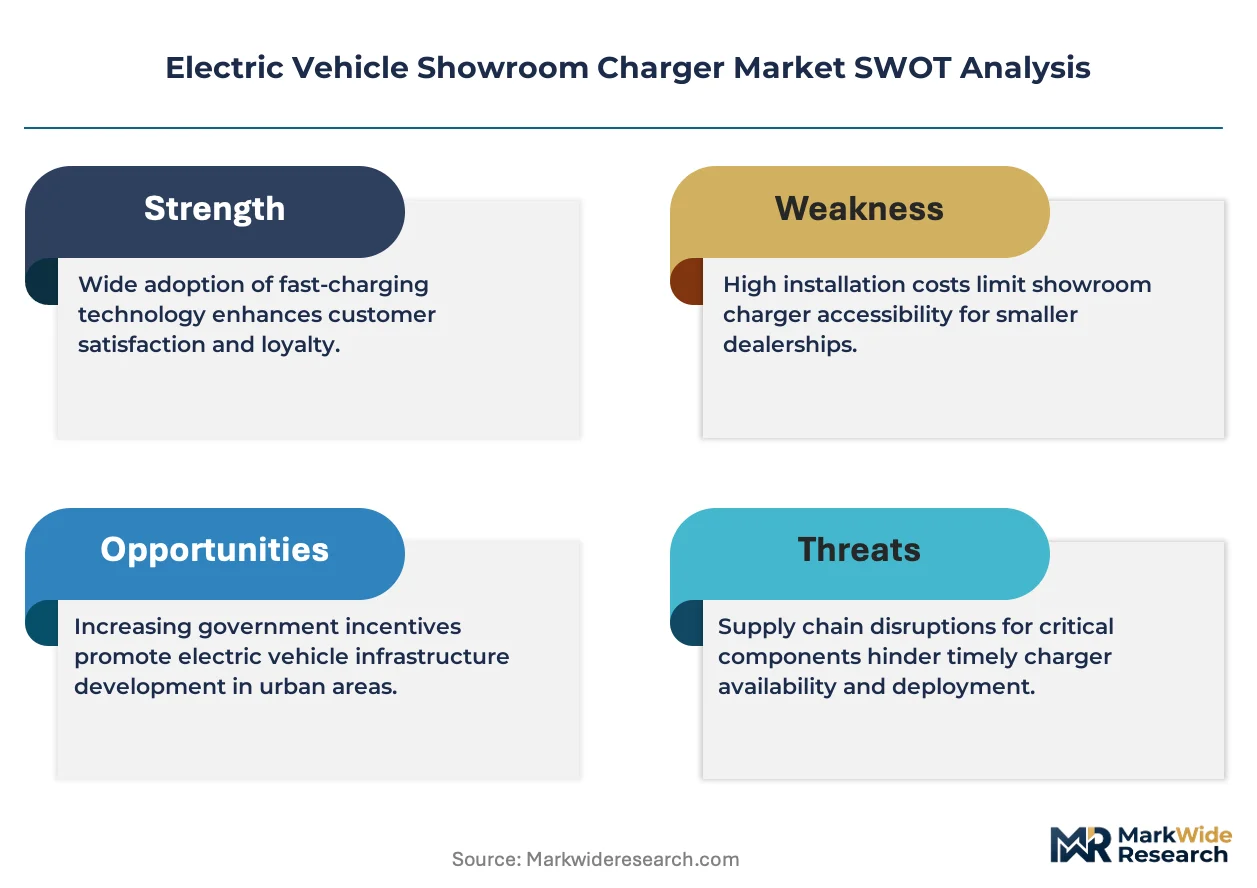
Asset-light leasing and power-purchase agreements for showroom charging hardware is fragmenting the competitive landscape, lowering barriers for regional installers and dealership groups to deploy branded charging without capital ownership. ABB leverages its electrification portfolio to anchor large-format showroom projects across European automotive retail networks. ChargePoint competes through software-integrated subscription models that bundle hardware, installation, and network management for multi-location dealer groups. Siemens sustains manufacturing scale advantages in modular AC and DC systems designed for indoor retail environments.
An electric vehicle showroom charger is a fixed electrical supply unit installed within automotive retail or display facilities, typically delivering AC power at 7–22 kW or DC fast charging at 50–350 kW to demonstrate charging speed and compatibility to prospective buyers. Its primary commercial purpose is to simulate ownership experience and reduce range anxiety during the sales process. Level 2 charger deployments dominate current showroom specifications due to lower electrical infrastructure costs and adequate dwell-time alignment with typical customer visits. DC fast charger installations are expanding fastest among premium brand flagships seeking to differentiate through demonstration of ultra-rapid replenishment capability. Connector type selection increasingly favors CCS configurations as North American and European OEMs consolidate away from CHAdeMO standards.
The US Federal Communications Commission governs wireless charger electromagnetic emissions, while the National Electrical Code through local AHJs mandates installation standards that directly shape product certification requirements and contractor qualification. The EU F-Gas Regulation and CE marking directives constrain cooling system designs for high-power indoor DC units, compressing margins for non-compliant imports. Stakeholders must monitor evolving building code harmonization between jurisdictions and pre-position for interoperability mandates that could obsolete proprietary connector strategies.
Market Dynamics
The US Inflation Reduction Act's commercial clean vehicle credits are compressing deployment timelines for showroom charging infrastructure, forcing automotive retailers to accelerate capital allocation decisions ahead of incentive phase-downs.
Growth Catalysts
- Policy Incentives:The IRA's Section 30C tax credits cover up to 30% of hardware and installation costs for qualified commercial EV charging property, directly reducing payback periods for dealership capital investments.
- China Experience Centers:Domestic OEMs operate thousands of branded retail facilities requiring captive charging infrastructure to demonstrate vehicle-technology integration during extended customer visits.
- Range Anxiety Simulation:DC fast charging demonstrations at premium flagships compress perceived charging time from hours to minutes, converting skeptical prospects into buyers during single showroom visits.
Market Restraints
- Electrical Infrastructure Costs:High-power DC installations require utility service upgrades, transformer replacements, and demand charge management systems that inflate total project costs beyond hardware sticker prices.
- Copper and Semiconductor Supply:Power electronics and cabling depend on concentrated mining and foundry capacity in Chile, the Democratic Republic of Congo, and Taiwan, exposing project timelines to raw material volatility.
- EU F-Gas Cooling Constraints:The regulation phases down hydrofluorocarbon refrigerants used in high-power DC unit thermal management, forcing redesign cycles that delay product certification for indoor retail environments.
Strategic Opportunities
- Asset-Light Leasing Models:Power-purchase agreements and hardware-as-a-service contracts allow regional dealer groups to deploy branded charging without capital ownership, fragmenting incumbent supplier relationships.
- Wireless Induction Integration:Parking pad demonstrations in premium showrooms merge automated charging with autonomous vehicle positioning, creating differentiated customer experiences unattainable with cable-based systems.
- Building Code Harmonization:Emerging interoperability mandates across US jurisdictions threaten proprietary connector strategies, creating first-mover advantage for suppliers pre-positioning with open-standard hardware architectures.
Industry Challenges
- Certification Timeline Compression:The National Electrical Code's evolving local amendments require jurisdiction-by-jurisdiction product approval, extending deployment schedules for multi-location dealer networks.
- Integration with Legacy Dealership Management Systems:Charging network software must interface with existing customer relationship platforms, inventory systems, and service scheduling tools without disrupting established operational workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Showroom Charger Market |
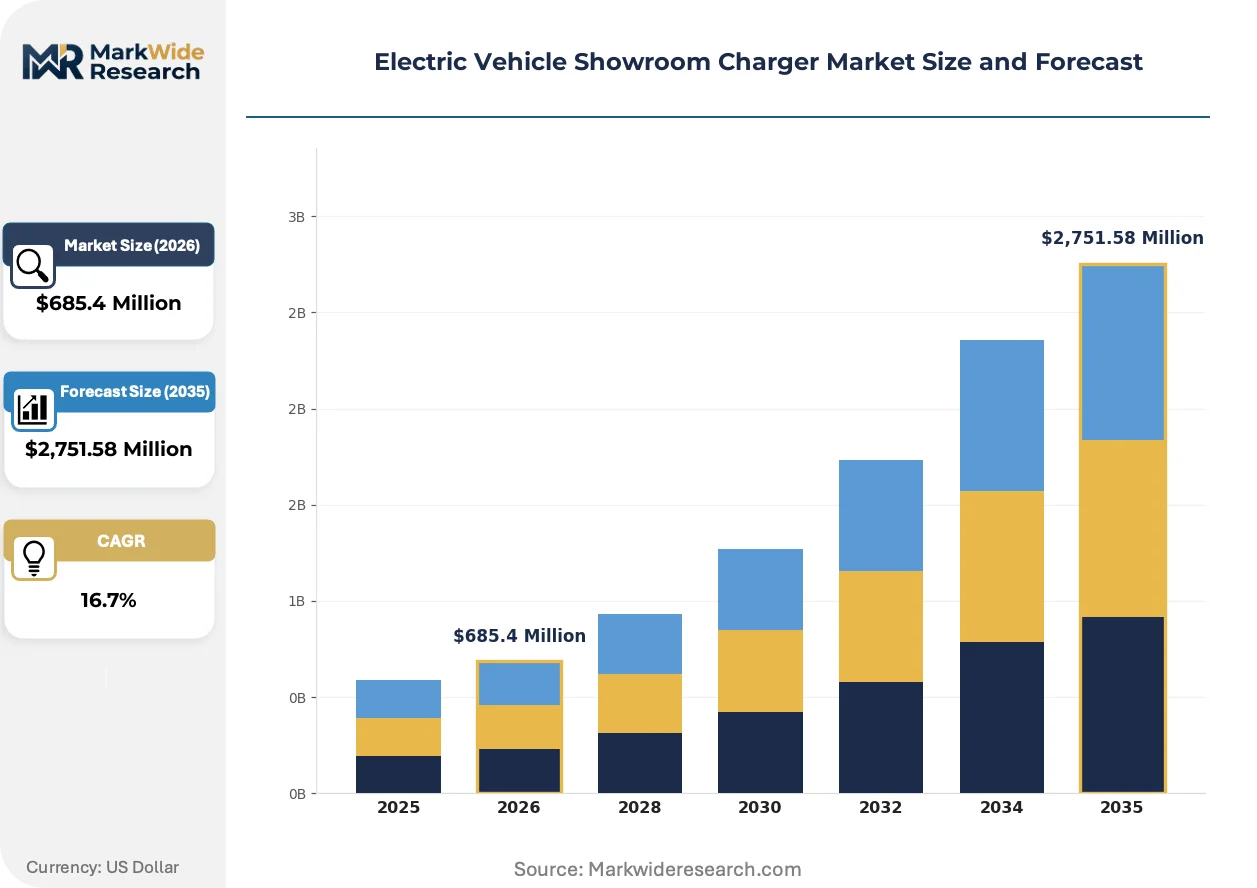
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,751.58 Million |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Charger Type: Level 1 Charger, Level 2 Charger, DC Fast Charger, Wireless Charger Installation Type: Indoor Installation, Outdoor Installation, Wall-mounted, Free-standing Connector Type: Type 1 Connector, Type 2 Connector, CCS Connector, CHAdeMO Connector End User: Automobile Showrooms, Maintenance Garages, Retail Fuel Outlets, Fleet Operators |
| Companies Covered | ChargePoint, ABB, Robert Bosch GmbH, Siemens, Tesla, Schneider Electric, Eaton, EVgo, Tritium, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Showroom Charger Market Trends and Innovations
Software-defined charging architectures are collapsing traditional hardware-software bundling, enabling subscription-based network management that separates capital equipment from ongoing service relationships.
Modular power conversion electronics are collapsing the cost differential between AC and DC showroom installations. Tier-one suppliers now offer 50 kW DC units with footprint and electrical requirements comparable to legacy 22 kW AC systems. European automotive retail networks are adopting these compact DC systems to demonstrate rapid charging without dedicated electrical rooms, compressing infrastructure investment thresholds for mid-market dealerships.
The EU F-Gas Regulation is forcing thermal management redesigns for indoor high-power charging units. Manufacturers must transition from conventional vapor-compression cooling to CO2-based or liquid-cooled architectures to maintain CE marking eligibility. This regulatory pressure most acutely affects imported DC fast charging systems, compressing margins for non-compliant suppliers while creating certification moats for European-integrated producers.
Automotive retailers are unbundling charging hardware procurement from network management services, treating the former as commodity infrastructure and the latter as strategic capability. Multi-location dealer groups now issue separate RFPs for installation contractors and software platforms, fragmenting vendor relationships that previously consolidated under single-source agreements. This pattern is most visible in US metropolitan markets where dealer consolidation has created large portfolio owners with centralized procurement functions.
Electric Vehicle Showroom Charger Market Segmentation
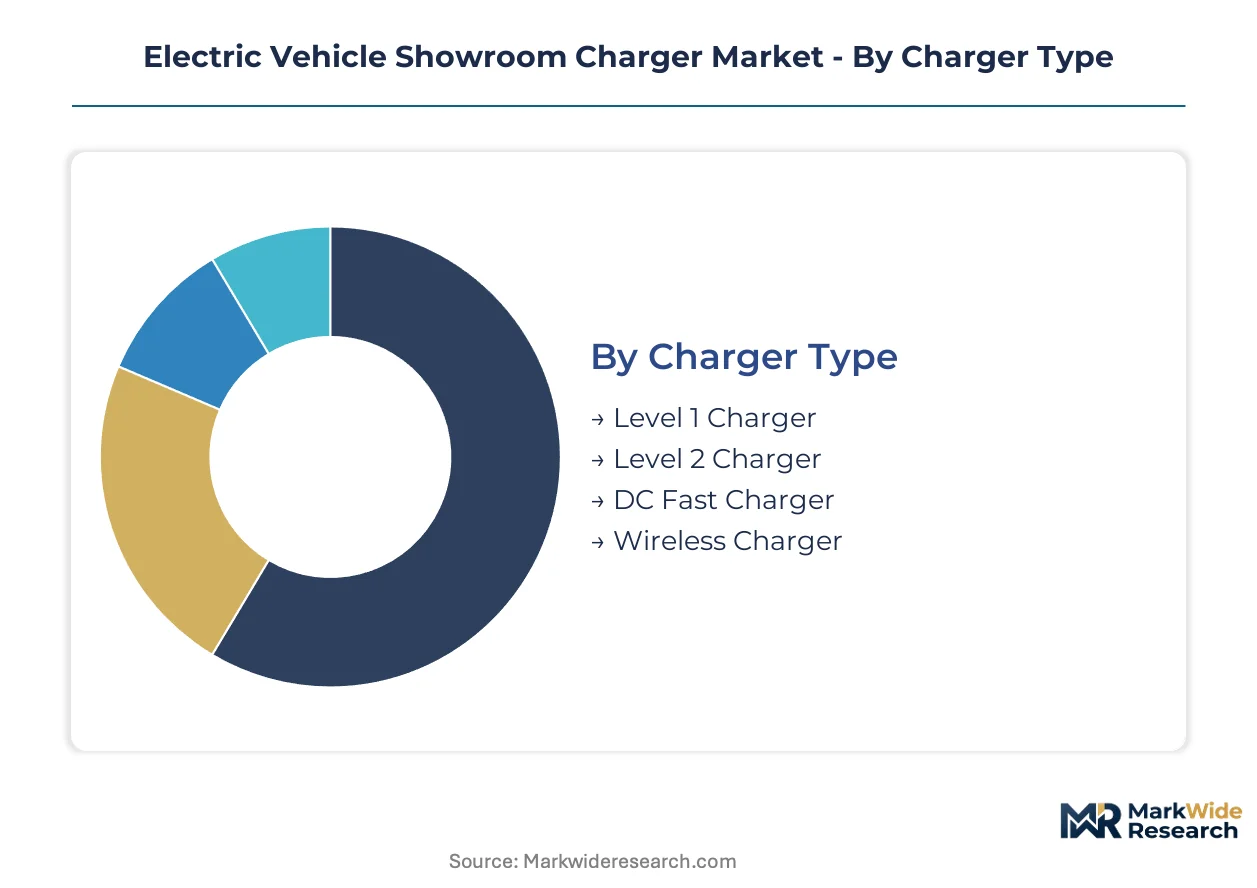
Charger specifications and installation configurations segment the Electric Vehicle Showroom Charger Market along technical, spatial, and customer dimensions. These divisions determine procurement patterns, electrical infrastructure requirements, and margin structures across automotive retail environments.
Charger Type:
Replacement cycles vary dramatically across charger categories, with DC fast chargers turning over every 5-7 years due to thermal stress and power electronics degradation, while Level 1 units persist for 10-15 years in low-utilization demonstration roles.
- Level 1 Charger:Delivers 120V AC power at 1.4-1.9 kW through standard household outlets, requiring no dedicated electrical infrastructure. Demand concentrates in small independent dealerships and rural showrooms where customer visits are brief and installation budgets are constrained by thin vehicle margins.
- Level 2 Charger:Supplies 240V AC power at 7-22 kW through dedicated circuits, balancing charging speed with infrastructure cost. Deployment dominates US and European showroom specifications where typical customer dwell times of 45-90 minutes align with meaningful range replenishment demonstrations.
- DC Fast Charger:Converts AC grid power to DC at 50-350 kW for direct battery injection, enabling 10-80% charging in 20-40 minutes. Premium brand flagships in Germany, California, and Shanghai deploy these units to compress perceived charging anxiety during single-visit purchase decisions.
- Wireless Charger:Transfers power through inductive coupling between parking pad and vehicle receiver, eliminating cable handling. Pilot installations at Mercedes-Benz and BMW experience centers demonstrate autonomous valet charging integration, though cost premiums limit volume deployment.
Level 2 Charger anchors the volume base while DC Fast Charger gains share at the steepest rate.
Installation Type:
Cost tiers separate indoor climate-controlled deployments from outdoor weather-hardened specifications, with wall-mounted configurations commanding 30-40% lower total project costs than free-standing units requiring concrete foundations and trenching.
- Indoor Installation:Positions charging hardware within showroom floors or service bays, protecting electronics from temperature extremes and enabling customer proximity during demonstrations. European automotive retail networks favor this approach due to CE marking requirements for indoor electrical equipment and F-Gas cooling constraints.
- Outdoor Installation:Deploys weather-sealed enclosures in parking lots or forecourts, expanding capacity without building expansion. US suburban dealerships with large surface lots utilize outdoor configurations to avoid HVAC load on showroom electrical panels, though NEC Article 625 mandates GFCI protection and disconnect requirements that inflate installation costs.
- Wall-mounted:Attaches charging hardware directly to building structures, minimizing footprint and eliminating foundation work. This configuration dominates retrofits of existing dealerships where floor space allocation prioritizes vehicle display over charging infrastructure.
- Free-standing:Installs on dedicated pedestals or canopies, enabling flexible positioning and future relocation. Premium brand flagship stores in China deploy free-standing DC units as architectural elements, integrating lighting and digital displays into charging station design.
Wall-mounted configurations anchor the volume base while free-standing installations expand most quickly in greenfield showroom construction.
Connector Type:
Application requirements and regional regulatory alignment determine connector selection, with fleet interoperability mandates and OEM standardization commitments driving consolidation away from legacy formats.
- Type 1 Connector:Implements J1772 standard for single-phase AC charging up to 19.2 kW, prevalent in North American and Japanese markets. Legacy installations persist at Toyota and Honda showrooms, though new deployments are declining as CCS adoption accelerates.
- Type 2 Connector:Supports three-phase AC charging up to 43 kW under IEC 62196-2, standard across European Union member states. BMW, Mercedes-Benz, and Volkswagen showrooms standardize on this connector for AC demonstrations, with Mennekes hardware dominating procurement specifications.
- CCS Connector:Combines AC Type 1 or Type 2 pins with DC fast charging contacts under IEC 62196-3 and SAE J1772 Combo standards. Ford, General Motors, and Hyundai-Kia showrooms in the US mandate CCS for DC fast charging demonstrations, aligning with IRA Section 30C eligibility requirements for open-standard infrastructure.
- CHAdeMO Connector:Provides DC fast charging through separate connector architecture developed by Japanese OEM consortium. Nissan and Mitsubishi showrooms maintain CHAdeMO compatibility for Leaf and Outlander PHEV demonstrations, though new installations are concentrating in Japan and select Southeast Asian markets.
CCS Connector anchors the volume base while Type 2 Connector climbs the fastest in European showroom electrification programs.
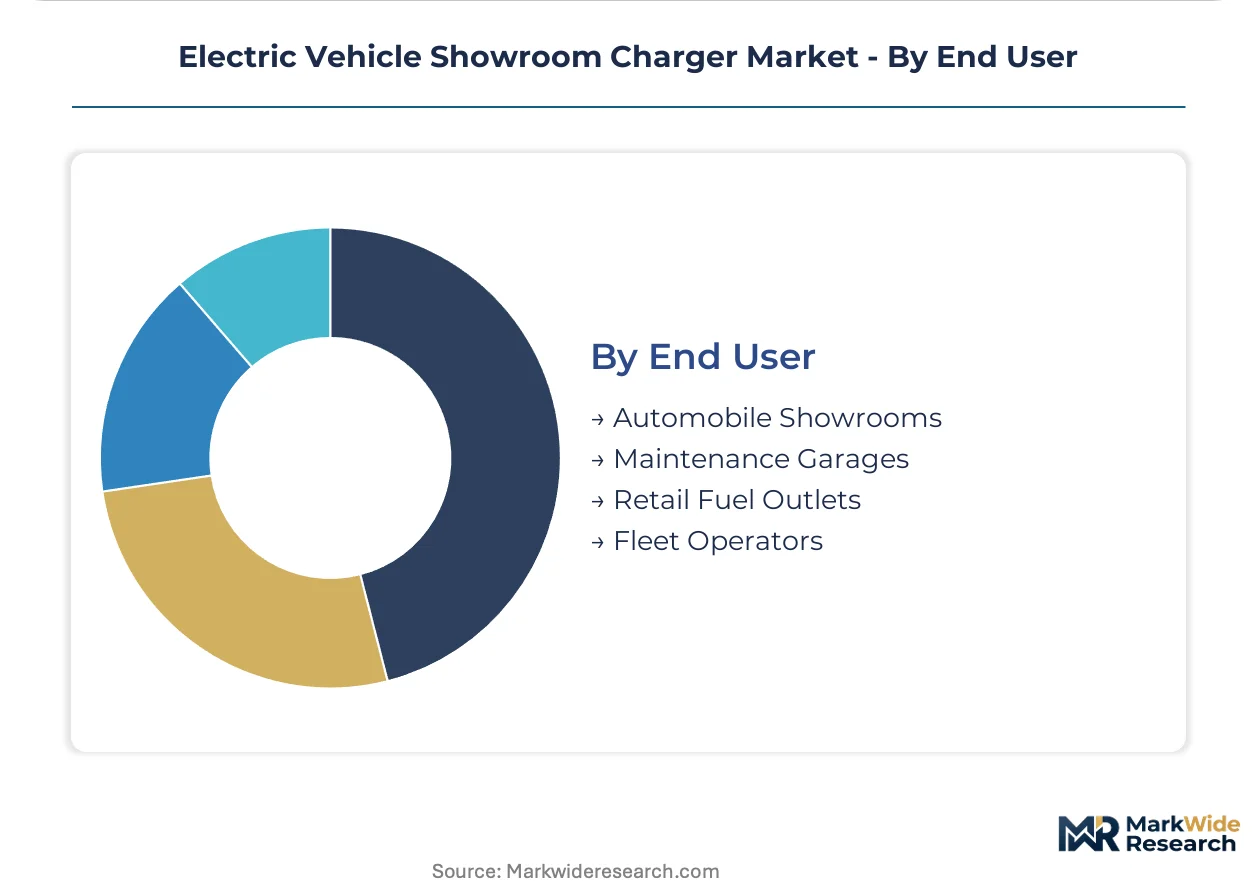
End User:
Customer type determines utilization intensity and procurement authority, with automobile showrooms optimizing for demonstration throughput while fleet operators prioritize total cost of ownership and vehicle uptime metrics.
- Automobile Showrooms:Deploy charging infrastructure to simulate ownership experience and convert foot traffic into vehicle purchases. US dealer groups issue centralized RFPs for multi-location charging programs, unbundling hardware procurement from network management services.
- Maintenance Garages:Utilize showroom-grade chargers for service bay diagnostics and customer vehicle handovers. Independent repair facilities in California and New York adopt Level 2 units to support EV service specialization, driven by state-level zero-emission vehicle mandates.
- Retail Fuel Outlets:Integrate charging alongside conventional fuel dispensers to capture transitioning drivers. Shell Recharge and BP Pulse installations at UK forecourts deploy showroom-equivalent DC fast chargers to maintain brand presence during the energy transition.
- Fleet Operators:Install charging at commercial vehicle display centers to demonstrate total cost of ownership to corporate procurement teams. Amazon and UPS last-mile delivery showcases in Germany and the Netherlands utilize high-power DC configurations to validate electric van operational viability.
Automobile Showrooms anchor the volume base while Fleet Operators expand charging infrastructure at the steepest rate as commercial electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive retailers with large vehicle portfolios concentrate showroom charger procurement authority, driving infrastructure deployment patterns across major automotive markets. Dealer group consolidation in metropolitan corridors accelerates multi-location charging programs. Regulatory incentive windows compress deployment timelines in jurisdictions with phase-down schedules.
United States
Multi-location dealer groups issue centralized RFPs for charging infrastructure across hundreds of rooftops. The IRA's Section 30C tax credits cover 30% of hardware and installation costs for qualified commercial EV charging property. Southern California's automotive retail corridor sees rapid DC fast charger deployment at premium brand flagships seeking to differentiate through ultra-rapid replenishment demonstrations.
Germany
Premium OEM experience centers in Stuttgart, Munich, and Wolfsburg require captive charging infrastructure for extended customer visits. The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants in high-power DC unit thermal management, forcing redesign cycles for CE marking eligibility. Bavaria's automotive cluster leads European adoption of compact 50 kW DC systems with footprint requirements comparable to legacy AC installations.
China
Domestic OEMs operate thousands of branded retail facilities requiring integrated charging demonstrations. MIIT's GB standards govern electromagnetic compatibility and safety certification for charging equipment. Shanghai's Pudong and Beijing's Chaoyang districts concentrate flagship experience centers with architectural free-standing DC units incorporating lighting and digital display integration.
United Kingdom
Retail fuel outlets integrate showroom-equivalent DC fast chargers alongside conventional dispensers to capture transitioning drivers. The UK's Building Regulations Part P mandate electrical installation standards through local authority building control. London's M25 corridor and Birmingham's automotive retail zone deploy wall-mounted Level 2 units in retrofitted dealerships where floor space prioritizes vehicle display.
Japan
Nissan and Mitsubishi maintain CHAdeMO-compatible demonstrations for legacy Leaf and Outlander PHEV models at domestic showrooms. METI's technical standards for EV charging infrastructure shape product certification requirements for indoor retail environments. Tokyo's Kanto region and Osaka's Kansai corridor concentrate OEM-branded experience centers with standardized AC charging demonstrations.
Electric Vehicle Showroom Charger Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement relationships. The vendor base separates into electrification conglomerates with manufacturing scale, software-integrated network operators, and regional installation contractors. Three archetypes dominate: integrated industrial suppliers with modular AC/DC portfolios, subscription-based charging network managers, and asset-light hardware-as-a-service providers. Competitive moves concentrate on unbundling hardware procurement from network management services and pre-positioning for interoperability mandates.
Among the integrated industrial tier, ABB, Siemens, and Schneider Electric occupy positions anchored by electrification portfolios spanning residential to utility-scale applications. ChargePoint exemplifies the software-integrated archetype through subscription models bundling hardware, installation, and network management. These named entities represent competitive positioning patterns rather than definitive market share claims.
| Leading Market Players |
|---|
| ChargePoint |
| ABB |
| Robert Bosch GmbH |
| Siemens |
| Tesla |
| Schneider Electric |
| Eaton |
| EVgo |
| Tritium |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese power electronics manufacturing is compressing margins for DC fast charger suppliers while simultaneously enabling aggressive pricing postures for asset-light leasing models. This utilization dynamic forces integrated industrial suppliers to unbundle hardware from software services, redirecting margin capture toward recurring network management contracts.
Pricing Analysis
Certification level creates the primary spread between indoor CE-marked units and outdoor NEC-compliant configurations, with EU F-Gas thermal management requirements adding cost premiums. Three-tier pricing structure across premium, standard, and economy levels reflects power output, cooling architecture, and software integration depth. Cost compression in mid-range DC systems is intensifying because modular power conversion electronics collapse AC-DC cost differentials. Fleet operators exhibit highest price sensitivity due to total cost of ownership scrutiny, while premium brand flagships prioritize demonstration impact over unit economics.
Supply Chain Analysis
Copper cathode feedstock draws from Chilean mining concentration and Indonesian smelter expansion, while semiconductor power modules hinge on Taiwanese foundry capacity and South Korean packaging expertise. Silicon carbide wafers and high-frequency magnetics represent critical input dependencies. Single-source vulnerability in Taiwan semiconductor fabrication exposes lead times to geopolitical disruption. Distribution runs through electrification conglomerates with direct OEM relationships, regional installation contractors, and emerging hardware-as-a-service aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks the automotive capital expenditure cycle, with IRA incentive phase-downs compressing deployment windows and forcing accelerated procurement decisions across dealer networks.
For Market Incumbents: Pre-empt interoperability mandates by accelerating open-standard hardware certification ahead of NEC harmonization across US jurisdictions. Anchor large-format showroom projects through power-purchase agreements that lock out regional installer competition. Defend against asset-light leasing fragmentation by embedding network management software into long-term service contracts. For New Entrants and Emerging Players: Southeast Asian automotive retail networks present underpenetrated white space where domestic OEMs lack captive charging infrastructure. Target independent dealer groups in secondary US metropolitan markets bypassed by centralized ChargePoint and ABB contracts. Pursue wireless induction pilot installations at premium brand experience centers as differentiation wedge. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-integrated charging network managers with multi-location dealer group subscriptions. Long-term viability favors suppliers with CE marking pre-certification for EU F-Gas thermal management compliance. Monitor IRA Section 30C reauthorization debates as signal for deployment trajectory inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Interoperability Pre-Certification | CE marking and NEC harmonization readiness creates regulatory moats against non-compliant imports. |
| Asset-Light Leasing Expansion | Power-purchase agreements fragment incumbent supplier relationships across regional dealer groups. |
| Wireless Induction Piloting | Parking pad demonstrations at Mercedes-Benz and BMW experience centers merge automated charging with autonomous positioning. |
| Software-Defined Architecture Migration | Subscription-based network management separates capital equipment from ongoing service relationships. |
| Compact DC System Deployment | 50 kW units with AC-comparable footprints compress infrastructure thresholds for mid-market dealerships. |
Research Methodology
A standing panel of charging network operations directors, automotive retail procurement managers, electrical contractor project leads, and utility interconnection specialists provided ongoing calibration against deployment realities. Primary fieldwork combined structured interviews with secondary validation through NEC Article 625 amendment tracking, IRA Section 30C guidance documents, EU F-Gas Regulation implementation notices, and MIIT GB standard certification databases. Bottom-up unit deployment estimates triangulated against top-down automotive retail construction permits.
Scenario-bracketing around IRA incentive phase-down schedules and EU F-Gas redesign cycles bounded high-low deployment trajectories across the projection horizon. Segmentation modeling incorporated charger type, installation configuration, connector standard, and end-user archetype dimensions. CAGRs derived from logistic adoption curves fitted to historical automotive retail infrastructure investment patterns, with cross-referencing against OEM experience center rollout announcements and dealer group capital expenditure disclosures.
Macroeconomic conditions sit as an overlay; deviation in copper price volatility, semiconductor foundry utilization, or commercial real estate construction costs would shift the trajectory. Forecasts embed assumptions regarding regulatory continuity and supply chain resiliency that warrant sensitivity testing. Cross-checking against utility interconnection queue data and automotive retail square footage expansion metrics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle Charging Adapter Market
Electric Vehicle Charging
Solar Charging Station Market
Electric Vehicle Charging
Integrated EV Chargers Market
Electric Vehicle Charging
Battery Liquid Cooling Plates for Electric Vehicle Market
Electric Vehicle Charging
Public EV Charger Market
Electric Vehicle Charging
China Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Asia Pacific Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
EV Charge Controller Market
Electric Vehicle Charging
High Power Charger for Electric Vehicle Market
Electric Vehicle Charging
Home EV Chargers Market
Electric Vehicle Charging
Electric Vehicle (EV) Public Charging Station Market
Electric Vehicle Charging
Electric Vehicle Rapid Charger Market
Electric Vehicle Charging
Electric Vehicle Charging Facilities Market
Electric Vehicle Charging
EV DC Chargers Market
Electric Vehicle Charging
Europe Electric Vehicle Charging Cable Market
Electric Vehicle Charging
Battery Swap Station Market