
 India Battery Swapping for Electric Two-Wheelers Market | 2026-2036
India Battery Swapping for Electric Two-Wheelers Market Size, Share, and Industry Trends Forecast 2026-2036
India Battery Swapping for Electric Two-Wheelers Market Foresight
Station-to-rider networks are rewriting last-mile energy access for electric two-wheelers across India. SUN Mobility anchors its position through proprietary swap station hardware deployed in high-frequency corridors. Ola Electric Mobility Ltd. leverages its scooter installed base to drive captive swapping demand. Battery Smart competes on asset-light franchise models that lower capital barriers for station operators.
Battery swapping for electric two-wheelers replaces onboard charging with depleted-battery exchange at automated stations, typically completing the swap in under three minutes using standardized lithium-ion packs with CAN-based communication protocols. The primary purpose eliminates range anxiety and downtime for commercial riders who cannot tolerate multi-hour plug-in cycles. Battery subscription models dominate revenue pools because they convert capital expenditure into recurring operating costs that fleet managers prefer. Fast charging technology leads infrastructure deployment, though inductive charging remains experimental for premium commuter segments. Delivery services represent the fastest-growing end user category as e-commerce logistics firms electrify last-mile operations.
BIS interoperability standards and the Ministry of Power's battery swapping policy shape product design by mandating common form factors and communication protocols across OEMs. State-level EV policies in Maharashtra and Karnataka complement central regulation with capital subsidies and preferential electricity tariffs for swap station operators. Stakeholders must monitor how PLI scheme allocations for battery manufacturing alter cell cost curves and station profitability thresholds.
Market Dynamics
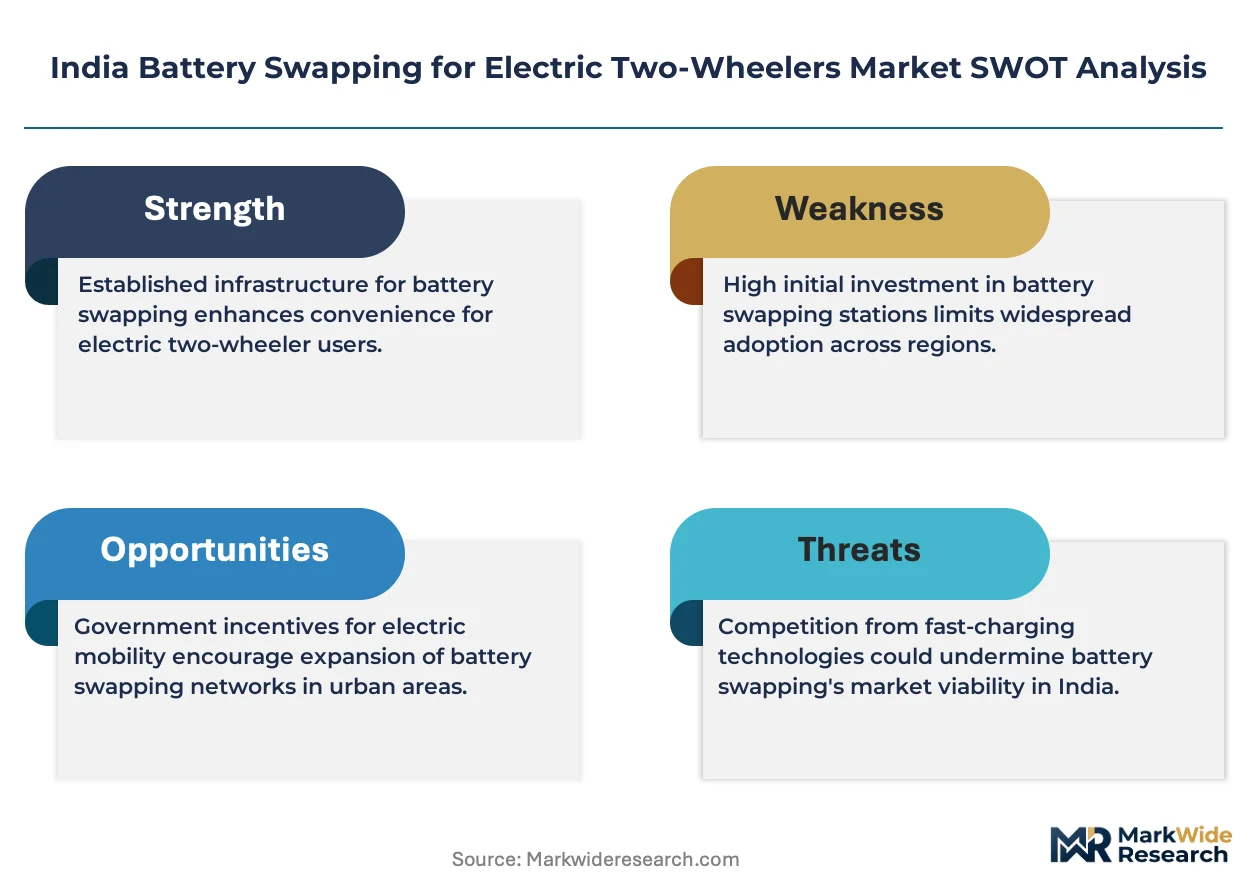
Battery swapping infrastructure economics in India hinge on achieving minimum viable station utilization above 80 swaps daily, a threshold that concentrates deployment along hyperlocal delivery corridors where fleet density justifies capital outlay.
Growth Catalysts
- PLI scheme allocations:Domestic cell manufacturing incentives under India's Production Linked Incentive scheme compress import dependency and reduce pack costs for swap station operators.
- Delivery fleet electrification mandates:E-commerce logistics firms including Zomato and Swiggy face Scope 3 emission targets that accelerate two-wheeler fleet turnover toward swappable-battery models.
- Karnataka EV policy:The state's capital subsidy framework for battery swapping infrastructure reduces payback periods for station operators in Bangalore's dense urban corridors.
Market Restraints
- Lithium cell import concentration:Over 90% of lithium-ion cells enter from China, exposing swap station operators to currency volatility and supply chain disruptions.
- BIS interoperability delays:Pending finalization of common battery form factor standards creates stranded asset risk for early station deployments.
- Onboard fast charging improvement:Advances in 15-minute DC fast charging for premium two-wheelers threaten the time-advantage value proposition of swapping for commuter segments.
Strategic Opportunities
- Tamil Nadu industrial corridors:Chennai's automotive supplier ecosystem offers underexploited locations for swap stations serving manufacturing facility commutes and intra-city logistics.
- Battery-as-a-service convergence:Integration with telematics platforms enables usage-based insurance products that deepen rider lock-in and expand revenue pools per subscriber.
- Maharashtra state EV policy extension:Proposed inclusion of battery swapping in commercial vehicle retrofit incentives would unlock second-life scooter conversions for gig workers.
Industry Challenges
- CAN protocol engineering talent scarcity:Shortage of embedded systems engineers familiar with battery management system communication standards delays station software deployment timelines.
- Multi-OEM pack certification complexity:Each original equipment manufacturer requires separate thermal runaway testing and BIS certification, fragmenting station inventory requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Battery Swapping for Electric Two-Wheelers Market |
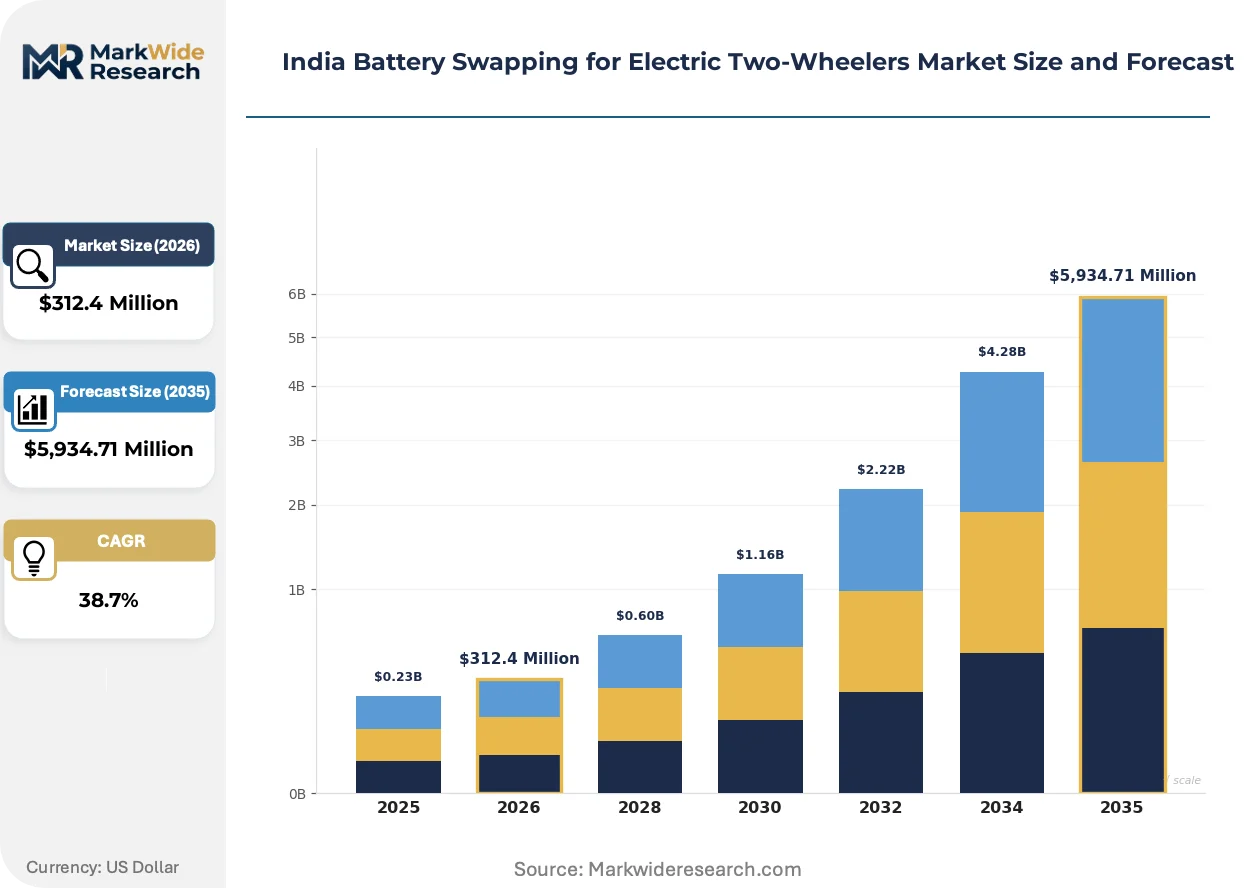
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $5,934.71 Million |
| CAGR (2026 – 2036) | 38.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Battery Exchange, Battery Subscription, Battery Leasing, Battery Maintenance Charging Technology: Fast Charging, Standard Charging, Inductive Charging, Solar Charging End User: Delivery Services, Commuters, Fleet Operators, Ride-Sharing Platforms Battery Capacity: Low Capacity, Medium Capacity, High Capacity, Ultra High Capacity |
| Companies Covered | Ola Electric Mobility Ltd., SUN Mobility, RACE Energy Limited, Upgrid Solutions Private Limited (Battery Smart), Bounce Infinity, Lithion Power Private Limited, Gogoro, Hero MotoCorp Ltd., Exide Industries Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Battery Swapping for Electric Two-Wheelers Market Shifts & Advancements
Station hardware automation and rider-facing software platforms are converging to compress swap transaction times below 90 seconds, redefining competitive differentiation beyond geographic coverage alone.
Automated guided vehicle systems for battery retrieval and storage are collapsing labor costs at high-throughput swap stations. Fleet operators with over 500 vehicles per depot are piloting these robotics in Bangalore and Hyderabad. The technology is collapsing the breakeven utilization threshold from 80 to 55 daily swaps per station.
BIS interoperability standards for battery form factors and communication protocols are mandating cross-OEM compatibility. The Ministry of Power's policy framework requires standardized CAN-based battery management systems by 2026. Commercial fleet managers are delaying procurement commitments until certified packs from multiple OEMs become available.
Subscription-based battery access is displacing upfront pack purchases for gig economy riders. Delivery platforms are negotiating enterprise rates with swap providers and deducting subscription fees from rider earnings. This model is most visible in Delhi NCR and Mumbai where platform-mediated employment concentrates two-wheeler utilization.
India Battery Swapping for Electric Two-Wheelers Market Segmentation
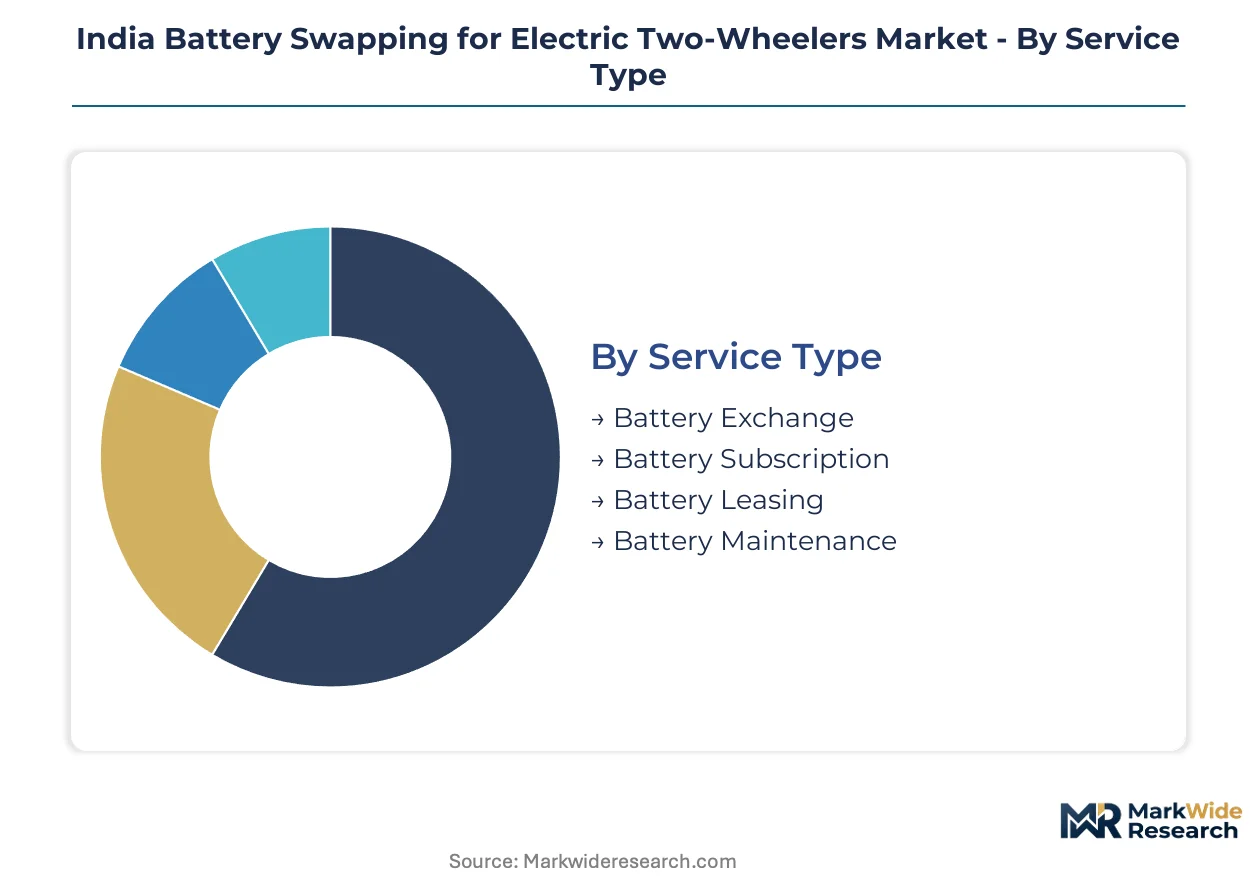
Segmentation in India's battery swapping market reveals how service economics, infrastructure technology, and rider profiles interact to determine station viability. Each dimension shapes capital deployment decisions and revenue model design differently across Maharashtra, Karnataka, and Tamil Nadu corridors.
Service Type:
After-sales service intensity varies dramatically across these models, with subscription and maintenance services demanding continuous rider relationship management rather than transactional exchange operations.
- Battery Exchange:The core transactional service where depleted packs are swapped for charged units at automated stations. Demand concentrates along Bangalore and Mumbai hyperlocal delivery corridors where gig workers complete 80-120 km daily and cannot tolerate charging downtime. Station utilization thresholds of 80 swaps daily determine profitability in these dense urban clusters.
- Battery Subscription:Converts capital expenditure into recurring operating costs through monthly access fees. Fleet operators at Swiggy and Zomato prefer this model for cash flow predictability. The Karnataka EV policy capital subsidy reduces operator payback periods, accelerating subscription penetration among commercial riders.
- Battery Leasing:Long-term asset financing structures where ownership remains with the swap provider. Chennai manufacturing facility commutes show emerging demand from captive fleet conversions.
- Battery Maintenance:Diagnostic and thermal management services ensuring pack health across swap cycles. BIS certification requirements for multi-OEM compatibility elevate maintenance complexity.
Battery exchange holds the largest share; momentum sits with battery subscription.
Charging Technology:
Cost tier differentiation separates premium automated infrastructure from basic manual stations, with technology choice directly determining labor requirements and throughput capacity.
- Fast Charging:DC infrastructure replenishes packs within 45-60 minutes at swap stations. Deployment concentrates in Delhi NCR and Hyderabad where fleet density justifies high-capacity grid connections. PLI scheme allocations for domestic cell manufacturing improve pack cost economics for fast-charging operators.
- Standard Charging:AC overnight charging at depot locations supplements station-based fast charging. Tamil Nadu industrial corridors leverage this for manufacturing facility shuttle services.
- Inductive Charging:Wireless power transfer remains experimental for premium commuter segments. Mumbai's luxury residential complexes pilot this for hassle-free overnight topping.
- Solar Charging:PV-integrated stations reduce grid dependency and electricity tariffs. Maharashtra's preferential renewable energy policies support solar-hybrid deployments in Pune and Nagpur.
Fast charging dominates infrastructure deployment; solar charging gains share fastest among new station approvals.
End User:
Application-specific utilization patterns create divergent station design requirements, from high-frequency commercial corridors to dispersed residential catchments.
- Delivery Services:E-commerce logistics firms including Zomato and Swiggy electrify last-mile fleets under Scope 3 emission mandates. These riders average 12-15 swaps monthly, generating the highest per-user revenue. Bangalore and Mumbai station networks prioritize delivery corridor density.
- Fleet Operators:Corporate and government vehicle pools with centralized depot management. Tamil Nadu's automotive supplier ecosystem offers underexploited locations for fleet-dedicated stations.
- Commuters:Individual riders with lower frequency, higher price sensitivity. Onboard fast charging improvements threaten swapping's time advantage for this segment.
- Ride-Sharing Platforms:Two-wheeler taxi services with intermittent high-utilization patterns. Platform-mediated employment models in Delhi NCR are negotiating enterprise swap rates.
Delivery services command the largest revenue pool; fleet operators show the steepest expansion trajectory as electrification mandates tighten.
Battery Capacity:
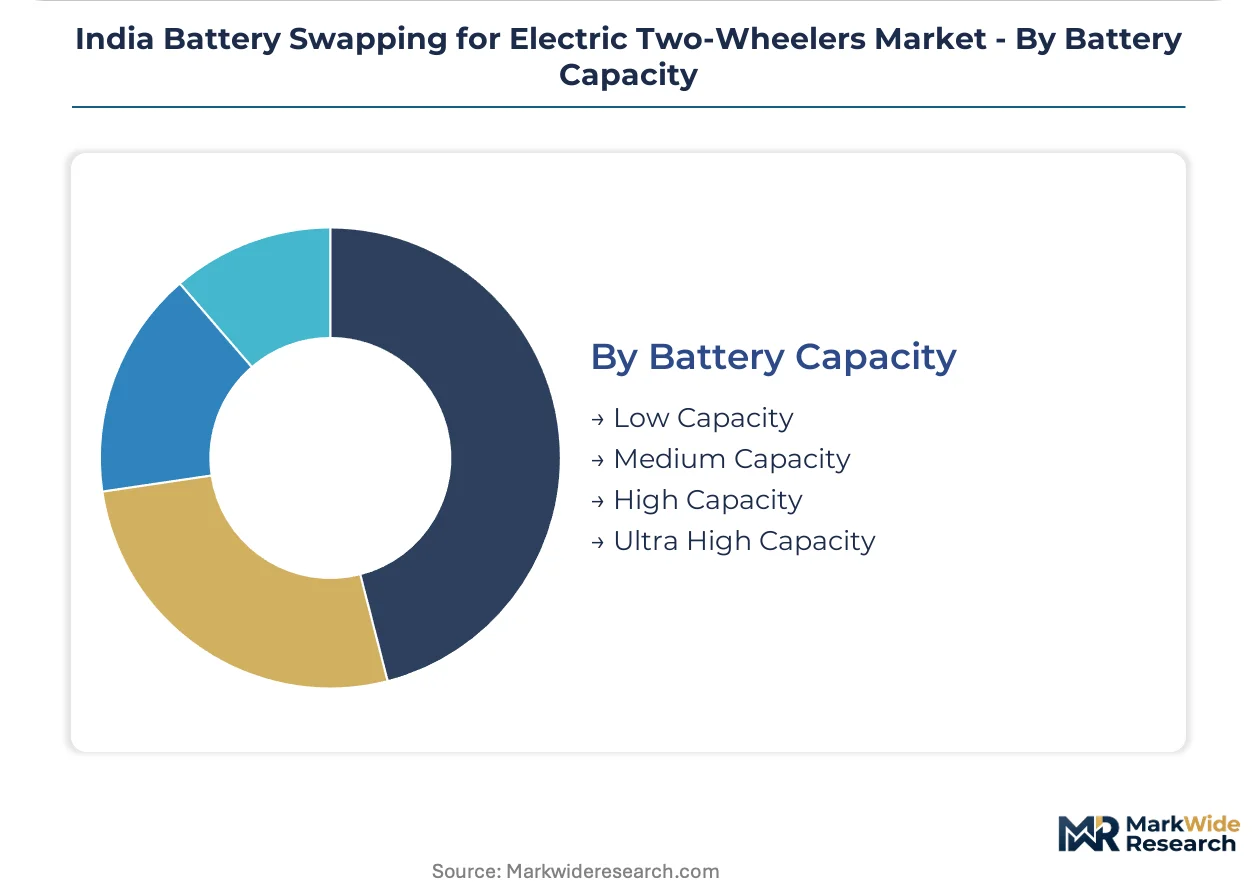
Volume concentration in medium-capacity packs reflects the sweet spot for Indian two-wheeler range requirements and station inventory efficiency.
- Medium Capacity:2-3 kWh packs balance range and weight for typical 80-100 km daily usage. These dominate swap station inventories across all major operator networks. BIS interoperability standards for this form factor are stabilizing procurement commitments from fleet managers.
- High Capacity:3-4 kWh units serve inter-city courier and premium commuter segments. Demand clusters along Mumbai-Pune and Bangalore-Chennai corridors.
- Low Capacity:Sub-2 kWh packs for lightweight scooters and short-distance urban hopping. Hyderabad's dense old-city lanes favor these compact units.
- Ultra High Capacity:4+ kWh packs for three-wheeler conversions and premium electric motorcycles. Limited deployment pending BIS certification completion.
Medium capacity leads station inventories; high capacity is climbing the fastest as range expectations rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ministry of Power anchors India's battery swapping policy framework through BIS interoperability mandates and capital subsidy structures that concentrate deployment across state-level EV corridors.
Maharashtra
Mumbai's hyperlocal delivery density and Pune's manufacturing base drive swap station demand along the Mumbai-Pune expressway. The state's EV policy offers preferential electricity tariffs for commercial swapping infrastructure. Nagpur and Nashik industrial corridors host emerging fleet-dedicated stations serving automotive supplier commutes.
Karnataka
Bangalore's gig economy concentration generates 80-120 km daily rider utilization that justifies station economics. The state capital subsidy framework reduces operator payback periods below 18 months. Hosur and Mysuru logistics corridors show fastest subscription model penetration among Swiggy and Zomato fleets.
Tamil Nadu
Chennai's automotive supplier ecosystem creates captive fleet conversion opportunities for manufacturing facility shuttles. State-level EV policy alignment with central BIS standards accelerates multi-OEM pack certification. Coimbatore and Hosur industrial clusters remain underexploited for swap station deployment.
Telangana
Hyderabad's dense old-city lanes favor compact sub-2 kWh pack configurations for lightweight scooter segments. The state's electronics manufacturing incentives attract swap station hardware assembly operations. Cyberabad logistics parks host pilot automated guided vehicle systems for high-throughput depot management.
Delhi-NCR
Platform-mediated employment models in Delhi concentrate two-wheeler utilization rates that sustain subscription economics. The NCR's air quality mandates accelerate delivery fleet electrification timelines. Gurugram and Noida corporate parks generate emerging demand for fleet operator-dedicated swapping infrastructure.
India Battery Swapping for Electric Two-Wheelers Market Competitive Landscape
Integrated OEM-swapping networks and pure-play infrastructure operators split the market along captive-versus-open access lines. Proprietary hardware developers compete against asset-light franchise platforms for station deployment capital. Two strategic archetypes dominate: vertically integrated mobility companies leveraging scooter installed bases, and independent swap providers offering multi-brand battery access. Capacity expansion along delivery corridors and technology licensing for automated station hardware represent the dominant competitive moves.
Within the integrated mobility tier, Ola Electric Mobility Ltd. exemplifies captive demand generation through proprietary scooter volumes. SUN Mobility anchors the independent infrastructure archetype with automated swap station deployment. Battery Smart occupies a position in the asset-light franchise segment that lowers capital barriers for regional station operators.
| Leading Market Players |
|---|
| Ola Electric Mobility Ltd. |
| SUN Mobility |
| RACE Energy Limited |
| Upgrid Solutions Private Limited (Battery Smart) |
| Bounce Infinity |
| Lithion Power Private Limited |
| Gogoro |
| Hero MotoCorp Ltd. |
| Exide Industries Ltd. |
| Others |
Supply & Pricing Matrix
Single-source lithium cell dependency from China compresses margin structures for Indian swap station operators while simultaneously forcing pricing stratification across premium automated infrastructure and basic manual stations. Tariff exposure on imported battery management system components widens the spread between subscription-tier pricing for fleet operators and transactional per-swap rates for individual commuters.
Pricing Analysis
Configured-to-order pricing for automated guided vehicle stations commands a 40% premium over standard manual swap cabinets due to robotics integration and software customization requirements. Three-tier pricing structure across premium, standard, and economy levels separates enterprise fleet subscriptions from gig-worker pay-per-swap models and residential commuter top-up services. Price differentiation rests on station automation grade and BIS certification tier, with uncertified legacy packs eroding margins in unregulated corridors. Delivery platforms exhibit highest price sensitivity due to volume-negotiated enterprise rates, while captive fleet operators at manufacturing facilities tolerate premium pricing for guaranteed uptime.
Supply Chain Analysis
Upstream lithium carbonate and cobalt sulfate feedstock draws from Chilean mining operations, Indonesian nickel processing, and Chinese refining complexes before reaching Indian cell assemblers. Lithium-ion cells, battery management systems, and thermal management components constitute the critical input trinity, with over 90% of cells sourced from China. Single-source vulnerability concentrates in the Ningbo-Shanghai logistics corridor, exposing operators to maritime chokepoint disruptions and currency volatility. Distribution runs through Tier 1 automotive supplier networks and dedicated swap station hardware assemblers in Chennai and Pune before final depot installation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in network effects: station density creates rider lock-in that compounds with each incremental deployment, while regulatory entrenchment through BIS certification requirements raises structural barriers for unapproved pack entrants.
For Market Incumbents: Entrench position through backward integration into domestic cell assembly under PLI scheme allocations, securing cost advantages against import-dependent challengers. Expand automated station capacity along Hosur-Mysuru logistics corridors before interoperability mandates commoditize hardware differentiation. Certification investment in multi-OEM thermal runaway testing protocols will defend against emerging asset-light franchise operators.
For New Entrants and Emerging Players: Tamil Nadu's Coimbatore industrial cluster offers underpenetrated white-space for manufacturing facility shuttle conversions, with lower station density competition than Bangalore or Mumbai. Asset-light franchise models that license automated hardware designs to regional operators bypass capital-intensive buildout requirements. Target second-life scooter retrofit segments in Maharashtra where proposed commercial vehicle incentives would subsidize conversion economics for gig workers.
For Investors and Strategic Acquirers: BIS interoperability standard finalization reshapes the acquisition landscape by validating which station networks can support multi-OEM pack inventories versus stranded proprietary systems. Long-term viability favors vertically integrated operators with captive scooter demand and in-house battery assembly capability. Monitor PLI scheme allocation disbursement velocity as the inflection signal for domestic cost competitiveness against Chinese import alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Station Hardware Deployment | Robotics integration collapses breakeven utilization thresholds from 80 to 55 daily swaps per station. |
| Multi-OEM Pack Certification Investment | BIS interoperability compliance unlocks fleet procurement commitments from delivery platform operators. |
| Subscription Model Platform Integration | Telematics convergence enables usage-based insurance products that deepen rider retention. |
| Solar-Hybrid Station Infrastructure | Maharashtra renewable energy tariffs reduce grid dependency and operating cost exposure. |
| Franchise Network Geographic Expansion | Asset-light licensing lowers capital barriers for regional operators in underpenetrated industrial corridors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and state EV policy documents through structured interviews with swap station operators, fleet procurement managers at delivery platforms, BIS certification engineers, and PLI scheme administrators. Primary intelligence gathering encompassed embedded systems developers for battery management protocols and grid connection specialists at state electricity boards. Secondary validation drew from Ministry of Power policy circulars, BIS standard drafts, and state-level EV policy compendia. Bottom-up station deployment counts triangulate against top-down market sizing from vehicle registration databases and subscription revenue estimates.
Forecast inputs span utilization rate trajectories, cell cost compression curves, and policy subsidy phase-out schedules across the modeling period. Segmentation dimensions encompass service type, charging technology, end-user category, battery capacity tier, and state-level regulatory cluster. CAGRs derive from logistic diffusion curves fitted to station deployment pipelines and fleet electrification mandate timelines. Industry-specific inputs include PLI scheme allocation disbursement velocity and BIS certification completion rates for multi-OEM pack interoperability.
Practitioners should monitor lithium carbonate spot price volatility, BIS standard finalization delays, and onboard fast charging efficiency gains for early signals requiring forecast reassessment. Cross-checking against state electricity board tariff revision schedules and delivery platform Scope 3 emission target announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Solar Carport Charging Station Market
Electric Vehicle Charging
Western Europe Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
Global Automotive Charging System Market
Electric Vehicle Charging
Second Life Electric Vehicle Battery Market
Electric Vehicle Charging
Denmark Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
EV Charging Networks Market
Electric Vehicle Charging
EV Charging System Test and Certification Equipment Market
Electric Vehicle Charging
Electric Vehicle Charging Products Market
Electric Vehicle Charging
Electric Vehicle Charging Systems Testing Market
Electric Vehicle Charging
Electric Vehicle Safe Charging Inlet Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station and Pile Operation and Management Market
Electric Vehicle Charging
France Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
APAC Electric Vehicle Charging Station Market
Electric Vehicle Charging
E-Bike Charging Station Market
Electric Vehicle Charging
High-Thermal-Conductivity Gap-Fill Adhesives for EV Battery Cooling Plates Market
Electric Vehicle Charging
Electric Vehicle Charger and Charging Station Market