
 Australia Electric Vehicle Charging Equipment Market | 2026-2036
Australia Electric Vehicle Charging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Electric Vehicle Charging Equipment Market Insights
The National Electric Vehicle Strategy is recalibrating procurement priorities across Australian fleet operators and property developers. Tritium leverages its Brisbane manufacturing base to dominate DC fast charger supply for highway corridors. JET Charge anchors the commercial installation segment through exclusive partnerships with retail and municipal property portfolios. EVSE Australia competes aggressively in the residential tier through direct-to-consumer channel control and certified installer networks.
Australia electric vehicle charging equipment comprises conductive power transfer systems rated from 2.3 kW single-phase residential units to 350 kW liquid-cooled DC rapid dispensers, engineered to replenish battery electric vehicle packs via Type 2 AC or CCS2 DC connectors under AS/NZS 3000 electrical safety standards. The primary commercial purpose is to bridge range anxiety gaps and enable fleet electrification by delivering controlled, metered energy transfer with integrated payment and load management protocols. DC Fast Chargers capture the dominant share of capital deployment despite lower unit volumes, while Smart Charging technology leads software-attached revenue pools through demand response and time-of-use optimization capabilities. Residential Users sustain the largest addressable base, though Commercial Fleet Operators generate the steepest growth trajectory as logistics and mining enterprises execute diesel displacement programs.
The Australian Energy Market Operator and state-level regulators including the Essential Services Commission of Victoria shape grid connection standards and demand charge frameworks that directly influence charger economics and site selection criteria. AS/NZS 3000 and IEC 61851 compliance requirements create certification barriers that favor established suppliers with in-house testing laboratories and local engineering presence. Stakeholders must monitor the evolution of distribution network service provider tariff reforms and building code mandates for new multi-unit residential developments, as these will determine whether charging infrastructure becomes a landlord obligation or tenant-funded amenity.
Market Dynamics
The National Electric Vehicle Strategy is forcing fleet operators and property developers to recalibrate procurement priorities around zero-emission mandates, while distribution network service providers reform tariffs that determine charger economics at commercial sites.
Growth Catalysts
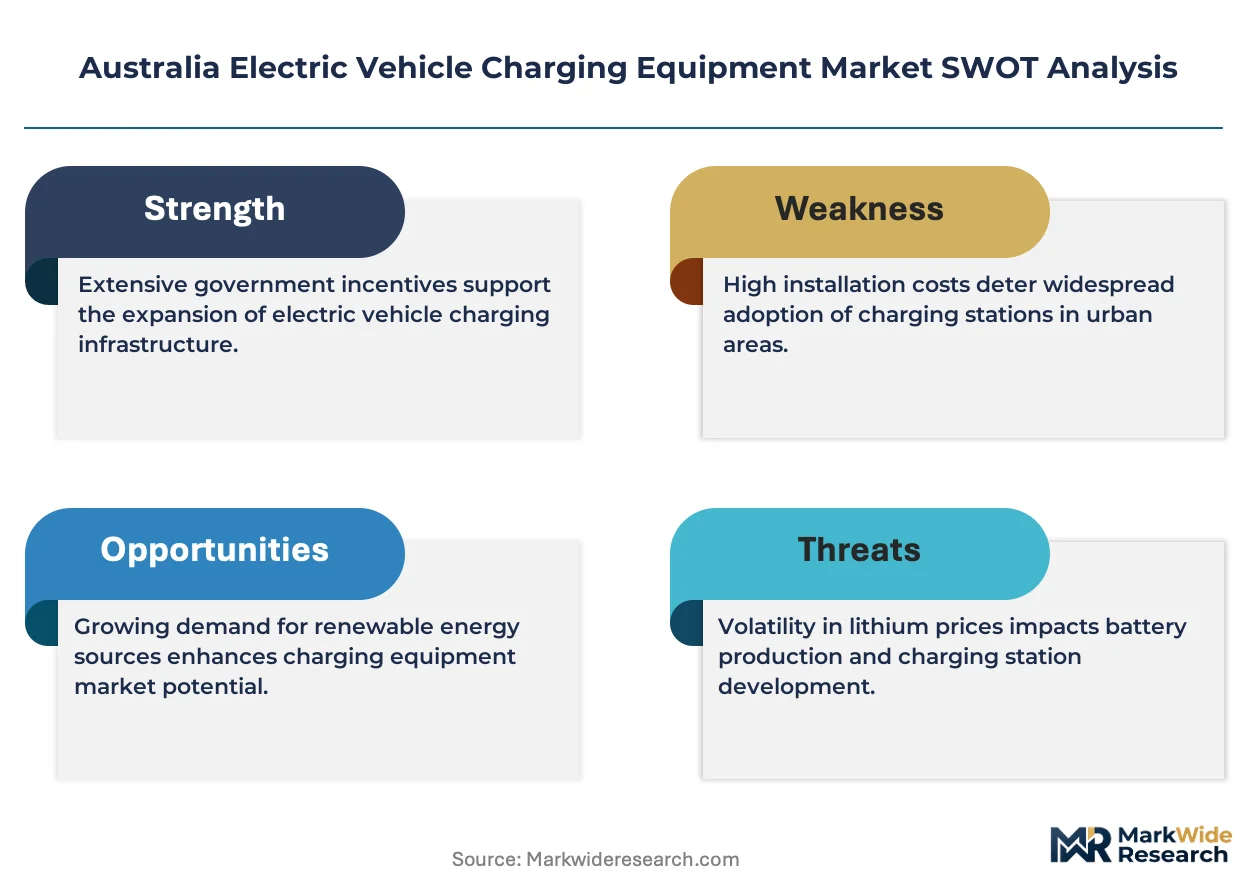
- ARENA Funding Programs:The Australian Renewable Energy Agency's capital deployment accelerates highway corridor and metropolitan destination charging installations across New South Wales and Victoria.
- Mining Fleet Electrification:Diesel displacement programs at resource extraction operations are driving demand for 350 kW liquid-cooled DC rapid dispensers and integrated load management systems.
- State-Level ZEV Mandates:Zero-emission vehicle requirements in multiple jurisdictions are compressing deployment timelines for AC and DC infrastructure at logistics hubs and retail properties.
Market Restraints
- Grid Connection Standards:Essential Services Commission of Victoria and Australian Energy Market Operator frameworks create extended approval timelines for high-capacity DC installations.
- AS/NZS 3000 Certification Barriers:In-house testing laboratory requirements and local engineering presence obligations favor established suppliers and constrain new market entrants.
- Copper and Power Electronics Volatility:Input cost fluctuations for conductive power transfer components compress margins on residential 2.3 kW single-phase units.
Strategic Opportunities
- Multi-Unit Residential Building Codes:Emerging mandates for new apartment developments create landlord obligation scenarios for embedded charging infrastructure in Queensland and Western Australia.
- Smart Charging Convergence:Integration of demand response protocols with time-of-use optimization software opens recurring revenue pools beyond hardware sales.
- Motorway Corridor Gaps:Underpenetrated segments of the Hume and Pacific Highway corridors present white space for DC fast charger networks serving intercity logistics.
Industry Challenges
- Certified Installer Network Scaling:AS/NZS 3000 qualified electrician scarcity constrains residential tier deployment velocity and service quality consistency.
- Distribution Network Tariff Reconfiguration:Demand charge uncertainty complicates site selection economics and long-term power purchase agreements for fleet operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Electric Vehicle Charging Equipment Market |
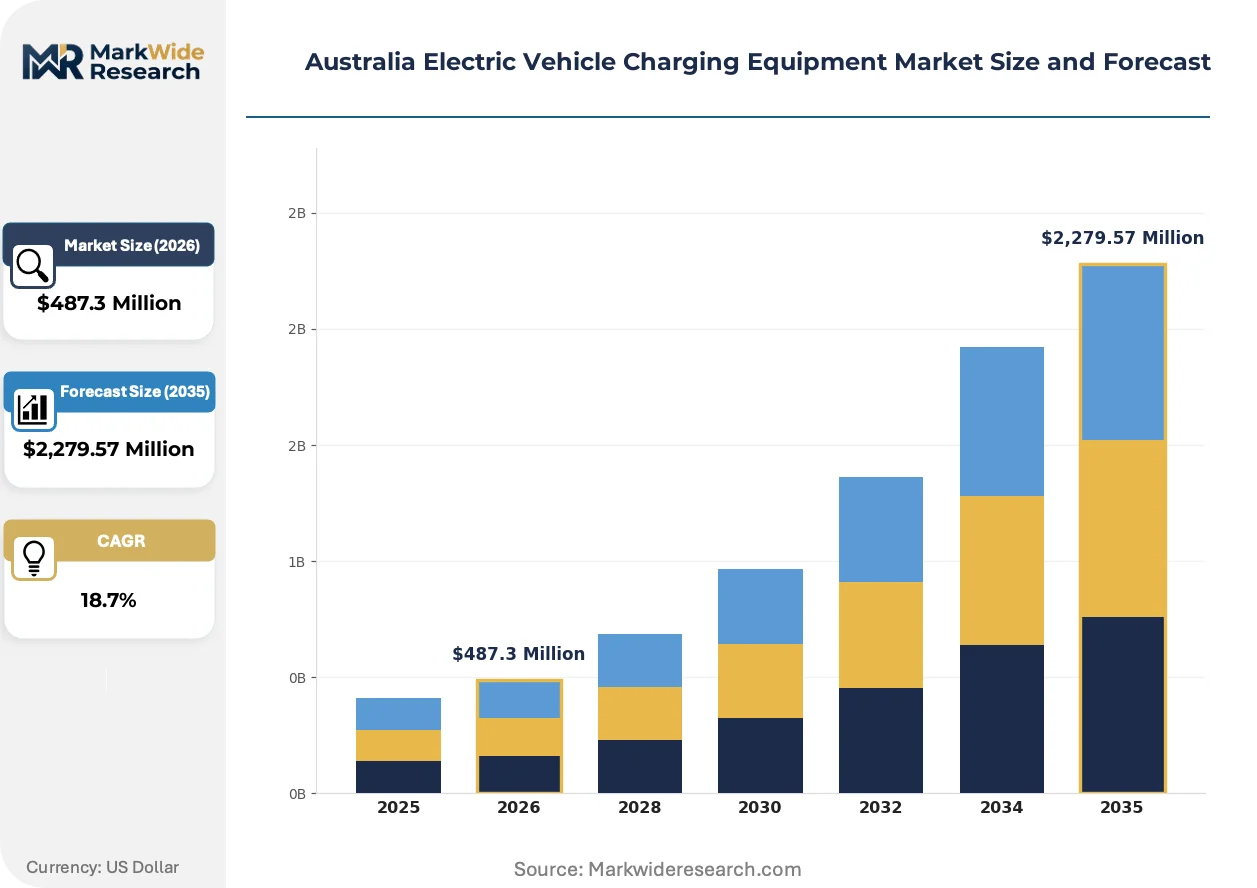
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $2,279.57 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Chargers, DC Fast Chargers, Level 1 Chargers, Level 2 Chargers End User: Residential Users, Commercial Fleet Operators, Government Agencies, Public Charging Stations Installation Type: Onsite, Offsite, Workplace, Home Technology: Wireless Charging, Smart Charging, Grid-Integrated, Standard Charging |
| Companies Covered | Tritium, EVSE Australia, JET Charge, Evnex, ABB Ltd, Siemens AG, Tesla Inc., Delta Electronics Inc., Schneider Electric, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Electric Vehicle Charging Equipment Market Trends and Innovations
Technology convergence and regulatory compression are reshaping how charging infrastructure integrates with grid systems and fleet management platforms across Australian states.
Vehicle-to-grid (V2G) bidirectional charging hardware is unifying energy storage and grid services functions in a single asset class. Fleet operators in mining and logistics are piloting these systems at depot locations to reduce peak demand charges. This convergence is compressing the boundary between transportation and distributed energy resources, enabling charger assets to generate ancillary revenue streams.
The Essential Services Commission of Victoria's demand charge frameworks are recalibrating site selection criteria for commercial installations. Industrial consequence includes accelerated adoption of on-site battery buffering to manage connection capacity constraints. Fast-charge corridor operators are responding by clustering sites near substations with available headroom.
Direct-to-consumer channel control is displacing traditional electrical wholesaler relationships in the residential segment. EVSE Australia's certified installer networks and online configuration tools are capturing end-user preference through simplified procurement journeys. This pattern concentrates in metropolitan New South Wales and Victoria where early adopter density supports digital-first buying behaviors.
Australia Electric Vehicle Charging Equipment Market Segmentation
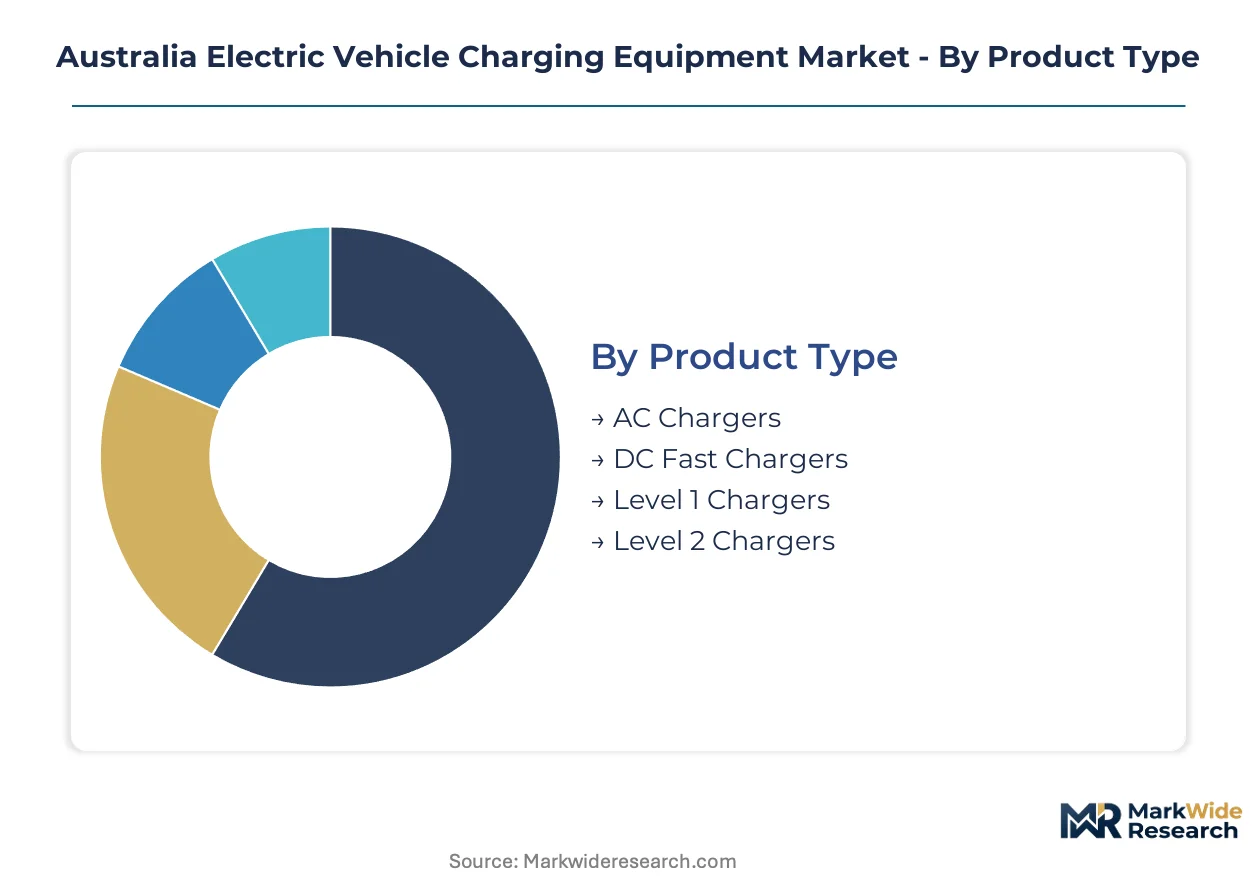
Segmentation reveals how capital deployment concentrates across power transfer technologies and customer archetypes. Understanding these divisions exposes where AS/NZS 3000 certification requirements and Essential Services Commission of Victoria tariff structures differentially shape procurement economics.
Product Type:
Supply concentration tilts toward high-capacity DC systems despite their lower unit volumes, while residential AC units dominate absolute shipment counts.
- AC Chargers:Conductive power transfer systems rated 2.3 kW to 22 kW utilizing Type 2 connectors for single-phase and three-phase residential and workplace installations. Demand clusters in metropolitan New South Wales and Victoria where apartment dwellers and suburban homeowners require overnight replenishment capability; Essential Services Commission of Victoria demand charge frameworks compress site economics for commercial AC deployments.
- DC Fast Chargers:Liquid-cooled dispensers spanning 50 kW to 350 kW with CCS2 connectors engineered for highway corridor and fleet depot applications. Mining and logistics operators across Queensland and Western Australia are driving orders for 350 kW units to support heavy-duty diesel displacement programs; Australian Energy Market Operator grid connection standards extend approval timelines for these high-capacity installations.
- Level 1 Chargers:Portable 2.3 kW single-phase units supplied with vehicle purchases for emergency top-up scenarios.
- Level 2 Chargers:Wall-mounted 7 kW to 22 kW fixed installations serving workplace and destination charging locations.
DC Fast Chargers absorb the bulk of installed capacity; AC Chargers are expanding most quickly.
End User:
Customer type determines whether procurement flows through certified installer networks or direct utility negotiations.
- Residential Users:Individual homeowners and apartment dwellers purchasing 2.3 kW to 22 kW units through direct-to-consumer channels. Metropolitan Sydney and Melbourne concentrate demand where early adopter density supports digital-first buying behaviors; AS/NZS 3000 qualified electrician scarcity constrains deployment velocity.
- Commercial Fleet Operators:Logistics, mining, and delivery enterprises executing diesel displacement programs across depot and highway corridor locations. Queensland resource extraction operations are piloting 350 kW liquid-cooled systems with integrated load management; Australian Renewable Energy Agency funding programs accelerate capital deployment for this cohort.
- Government Agencies:Municipal and state entities procuring public charging infrastructure under zero-emission vehicle mandates.
- Public Charging Stations:Retail property portfolios and motorway service operators deploying destination and corridor charging assets.
Commercial Fleet Operators capture the steepest expansion trajectory; Residential Users maintain the largest addressable base.
Installation Type:
Physical siting governs whether infrastructure becomes landlord obligation or tenant-funded amenity under emerging building code mandates.
- Onsite:Depot and facility-integrated installations at mining operations, logistics hubs, and corporate campuses. Western Australia and Queensland mining districts concentrate demand for 350 kW DC systems with on-site battery buffering to manage Australian Energy Market Operator connection capacity constraints.
- Offsite:Standalone charging plazas and highway corridor locations requiring dedicated grid infrastructure. Pacific Highway and Hume Highway corridors present white space for intercity logistics networks; distribution network service provider tariff reforms complicate long-term power purchase agreements.
- Workplace:Employer-sponsored AC charging at commercial properties.
- Home:Residential garage and driveway installations.
Onsite deployments command the majority of capital expenditure; Offsite installations are gaining share fastest.
Technology:
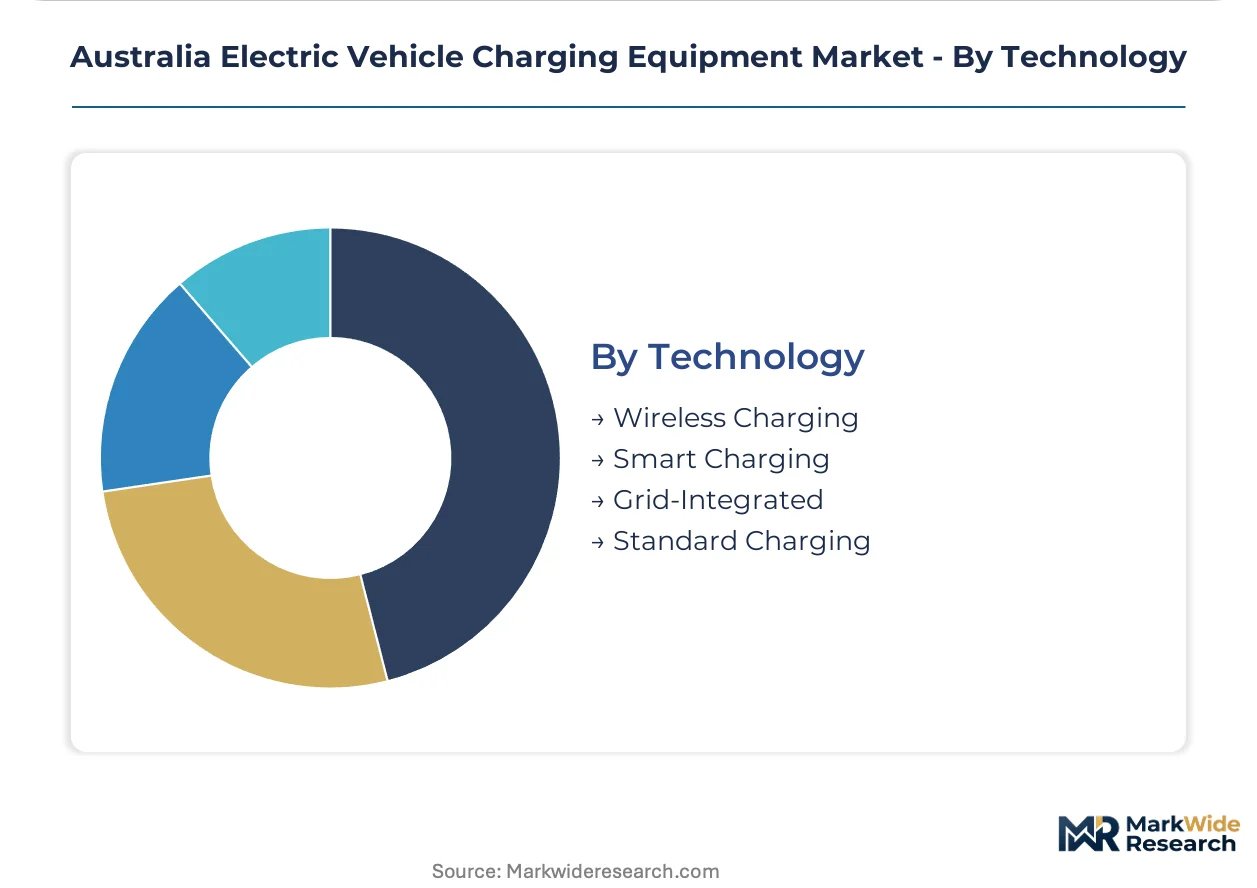
Software-attached revenue pools diverge sharply between basic conductive systems and grid-interactive platforms.
- Smart Charging:Demand response and time-of-use optimization protocols integrated with charger hardware. Fleet operators in Victoria and New South Wales are adopting these systems to reduce peak demand charges under Essential Services Commission of Victoria frameworks; recurring software revenue extends customer lifetime value beyond initial hardware sales.
- Grid-Integrated:Vehicle-to-grid bidirectional charging hardware unifying energy storage and grid services functions. Mining fleet pilots in Queensland are testing depot-based systems to generate ancillary revenue streams; this convergence compresses the boundary between transportation and distributed energy resources.
- Wireless Charging:Inductive power transfer systems for automated fleet applications.
- Standard Charging:Basic conductive systems without network connectivity or load management capabilities.
Smart Charging dominates software-attached revenue pools; Grid-Integrated systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sydney and Melbourne anchor Australia's electric vehicle charging infrastructure deployment, with motorway corridors and mining districts driving divergent regional investment patterns across state jurisdictions.
New South Wales
Metropolitan Sydney and the Pacific Highway corridor concentrate destination charging and DC fast charger networks. The state's zero-emission vehicle strategy mandates public fleet electrification timelines that compress procurement schedules for highway corridor operators. Port Botany logistics clusters and Blue Mountains transit routes are prioritizing 350 kW liquid-cooled installations to service intermodal freight electrification.
Victoria
Melbourne's metropolitan ring and the Hume Highway corridor dominate AC workplace charging and DC highway deployments. Essential Services Commission of Victoria demand charge frameworks are recalibrating site selection economics toward on-site battery buffering. Geelong manufacturing zones and Latrobe Valley industrial precincts are piloting grid-integrated vehicle-to-grid systems for fleet depot applications.
Queensland
Resource extraction operations in the Bowen Basin and Surat Basin are driving orders for heavy-duty DC rapid dispensers under diesel displacement programs. Australian Renewable Energy Agency funding accelerates capital deployment for mining fleet electrification pilots. Brisbane's metropolitan charging network and the Bruce Highway corridor are expanding destination charging at retail and municipal properties.
Western Australia
Pilbara mining districts and Perth metropolitan corridors present divergent infrastructure requirements spanning 350 kW depot systems and residential AC installations. Grid connection capacity constraints at remote mine sites are accelerating adoption of integrated battery storage with charging assets. Kwinana industrial precincts and Fremantle port logistics hubs are prioritizing smart charging protocols under state-level clean transport mandates.
South Australia
Adelaide's metropolitan network and the Stuart Highway corridor are expanding public charging density under renewable energy integration targets. The state's high solar penetration is driving vehicle-to-grid pilot programs that unify transportation and distributed energy resources. Barossa Valley agricultural logistics and Port Augusta industrial zones are testing off-grid charging configurations with on-site generation.
Australia Electric Vehicle Charging Equipment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification complexity and local engineering presence requirements. The vendor base organizes around three strategic tiers: domestic manufacturers with in-house testing laboratories, international suppliers with Australian engineering subsidiaries, and direct-to-consumer residential specialists. Competitive moves concentrate on certified installer network scaling and strategic partnerships with distribution network service providers for grid connection priority.
Within the domestic manufacturing tier, Tritium exemplifies premium positioning through its Brisbane-based production footprint. JET Charge and EVSE Australia occupy complementary positions across commercial installation and residential direct-to-consumer channels respectively. These three anchors illustrate how AS/NZS 3000 certification requirements and local engineering obligations stratify competitive positioning around regulatory compliance depth rather than scale alone.
| Leading Market Players |
|---|
| Tritium |
| EVSE Australia |
| JET Charge |
| Evnex |
| ABB Ltd |
| Siemens AG |
| Tesla Inc. |
| Delta Electronics Inc. |
| Schneider Electric |
| Others |
Pricing and Supply Chain Analysis
Copper and power electronics volatility cascades from raw material markets through three distinct pricing tiers for Australian charging equipment, compressing margins on residential 2.3 kW single-phase units while premium 350 kW liquid-cooled DC systems retain pricing power through AS/NZS 3000 certification bundling.
Pricing Analysis
Throughput-based pricing anchors commercial DC fast charger procurement, with fleet operators negotiating rates tied to energy delivered per site rather than hardware acquisition cost alone. Price differentiation separates AS/NZS 3000 certified premium tiers from uncertified economy imports, with brand premiums commanding additional margin for Tritium's Brisbane-manufactured units. Cost compression in the residential AC segment intensifies because EVSE Australia's direct-to-consumer channel control forces wholesaler-dependent competitors into price erosion. Mining and logistics fleet operators exhibit lowest price sensitivity, prioritizing uptime guarantees and load management integration over unit economics.
Supply Chain Analysis
AS/NZS 3000 qualified electrician scarcity gates downstream installation capacity, constraining residential tier deployment velocity regardless of upstream manufacturing output. Supply concentrates in China for power electronics modules, South Korea for battery management systems, and Germany for precision cooling components. The supply chain rests on copper conductor and silicon carbide semiconductor dependencies. Single-source vulnerability runs through Chinese power module suppliers subject to Australian customs inspection protocols. Distribution runs through certified installer networks for residential tiers and direct utility negotiations for commercial DC deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's charging equipment market is accelerating into a vertical-integration race, with domestic manufacturers capturing margin through captive Brisbane production and in-house testing laboratories while importers struggle with AS/NZS 3000 certification barriers.
For Market Incumbents: Acquire certified installer networks to lock residential channel control against EVSE Australia's digital-first encroachment. Secure exclusive distribution network service provider partnerships for grid connection priority at highway corridor sites. Defensive consolidation must address JET Charge's municipal property portfolio exclusives through deeper Essential Services Commission of Victoria regulatory engagement. For New Entrants and Emerging Players: Apartment dwellers in Queensland and Western Australia represent the most penetrable buyer archetype, as emerging multi-unit residential building codes create landlord obligation scenarios without established supplier relationships. White space targets include Bruce Highway corridor gaps and Surat Basin mining depot locations underserved by Tritium's highway focus. Go-to-market execution should anchor in ARENA funding program co-application to bypass capital barrier constraints. For Investors and Strategic Acquirers: Essential Services Commission of Victoria demand charge framework finalization is the leading indicator that smart charging software revenue pools will separate hardware-margin players from recurring-revenue winners. Long-term viability across the projection horizon favors targets with integrated load management platforms and vehicle-to-grid pilot deployments. Acquisition focus should center on mid-cap specialists with Queensland mining fleet relationships and pending grid-integrated technology certifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Electronics | Captive semiconductor sourcing insulates margins from Chinese supply volatility under Australian customs protocols. |
| Smart Charging Platform Integration | Demand response software attachment extends customer lifetime value beyond Essential Services Commission of Victoria tariff uncertainty. |
| ARENA Funding Program Partnership | Co-investment structures accelerate capital deployment for mining fleet electrification pilots in Queensland. |
| Certified Installer Network Acquisition | Channel control replication of EVSE Australia's residential tier dominance requires AS/NZS 3000 qualified electrician capture. |
| Vehicle-to-Grid Technology Licensing | Grid-integrated hardware convergence enables ancillary revenue streams for depot-based mining operations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across fleet procurement managers, distribution network service provider planning officers, certified electrical contractors, and ARENA program administrators. Australian Energy Market Operator grid connection databases, Essential Services Commission of Victoria tariff schedules, and Australian Bureau of Statistics import records provided demand-side validation. Bottom-up charger shipment tallies triangulated against top-down infrastructure investment flows from state-level zero-emission vehicle mandate disclosures.
Data-stream reconciliation across product type, end user archetype, installation location, and power transfer technology dimensions shaped the analytical framework. CAGRs were derived from segment-level trajectory modeling against ARENA funding disbursement schedules and mining fleet electrification announcement pipelines. Forecast inputs incorporated AS/NZS 3000 certification timeline assumptions and distribution network tariff reform probability weights.
Revisions become necessary when Essential Services Commission of Victoria demand charge frameworks materially diverge from modeled scenarios or when copper and power electronics input costs shift beyond historical volatility bands. A model refresh is warranted upon material change in ARENA funding allocation priorities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Wireless Charging Market
Electric Vehicle Charging
Electric Vehicle Charger and Charging Station Market
Electric Vehicle Charging
EV DC Chargers Market
Electric Vehicle Charging
Automotive EV Charging Adapters Market
Electric Vehicle Charging
Portable EV Charger Market
Electric Vehicle Charging
Electric Vehicle DC Fast Charging Station Market
Electric Vehicle Charging
Electric Vehicle Charging Facilities Market
Electric Vehicle Charging
Electric Vehicle Fast and Rapid Charger Market
Electric Vehicle Charging
North America EV Charging Stations Market
Electric Vehicle Charging
Germany Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Europe Electric Vehicle Charging Cable Market
Electric Vehicle Charging
Asia Pacific Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
High-Thermal-Conductivity Gap-Fill Adhesives for EV Battery Cooling Plates Market
Electric Vehicle Charging
Europe EV Charging Stations Market
Electric Vehicle Charging
Pantograph Charger Market
Electric Vehicle Charging
Two Wheel Electric Vehicle Charger Market