
 Western Europe Electric Vehicle (EV) Charging Equipment Market | 2026-2036
Western Europe Electric Vehicle (EV) Charging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Western Europe Electric Vehicle (EV) Charging Equipment Market Insights
Copper-intensive cable assemblies are shifting toward aluminum-core and composite conductor designs in mid-power charging hardware. ABB Ltd leverages its Swiss manufacturing base to sustain high-voltage R&D throughput for DC fast charging modules. Siemens AG anchors its position through grid-integration software that couples charging stations with building energy management. Schneider Electric SE competes on commercial installation scale across French retail and office portfolios.
Western Europe Electric Vehicle (EV) Charging Equipment comprises electrical infrastructure that converts grid alternating current to direct current at power levels from 3.7 kW residential wallboxes to 350 kW highway dispensers, incorporating power electronics, cooling systems, and communication protocols for vehicle-to-grid authentication. Its primary purpose is to replenish battery electric vehicle energy stores while managing peak demand charges and renewable intermittency. DC Fast Chargers dominate capital deployment in highway corridor tenders, while Smart Charging technology captures software margin pools through dynamic load balancing and time-of-use optimization. Wallbox Chargers lead unit volumes in residential retrofit markets where Installation costs drive total ownership economics.
The EU Green Deal mandates binding national targets that shape charger density requirements, while CE marking and the F-Gas Regulation govern refrigerant-based thermal management in liquid-cooled dispensers. Germany's KBA enforces interoperability standards that determine product market access for cross-border fleet operators. Stakeholders must monitor how France's ANSM-linked grid codes and the Netherlands' net metering revisions alter site host economics for public charging investments.
Market Dynamics
The EU Green Deal's binding emissions targets are compressing infrastructure deployment timelines ahead of vehicle fleet turnover, forcing charging asset buildouts to front-run EV sales curves in Germany, France, and the Netherlands.
Growth Catalysts
- Municipal Transit Mandates:Transit agencies in Germany and France are accelerating fleet electrification schedules, creating concentrated demand for depot charging systems and opportunity charging infrastructure.
- CE Marking Harmonization:Unified certification standards under the EU Green Deal are reducing cross-border deployment friction for equipment manufacturers serving the Rhine-Ruhr corridor.
- Liquid-Cooled Thermal Management:Advances in refrigerant-based cooling systems are enabling sustained 350 kW output in highway dispensers, expanding serviceable vehicle classes.
Market Restraints
- Copper Price Volatility:Cable assembly costs remain exposed to commodity swings, pressuring margins on copper-intensive AC charging hardware.
- Grid Connection Queues:Distribution network operators in the Netherlands' Randstad logistics belt are extending lead times for high-capacity site connections.
- F-Gas Regulatory Burden:The F-Gas Regulation is imposing refrigerant phase-down schedules that complicate thermal system design cycles for liquid-cooled dispensers.
Strategic Opportunities
- Vehicle-to-Grid Integration:Bidirectional charging protocols are opening revenue streams from grid services, with French retail hosts piloting building energy arbitrage.
- Aluminum-Core Conductor Migration:Composite conductor designs are creating cost-advantaged positions in mid-power commercial segments.
- ANSM Grid Code Alignment:France's updated connection standards are streamlining co-location of storage and charging assets for C&I site hosts.
Industry Challenges
- Interoperability Certification Bottlenecks:Germany's KBA testing protocols are extending time-to-market for cross-border fleet operators requiring multi-network roaming.
- Power Electronics Talent Scarcity:High-voltage DC module engineering capacity is concentrating among Swiss and German specialist firms, constraining R&D throughput for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Western Europe Electric Vehicle (EV) Charging Equipment Market |
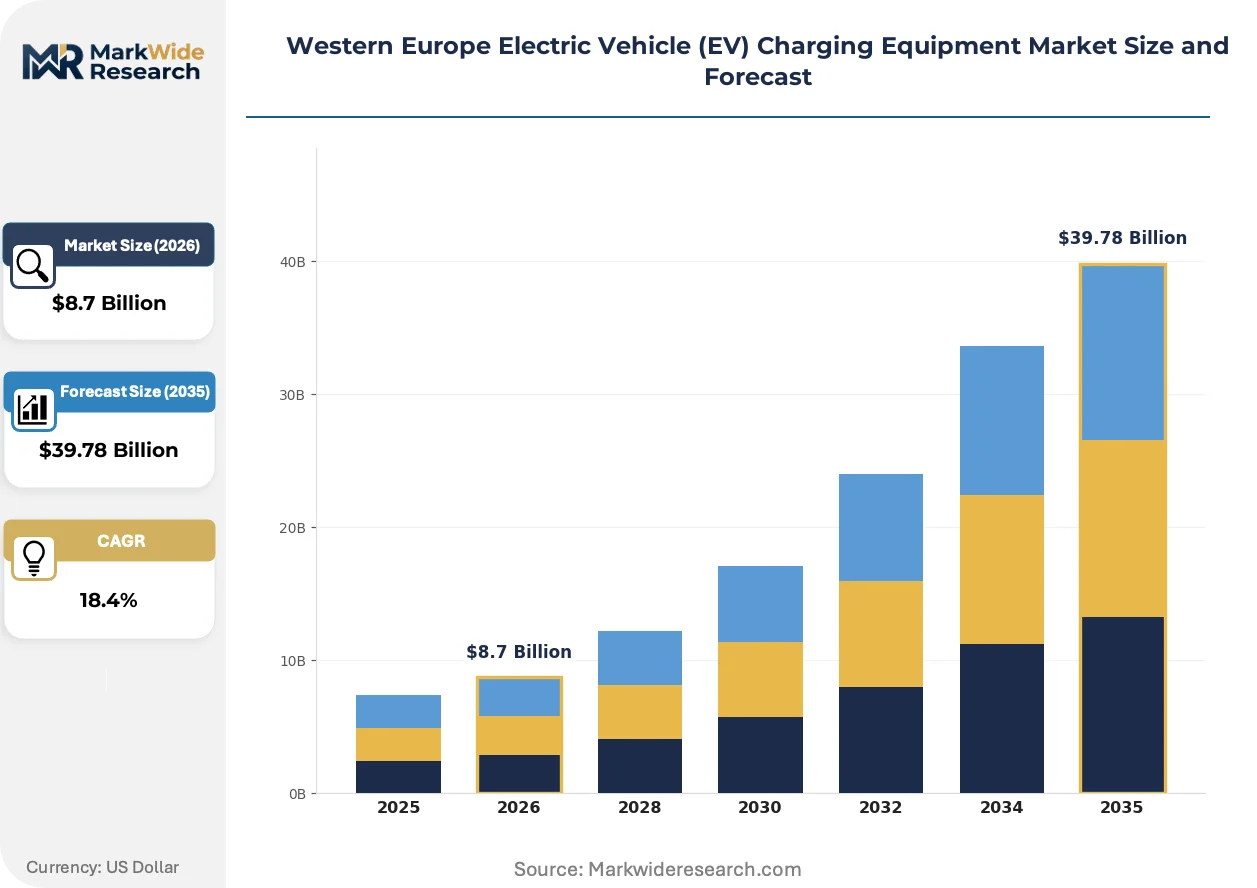
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Chargers, DC Fast Chargers, Wallbox Chargers, Portable Chargers Technology: Smart Charging, Wireless Charging, Ultra-Fast Charging, Bidirectional Charging Installation: Home Installations, Public Charging Stations, Commercial Installations, Fleet Charging Solutions End User: Individual Consumers, Businesses, Government, Transportation Fleets |
| Companies Covered | ABB Ltd, Siemens AG, ChargePoint Holdings Inc., Schneider Electric SE, Tesla Inc., Robert Bosch GmbH, EVBox Group, Webasto Group, Shell Plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Western Europe Electric Vehicle (EV) Charging Equipment Market Trends and Innovations
Charging infrastructure is converging with building energy systems and grid management platforms, compressing the boundary between mobility and stationary power assets across Western European deployment sites.
Silicon carbide power semiconductors are unifying conversion efficiency gains across DC fast charging modules, enabling higher switching frequencies with reduced thermal losses. Fleet operators in Germany's logistics corridors are specifying SiC-based hardware for depot installations to minimize demand charge exposure. This technology is unifying hardware footprints and cooling requirements, compressing total installed cost per port.
The F-Gas Regulation is tightening refrigerant containment standards for liquid-cooled dispensers, forcing redesigns of thermal management architectures. Equipment manufacturers are responding with sealed-loop systems and alternative working fluids to maintain 350 kW sustained output. Highway corridor tenders in France and the Netherlands are most affected, with specifiers now requiring decade-long refrigerant integrity guarantees.
Fleet procurement patterns are consolidating around energy-as-a-service models that unbundle hardware capital from operational expenditure. Logistics operators in the Randstad belt are shifting from ownership to subscription structures covering installation, maintenance, and energy optimization. This reconfiguration is most visible among Dutch last-mile delivery fleets, where total cost-per-mile metrics now dominate supplier selection criteria.
Western Europe Electric Vehicle (EV) Charging Equipment Market Segmentation
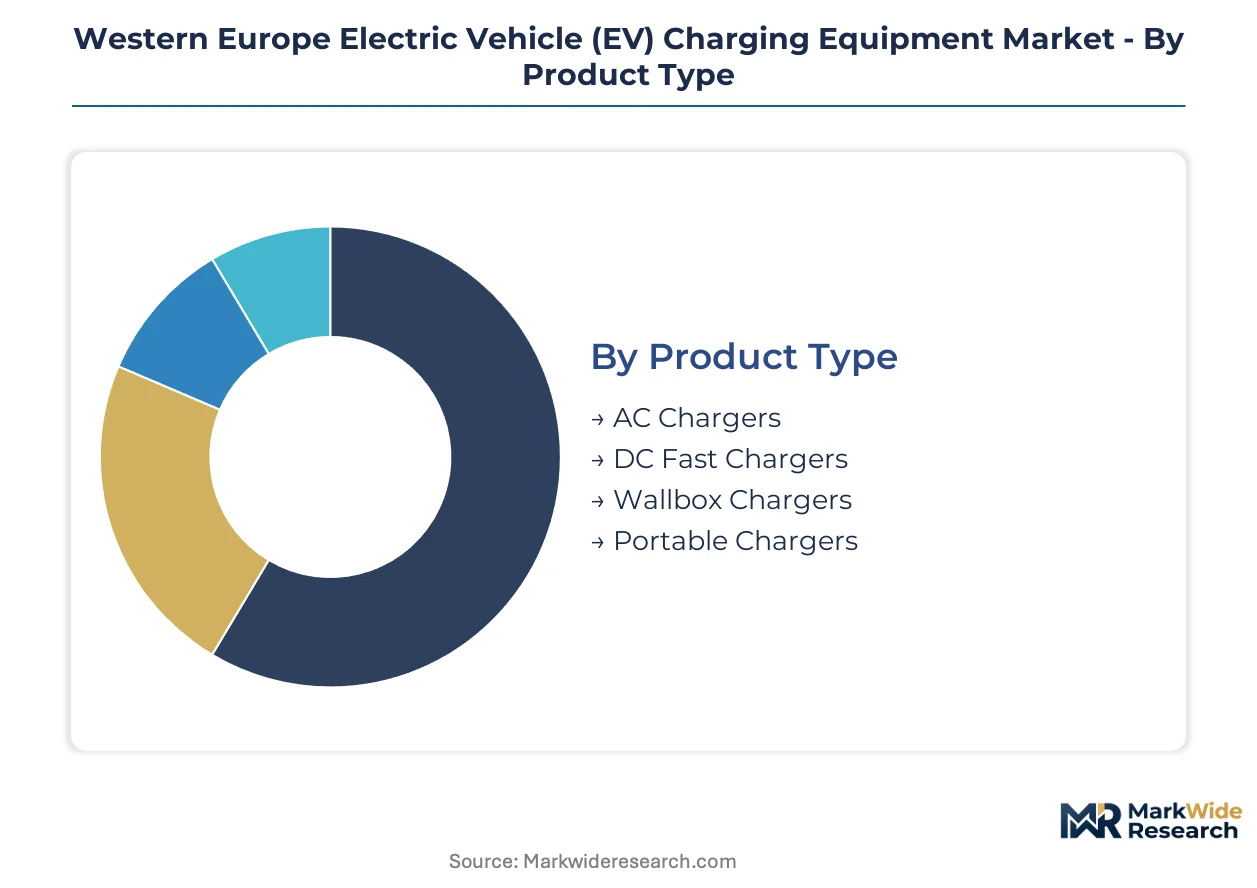
Segmentation in Western Europe's EV charging equipment market reveals how hardware specifications, software integration, and ownership models diverge across deployment contexts. Charging asset procurement splits between standardized high-volume residential units and customized commercial systems requiring site-specific engineering.
Product Type:
Standardization dominates residential and highway segments where interoperability mandates limit design variation, while depot and commercial installations demand customized power electronics and thermal configurations.
- AC Chargers:These units convert grid alternating current at power levels from 3.7 kW to 22 kW through onboard vehicle rectifiers. Demand clusters in German multi-unit residential retrofits where installation cost sensitivity shapes procurement decisions. Copper price volatility is accelerating aluminum-core conductor adoption in mid-power cable assemblies.
- DC Fast Chargers:Direct current dispensers bypass onboard conversion, delivering 50 kW to 350 kW through high-voltage power modules with liquid-cooled thermal management. Highway corridor tenders across France and the Netherlands specify these units for intercity fleet routing. The F-Gas Regulation is forcing refrigerant system redesigns to maintain sustained output.
- Wallbox Chargers:Compact residential units mount on garage walls or parking structures, integrating load balancing software for time-of-use optimization.
- Portable Chargers:Mobile emergency units provide temporary charging capability through standard household outlets, serving backup power needs for individual consumers.
Most installed capacity flows through AC Chargers. Expansion is steepest in DC Fast Chargers.
Technology:
Cost tiers separate commodity power delivery from premium software-enabled systems that capture recurring revenue through energy management services.
- Smart Charging:Networked systems dynamically balance load across multiple ports using real-time grid signals and vehicle state-of-charge data. French retail hosts are piloting building energy arbitrage through these protocols. CE marking harmonization is reducing cross-border deployment friction for software-integrated hardware.
- Ultra-Fast Charging:Silicon carbide power semiconductors enable 350 kW output with reduced thermal losses, compressing hardware footprints for space-constrained urban sites. German logistics corridors specify SiC-based depot installations to minimize demand charge exposure.
- Wireless Charging:Inductive pad systems eliminate cable handling through electromagnetic coupling, targeting premium residential and automated fleet applications.
- Bidirectional Charging:Vehicle-to-grid protocols allow battery discharge back to building or grid infrastructure, creating ancillary revenue streams for C&I site hosts.
Smart Charging captures the majority of software margin pools. Ultra-Fast Charging is gaining share fastest among fleet operators.
Installation:
Volume concentration varies by customer procurement maturity, with residential markets scaling through retail channels and commercial deployments requiring extended engineering cycles.
- Home Installations:Single-point residential retrofits dominate unit volumes across the Netherlands, where net metering revisions alter total ownership economics. Installation labor and permitting represent significant cost components relative to hardware.
- Public Charging Stations:Highway and urban street furniture deployments serve occasional charging needs for private vehicle owners. Germany's KBA interoperability standards determine product market access for cross-border roaming.
- Commercial Installations:Workplace and retail parking systems integrate with building energy management platforms. Schneider Electric anchors position through French office and retail portfolio scale.
- Fleet Charging Solutions:Depot and opportunity charging infrastructure serves municipal transit agencies accelerating electrification timelines across Germany and France.
Home Installations lead unit shipments. Fleet Charging Solutions show the steepest expansion trajectory as municipal mandates compress deployment timelines.
End User:
Customer type determines procurement structure, with individual consumers purchasing hardware directly and fleet operators shifting toward energy-as-a-service subscriptions.
- Transportation Fleets:Logistics operators and municipal transit agencies specify charging infrastructure through total cost-per-mile metrics. Dutch last-mile delivery fleets in the Randstad belt are unbundling hardware capital from operational expenditure through subscription structures.
- Businesses:Corporate fleet managers and facility operators procure charging as employee amenity or customer retention tool. Grid connection queues in the Netherlands' Randstad logistics belt are extending lead times for high-capacity site connections.
- Individual Consumers:Private vehicle owners purchase residential charging hardware through automotive dealer channels or direct retail.
- Government:Municipal and national agencies fund public charging infrastructure to meet EU Green Deal binding emissions targets.
Transportation Fleets command the largest project scale. Businesses are expanding most quickly as workplace charging becomes standard employee benefit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr corridor anchors charger deployment density, with municipal transit agencies and logistics operators compressing installation timelines ahead of fleet turnover mandates across Germany, France, the Netherlands, Belgium, and Switzerland.
Germany
Depot charging systems for municipal bus fleets and highway corridor tenders for 350 kW dispensers dominate procurement pipelines. KBA interoperability standards determine product market access for cross-border fleet operators requiring multi-network roaming capabilities. The Rhine-Ruhr logistics belt concentrates demand from last-mile delivery electrification programs.
France
ANSM-linked grid code revisions are streamlining co-location of battery storage with charging assets for commercial and industrial site hosts. Highway corridor tenders specify liquid-cooled dispensers with decade-long refrigerant integrity guarantees under F-Gas Regulation phase-down schedules. The Île-de-France region leads workplace charging installations across office portfolios.
Netherlands
Randstad logistics belt operators are unbundling hardware capital from operational expenditure through energy-as-a-service subscription structures. Net metering revisions alter total ownership economics for residential retrofit markets where installation labor dominates project costs. Grid connection queues extend lead times for high-capacity site connections.
Belgium
CE marking harmonization reduces cross-border deployment friction for equipment manufacturers serving the Benelux logistics corridor. Brussels-based fleet operators specify smart charging protocols for building energy arbitrage and peak demand charge management. Flemish port authorities accelerate shore power and depot charging infrastructure for maritime freight electrification.
Switzerland
Swiss manufacturing bases sustain high-voltage DC module R&D throughput for power electronics specialists serving adjacent European markets. Alpine highway corridor tenders prioritize liquid-cooled thermal management for sustained high-altitude output. Zurich and Geneva metropolitan areas concentrate residential wallbox retrofits with load balancing software integration.
Western Europe Electric Vehicle (EV) Charging Equipment Market Competitive Landscape
Global majors compete with regional champions across hardware standardization and grid-integration software dimensions, producing a tiered structure where Swiss and German engineering specialists anchor premium DC fast charging segments while diversified electrical conglomerates capture commercial installation scale. Three archetypes dominate: power electronics specialists with captive high-voltage R&D capacity, building energy management platforms extending into charging infrastructure, and integrated energy majors leveraging retail fuel station networks. Competitive moves concentrate on strategic partnerships for grid code alignment and portfolio diversification into vehicle-to-grid protocols.
Within the power electronics specialist tier, ABB Ltd and Siemens AG exemplify engineering-intensive positioning, with the former representing Swiss-based high-voltage DC module development and the latter anchoring German grid-integration software capabilities. Schneider Electric SE occupies a position bridging commercial installation scale with building energy management platforms across French retail and office portfolios.
| Leading Market Players |
|---|
| ABB Ltd |
| Siemens AG |
| ChargePoint Holdings Inc. |
| Schneider Electric SE |
| Tesla Inc. |
| Robert Bosch GmbH |
| EVBox Group |
| Webasto Group |
| Shell Plc |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up specialists in depot charging systems are consolidating procurement leverage across Germany's Rhine-Ruhr corridor, compressing supplier margins while extending payment terms that feed back into aluminum-core conductor adoption for cost-down positioning.
Pricing Analysis
Input-cost pass-through from copper and silicon carbide semiconductors is reshaping hardware economics across power tiers. Three-tier pricing structure across premium liquid-cooled dispensers, standard AC wallboxes, and economy portable units separates certification-grade highway corridor equipment from residential retrofit hardware. Pricing pressure stems from municipal tender standardization in France and the Netherlands. Fleet operators show lowest price sensitivity due to total cost-per-mile procurement metrics, while individual residential buyers in the Netherlands drive hardest bargain on installation-included packages.
Supply Chain Analysis
Reverse-logistics flows for power electronics refurbishment are emerging from Swiss and German specialist firms serving warranty replacement programs across Western European installed bases. Manufacturing concentrates in Switzerland, Germany, and the Netherlands for high-voltage DC modules, cable assemblies, and grid-integration software respectively. Component sourcing draws from Chinese silicon carbide foundries, Chilean copper smelters, and German power semiconductor packaging operations. Single-source vulnerability in SiC substrate supply creates exposure. Distribution runs through electrical wholesale channels for commercial installations and automotive dealer networks for residential retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through aluminum-core conductor substitution and silicon carbide efficiency gains that compress thermal management costs across mid-power segments.
For Market Incumbents: Cement grid-integration software lock-in through building energy management coupling, defending against pure-play hardware commoditization. Extend captive high-voltage R&D capacity in Swiss manufacturing clusters to maintain DC fast charging module differentiation. Prioritize CE marking harmonization investments to reduce cross-border deployment friction. For New Entrants and Emerging Players: Launch via energy-as-a-service subscription models targeting Dutch last-mile delivery fleets in the Randstad belt. Penetrate bidirectional charging protocols for French retail hosts piloting building energy arbitrage. White space sits in aluminum-core cable assembly manufacturing for cost-sensitive AC charger tiers. For Investors and Strategic Acquirers: Valuations sit cheapest among component suppliers without captive installation service arms. Long-term viability favors power electronics specialists with backward integration into semiconductor packaging. Monitor F-Gas Regulation refrigerant phase-down schedules as inflection signal for thermal management redesign cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Module Scale-Up | Swiss and German specialists compress thermal losses for 350 kW highway dispensers. |
| Grid Code Alignment Partnership | ANSM-linked standards in France streamline storage co-location for C&I hosts. |
| Aluminum-Core Conductor Transition | Mid-power AC charger suppliers offset copper volatility through composite designs. |
| Energy-as-a-Service Platform Launch | Dutch logistics operators unbundle hardware capital from operational expenditure. |
| Vehicle-to-Grid Protocol Certification | French retail hosts capture ancillary revenue through bidirectional charging pilots. |
Research Methodology
Coverage spans Western Europe with primary inputs from each national market, combining interviews with power electronics engineers at charging equipment manufacturers, procurement directors at municipal transit agencies, grid integration specialists at distribution network operators, and facility managers at commercial site hosts. Secondary validation draws from EU Green Deal implementation reports, KBA interoperability standards filings, F-Gas Regulation compliance databases, and national energy agency deployment statistics. Bottom-up unit shipment modeling triangulates against top-down infrastructure investment tracking across the analysis window.
Granularity-level modeling disaggregates volume and value across product type, installation context, technology tier, and end-user archetype throughout the forecast period. CAGRs derive from infrastructure deployment curves front-running EV sales penetration, with segment-specific drivers including municipal fleet electrification mandates, highway corridor tender awards, and residential retrofit incentive programs. Forecast inputs incorporate copper price trajectory assumptions and silicon carbide adoption S-curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under copper commodity spikes or grid connection queue extensions. Projections reflect assumptions on EU Green Deal target enforcement and CE marking harmonization timelines. Practitioners should monitor KBA interoperability certification bottlenecks and ANSM grid code revision implementation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
EV Charging Management Software Platform Market
Electric Vehicle Charging
EV DC Chargers Market
Electric Vehicle Charging
Smart EV Charger Market
Electric Vehicle Charging
EV Charging Software Market
Electric Vehicle Charging
Second Life Electric Vehicle Battery Market
Electric Vehicle Charging
Electric Vehicle AC Charging Pile Market
Electric Vehicle Charging
Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Electric Vehicle Charger and Charging Station Market
Electric Vehicle Charging
China Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Charging Management Software Market
Electric Vehicle Charging
Europe EV Charging Stations Market
Electric Vehicle Charging
Solar-Based Electronic Vehicle Market
Electric Vehicle Charging
France Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Asia-Pacific Portable EV Charger Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Infrastructure Market
Electric Vehicle Charging
Combined Charging System Market