
 Netherlands Electric Vehicle Charging Equipment Market | 2026-2036
Netherlands Electric Vehicle Charging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Electric Vehicle Charging Equipment Market Insights
The EU Green Deal is expanding infrastructure mandates across Dutch metropolitan corridors. Alfen N.V. anchors domestic manufacturing capacity for grid-integrated charging systems. EVBox Group B.V. dominates software-integrated hardware deployments across European markets. Schneider Electric SE leverages energy management expertise to differentiate integrated charging solutions.
Netherlands electric vehicle charging equipment comprises electrical systems that convert grid power to vehicle-compatible DC or AC output, typically operating at 230V single-phase or 400V three-phase with power ratings from 3.7 kW to 350 kW depending on charger classification. These systems enable energy transfer to battery electric vehicles and plug-in hybrids across residential, commercial, and public environments. DC Fast Chargers command premium positioning due to higher capital requirements and utility interconnection complexity, while AC Chargers sustain volume leadership in residential and workplace applications. Fleet Operators represent the fastest-growing end user segment as logistics electrification intensifies across Dutch distribution networks.
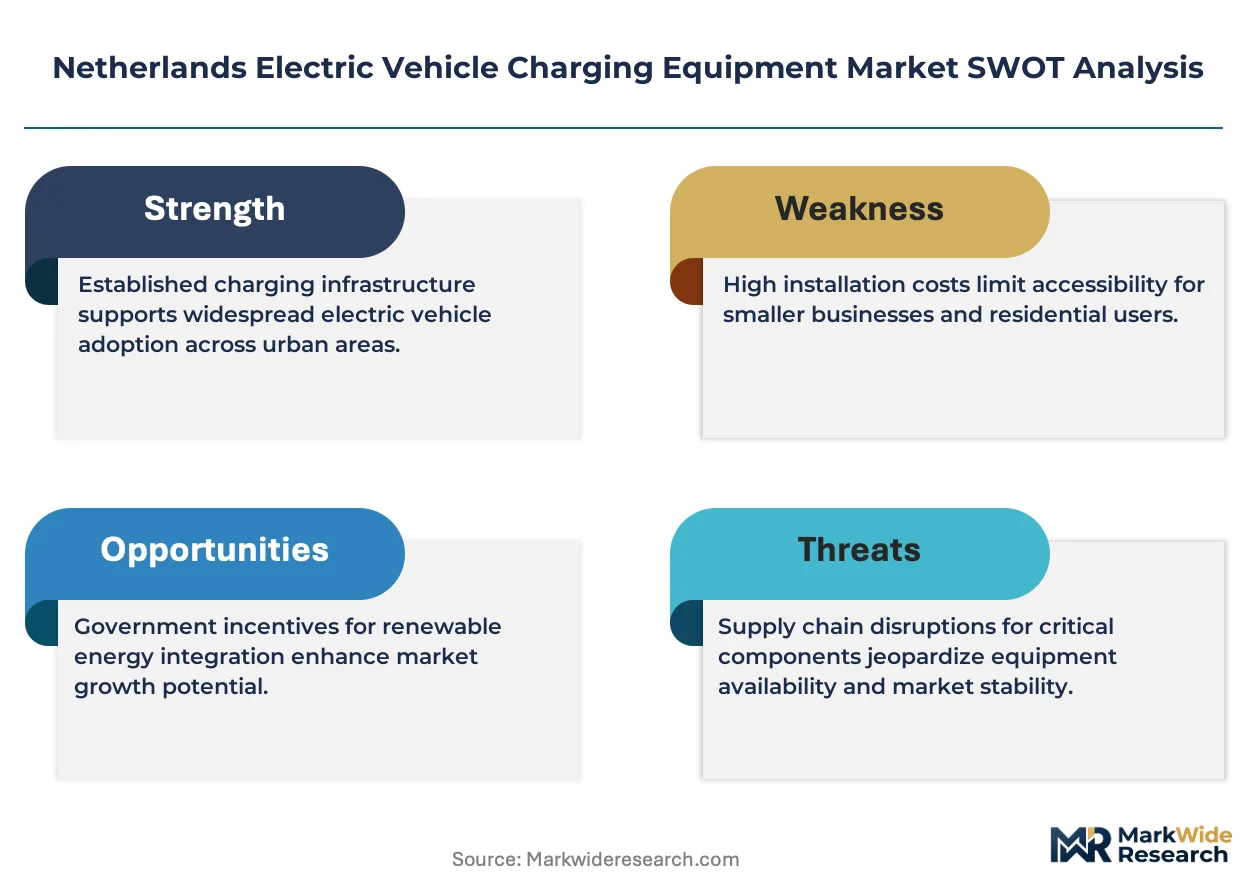
The Netherlands Authority for Consumers and Markets (ACM) oversees grid connection standards and tariffs, while the EU F-Gas Regulation and CE marking requirements shape equipment import and deployment protocols. The Dutch government's national charging infrastructure framework mandates standardized payment interoperability and minimum power output thresholds for public installations. Stakeholders must monitor grid capacity allocation policies and evolving utility rate structures as electrification scales beyond current distribution network limits.
Market Dynamics
Fleet electrification across Dutch logistics corridors is compressing installation timelines and forcing grid capacity reallocation decisions before distribution network upgrades complete. This demand surge from commercial vehicle operators is restructuring procurement priorities away from residential toward high-power DC infrastructure.
Growth Catalysts
- EU Green Deal ICE Phase-Out:The 2035 internal combustion engine ban mandates charging infrastructure density targets across Dutch metropolitan clusters, compelling public and private capital deployment.
- Randstad Logistics Electrification:Freight operators connecting Amsterdam, Rotterdam, The Hague, and Utrecht are converting distribution fleets, creating concentrated demand for 150+ kW DC fast charging corridors.
- Vehicle-to-Grid Integration:Bidirectional charging protocols are enabling fleet operators to monetize battery assets through frequency regulation services, improving total cost of ownership calculations.
Market Restraints
- Transformer Lead Times:Medium-voltage grid connection equipment faces 18-24 month procurement delays from European manufacturers, throttling site activation regardless of charger availability.
- Copper and Silicon Carbide Cost Volatility:Power electronics materials experience commodity price swings that compress hardware margins and destabilize project finance assumptions.
- Permitting Fragmentation:Municipal zoning authorities across Dutch provinces apply inconsistent technical requirements for public charging installations, extending approval timelines.
Strategic Opportunities
- Workplace Charging Mandates:Dutch commercial building codes are evolving to require EV-ready parking infrastructure in new construction, opening B2B channel expansion.
- North Sea Offshore Wind Integration:Coastal charging hubs can access direct renewable power purchase agreements, differentiating offerings through carbon intensity claims.
- Heavy-Duty Depot Electrification:Bus and truck fleet operators require megawatt-scale charging systems that current market supply inadequately serves, creating white space for specialized providers.
Industry Challenges
- Grid Integration Engineering Talent:Specialized power systems engineers capable of utility interconnection design are scarce relative to deployment targets, inflating labor costs.
- Payment Interoperability Certification:The Netherlands Authority for Consumers and Markets mandates complex roaming protocol compliance that extends software validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Electric Vehicle Charging Equipment Market |
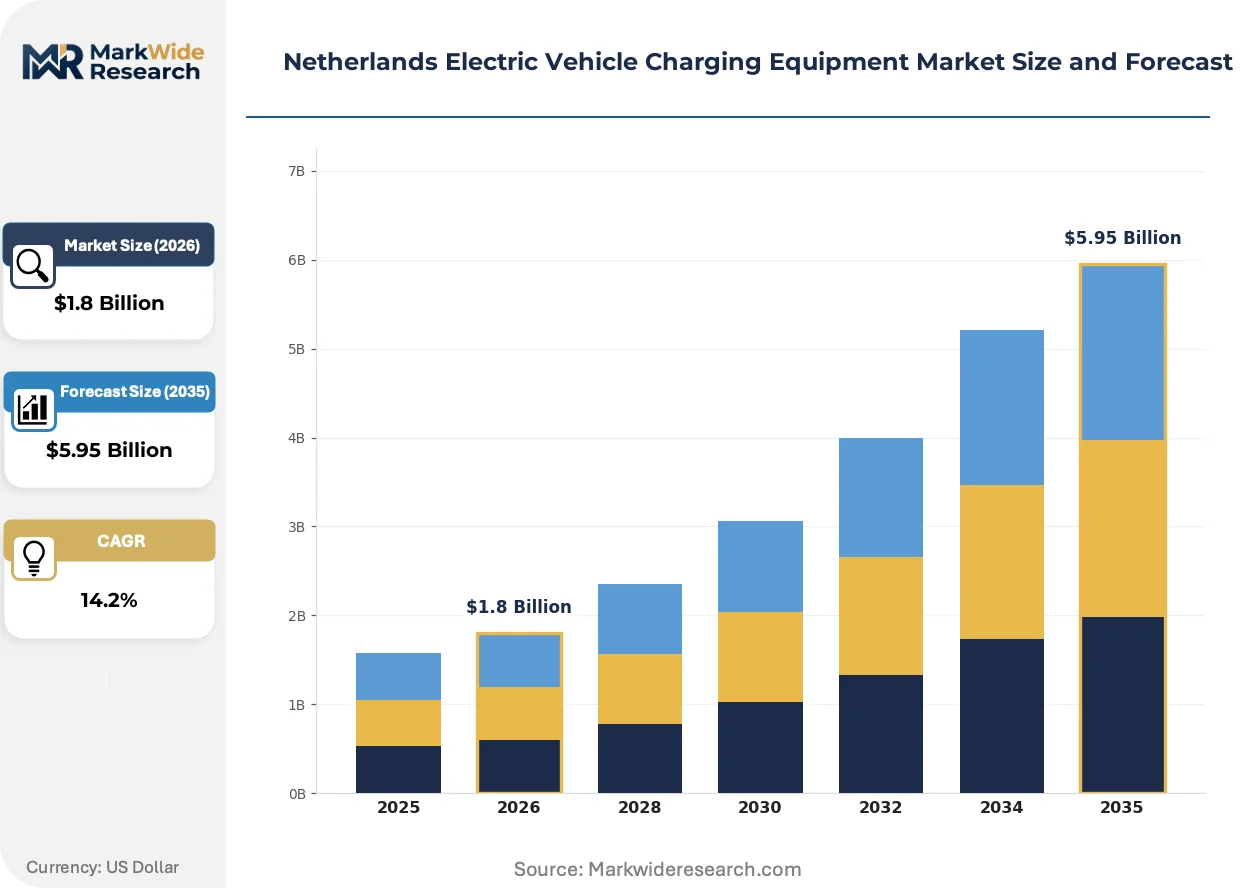
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Chargers, DC Fast Chargers, Wireless Chargers, Portable Chargers, Wall-Mounted Chargers Charging Speed: Level 1, Level 2, Rapid Charge, Ultra-Fast Charge, Supercharge End User: Fleet Operators, Commercial Complexes, Residential Buildings, Public Parking Lots, Retail Centers Installation Type: Indoor, Outdoor, Curbside, Garage, Workplace |
| Companies Covered | ABB Ltd, EVBox Group B.V., Alfen N.V., ChargePoint Inc., Heliox, NewMotion, Schneider Electric SE, Delta Electronics Inc., Wallbox Chargers S.L., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Electric Vehicle Charging Equipment Market Trends and Innovations
Hardware-software convergence is redefining competitive differentiation as charging systems evolve from passive electrical equipment to grid-interactive energy assets. This transformation is compressing vendor margins while elevating data and energy management capabilities.
Silicon carbide power semiconductors are consolidating thermal management architectures in high-power DC chargers. Fleet operators deploying 350 kW systems are specifying these components to reduce cooling system footprint and enable higher power density cabinets. The technology is consolidating supplier tiers as only integrated module manufacturers can deliver qualified systems at volume.
The EU F-Gas Regulation is accelerating refrigerant transitions in liquid-cooled charging systems. Equipment manufacturers must redesign thermal loops to accommodate lower global warming potential coolants before 2027 phase-down deadlines. Dutch installations in port and industrial zones face accelerated compliance timelines due to proximity to sensitive ecosystems.
Fleet procurement teams are consolidating vendor relationships through long-term service agreements that bundle hardware, installation, and energy management. Traditional equipment-only distributors are losing access to large logistics operators who prefer single-accountability contracts. This pattern is most pronounced among Randstad-based freight companies operating cross-border European routes.
Netherlands Electric Vehicle Charging Equipment Market Segmentation
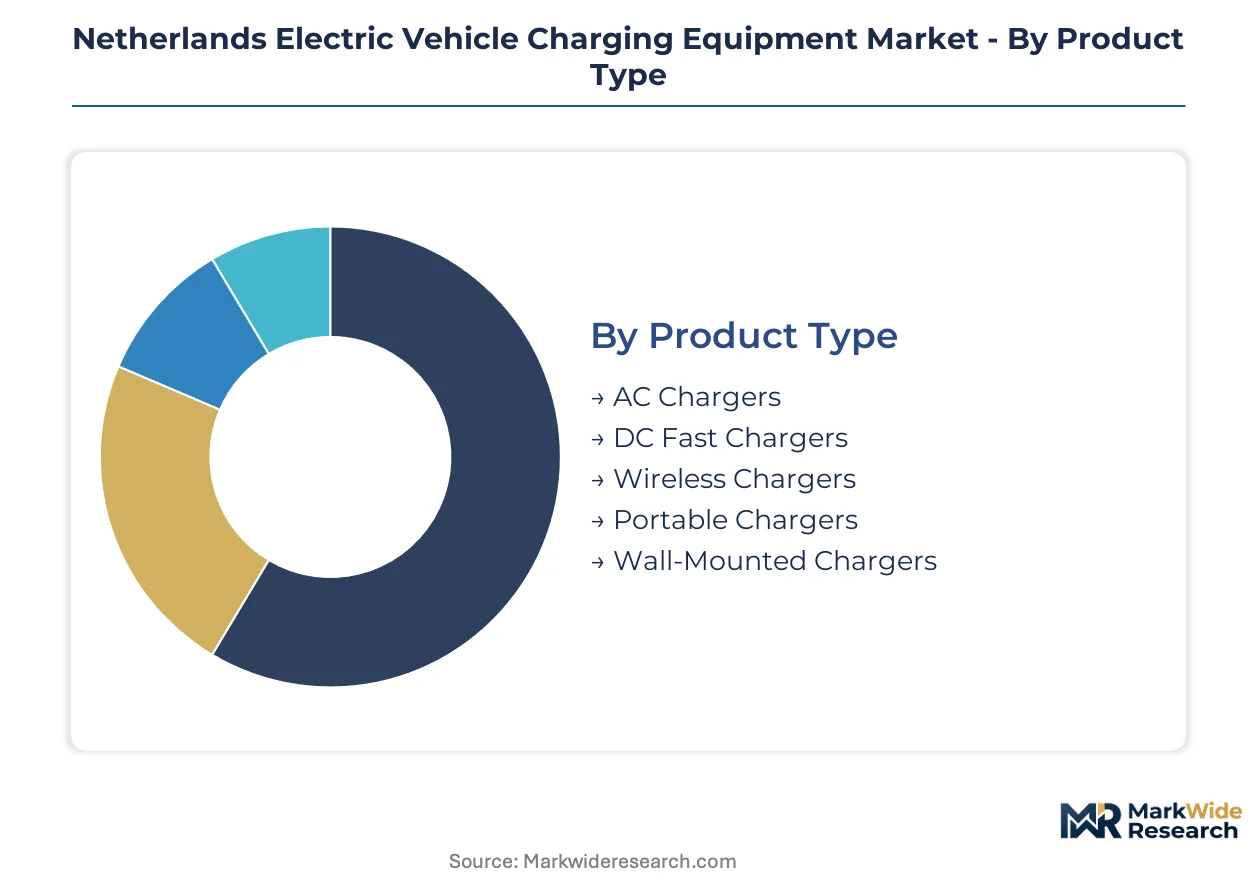
Segmentation reveals how capital intensity, installation complexity, and user requirements fragment procurement patterns across Dutch charging infrastructure. Understanding these divides exposes where margins concentrate and which technology trajectories will reshape deployment economics.
Product Type:
Capital intensity varies dramatically across hardware categories, with grid interconnection costs often exceeding charger hardware expenditure in high-power segments.
- AC Chargers:These units convert grid alternating current to vehicle-compatible power at 3.7-22 kW ratings through onboard vehicle rectifiers. Residential installations across Dutch suburbs and workplace parking in Utrecht business parks absorb the majority of volume, driven by lower electrical upgrade requirements and simpler utility approvals.
- DC Fast Chargers:Direct current systems bypass onboard conversion, delivering 50-350 kW through dedicated rectification cabinets and liquid-cooled cables. Randstad logistics corridors connecting Rotterdam port facilities to Amsterdam distribution centers concentrate demand, where fleet operators require sub-30-minute charging cycles for commercial vehicle uptime.
- Wireless Chargers:Inductive power transfer systems eliminate cable connections through ground-mounted transmitter pads and vehicle receiver coils. Municipal bus depots in The Hague are piloting these for automated overnight charging sequences.
- Portable Chargers:Compact 3.7-7.4 kW units with standard domestic plug connections provide emergency backup charging. Rural provinces without dense public infrastructure see concentrated household adoption.
- Wall-Mounted Chargers:Fixed AC units with integrated cable management and smart metering capabilities. Dutch apartment complexes increasingly specify these for shared parking facilities.
AC Chargers absorb the bulk of installed capacity; DC Fast Chargers are expanding most quickly.
Charging Speed:
Speed classification determines utility rate structures and grid connection priority across Dutch distribution networks.
- Level 1:Standard 230V single-phase residential connections delivering 2.3-3.7 kW through conventional household circuits. Overnight charging in Dutch single-family homes represents the dominant use case, constrained by limited power delivery and extended dwell times.
- Level 2:400V three-phase infrastructure supporting 11-22 kW output through dedicated circuit installation. Workplace parking installations in Amsterdam Zuidas commercial district favor these for employee vehicle turnaround during standard work hours.
- Rapid Charge:50 kW DC systems enabling 80% battery replenishment within 30-60 minutes. Highway service stations along A1 and A2 motorways deploy these for intercity travel corridors.
- Ultra-Fast Charge:150-350 kW high-power configurations requiring dedicated medium-voltage transformers and active liquid cooling. Rotterdam port logistics operators are specifying these for heavy-duty truck electrification.
- Supercharge:Proprietary high-speed protocols exceeding 250 kW with vehicle-specific communication handshakes. Premium passenger vehicle segments in North Holland province show concentrated adoption.
Level 2 infrastructure carries the highest cumulative installation count; Ultra-Fast Charge systems are climbing the fastest as fleet electrification accelerates.
End User:
Customer type dictates procurement scale, payment complexity, and service-level requirements across Dutch deployment channels.
- Fleet Operators:Logistics companies managing centralized vehicle pools require coordinated depot charging and corridor infrastructure. Dutch freight operators converting distribution networks across Randstad metropolitan clusters are driving megawatt-scale procurement with integrated energy management requirements.
- Commercial Complexes:Office campuses and mixed-use developments installing visitor and tenant charging amenities. Amsterdam business districts prioritize these for building certification compliance and tenant retention.
- Residential Buildings:Multi-unit dwellings and single-family installations with individual or shared charging access. Homeowner associations in Utrecht suburbs negotiate collective procurement for apartment parking retrofits.
- Public Parking Lots:Municipal and privately operated off-street facilities with mixed-user payment systems. Dutch cities mandate interoperability standards for these installations under ACM oversight.
- Retail Centers:Shopping complexes deploying charging as dwell-time extension amenities. Highway-adjacent retail locations in Gelderland province leverage these for customer capture during longer charging sessions.
Residential Buildings account for the largest cumulative installed base; Fleet Operators are gaining share fastest as logistics electrification intensifies.
Installation Type:
Physical siting determines environmental protection ratings, civil engineering requirements, and exposure to vandalism or weather degradation.
- Indoor:Climate-controlled environments within parking structures or maintenance facilities. Dutch corporate headquarters in The Hague favor these for executive vehicle fleets and visitor amenities.
- Outdoor:Exposed installations requiring IP65+ enclosure ratings and enhanced cable management. Street-side public charging in Amsterdam canal districts concentrates demand where indoor parking is unavailable.
- Curbside:Urban sidewalk deployments integrated with street furniture and pedestrian access requirements. Rotterdam municipal authorities prioritize these for residential neighborhoods lacking off-street parking.
- Garage:Multi-level parking structures with ventilation and fire suppression specifications. Underground installations in Utrecht city center face accelerated safety compliance timelines.
- Workplace:Employer-sponsored charging at commercial properties with fleet and employee mixed usage. Dutch tax incentives for workplace charging are expanding deployment across Eindhoven technology campuses.
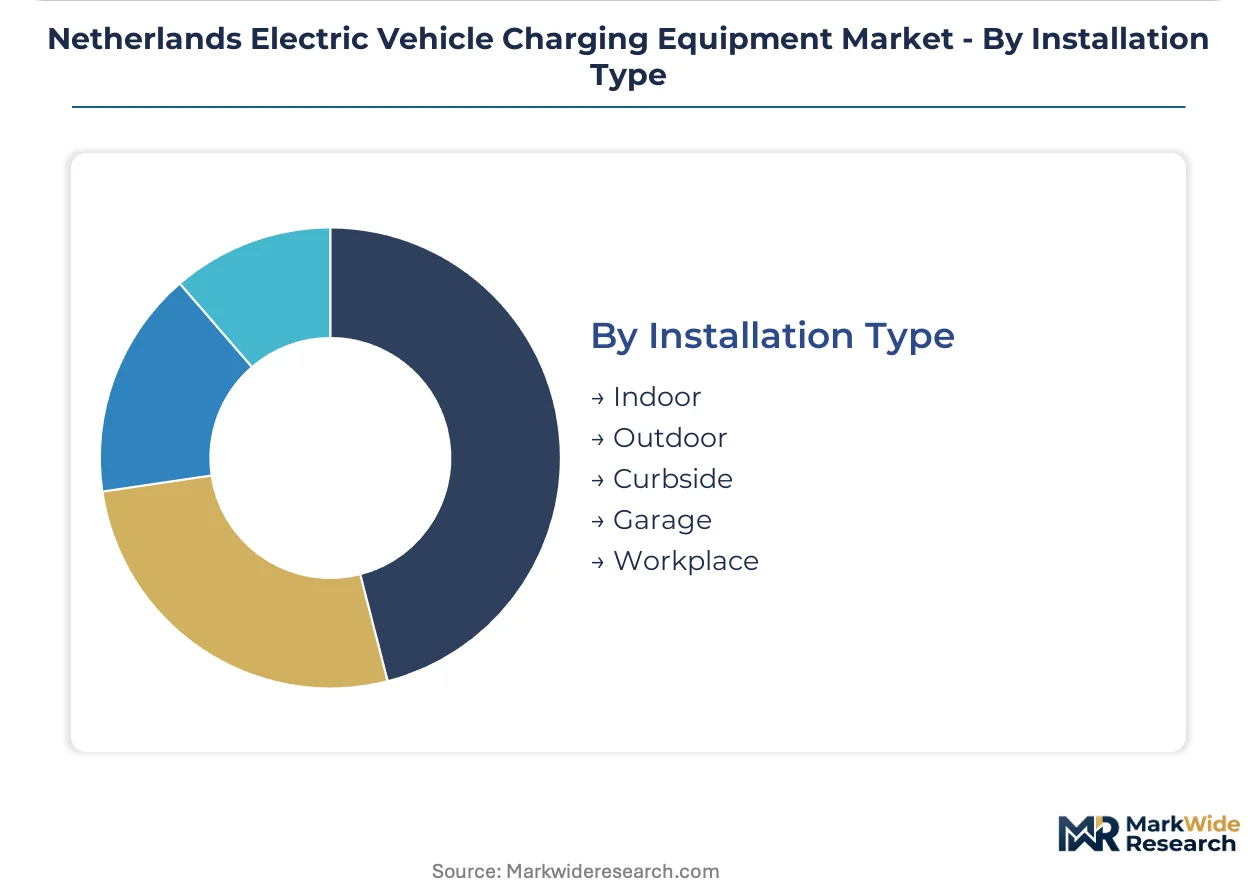
Outdoor installations carry the highest cumulative deployment; Workplace charging is expanding most quickly as commercial building codes evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Randstad metropolitan clusters linking Amsterdam, Rotterdam, The Hague, and Utrecht concentrate charging infrastructure deployment across Dutch logistics corridors and urban mobility networks.
North Holland
Amsterdam Zuidas commercial district and port-adjacent industrial zones drive workplace and fleet charging procurement. The Netherlands Authority for Consumers and Markets enforces payment interoperability standards here. Amsterdam's canal districts see concentrated curbside deployment where indoor parking remains unavailable.
South Holland
Rotterdam port logistics operators and distribution centers anchor heavy-duty truck electrification demand. EU F-Gas Regulation compliance timelines accelerate for coastal installations near sensitive ecosystems. Rotterdam municipal authorities prioritize curbside infrastructure in residential neighborhoods lacking off-street parking.
Utrecht
Suburban homeowner associations negotiate collective AC charger procurement for apartment parking retrofits. Dutch national charging infrastructure framework mandates standardized minimum power thresholds. Utrecht business parks absorb significant workplace Level 2 installation volume.
North Brabant
Eindhoven technology campuses expand workplace charging deployment under evolving commercial building codes. Dutch tax incentives for employer-sponsored charging accelerate B2B channel growth. The region's automotive heritage supports specialized engineering talent pools for grid integration design.
Northern Netherlands
Rural provinces without dense public infrastructure see concentrated portable charger adoption for emergency backup. Grid capacity allocation policies from distribution network operators shape deployment feasibility. Highway service stations along A1 and A2 motorways deploy rapid charge systems for intercity corridors.
Netherlands Electric Vehicle Charging Equipment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across hardware-software integration depth and grid-interactive energy management capabilities. The vendor base clusters around three strategic archetypes: integrated energy management specialists, hardware-focused equipment fabricators, and software-integrated platform operators. Consolidation pressure intensifies as fleet procurement teams demand single-accountability contracts bundling installation, maintenance, and energy services. Dominant competitive moves include long-term service agreement structures and silicon carbide power electronics integration for thermal density advantages.
Among Netherlands-based specialists, Alfen N.V. and EVBox Group B.V. exemplify the domestic integrated platform archetype, while Schneider Electric SE represents the multinational energy management tier. These anchors occupy positions across the premium-standard margin spectrum based on software differentiation and grid interconnection engineering depth.
| Leading Market Players |
|---|
| ABB Ltd |
| EVBox Group B.V. |
| Alfen N.V. |
| ChargePoint Inc. |
| Heliox |
| NewMotion |
| Schneider Electric SE |
| Delta Electronics Inc. |
| Wallbox Chargers S.L. |
| Others |
Pricing and Supply Chain Analysis
Backward integration into silicon carbide power module manufacturing anchors both supply security and pricing power for Dutch charging equipment vendors. This upstream control over critical power electronics insulates integrated manufacturers from commodity volatility while enabling premium positioning through thermal density advantages.
Pricing Analysis
Throughput-based pricing tied to vehicle charging cycles per day dominates fleet procurement contracts across Randstad logistics corridors. Three-tier pricing structure across premium, standard, and economy levels separates silicon carbide-enabled 350 kW systems from conventional IGBT-based hardware and basic AC residential units. Cost compression in economy AC tiers is intensifying because of commodity copper price swings and Asian import competition. Fleet operators show lowest price sensitivity due to total cost of ownership calculations incorporating vehicle uptime and energy management services.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Eindhoven anchor hub-and-spoke patterns for hardware deployment across Dutch provinces. Manufacturing concentrates in China for power electronics, Germany for precision engineering components, and the Netherlands for final system integration and software loading. Copper busbars, silicon carbide wafers, and liquid-cooled cable assemblies constitute critical input dependencies. Single-source vulnerability in European silicon carbide substrate supply poses structural risk. Distribution runs through certified installer networks with direct-to-fleet channels gaining share for large depot projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated platform providers capable of bundling hardware, installation, and energy management under single-accountability contracts. Fleet procurement teams are forcing weaker equipment-only distributors toward exit or acquisition.
For Market Incumbents: Acquire grid interconnection engineering capabilities to defend against specialized power systems consultancies entering from adjacent energy infrastructure markets. Prioritize silicon carbide module qualification programs that lock in thermal performance advantages over IGBT-based competitors. Strengthen long-term service agreement structures with Randstad-based freight operators before regional logistics electrification peaks. For New Entrants and Emerging Players: Launch via heavy-duty depot electrification partnerships targeting megawatt-scale charging systems underserved by current supply. Focus initial penetration on North Brabant technology campuses where workplace charging mandates are expanding fastest under evolving commercial building codes. Differentiate through direct renewable power purchase agreements tied to North Sea offshore wind development. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by multinational energy management conglomerates seeking Dutch market presence ahead of EU Green Deal infrastructure deadlines. Five-to-ten-year viability favors vendors with certified silicon carbide supply chains and ACM payment interoperability compliance already secured. Monitor transformer procurement lead time compression as the inflection signal indicating grid capacity expansion is accelerating faster than distribution network engineering bottlenecks predict.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Module Qualification | Enables 350 kW thermal density that IGBT systems cannot match in Randstad depot deployments. |
| Grid Interconnection Engineering Acquisition | Secures scarce power systems talent essential for medium-voltage utility approvals under ACM oversight. |
| Long-term Service Agreement Structuring | Bundles hardware, installation, and energy management to meet fleet operator single-accountability demands. |
| Direct Renewable PPA Development | Links coastal charging hubs to North Sea offshore wind for carbon intensity differentiation claims. |
| ACM Interoperability Certification Investment | Accelerates software validation cycles for public charging roaming protocol compliance mandates. |
Research Methodology
Document review covered EU F-Gas Regulation filings, ACM grid connection tariff documentation, and Dutch national charging infrastructure framework mandates, complemented by interviews with fleet operations directors, utility interconnection engineers, and charging equipment procurement managers at Randstad logistics operators. Secondary validation drew from distribution network operator capacity allocation disclosures, silicon carbide supply chain trade data, and CE marking compliance registries. Bottom-up installation forecasts triangulated against top-down infrastructure investment projections from national transport electrification programs.
Cross-referencing historical deployment patterns against expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled included charger product type, charging speed classification, end user archetype, and installation environment. CAGRs were derived from infrastructure buildout trajectories mandated by EU Green Deal ICE phase-out deadlines, fleet electrification timelines, and grid capacity expansion schedules. Forecast inputs incorporated transformer procurement lead times and municipal permitting fragmentation indices across Dutch provinces.
Copper and silicon carbide commodity volatility, ACM regulatory interpretation shifts, and distribution network upgrade pacing are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions about infrastructure investment continuity and technology cost curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Copper in Electric Vehicle Market
Electric Vehicle Charging
Global EV Charging Adapter Market
Electric Vehicle Charging
Belgium Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Battery Liquid Cooling Plates for Electric Vehicle Market
Electric Vehicle Charging
EV Charging Networks Market
Electric Vehicle Charging
Electric Vehicle Charging Plugs Market
Electric Vehicle Charging
France Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
EV DC Chargers Market
Electric Vehicle Charging
HVAC Electronically Commutated Motor (ECM) Market
Electric Vehicle Charging
Italy Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
E-Bike Charging Station Market
Electric Vehicle Charging
Electric Vehicle Charging Adapter Market
Electric Vehicle Charging
Electric Vehicle Charging Management Software Market
Electric Vehicle Charging
Two Wheel Electric Vehicle Charger Market
Electric Vehicle Charging
Electric Vehicle Charging Pile Cables Market
Electric Vehicle Charging
North America EV Charging Stations Market