
 Global EV Charging Adapter Market | 2026-2036
Global EV Charging Adapter Market Size, Share, and Industry Trends Forecast 2026-2036
Global EV Charging Adapter Market Analysis
Subscription-based firmware and maintenance bundling is rebalancing how EV charging adapters get monetized beyond hardware margins. Tesla leverages its proprietary connector ecosystem to sustain captive demand across its Supercharger network. ABB anchors industrial-grade DC fast charging adapter production with heavy R&D spending on thermal management. Siemens competes through IEC standard alignment and utility-scale project integration.
An EV charging adapter is an electromechanical interface that bridges incompatible connector geometries and communication protocols between electric vehicles and charging infrastructure, typically incorporating power pins rated up to 350 kW, temperature sensors, and PLC or CAN bus controllers for ISO 15118 handshake compliance. Its primary commercial purpose is to eliminate stranded-asset risk for charging station operators and vehicle owners facing multi-standard fragmentation across regional markets. CCS Combo adapters command the deepest margin pools in DC fast charging deployments where high-current handling justifies premium pricing, while Type 2 hardware dominates volume across European public charging networks due to regulatory harmonization. Wireless charging adapters represent the fastest-growing structural category as inductive pad installations expand for fleet depots seeking automated opportunity charging.
The EU Green Deal and F-Gas Regulation shape adapter demand through interoperability mandates and refrigerant-phaseout timelines affecting thermal system design, while China's GB/T standards and NMPA certification requirements create distinct market access barriers for foreign suppliers. The US NHTSA and EPA influence product specifications through vehicle electrification targets and charging infrastructure funding eligibility rules tied to SAE J1772 and CCS compatibility. Stakeholders must monitor which regulatory jurisdictions move first on mandating bidirectional charging protocols, as this will determine adapter architecture investments for vehicle-to-grid integration.
Market Dynamics
Multi-standard fragmentation across CCS, GB/T, CHAdeMO, and Tesla NACS protocols is forcing adapter manufacturers to engineer modular architectures that bridge incompatible charging ecosystems without hardware obsolescence.
Growth Catalysts
- California's Advanced Clean Trucks regulation:Fleet electrification mandates in the United States are accelerating commercial adapter procurement for heavy-duty depots requiring multi-standard compatibility.
- Heavy-duty logistics electrification:Electric truck deployments across European freight corridors are generating specialized demand for high-amperage DC fast charging adapters rated above 350 kW.
- Copper-nickel alloy thermal cores:Advanced pin metallurgy is extending duty cycles under sustained high-current loads, reducing replacement frequency for station operators.
Market Restraints
- Raw material concentration:Rare earth magnet supply from Chinese processing facilities creates vulnerability in inductive wireless adapter coil production.
- Technical interoperability limits:ISO 15118-20 bidirectional power flow specifications remain incompletely implemented across installed vehicle bases, constraining V2G adapter functionality.
- Regulatory friction from F-Gas timelines:EU refrigerant phaseout schedules are compressing thermal management system redesign windows for liquid-cooled adapter housings.
Strategic Opportunities
- India's PLI scheme for auto components:Domestic manufacturing incentives are opening localized production pathways for GB/T-to-CCS conversion adapters serving export markets.
- Wireless pad integration:Inductive charging convergence with automated guided vehicle systems is creating depot automation opportunities in German industrial zones.
- Subscription firmware bundling:Over-the-air protocol updates are shifting revenue models toward recurring service contracts decoupled from hardware sales cycles.
Industry Challenges
- Power electronics engineering scarcity:Specialized talent for high-frequency magnetics design remains concentrated among semiconductor industry incumbents, constraining adapter OEM hiring pipelines.
- Multi-jurisdiction certification complexity:Simultaneous UL, CE, and CCC approval timelines for a single SKU extend product launch windows by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global EV Charging Adapter Market |
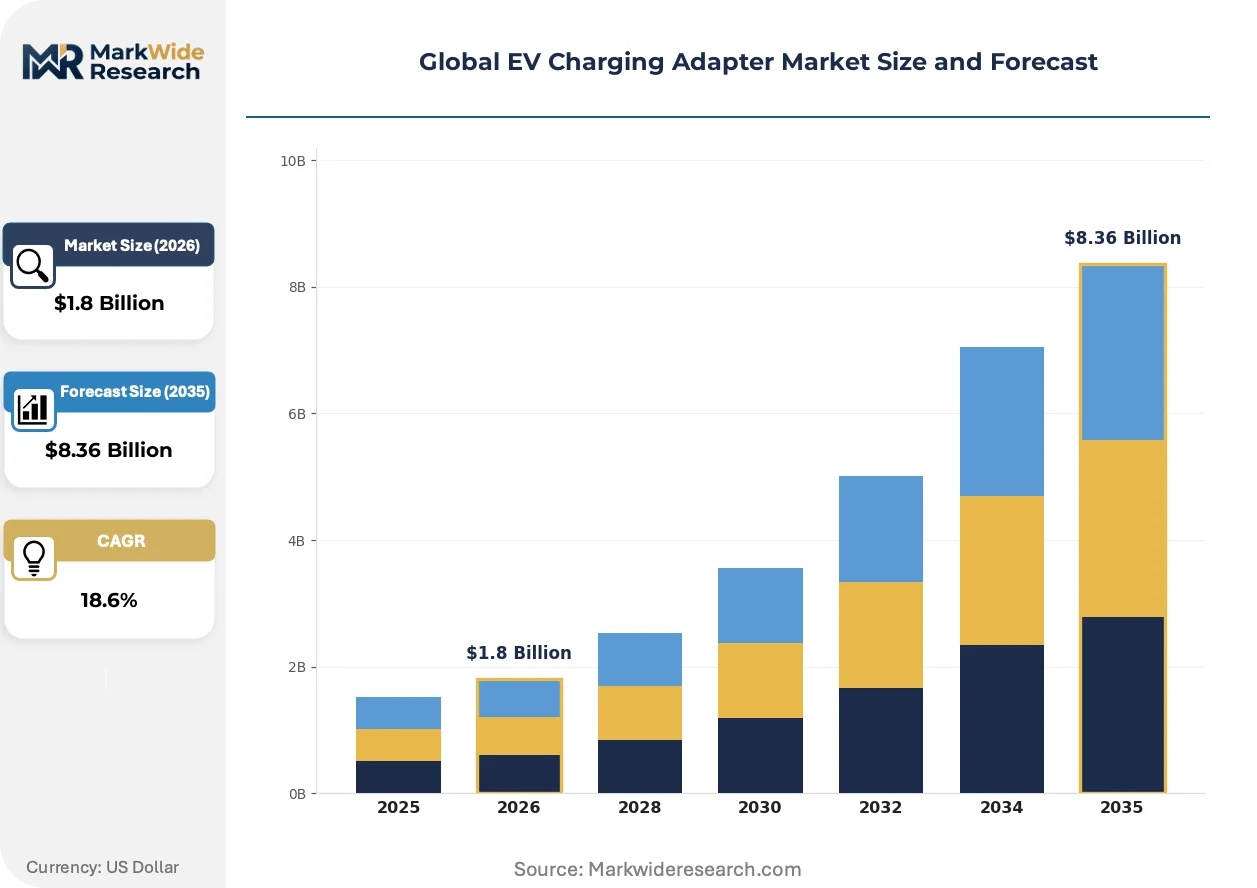
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Type 1, Type 2, CHAdeMO, CCS Combo, Tesla Connector Charging Level: Level 1, Level 2, DC Fast Charging, Wireless Charging End User: Vehicle Manufacturers, Fleet Operators, Public Charging Stations, Homeowners Distribution Channel: Online Retailers, Specialty Stores, Automotive Dealerships, Direct Sales |
| Companies Covered | Tesla, ChargePoint, ABB, Siemens, Schneider Electric, EVBox, Wallbox, Delta Electronics, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global EV Charging Adapter Market Emerging Trajectories
Silicon carbide power semiconductors and liquid-cooled thermal architectures are compressing adapter form factors while elevating sustained power handling, fundamentally altering unit economics for high-speed charging infrastructure.
Silicon carbide MOSFETs are replacing legacy IGBT modules in DC fast charging adapter power conditioning stages. Tier-1 charging hardware manufacturers are adopting these devices for new station builds across Germany and the United States. This transition is overtaking conventional thermal management approaches by enabling passive cooling architectures that eliminate pump and refrigerant subsystems.
The EU F-Gas Regulation is accelerating refrigerant-phaseout timelines for liquid-cooled charging systems. Adapter manufacturers must redesign thermal loops using dielectric fluid or direct-contact cooling to maintain certification eligibility. European public charging networks are responding by specifying adapter housings compatible with next-generation thermal media in procurement tenders.
Fleet operators are unbundling hardware acquisition from maintenance and firmware update obligations. Direct procurement from adapter OEMs is displacing distributor-mediated purchasing for large commercial depots in China and the United States. This restructuring concentrates contract negotiation leverage among buyers operating above 500-vehicle thresholds, compressing margin capture for intermediary channel partners.
Global EV Charging Adapter Market Segmentation
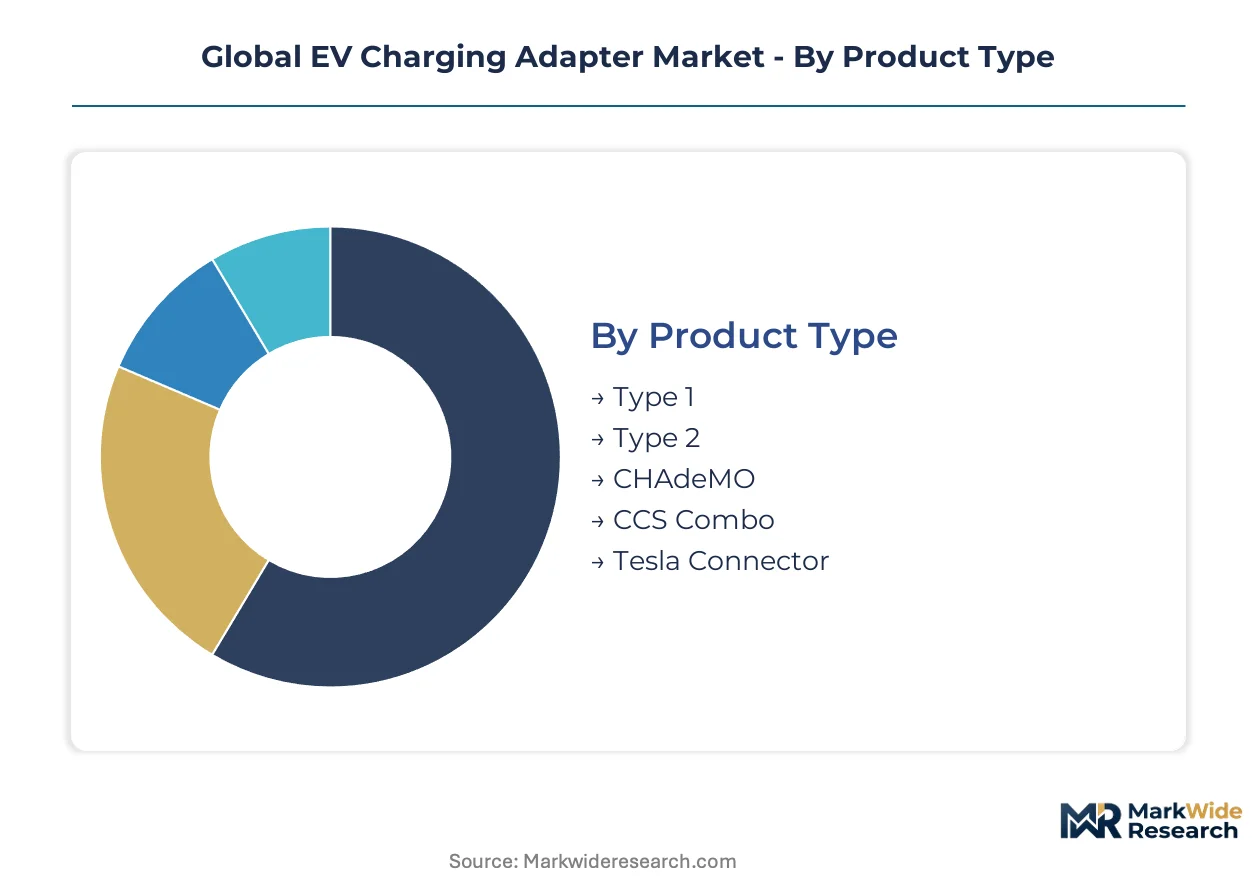
Adapter procurement patterns diverge sharply across buyer types, with fleet operators prioritizing ruggedized DC hardware and homeowners gravitating toward plug-and-play Level 2 solutions. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume scales.
Product Type:
Buyers in this category differentiate by the charging protocol ecosystem their vehicles must access, which determines pin geometry, current ratings, and communication controller requirements.
- CCS Combo:Combines AC Type 2 inlet with two additional DC power pins for high-speed charging up to 350 kW. Demand concentrates across German public charging networks where EU interoperability mandates require multi-standard station compatibility, and fleet operators electrifying heavy-duty corridors need sustained high-current handling.
- CHAdeMO:Features a distinct circular connector with ten pins supporting bidirectional power flow for vehicle-to-grid applications. Japanese automotive OEMs anchor procurement volumes through dedicated fast-charging partnerships, though CCS convergence is compressing new deployment share in European and North American markets.
- Type 1:Single-phase AC connector dominant in earlier Japanese and North American vehicle generations.
- Type 2:Three-phase AC standard mandated across EU public infrastructure, commanding volume through regulatory harmonization.
- Tesla Connector:Proprietary geometry now transitioning toward NACS standardization with third-party licensing expansion.
Volume sits with Type 2 hardware across European deployments; growth tilts toward CCS Combo as DC fast charging infrastructure accelerates in China and the United States.
Charging Level:
Cost tier separates segments here, with hardware price points spanning two orders of magnitude from residential Level 1 units to liquid-cooled DC fast charging systems.
- DC Fast Charging:Delivers 50-350 kW through direct current bypassing onboard converters, requiring active thermal management and high-voltage silicon carbide power conditioning. Fleet depots in California's Central Valley anchor procurement volumes under Advanced Clean Trucks compliance deadlines, with copper-nickel alloy pin metallurgy extending duty cycles under sustained loads.
- Wireless Charging:Inductive pad systems transferring power through magnetic resonance without physical contact. German industrial zones drive pilot deployments where automated guided vehicle integration enables opportunity charging for logistics automation, though rare earth magnet supply concentration creates procurement vulnerability.
- Level 1:Standard 120V residential charging delivering 1-1.4 kW through standard household outlets.
- Level 2:240V AC systems delivering 3-19 kW, dominating residential and workplace installations.
Revenue concentrates in DC Fast Charging deployments; Wireless Charging is gaining share fastest as fleet automation requirements mature.
End User:
Application environment determines durability specifications, with commercial operators demanding IP67 sealing and vibration resistance absent from residential use cases.
- Fleet Operators:Commercial buyers managing 500-plus vehicle deployments who unbundle hardware from maintenance contracts. Procurement concentrates in Chinese and United States logistics corridors where electric truck scaling creates specialized demand for high-amperage adapters rated above 350 kW, with direct OEM relationships displacing distributor channels.
- Public Charging Stations:Network operators requiring multi-standard compatibility to minimize stranded-asset risk. EU Green Deal interoperability mandates drive specification requirements across German, French, and Dutch networks, with ISO 15118-20 bidirectional protocol implementation determining adapter architecture investments.
- Vehicle Manufacturers:OEMs bundling adapters with new vehicle sales or warranty programs.
- Homeowners:Residential buyers prioritizing plug-and-play simplicity and cost minimization.
Contract value peaks with Fleet Operators; deployment velocity runs highest through Public Charging Station networks.
Distribution Channel:
Customer scale and technical sophistication determine channel preference, with large buyers bypassing intermediaries while fragmented residential demand sustains retail layers.
- Direct Sales:Manufacturer-to-buyer relationships dominating procurement above 500-vehicle fleet thresholds. Contract negotiation leverage concentrates among United States and Chinese logistics operators, compressing margin capture for intermediary channel partners while enabling subscription-based firmware bundling.
- Online Retailers:E-commerce platforms capturing fragmented residential and small commercial demand. Specialty technical specifications and certification documentation requirements create friction, though return logistics complexity constrains category expansion for high-value DC hardware.
- Specialty Stores:Electrical supply and EV-focused retail serving contractor and installer segments.
- Automotive Dealerships:OEM-affiliated channels bundling adapters with vehicle purchases.
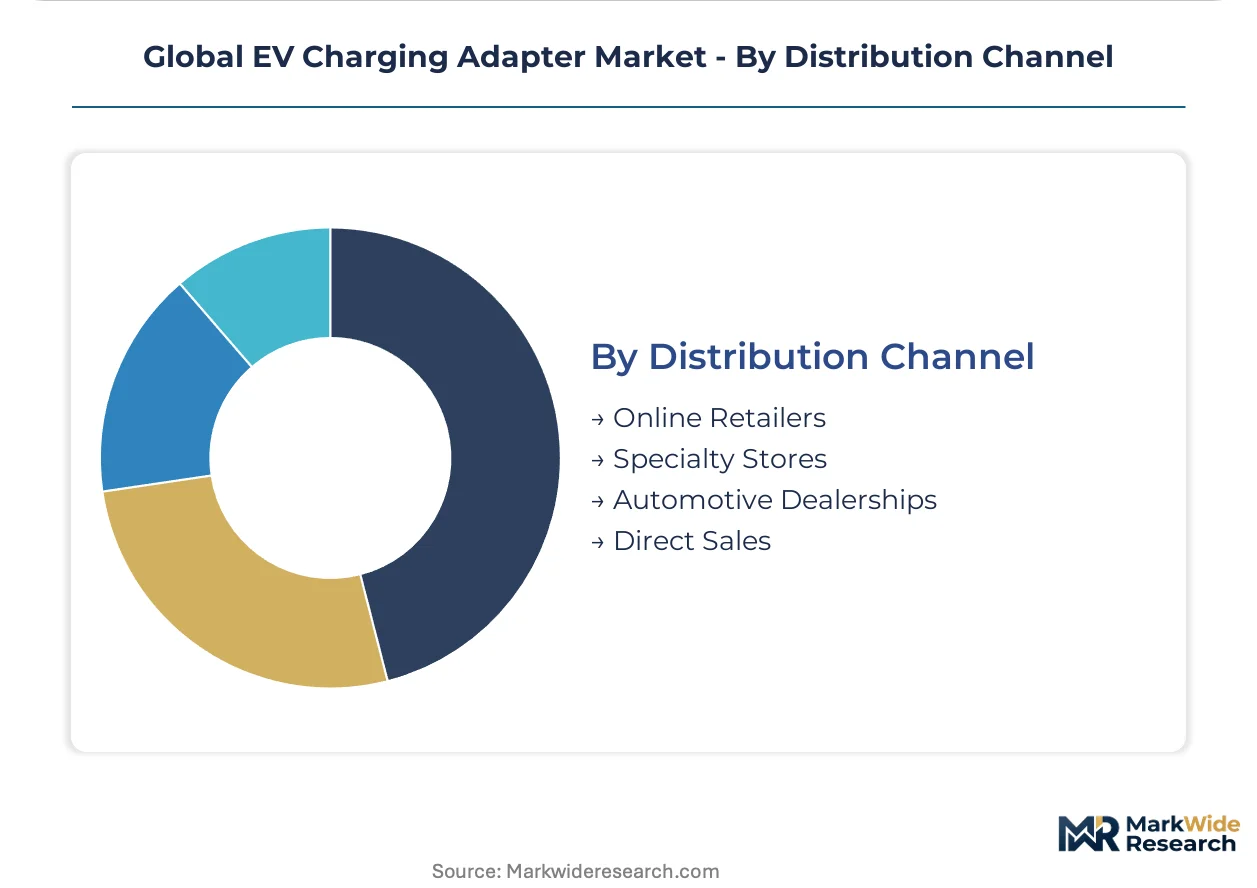
Transaction volume flows through Online Retailers; profit pool depth concentrates in Direct Sales relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Yangshan Deep Water Port anchors Asia-Pacific adapter procurement as Chinese electric truck deployments scale across the Yangtze River Delta logistics corridor. Fleet electrification mandates and charging infrastructure buildouts are concentrating manufacturing and testing activity in specific industrial clusters across four major economies.
United States
California's Central Valley freight corridors generate concentrated demand for high-amperage DC adapters under Advanced Clean Trucks regulation deadlines. The EPA's vehicle electrification targets and NHTSA charging infrastructure funding rules tied to SAE J1772 compatibility shape procurement specifications. Detroit-Warren automotive suppliers are integrating adapter production into existing power electronics manufacturing footprints.
Germany
Ruhr industrial zone logistics operators are unbundling hardware procurement from maintenance contracts for electric truck depots. The EU Green Deal interoperability mandates and F-Gas Regulation refrigerant-phaseout timelines drive thermal system redesign requirements. Stuttgart engineering clusters concentrate silicon carbide power semiconductor integration for next-generation DC fast charging adapters.
China
Shenzhen's electric vehicle manufacturing ecosystem generates captive demand for GB/T-to-CCS conversion adapters serving export markets. NMPA certification requirements and MIIT GB standards create distinct market access barriers for foreign suppliers. Ningbo-Zhoushan port logistics automation is piloting wireless inductive pad integration for automated guided vehicle charging systems.
Japan
CHAdeMO protocol heritage sustains domestic adapter demand through automotive OEM fast-charging partnerships. METI industrial policy and JIS standards alignment influence product specification requirements for bidirectional vehicle-to-grid functionality. Nagoya manufacturing clusters are engineering modular architectures that bridge CHAdeMO and CCS convergence pressures.
India
Maharashtra automotive corridors are localizing production under the PLI scheme for auto components to serve regional export demand. BIS certification timelines and CEA grid integration standards shape adapter architecture investments. Tamil Nadu industrial zones are concentrating contract manufacturing capacity for copper-nickel alloy thermal core fabrication.
Global EV Charging Adapter Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the adapter value chain. Integrated charging station manufacturers with captive adapter production face competition from specialized electromechanical component suppliers. Three archetypes dominate: industrial automation conglomerates with power electronics heritage, automotive-tier suppliers leveraging vehicle-side connector expertise, and pure-play charging hardware specialists. Competitive moves concentrate on silicon carbide technology licensing and direct sales channel expansion for fleet operator accounts.
Among North American technology-integrated operators, Tesla and ChargePoint occupy positions bridging proprietary connector ecosystems with third-party interoperability demands. ABB anchors European industrial-grade production with heavy capital deployment in thermal management engineering. These three exemplify divergent strategic postures: captive network control, platform-agnostic hardware scale, and utility-scale project integration respectively.
| Leading Market Players |
|---|
| Tesla |
| ChargePoint |
| ABB |
| Siemens |
| Schneider Electric |
| EVBox |
| Wallbox |
| Delta Electronics |
| Eaton |
| Others |
Supply Flow & Price Mechanics
Power electronics engineering talent concentrated in Stuttgart and Silicon Valley feeds labor-cost differentials that widen pricing-tier spreads between premium silicon carbide-enabled adapters and economy-grade hardware.
Pricing Analysis
Throughput-based pricing anchors adapter monetization, with fleet operators paying premiums for guaranteed uptime and firmware update entitlements. Three-tier pricing structure across premium, standard, and economy levels separates liquid-cooled DC fast charging systems from passive-cooled residential units and unbranded import alternatives. Cost compression in economy tiers is intensifying because Chinese contract manufacturers are scaling copper-nickel alloy thermal core production. Fleet operators operating above 500-vehicle thresholds exhibit lowest price sensitivity due to unbundled procurement leverage, while residential homeowners drive volume through online retail channels with high elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from United States and Chinese fleet operators, displacing distributor-mediated purchasing for commercial depots. Manufacturing concentrates in China, Germany, and the United States, with Ningbo-Zhoushan port logistics automation and Ruhr industrial zone engineering clusters anchoring regional production gravity. Rare earth magnet processing draws from Chinese facilities, silicon carbide wafers rest on Taiwanese and German supply bases, and copper-nickel alloy pin metallurgy hinges on Indian Tamil Nadu fabrication capacity. Single-source vulnerability in rare earth magnet coil production for wireless adapters creates procurement exposure. Distribution runs through direct sales relationships for fleet accounts and online retailers for fragmented residential demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized power electronics engineering scarcity props adapter pricing, as semiconductor industry incumbents concentrate high-frequency magnetics design talent that adapter OEMs cannot readily replicate.
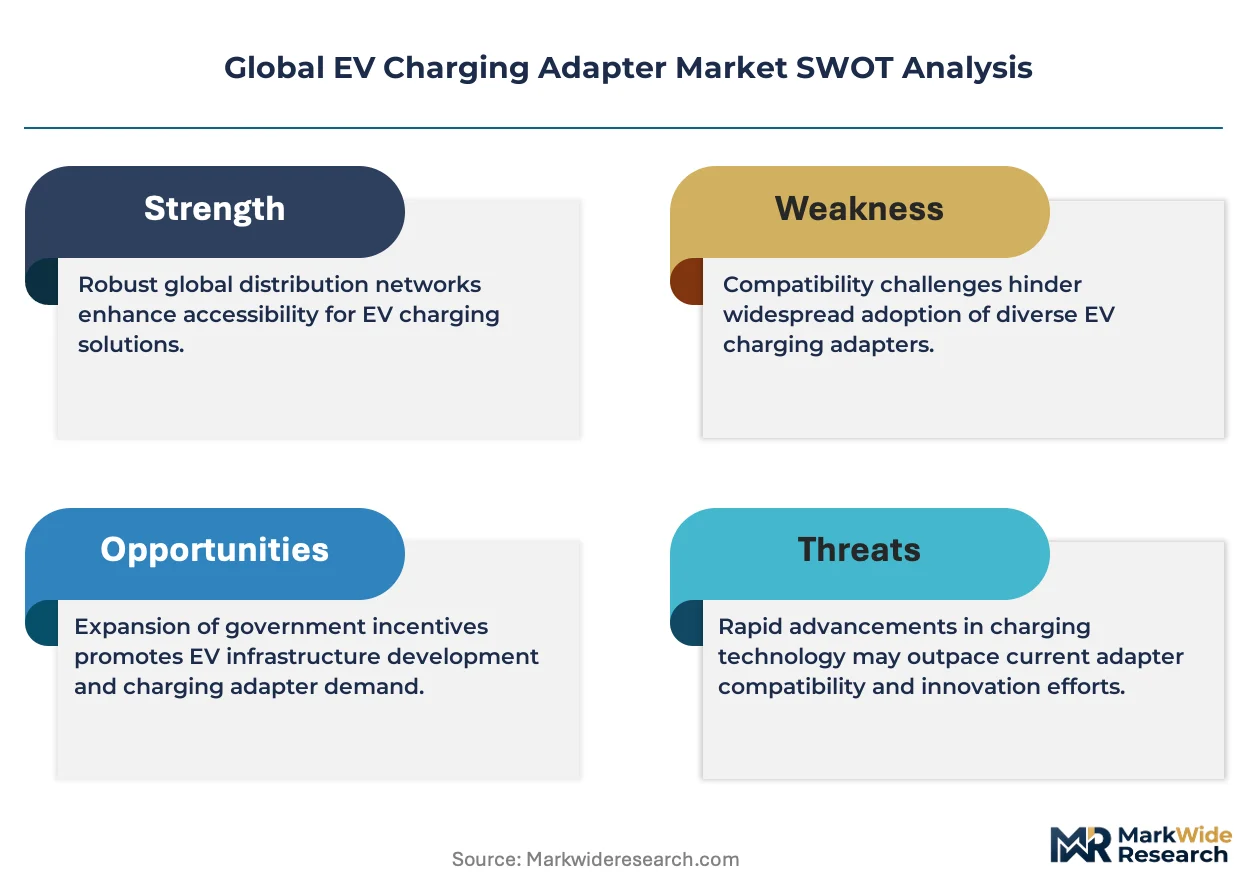
For Market Incumbents: Anticipate margin compression from Chinese contract manufacturers scaling thermal core production under India's PLI scheme by securing backward integration into silicon carbide power semiconductor sourcing. Defend positioning through captive firmware subscription bundling that locks fleet operator switching costs, while accelerating CE-UL-CCC simultaneous certification investments to compress new entrant launch windows. For New Entrants and Emerging Players: California's Advanced Clean Trucks regulation opens a window for specialized high-amperage DC adapter penetration in Central Valley freight corridors before incumbent channel relationships solidify. Target wireless charging pad integration for German industrial zone automated guided vehicle systems where rare earth supply constraints have left established players exposed. Pursue direct sales relationships with 500-plus vehicle fleet operators as the primary go-to-market angle, bypassing distributor margin capture entirely. For Investors and Strategic Acquirers: Re-rating potential sits with pure-play charging hardware specialists given silicon carbide technology licensing inflections and fleet operator direct procurement concentration. Five-to-ten year viability favors adapter OEMs with captive thermal management engineering and multi-jurisdiction certification capabilities. Monitor which regulatory jurisdictions move first on mandating bidirectional ISO 15118-20 protocols as the signal for vehicle-to-grid adapter architecture investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Technology Licensing | Enables passive cooling architectures that eliminate pump and refrigerant subsystems for next-generation DC fast charging stations. |
| Fleet Operator Direct Sales Expansion | Concentrates contract negotiation leverage among United States and Chinese logistics operators above 500-vehicle thresholds. |
| Multi-Jurisdiction Certification Investment | Compresses product launch windows by 8-14 months through simultaneous UL, CE, and CCC approval pathways. |
| Wireless Charging Pad Integration | Captures German industrial zone automation demand where automated guided vehicle opportunity charging requirements mature. |
| Subscription Firmware Bundling | Shifts revenue models toward recurring service contracts decoupled from hardware sales cycles for fleet depots. |
Methodological Framework
Trade association filings, customs and import-export databases, and SEC 10-K disclosures formed the secondary backbone, supplemented by primary interviews with charging station procurement managers, Tier 1 supplier power electronics engineers, fleet operator maintenance directors, and thermal management R&D leads. Bottom-up unit shipment modeling and top-down infrastructure spending allocation were triangulated against regulatory mandate timelines to validate market sizing across the projection horizon.
Historical trendline analysis of adapter deployment patterns against electric truck production scaling and public charging network buildout rates established baseline growth trajectories. Segmentation dimensions modeled include charging protocol ecosystem, power level tier, end-user application environment, and regional regulatory cluster. CAGRs were derived from infrastructure investment elasticity coefficients and fleet electrification mandate compliance deadlines, with silicon carbide adoption curves and wireless charging pad installation rates serving as industry-specific forecast inputs.
Caveats apply where rare earth magnet supply disruptions, refrigerant-phaseout timeline accelerations under EU F-Gas Regulation, or premature NACS standardization convergence could materially shift the outlook. Forecasts reflect documented assumptions regarding interoperability mandate implementation pacing and fleet operator procurement unbundling velocity. Periodic stress-testing of base assumptions against charging infrastructure funding allocation and electric truck deployment actuals is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Two Wheel Electric Vehicle Charger Market
Electric Vehicle Charging
Multi-Brand Universal Home Charging Pile Market
Electric Vehicle Charging
South America Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
EV Charging Station Market
Electric Vehicle Charging
Solar Carport Charging Station Market
Electric Vehicle Charging
Electric Vehicle Charging Management Software Market
Electric Vehicle Charging
Electric Vehicle Fast and Rapid Charger Market
Electric Vehicle Charging
Asia Pacific Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Australia Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Second Life Electric Vehicle Battery Market
Electric Vehicle Charging
EV Charge Controller Market
Electric Vehicle Charging
APAC Electric Vehicle Charging Station Market
Electric Vehicle Charging
High-Thermal-Conductivity Gap-Fill Adhesives for EV Battery Cooling Plates Market
Electric Vehicle Charging
Sweden Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
United Kingdom Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Connector Market