
 UAE Microwave Ovens Market | 2026-2036
UAE Microwave Ovens Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Microwave Ovens Market Analytics
Aftermarket service revenue is rewriting profit expectations for appliance distributors in the Emirates. Samsung Electronics leverages its Gulf-wide service infrastructure to capture extended warranty pools. LG Electronics anchors its position through dedicated UAE technical centers that reduce repair turnaround times. Panasonic Corporation differentiates by controlling spare parts availability across Abu Dhabi and Sharjah distribution nodes.
A microwave oven is an electric appliance that generates electromagnetic radiation at approximately 2.45 GHz to excite water molecules and produce thermal energy for cooking, reheating, or defrosting food substrates. The primary commercial purpose centers on rapid thermal processing in settings where speed and space efficiency outweigh conventional convection methods. Built-in units command premium positioning in high-rise residential developments across Dubai Marina and Downtown Dubai, while countertop models dominate volume in Saudi-export channels and Sharjah retail warehouses. Smart technology penetration remains nascent but gathers momentum as Wi-Fi-enabled inventory management appeals to hospitality procurement teams seeking remote diagnostics.
MOHAP enforces electromagnetic compatibility and food-contact material safety standards that shape import clearance timelines for manufacturers seeking UAE market access. The Emirates Authority for Standardization and Metrology (ESMA) administers energy efficiency labeling requirements that increasingly filter lower-tier imports from regional trading routes. Stakeholders must track how Dubai Municipality building codes for new commercial kitchen installations evolve alongside sustainability mandates, as these specifications directly determine product qualification thresholds for project-based volume sales.
Market Dynamics
Hospitality procurement teams in Dubai are compressing replacement cycles as cloud kitchen deployments multiply across the emirate's food service corridor. This operational tempo shift is restructuring volume allocation between countertop and built-in configurations.
Growth Catalysts
- MOHAP Electromagnetic Standards:Mandatory emission limits and energy labeling requirements are filtering lower-tier imports, creating qualification barriers that favor established distributors with compliance infrastructure.
- Cloud Kitchen Proliferation:Dubai's commercial food services corridor is driving accelerated equipment turnover as centralized cooking facilities demand space-optimized thermal processing solutions.
- High-Rise Residential Development:Built-in microwave positioning commands premium placement in Dubai Marina and Downtown Dubai towers, anchoring project-based specification pipelines.
Market Restraints
- Import Concentration Risk:Heavy reliance on Saudi-export channels and Sharjah retail warehouses creates vulnerability to regional trade route disruptions and customs clearance volatility.
- Copper and Magnetron Cost Pressure:Input material price fluctuations for core components compress margin structures for distributors without captive supply arrangements.
- Convection Oven Substitution:Full-service hospitality kitchens in Abu Dhabi luxury hotels retain preference for conventional thermal methods where speed requirements allow.
Strategic Opportunities
- Sharjah Warehouse Modernization:Underpenetrated distribution nodes in the northern emirate present whitespace for technical service center deployment and spare parts localization.
- Wi-Fi Inventory Convergence:Remote diagnostics and connected kitchen management systems are converging with microwave hardware to create procurement differentiation for hospitality technology buyers.
- ESMA Energy Label Tier Advancement:Stricter efficiency thresholds scheduled under Emirates Authority for Standardization and Metrology protocols will reward early compliance investment with preferential retail placement.
Industry Challenges
- Electromagnetic Compatibility Certification:Extended MOHAP testing timelines for new product introductions delay market entry by 8-14 weeks, compressing launch windows against competitive cycles.
- Legacy Kitchen Integration:Retrofit installations in established Dubai commercial properties face spatial constraints and electrical infrastructure mismatches that complicate specification sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Microwave Ovens Market |
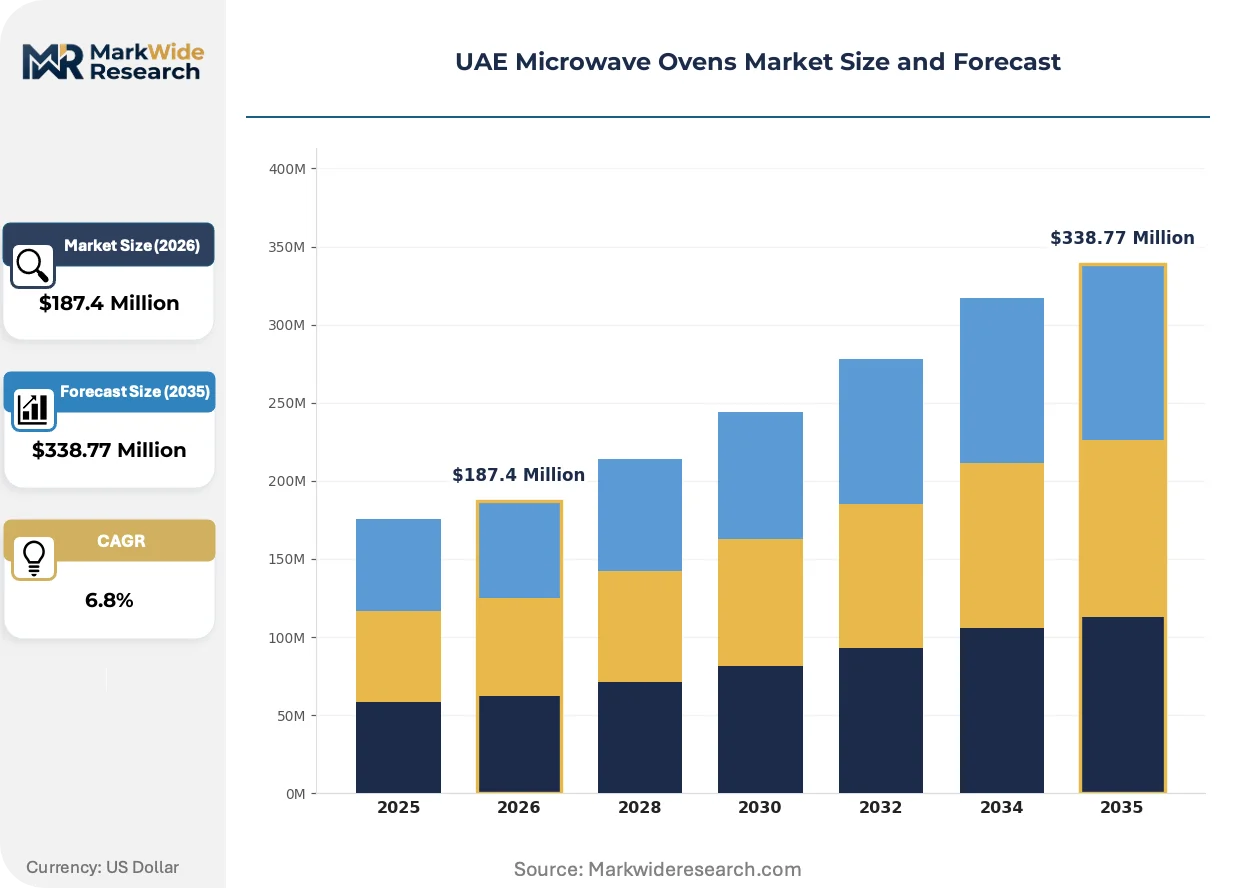
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Built-in, Over-the-range, Convection Technology: Conventional, Inverter, Grill, Smart End User: Residential, Commercial, Hospitality, Food Services Distribution Channel: Online, Offline, Supermarkets, Specialty Stores |
| Companies Covered | Samsung Electronics, LG Electronics, Panasonic Corporation, AB Electrolux, Whirlpool Corporation, Sharp Corporation, Hoover Limited, Haier Group, Midea Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Microwave Ovens Market Evolving Landscape
Smart connectivity is penetrating commercial kitchen procurement specifications faster than residential adoption curves projected. This connectivity pivot is compressing the traditional equipment replacement timeline and redefining after-sales revenue models.
Inverter power delivery technology is collapsing the performance gap between compact countertop units and full-size built-in configurations. Hospitality procurement teams in Dubai's cloud kitchen clusters are adopting inverter-equipped models at twice the rate of conventional magnetron designs. The technology is collapsing the historical segmentation between premium built-in and economy countertop categories, forcing manufacturers to reposition entire product lines.
MOHAP's electromagnetic compatibility enforcement protocols are extending import clearance timelines for manufacturers without pre-established UAE testing partnerships. The industrial consequence is a consolidation of distribution relationships around established service infrastructure holders. Small-format commercial operators in Sharjah are experiencing the longest delays, driving them toward distributors with dedicated compliance teams.
Buying committees in Abu Dhabi hospitality groups are unbundling equipment procurement from after-sales service contracts, creating separate vendor selection processes. Traditional full-service distributors are losing exclusivity as specialized service providers capture maintenance revenue pools. This pattern is most visible in Dubai's hotel management company procurement offices, where technical service response time now outweighs equipment brand preference in vendor scorecards.
UAE Microwave Ovens Market Segmentation
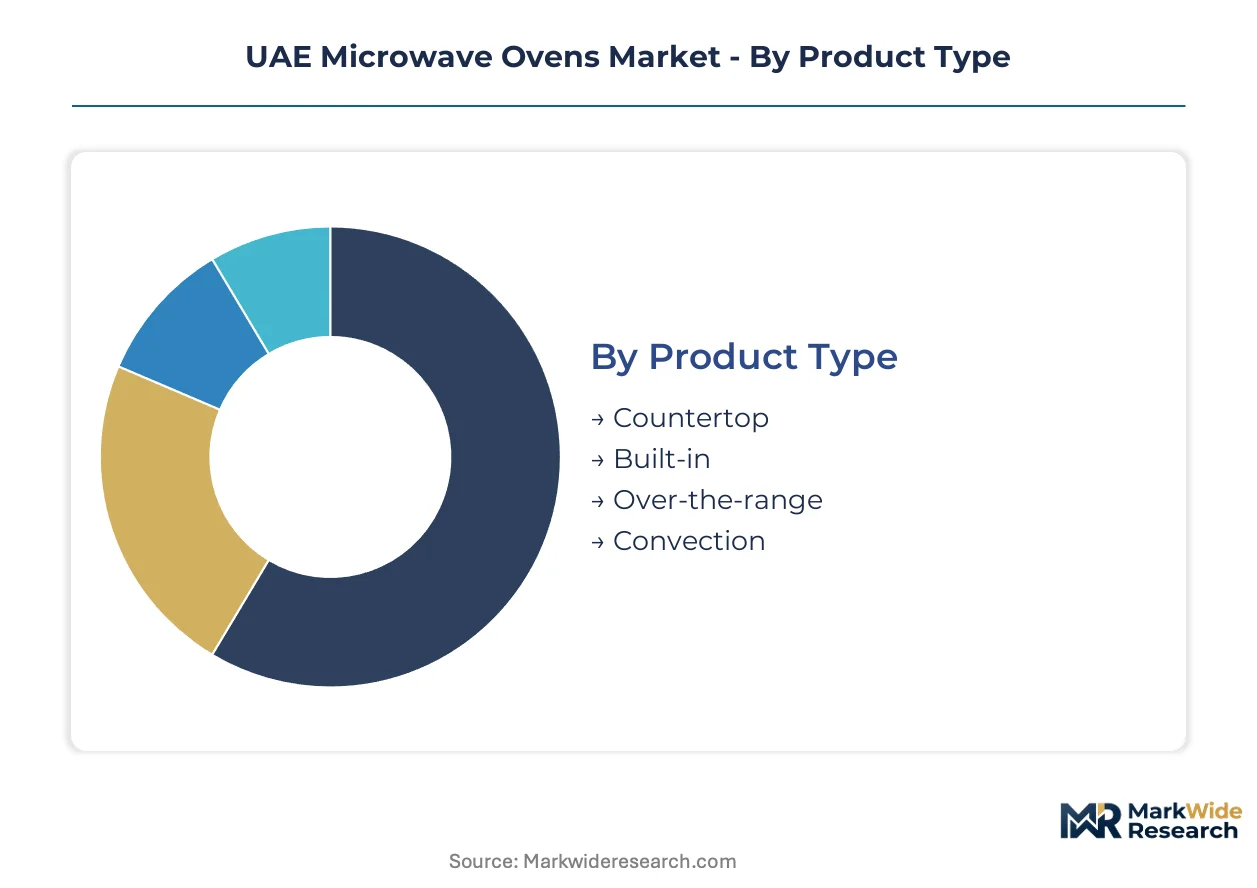
Segmentation patterns in the UAE microwave market reveal divergent service intensity requirements. After-sales infrastructure investments cluster around segments with compressed replacement cycles and remote diagnostic potential.
Product Type:
Service attach rates vary dramatically across installation formats, with built-in configurations demanding specialized technical labor.
- Countertop:Portable units with plug-and-play electrical requirements dominate Sharjah retail warehouse volumes. Demand concentrates in Saudi-export channels where price sensitivity overrides specification complexity. Service revenue per unit remains minimal due to disposable replacement economics.
- Built-in:Cabinet-integrated designs with custom trim kits command project-based specification pipelines in Dubai Marina and Downtown Dubai high-rises. Hospitality procurement teams prioritize these units for space optimization in cloud kitchen deployments, driving extended warranty attachment rates above category averages.
- Over-the-range:Ventilation-combined units face constrained adoption due to Dubai Municipality commercial kitchen code restrictions on recirculating hood systems.
- Convection:Hybrid thermal processing units with fan-assisted heat distribution appeal to Abu Dhabi luxury hotel kitchens seeking menu versatility without equipment redundancy.
Built-in holds the largest share; momentum sits with convection as kitchen footprints shrink.
Technology:
Margin structures compress toward conventional magnetron designs while inverter and smart platforms capture premium positioning.
- Conventional:Fixed-power magnetron assemblies with transformer-based voltage regulation anchor volume in economy distribution tiers. Sharjah small-format operators default to this technology due to lower upfront capital requirements and minimal technical training needs.
- Inverter:Variable power delivery systems using IGBT semiconductor control enable precise temperature modulation and reduced cooking time variance. Dubai cloud kitchen clusters are adopting these units at accelerated rates as procurement teams prioritize throughput consistency over equipment cost.
- Grill:Supplementary quartz or sheath heater elements add browning capability without full convection system complexity, occupying a mid-tier specification niche.
- Smart:Wi-Fi-enabled units with API-accessible diagnostic protocols remain nascent in residential channels but gain traction in hospitality procurement specifications seeking remote inventory management integration.
Conventional technology retains volume leadership; inverter platforms are climbing the fastest as cloud kitchen density increases.
End User:
Procurement authority fragmentation creates distinct vendor selection criteria across buyer categories.
- Residential:Individual household purchases through retail channels prioritize countertop convenience and aesthetic integration with kitchen cabinetry. Dubai high-rise developers increasingly pre-specify built-in units as standard apartment fittings, shifting volume toward project-based sales.
- Commercial:Non-hospitality business installations including corporate cafeterias and institutional food service operations demand durability specifications and rapid technical response guarantees.
- Hospitality:Hotel group procurement offices in Dubai and Abu Dhabi unbundle equipment from service contracts, creating separate vendor evaluation tracks where technical response time outweighs brand preference.
- Food Services:Centralized cooking facilities and delivery-only kitchen operations prioritize space-optimized thermal processing with minimal ventilation requirements, driving specification convergence toward compact high-output designs.
Hospitality holds the largest share; food services is gaining share fastest as cloud kitchen proliferation accelerates.
Distribution Channel:
Channel economics reflect divergent fulfillment cost structures and customer acquisition patterns.
- Online:E-commerce platforms with warehouse fulfillment models capture residential replacement demand and specification research phases, though commercial procurement maintains offline final purchase authority.
- Offline:Physical retail and trade counter networks retain dominance in commercial and hospitality segments where installation coordination and immediate availability determine vendor selection.
- Supermarkets:Mass merchandisers with household goods focus concentrate countertop unit volumes in price-sensitive consumer segments.
- Specialty Stores:Kitchen appliance showrooms with project consultation capabilities anchor built-in specification pipelines and developer relationship management.
Offline channels hold the largest share; online platforms show the steepest expansion trajectory as procurement research digitizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across UAE emirates. Dubai buyers prioritize specification compliance over unit cost, while Sharjah and northern emirates exhibit pronounced price sensitivity that channels volume toward economy-tier distribution.
Dubai
Cloud kitchen proliferation along Sheikh Zayed Road corridor is accelerating equipment replacement cycles. Dubai Municipality building codes for commercial kitchen installations mandate specific ventilation and electrical standards that filter product qualification. Downtown Dubai and Dubai Marina high-rise developments anchor built-in microwave specification pipelines for premium residential projects.
Abu Dhabi
Luxury hospitality procurement in Saadiyat Island and Yas Island developments favors convection-hybrid configurations for menu versatility. MOHAP electromagnetic compatibility enforcement extends clearance timelines for new market entrants without established UAE testing partnerships. The emirate's hotel management companies are unbundling equipment procurement from service contracts, elevating technical response time in vendor selection.
Sharjah
Small-format commercial operators concentrate in industrial zones where minimal ventilation requirements drive compact high-output microwave adoption. ESMA energy efficiency labeling requirements increasingly filter lower-tier imports from Saudi-export channels. The emirate's retail warehouse nodes remain underpenetrated for technical service infrastructure, creating whitespace for spare parts localization investments.
Northern Emirates
Ras Al Khaimah and Fujairah hospitality developments are expanding kitchen capacity as tourism infrastructure scales. Federal MOHAP appliance safety standards apply uniformly across all emirates, though enforcement bandwidth varies by municipal resources. These markets rely heavily on Sharjah distribution nodes, amplifying vulnerability to regional trade route disruptions.
UAE Microwave Ovens Market Competitive Landscape
Capability concentration sits with full-service distributors possessing compliance infrastructure and technical service networks; scale advantage sits with multinational electronics conglomerates with Gulf-wide logistics footprints. The market exhibits tiered structure with premium built-in specifications, mid-tier inverter platforms, and economy countertop volumes. Three archetypes dominate: integrated service-infrastructure holders, component technology licensors, and volume-driven retail distributors. Competitive moves center on extended warranty pool capture and spare parts localization across distribution nodes.
Within the service-infrastructure tier, Samsung Electronics leverages Gulf-wide technical networks to anchor aftermarket revenue pools. LG Electronics occupies a parallel position through dedicated UAE technical centers that compress repair turnaround times. Panasonic Corporation exemplifies the parts-control archetype by managing spare parts availability across Abu Dhabi and Sharjah distribution nodes.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Panasonic Corporation |
| AB Electrolux |
| Whirlpool Corporation |
| Sharp Corporation |
| Hoover Limited |
| Haier Group |
| Midea Group |
| Others |
Value Network & Pricing Analysis
Overcapacity in Sharjah retail warehouse nodes compresses distributor margins while simultaneously accelerating price competition in Saudi-export channels. This utilization imbalance rewards established service-infrastructure holders with pricing power in built-in specifications, while forcing volume-driven players toward commodity positioning in countertop tiers.
Pricing Analysis
After-sales revenue pools from extended warranty contracts and spare parts availability drive lifetime value differentiation across distributor tiers. Pricing stratifies across premium built-in, mid-tier inverter, and economy countertop levels, with ESMA energy label tier advancement and MOHAP compliance certification serving as primary price differentiation drivers. Cost compression in magnetron and copper inputs is intensifying margin pressure on conventional technology tiers. Sharjah small-format operators exhibit highest price sensitivity, while Dubai hospitality procurement teams prioritize technical response guarantees over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with China-based EMS providers and Southeast Asian assembly operations serving Gulf distribution nodes. Magnetron assemblies draw from Chinese and South Korean component suppliers, while IGBT semiconductor control modules for inverter platforms source from Taiwan and Japan. Single-source vulnerability in magnetron supply creates exposure to regional trade route disruptions through Sharjah warehouse nodes. Distribution runs through Saudi-export channels for economy tiers and direct project specification pipelines for built-in configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. MOHAP electromagnetic compatibility certification timelines create switching costs that lock procurement relationships around established compliance infrastructure.
For Market Incumbents: Insulate specification pipelines by deepening spare parts localization across Abu Dhabi and Sharjah distribution nodes. Capture extended warranty pools through dedicated UAE technical centers that compress repair turnaround times below competitor thresholds. Vertical integration into inverter IGBT sourcing reduces exposure to Taiwan semiconductor supply volatility.
For New Entrants and Emerging Players: Establish a beachhead in Sharjah warehouse technical service whitespace where underpenetrated distribution nodes lack rapid response capabilities. Target cloud kitchen procurement clusters in Dubai's Sheikh Zayed Road corridor with inverter-equipped compact units emphasizing throughput consistency. Lead with MOHAP pre-certification investment to compress import clearance timelines against established distributor benchmarks.
For Investors and Strategic Acquirers: Long-term, this sits as a service-infrastructure play because aftermarket revenue pools increasingly outweigh hardware margin capture in distributor valuations. Acquisition targets should display dense UAE technical center footprints and established ESMA energy label tier positioning. Monitor Dubai Municipality building code evolution for commercial kitchen ventilation standards as inflection signal for built-in specification demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Spare Parts Localization | Reduces repair turnaround times for Dubai hospitality procurement scorecards. |
| MOHAP Pre-Certification Investment | Compresses import clearance timelines against competitive launch windows. |
| Inverter Platform Expansion | Captures cloud kitchen density growth in Sheikh Zayed Road corridor. |
| Extended Warranty Pool Capture | Locks recurring revenue from Abu Dhabi luxury hotel management companies. |
| Sharjah Technical Center Deployment | Addresses service infrastructure whitespace in northern emirate industrial zones. |
Research Methodology
Operator-level perspectives from hospitality procurement directors, commercial kitchen equipment distributors, MOHAP compliance officers, and Sharjah warehouse logistics managers anchored the qualitative base. Primary interview intelligence combined with secondary validation from ESMA energy labeling databases, Dubai Municipality building code filings, and customs/trade flow records through Saudi-export channels. Bottom-up channel volume estimates triangulated against top-down emirate-level appliance import data.
Scenario-bracketing around MOHAP enforcement intensity and cloud kitchen deployment velocity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product installation format, inverter versus conventional technology, end-user procurement authority, and distribution channel economics. CAGRs derived from equipment replacement cycle compression rates and hospitality capacity expansion pipelines, with inverter adoption curves and Wi-Fi connectivity penetration serving as technology-specific forecast inputs.
Stress conditions across copper and magnetron input pricing, regional trade route disruption probability, and MOHAP clearance timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding ESMA energy label tier advancement schedules and Dubai Municipality commercial kitchen code evolution. Quarterly review of cloud kitchen licensing data and hospitality project pipeline announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Household Side by Side Refrigerator Market
Appliances
North America Compact Dishwasher Market
Appliances
Global Vended Laundry Equipment Market
Appliances
APAC White Goods Market
Appliances
Global Electric Water Heaters Market
Appliances
Hairdryer Market
Appliances
Egypt Dishwashers Market
Appliances
Europe Household Electric Grills Market
Appliances
Personal Care Appliances Market
Appliances
US Washing Machine Parts Market
Appliances
Tumble Dryer Market
Appliances
Conveyor Dishwasher Market
Appliances
North America Personal Care Appliances Market
Appliances
United States Electronics and Appliance Stores Market
Appliances
Electric Iron Market
Appliances
GCC Dishwashers Market