
 UAE Dishwasher Market | 2026-2036
UAE Dishwasher Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Dishwasher Market Analytics
Asset-light leasing and project finance for fit-out contracts is fragmenting the competitive landscape in the UAE dishwasher market. Robert Bosch GmbH leverages its German engineering heritage to anchor premium residential channels across Dubai's master-planned communities. Samsung Electronics Co., Ltd. competes aggressively on smart connectivity features that appeal to tech-forward hospitality operators. Whirlpool Corporation sustains broad distribution through wholesale partnerships serving mid-market food service clients.
A dishwasher is an electromechanical appliance engineered to clean dishware, utensils, and cookware through automated spraying of heated water combined with detergent, typically operating at wash temperatures between 45°C and 75°C and incorporating filtration, drying, and rinse-aid systems for commercial and domestic sanitation compliance. Built-in installations dominate value pools in the UAE, as developers specify integrated kitchen packages for luxury apartments and villas. Energy-efficient technology is gaining fastest traction, driven by ESMA labeling requirements and rising electricity tariffs that penalize conventional models. Smart technology occupies a niche but growing position among hospitality chains pursuing centralized fleet management of kitchen equipment.
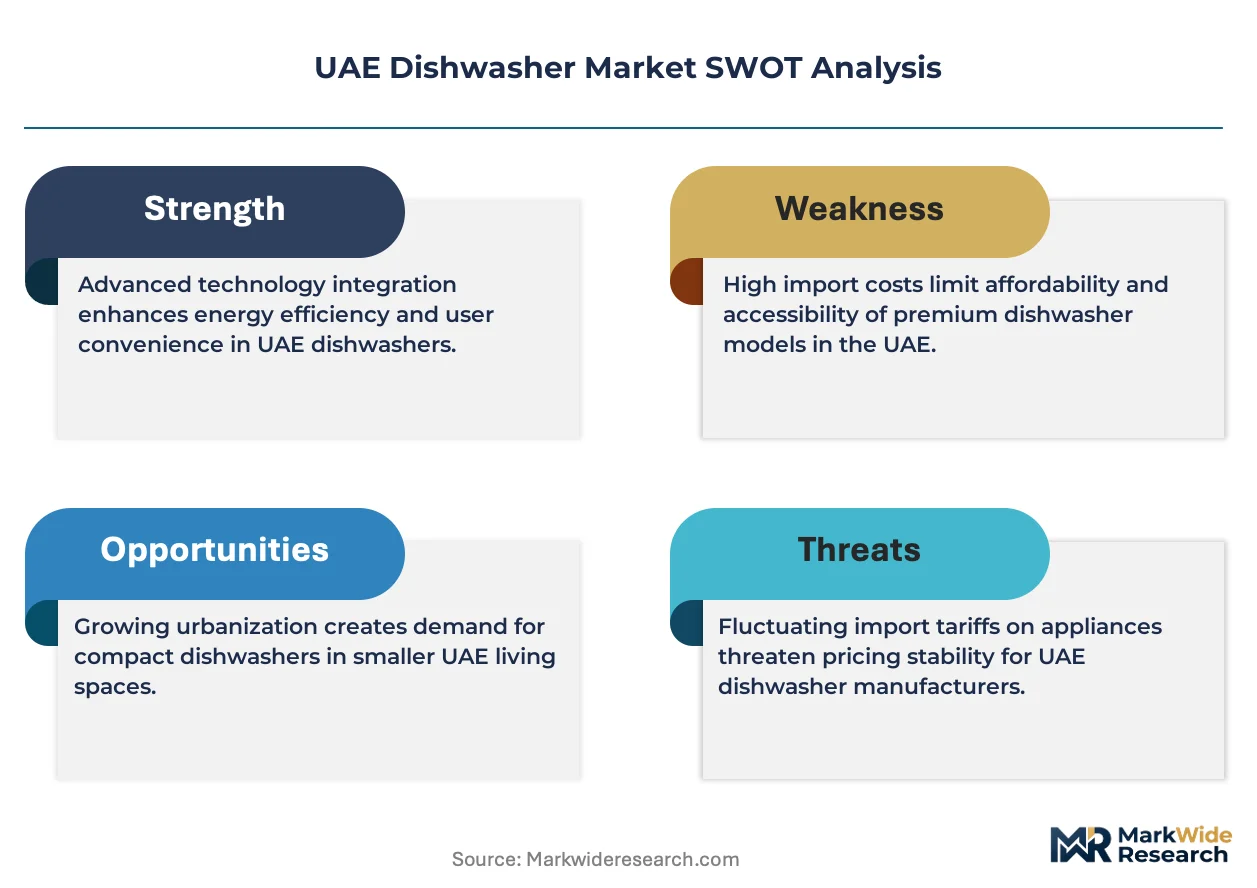
ESMA water-efficiency mandates and the UAE's broader net-zero commitments are tightening product standards and restricting market access for non-compliant imports. MOHAP food safety protocols for commercial kitchens indirectly shape dishwasher specifications by requiring validated sanitation cycles. Dubai Municipality building codes for new developments increasingly prescribe energy-efficient appliances as a condition of construction approval. Stakeholders must monitor how federal efficiency benchmarks evolve alongside emirate-level green building certifications to anticipate which product configurations will retain market access.
Market Dynamics
ESMA water-efficiency mandates are compressing product lifecycles and forcing manufacturers to redesign thermal systems around heat-pump technology, fundamentally altering how suppliers compete for construction-specification contracts in Dubai and Abu Dhabi.
Growth Catalysts
- Net-zero building codes:Dubai Municipality now mandates energy-efficient appliance specifications for new luxury residential developments, accelerating built-in dishwasher procurement cycles.
- Heat-pump drying systems:This technology reduces per-cycle electricity consumption by recapturing waste heat, aligning with ESMA labeling thresholds that favor A+++ rated models.
- Premium hospitality expansion:Food service operators in Dubai's hotel sector are replacing conventional under-counter units with validated sanitation systems that meet MOHAP food safety protocols.
Market Restraints
- Stainless steel input volatility:Fluctuations in nickel and chromium prices squeeze margin structures for mid-market manufacturers dependent on imported sheet metal.
- Import concentration risk:European and East Asian suppliers control over 80% of heat-pump compressor supply, creating vulnerability to shipping disruptions through the Strait of Hormuz.
- Water hardness calibration limits:Existing ion-exchange systems struggle with the UAE's variable groundwater mineral content, requiring costly regional adaptation of standard European designs.
Strategic Opportunities
- Ras Al Khaimah hospitality pipeline:New resort developments outside Dubai-Abu Dhabi cores present first-mover advantages for suppliers establishing service infrastructure.
- IoT-enabled predictive maintenance:Convergence of sensor telemetry with cloud analytics allows hospitality chains to centralize fleet management across multiple properties.
- Asset-light leasing models:Fit-out contractors are shifting from purchase to operational expenditure structures, opening recurring revenue streams for OEMs with captive financing arms.
Industry Challenges
- Heat-pump technician scarcity:The shift from resistive heating to vapor-compression drying systems demands refrigeration-certified service personnel that remain concentrated in European training pipelines.
- ESMA certification timelines:Water-efficiency testing protocols require 12-18 month validation cycles, delaying product launches and compressing effective selling seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Dishwasher Market |
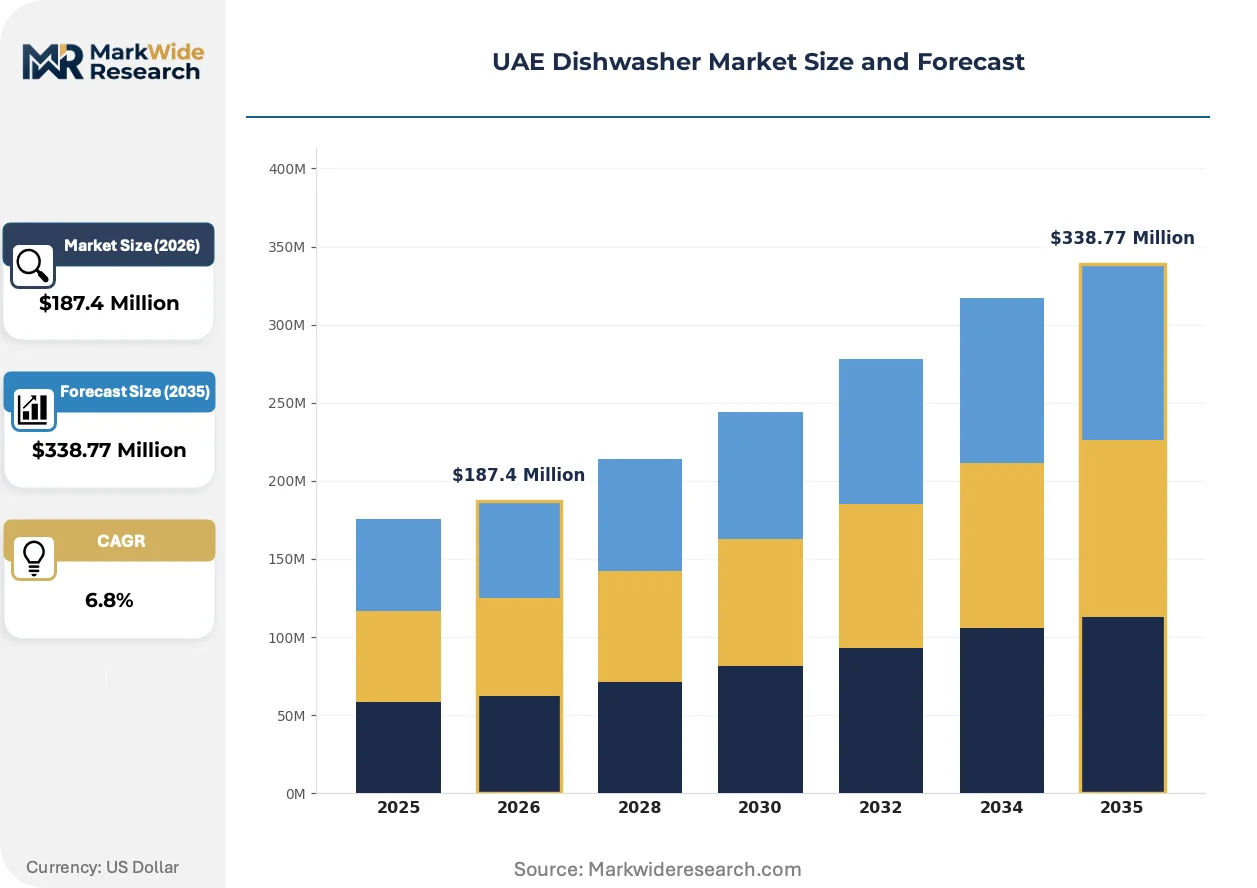
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Built-in, Freestanding, Compact, Portable End User: Residential, Commercial, Hospitality, Food Service Technology: Smart, Energy Efficient, Standard, Conventional Distribution Channel: Online, Offline, Specialty Stores, Wholesale |
| Companies Covered | Robert Bosch GmbH, Siemens AG, Indesit Co., Beko Plc, Westpoint, Electrolux AB, LG Electronics Inc., Samsung Electronics Co., Ltd., Whirlpool Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Dishwasher Market Evolving Landscape
Three interconnected shifts are reconfiguring competitive advantage: thermal system architecture is pivoting toward heat-pump platforms, regulatory pressure is tightening product standards, and buyer procurement logic is migrating from ownership to service-based models.
Heat-pump drying technology is hybridizing conventional resistive heating with vapor-compression heat recovery, cutting per-cycle energy draw by 40-50% versus legacy designs. Premium residential developers in Dubai's master-planned communities are specifying these systems as standard, while hospitality procurement teams evaluate total cost of ownership over 7-year replacement cycles. This thermal architecture shift is compressing the addressable market for conventional condenser-dryer models and forcing mid-tier suppliers to license heat-pump IP or exit the premium segment entirely.
ESMA's mandatory water-efficiency labeling framework now requires disclosure of liters per place setting, creating a transparent performance hierarchy that procurement officers exploit in competitive tendering. The regulation's industrial consequence is a bifurcation between A+++ rated models that qualify for green building certification points and unrated imports restricted to secondary replacement markets. Commercial kitchen operators in Abu Dhabi's healthcare and education sectors are responding by embedding ESMA tier requirements into mandatory technical specifications, effectively filtering non-compliant suppliers from bid pools.
Hospitality procurement teams are unbundling equipment purchase from after-sales service, favoring suppliers offering guaranteed uptime contracts with remote diagnostics. This behavior shift disrupts traditional wholesale distribution channels that lacked technical service capabilities, replacing them with manufacturer-direct or authorized service partnerships. The transformation is most visible in Dubai's premium hotel sector, where international chains centralize kitchen equipment decisions at regional headquarters and demand standardized IoT connectivity for fleet visibility.
UAE Dishwasher Market Segmentation
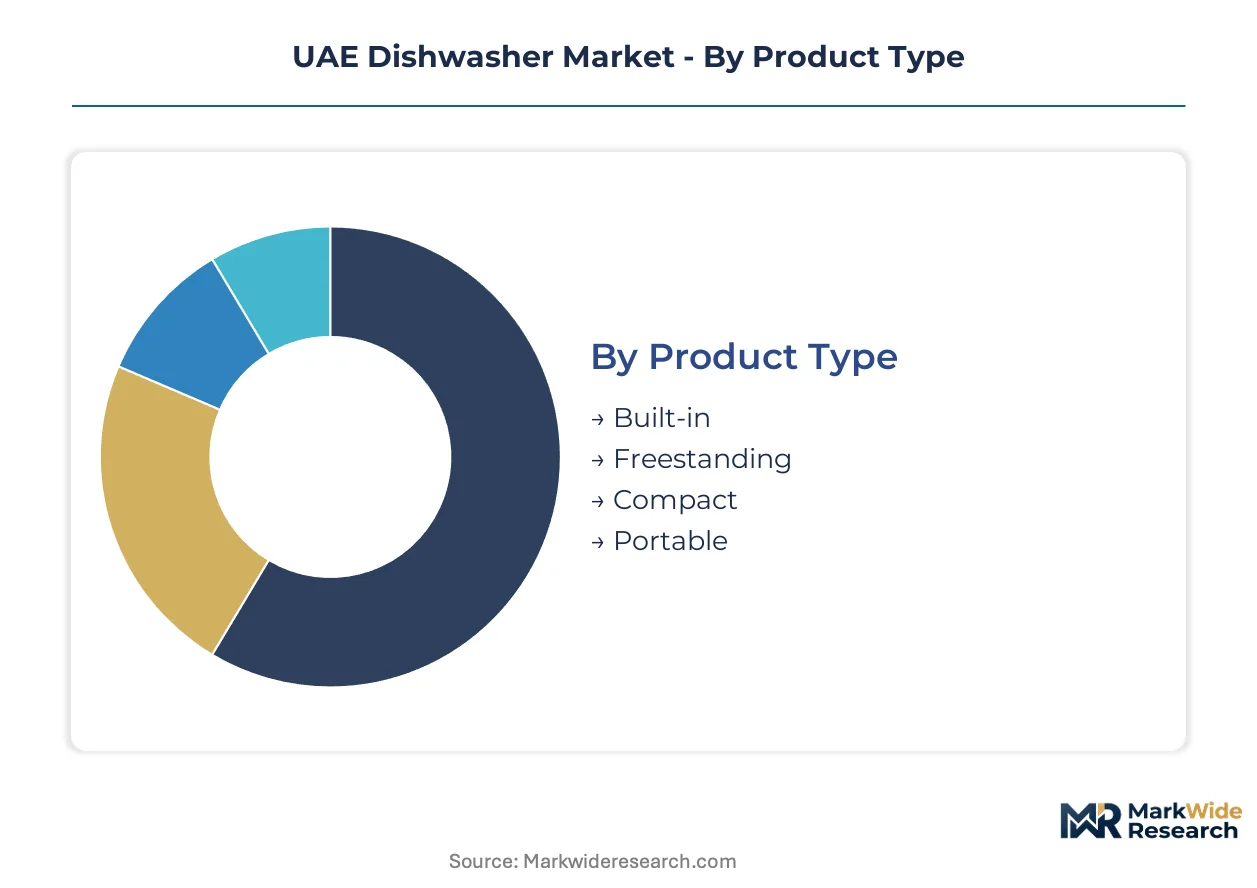
Dishwasher procurement cycles in the UAE diverge sharply between construction-specified built-in units with decade-long replacement horizons and food service equipment turning over every five to seven years. Understanding these temporal patterns helps suppliers align inventory, service infrastructure, and financing structures to the dominant buyer types in each segment.
Product Type:
Replacement cycles stretch from three years for portable units to fifteen-plus years for premium built-in installations, creating distinct margin and service revenue profiles across each tier.
- Built-in:Integrated cabinetry designs specified during construction of Dubai's master-planned communities and Abu Dhabi's luxury residential towers. ESMA water-efficiency labeling requirements now filter non-compliant models from green building certification pathways, accelerating specification shifts toward heat-pump platforms.
- Freestanding:Modular units serving rental properties and mid-market residential renovations where kitchen layouts preclude permanent installation. Demand concentrates in Sharjah and Ajman secondary residential markets where tenant turnover drives shorter replacement cycles.
- Compact:Countertop and slimline formats addressing space-constrained apartments in older Dubai districts. European expatriate households in Jumeirah and Al Barsha represent core demand.
- Portable:Mobile units with temporary hookup requirements serving catering operations and seasonal hospitality pop-ups. Ras Al Khaimah's emerging resort pipeline generates replacement-heavy demand.
Built-in dominates installed base. Freestanding is where expansion concentrates.
End User:
Cost tiers separate specification-driven procurement at the top from price-sensitive replacement buying at the bottom, with hospitality occupying a distinct middle ground prioritizing total cost of ownership over capital outlay.
- Residential:Owner-occupied villas and apartments in Dubai's Emirates Hills, Palm Jumeirah, and Abu Dhabi's Saadiyat Island where developers bundle premium appliances into sale prices. Heat-pump technology penetration runs highest here.
- Commercial:Corporate cafeterias, healthcare facilities, and educational institutions governed by MOHAP food safety protocols requiring validated sanitation cycles. Procurement teams emphasize ESMA tier ratings in competitive tendering.
- Hospitality:Hotel kitchens and back-of-house operations where international chains centralize equipment decisions at regional headquarters. Fleet management requirements drive IoT connectivity adoption.
- Food Service:Independent restaurants, cloud kitchens, and catering operators with high throughput demands and compressed replacement timelines. Wholesale distribution channels retain strongest penetration here.
Hospitality commands highest per-unit value. Food Service is climbing the fastest.
Technology:
Volume concentration favors legacy platforms while margin pools shift toward connected and efficient systems that qualify for regulatory incentives and green building points.
- Smart:Sensor-integrated platforms with cloud connectivity enabling remote diagnostics and predictive maintenance. Dubai's premium hotel chains deploy these for centralized fleet visibility across multiple properties.
- Energy Efficient:Heat-pump drying and optimized wash cycles meeting ESMA A+++ thresholds. Federal efficiency mandates and rising DEWA tariffs accelerate displacement of conventional thermal systems.
- Standard:Condenser-dryer and resistive-heating platforms still prevalent in mid-market residential and food service replacement cycles. Price positioning sustains volume despite regulatory pressure.
- Conventional:Basic wash systems without heat recovery or connectivity features. Market access narrows as ESMA labeling requirements tighten and green building codes exclude unrated imports.
Standard retains largest shipment volumes. Energy Efficient is gaining share fastest.
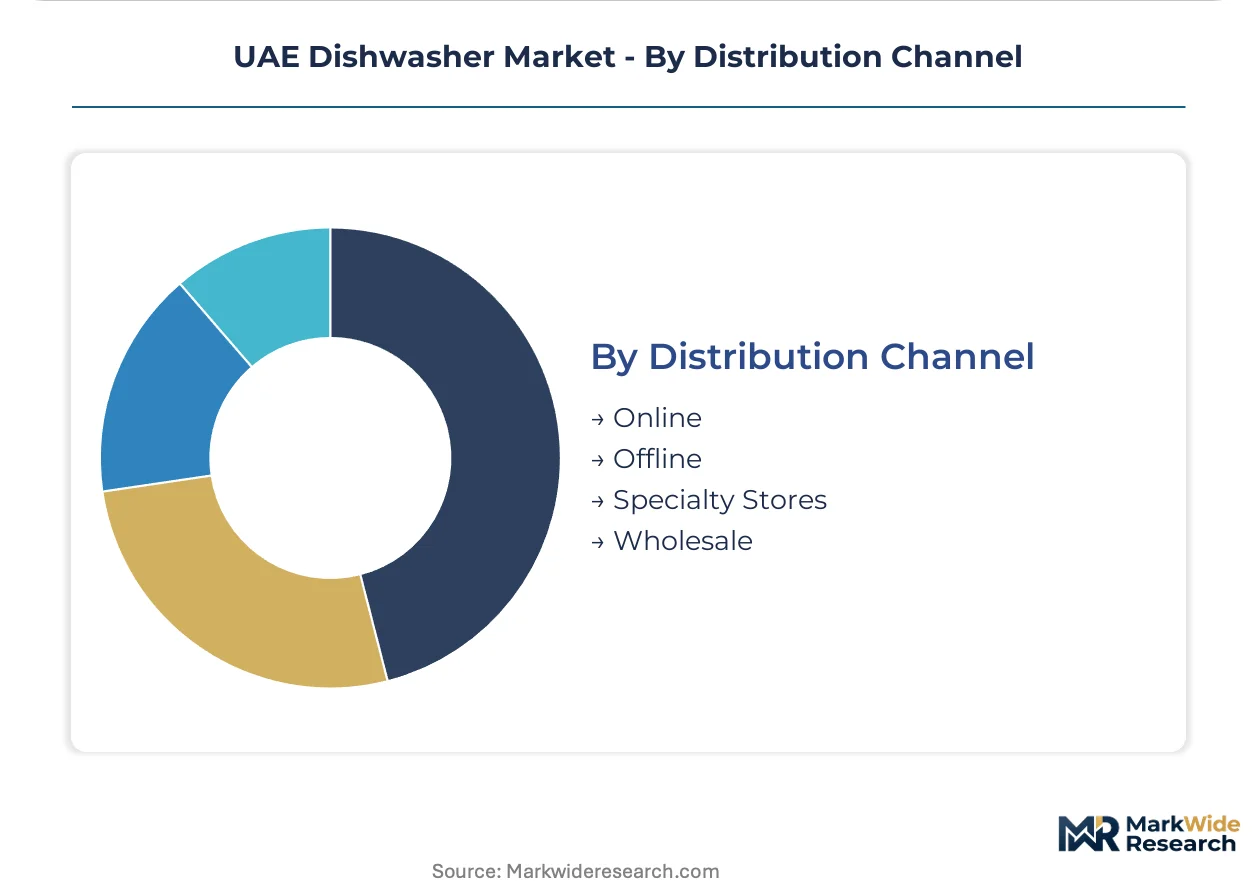
Distribution Channel:
Customer type stratification separates project-specified bulk procurement through wholesale and specialty channels from individual replacement buying migrating online.
- Online:E-commerce platforms capturing residential replacement demand and compact/portable category growth. Younger expatriate demographics in Dubai Marina and Downtown Dubai favor digital purchase journeys.
- Offline:Big-box retailers and appliance showrooms serving walk-in buyers requiring physical product comparison. Mid-market residential renovation projects in older Dubai districts sustain this channel.
- Specialty Stores:Kitchen design studios and developer showrooms where built-in specifications are finalized during pre-construction phases. Relationships with master-planned community developers determine competitive position.
- Wholesale:Project distributors and fit-out contractors serving hospitality and commercial new-build pipelines. Asset-light leasing models are restructuring traditional wholesale relationships toward service-based recurring revenue.
Wholesale anchors hospitality and commercial procurement. Online is expanding most quickly in residential segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal net-zero building codes and ESMA efficiency mandates are redistributing dishwasher procurement across the Emirates, with construction-specified built-in units concentrating in high-end developments while replacement demand fragments across secondary markets.
Dubai
Master-planned communities in Emirates Hills and Palm Jumeirah specify integrated kitchen packages with heat-pump dishwashers as standard. Dubai Municipality's green building certification requirements filter non-compliant models from new luxury residential pipelines. The Downtown Dubai and Dubai Marina corridors sustain demand for compact and smart-connected units among younger expatriate demographics.
Abu Dhabi
Saadiyat Island and Al Reem Island developments anchor built-in procurement cycles with decade-long replacement horizons. The emirate's healthcare and education sectors drive commercial dishwasher tendering governed by MOHAP food safety protocols. Procurement teams embed ESMA A+++ tier requirements into mandatory technical specifications.
Sharjah
Mid-market residential renovations and rental property turnover generate freestanding dishwasher demand with compressed three-to-five-year replacement cycles. Secondary residential markets here prioritize price positioning over energy efficiency ratings. Wholesale distribution channels retain strongest penetration in this cost-sensitive segment.
Northern Emirates
Ras Al Khaimah's emerging resort pipeline creates first-mover opportunities for suppliers establishing service infrastructure outside Dubai-Abu Dhabi cores. Seasonal hospitality pop-ups and catering operations drive portable unit procurement. Asset-light leasing models are restructuring traditional wholesale relationships toward operational expenditure structures.
UAE Dishwasher Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where premium residential specifications and hospitality fleet contracts concentrate value pools. The vendor base stratifies between German-engineering heritage brands anchoring master-planned community developments and Asian electronics conglomerates competing on smart connectivity and scale economics. Strategic archetypes include full-line appliance manufacturers with captive financing arms, component-integrated electronics specialists, and regional project distributors pivoting toward service-based recurring revenue. Dominant competitive moves encompass technology licensing agreements for heat-pump IP and backward integration into compressor supply.
Among German-engineering heritage manufacturers, Robert Bosch GmbH and Siemens AG occupy positions exemplifying premium-channel dominance through construction-specification relationships. Samsung Electronics Co., Ltd. represents the scale-driven archetype competing on connected-platform ecosystems. Whirlpool Corporation sits within the full-line manufacturer tier with broad wholesale distribution serving mid-market food service procurement.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Siemens AG |
| Indesit Co. |
| Beko Plc |
| Westpoint |
| Electrolux AB |
| LG Electronics Inc. |
| Samsung Electronics Co., Ltd. |
| Whirlpool Corporation |
| Others |
Value Network & Pricing Analysis
Jebel Ali's port-centric industrial corridor anchors heat-pump compressor import flows, concentrating pricing power among European and East Asian suppliers who control thermal system architectures. ESMA water-efficiency labeling requirements filter non-compliant models from green building certification pathways, compressing margin structures for mid-tier manufacturers dependent on standard condenser-dryer platforms.
Pricing Analysis
Certification level creates the primary spread across the UAE dishwasher market. ESMA A+++ tier ratings command substantial premiums in Dubai's master-planned community specifications, while unrated imports compete on transactional pricing in Sharjah's cost-sensitive replacement markets. Cost compression in mid-market segments is intensifying because stainless steel input volatility squeezes manufacturers dependent on imported nickel and chromium sheet metal. Food service operators exhibit highest price sensitivity, prioritizing capital outlay over total cost of ownership, whereas hospitality procurement teams embedded in international chains demonstrate lowest sensitivity due to centralized fleet standardization mandates.
Supply Chain Analysis
Contract manufacturing concentration for heat-pump thermal systems rests with specialized compressor producers in Germany, South Korea, and Japan. The UAE dishwasher supply chain draws from European refrigeration component specialists for vapor-compression drying modules and East Asian electronics integrators for IoT connectivity platforms. Single-source vulnerability concentrates in heat-pump compressor supply, with over 80% controlled by a narrow supplier base creating exposure to shipping disruptions through the Strait of Hormuz. Distribution runs through project distributors and fit-out contractors serving hospitality new-build pipelines, with asset-light leasing models restructuring traditional wholesale relationships toward service-based recurring revenue structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE dishwasher market represents an early-cycle expansion story. Net-zero building codes and ESMA efficiency mandates are accelerating replacement cycles for conventional thermal systems before saturation in premium residential segments.
For Market Incumbents: Pre-empt margin erosion in mid-market segments by securing captive heat-pump compressor supply through backward integration or long-term offtake agreements with European suppliers. Establish service infrastructure in Ras Al Khaimah's emerging resort pipeline before competitor entry, as first-mover positioning in Northern Emirates hospitality creates durable specification relationships. Defend against Asian electronics conglomerates competing on smart connectivity by anchoring German engineering heritage in Dubai's master-planned community developer relationships.
For New Entrants and Emerging Players: Build out asset-light leasing capabilities targeting food service operators shifting from capital expenditure to operational expenditure structures. Ras Al Khaimah's hospitality pipeline offers the most penetrable geography, with seasonal resort developments requiring portable unit procurement and localized service presence absent from incumbent coverage maps. Target cloud kitchen and catering operator segments through wholesale distribution partnerships emphasizing rapid replacement turnaround and flexible financing terms.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors OEMs with captive heat-pump IP and established ESMA certification pathways over pure-play connectivity specialists. Long-term viability over the next decade rests on regulatory compliance infrastructure and service network density rather than manufacturing scale alone. Acquisition targets should demonstrate established relationships with Dubai Municipality green building certification processes. The signal to watch is ESMA's evolution of water-efficiency testing protocols, as accelerated certification timelines would favor incumbent compliance infrastructure and compress windows for new entrant product launches.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Technology Licensing | Secures thermal system IP from European specialists to meet ESMA A+++ thresholds in Dubai specifications. |
| Service Infrastructure Expansion | Establishes refrigeration-certified technician networks in Ras Al Khaimah ahead of resort pipeline completion. |
| Asset-Light Leasing Model Development | Captures recurring revenue from food service operators migrating to operational expenditure procurement structures. |
| IoT Platform Integration | Enables centralized fleet management for hospitality chains operating multiple Dubai properties. |
| ESMA Certification Fast-Track Investment | Compresses 12-18 month validation cycles to secure first-mover positioning in efficiency tier upgrades. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this study. The research team conducted structured discussions with kitchen equipment procurement managers at Dubai hospitality chains, fit-out contractors serving Abu Dhabi commercial developments, and ESMA certification specialists. Secondary sources encompassed Emirates Authority for Standardization and Metrology technical specifications, Dubai Municipality green building code documentation, and MOHAP food safety protocol filings. Bottom-up demand modeling from construction pipeline data and top-down market sizing from import trade records were triangulated to establish volume benchmarks.
Calibration against historical replacement cycle patterns and efficiency mandate adoption curves shaped the projection framework. Segmentation dimensions modeled include product type, end-user category, technology tier, and distribution channel, with additional granularity on emirate-level regulatory enforcement variation. CAGRs were derived from fitted adoption curves for heat-pump technology penetration and hospitality fleet standardization timelines. Key forecast inputs incorporated DEWA electricity tariff trajectories and master-planned community construction schedules from Dubai and Abu Dhabi development authorities.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Asian electronics conglomerates or accelerated ESMA protocol revisions would shift outcomes. Model boundaries exclude gray-market import flows and informal service provider activity concentrated in Northern Emirates secondary markets. Quarterly review of ESMA certification backlog data and Jebel Ali port import manifests is advised to detect inflection in supply availability and regulatory enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
North America Washing Machine Market
Appliances
Europe Induction Hobs Market
Appliances
Water Dispenser Market
Appliances
Japan Massage Equipment Market
Appliances
Intelligent Electric Rice Cooker Market
Appliances
US Electric Rice Cooker Market
Appliances
Electric Kettle Market
Appliances
Oman Microwave Ovens Market
Appliances
Smart Washing Machine Market
Appliances
Laundry Appliances Market
Appliances
US Washing Machine Parts Market
Appliances
Toaster Ovens Market
Appliances
Vacuum Cleaner Market
Appliances
Middle East Portable Washing Machines Market
Appliances
Household Side by Side Refrigerator Market
Appliances
Space Heaters Market