
 Space Heaters Market | 2026-2036
Space Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Space Heaters Market Outlook
EU Ecodesign Directive revisions is consolidating compliance costs around seasonal efficiency metrics and standby power limits. De'Longhi Appliances S.r.l. leverages its Italian manufacturing base to sustain premium positioning across European retail channels. Honeywell International Inc. anchors North American distribution through big-box partnerships and connected-home integration. Dyson Ltd. differentiates via bladeless airflow engineering and advanced thermostat algorithms.
Space heaters are self-contained thermal appliances designed to raise ambient temperature in localized zones through radiant, convective, or forced-air heat transfer, typically rated between 500 and 1,500 watts for consumer units. Their primary purpose centers on supplemental heating in residential dwellings, commercial offices, and industrial workshops where central systems prove inadequate or cost-prohibitive. Electric technology leads unit shipments due to installation simplicity and plug-and-play portability, while infrared heaters command margin premiums for patio and warehouse applications targeting spot heating. The residential end-user segment dominates volume, though commercial installations in hospitality and healthcare settings offer longer replacement cycles and service attach rates.
FERC efficiency guidelines in the United States, EU Ecodesign Directive mandates across Europe, and GB standards administered by SAMR in China collectively shape product certification requirements and cross-border market access. These frameworks elevate minimum performance thresholds, effectively filtering out low-efficiency imports and rewarding manufacturers with certified testing laboratories. Stakeholders must monitor evolving carbon-border adjustment mechanisms and region-specific labeling schemes to preserve competitive positioning without eroding price accessibility.
Market Dynamics
The EU Ecodesign Directive's tightening seasonal efficiency metrics and standby power limits is compressing replacement cycles while filtering low-efficiency imports from European retail channels. Residential retrofit programs across Germany, France, and the United Kingdom are accelerating unit turnover as older electric models face compliance obsolescence.
Growth Catalysts
- EU Ecodesign Directive revisions:Minimum efficiency standards for portable heating appliances are forcing replacement of legacy units across single-family homes in suburban and rural France, creating sustained demand pull.
- Infrared technology adoption:Spot heating applications in hospitality patios and industrial warehouses command margin premiums, expanding addressable use cases beyond residential supplement.
- Residential retrofit programs:Government-funded renovation schemes in Germany and the United Kingdom subsidize energy-efficient appliance upgrades, shortening payback periods for consumers.
Market Restraints
- Copper and semiconductor input volatility:Heating element materials and thermostat control chips face price swings that compress manufacturer margins without commensurate pricing power.
- Chinese manufacturing concentration:GB standards administered by SAMR shape certification requirements, creating cross-border friction for non-domestic suppliers seeking market access.
- Heat pump substitution threat:Whole-home electrification programs in Nordic markets displace supplemental heating demand as primary systems improve efficiency.
Strategic Opportunities
- Connected-home integration:Smart thermostat algorithms and app-controlled scheduling converge with HVAC ecosystems, opening premium positioning in North American big-box retail.
- Commercial hospitality applications:Hotels and restaurants in Mediterranean climates seek outdoor heating solutions with weather resistance and design aesthetics.
- Carbon-border adjustment mechanisms:Emerging EU trade instruments reward certified testing laboratories with competitive positioning against uncertified imports.
Industry Challenges
- Multi-jurisdiction certification timelines:FERC efficiency guidelines in the United States, EU Ecodesign mandates, and GB standards require parallel testing protocols that delay product launches.
- Legacy system integration complexity:Smart heaters must interoperate with existing home automation standards, fragmenting R&D resources across incompatible protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Heaters Market |
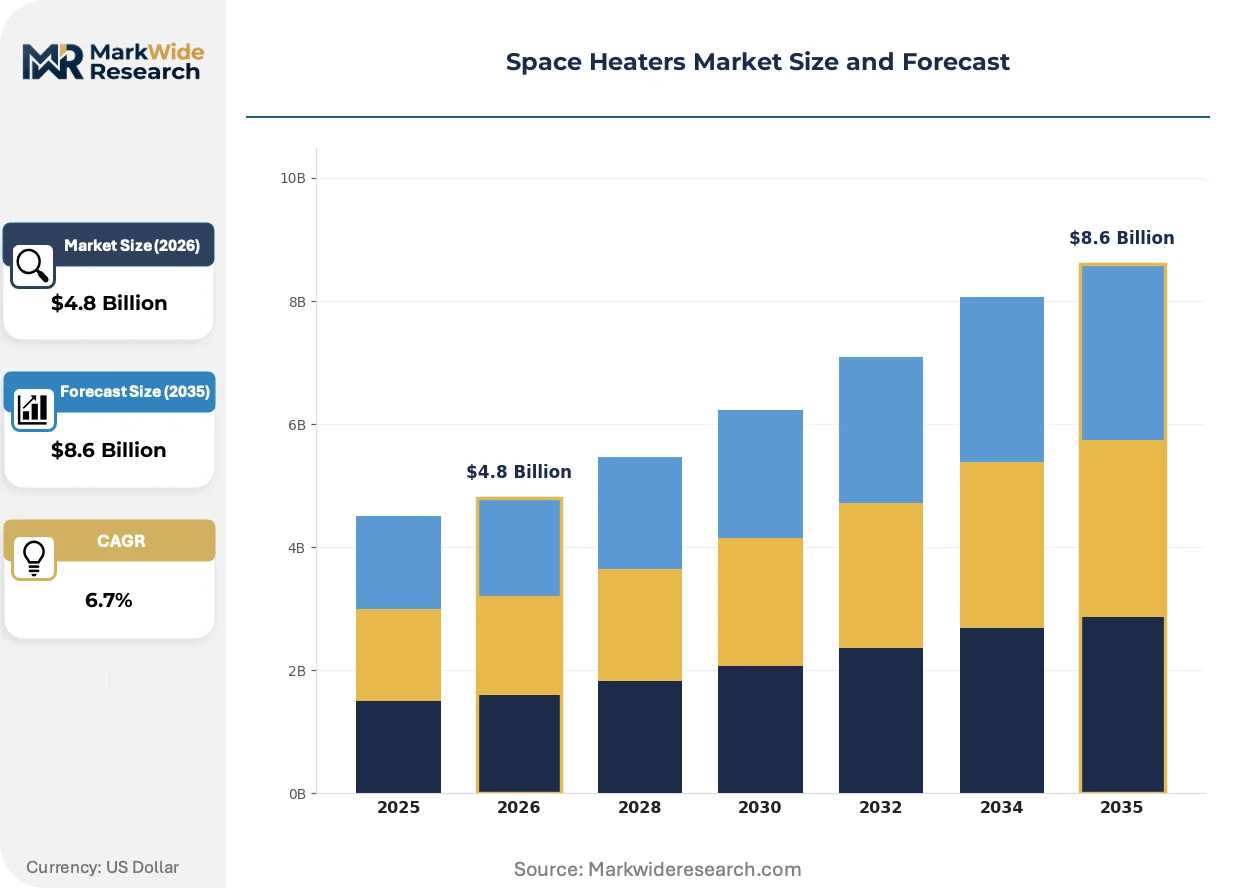
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Heaters, Oil-Filled Heaters, Convection Heaters, Fan Heaters Technology: Electric, Gas, Hydronic, Propane End User: Residential, Commercial, Industrial, Educational Energy Source: Electricity, Natural Gas, Renewable, Other |
| Companies Covered | De'Longhi Appliances S.r.l., Honeywell International Inc., Lasko Products, LLC, Dyson Ltd., Vornado Air, LLC, Midea Group, Newell Brands, DAIKIN INDUSTRIES, Ltd., Crane - USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Heaters Market Strategic Shifts
Product development is bifurcating between premium connected units with advanced controls and cost-optimized models targeting price-sensitive retrofit markets. This divergence is compressing mid-tier positioning while rewarding manufacturing scale or patent-protected differentiation.
Ceramic heating elements with positive temperature coefficient thermistors are integrating into consumer-grade space heaters to enable faster thermal response and tip-over safety shutdowns. Residential buyers in Germany and France are prioritizing these units for nursery and elderly care applications. The technology is integrating seasonal efficiency algorithms that adjust wattage draw based on ambient temperature readings, compressing energy consumption variance against rated performance.
The EU Ecodesign Directive's 2019 and 2023 amendments have tightened seasonal efficiency metrics and standby power limits for portable heating appliances. Manufacturers must now maintain certified testing laboratories to document compliance, elevating fixed costs for market entry. Small appliance specialists in Italy and Spain are responding by consolidating production lines to capture scale economies in testing and certification.
Buyers are compressing replacement cycles as retrofit subsidies and efficiency labeling schemes reduce payback periods for newer units. Big-box retail partnerships in North America are displacing traditional hardware store distribution for connected-home compatible models. This pattern is most visible in suburban United States markets where utility rebate programs stack with federal incentives.
Space Heaters Market Segmentation
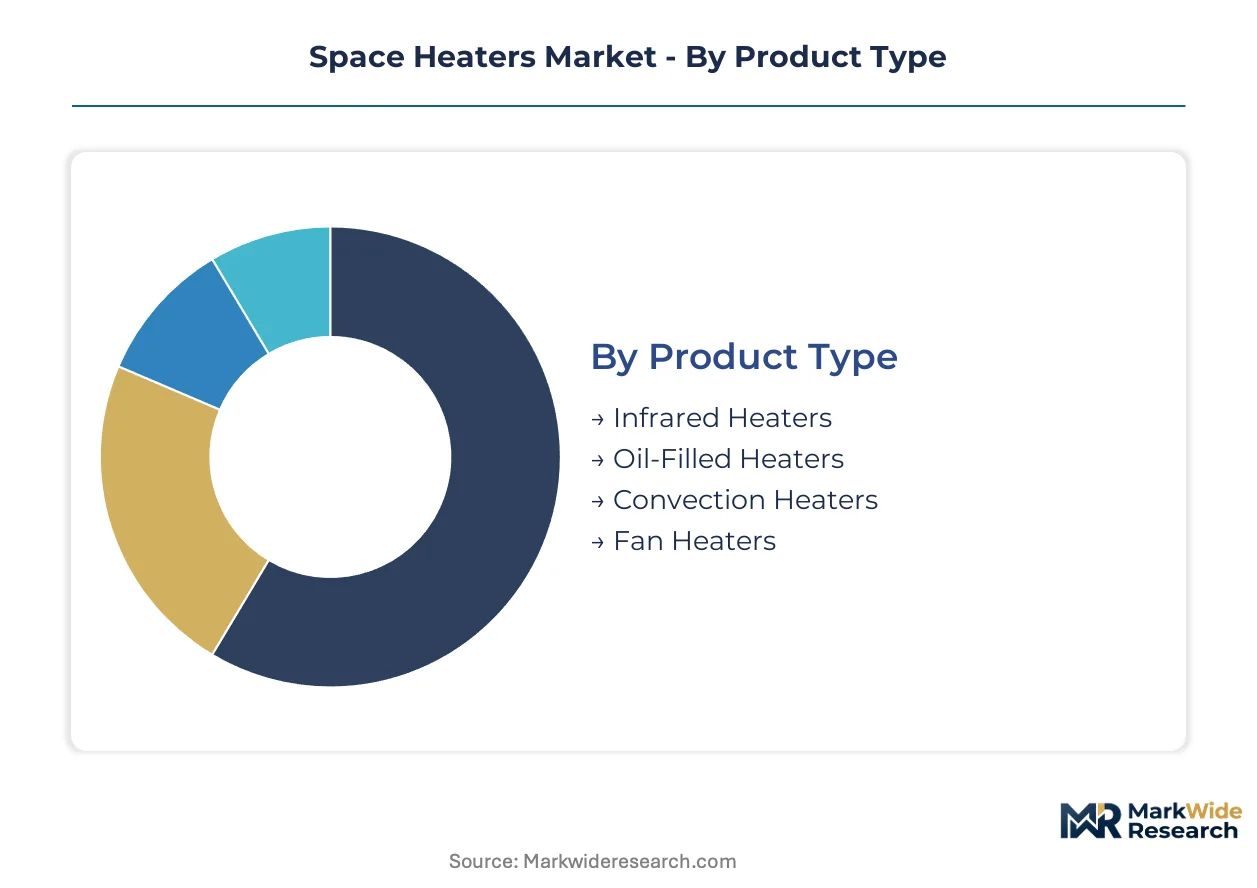
Space heater procurement patterns diverge sharply across use cases, with replacement cycles and efficiency mandates driving category-specific demand. Manufacturers must align product portfolios to distinct thermal performance requirements and regulatory compliance tiers rather than pursuing undifferentiated volume strategies.
Product Type:
Replacement cycles accelerate where EU Ecodesign Directive efficiency thresholds render legacy units non-compliant, compressing upgrade windows for homeowners and facility managers alike.
- Infrared Heaters:Radiant heat transfer through quartz or carbon fiber elements delivers instantaneous spot warming without air circulation. Hospitality patios in France and industrial warehouses in Germany prioritize these units for zonal comfort with minimal energy waste.
- Fan Heaters:Forced-air convection through ceramic or wire-wound heating coils enables rapid space conditioning in compact footprints. Residential buyers in suburban United Kingdom markets favor these for nursery applications where tip-over safety and fast thermal response matter.
- Oil-Filled Heaters:Diathermic oil reservoirs with convection fins provide silent, steady radiant output suited to overnight bedroom heating.
- Convection Heaters:Natural airflow through heated aluminum panels distributes warmth evenly across enclosed spaces without mechanical noise.
Fan Heaters sits at the top of the volume ranking, with Infrared Heaters climbing the fastest.
Technology:
Cost-tier stratification separates premium connected controls from basic electromechanical thermostats, with mid-tier positioning eroding as buyers polarize toward feature-rich or price-optimized endpoints.
- Electric:Resistance heating through nichrome or ceramic elements dominates unit shipments due to plug-and-play installation simplicity. Retrofit programs across Germany, France, and the United Kingdom subsidize efficient electric replacements, sustaining demand pull despite heat pump competition.
- Gas:Blue-flame or infrared catalytic combustion delivers higher BTU output for unventilated commercial and industrial spaces. Warehouse operators in Nordic climates specify these where electrical infrastructure cannot support wattage loads.
- Hydronic:Hot water or glycol circulation through finned radiators integrates with existing boiler systems for whole-zone supplemental heating.
- Propane:Portable tank-fed combustion serves off-grid construction sites and rural outbuildings lacking utility connections.
Electric commands absolute volume leadership, though Gas technology is gaining share fastest in commercial cold-climate applications.
End User:
Application-specific duty cycles and replacement frequencies create divergent margin profiles across customer types, with commercial installations offering longer service attach rates than residential impulse purchases.
- Residential:Single-family homeowners in suburban and rural France drive replacement demand as Ecodesign labeling schemes clarify efficiency payback. Nursery and elderly care applications prioritize tip-over safety and programmable thermostats.
- Commercial:Hotels, restaurants, and retail chains in Mediterranean climates specify weather-resistant outdoor heating with design-forward aesthetics. These buyers accept premium pricing for durability and brand alignment.
- Industrial:Warehouse and workshop operators require spot heating for employee zones without conditioning entire volumes.
- Educational:School districts and universities face capital budget constraints that favor lowest-first-cost procurement despite higher lifetime operating expenses.
Residential dominates absolute unit volume, with Commercial expanding most quickly on hospitality and healthcare retrofit investment.
Energy Source:
Supply concentration in electricity generation and distribution infrastructure shapes regional fuel switching feasibility, with grid decarbonization timelines influencing long-run technology bets.
- Electricity:Grid-delivered power enables precise thermostatic control and zero on-site emissions, aligning with residential electrification mandates. FERC efficiency guidelines and utility rebate programs in the United States reinforce this trajectory.
- Natural Gas:Pipeline-delivered methane offers cost advantages in regions with mature distribution infrastructure. Industrial facilities in Germany retain gas heating where process heat requirements exceed electrical capacity.
- Renewable:Solar-thermal or biomass-fed systems serve niche off-grid and sustainability-certified building projects.
- Other:Kerosene, diesel, and waste-oil combustion persists in emergency backup and remote construction applications.
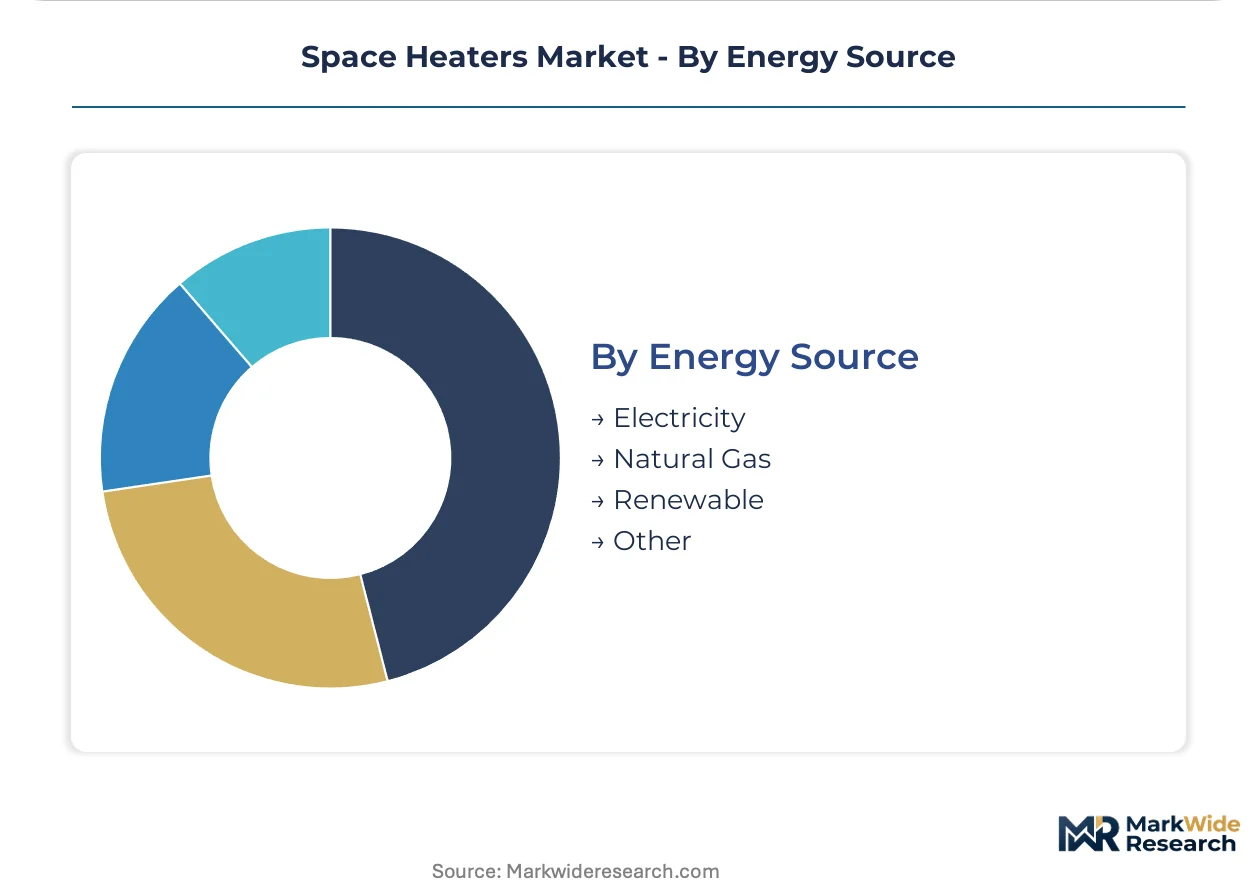
Electricity holds unchallenged volume leadership, with Renewable showing steepest expansion trajectory on building decarbonization commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The space heater industry traces its modern commercial roots to post-war European electrification and North American suburban expansion, with Germany and the United States establishing early manufacturing bases for portable heating appliances that now face retrofit-driven replacement cycles.
Germany
Single-family homeowners in suburban Bavaria and North Rhine-Westphalia drive replacement demand through government-funded renovation schemes. The EU Ecodesign Directive's seasonal efficiency mandates render pre-2019 electric units non-compliant, compressing upgrade windows. Industrial clusters around Stuttgart and Munich host testing laboratories certifying compliance for export to neighboring markets.
United States
Utility rebate programs in California and Texas stack with federal incentives to shorten payback periods for connected-home compatible models. FERC efficiency guidelines elevate minimum performance thresholds, filtering low-efficiency imports from big-box retail channels. The Southeast corridor from Florida to Georgia concentrates hospitality procurement for weather-resistant outdoor heating solutions.
France
Residential retrofit programs concentrate in Île-de-France and Auvergne-Rhône-Alpes, where single-family homeowners replace legacy electric units. ANSM and national energy agencies administer labeling schemes that clarify efficiency payback. Nursery and elderly care applications in Lyon and Marseille prioritize tip-over safety certifications and programmable thermostat integration.
United Kingdom
Fan heater demand clusters in suburban Greater London and Midlands markets where fast thermal response matters for compact residential footprints. Government-funded renovation schemes subsidize energy-efficient appliance upgrades. Retail partnerships in Manchester and Birmingham displace traditional hardware store distribution for connected-home compatible models.
China
GB standards administered by SAMR shape certification requirements for domestic manufacturers and create cross-border friction for non-domestic suppliers. Production gravity centers on Guangdong and Zhejiang provinces, where scale economies in ceramic heating element fabrication support cost-optimized export models. Yangtze River Delta clusters integrate seasonal efficiency algorithms for premium-tier European shipments.
Space Heaters Market Competitive Environment
The competitive structure tilts toward diversified appliance conglomerates with captive distribution networks. Tiered positioning separates premium connected units with advanced controls from cost-optimized models targeting price-sensitive retrofit markets, compressing mid-tier viability. Two strategic archetypes dominate: European heritage brands leveraging certified testing infrastructure for regulatory compliance, and Asian scale manufacturers capturing volume through ceramic element integration. Dominant competitive moves include backward integration into heating element production and strategic partnerships with utility rebate programs.
Among diversified appliance conglomerates, De'Longhi Appliances S.r.l. and Midea Group occupy positions at opposite ends of the premium-volume spectrum, with the former representing European heritage manufacturing and the latter exemplifying Asian scale production. Dyson Ltd. anchors the engineering-led tier through industrial design differentiation. These three entities collectively illustrate the market's tripartite structure: heritage compliance specialists, scale-driven fabricators, and technology-forward disruptors.
| Leading Market Players |
|---|
| De'Longhi Appliances S.r.l. |
| Honeywell International Inc. |
| Lasko Products, LLC |
| Dyson Ltd. |
| Vornado Air, LLC |
| Midea Group |
| Newell Brands |
| DAIKIN INDUSTRIES, Ltd. |
| Crane - USA |
| Others |
Value Chain & Pricing Dynamics
Guangdong and Zhejiang provinces' ceramic heating element fabrication workforce concentration compresses labor-cost differentials between premium connected units and cost-optimized retrofit models. This regional specialization widens pricing-tier spreads as EU Ecodesign Directive compliance costs fix at the premium tier while scale economies protect entry-level positioning.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates connected-home compatible models with FERC-certified seasonal efficiency from basic electromechanical units and uncertified imports. Price differentiation rests on GB standards compliance tier and ceramic element quality grade. Cost compression in the economy tier is intensifying because SAMR certification timelines delay Chinese manufacturer margin recovery. Educational procurement committees exhibit highest price sensitivity, while Mediterranean hospitality buyers accept premium positioning for weather-resistant design aesthetics.
Supply Chain Analysis
Dual-sourcing requirements from big-box retail partners in the United States and Germany mandate multi-supplier qualification for heating element and thermostat control chip vendors. Manufacturing gravity centers on China, Italy, and Mexico, with nichrome wire and ceramic substrates anchoring input dependencies. Single-source vulnerability concentrates in semiconductor thermostat controllers from Taiwan and South Korea. Distribution runs through utility rebate program partnerships in North America and renovation scheme administrators in France and the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Ecodesign Directive efficiency mandates generate replacement demand independent of macroeconomic cycles. The 2019 and 2023 amendments tightening seasonal efficiency metrics and standby power limits created sustained compliance obsolescence cycles.
For Market Incumbents: Deepen backward integration into ceramic heating element production to capture margin compression from copper and semiconductor input volatility. Anchor channel control through certified testing laboratory investments that accelerate multi-jurisdiction product launches against heat pump substitution threats in Nordic markets. For New Entrants and Emerging Players: Direct-to-consumer digital channels offer the most penetrable route for connected-home compatible models targeting suburban United States utility rebate stacking opportunities. White-space exists in commercial hospitality weather-resistant outdoor heating for Mediterranean climates, where design-forward aesthetics command premium positioning absent from incumbent catalogs. For Investors and Strategic Acquirers: Diversified appliance conglomerates with captive European distribution networks are the most active acquirer in this space, consolidating Italian and Spanish specialists to capture Ecodesign compliance scale economies. Acquisition targets should display certified testing infrastructure and utility rebate program partnerships. Watch carbon-border adjustment mechanism implementation timelines as the signal for import-competitive positioning inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heating Elements | Captures margin from Guangdong ceramic substrate supply concentration and insulates against copper volatility. |
| Connected-Home Platform Integration | Opens premium positioning through FERC-certified seasonal efficiency algorithms and app-controlled scheduling. |
| Certified Testing Laboratory Investment | Accelerates EU Ecodesign Directive compliance documentation and filters uncertified import competition. |
| Utility Rebate Program Partnership | Stacks federal incentives in California and Texas markets to shorten consumer payback periods. |
| Commercial Hospitality Product Line Extension | Targets Mediterranean climate hotels with weather-resistant design aesthetics and longer replacement cycles. |
Study Parameters
Coverage spans Germany, France, the United Kingdom, the United States, and China, with primary inputs from each market. The research combines interviews with product development executives at heating appliance manufacturers, regulatory affairs leads navigating FERC and EU Ecodesign compliance, big-box retail category buyers, and industrial procurement managers at warehouse operators. Secondary validation draws from SAMR GB standards documentation, FERC efficiency guideline filings, EU Ecodesign Directive amendment texts, and customs trade data for heating element imports. Bottom-up unit shipment estimates triangulate against top-down replacement cycle modeling across residential retrofit programs.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon. The analytical framework models segmentation dimensions including product type, technology tier, end-user application, and energy source, with regional regulatory cluster as an industry-specific overlay. CAGRs derive from fitted trend extrapolation adjusted for compliance-driven replacement cycle compression. Forecast inputs include EU Ecodesign Directive phase-out schedules, utility rebate program budget allocations, and heat pump penetration rates in Nordic markets.
Copper and semiconductor price volatility, carbon-border adjustment mechanism implementation timing, and heat pump substitution acceleration are the dominant revision risks. Forecasts reflect documented assumptions about retrofit subsidy continuation and efficiency labeling scheme adoption rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
UK Residential Vacuum Cleaner Market
Appliances
United States Microwave Oven Market
Appliances
Dishwasher Market
Appliances
Industrial Gas Stove Market
Appliances
North America Washing Machine Market
Appliances
Saudi Arabia Gas Hobs Market
Appliances
Mexico Laundry Appliances Market
Appliances
Egypt Dishwashers Market
Appliances
Asia-Pacific Tumble Dryers Market
Appliances
Global Vended Laundry Equipment Market
Appliances
Colombia Laundry Appliances Market
Appliances
Kuwait Dishwasher Market
Appliances
North America Compact Dishwasher Market
Appliances
North America Tumble Dryers Market
Appliances
China Induction Hobs Market
Appliances
Consumer Appliances Market