
 Smart Ceiling Fan Market | 2026-2036
Smart Ceiling Fan Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Ceiling Fan Market Analytics
China is rewriting assembly economics for smart ceiling fans through concentrated motor and PCB manufacturing zones in Guangdong and Zhejiang provinces. Hunter Fan Company leverages century-old brand equity to sustain premium positioning across North American retail channels. Atomberg specializes in brushless DC motor technology to differentiate its energy-efficient portfolio in price-sensitive South Asian markets.
A smart ceiling fan integrates electronically commutated motors, wireless connectivity modules, and environmental sensors to automate airflow, lighting, and temperature regulation in enclosed spaces. Wi-Fi enabled units dominate residential installations due to smartphone interoperability, while Zigbee and Z-Wave variants anchor commercial deployments requiring mesh network reliability. The hospitality end user segment generates outsized margin pools as hotel operators specify branded, app-integrated fixtures for guest experience differentiation.
India's Bureau of Energy Efficiency mandates star ratings for ceiling fans, compressing demand toward inverter-motor models that qualify for higher tiers. The EU F-Gas Regulation and Ecodesign Directive shape import eligibility by restricting refrigerant-linked HVAC alternatives and setting minimum efficiency thresholds for electrically operated circulators. Stakeholders must monitor how fragmented smart home platform standards fragment procurement specifications across regional ecosystems.
Market Dynamics
Brushless DC motor adoption is compressing energy consumption thresholds while India's BIS star-rating mandates force inverter-motor upgrades across residential new-build specifications.
Growth Catalysts
- BIS Energy Labeling Mandates:India's Bureau of Indian Standards enforces tiered efficiency ratings that disqualify conventional AC motor models from government procurement and star-rated housing projects.
- Wi-Fi Module Cost Collapse:Mass production of ESP32 and similar connectivity chipsets in Guangdong manufacturing clusters has collapsed integration costs for smartphone-interoperable fan controllers.
- Hospitality Experience Differentiation:Hotel operators in Dubai and Singapore specify app-integrated fixtures with occupancy-sensing automation to reduce housekeeping touchpoints and energy waste.
Market Restraints
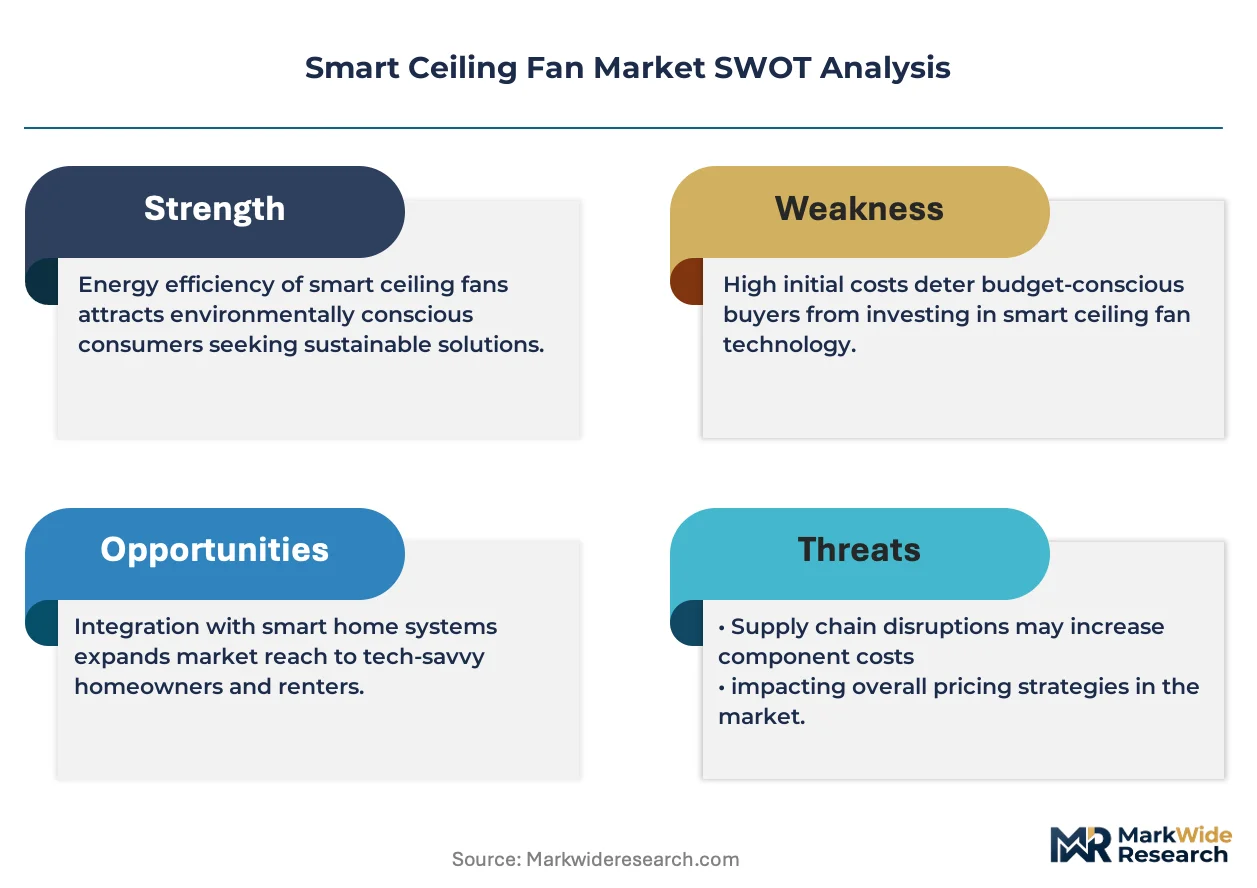
- Copper and Rare Earth Input Volatility:Neodymium magnet prices and copper winding costs swing with electric vehicle battery competition, squeezing brushless DC motor margins.
- Guangdong PCB Supply Concentration:Over 70 percent of smart fan control boards originate from Shenzhen and Dongguan, exposing brands to single-region logistics disruptions.
- EU F-Gas Regulation Substitution Pressure:Restrictions on refrigerant-linked HVAC systems are redirecting cooling demand toward ductless mini-splits that compete with ceiling air circulation.
Strategic Opportunities
- Vietnamese Manufacturing Migration:Labor cost arbitrage and US tariff positioning are pulling final assembly from coastal China to Hai Phong and Ho Chi Minh City industrial zones.
- Matter Protocol Convergence:Unified smart home interoperability standards are collapsing platform fragmentation that previously required brand-specific hub investments.
- Commercial Building Retrofit Incentives:The US Inflation Reduction Act tax credits for building electrification are accelerating replacement cycles in aging office and retail stock.
Industry Challenges
- Firmware Security Certification Delays:UL 2900 and IEC 62443 cybersecurity validation for connected appliances extends product launch timelines by four to six months.
- Legacy HVAC Integration Complexity:Building management system protocols from Honeywell, Siemens, and Johnson Controls require custom middleware development for unified climate control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Ceiling Fan Market |
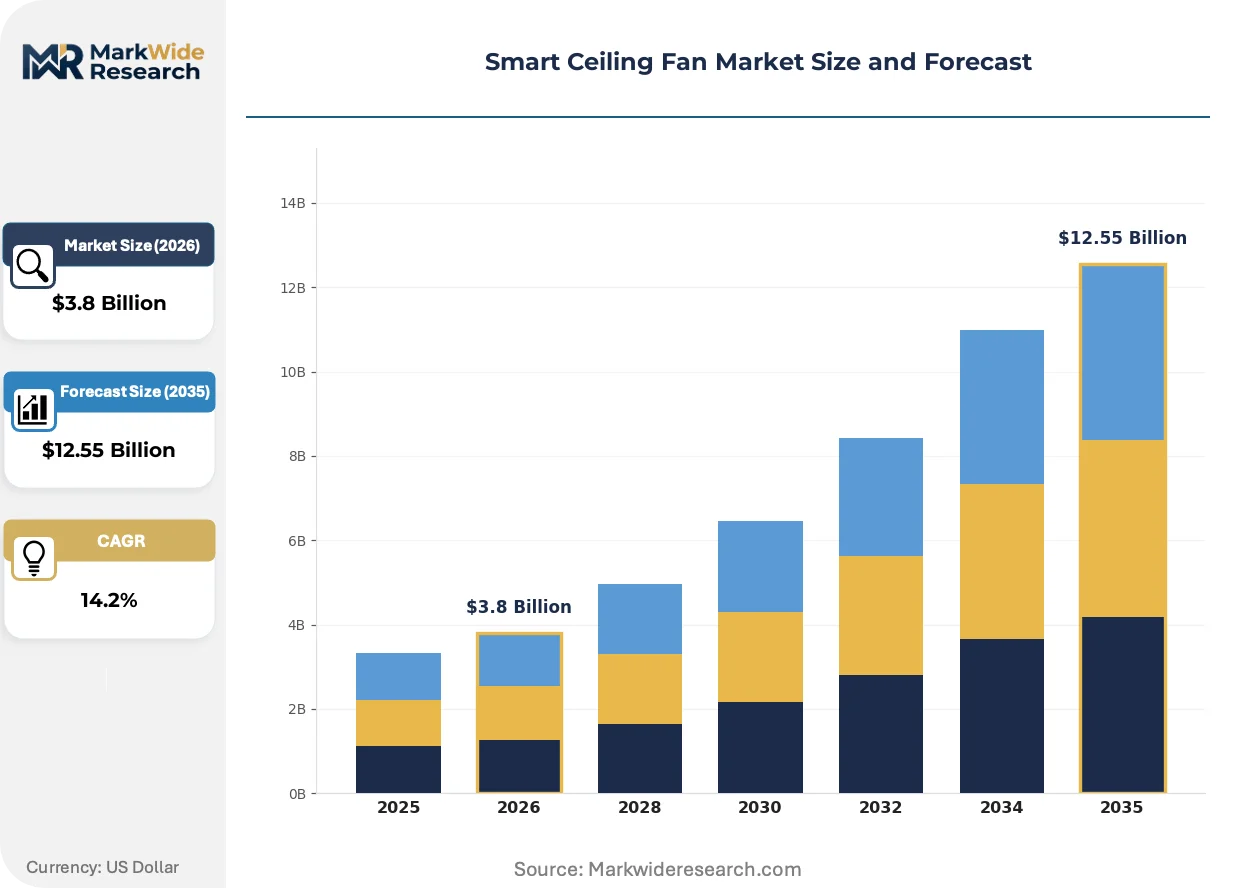
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Fans, Energy-Efficient Fans, Remote-Controlled Fans, Bluetooth-Enabled Fans Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth Low Energy End User: Residential, Commercial, Hospitality, Institutional Installation: Ceiling Mount, Wall Mount, Recessed, Flush Mount |
| Companies Covered | DREO, Big Ass Fans, Hunter Fan Company, WAC Lighting, Hunter Industrial, Atomberg, Smafan, Minka Aire, LG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Ceiling Fan Market Evolving Landscape
Sensor fusion and edge computing are migrating environmental intelligence from cloud dependency to on-device processing, compressing latency and connectivity infrastructure requirements.
Brushless DC motor architectures with integrated variable frequency drives are rendering obsolete single-speed induction motor platforms across residential and light commercial segments. Homebuilders in Texas and Florida are specifying these as standard in new construction. The technology is rendering obsolete the aftermarket retrofit market for external speed controllers.
The EU Ecodesign Directive's 2024 tightened thresholds for electrically operated circulators are forcing importers to recertify entire product lines or exit the market. Minimum efficiency requirements now exclude conventional capacitor-run motors from CE marking eligibility. German and Dutch distributors are consolidating supplier relationships around pre-certified inverter-motor platforms.
Direct-to-installer procurement through specialized electrical supply platforms is bypassing traditional retail markup structures. Contractors in California and New York are sourcing Wi-Fi enabled units through Procore and similar trade-specific marketplaces. This channel shift is most pronounced in multi-unit residential projects where bulk specification authority rests with electrical subcontractors rather than end consumers.
Smart Ceiling Fan Market Segmentation
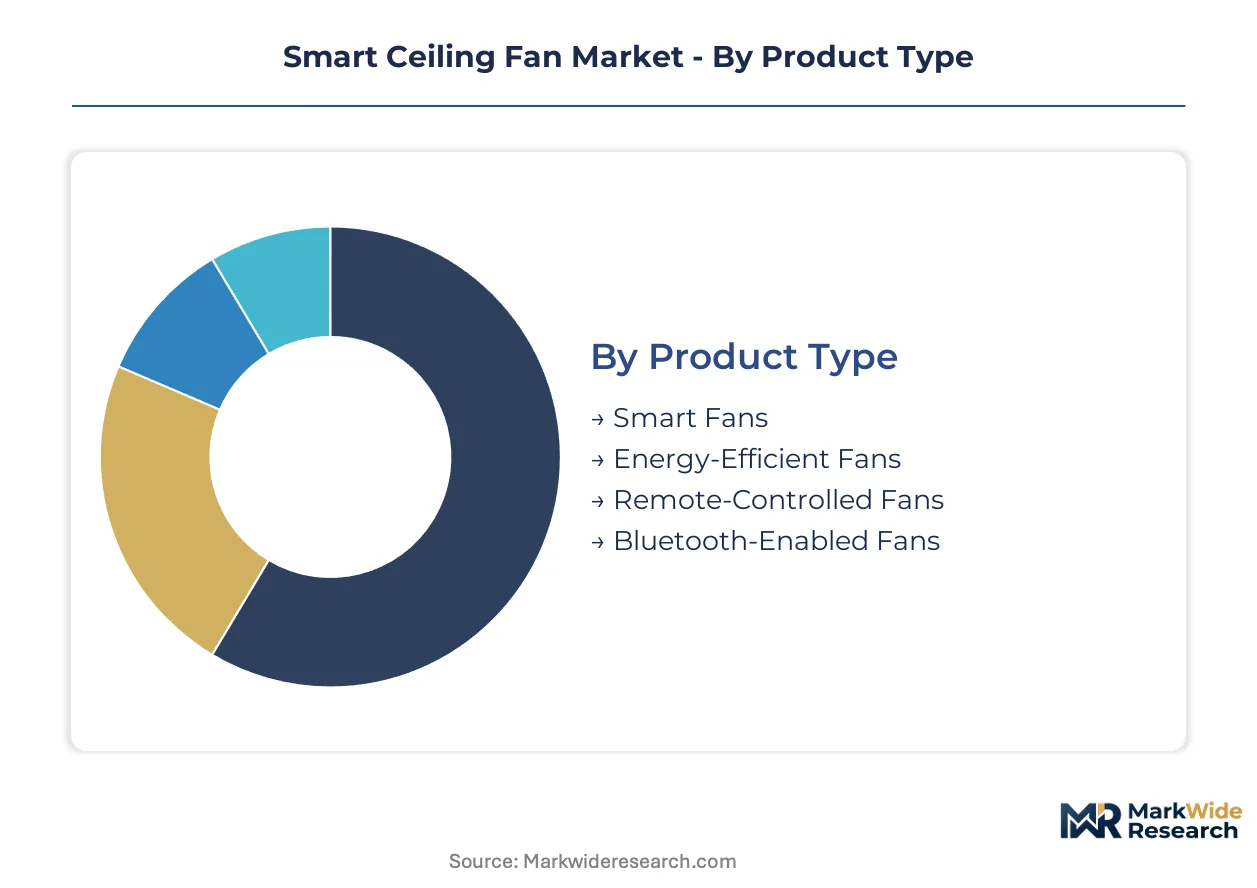
Smart ceiling fan procurement patterns diverge sharply across installation contexts, with hospitality operators demanding white-glove commissioning support while residential buyers prioritize plug-and-play simplicity. Service intensity directly shapes margin structures and channel economics for each segment cluster.
Product Type:
After-sales service intensity varies dramatically across product tiers, with fully integrated smart fans requiring firmware update commitments and energy-efficient models demanding minimal post-installation support.
- Smart Fans:Electronically commutated motors pair with cloud-connected control boards to enable smartphone scheduling, voice assistant integration, and occupancy-based automation. Hospitality operators in Dubai and Singapore specify these for guest room energy management, absorbing higher upfront costs to reduce housekeeping touchpoints and utility expenditures.
- Energy-Efficient Fans:Brushless DC motor platforms with integrated variable frequency drives slash power consumption versus conventional AC induction units. India's BIS star-rating mandates compress demand toward this segment as residential builders seek compliance with minimum efficiency thresholds for government housing projects.
- Remote-Controlled Fans:Radio-frequency handheld controllers enable basic speed and lighting adjustment without smartphone dependency. This segment serves aging demographics and rental property markets where tenant turnover complicates app-based ecosystem investments.
- Bluetooth-Enabled Fans:Short-range wireless connectivity supports localized control without home network infrastructure. These units penetrate price-sensitive South Asian markets where Wi-Fi penetration remains uneven in secondary cities.
By volume, energy-efficient fans lead. By growth pace, smart fans are expanding most quickly.
Technology:
Connectivity protocol selection drives ecosystem lock-in effects and determines which smart home platforms can integrate natively.
- Wi-Fi:Direct router connectivity eliminates hub requirements and maximizes smartphone interoperability across iOS and Android ecosystems. US residential installations concentrate here due to consumer familiarity with app-based control and minimal setup friction.
- Zigbee:Mesh networking architecture enables reliable operation across large commercial footprints with multiple simultaneous connections. Hotel properties and office buildings specify Zigbee variants to ensure consistent performance where Wi-Fi congestion threatens responsiveness.
- Z-Wave:Sub-GHz frequency bands penetrate building materials more effectively than 2.4 GHz alternatives. North American security integrators favor this protocol for whole-home automation bundles including climate and lighting control.
- Bluetooth Low Energy:Minimal power draw suits battery-powered remote accessories and localized phone-to-fan pairing. This technology anchors entry-level products targeting first-time smart home adopters.
Wi-Fi dominates current installations. Zigbee is climbing the fastest in commercial new construction.
End User:
Specification authority and procurement cadence differ fundamentally between owner-occupied residential and institutional deployment contexts.
- Residential:Individual homeowners and landlords drive demand through retail and direct-to-installer channels. Texas and Florida homebuilders specify brushless DC models as standard in new construction, eliminating aftermarket retrofit opportunities.
- Commercial:Facility managers prioritize Building Management System integration and centralized energy dashboards. US Inflation Reduction Act tax credits for building electrification accelerate replacement cycles in aging office and retail stock.
- Hospitality:Branded guest experience requirements drive specification of app-integrated fixtures with occupancy-sensing automation. This segment generates outsized margin pools as operators seek differentiation through seamless environmental control.
- Institutional:Schools, hospitals, and government facilities emphasize durability certifications and extended warranty terms. Procurement runs through formal bidding processes with multi-year maintenance contracts.
Residential captures the greatest unit volume. Hospitality shows the steepest margin expansion trajectory.
Installation:
Mounting configuration determines electrical contractor skill requirements and project timeline complexity.
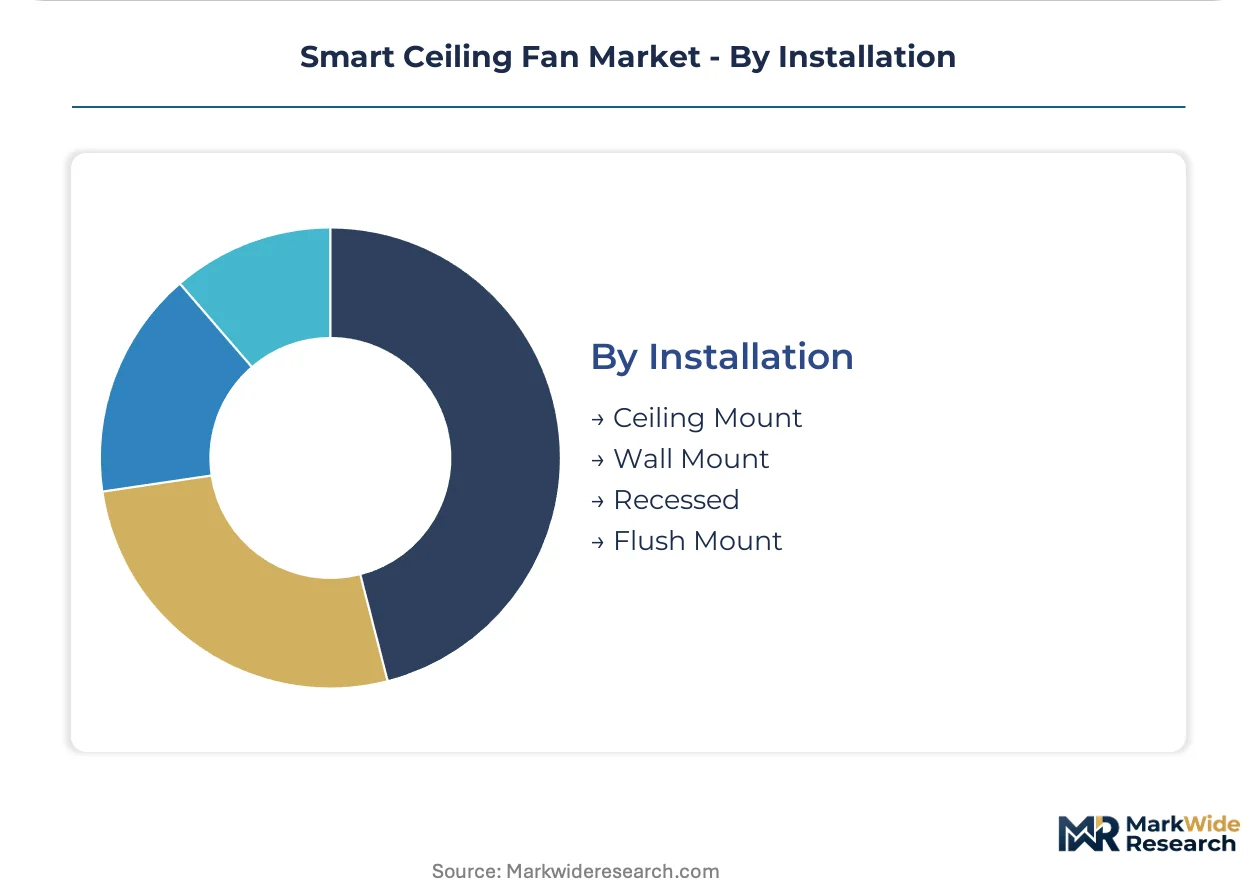
- Ceiling Mount:Standard downrod suspension accommodates sloped ceilings and varying room heights. This configuration dominates residential retrofits and remains the default specification across all end-user segments.
- Wall Mount:Vertical orientation suits spaces with low ceiling clearance or specialized ventilation needs. Industrial kitchens and covered outdoor areas specify these for targeted airflow delivery.
- Recessed:Flush integration with ceiling planes delivers minimalist aesthetics for premium residential and hospitality interiors. Installation demands precise rough-in coordination during construction phases.
- Flush Mount:Low-profile housings suit rooms with ceiling heights below eight feet. Multi-unit residential developers in dense urban markets specify these to maximize perceived spatial volume.
Ceiling mount leads by installation count. Recessed is gaining share fastest in luxury hospitality development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BIS energy labeling mandates anchor demand compression in India, while Wi-Fi module cost collapses in Guangdong manufacturing clusters reshape procurement economics across North American residential channels.
United States
Texas and Florida homebuilders specify brushless DC motor platforms as standard in new construction, eliminating aftermarket retrofit opportunities for external speed controllers. The US Inflation Reduction Act tax credits for building electrification accelerate replacement cycles in aging office and retail stock. Silicon Valley smart home platform developers in California drive interoperability standardization through Matter protocol adoption.
China
Guangdong and Zhejiang provinces concentrate motor and PCB manufacturing zones that rewrite assembly economics through vertically integrated component supply. MIIT industrial policy supports dual carbon goals by incentivizing electronically commutated motor production over conventional AC induction platforms. Shenzhen and Dongguan control board fabricators supply over 70 percent of global smart fan controllers, exposing brands to single-region logistics concentration.
India
Residential builders scale smart home deployments under BIS star-rating mandates that disqualify conventional AC motor models from government procurement. The Bureau of Energy Efficiency compresses demand toward inverter-motor models qualifying for higher efficiency tiers in star-rated housing projects. Mumbai and Bangalore electrical contractors source brushless DC platforms through direct-to-installer channels bypassing traditional retail markup structures.
Germany
The EU Ecodesign Directive's 2024 tightened thresholds for electrically operated circulators force importers to recertify entire product lines or exit CE marking eligibility. German distributors consolidate supplier relationships around pre-certified inverter-motor platforms compliant with F-Gas Regulation restrictions on refrigerant-linked HVAC alternatives. Bavaria and North Rhine-Westphalia facility managers prioritize Building Management System integration for centralized energy dashboards in commercial retrofits.
Vietnam
Labor cost arbitrage and US tariff positioning pull final assembly from coastal China to Hai Phong and Ho Chi Minh City industrial zones. Vietnamese manufacturing migration accelerates as brands seek supply chain diversification away from Guangdong PCB concentration. Dong Nai Province electronics assemblers scale capacity for Wi-Fi enabled fan controller integration serving North American export demand.
Smart Ceiling Fan Market Competitive Landscape
Capability concentration sits with motor technology specialists; scale advantage sits with century-old retail brands with established North American channel presence. The vendor base organizes around three strategic archetypes: heritage brands leveraging brand equity for premium positioning, motor technology specialists differentiating on energy efficiency, and platform-native entrants exploiting Wi-Fi module cost collapses for smartphone-interoperable offerings. Dominant competitive moves include backward integration into brushless DC motor production and strategic partnerships with smart home platform developers for Matter protocol certification.
Within the heritage brand tier, Hunter Fan Company and Hunter Industrial occupy positions sustained through century-old retail channel relationships across North American home improvement networks. Among motor technology specialists, Atomberg exemplifies the brushless DC differentiation strategy targeting price-sensitive South Asian markets under BIS efficiency mandates. DREO represents the platform-native archetype exploiting ESP32 chipset cost structures for smartphone-interoperable residential installations.
| Leading Market Players |
|---|
| DREO |
| Big Ass Fans |
| Hunter Fan Company |
| WAC Lighting |
| Hunter Industrial |
| Atomberg |
| Smafan |
| Minka Aire |
| LG |
| Others |
Value Network & Pricing Analysis
Trans-Pacific container freight corridors from Shenzhen to Long Beach transmit Guangdong PCB cost compression into North American retail pricing tiers, while simultaneously amplifying margin differentiation between hub-dependent Zigbee commercial systems and direct-to-consumer Wi-Fi residential units.
Pricing Analysis
Geographic price spreads between US retail channels and Indian direct-to-installer procurement exceed three-to-one ratios for equivalent brushless DC motor specifications. Three-tier pricing structure across premium hospitality, standard commercial, and economy residential levels dominates transactional models, with differentiation anchored in BIS star-rating certification tiers and after-sales firmware support bundling. Pricing pressure stems from ESP32 chipset commoditization collapsing connectivity module costs. Residential landlords in Texas and Florida exhibit highest price sensitivity, while Dubai hotel operators absorb premium positioning for guest experience differentiation.
Supply Chain Analysis
Contract manufacturing concentration rests with Foxconn and Luxshare Precision facilities in Dongguan and Zhengzhou, supplemented by emerging Vietnamese EMS capacity in Hai Phong. Guangdong, Zhejiang, and Vietnam concentrate final assembly, drawing from neodymium magnet suppliers in Inner Mongolia and copper winding processors in Jiangxi. Single-region PCB fabrication vulnerability in Shenzhen-Dongguan corridors exposes brands to logistics disruptions. Distribution runs through home improvement retail chains, direct-to-installer electrical supply platforms, and hospitality procurement consortiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brushless DC motor control algorithm expertise represents the scarcest capability layer, with fewer than twelve engineering teams globally capable of integrating variable frequency drives with Matter protocol stacks at commercial scale.
For Market Incumbents: Build firmware security certification moats through UL 2900 and IEC 62443 validation investments that extend competitor launch timelines by four to six months. Consolidate supplier relationships around pre-certified inverter-motor platforms to preempt EU Ecodesign Directive recertification failures. Channel control through Procore and similar trade-specific marketplaces defends against direct-to-installer disintermediation threats. For New Entrants and Emerging Players: Mid-market commercial buildings in Vietnam and Indonesia represent the most penetrable entry point, where US tariff positioning and labor cost arbitrage create procurement preference for non-Chinese assembly. Bluetooth-enabled residential units in South Asian secondary cities bypass Wi-Fi infrastructure gaps. Go-to-market through electrical contractor co-development programs bypasses retail markup capture. For Investors and Strategic Acquirers: Motor control IP specialists with captive brushless DC design capabilities and existing BIS certification trajectories offer the strongest acquisition profile for long-term viability. Platform-native entrants exploiting ESP32 cost structures but lacking motor expertise face consolidation pressure as Matter protocol convergence collapses hub-based differentiation. Monitor Matter certification completion rates as inflection indicator for ecosystem lock-in durability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brushless DC Motors | Captive motor production insulates margins from neodymium and copper volatility while satisfying BIS mandates. |
| Matter Protocol Certification Investment | Unified interoperability standards collapse platform fragmentation and reduce hub-specific R&D duplication. |
| Vietnamese Manufacturing Migration | Hai Phong and Ho Chi Minh City assembly diversifies supply chain exposure from Guangdong concentration. |
| Direct-to-Installer Channel Development | Procore and electrical supply platform partnerships bypass retail markup in multi-unit residential projects. |
| Firmware Security Certification Acceleration | UL 2900 and IEC 62443 validation extends product launch timelines for competitors without equivalent investment. |
Research Methodology
The analysis maps Wi-Fi residential, Zigbee commercial, and Bluetooth entry-level segments, each validated through electrical contractor interviews, hospitality procurement directors, smart home platform engineers, and motor control specialists. Primary fieldwork combined with secondary validation from BIS certification databases, EU Ecodesign Directive filings, SEC equipment manufacturer disclosures, and customs trade data. Bottom-up unit shipment estimates triangulated against top-down energy efficiency mandate penetration models.
Assumptions held BIS star-rating tier thresholds and Matter protocol adoption curves fixed across the analysis window, while varying copper and rare earth input cost scenarios. Segmentation dimensions modeled include connectivity protocol, motor architecture, end-user vertical, installation configuration, and regional regulatory cluster. CAGRs derived from install-base replacement cycle analysis and new construction penetration elasticity. Forecast inputs incorporated HVAC substitution pressure from F-Gas Regulation restrictions and Inflation Reduction Act tax credit utilization rates.
Practitioners should monitor neodymium magnet price volatility, Guangdong logistics disruption indices, and Matter certification completion rates for early signals of forecast revision necessity. Quarterly review of BIS mandate enforcement intensity, EU Ecodesign recertification failure rates, and Vietnamese EMS capacity expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Small Electric Kettles Market
Appliances
Bathroom Heaters Market
Appliances
US Electric Rice Cooker Market
Appliances
Washing Appliances Market
Appliances
Israel Laundry Appliances Market
Appliances
China Washing Machine Market
Appliances
Colombia Appliances and Electronics Market
Appliances
South Africa Laundry Appliances Market
Appliances
United Kingdom Tumble Dryers Market
Appliances
Mini Washing Machine Market
Appliances
Small Appliances Market
Appliances
Microwave Market
Appliances
Fully Automatic Dishwasher Market
Appliances
United States Microwave Oven Market
Appliances
GCC Microwave Oven Market
Appliances
Portable Fridges Market