
 Smart Bathroom Market | 2026-2036
Smart Bathroom Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Bathroom Market Intelligence
China's Guangdong province is narrowing its cost gap with European smart fixture production through automated ceramic forming and IoT module assembly. TOTO leverages vertically integrated porcelain manufacturing to sustain quality consistency across its Washlet lines. Kohler anchors North American distribution through exclusive builder partnerships and direct-to-contractor digital portals. Geberit competes in concealed cistern and flush plate integration, a niche where European plumbing standards create technical barriers.
Smart bathrooms integrate sensor networks, microprocessor-controlled water delivery, and connected hygiene systems into residential and commercial washroom environments, with ceramic vitrification firing at 1,200°C ensuring durability of electronically embedded fixtures. The primary purpose centers on water conservation, personalized user profiles, and operational data capture for facility management. Smart toilets dominate value pools due to electromechanical complexity and replacement cycles, while intelligent showers represent the fastest-expanding segment as Bluetooth-enabled thermostatic valves penetrate wellness center retrofits. Voice recognition technology remains nascent in hospitality suites but carries premium pricing potential where multilingual guest interfaces justify integration costs.
FCC certification governs wireless connectivity modules in US-imported fixtures, while CE marking and EU Ecodesign water-flow limits shape product development for European export qualification. China's GB standards for electronic sanitation appliances, administered by SAMR, mandate safety testing for heated seats and automatic lid mechanisms. Stakeholders must monitor divergence between regional cybersecurity protocols for IoT-enabled fixtures and evolving water-efficiency thresholds that threaten to obsolete non-compliant installed bases.
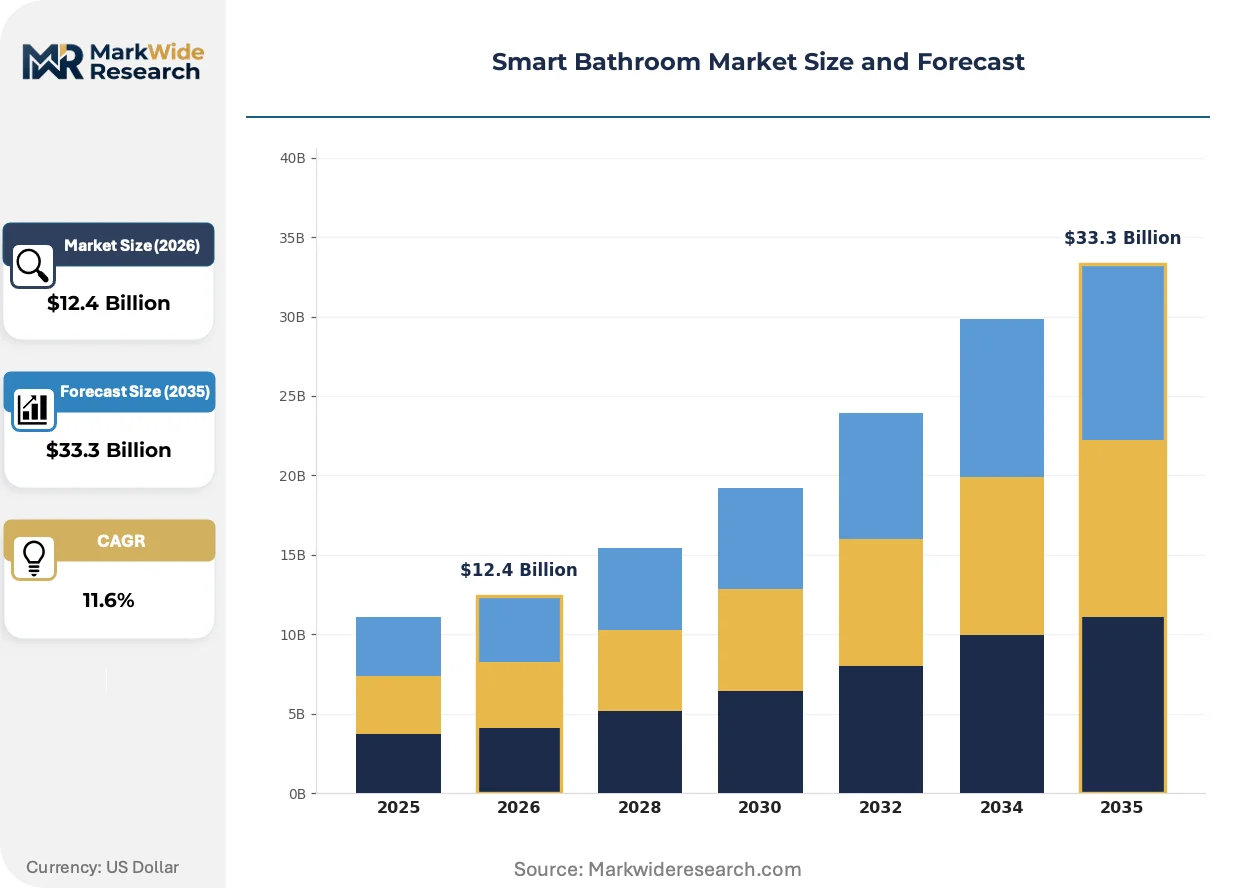
Market Dynamics
Water-efficiency mandates under EPA WaterSense and EU Ecodesign are compressing replacement cycles for conventional fixtures while sensor-activated systems capture specification share in new construction and hospitality retrofits.
Growth Catalysts
- EPA WaterSense Certification:Federal procurement preferences and rebate programs accelerate specification of sensor-activated faucets and dual-flush systems in US commercial buildings.
- Hospitality Wellness Suites:Dubai and Singapore luxury properties deploy connected hygiene systems to differentiate guest experiences and capture operational data.
- Automated Ceramic Forming:Guangdong manufacturers narrow cost differentials through robotic vitrification and in-house IoT module assembly.
Market Restraints
- Semiconductor Supply Concentration:Microcontroller and MEMS sensor sourcing concentrates in Taiwan and South Korea, exposing fixture assemblers to allocation volatility.
- Installation Skill Thresholds:Concealed cistern and flush-plate integration demands certified plumbing contractors, limiting retrofit penetration in aging building stock.
- Legacy Fixture Longevity:Conventional porcelain fixtures operate 20-30 year lifespans, delaying replacement demand despite efficiency advantages.
Strategic Opportunities
- EU Ecodesign Water-Flow Limits:Tightening thresholds for showerheads and taps create compliance-driven replacement waves across German and French residential stock.
- Voice Recognition Convergence:Integration of multilingual guest interfaces in hospitality suites unlocks premium pricing for fixture OEMs with embedded NLP capabilities.
- Direct-to-Contractor Digital Portals:Builder-exclusive distribution models bypass traditional wholesale channels, capturing specification decisions earlier in project timelines.
Industry Challenges
- Cybersecurity Protocol Divergence:IoT-enabled fixtures face fragmented regional certification requirements for data transmission security, complicating platform development.
- Electromechanical Integration Complexity:Heated seats, automatic lid mechanisms, and sensor networks demand cross-functional engineering teams spanning ceramics, electronics, and fluid dynamics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Bathroom Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $33.3 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Toilets, Intelligent Showers, Connected Faucets, Automated Mirrors, Sensor-Activated Lighting Technology: Internet of Things, Voice Recognition, Motion Sensors, Bluetooth Connectivity, Touchscreen Interface Application: Residential Homes, Hospitality Suites, Wellness Centers, Luxury Spas, Smart Apartments End User: Homeowners, Hotels & Resorts, Fitness Facilities, Real Estate Developers, Facility Managers |
| Companies Covered | LIXIL, Villeroy & Boch, TOTO, American Standard, Panasonic, Kohler, Geberit, Grohe, Duravit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Bathroom Market Strategic Shifts & Innovations
Bluetooth-enabled thermostatic valves are penetrating wellness center retrofits while regulatory water-flow limits force hardware redesigns and procurement patterns shift toward specification-grade bundled systems.
Thermostatic valve technology with embedded Bluetooth connectivity is collapsing the distinction between residential and commercial shower hardware specifications. Wellness centers and boutique fitness chains specify these valves for remote temperature preset and usage analytics. The technology is collapsing price bands between premium residential and mid-tier commercial product lines as volume manufacturing scales.
EU Ecodesign water-flow limits for taps and showerheads are forcing hardware redesigns across European export portfolios. Manufacturers must re-engineer aerator geometries and valve orifices to maintain user experience within mandated consumption ceilings. German and French sanitary ware producers face compressed development timelines to qualify redesigned product families before enforcement phases tighten.
Specification decisions are migrating from wholesale distributors to direct contractor and builder relationships, disrupting traditional channel economics. Digital portals with real-time inventory and project-specific pricing capture specification authority earlier in construction workflows. This pattern concentrates in North American residential construction where national builders standardize fixture packages across multi-unit developments.
Smart Bathroom Market Segmentation
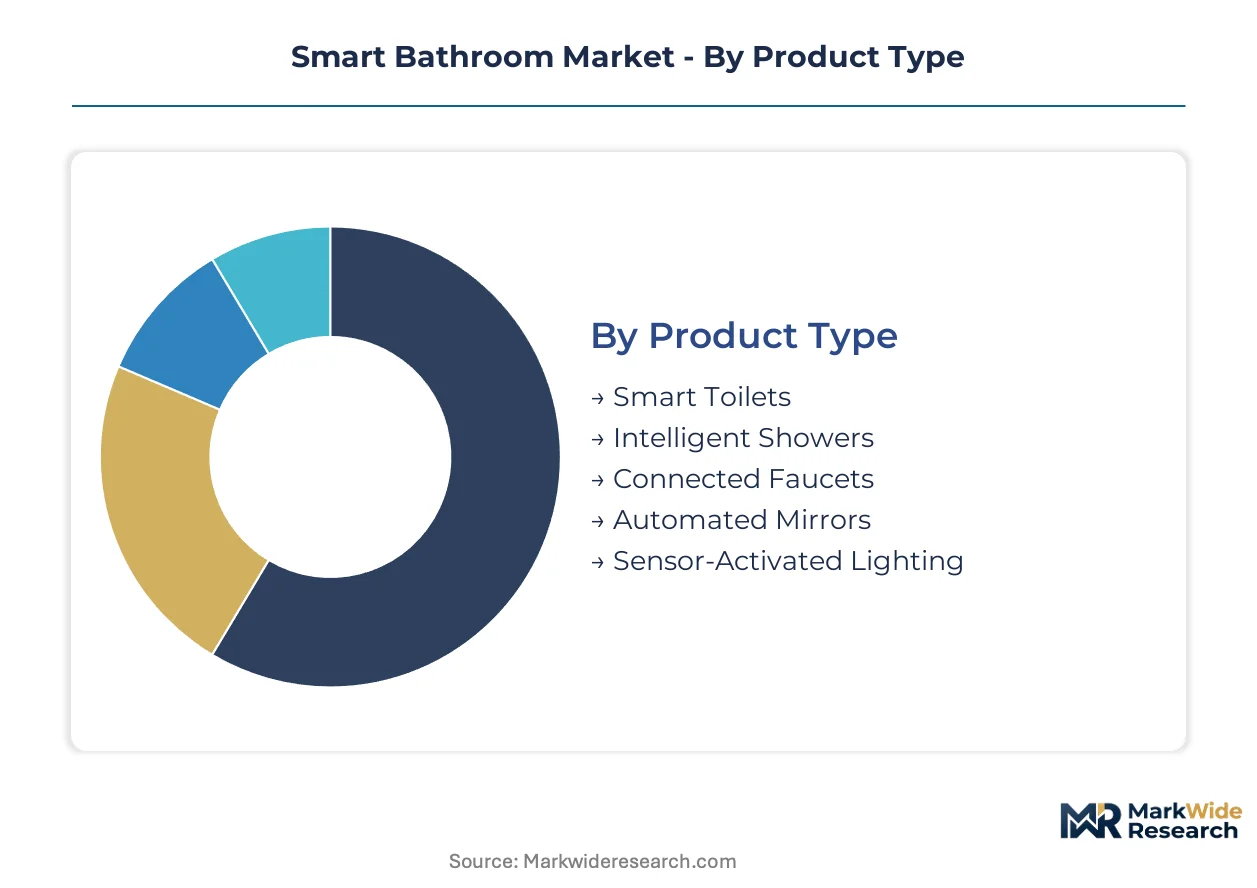
Smart bathroom segmentation tracks how electromechanical complexity, connectivity protocols, and installation requirements fragment demand across price bands and use cases. Fixture OEMs configure product portfolios around ceramic forming capabilities, sensor integration depth, and regulatory compliance tiers rather than simple feature checklists.
Product Type:
Cost tier stratification in smart fixtures separates electromechanically intensive products from passive connected hardware, with premium capture concentrated in systems requiring heated components and precision fluid control.
- Smart Toilets:Ceramic vitrification at 1,200°C embeds heated seats, automatic lid mechanisms, and integrated bidet functions within porcelain housings. Hospitality suites in Dubai and Singapore specify these for guest experience differentiation and operational data capture.
- Intelligent Showers:Bluetooth-enabled thermostatic valves with microprocessor-controlled water delivery enable remote temperature presets and usage analytics. Wellness centers and boutique fitness chains drive specification as these systems collapse price bands between premium residential and mid-tier commercial lines.
- Connected Faucets:Sensor-activated water delivery with EPA WaterSense certification targets federal procurement preferences and commercial rebate programs.
- Automated Mirrors:Anti-fog heating elements and integrated lighting controls serve luxury residential and hospitality vanity installations.
- Sensor-Activated Lighting:Motion-triggered illumination systems complete connected bathroom ecosystems with lower electromechanical complexity.
Smart toilets hold installed capacity. Intelligent showers are rotating up the share rankings.
Technology:
Application context determines which connectivity protocols and interface modalities justify integration costs, with multilingual hospitality environments demanding more sophisticated interaction layers than residential installations.
- Internet of Things:Embedded sensor networks and cloud connectivity enable facility management dashboards and predictive maintenance algorithms. EU Ecodesign compliance and cybersecurity protocol divergence complicate platform development for fixtures serving multiple export markets.
- Voice Recognition:Natural language processing capabilities support multilingual guest interfaces in premium hospitality suites. The technology carries premium pricing potential where operational complexity justifies integration investment.
- Motion Sensors:MEMS-based activation triggers water delivery and lighting without physical contact, reducing pathogen transmission risk in high-traffic facilities.
- Bluetooth Connectivity:Short-range wireless protocols enable smartphone-based control and usage logging without full IoT infrastructure requirements.
- Touchscreen Interface:Direct digital control panels concentrate in high-end residential and luxury spa environments where user customization justifies cost premiums.
Internet of Things systems anchor current specification volumes. Voice recognition is climbing the fastest as hospitality chains standardize guest experience platforms.
Application:
Volume concentration varies sharply by installation complexity, with new construction and full-gut renovations absorbing concealed cistern systems that aging building stock cannot accommodate.
- Residential Homes:Single-family and multi-unit housing drives replacement cycles for conventional fixtures approaching end-of-life. German residential stock faces compliance-driven replacement waves as EU Ecodesign water-flow limits tighten.
- Hospitality Suites:Luxury properties deploy connected hygiene systems to differentiate guest experiences and capture operational efficiency data. Singapore and Dubai developments anchor specification demand for integrated voice and sensor platforms.
- Wellness Centers:Boutique fitness chains specify Bluetooth-enabled thermostatic valves for remote temperature control and usage analytics.
- Luxury Spas:High-touch environments demand full-spectrum automation including intelligent showers, connected faucets, and automated mirrors.
- Smart Apartments:Build-to-rent developments standardize fixture packages across multi-unit projects, concentrating procurement authority with national builders.
Residential homes maintain the largest installed base. Hospitality suites are gaining share fastest on wellness-driven capital expenditure.
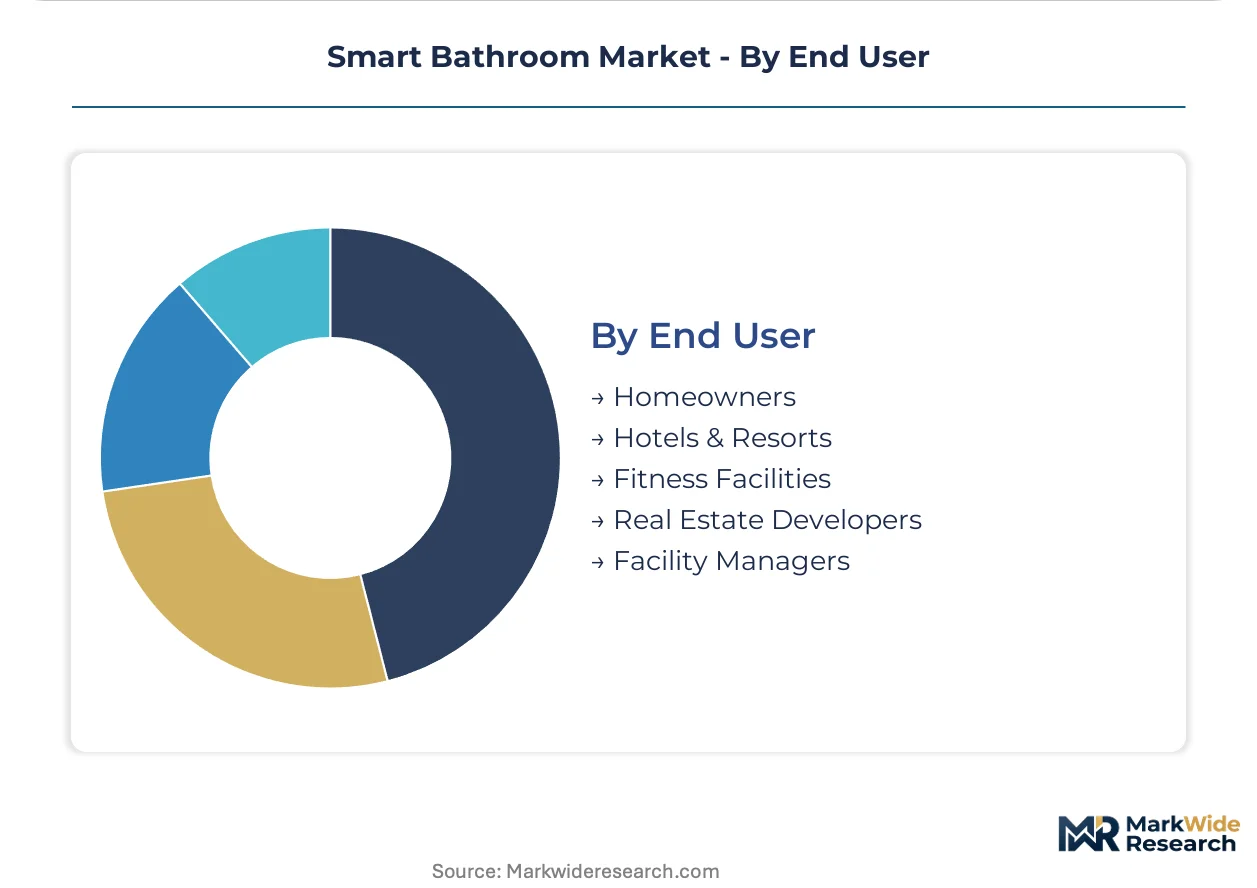
End User:
Customer type shapes procurement channel preferences, with direct-to-contractor digital portals displacing traditional wholesale distribution for project-based buyers.
- Homeowners:Individual purchasers prioritize ease of installation and retrofit compatibility over full-system integration. Aging building stock limits concealed cistern penetration.
- Hotels & Resorts:Brand-standardized procurement across property portfolios concentrates volume with fixture OEMs offering global specification support and multilingual interface capabilities.
- Fitness Facilities:Wellness centers prioritize Bluetooth-enabled shower systems for member experience differentiation and operational data capture.
- Real Estate Developers:National builders standardize fixture packages across multi-unit residential developments, migrating specification decisions to digital portals with real-time inventory.
- Facility Managers:Commercial building operators demand IoT-enabled systems for water consumption monitoring and predictive maintenance scheduling.
Hotels and resorts command premium pricing tiers. Real estate developers are rotating up the share rankings on build-to-rent expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA WaterSense certification anchors the United States as the dominant geography, with federal procurement preferences and rebate programs accelerating sensor-activated fixture adoption in commercial buildings.
United States
Federal buildings mandate EPA WaterSense-certified fixtures, compressing replacement cycles for conventional hardware. The EPA administers rebate programs that tilt specification toward dual-flush and sensor-activated systems. Dallas and Miami hospitality retrofits deploy connected hygiene platforms for operational data capture.
Germany
EU Ecodesign water-flow limits force hardware redesigns across residential and commercial portfolios. The country's national regulator enforces tightening thresholds for taps and showerheads ahead of phased compliance deadlines. North Rhine-Westphalia manufacturing clusters anchor production of concealed cistern and flush-plate integration systems.
China
Guangdong province narrows cost gaps with European production through automated ceramic forming and in-house IoT module assembly. SAMR administers GB standards for electronic sanitation appliances including heated seat safety testing. Shenzhen and Foshan concentrate robotic vitrification capacity for export-qualified fixture manufacturing.
Japan
Wellness center retrofits drive specification of electromechanically intensive toilet systems with integrated bidet functions. METI oversees JIS standards for connected sanitation appliances and energy efficiency labeling. Kitakyushu ceramic clusters sustain vertically integrated porcelain manufacturing for quality consistency.
Singapore
Luxury hospitality suites deploy voice-recognition and sensor platforms to differentiate guest experiences in competitive tourism markets. The country's national building regulator enforces water efficiency labeling for sanitary ware imports. Marina Bay and Sentosa developments concentrate premium specification demand for multilingual interface systems.
Smart Bathroom Market Key Industry Players
Capability concentration sits with European specialists mastering concealed cistern integration; scale advantage sits with Asia-Pacific manufacturers leveraging automated ceramic forming. The market structures around three tiers: premium fixture OEMs with vertically integrated porcelain operations, mid-tier assemblers sourcing MEMS sensors and microcontrollers from Taiwan and South Korea, and private-label fabricators serving retail channels. Dominant competitive moves include direct-to-contractor digital portal development and backward integration into IoT module assembly to reduce semiconductor allocation exposure.
Within the premium tier, LIXIL Corporation and TOTO Ltd. exemplify vertically integrated specialists controlling porcelain manufacturing and electromechanical assembly. Kohler Co. occupies a position among North American scale players anchoring distribution through builder-exclusive relationships. Grohe AG represents German engineering-focused fabricators competing on concealed system integration where European plumbing standards create technical barriers.
| Leading Market Players |
|---|
| LIXIL |
| Villeroy & Boch |
| TOTO |
| American Standard |
| Panasonic |
| Kohler |
| Geberit |
| Grohe |
| Duravit |
| Others |
Cost & Logistics Intelligence
Automated ceramic forming overcapacity in Guangdong province compresses supplier margins while accelerating price convergence between Asia-Pacific and European fixture production. This utilization imbalance forces manufacturers to absorb component cost volatility or sacrifice market share in specification-grade segments.
Pricing Analysis
Geographic price spreads between German-engineered concealed cistern systems and Guangdong-assembled alternatives have narrowed to sub-20% differentials at equivalent certification tiers. Pricing stratifies across premium, standard, and economy tiers based on electromechanical complexity and EPA WaterSense or EU Ecodesign qualification status. Cost compression in mid-tier sensor-activated faucets is intensifying because MEMS sensor allocation volatility forces assemblers to discount finished goods. Real estate developers exhibit highest price sensitivity due to standardized multi-unit procurement volumes, while hospitality chains prioritize multilingual interface capabilities over unit economics.
Supply Chain Analysis
Extended payment terms from European fixture OEMs to Taiwanese semiconductor suppliers have compressed working capital cycles throughout the tiered supplier base. Microcontroller and MEMS sensor sourcing concentrates in Taiwan and South Korea, while ceramic vitrification capacity clusters in Guangdong and North Rhine-Westphalia. Supply chain risk centers on single-source vulnerability for precision thermostatic valve components. Distribution runs through direct-to-contractor digital portals that displace traditional wholesale channels in North American residential construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among national real estate developers standardizing fixture packages across build-to-rent portfolios. This procurement consolidation fragments specification authority away from traditional wholesale distributors.
For Market Incumbents: Harden defensive positions through backward integration into IoT module assembly to reduce semiconductor allocation exposure. Secure exclusive builder partnerships before specification decisions migrate entirely to digital procurement portals. Threat of concealed cistern installation skill thresholds limits retrofit penetration; lever is certification investment for EPA WaterSense and EU Ecodesign compliance to capture mandated replacement cycles. For New Entrants and Emerging Players: Aging residential building stock in Germany and France presents the most penetrable white-space for retrofit-compatible connected faucet systems bypassing concealed installation complexity. Target wellness center retrofits in Japan and boutique fitness chains specifying Bluetooth-enabled thermostatic valves for usage analytics. Go-to-market angle: direct-to-contractor digital portals with real-time inventory and project-specific pricing. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fixture OEMs with vertically integrated porcelain manufacturing and captive IoT platform development. Long-term viability across the analysis window favors specialists controlling ceramic vitrification at 1,200°C and electromechanical assembly under one roof. Acquisition target archetype: mid-tier assemblers with established concealed cistern integration capabilities but underdeveloped connectivity modules. Signal to watch: divergence between regional cybersecurity protocols for IoT-enabled fixtures forcing platform fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into IoT Module Assembly | Reduces semiconductor allocation exposure from Taiwan and South Korea suppliers. |
| Direct-to-Contractor Digital Portal Launch | Captures specification authority from wholesale distributors in North American residential construction. |
| EU Ecodesign Compliance Certification | Qualifies product families for German and French residential replacement waves. |
| Voice Recognition Platform Development | Unlocks premium pricing in Dubai and Singapore hospitality suites. |
| Automated Ceramic Forming Scale-Up | Narrows cost gaps with European production in Guangdong province. |
Research Approach
Desk research of regulatory filings, trade customs data, and sanitary ware certification databases preceded structured interviews with fixture OEM product managers, plumbing contractor procurement leads, hospitality facility directors, and semiconductor distribution specialists. Primary fieldwork captured specification decision timelines and channel migration patterns. Secondary validation drew from EPA WaterSense certification rosters, EU Ecodesign compliance declarations, and SAMR GB standard registrations. Bottom-up volume modeling triangulated against top-down market sizing across product type, technology, and application segments.
Assumption sets held regulatory enforcement timelines and semiconductor allocation patterns fixed while varying hospitality capital expenditure intensity and residential replacement cycle acceleration. The analytical framework modeled smart toilets, intelligent showers, connected faucets, and automated mirrors across residential, hospitality, wellness center, and smart apartment applications. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs included ceramic vitrification capacity utilization rates and voice recognition technology adoption curves in multilingual hospitality environments.
Macroeconomic conditions sit as an overlay; deviation in construction spending cycles or semiconductor supply normalization would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement stringency and hospitality sector capital allocation priorities. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
LAMEA Robotic Pool Cleaner Market
Household Items
Jet Hand Dryer Market
Household Items
Drinkware Market
Household Items
US Digital Showers Market
Household Items
Middle East and Africa Robotic Vacuum Cleaner Market
Household Items
Household Scales Market
Household Items
United States Smart Shower Market
Household Items
Global Electric Scissors Market
Household Items
USA Residential Cotton Candy Maker Market
Household Items
Portable Iron Market
Household Items
Dishwasher Tablets Market
Household Items
Paper Towel Dispenser Market
Household Items
India Non-Stick Cookware Market
Household Items
Germany Digital Showers Market
Household Items
Soap Tablet Market
Household Items
Italy Digital Showers Market