
 Fully Automatic Dishwasher Market | 2026-2036
Fully Automatic Dishwasher Market Size, Share, and Industry Trends Forecast 2026-2036
Fully Automatic Dishwasher Market Insights
Market Context
AI-driven sensor calibration is rewriting how fully automatic dishwashers optimize cycle parameters in real time. BSH Hausgeräte leverages its captive testing infrastructure in Germany to validate algorithmic wash protocols before regional rollout. Samsung Electronics anchors smart-home integration through proprietary IoT ecosystems that sync dishwasher operations with broader appliance networks. Miele differentiates through in-house production of stainless-steel wash arms and pump assemblies that command premium positioning in European markets.
Technical Definition and Segment Structure
A fully automatic dishwasher is a self-contained electromechanical appliance that sprays heated water and detergent across soiled dishware through rotating wash arms, then rinses and dries loads without manual intervention; core specifications include water consumption below 3.5 gallons per cycle and noise thresholds measured in decibel ratings for residential certification. Built-in units dominate value pools in North American and European residential construction, while drawer configurations capture renovation-driven demand where cabinet retrofit constraints limit standard cavity dimensions. The commercial end-user segment concentrates procurement among multi-unit hospitality operators who negotiate fleet pricing tied to energy-efficient technology tiers and hygiene cycle certifications required by food safety inspectors.
Regulatory Framework
The EPA Energy Star program and DOE minimum efficiency standards govern water and electricity consumption thresholds for residential units sold in the United States, while the EU Ecodesign Directive and F-Gas Regulation constrain refrigerant-based drying systems and mandate recycled material content disclosures. These frameworks compel manufacturers to redesign thermal management systems and validate compliance through third-party testing before market access. Stakeholders must monitor how emerging state-level water restrictions in the western United States and proposed amendments to EU energy labeling rules will reshape R&D allocation between condensation drying and heat-pump alternatives.
Market Dynamics
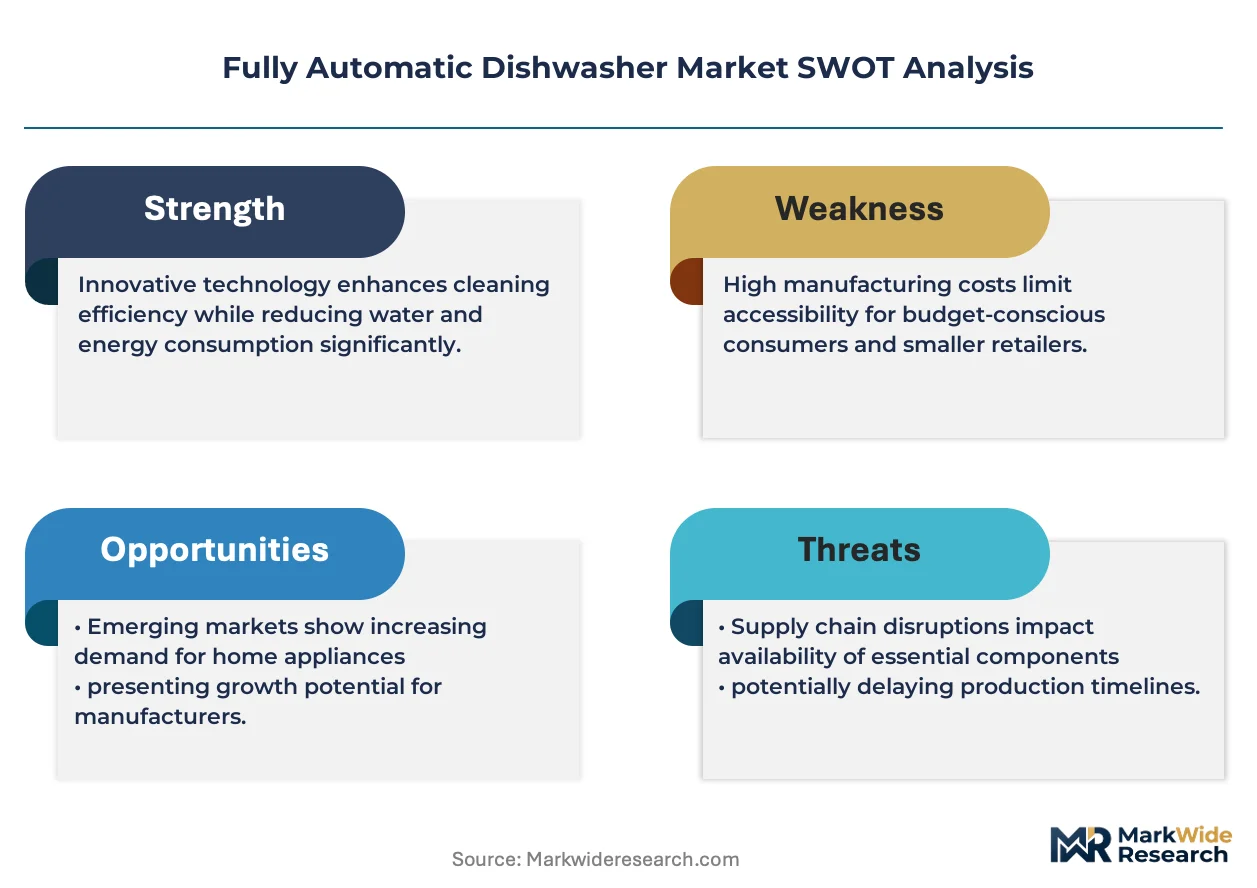
Water-efficiency mandates in California and the European Union are compressing replacement cycles across the hospitality sector, forcing manufacturers to redesign thermal management systems around heat-pump and condensation drying architectures before third-party certification gates.
Growth Catalysts
- EU Ecodesign Directive:Mandates on recycled material content and F-Gas constraints push manufacturers toward heat-pump drying systems, creating upgrade demand across European commercial kitchens.
- AI-driven sensor calibration:Real-time cycle optimization algorithms reduce water consumption below 3.5 gallons per cycle, satisfying EPA Energy Star thresholds for residential certification in the United States.
- Hospitality fleet procurement:Multi-unit operators negotiate volume pricing tied to energy-efficient technology tiers, accelerating replacement of legacy units in Germany and California.
Market Restraints
- Stainless-steel input volatility:In-house production of wash arms and pump assemblies requires captive stainless-steel supply, exposing margins to commodity price swings.
- German manufacturing concentration:Premium production clusters around BSH Hausgeräte and Miele testing infrastructure create geographic supply risk for algorithmic validation pipelines.
- Refrigerant-based drying phase-out:EU F-Gas Regulation constraints force complete thermal system redesigns, extending R&D timelines before market access.
Strategic Opportunities
- Drawer configuration retrofit:Cabinet dimension constraints in renovation-driven residential markets favor compact form factors over standard built-in cavities.
- IoT ecosystem convergence:Smart-home integration protocols enable sync between dishwashers and broader appliance networks, creating service revenue streams.
- Western US water restrictions:Emerging state-level mandates beyond California create regulatory tailwinds for sub-3.5-gallon cycle technologies.
Industry Challenges
- Algorithm validation timelines:Captive testing infrastructure requirements in Germany delay regional rollout of AI-driven wash protocols.
- Heat-pump integration complexity:Legacy condensation drying supply chains require reconfiguration to accommodate new thermal architectures.
- Third-party certification bottlenecks:DOE minimum efficiency standards and EPA Energy Star validation create compliance backlogs for redesigned units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fully Automatic Dishwasher Market |
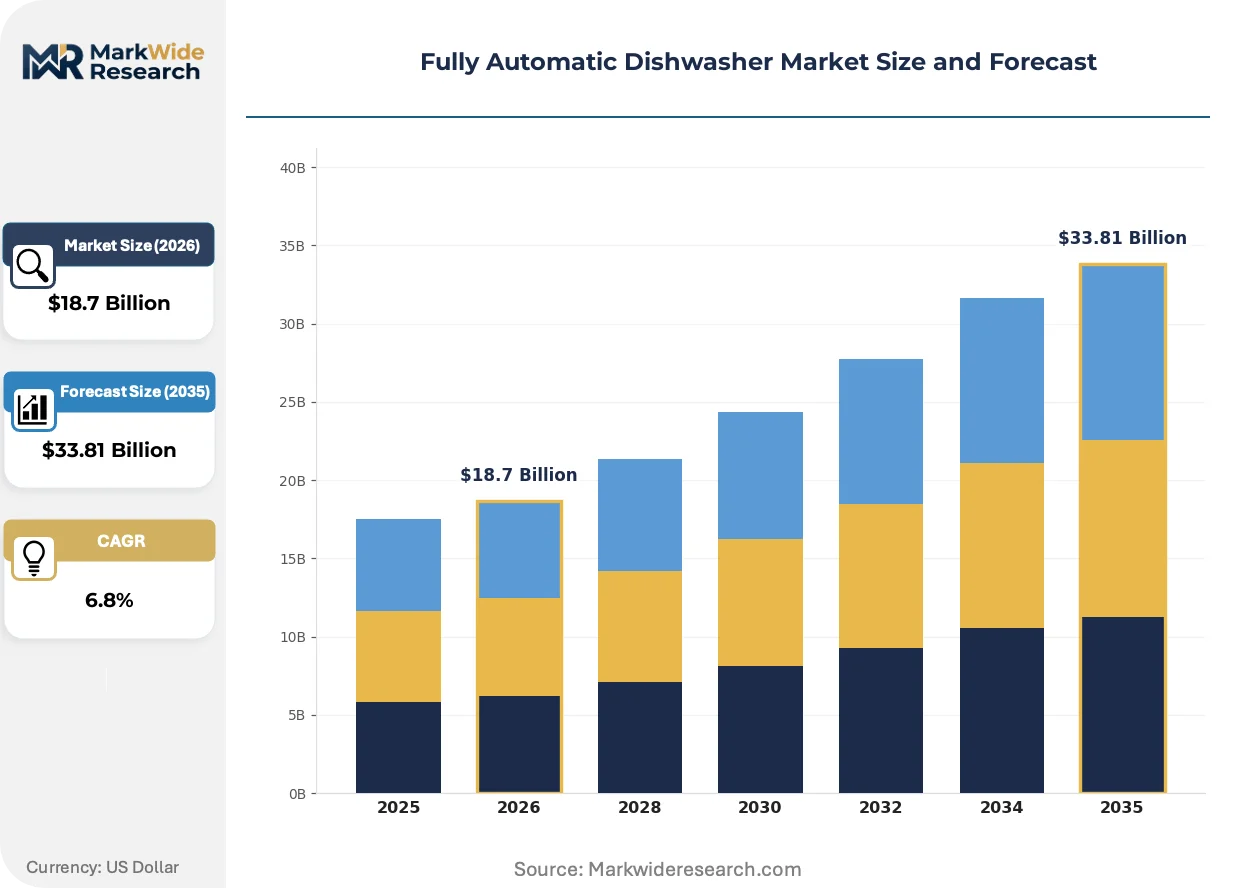
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Built-In, Drawer, Portable End User: Residential, Commercial, Hospitality, Institutional Technology: Smart, Traditional, Energy Efficient, Standard Feature: Noise Reduction, Quick Wash, Water Softener, Hygiene Cycle |
| Companies Covered | Whirlpool Corporation, BSH Hausgeräte GmbH, Samsung Electronics, LG Electronics, Electrolux AB, Haier Smart Home, Miele, GE Appliances, ASKO Appliances, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fully Automatic Dishwasher Market Trends and Innovations
Sensor fusion and connectivity protocols are rewriting how dishwashers interact with building management systems and residential IoT networks, compressing the boundary between standalone appliances and integrated home infrastructure.
Machine learning algorithms embedded in wash-cycle controllers analyze soil density and water turbidity in real time. High-end residential buyers in Germany and the United States are specifying these units in new construction at accelerating rates. This capability is digitizing the traditional trade-off between cycle duration and cleaning efficacy, collapsing the premium-mid-economy performance gap.
The EU F-Gas Regulation is eliminating refrigerant-based drying systems from new product introductions. Manufacturers are redirecting R&D allocation toward heat-pump alternatives and condensation drying with advanced moisture extraction. Commercial end-users in European hospitality face the steepest compliance deadlines, compressing procurement decisions into shorter evaluation windows.
Buyers in renovation markets are rejecting standard built-in dimensions in favor of drawer configurations that accommodate existing cabinet cavities. Kitchen designers and contractors are specifying these units in retrofit projects across North American and European urban cores. This pattern is most visible in secondary cities where housing stock predates modern kitchen standards.
Fully Automatic Dishwasher Market Segmentation
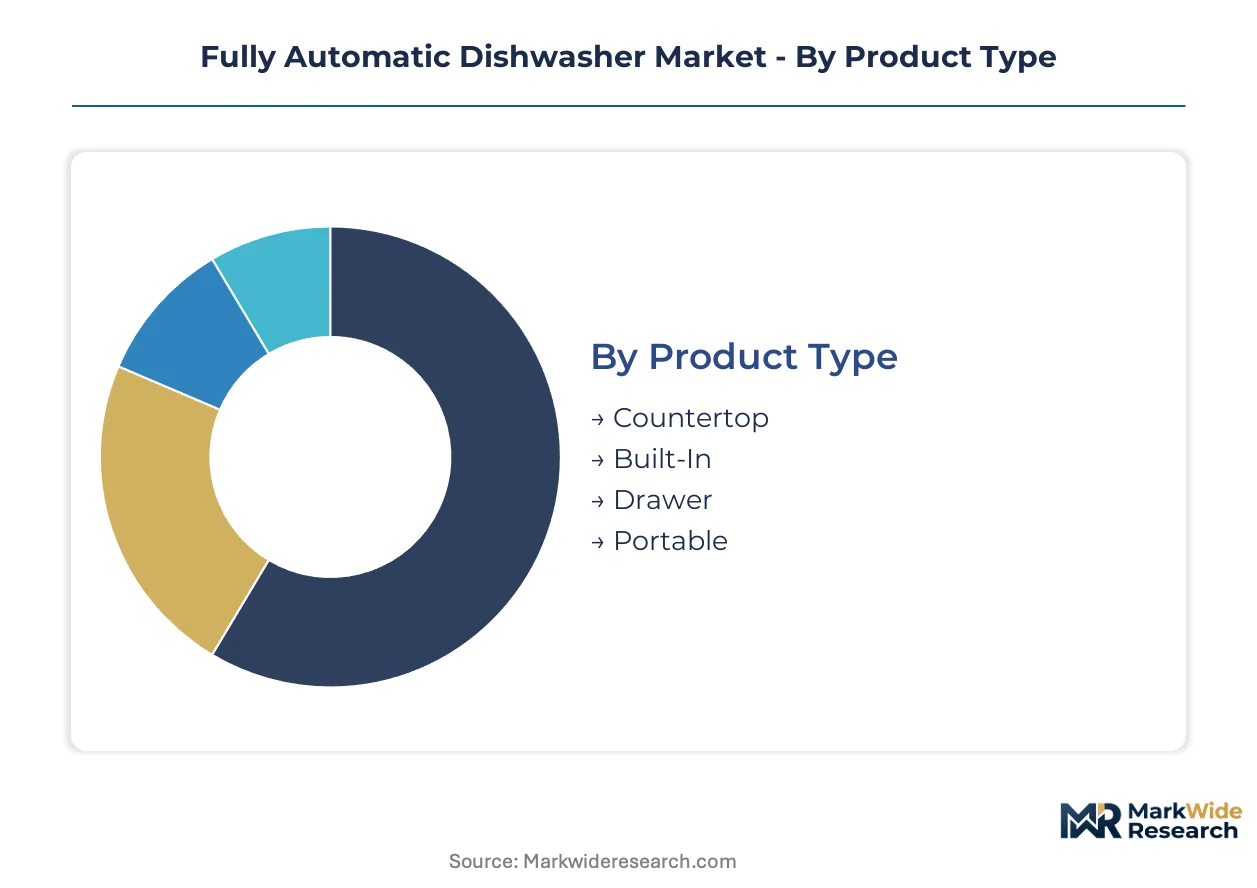
Segmentation in the fully automatic dishwasher market reveals how form factor constraints, end-use hygiene mandates, and energy certification tiers reshape procurement patterns across residential renovations and commercial fleet replacements. Understanding these divides exposes where technology premiums concentrate and where standardization pressures dominate.
Product Type:
Cost tier differentiation separates compact retrofit solutions from integrated new-construction installations, with cavity dimensions and plumbing infrastructure determining accessible price bands.
- Countertop:Compact units under 18 inches wide accommodate rental apartments and temporary installations where permanent plumbing modifications are prohibited. Demand clusters in Japanese urban cores and European secondary cities with pre-1940 housing stock, constrained by countertop load-bearing limits and drainage proximity requirements.
- Built-In:Standard 24-inch and 18-inch cavity units integrate beneath countertops with dedicated electrical and plumbing rough-ins. New residential construction in the United States and Germany specifies these units at accelerating rates, driven by builder incentives tied to EPA Energy Star certification thresholds and EU Ecodesign Directive compliance.
- Drawer:Dual-drawer or single-drawer configurations retrofit into existing cabinet dimensions without structural modification. Kitchen renovation contractors in North American urban cores favor these units where standard cavity depths exceed available space, particularly in pre-1980 housing stock.
- Portable:Castor-mounted units with temporary faucet connections serve rental markets and outdoor kitchen installations. Limited uptake outside North American multi-unit housing with restrictive lease terms on permanent appliance installation.
Built-In commands the established base. The steepest expansion runs through Drawer configurations.
End User:
Application-specific hygiene protocols and volume throughput requirements create divergent technology specifications across residential, commercial, and institutional procurement channels.
- Residential:Single-family and multi-family households prioritize noise thresholds below 44 decibels and water consumption below 3.5 gallons per cycle. German and US buyers in new construction specify smart-connected units with soil-sensor calibration at increasing rates.
- Commercial:Independent restaurants and catering operations require NSF International certification for food-contact surface sanitation and rapid cycle turnaround under 90 seconds per rack. California water-efficiency mandates are compressing replacement timelines for legacy high-volume units.
- Hospitality:Multi-unit hotel and resort operators negotiate fleet pricing tied to energy-efficient technology tiers and centralized IoT monitoring capabilities. EU F-Gas Regulation deadlines are forcing thermal system redesigns across European hospitality procurement.
- Institutional:Healthcare facilities, educational institutions, and government cafeterias mandate HACCP-aligned hygiene cycles with temperature logging for regulatory audit trails. Procurement concentrates through group purchasing organizations with extended warranty requirements.
Hospitality commands the established base. The steepest expansion runs through Institutional procurement channels.
Technology:
Volume-based tiering separates connected, algorithm-optimized units from basic electromechanical systems, with certification thresholds determining accessible market segments.
- Smart:Wi-Fi-enabled units with machine learning wash-cycle controllers analyze soil density and water turbidity in real time. Samsung Electronics and BSH Hausgeräte dominate this segment through proprietary IoT ecosystem integration.
- Traditional:Electromechanical timer-based systems without sensor feedback or connectivity capabilities. Persistent demand in price-sensitive replacement markets and regions with unreliable broadband infrastructure.
- Energy Efficient:Heat-pump drying architectures and advanced condensation systems meeting EU Ecodesign Directive and EPA Energy Star thresholds. Miele and premium European manufacturers anchor production clusters in Germany.
- Standard:Basic condensation drying with fixed-cycle programming, positioned below certification tiers for budget residential and commercial entry-level procurement.
Traditional commands the established base. The steepest expansion runs through Energy Efficient systems.
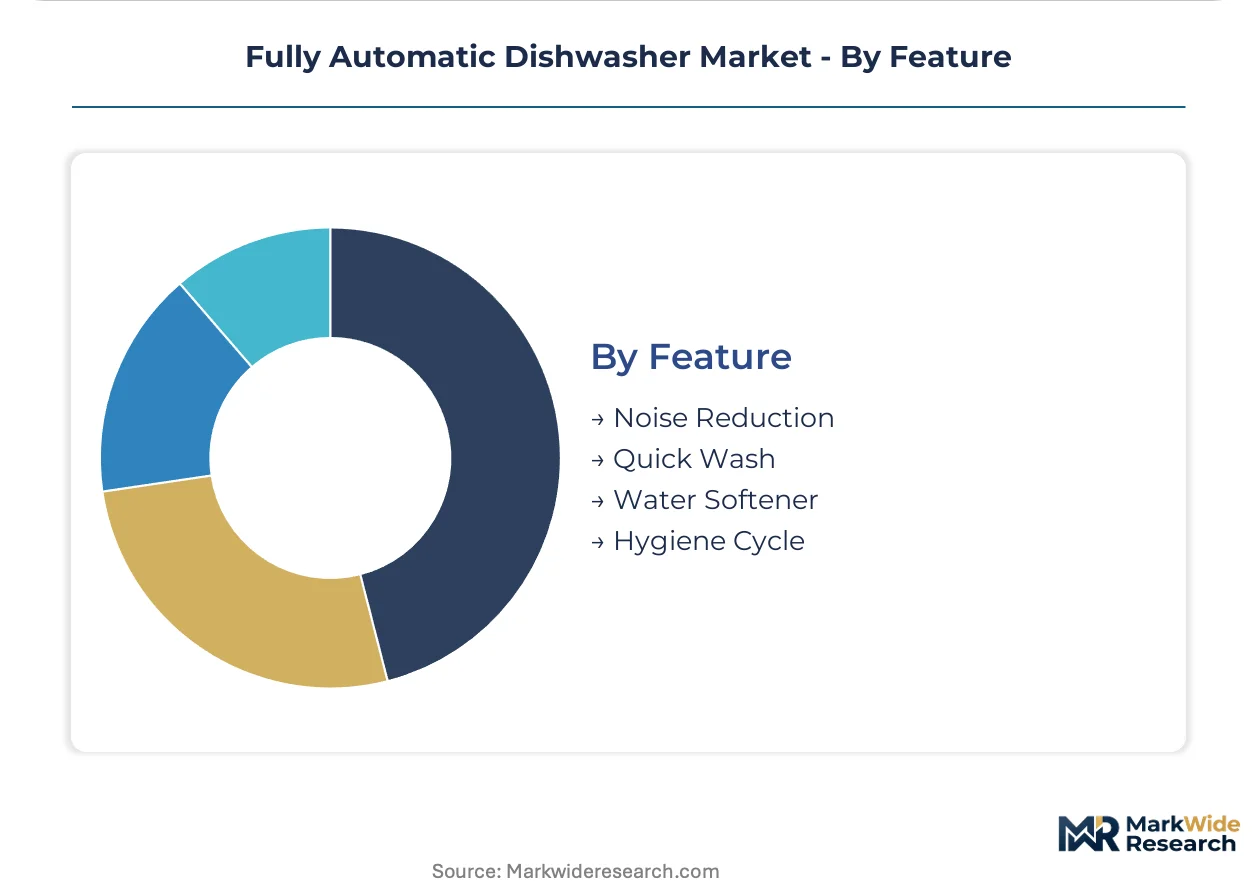
Feature:
Customer-type preferences for acoustic comfort, speed, water chemistry management, and pathogen control create modular upgrade pathways across product lines.
- Noise Reduction:Insulated wash chambers and variable-speed pumps achieving sub-42 decibel operation. Urban residential buyers in dense housing configurations prioritize this feature for open-plan kitchen layouts.
- Quick Wash:Accelerated 30-minute cycles sacrificing energy efficiency for speed. Single-person households and commercial lunch-rush operations specify this capability despite higher water consumption per item cleaned.
- Water Softener:Integrated ion-exchange resin systems preventing limescale accumulation in hard-water regions. Essential specification in UK southeast, US southwest, and Indian metropolitan areas with groundwater mineral content exceeding 300 ppm.
- Hygiene Cycle:NSF-certified high-temperature rinses exceeding 150°F for pathogen elimination. Healthcare institutional procurement and commercial foodservice operators in California and EU member states mandate this feature for regulatory compliance.
Water Softener commands the established base. The steepest expansion runs through Hygiene Cycle specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export heat-pump-equipped dishwashers to hospitality operators across California and the European Union, while Chinese producers supply compact countertop units to Japanese urban rental markets. Trade corridors concentrate premium thermal technology in Western regulatory jurisdictions and value-oriented configurations in Asia-Pacific density centers.
United States
California water-efficiency mandates and EPA Energy Star certification thresholds compress replacement cycles in commercial kitchens. The DOE minimum efficiency standards govern electricity consumption thresholds for residential units nationwide. Builder incentives in Texas and Florida accelerate smart-connected unit specification in new residential construction.
Germany
BSH Hausgeräte and Miele anchor premium manufacturing clusters with captive testing infrastructure for algorithmic wash protocols. The EU Ecodesign Directive and F-Gas Regulation constrain refrigerant-based drying systems and mandate recycled material content disclosures. Bavaria-based production facilities validate compliance through third-party certification before regional rollout.
China
MIIT efficiency standards and dual carbon goals redirect domestic production toward heat-pump architectures for export markets. Yangtze River Delta manufacturing clusters supply drawer configurations to North American renovation contractors. Shanghai and Shenzhen anchor smart-home integration development for IoT-enabled residential units.
Japan
METI energy conservation standards and compact housing stock drive demand for sub-18-inch countertop units in Tokyo and Osaka metropolitan areas. JIS certification requirements govern noise thresholds and water consumption metrics. Nagoya-based suppliers specialize in sensor-fusion technology for soil-density detection.
United Kingdom
Hard-water regions in the southeast specify integrated water-softener features to prevent limescale accumulation. The country's national energy regulator enforces efficiency labeling aligned with EU Ecodesign thresholds post-Brexit. London and Southeast England concentrate renovation-driven demand for drawer configurations in pre-1940 housing stock.
Fully Automatic Dishwasher Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered certification and connectivity vectors. The vendor base stratifies between scale-driven appliance conglomerates with captive retail distribution and precision-engineering specialists with in-house component production. Two dominant archetypes emerge: ecosystem-integrators leveraging proprietary IoT platforms, and thermal-technology specialists commanding premium positioning through heat-pump drying architectures. Competitive moves concentrate on vertical integration into stainless-steel component supply and strategic partnerships with hospitality fleet operators.
Within the ecosystem-integrator tier, Samsung Electronics and LG Electronics exemplify scale-driven players leveraging smart-home convergence. Among precision-engineering specialists, BSH Hausgeräte GmbH occupies a position representing German manufacturing concentration with captive testing infrastructure. Miele sits within the premium thermal-technology archetype, exemplifying in-house production capabilities for wash arms and pump assemblies.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| BSH Hausgeräte GmbH |
| Samsung Electronics |
| LG Electronics |
| Electrolux AB |
| Haier Smart Home |
| Miele |
| GE Appliances |
| ASKO Appliances |
| Others |
Pricing and Supply Chain Analysis
Stainless-steel input volatility determines both tiered pricing spreads across heat-pump and condensation-drying architectures and the geographic clustering of captive component production. Manufacturers with in-house wash-arm fabrication command premium positioning while exposed margins force standard-tier competitors toward modular outsourcing.
Pricing Analysis
Heat-pump-equipped next-generation units carry technology-generation premiums over prior-gen condensation systems and basic electromechanical configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with EPA Energy Star and EU Ecodesign thresholds creating discrete price bands. Cost compression in standard tiers is intensifying because Chinese producers supply drawer configurations to North American renovation contractors. Hospitality fleet operators show least price sensitivity, while rental-market countertop buyers demand entry-level positioning.
Supply Chain Analysis
Extended payment terms from Yangtze River Delta fabricators to German OEMs reveal supplier-financing dependencies that compress working-capital cycles. Manufacturing concentrates in China, Germany, and South Korea, with stainless-steel wash arms and pump assemblies drawing from captive foundries and commodity spot markets. Single-source vulnerability runs through Bavaria-based algorithm-validation infrastructure. Distribution runs through builder channels for new construction and kitchen-renovation contractors for retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart-home platform economics are displacing standalone appliance value capture, with interoperability protocols from Samsung and BSH Hausgeräte creating winner-take-most dynamics that favor ecosystem-integrated players over component specialists.
For Market Incumbents: Pre-empt margin erosion from Chinese drawer-configuration imports by securing captive stainless-steel supply through backward integration into Yangtze River Delta forging partnerships. Accelerate heat-pump R&D allocation before EU F-Gas Regulation deadlines harden compliance gates. Defend hospitality fleet relationships through centralized IoT monitoring capabilities that raise switching costs.
For New Entrants and Emerging Players: Build out countertop distribution in Japanese urban rental markets where METI standards and compact housing constraints limit incumbent reach. Target institutional procurement channels where HACCP-aligned hygiene cycles and extended warranty requirements create specification barriers for generalist competitors. Pursue group purchasing organization certification as the primary go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a regulatory-compliance inflection phase that favors thermal-technology specialists with validated heat-pump architectures over ecosystem-integrators facing platform-commoditization risk. Long-term viability hinges on component-level IP rather than connectivity software. Monitor EU Ecodesign Directive amendment timelines as the signal for R&D allocation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Manufacturing Scale-Up | EU F-Gas Regulation deadlines force thermal-system transitions before market-access gates. |
| Smart-Home Platform Integration | Proprietary IoT ecosystems from Samsung and BSH Hausgeräte raise competitor switching costs. |
| Stainless-Steel Component Backward Integration | In-house wash-arm production shields margins from commodity volatility and supply disruption. |
| Hospitality Fleet Partnership | Multi-unit operators negotiate volume pricing tied to energy-efficient technology tiers. |
| Drawer Configuration Geographic Expansion | North American renovation contractors favor retrofit-compatible form factors in pre-1980 housing stock. |
Research Methodology
A standing panel of appliance manufacturing executives, hospitality procurement directors, kitchen-renovation contractors, and regulatory compliance officers provided ongoing calibration against secondary validation from SEC filings, EPA Energy Star certification databases, EU Ecodesign Directive implementation reports, and customs trade records. Bottom-up shipment data triangulated against top-down construction-permit analysis across the analysis window.
Scenario-bracketing around regulatory amendment timelines and commodity-price bands anchored the projection framework across product type, end user, technology tier, and regional adoption-pattern dimensions. CAGRs derived from segment-level volume trajectories weighted by replacement-cycle compression in California and EU hospitality markets. Forecast inputs incorporated water-efficiency mandate stringency indices and heat-pump cost-curve assumptions.
Practitioners should monitor EU F-Gas Regulation enforcement intensity and western US state-level water-restriction propagation for early signals of thermal-technology demand inflection. Forecasts reflect documented assumptions about replacement-cycle duration and certification-compliance rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Kuwait Dishwasher Market
Appliances
Electric Kettle Market
Appliances
Laundry Appliances Market
Appliances
France Household Side by Side Refrigerator Market
Appliances
Dishwasher Market
Appliances
Household Beauty Appliances Market
Appliances
Automatic Dishwasher Market
Appliances
North America Washing Machine Market
Appliances
Oman Dishwashers Market
Appliances
United Kingdom Handheld Vacuum Cleaners Market
Appliances
Egypt Dishwashers Market
Appliances
Hairdryer Market
Appliances
Wall Oven Market
Appliances
Washing Appliances Market
Appliances
South Africa Laundry Appliances Market
Appliances
Portable Mini Fridge Market