
 Global Vended Laundry Equipment Market | 2026-2036
Global Vended Laundry Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vended Laundry Equipment Market Outlook
Student housing is consolidating as the fastest-growing end-use vertical for vended laundry equipment, displacing traditional coin-laundromat dominance in North American procurement budgets. Alliance Laundry Systems LLC leverages its route-distributor network to anchor commercial placement in university housing authorities. Electrolux Professional competes through energy-certified washer-extractor lines that sustain premium positioning in European municipal tenders. Dexter Laundry specializes in heavy-duty construction that dominates laundromat operator loyalty in high-turnover US markets.
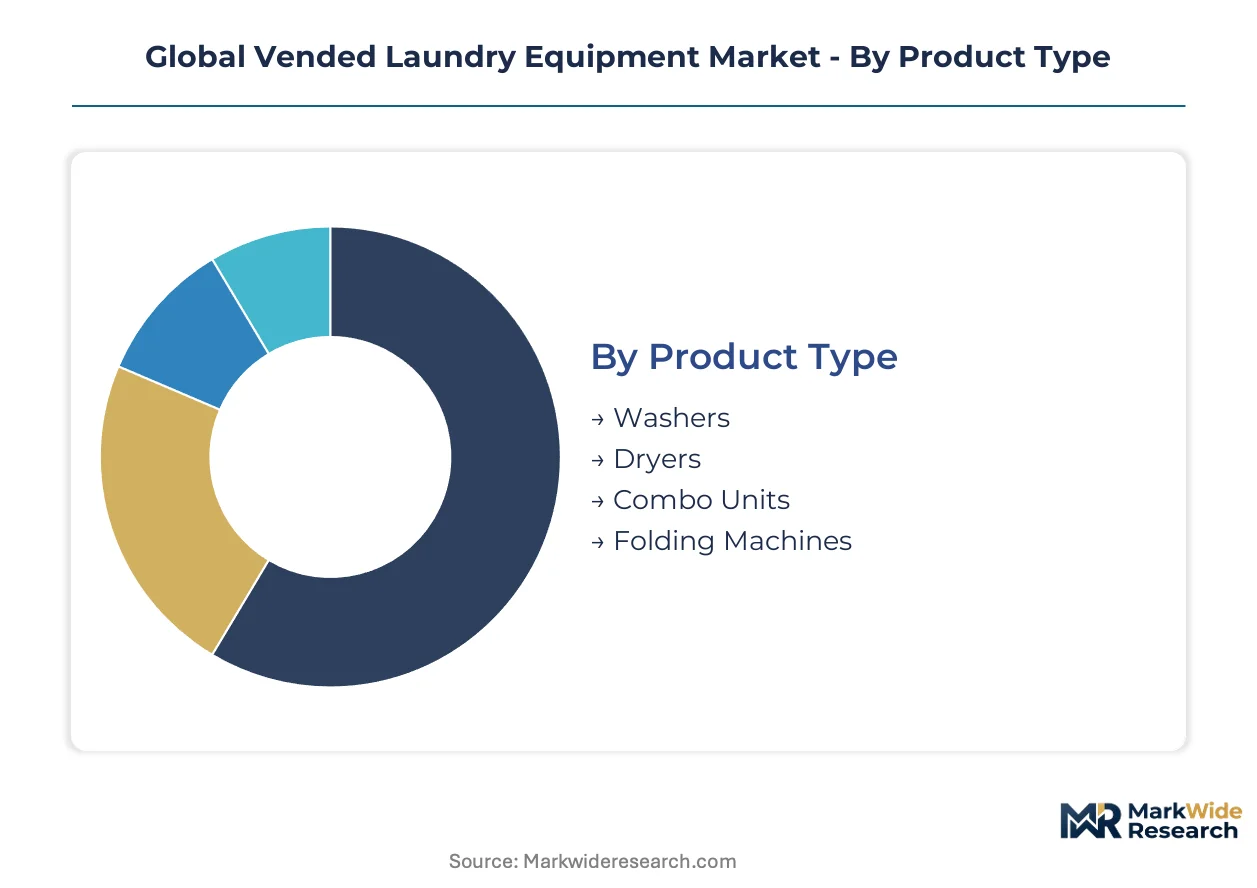
Vended laundry equipment encompasses coin- and card-operated washers, dryers, and ancillary finishing machines designed for unattended public use, typically constructed with stainless-steel drums, programmable controls, and reinforced suspension systems rated for 10,000-plus cycle lifespans. The primary commercial purpose is to provide revenue-generating fabric-care services in multi-tenant residential, hospitality, and institutional settings without dedicated on-site staff. Washers occupy the largest product-type margin pool due to higher replacement frequency and water-utility rebate eligibility, while combo units represent the fastest-growing configuration as space-constrained apartment developers prioritize footprint efficiency. Smart controls and IoT connectivity within the technological-feature dimension are displacing mechanical timers, creating recurring software-service revenue streams that reshape manufacturer-customer relationships beyond hardware transactions.
EPA Energy Star and DOE minimum efficiency standards shape US product development cycles, while the EU Ecodesign Directive and F-Gas Regulation restrict refrigerant choices in heat-pump dryer platforms sold across Europe. ISO 10472 safety standards govern industrial washing machine construction, creating compliance barriers for emerging-market entrants seeking OECD distribution partnerships. Stakeholders must monitor how real-time water-usage reporting mandates from US municipal utilities reshape specification criteria for multi-housing procurement officers evaluating total-cost-of-ownership models against upfront capital expenditure.
Market Dynamics
Heat-pump dryer architectures are forcing capital reallocation across manufacturing footprints as EPA Energy Star certification thresholds tighten water and energy intensity requirements for commercial placement.
Growth Catalysts
- Student Housing Modernization:University housing authorities in the United States are replacing aging coin-operated fleets with card-activated systems, expanding machine counts per capita to match residential amenity benchmarks.
- EU F-Gas Regulation:Refrigerant phase-down mandates are accelerating heat-pump dryer R&D in European manufacturing, creating first-mover advantages for compliant equipment lines in municipal tender processes.
- IoT Connectivity Integration:Smart control platforms enabling remote monitoring and dynamic pricing are capturing recurring software revenue streams that extend manufacturer-customer relationships beyond hardware replacement cycles.
Market Restraints
- Stainless-Steel Input Volatility:Drum and chassis fabrication depends on nickel-alloy sheet metal subject to commodity price swings that compress margin predictability for mid-tier equipment producers.
- Route-Distributor Concentration:North American commercial placement flows through a consolidated network of authorized distributors, creating channel access barriers for new entrants lacking established service infrastructure.
- Heat-Pump Technical Limitations:Lower operating temperatures in refrigerant-based drying cycles extend cycle times versus traditional gas-fired systems, creating throughput disadvantages in high-turnover laundromat environments.
Strategic Opportunities
- Indian Student Housing:Private campus developers in tier-one cities are specifying vended laundry pods for the first time, creating greenfield demand as domestic higher education capacity expands.
- Water-Utility Rebate Stacking:Municipal conservation programs in California, Texas, and Florida are layering equipment incentives atop federal tax credits, reducing effective payback periods for multi-housing developers.
- Combo Unit Configuration:Space-constrained apartment construction in Japan and South Korea is prioritizing washer-dryer combinations that eliminate venting requirements and reduce mechanical room footprints.
Industry Challenges
- Heat-Pump Technician Scarcity:Refrigeration-certified service personnel are concentrated in HVAC trades, creating field-repair bottlenecks as heat-pump dryer penetration accelerates in commercial settings.
- ISO 10472 Certification Timelines:Safety testing protocols for industrial washing machine construction impose 12-18 month approval windows that delay market entry for redesigned product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vended Laundry Equipment Market |
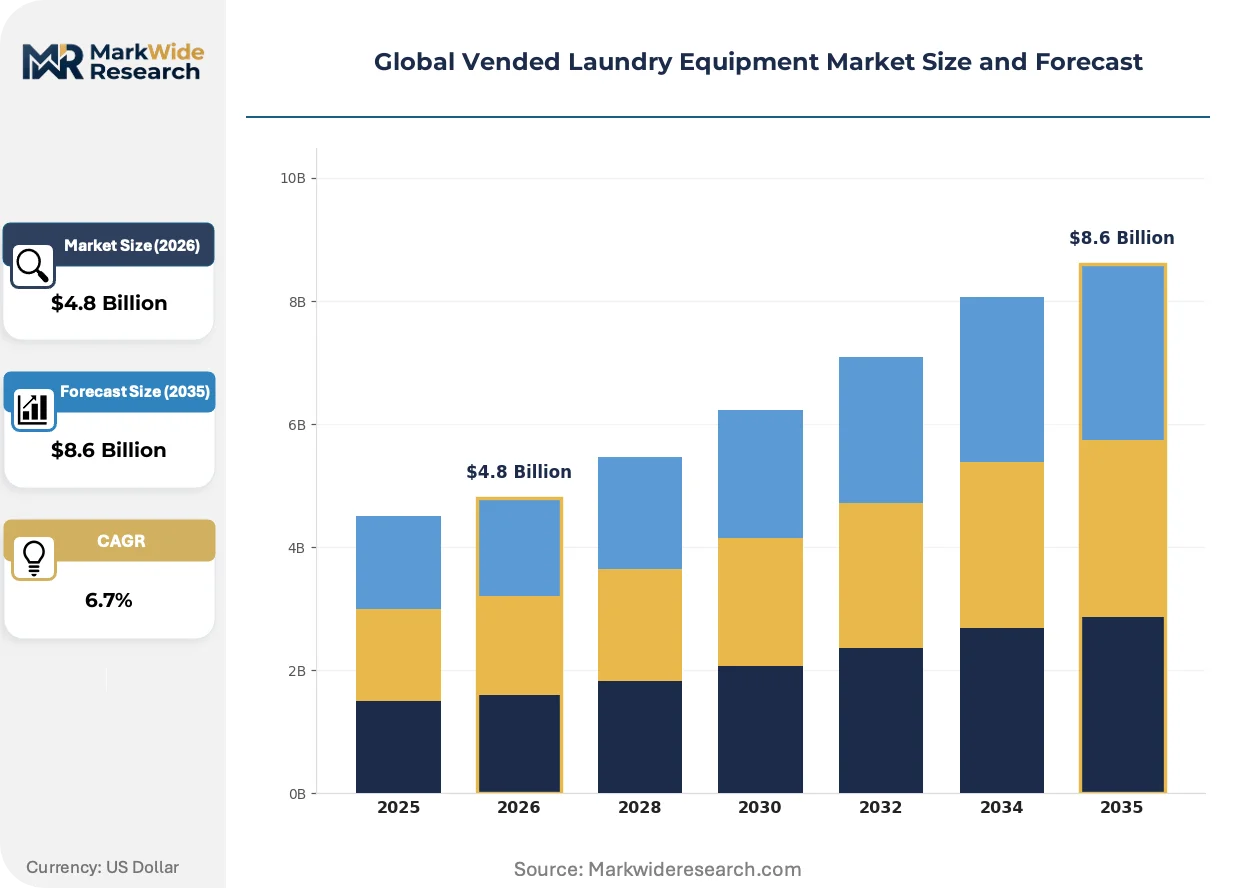
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Washers, Dryers, Combo Units, Folding Machines End User: Coin Laundromats, Apartment Complexes, Hotels, Universities Deployment: Self-Service, Attended Service, Mobile Apps, Remote Monitoring Technological Feature: Energy Efficiency, Smart Controls, IoT Connectivity, Payment Integration |
| Companies Covered | Alliance Laundry Systems LLC, Electrolux Professional, Whirlpool, Girbau S.A., Dexter Laundry, Fagor Professional, Ellis Corporation, AAdvantage Laundry Systems, Maxi Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vended Laundry Equipment Market Strategic Shifts
Connected equipment platforms are restructuring how manufacturers monetize installed bases, shifting revenue from transactional hardware sales toward ongoing software and data-service relationships.
Cloud-based machine management software is decentralizing operational control away from on-site attendants toward remote monitoring centers. Multi-housing property managers in the United States are adopting these platforms to reduce service call frequency and optimize revenue per machine through dynamic pricing algorithms. This architecture compresses the role of traditional route operators while enabling real-time performance benchmarking across distributed equipment fleets.
The EU Ecodesign Directive is tightening minimum efficiency requirements for commercial dryers sold across member states, mandating heat-pump or condensing technologies in place of vented electric resistance models. Manufacturers serving European municipal tenders are reconfiguring product portfolios to prioritize refrigerant-based platforms, even where gas infrastructure remains available. This regulatory pressure is most acute in German and French public housing procurement, where lifecycle cost calculations now embed carbon pricing assumptions.
Facility managers are consolidating vendor relationships around full-service contracts that bundle equipment, maintenance, and payment processing into single-source agreements. This behavior compresses procurement cycles for standalone hardware purchases while elevating financing and service capabilities as competitive differentiators. The shift is most visible in United States student housing, where university procurement officers favor turnkey operators over fragmented supplier arrangements.
Global Vended Laundry Equipment Market Segmentation
Equipment specification varies sharply across installation contexts. Multi-housing developers prioritize footprint efficiency and payment integration, while institutional buyers emphasize durability ratings and utility rebate eligibility.
Product Type:
Standalone washers and dryers dominate revenue pools, while combination units embed into space-constrained mechanical rooms.
- Washers:Stainless-steel drum construction rated for 10,000-plus cycles anchors replacement demand. Water-utility rebate programs in California and Texas concentrate procurement around Energy Star-certified front-load configurations.
- Dryers:Heat-pump architectures displace gas-fired systems under EPA certification thresholds. German and French municipal housing authorities now specify refrigerant-based platforms exclusively in public tenders.
- Combo Units:Ventless washer-dryer integrations reduce mechanical room footprints in Japanese and South Korean apartment construction.
- Folding Machines:Automated finishing equipment serves high-throughput coin-laundromat operators in US urban corridors.
Washers lead volumes today; combo units are gaining share fastest.
End User:
Procurement sophistication separates institutional buyers from fragmented independent operators.
- Coin Laundromats:Independent operators in US metropolitan areas specify heavy-duty construction for 16-hour daily utilization cycles. Route-distributor networks concentrate placement decisions around service response guarantees.
- Apartment Complexes:Multi-housing developers in Florida and Texas prioritize card-activated systems with IoT monitoring to reduce on-site management burden.
- Hotels:Hospitality procurement in France and Italy emphasizes water-extraction efficiency to minimize drying energy loads.
- Universities:US student housing authorities expand machine counts per capita to match residential amenity benchmarks.
Coin laundromats anchor installed base; universities show steepest expansion trajectory.
Deployment:
Operational labor intensity determines technology selection across customer types.
- Self-Service:Unattended card-activated systems dominate US multi-housing new construction.
- Attended Service:Staffed facilities persist in European urban centers with higher labor cost tolerance.
- Mobile Apps:Smartphone payment integration spreads through US university housing authorities.
- Remote Monitoring:Cloud-based platforms enable dynamic pricing algorithms for multi-housing property managers.
Self-service leads volumes today; remote monitoring is gaining share fastest.
Technological Feature:
Regulatory pressure and revenue model innovation reshape specification priorities.
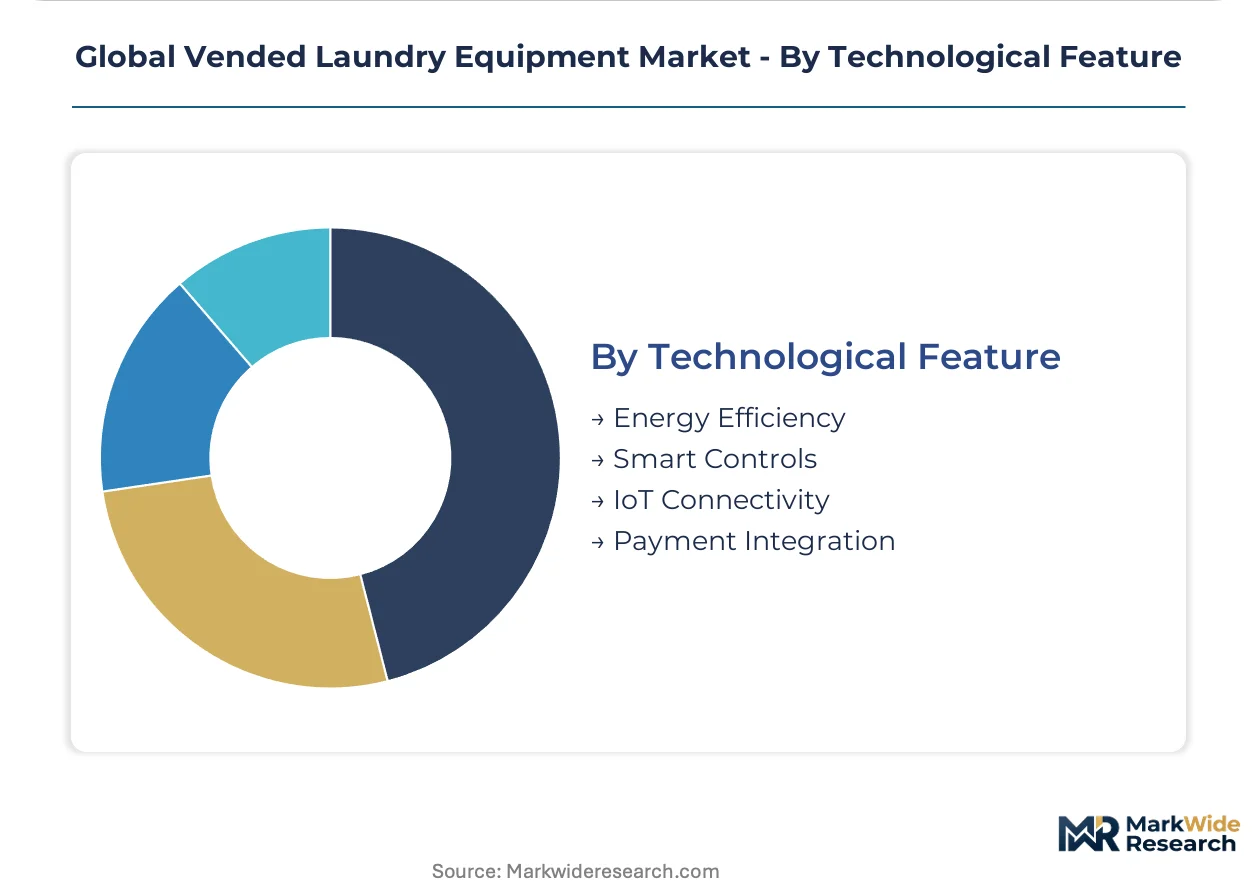
- Energy Efficiency:Heat-pump and condensing technologies satisfy EU Ecodesign Directive minimums.
- Smart Controls:Programmable interfaces enable cycle customization and usage analytics.
- IoT Connectivity:Real-time performance data creates recurring software-service revenue streams for manufacturers.
- Payment Integration:Card and mobile systems displace coin mechanisms in US municipal and institutional procurement.
Energy efficiency leads specification weight today; IoT connectivity is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are reallocating assembly capacity across jurisdictions to exploit divergent energy-efficiency compliance costs. The EPA's tightening Energy Star thresholds impose capital-intensive heat-pump retooling burdens in the United States, while European F-Gas phase-down schedules accelerate refrigerant-platform transitions ahead of Asian regulatory adoption curves.
United States
Multi-housing developers in Texas and Florida specify card-activated systems with IoT monitoring to reduce on-site management overhead. The EPA Energy Star program layers federal efficiency mandates atop state-level water-utility rebate programs in California. Chicago and Dallas metropolitan clusters concentrate route-distributor networks that control commercial placement access for university housing authorities.
Germany
Municipal housing procurement officers in Berlin and Munich now specify heat-pump dryers exclusively in public tenders based on lifecycle carbon pricing. The EU Ecodesign Directive and F-Gas Regulation restrict refrigerant choices in commercial dryer platforms sold across member states. The Rhine-Ruhr industrial corridor anchors component fabrication for heat-pump compressors serving pan-European equipment lines.
China
Domestic manufacturers supply cost-optimized washer-extractor lines for Southeast Asian export markets while absorbing stainless-steel input volatility. The Ministry of Ecology and Environment enforces dual carbon goals that tighten industrial energy-intensity standards for factory operations. The Yangtze River Delta manufacturing cluster around Shanghai dominates drum and chassis fabrication for mid-tier global equipment producers.
Japan
Apartment developers in Tokyo and Osaka prioritize ventless combo units that eliminate mechanical room footprints in space-constrained urban construction. METI efficiency standards push heat-pump adoption ahead of regulatory mandates in neighboring markets. The Kansai industrial region around Osaka specializes in compact heat-exchanger engineering for residential-scale laundry equipment.
India
Private campus developers in Bangalore and Hyderabad are specifying vended laundry pods for the first time as domestic higher education capacity expands. BIS certification requirements create compliance timelines that delay market entry for redesigned product lines. The Delhi-NCR corridor concentrates demand from student housing operators upgrading amenity benchmarks to match international campus standards.
Global Vended Laundry Equipment Market Competitive Environment
Portfolio diversification dominates the current landscape as manufacturers reconfigure product mixes to capture heat-pump efficiency premiums. The vendor base stratifies across three tiers: multinational industrial conglomerates with captive distribution networks, mid-cap specialists with regional route-distributor relationships, and emerging-market fabricators competing on stainless-steel chassis cost. Strategic archetypes include full-service contract bundlers, component-technology licensors, and vertical specialists in unattended payment integration. M&A activity concentrates on route-distributor acquisitions that secure channel access, while capacity expansion focuses on heat-pump compressor assembly in low-regulation jurisdictions.
Among North American route-distribution specialists, Alliance Laundry Systems LLC and Dexter Laundry exemplify the heavy-duty construction archetype that sustains operator loyalty in high-turnover environments. Electrolux Professional occupies a position within the multinational conglomerate tier, leveraging energy-certified product lines to anchor premium positioning in European municipal tenders. These three companies represent divergent strategic paths: distributor-network control, durability-focused engineering, and efficiency-certification premium capture.
| Leading Market Players |
|---|
| Alliance Laundry Systems LLC |
| Electrolux Professional |
| Whirlpool |
| Girbau S.A. |
| Dexter Laundry |
| Fagor Professional |
| Ellis Corporation |
| AAdvantage Laundry Systems |
| Maxi Companies |
| Others |
Value Chain & Pricing Dynamics
Captive compressor fabrication in the Rhine-Ruhr corridor anchors European manufacturers' cost position against Asian competitors while insulating pricing power from nickel-alloy volatility. This vertical control over heat-pump core components lets incumbent producers defend premium positioning in municipal tenders without surrendering margin to commodity drum suppliers.
Pricing Analysis
Distributor margin layers absorb 18-25 points of end-equipment value in North American route networks, compressing manufacturer realized prices against direct European municipal sales. Three-tier pricing structure across premium certified, standard efficiency, and economy-grade equipment reflects Energy Star tier differentiation and after-sales service bundling. Cost compression in mid-tier washers is intensifying because Chinese drum suppliers are absorbing stainless-steel volatility through volume commitments. Independent coin-laundromat operators show highest price sensitivity, while university housing authorities prioritize total-cost-of-ownership over upfront capital.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale multi-housing developer demand in Texas and Florida, bypassing traditional route-distributor markups for 500-plus unit placements. Component fabrication concentrates in China for drum and chassis stamping, Germany for heat-pump compressor assembly, and the United States for final integration and payment-system installation. Supply chains draw from nickel-alloy sheet metal, refrigerant gases, and programmable control modules. Single-source vulnerability in HVAC-certified service technician pools creates field-repair bottlenecks as heat-pump penetration accelerates. Distribution runs through authorized route networks in North America and direct municipal procurement in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where student housing procurement officers are displacing price-first laundromat operators with specification-heavy amenity benchmarks. Heat-pump efficiency certification and IoT connectivity now dominate RFP scoring over raw equipment cost.
For Market Incumbents: Anchor route-distributor relationships through exclusive service-territory guarantees that lock out emerging heat-pump specialists lacking technician networks. Deepen backward integration into compressor assembly in low-regulation jurisdictions to offset EPA retooling costs. Defend against white-label Chinese entrants by accelerating ISO 10472 certification timelines that delay competitor product launches.
For New Entrants and Emerging Players: Route-distributor acquisition targets in secondary US metropolitan clusters offer channel access without confronting Alliance Laundry Systems' entrenched university relationships. Indian private campus developers in Bangalore and Hyderabad represent the most penetrable geography, with first-mover advantage in vended laundry pod specification. A go-to-market angle pairing BIS certification navigation with turnkey IoT platform bundling bypasses incumbent hardware-only positioning.
For Investors and Strategic Acquirers: Consolidation pressure builds where route-distributor networks overlap in Chicago and Dallas metropolitan clusters, creating rollup opportunities for platform operators. Long-term viability favors full-service contract bundlers capturing recurring software revenue over transactional hardware sellers. Acquisition target archetype: mid-cap specialists with captive heat-pump engineering and underpenetrated university housing relationships. Watch EPA Energy Star threshold announcements as inflection indicators for capital reallocation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Platform Transition | EPA Energy Star thresholds force refrigerant-based R&D allocation ahead of gas-fired obsolescence. |
| Route-Distributor Acquisition | Channel control in Dallas and Chicago clusters secures university housing placement access. |
| IoT Software Stack Development | Recurring revenue from remote monitoring platforms extends customer lifetime value beyond hardware cycles. |
| Indian Market Entry Partnership | BIS certification navigation with local campus developers captures greenfield student housing expansion. |
| Compressor Assembly Relocation | Low-regulation jurisdiction manufacturing offsets EU F-Gas and EPA compliance cost burdens. |
Study Parameters
Multiple input streams — primary interviews with route-distributor principals, university housing procurement officers, and heat-pump service technicians, alongside secondary validation from EPA Energy Star certification databases, EU Ecodesign Directive filings, and stainless-steel commodity trade data — were reconciled through bottom-up equipment shipment tallies and top-down macroeconomic absorption models. Stakeholder conversations spanned maintenance directors at multi-housing operators, OEM procurement teams specifying washer-extractor lines, and aftermarket service heads managing distributed equipment fleets.
Data-stream reconciliation across product-type segmentation by configuration, end-user procurement sophistication tiers, deployment labor intensity levels, and technological feature certification grades produced volume and value estimates throughout the forecast period. CAGRs were derived from fitted growth curves against historical replacement cycle patterns and regulatory mandate implementation schedules. Industry-specific forecast inputs included water-utility rebate program expansion timelines in California and Texas, plus F-Gas Regulation phase-down compliance trajectories across German and French municipal tenders.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA Energy Star threshold revisions, nickel-alloy price volatility, and heat-pump technician training pipeline expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Household Side by Side Refrigerator Market
Appliances
Electrical Appliances Plastics Market
Appliances
Electric Iron Market
Appliances
Egypt Dishwashers Market
Appliances
North America Microwave Oven Market
Appliances
Toaster Ovens Market
Appliances
Consumer Appliances Market
Appliances
Germany Compact Dishwasher Market
Appliances
Colombia Laundry Appliances Market
Appliances
Israel Laundry Appliances Market
Appliances
Automatic Dishwasher Market
Appliances
France Household Electric Grills Market
Appliances
Germany Consumer Appliances Market
Appliances
Smart Connected Washing Machine Market
Appliances
Shared Shoe Washing Machine Market
Appliances
Oman Microwave Ovens Market