
 Bath Soap Market | 2026-2036
Bath Soap Market Size, Share, and Industry Trends Forecast 2026-2036
Bath Soap Market Intelligence
Plant-derived surfactant chemistry is hardening cost structures across mid-tier bar soap production. Unilever Plc leverages its palm-oil sourcing networks to stabilize input costs across Southeast Asian manufacturing hubs. Procter & Gamble sustains formulation R&D intensity in antibacterial and moisturizing variants. Kao Corporation anchors premium positioning through ceramide-infused bar technologies in Japanese and broader Asian retail channels.
Bath soap denotes a surfactant-based cleansing product formulated with alkali salts of fatty acids, typically containing 80-85% soap base with added glycerin, fragrances, and functional additives, manufactured through continuous saponification or neutralization processes for personal hygiene applications. Bar soap retains dominant volume share in emerging-market mass retail due to lower unit economics and minimal packaging overhead, while liquid soap occupies faster-expanding shelf space in premium urban supermarkets and hospitality procurement channels. Antibacterial formulation commands margin premiums in institutional and healthcare-adjacent segments, though organic certification requirements are reshaping ingredient sourcing compliance costs across European and North American supply chains.
India's BIS mandates ingredient-labeling standards for all cosmetic soaps sold domestically, while REACH in Europe restricts specific preservative chemistries and drives reformulation costs for exporters. The FDA in the United States maintains separate monograph requirements for antibacterial soap claims, creating divergent compliance pathways for multinational portfolios. Stakeholders must monitor evolving preservative bans and biodegradability thresholds as these frameworks tighten across their priority export jurisdictions.
Market Dynamics
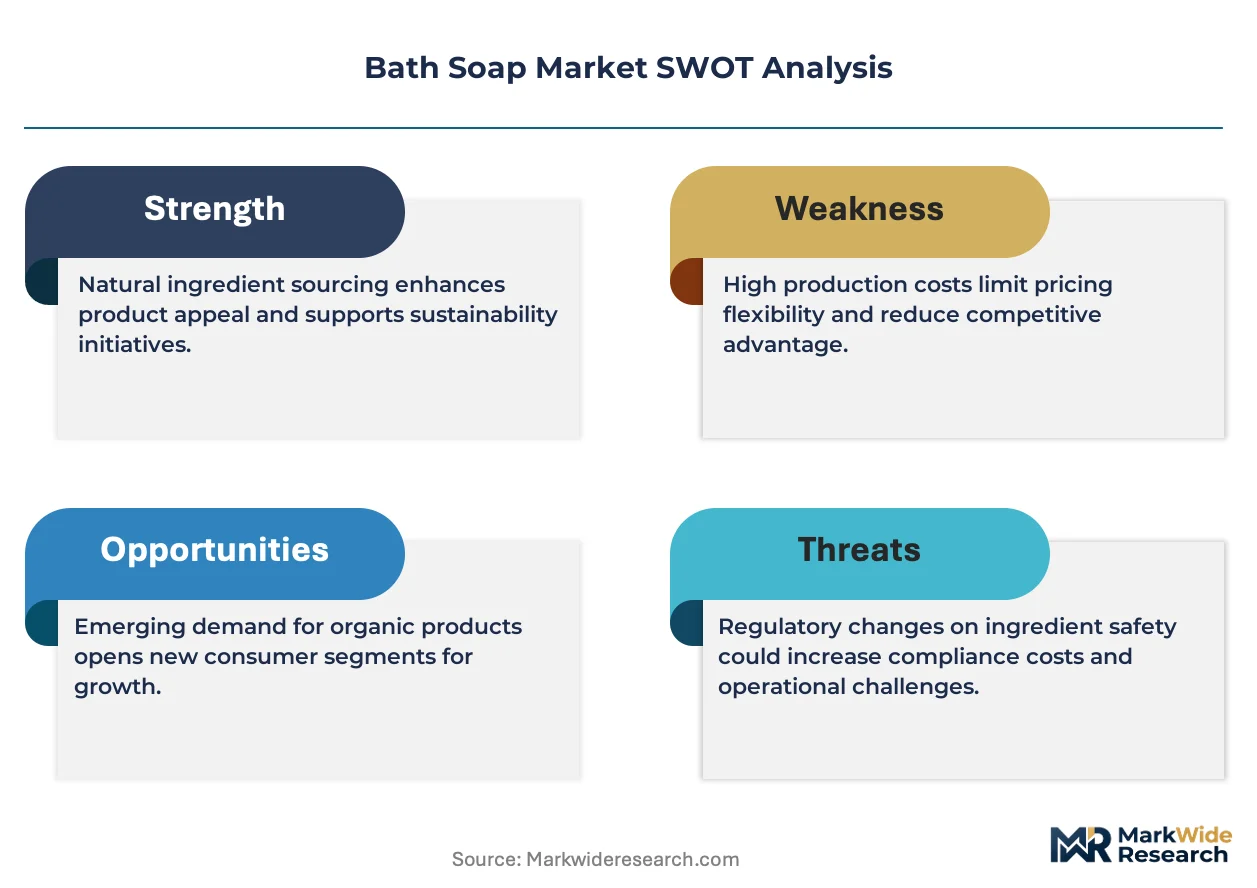
Ingredient-disclosure mandates from India's BIS and the EU REACH framework are forcing simultaneous reformulation across mass and premium soap portfolios, compressing margin structures while opening compliance-driven differentiation pathways.
Growth Catalysts
- Urban household premiumization:Metropolitan and tier-two city consumers in India are trading up to ceramide-infused and antibacterial formulations, expanding addressable wallet share per capita.
- REACH chemical restrictions:The EU framework's tightening preservative bans are accelerating clean-label innovation cycles among export-oriented manufacturers.
- Palm-oil sourcing networks:Southeast Asian integrated supply chains are stabilizing input cost volatility for regional production hubs serving Asian retail channels.
Market Restraints
- Fatty acid alkali salt volatility:Tallow and palm kernel oil price swings compress mid-tier bar soap margins during commodity upcycles.
- Preservative chemistry restrictions:REACH Annex XVII updates and FDA antibacterial monograph divergence create parallel compliance cost streams for multinational portfolios.
- Liquid soap substitution:Premium urban supermarkets and hospitality procurement channels are displacing bar formats in hygiene-sensitive applications.
Strategic Opportunities
- Tier-two city expansion:India's secondary urban corridors remain underpenetrated by premium formulations relative to metropolitan saturation.
- Organic certification tailwinds:EU Green Deal procurement guidelines and North American retailer sustainability mandates favor certified supply chain investments.
- E-commerce direct channels:Subscription-based personal care platforms are bypassing traditional FMCG distribution markups for niche and premium variants.
Industry Challenges
- Biodegradability testing capacity:Laboratory bottlenecks for aquatic toxicity validation are extending new product launch timelines by six to twelve months.
- Legacy saponification retrofit costs:Continuous neutralization process upgrades require capital deployment that mid-tier manufacturers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bath Soap Market |
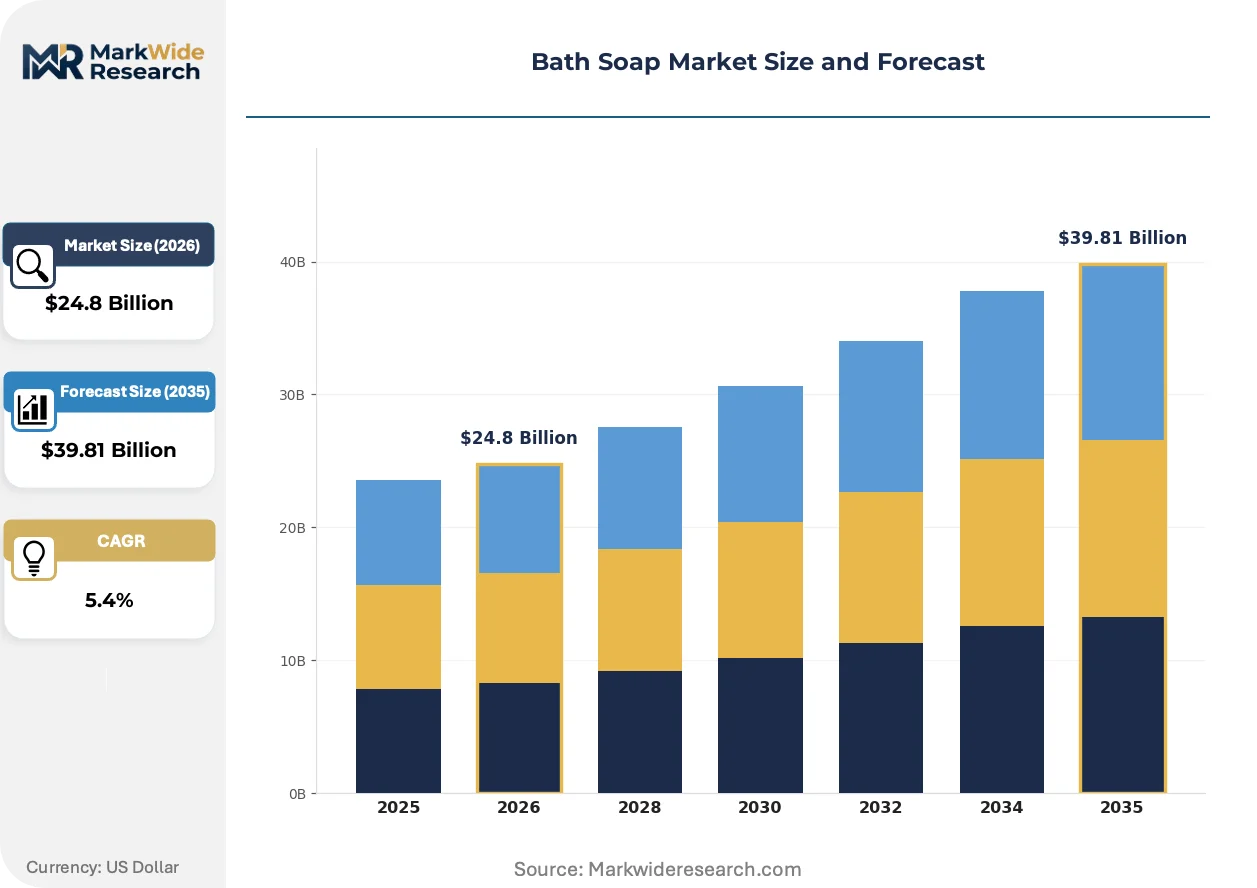
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $39.81 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Soap, Bar Soap, Foam Soap, Gel Soap End User: Adults, Children, Seniors, Infants Formulation: Organic, Antibacterial, Moisturizing, Exfoliating Packaging Type: Plastic Bottle, Pump Dispenser, Bar Packaging, Refillable Pouch |
| Companies Covered | Johnson & Johnson Services, Inc., Reckitt Benckiser Group Plc, The Procter & Gamble Company, Kao Corporation, L'Oréal, Unilever Plc, Henkel AG & Co. KGaA, Beiersdorf AG, The Colgate-Palmolive Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bath Soap Market Strategic Shifts & Innovations
Formulation chemistry and disclosure protocols are absorbing the bulk of competitive investment, with surfactant innovation and regulatory compliance emerging as the primary axes of product differentiation.
Ceramide-infused bar technologies are absorbing premium positioning investments from Japanese and broader Asian manufacturers. High-end retail channels and hospitality procurement segments are adopting these formulations at accelerated rates. The technology is absorbing margin compression from conventional moisturizing variants while commanding shelf space premiums.
REACH Annex XVII updates on preservative restrictions are forcing systematic reformulation across European export portfolios. Manufacturers serving EU markets face parallel testing requirements that duplicate FDA monograph pathways for antibacterial claims. Specialty and organic-certified segments are responding fastest by preemptively eliminating restricted chemistries.
Urban Indian households are consolidating purchases around BIS-compliant labels with full ingredient transparency. Traditional unbranded and loosely regulated alternatives are losing share in metropolitan corridors and tier-two cities. This preference shift is most visible in Maharashtra and Karnataka retail channels where enforcement intensity has tightened.
Bath Soap Market Segmentation
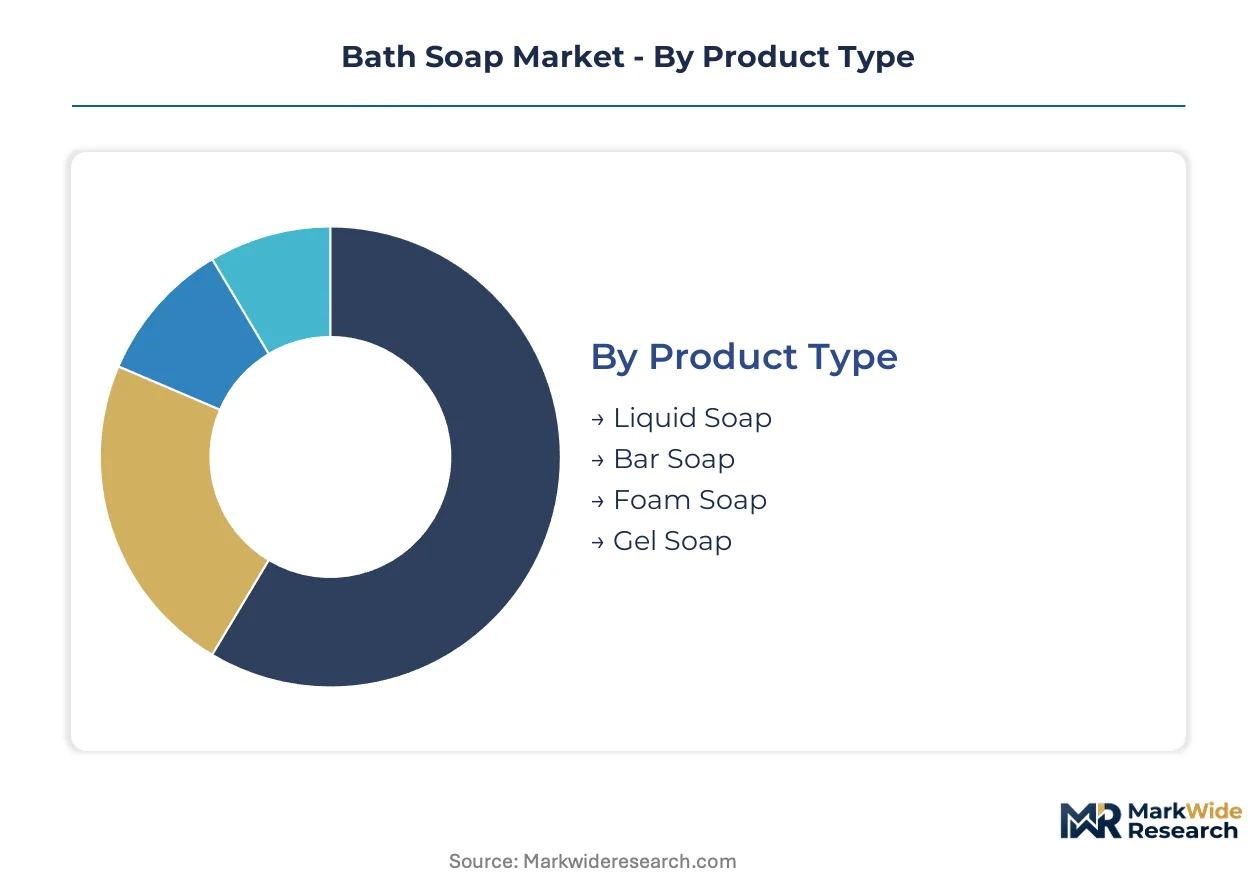
Bath soap segmentation tracks divergent cost structures and compliance burdens across physical formats and demographic targets. Manufacturers align R&D and sourcing investments to the margin and regulatory profiles of each category.
Product Type:
Buyers in this category differentiate primarily by unit economics and packaging overhead tolerance.
- Bar Soap:Alkali salt of fatty acids formulation with 80-85% soap base content, minimal packaging, and lower per-unit production cost. Volume concentrates in Indian metropolitan corridors and tier-two cities where price sensitivity dominates household procurement. BIS ingredient-labeling mandates favor transparent supply chains from established manufacturers over unbranded alternatives.
- Liquid Soap:Surfactant-based emulsion requiring pump or bottle dispensing systems, commanding premium shelf positioning in urban supermarkets and hospitality channels. Demand is accelerating in Maharashtra and Karnataka retail networks where hygiene awareness and dispenser infrastructure penetration enable format substitution.
- Foam Soap:Pre-lathered surfactant delivery reducing water consumption per use, gaining traction in institutional and commercial washroom installations.
- Gel Soap:Thickened aqueous formulation with visual clarity appeal, occupying niche positioning in premium personal care assortments.
Bar soap leads volumes today; liquid soap is gaining share fastest.
End User:
Skin sensitivity thresholds and pH tolerance requirements drive distinct formulation specifications across age cohorts.
- Adults:Standard surfactant tolerance with broad fragrance and functional additive compatibility. Demand clusters in urban Indian households trading up to ceramide-infused and antibacterial variants, expanding wallet share per capita in metropolitan corridors.
- Children:Milder pH-balanced formulations with restricted preservative chemistries to minimize dermal irritation risk. REACH Annex XVII compliance costs weigh on European export portfolios serving this segment.
- Seniors:Enhanced moisturizing base with reduced alkalinity to address age-related skin barrier degradation.
- Infants:Hypoallergenic specification with minimal fragrance load and certified organic sourcing requirements, commanding steepest formulation and testing cost premiums.
Adult formulations generate dominant revenue; infant segments command the highest per-unit margins.
Formulation:
Certification status and functional claims determine regulatory pathway complexity and pricing latitude.
- Organic:Plant-derived surfactant chemistry with certified supply chain documentation, absorbing compliance investment from EU Green Deal procurement guidelines and North American retailer sustainability mandates. Hard cost structures from palm-oil and coconut-oil sourcing networks compress mid-tier manufacturer margins.
- Antibacterial:Triclosan-alternative active ingredients complying with FDA monograph requirements in the United States and divergent ECHA restrictions in Europe. Institutional and healthcare-adjacent procurement channels pay margin premiums for validated efficacy claims.
- Moisturizing:Glycerin and emollient enrichment competing with ceramide-infused premium positioning from Japanese manufacturers.
- Exfoliating:Physical or chemical abrasive additives targeting specific skin texture concerns with narrower demographic appeal.
Moisturizing variants anchor mass-market volumes; organic certification is expanding most quickly in premium channels.
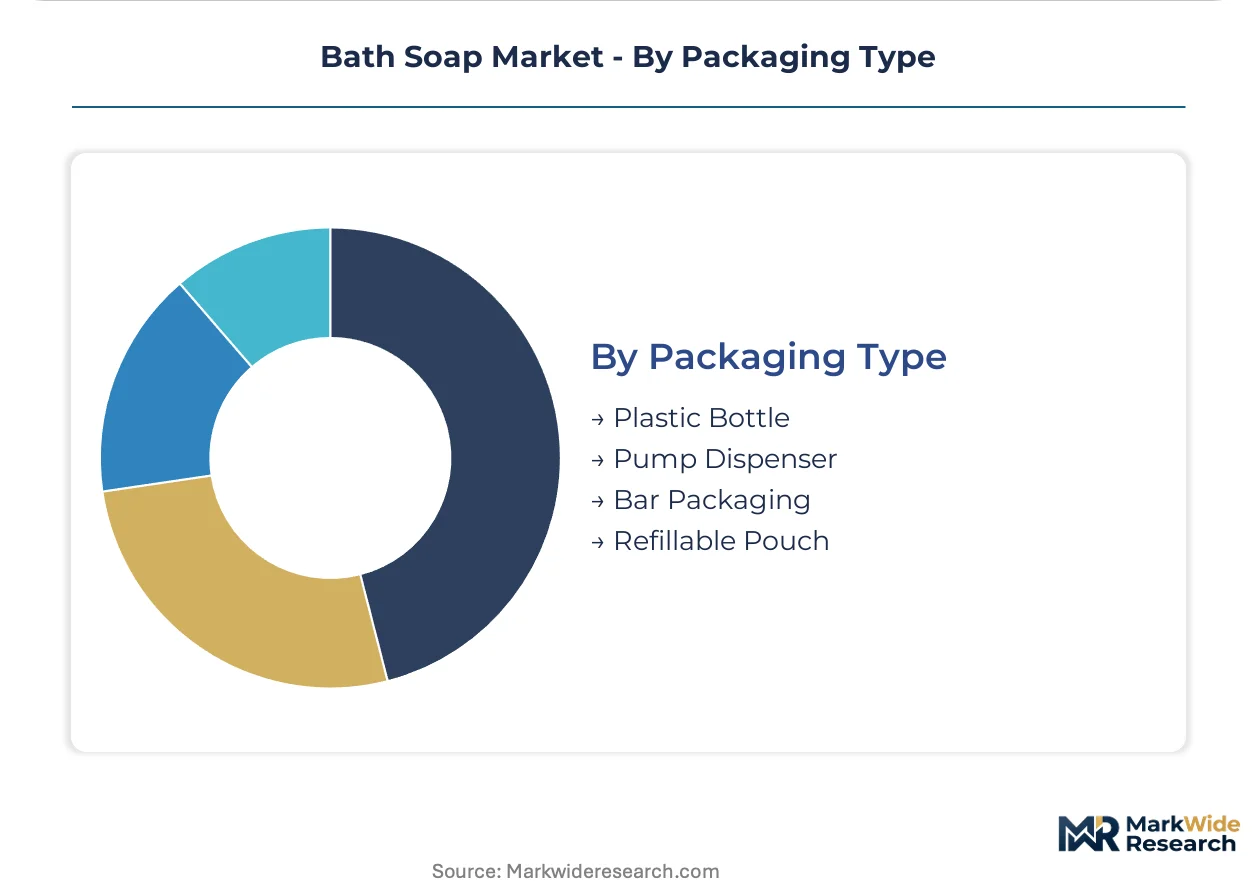
Packaging Type:
Distribution channel requirements and sustainability mandates shape material selection and cost structures.
- Plastic Bottle:Conventional PET or HDPE containment for liquid and gel formats, facing pressure from EU single-use plastic directives and Indian extended producer responsibility frameworks.
- Pump Dispenser:Mechanical dosing systems enabling controlled consumption and premium positioning in hospitality and commercial installations.
- Bar Packaging:Paperboard or flow-wrap systems with minimal material mass, aligning with biodegradability thresholds and lowest packaging cost per unit.
- Refillable Pouch:Flexible film formats reducing per-use material intensity, gaining adoption in e-commerce direct channels and subscription-based personal care platforms.
Plastic bottles retain installed base dominance; refillable pouches are climbing the fastest in sustainability-focused procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's metropolitan corridors anchor demand concentration for bath soap, with Maharashtra and Karnataka retail channels absorbing premium formulation volumes. Regulatory divergence across the United States, European Union, and India is fragmenting compliance pathways for multinational portfolios.
United States
FDA monograph requirements for antibacterial claims drive parallel testing investments from export-oriented manufacturers. Institutional procurement channels in Texas and California absorb validated efficacy formulations at margin premiums. The Southeast manufacturing belt concentrates bar soap production serving mass retail distribution networks.
Germany
ECHA restrictions under REACH Annex XVII accelerate clean-label reformulation cycles among specialty manufacturers. EMAS-registered facilities in North Rhine-Westphalia absorb compliance-driven differentiation investments. The Bavarian chemical cluster anchors surfactant R&D serving premium personal care export portfolios.
India
BIS ingredient-labeling mandates favor transparent supply chains from established manufacturers over unbranded alternatives. Maharashtra and Karnataka enforcement corridors tighten compliance intensity in metropolitan and tier-two retail channels. The Gujarat chemical belt concentrates alkali salt production feeding domestic bar soap volumes.
Japan
Ceramide-infused bar technologies command shelf space premiums in Kanto and Kansai retail networks. METI-aligned quality frameworks drive formulation R&D intensity among domestic manufacturers. The Osaka-Kobe industrial corridor anchors premium positioning exports serving broader Asian hospitality procurement channels.
Brazil
ANVISA cosmetic registration pathways extend product launch timelines for imported formulations. São Paulo state retail channels absorb mass-market bar soap volumes from regional production hubs. The Southeast manufacturing cluster concentrates palm-oil derivative processing for cost-competitive domestic supply.
Bath Soap Market Key Industry Players
Portfolio diversification dominates the current landscape as manufacturers absorb simultaneous reformulation pressures across multiple regulatory jurisdictions. The vendor base concentrates around multinational FMCG conglomerates with integrated palm-oil sourcing networks and regional specialty formulators with certified organic positioning. Three strategic archetypes define competitive positioning: scale-driven mass-market suppliers, premium-tier formulation specialists, and compliance-forward organic certifiers. M&A activity and capacity expansion in Southeast Asian production hubs represent the dominant competitive moves reshaping supply configuration.
Within the scale-driven tier, Unilever Plc and Procter & Gamble occupy positions anchored by integrated sourcing networks and R&D intensity across antibacterial and moisturizing variants. Kao Corporation exemplifies the premium formulation archetype through Japanese-market ceramide technologies. Reckitt Benckiser Group Plc sits within the hygiene-specialist segment serving institutional procurement channels with validated efficacy claims. These three entities represent distinct competitive vectors rather than overlapping strategic positioning.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Reckitt Benckiser Group Plc |
| The Procter & Gamble Company |
| Kao Corporation |
| L'Oréal |
| Unilever Plc |
| Henkel AG & Co. KGaA |
| Beiersdorf AG |
| The Colgate-Palmolive Company |
| Others |
Cost & Logistics Intelligence
Urban Indian household procurement in metropolitan and tier-two corridors anchors a three-tier pricing structure across premium, standard, and economy levels, with BIS-compliant transparency premiums commanding measurable shelf space advantages over unbranded alternatives.
Pricing Analysis
Input-cost pass-through from palm kernel oil and tallow volatility compresses mid-tier bar soap margins during commodity upcycles, forcing manufacturers to absorb or redistribute fatty acid alkali salt swings across their portfolios. Price differentiation rests on certification grade—REACH Annex XVII compliance versus conventional preservative chemistry—and brand equity in institutional channels. Pricing pressure stems from REACH and FDA monograph divergence creating parallel compliance investments. Mass-market bar formats exhibit highest price sensitivity; ceramide-infused premium variants show lowest elasticity.
Supply Chain Analysis
Certification gating through BIS labeling mandates, REACH Annex XVII compliance, and FDA antibacterial monographs fragments supplier qualification pathways across export portfolios. Raw material sourcing concentrates in Indonesia and Malaysia for palm-oil derivatives, India for alkali salt production, and Japan for ceramide formulation technologies. Supply chain risk centers on single-source vulnerability for certified organic surfactant feedstocks. Distribution runs through Southeast Asian manufacturing hubs feeding Asian retail channels, with e-commerce direct channels gaining share in subscription-based personal care platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bath soap market functions as a stable compounder, with urban household premiumization in India's metropolitan corridors delivering predictable per-capita wallet expansion across the analysis window.
For Market Incumbents: To counter liquid soap substitution in hygiene-sensitive hospitality and premium supermarket channels, incumbents should deepen backward integration into Southeast Asian palm-oil sourcing networks to stabilize input cost volatility. Simultaneously, accelerate BIS-compliant label investments to capture share from unbranded alternatives in Maharashtra and Karnataka enforcement corridors. For New Entrants and Emerging Players: Begin with tier-two Indian cities where premium formulation penetration lags metropolitan saturation, targeting ceramide-infused and antibacterial variants through e-commerce subscription platforms that bypass traditional FMCG distribution markups. Organic certification investments align with EU Green Deal procurement tailwinds. For Investors and Strategic Acquirers: Consumer goods conglomerates with integrated sourcing networks are the most active acquirer in this space, seeking certified organic formulators and regional specialty manufacturers. Over a multi-year horizon, prioritize targets with REACH-compliant portfolios and established BIS documentation. Watch for REACH Annex XVII expansion beyond current preservative restrictions as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palm-Oil Sourcing | Unilever's captive supply networks in Indonesia stabilize margin compression from fatty acid volatility. |
| REACH Annex XVII Compliance Investment | Specialty manufacturers in Germany's North Rhine-Westphalia cluster preempt reformulation cycles ahead of regulatory expansion. |
| Ceramide-Infused Premium Tier Introduction | Kao Corporation's Japanese-market technologies command shelf space premiums in Kanto and Kansai retail networks. |
| E-Commerce Direct Channel Expansion | Subscription-based platforms bypass traditional distribution markups for niche and premium variants in urban Indian households. |
| Organic Certification Program | EU Green Deal procurement guidelines and North American retailer mandates favor certified supply chain investments. |
Research Approach
Direct dialogue with brand managers at multinational FMCG conglomerates, category buyers at Indian metropolitan retailers, supply planners managing palm-oil derivative procurement, and technical R&D directors overseeing surfactant formulation anchored the qualitative foundation. Secondary validation drew from BIS regulatory filings, EU REACH Annex XVII updates, FDA antibacterial monograph documentation, and Nielsen retail audit data across Indian enforcement corridors. Bottom-up segment modeling and top-down macroeconomic triangulation converged on volume and value estimates.
Bottom-up analysis built forecasts from product-type, end-user demographic, formulation certification status, and packaging format segments, with particular weighting on urban Indian household premiumization rates and REACH compliance cost pass-through. Top-down validation cross-checked against macroeconomic indicators and personal care expenditure trends across the projection horizon. CAGRs derived from segment-level growth rate distributions, with specific inputs including BIS enforcement intensity in Maharashtra and Karnataka and biodegradability testing timeline extensions.
Several conditions sit outside the modeled scope, including unforeseen REACH Annex XVII expansion beyond current preservative restrictions, abrupt BIS labeling mandate enforcement shifts, and palm-oil price volatility exceeding historical bands. Forecasts reflect documented assumptions about regulatory stability and commodity input trends. Deviation in biodegradability testing capacity bottlenecks or tier-two city infrastructure development would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Camellia Skincare and Cosmetics Market
Cosmetics & Skincare
North America Bath Soap Market
Cosmetics & Skincare
Baby Skincare Market
Cosmetics & Skincare
Sports Sun Care Market
Cosmetics & Skincare
Myanmar Skin Care Products Market
Cosmetics & Skincare
Israel Cosmetics Products Market
Cosmetics & Skincare
Dark Circles Removing Eye Cream Market
Cosmetics & Skincare
Natural Baby Skin Care Products Market
Cosmetics & Skincare
Body Blurring Cosmetics Market
Cosmetics & Skincare
Scalp Scrub Market
Cosmetics & Skincare
Canada Cosmetic Products Market
Cosmetics & Skincare
Herbal Soap Market
Cosmetics & Skincare
Asia-Pacific Face Compact Market
Cosmetics & Skincare
Beauty Facial Mask Market
Cosmetics & Skincare
Mascara Applicators Market
Cosmetics & Skincare
Natural and Organic Lipstick Market