
 Natural Baby Skin Care Products Market | 2026-2036
Natural Baby Skin Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Baby Skin Care Products Market Outlook
The capital-intensity gap between mass-market incumbents and botanical specialists is collapsing as clean-label manufacturing scales. Weleda leverages its biodynamic farming network to secure rare botanical inputs. Johnson & Johnson Services Inc. competes through reformulated fragrance-free lines that meet pediatric dermatology standards. California Baby dominates the premium pharmacy channel with NSF-certified organic processing.
Natural baby skin care products are topical formulations designed for infant epidermal barriers, typically excluding synthetic fragrances, parabens, sulfates, and petrochemical derivatives; manufacturers cold-press plant oils and emulsify them with natural waxes to maintain stratum corneum hydration without disrupting developing microbiomes. Lotion and cream formats lead volume due to daily moisturizing rituals, while balm segments command higher margins through concentrated occlusive formulations for diaper dermatitis. Coconut oil and shea butter ingredient lines anchor supply chains through established agricultural cooperatives, whereas chamomile extracts differentiate premium positioning via anti-inflammatory claims.
FDA oversees cosmetic safety labeling for products sold in the United States, while the EU REACH regulation and ECHA restrict allergenic preservatives across European formulations; compliance costs favor larger manufacturers with dedicated regulatory affairs teams. Stakeholders must monitor evolving state-level ingredient disclosure mandates and third-party certification fragmentation as purchase criteria for parent buyers.
Market Dynamics
The collapse of capital-intensity barriers between mass-market incumbents and botanical specialists is compressing competitive moats as clean-label manufacturing scales across contract manufacturers.
Growth Catalysts
- EU REACH restrictions on synthetic preservatives:European manufacturers accelerate reformulation toward plant-derived antimicrobials, expanding compliant supplier networks.
- Naturopathic retail channel expansion:Germany's pharmacy and health food chains sustain premium positioning for biodynamic baby care brands through trained consultation services.
- Cold-pressed oil processing:Advances in low-temperature extraction preserve bioactive compounds in coconut and shea butter formulations, improving efficacy claims.
Market Restraints
- Shea butter supply concentration:West African cooperative networks face climate volatility and political instability, creating input cost unpredictability.
- Third-party certification fragmentation:Competing standards from NSF, ECOCERT, and COSMOS create compliance complexity and consumer confusion.
- Technical limitation in natural preservation:Plant-derived antimicrobial systems demonstrate shorter shelf stability versus synthetic alternatives, constraining distribution reach.
Strategic Opportunities
- Underpenetrated pharmacy channels in France:French parapharmacies show lower natural baby care penetration versus German counterparts, presenting expansion white space.
- Biome-friendly formulation convergence:Integration of prebiotic oligosaccharides with traditional botanical bases creates differentiation in microbiome-conscious positioning.
- Subscription direct-to-consumer models:Recurring delivery platforms bypass retail margin capture while building longitudinal customer data for personalization.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in natural emulsion stability and preservative-free systems commands premium compensation, constraining R&D throughput.
- Organic certification timeline compression:Multi-year farmland conversion requirements for biodynamic inputs delay new product pipeline velocity.
- Supply chain traceability integration:Blockchain-enabled ingredient provenance systems require significant IT infrastructure investment for smaller botanical specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Baby Skin Care Products Market |
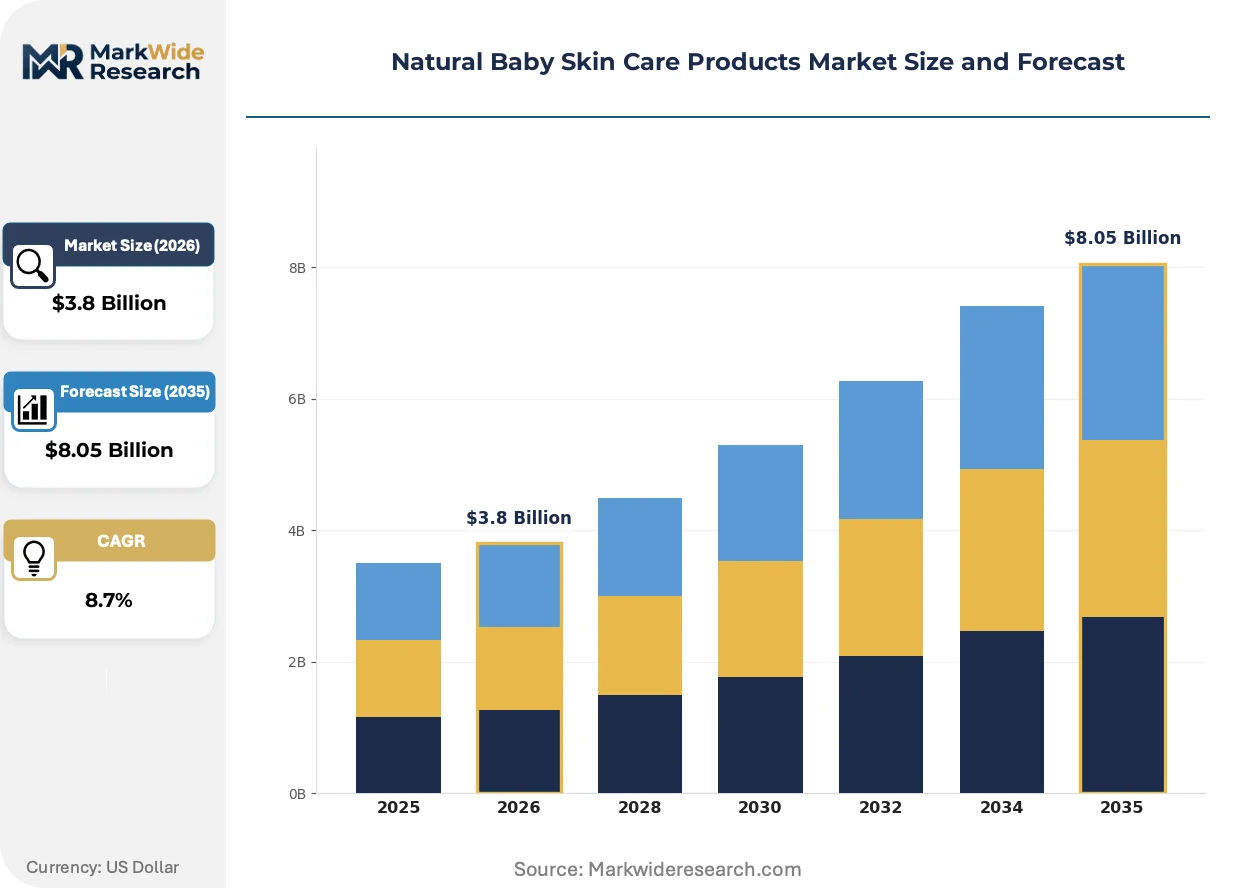
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lotion, Balm, Oil, Cream Ingredient: Aloe Vera, Shea Butter, Coconut Oil, Chamomile Packaging Type: Tube, Jar, Pump Bottle, Spray Distribution Channel: Online, Retail Stores, Pharmacies, Baby Specialty Shops |
| Companies Covered | Weleda, Childs Farm, Johnson & Johnson Services Inc., California Baby, Burt's Bees Baby, Laboratoires Expanscience, Gaia Skin Natural, Babo Botanicals, Beiersdorf AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Baby Skin Care Products Market Strategic Shifts
Formulation science is fragmenting along microbiome-respectful versus conventional efficacy lines, with processing technology and retail channel strategy diverging accordingly.
Biome-compatible emulsification technology is bifurcating the preservative landscape. Cold-processed lamellar gel networks replace traditional heat-thickened creams, preserving stratum corneum lipid architecture. Pediatric dermatology clinics in urban centers adopt these systems for atopic-prone infants. The technology is bifurcating R&D investment between microbiome-focused startups and reformulating mass-market portfolios.
EU REACH Annex V updates on allergenic fragrance compounds force systematic reformulation across European manufacturing. The regulation mandates disclosure of 26 specific sensitizers above threshold concentrations, elevating compliance documentation burdens. German and French manufacturers redirect toward certified fragrance-free lines, while Italian producers emphasize native citrus extracts with documented low-sensitization profiles.
Parent purchasing behavior is rotating toward certification-driven channel selection. Millennial buyers in metropolitan areas complete pre-store research on EWG Skin Deep and Yuka app ratings, bypassing traditional advertising influence. Pharmacy and specialty retail capture this traffic through trained staff consultation. France and urban UK clusters show the most pronounced shift from mass retail toward verified-clean channels.
Natural Baby Skin Care Products Market Segmentation
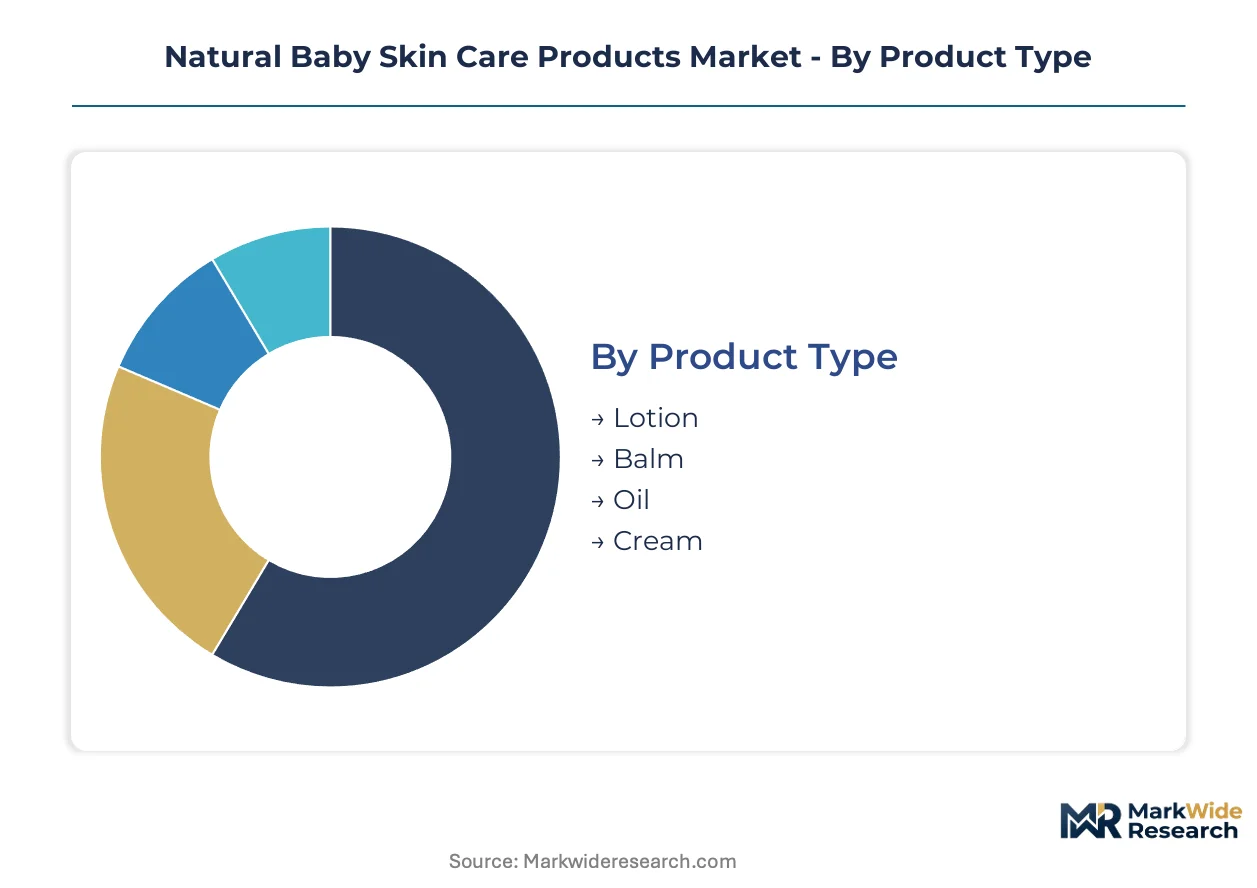
Segmentation in natural baby skin care reflects divergent regulatory pressures across formulation chemistry and channel access. Parents navigate certification complexity through format and packaging preferences that signal safety assurance.
Product Type:
FDA cosmetic labeling requirements and EU REACH preservative restrictions reshape formulation priorities across each format category.
- Lotion:Lightweight aqueous emulsions with high water content demand sophisticated natural preservation systems. Daily full-body application rituals in US urban households concentrate volume, though shorter shelf stability constrains mass retail distribution reach.
- Balm:Anhydrous occlusive formulations rely on concentrated shea butter and beeswax bases without water-phase preservation challenges. Diaper dermatitis prevention drives pharmacy channel placement in Germany, where trained consultation justifies premium positioning.
- Oil:Single-ingredient or simple blend formats bypass emulsion stability complexities entirely. Cold-pressed coconut oil lines anchor supply through established agricultural cooperatives.
- Cream:Thicker emulsions balance occlusion with spreadability for facial and extremity application. Eczema-prone infant segments favor fragrance-free cream variants in UK metropolitan clusters.
Lotion handles the majority of throughput; Balm is the fastest mover on share.
Ingredient:
Raw material provenance and extraction method determine certification eligibility and margin structure across botanical supply chains.
- Shea Butter:West African cooperative networks supply the foundational lipid for barrier repair claims. Climate volatility and political instability in Burkina Faso and Ghana create input cost unpredictability that favors long-term supplier contracts.
- Coconut Oil:Cold-pressed virgin grades from Philippine and Indonesian cooperatives anchor mid-market positioning. Lauric acid content supports antimicrobial marketing claims without synthetic additive disclosure requirements.
- Aloe Vera:Mexican and Texan cultivation zones supply mucopolysaccharide-rich gel for soothing formulations. Processing concentration in Guadalajara creates supply chain vulnerability.
- Chamomile:German and Egyptian cultivation sources provide bisabolol for anti-inflammatory differentiation. Organic certification timelines stretch procurement cycles for biodynamic grades.
Coconut Oil commands the volume base; Chamomile is expanding most quickly on premium positioning.
Packaging Type:
Format selection balances contamination risk, dosing precision, and shelf-life extension without synthetic preservative reliance.
- Pump Bottle:Airless dispensing systems minimize oxidative degradation and microbial introduction. German pharmacy chains favor pump formats for preservative-free emulsion stability.
- Tube:Collapsible aluminum or laminate structures protect photosensitive botanical actives. Travel-size tube assortments dominate subscription direct-to-consumer trial programs.
- Jar:Wide-mouth glass containers suit thick balm and cream textures requiring finger application. Repeated digit contact necessitates robust natural preservation systems or anhydrous formulations.
- Spray:Fine-mist delivery enables water-based thermal spring water or hydrosol applications. French parapharmacy channels show emerging adoption for post-sun soothing rituals.
Pump Bottle leads on hygiene-sensitive positioning; Spray is climbing the fastest on convenience innovation.
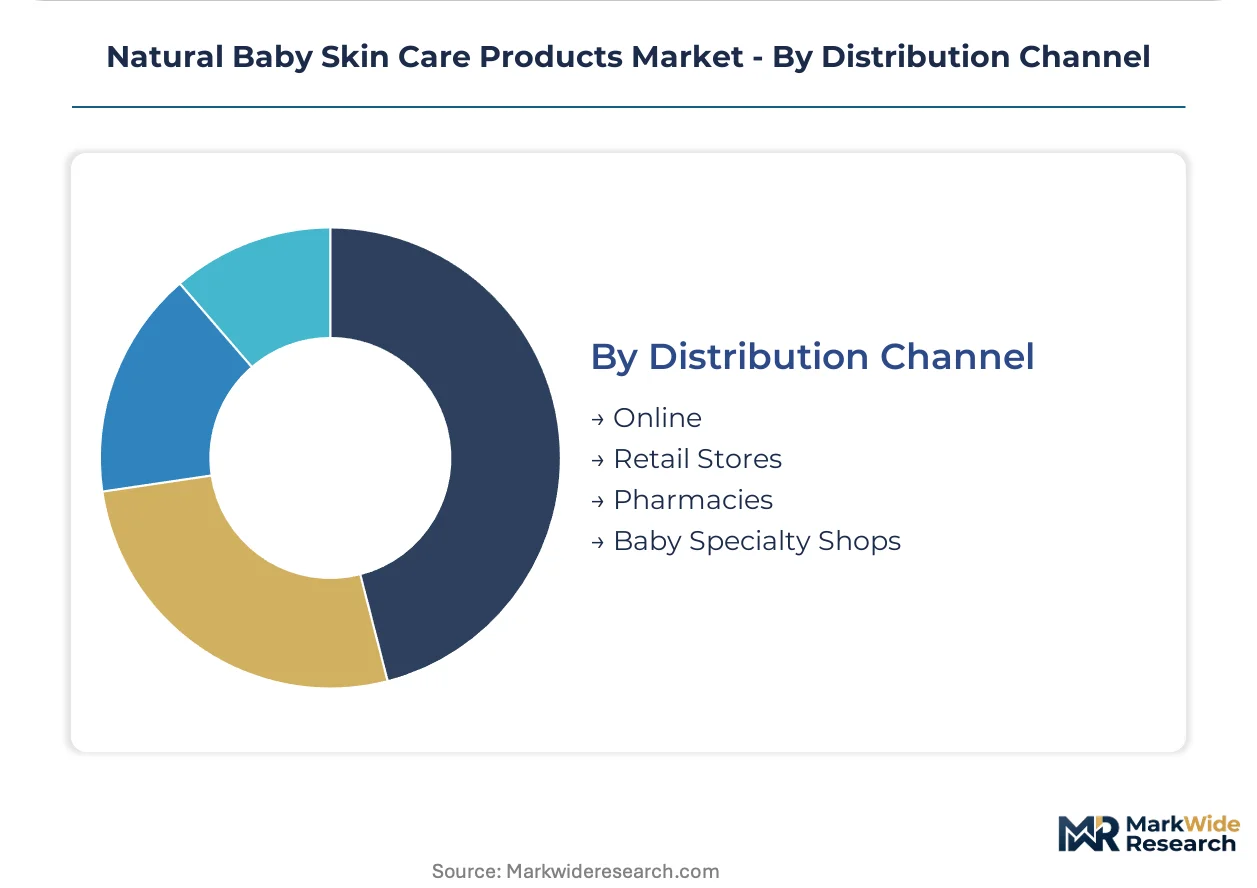
Distribution Channel:
Channel strategy determines margin capture, certification verification, and parent education depth at point of purchase.
- Pharmacies:German and French parapharmacy networks provide trained consultation for atopic-prone infant segments. EU REACH compliance documentation satisfies professional buyer scrutiny.
- Online:Direct-to-consumer platforms bypass retail margin capture while building longitudinal purchase data. EWG Skin Deep and Yuka app integration enables pre-purchase verification.
- Retail Stores:Mass retail placement demands scale economies and extended shelf-life stability. Reformulated fragrance-free lines from mass-market incumbents compete here on price accessibility.
- Baby Specialty Shops:Curated assortments emphasize third-party certification visibility and staff product knowledge. Urban UK clusters show strongest channel performance for premium biodynamic brands.
Pharmacies dominate premium value capture; Online is gaining share fastest on subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German parents accept premium pricing for biodynamic certification, while US mass-market buyers prioritize accessible clean-label reformulations. Southeast Asian markets concentrate volume in cold-pressed oil formats at lower price points.
Germany
Naturopathic pharmacy channels sustain premium positioning through trained consultation services. EU REACH Annex V mandates disclosure of allergenic fragrance compounds, forcing systematic reformulation toward certified fragrance-free lines. The Baden-Württemberg region hosts biodynamic farming cooperatives supplying rare botanical inputs to domestic manufacturers.
United States
Millennial parents in metropolitan clusters complete pre-purchase verification via EWG Skin Deep and Yuka app ratings. FDA cosmetic safety labeling requirements govern formulation disclosure without restricting specific ingredients. Greater Boston and Pacific Northwest urban centers show strongest adoption of subscription direct-to-consumer models.
France
Parapharmacy channels show emerging adoption of spray-format thermal spring water applications for post-sun soothing rituals. ANSM oversees cosmetic safety with emphasis on allergen documentation. The Provence-Alpes-Côte d'Azur region supplies native citrus extracts with documented low-sensitization profiles for fragrance-conscious formulations.
United Kingdom
Urban clusters demonstrate pronounced channel shift from mass retail toward verified-clean specialty retailers. The UK retains EU REACH alignment post-Brexit through retained harmonized standards. London and Southeast England concentrate demand for eczema-prone infant cream variants in pharmacy and baby specialty channels.
Australia
Parent buyers emphasize biome-friendly positioning with prebiotic oligosaccharide integration. TGA oversees therapeutic claims while ACCC monitors general consumer protection. Victoria and New South Wales metropolitan areas drive adoption of cold-pressed coconut oil lines through established agricultural cooperative networks.
Natural Baby Skin Care Products Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier that competes on certification depth and botanical provenance. Mass-market incumbents reformulate fragrance-free portfolios to meet pediatric dermatology standards, while biodynamic specialists leverage captive agricultural supply chains. Two strategic archetypes dominate: vertically integrated botanical processors with farm-to-formulation control, and clean-label contract manufacturers serving private-label demand. Competitive moves concentrate on M&A for certification assets and strategic partnerships for rare ingredient access.
Within the biodynamic specialist tier, Weleda exemplifies integrated agricultural control through its farming network operations. California Baby occupies a position anchoring premium pharmacy channel presence with NSF-certified organic processing credentials. Johnson & Johnson Services Inc. represents the reformulating incumbent archetype, leveraging scale infrastructure to meet clean-label standards without full portfolio conversion.
| Leading Market Players |
|---|
| Weleda |
| Childs Farm |
| Johnson & Johnson Services Inc. |
| California Baby |
| Burt's Bees Baby |
| Laboratoires Expanscience |
| Gaia Skin Natural |
| Babo Botanicals |
| Beiersdorf AG |
| Others |
Value Chain & Pricing Dynamics
Cold-pressed coconut oil displacement of petrochemical-based emollients redraws procurement geography toward Philippine and Indonesian cooperative networks while compressing margin structures for synthetic-dependent formulators. This substitution dynamic elevates agricultural input costs as a pricing determinant and rewards manufacturers with backward integration into farming operations.
Pricing Analysis
Subscription replenishment revenue streams anchor lifetime value capture for direct-to-consumer botanical brands. Three-tier pricing structure across premium biodynamic, standard certified-organic, and economy cold-pressed tiers separates NSF-certified pharmacy lines from mass-market reformulations. Cost compression in standard tiers intensifies as contract manufacturers achieve scale economies in natural emulsion processing. Mass-market parents in US metropolitan clusters exhibit highest price sensitivity, while German pharmacy buyers accept premium positioning for trained consultation services.
Supply Chain Analysis
Shea butter cooperative concentration in Burkina Faso and Ghana creates single-source vulnerability for barrier-repair formulations. West African agricultural networks, Philippine coconut oil processors, and Egyptian chamomile cultivation zones anchor raw material flows. Climate volatility in the Sahel region threatens input cost stability. Distribution runs through German pharmacy chains, French parapharmacies, and US subscription platforms with diverging margin capture profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemist scarcity constrains R&D throughput for natural emulsion stability and preservative-free systems, concentrating competitive advantage with employers offering premium compensation and captive agricultural supply.
For Market Incumbents: Consolidate certification assets through strategic acquisition of biodynamic farming operations to secure rare botanical inputs. Lock in multi-year supply contracts with West African shea butter cooperatives before climate volatility escalates. Redirect R&D investment toward cold-processed lamellar gel networks that preserve stratum corneum lipid architecture for atopic-prone infant segments. For New Entrants and Emerging Players: Subscription consultation services represent an under-served layer where incumbents under-serve millennial parents seeking personalized regimen guidance. French parapharmacy channels show lower natural baby care penetration versus German counterparts, presenting expansion white space. Enter through biome-friendly positioning with prebiotic oligosaccharide integration to differentiate from established botanical lines. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated botanical processors with farm-to-formulation control over clean-label contract manufacturers. Long-term viability rests on captive agricultural supply chains that insulate input cost volatility. Monitor EU REACH Annex V enforcement intensity as the signal for regulatory-driven M&A acceleration in fragrance-free formulation capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Biodynamic Farming Acquisition | Captive supply of rare botanical inputs secures NSF and ECOCERT certification eligibility. |
| Cold-Process Manufacturing Scale-Up | Low-temperature extraction preserves bioactive compounds in coconut and shea butter formulations. |
| Subscription Direct-to-Consumer Launch | Recurring delivery platforms bypass retail margin capture while building longitudinal customer data. |
| Pharmacy Channel Expansion | Trained consultation services in German and French parapharmacies justify premium positioning. |
| Biome-Friendly Certification Program | Prebiotic oligosaccharide integration differentiates positioning in microbiome-conscious segments. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA cosmetic labeling guidance, EU REACH Annex V documentation, and EWG Skin Deep database methodologies. Interviews with formulation chemists, pharmacy category managers, agricultural cooperative directors, and pediatric dermatology clinicians informed demand-side and supply-side dynamics. Customs records, NSF certification registries, and botanical trade association publications provided secondary validation. Bottom-up product-level modeling and top-down category sizing triangulated volume estimates.
Segmentation dimensions modeled include product format, botanical ingredient type, packaging technology, and distribution channel across the analysis window. Growth projections incorporate cold-pressed processing capacity expansion, naturopathic retail channel development, and parent purchasing behavior shifts toward certification-driven verification. CAGRs derive from regression analysis of historical premium personal care category performance adjusted for infant-specific regulatory constraints.
Underlying assumptions cover sustained EU REACH enforcement intensity and stable West African agricultural output, with deviation risk concentrated in shea butter supply disruptions and third-party certification fragmentation. Practitioners should keep alternative scenarios live as climate volatility in key cultivation zones and state-level ingredient disclosure mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Skin Care Products Market
Cosmetics & Skincare
Global Facial Cleanser Market
Cosmetics & Skincare
Reusable Makeup Remover Pad Market
Cosmetics & Skincare
Vietnam Skin Care Products Market
Cosmetics & Skincare
Medicated Shampoo Market
Cosmetics & Skincare
Face Cream Market
Cosmetics & Skincare
Organic Soaps Market
Cosmetics & Skincare
Snail Beauty Products Market
Cosmetics & Skincare
Mascara Applicators Market
Cosmetics & Skincare
Hyaluronic Acid Beauty Products Market
Cosmetics & Skincare
Botanical Skin Care Ingredients Market
Cosmetics & Skincare
Waterproof Temporary Tattoo Sticker Market
Cosmetics & Skincare
Anti-Fatigue Cosmetics Market
Cosmetics & Skincare
Pillow Spray Market
Cosmetics & Skincare
United Arab Emirates Cosmetic Products Market
Cosmetics & Skincare
France Lip Care Products Market