
 Dark Circles Removing Eye Cream Market | 2026-2036
Dark Circles Removing Eye Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Dark Circles Removing Eye Cream Market Insights
ISO 22716 Good Manufacturing Practices certification is reorganizing competitive entry in the Dark Circles Removing Eye Cream Market, forcing smaller manufacturers to upgrade facility standards or exit. Estée Lauder leverages its prestige distribution network to sustain premium positioning across North American department stores. L'Oréal anchors mass-market penetration through pharmacy and e-commerce channels with retinol-based lines. Shiseido competes on fermented ingredient technology leadership, particularly in peptide complexes targeting periorbital hyperpigmentation.
Dark Circles Removing Eye Cream comprises topical dermatological formulations designed to reduce periorbital discoloration through vasoconstriction, melanin inhibition, or collagen stimulation, typically containing active concentrations of caffeine, retinol, or vitamin C at pH levels optimized for thin periorbital skin. Cream and serum formulations capture the highest margin pools due to longer wear times and premium positioning, while roll-on delivery systems are gaining fastest among male and professional end users seeking convenient application. Peptide ingredient types are expanding share as consumers shift from cosmetic cover-up to biologically active repair claims.
The EU's MDR and REACH frameworks mandate rigorous safety dossiers for eye-area cosmetics, while the FDA oversees cosmetic labeling and adverse event reporting in the United States, creating divergent compliance costs that favor multinational scale. China's NMPA requires animal-alternative testing validation for imported eye creams, adding regulatory friction for Western brands entering that market. Stakeholders must monitor evolving patch-testing protocols and ingredient ban lists across jurisdictions to anticipate reformulation cycles and geographic expansion feasibility.
Market Dynamics
K-beauty R&D cycles and peptide formulation patents are compressing product lifecycles, forcing incumbent manufacturers to accelerate clinical validation timelines or cede shelf space to biotech-backed challengers.
Growth Catalysts
- EU MDR safety dossier mandates:Stricter periorbital testing protocols under the Medical Device Regulation are elevating clinical credibility for brands that complete ophthalmologist-supervised trials.
- Dermatology clinic channel expansion:Medical spas in South Korea and the United States are prescribing peptide-complex eye creams as adjuncts to laser treatments, creating professional endorsement loops.
- Fermented ingredient biotechnology:Shiseido's advances in postbiotic peptide extraction are lowering production costs for melanin-inhibiting actives previously limited to luxury tiers.
Market Restraints
- Retinol supply concentration:Three BASF and DSM manufacturing sites in Germany and Switzerland control pharmaceutical-grade retinol feedstock, exposing formulators to input volatility.
- China NMPA animal-testing waiver friction:Western brands face 18-24 month validation delays for cruelty-free alternative methods, blocking market entry despite consumer demand.
- Vitamin C degradation chemistry:L-ascorbic acid instability in aqueous bases limits shelf life to 6-9 months, constraining mass-market distribution economics.
Strategic Opportunities
- India pharmacy channel underpenetration:Organized retail chains like Apollo and MedPlus lack dedicated eye-care cosmetic sections, presenting first-mover positioning for stabilized vitamin C serums.
- Roll-on applicator male grooming pivot:Convenience-driven delivery formats are capturing professional end users in Japan's salaryman demographic, an underserved segment versus female-targeted jars.
- US IRA cosmetic ingredient transparency incentives:Pending FDA modernization legislation may subsidize domestic manufacturing of peptide actives, reducing import dependency.
Industry Challenges
- ISO 22716 facility certification timelines:Smaller manufacturers face 12-18 month GMP upgrade cycles, freezing new product launches during capital-intensive audits.
- Peptide patent thickets:Palmitoyl tripeptide and copper peptide complexes are encumbered by overlapping university and biotech licensing claims, complicating formulation freedom-to-operate.
- Periorbital patch-test standardization gaps:Divergent dermatological protocols across France's ANSM, Germany's BfArM, and the US FDA create redundant safety documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dark Circles Removing Eye Cream Market |
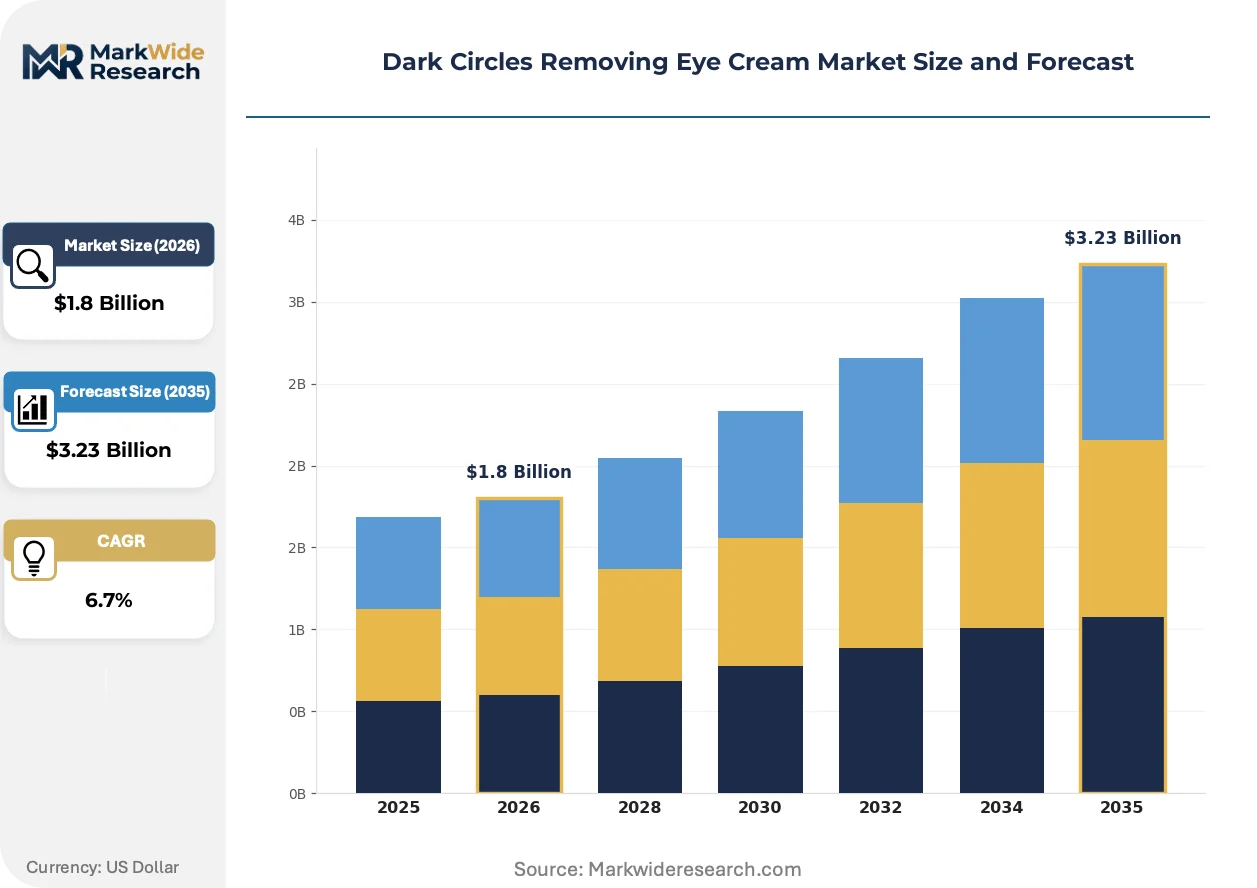
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roll-On, Gel, Cream, Serum Ingredient Type: Caffeine, Retinol, Vitamin C, Peptides Packaging Type: Tubes, Jars, Pumps, Sachets End User: Women, Men, Unisex, Professional |
| Companies Covered | Estée Lauder, L'Oréal, Shiseido, Unilever, Procter & Gamble, Chanel, Amorepacific Corporation, Beiersdorf AG, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dark Circles Removing Eye Cream Market Trends and Innovations
Active ingredient delivery systems and biologically validated claims are displacing cosmetic-only positioning, splitting manufacturer investment between clinical-grade peptide R&D and accessible mass-market retinol stabilization.
Encapsulated retinol microsphere technology is bifurcating the market between tolerated daily-use concentrations for sensitive periorbital skin and professional-grade peels requiring dermatologist supervision. Medical spas in South Korea and the United States are adopting the higher-potency formats for pre-treatment priming, while pharmacy channels in Germany and France favor the encapsulated variants for consumer self-application. This technology split is compressing mid-tier brands that lack capital for dual-formulation development.
REACH ingredient disclosure expansions are forcing reformulation of fragrance and preservative systems in eye-area products, with ECHA's 2024 SVHC candidate list additions targeting previously exempt sensitizers. Manufacturers serving the EU market are stripping out botanical extracts with insufficient safety dossiers, replacing them with synthetic alternatives that carry lower regulatory risk but command higher raw material costs. Premium positioned brands with dedicated toxicology teams are capturing shelf space from smaller competitors exiting the compliance burden.
Subscription replenishment models are displacing traditional retail replenishment cycles for eye cream consumers, with direct-to-consumer channels in the United States and United Kingdom capturing repeat purchase loyalty through auto-ship peptide complexes. Department store counter sales in North America are contracting as trial-sized introductory formats convert online, shifting margin pools from prestige retail markup to fulfillment infrastructure investment. This channel rotation is most visible among millennial and Gen-Z demographics in urban coastal markets, where convenience positioning outweighs in-store consultation value.
Dark Circles Removing Eye Cream Market Segmentation
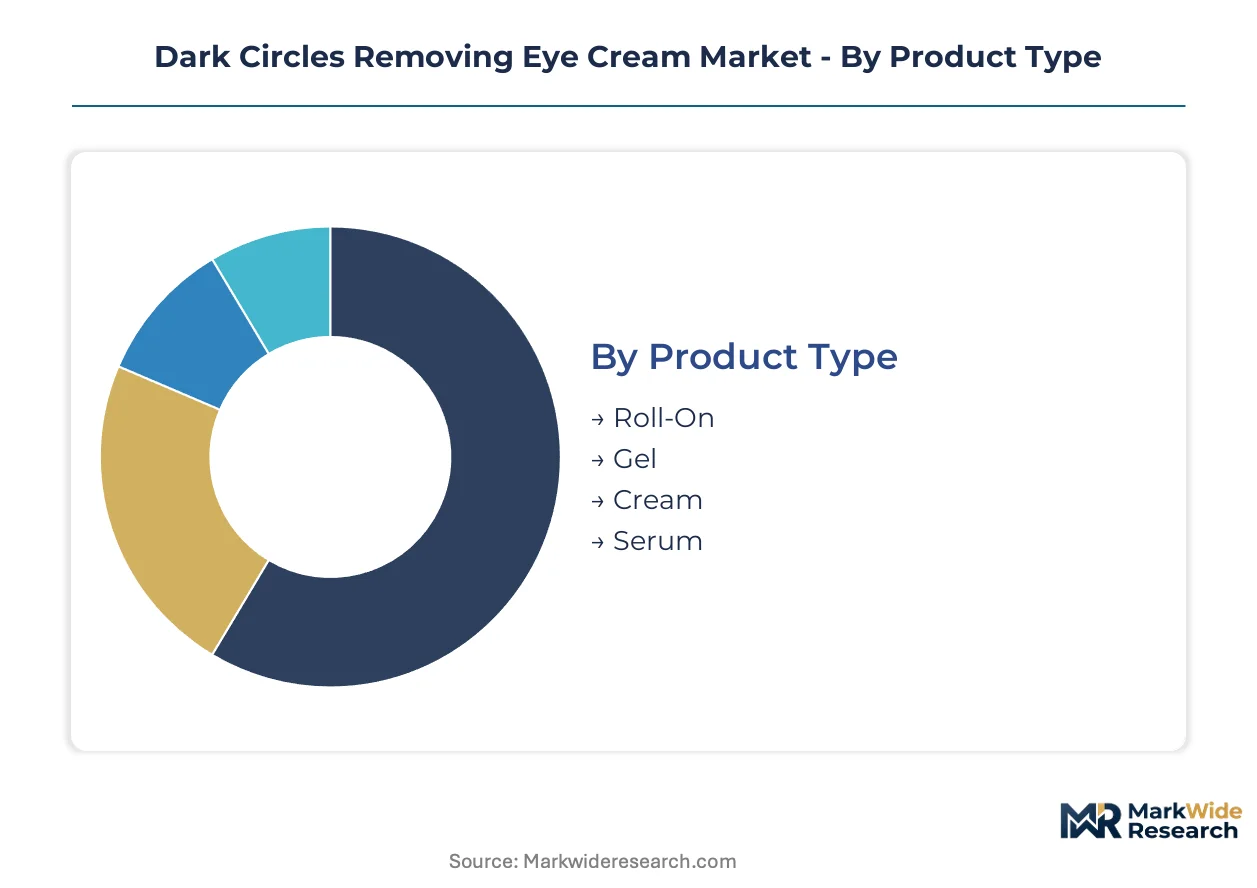
Segmentation in the Dark Circles Removing Eye Cream Market determines formulation complexity, regulatory pathway, and channel economics. Product and ingredient choices dictate whether brands pursue mass-market pharmacy distribution or professional dermatology endorsement.
Product Type:
EU MDR ophthalmologist-supervised testing requirements create divergent compliance burdens across delivery formats, with some categories demanding full clinical dossiers while others operate under standard cosmetic frameworks.
- Cream:Oil-in-water emulsions with occlusive bases support extended wear times for overnight repair claims. Demand concentrates in South Korean medical spas where clinicians prescribe peptide-cream adjuncts to laser periorbital treatments, constrained by ISO 22716 facility certification timelines for smaller manufacturers.
- Serum:Low-viscosity aqueous or silicone-based vehicles enable high actives loading at skin-compatible pH levels. Demand concentrates in German pharmacy channels where consumers self-select stabilized vitamin C and encapsulated retinol formats, driven by REACH-mandated ingredient disclosure stripping out unverified botanicals.
- Roll-On:Metal-ball applicators deliver cooling mechanical massage with instant de-puffing claims. Japan's salaryman demographic favors this format for office-based application speed.
- Gel:Hydro-alcoholic or carbomer-thickened bases target oily skin types and tropical climates. Indian organized retail chains lack dedicated eye-care sections, constraining mass-market penetration.
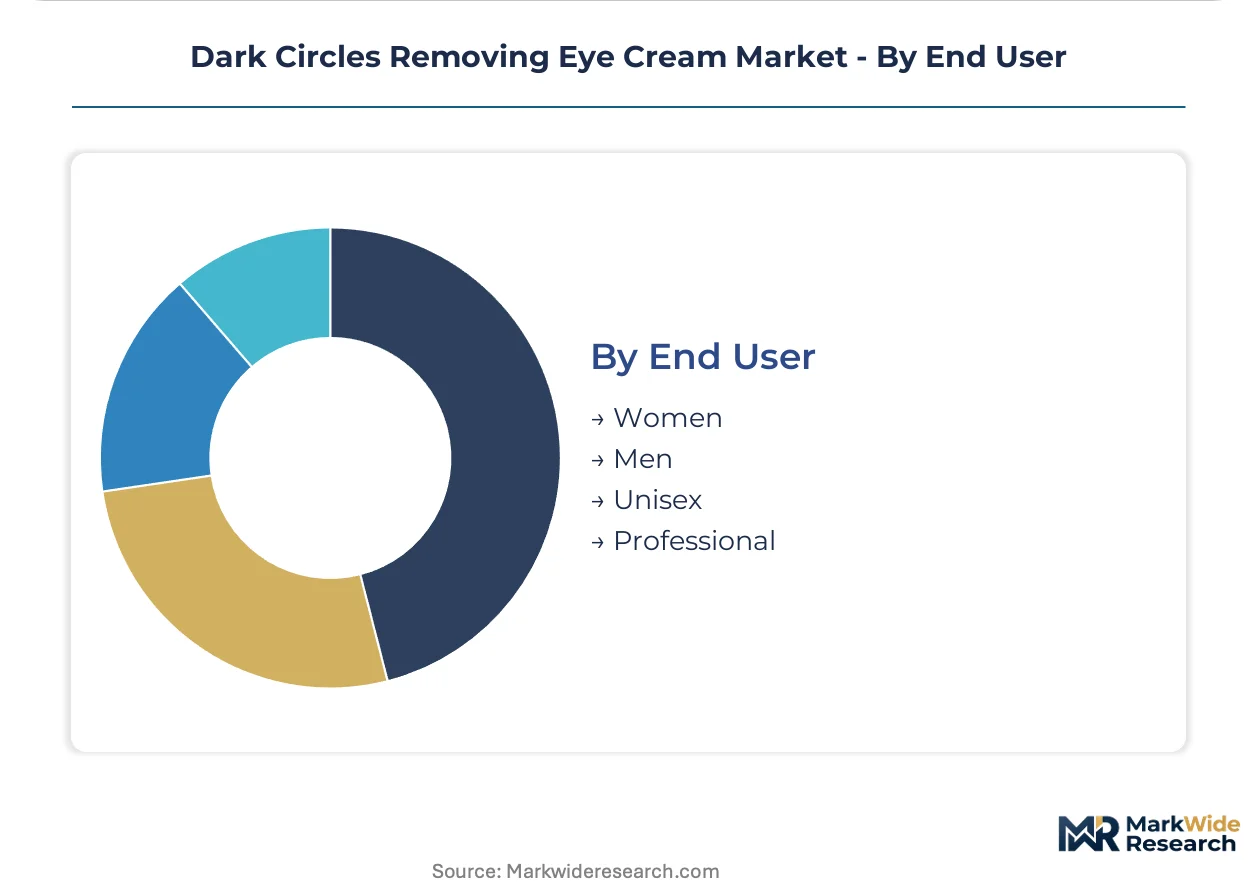
Cream handles the majority of throughput; Serum is expanding most quickly on share.
Ingredient Type:
Cost tiers separate pharmaceutical-grade actives requiring GMP-certified synthesis from commodity botanicals facing REACH substitution pressure.
- Peptides:Palmitoyl tripeptide and copper peptide complexes stimulate collagen synthesis and modulate melanin production through cell-signaling pathways. Demand concentrates in South Korea where K-beauty R&D cycles compress product lifecycles and biotech-backed challengers patent novel sequences, complicated by overlapping university licensing claims.
- Retinol:Vitamin A derivatives accelerate cellular turnover and thicken dermal matrix through retinoic acid receptor activation. Three BASF and DSM manufacturing sites in Germany and Switzerland control pharmaceutical-grade feedstock, exposing formulators to supply volatility and forcing dual-sourcing strategies.
- Vitamin C:L-ascorbic acid and stabilized derivatives inhibit tyrosinase and provide antioxidant photoprotection. Aqueous instability limits shelf life, constraining distribution economics for mass-market brands lacking cold-chain infrastructure.
- Caffeine:Methylxanthine compounds induce vasoconstriction and reduce periorbital edema through adenosine receptor antagonism. Lower regulatory burden supports rapid formulation iteration.
Retinol handles the majority of throughput; Peptides are gaining share fastest.
Packaging Type:
Volume economics and contamination risk determine whether brands invest in airless systems or accept shorter shelf lives for price-accessible formats.
- Pumps:Airless dispensing systems minimize oxidative degradation of sensitive actives like L-ascorbic acid and unencapsulated retinol. Professional end users in United States medical spas specify pump formats for treatment-room hygiene protocols.
- Jars:Wide-mouth containers enable finger-application of rich cream bases but introduce microbial contamination risk requiring robust preservative systems. REACH SVHC candidate list expansions force reformulation of traditional preservative cocktails.
- Tubes:Collapsible aluminum or laminate structures balance cost and barrier protection for mid-tier positioning. German pharmacy channels favor tube formats for travel-size peptide introductions.
- Sachets:Single-use foil pouches enable trial sampling and airline amenity distribution. Higher per-unit cost limits repeat purchase economics outside promotional contexts.
Pumps handle the majority of throughput; Jars show the steepest expansion trajectory.
End User:
Customer type dictates marketing investment allocation between clinical validation for professional endorsement and convenience messaging for male grooming pivots.
- Women:Historical core demographic driving jar and cream format preferences with multi-step routine integration. Subscription replenishment models in United States and United Kingdom urban coastal markets displace department store counter loyalty.
- Professional:Dermatologists, aestheticians, and medical spa operators prescribe peptide complexes as pre- and post-treatment adjuncts. FDA cosmetic labeling requirements and EU MDR safety dossier mandates elevate documentation burdens for professional-channel suppliers.
- Men:Underrepresented segment showing fastest response to roll-on applicators and simplified positioning. Japan's salaryman demographic and United States millennial professionals drive convenience-format trial.
- Unisex:Neutral positioning expands addressable market but dilutes targeted messaging effectiveness in crowded retail environments.
Women handle the majority of throughput; Men are climbing the fastest on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU MDR safety dossier mandates and China's NMPA animal-testing waivers are reshaping geographic entry strategies for eye cream manufacturers. South Korea's MFDS accelerates peptide innovation cycles while India's pharmacy channel liberalization opens new distribution corridors.
United States
Medical spa channel expansion drives professional-grade peptide demand in Los Angeles and Miami aesthetic clusters. FDA cosmetic labeling requirements and adverse event reporting protocols elevate documentation burdens for clinical claims. New York Metro hosts prestige brand headquarters concentrating subscription direct-to-consumer fulfillment infrastructure.
South Korea
K-beauty R&D compression cycles force 12-month product refresh timelines in Seoul Capital Area biotech corridors. MFDS regulates functional cosmetic claims with accelerated approval pathways for melanin-inhibiting actives. Busan-Ulsan manufacturing belt concentrates fermented peptide extraction facilities serving domestic and export markets.
Germany
Pharmacy channel self-selection favors stabilized vitamin C and encapsulated retinol formats in Berlin and Munich retail networks. REACH SVHC candidate list expansions force preservative system reformulation across eye-area products. BASF Ludwigshafen site anchors pharmaceutical-grade retinol feedstock production for European formulators.
China
NMPA animal-alternative testing validation delays 18-24 months for cruelty-free Western brands seeking Shanghai and Beijing entry. Yangtze River Delta domestic manufacturers capture local demand with streamlined regulatory pathways. Pearl River Delta e-commerce logistics hubs enable cross-border peptide serum distribution despite import friction.
India
Apollo and MedPlus organized retail chains lack dedicated eye-care cosmetic sections, presenting first-mover gaps for stabilized vitamin C introductions. CDSCO regulates cosmetic imports with accelerating harmonization toward ASEAN standards. Maharashtra pharmaceutical manufacturing clusters repurpose GMP facilities for dermocosmetic production expansion.
Dark Circles Removing Eye Cream Market Competitive Landscape
Player mix skews toward multinational conglomerates with dedicated dermatology divisions and regional biotech specialists. Three-tier concentration separates prestige houses with medical spa endorsement from mass-market pharmacy players and emerging peptide-focused challengers. Dominant competitive moves include M&A for fermentation technology access and strategic partnerships with South Korean R&D labs.
Within the multinational conglomerate tier, Estée Lauder and L'Oréal occupy positions spanning prestige department store and mass-market pharmacy channels respectively. Shiseido exemplifies the biotechnology-specialist archetype through fermented ingredient leadership. These three anchors represent divergent strategic vectors: North American prestige distribution network leverage, European pharmacy channel scale, and Asian R&D cycle acceleration.
| Leading Market Players |
|---|
| Estée Lauder |
| L'Oréal |
| Shiseido |
| Unilever |
| Procter & Gamble |
| Chanel |
| Amorepacific Corporation |
| Beiersdorf AG |
| Johnson & Johnson |
| Others |
Pricing and Supply Chain Analysis
Eighteen-month ISO 22716 facility certification timelines compress inventory turnover for smaller manufacturers, forcing capital allocation toward compliance infrastructure rather than price-competitive sourcing. This lead-time burden concentrates pricing power with multinational conglomerates that amortize certification costs across diversified product portfolios, while specialty peptide suppliers extract premiums through pharmaceutical-grade synthesis capabilities.
Pricing Analysis
Certification level creates the primary spread between mass-market pharmacy tiers and professional dermatology channels. Three-tier pricing structure across premium peptide complexes, standard retinol formulations, and economy caffeine-based lines reflects GMP synthesis costs and clinical validation depth. Pricing pressure stems from REACH-mandated preservative reformulation, which elevates raw material expenses for mid-tier brands lacking dedicated toxicology teams. Professional end users in United States medical spas exhibit lowest price sensitivity due to treatment-room markup economics, while Indian pharmacy consumers drive volume through cost-conscious self-selection.
Supply Chain Analysis
Inventory concentration at three BASF and DSM manufacturing sites in Germany and Switzerland exposes formulators to pharmaceutical-grade retinol feedstock volatility. Active ingredient procurement draws from South Korean fermented peptide extraction facilities, Swiss precision chemical synthesis plants, and Indian botanical supply bases recovering from REACH substitution pressure. Single-source vulnerability concentrates in retinol precursor manufacturing, where geographic clustering amplifies disruption risk from regulatory inspections or logistics congestion. Distribution runs through German pharmacy networks, South Korean medical spa procurement channels, and United States direct-to-consumer fulfillment infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as subscription replenishment models displace department store loyalty, creating niches for direct-to-consumer specialists with peptide-complex differentiation.
For Market Incumbents: Compound clinical validation advantages through ophthalmologist-supervised trial expansion, locking in professional channel endorsement before biotech-backed challengers patent novel sequences. Accelerate backward integration into fermented peptide extraction to capture margin pools currently flowing to South Korean R&D labs, insulating against K-beauty innovation cycle compression. For New Entrants and Emerging Players: Roll-on applicator convenience gaps in male grooming segments present underexploited white space, particularly among Japan's salaryman demographic seeking office-based application speed. Target India's organized pharmacy retail chains with stabilized vitamin C serum introductions, exploiting first-mover positioning in eye-care cosmetic sections that Apollo and MedPlus have yet to develop. Pursue cruelty-free certification early to circumvent China NMPA animal-testing waiver friction blocking Western brand entry. For Investors and Strategic Acquirers: Long-term, this sits as a dermatology-channel consolidation play because professional endorsement loops in medical spas create durable competitive moats around peptide-complex formulations. Acquisition candidates include mid-tier manufacturers with ISO 22716-certified facilities but underutilized capacity, positioned for rollup into multinational distribution networks. Signal to monitor: MFDS accelerated approval pathway expansions for melanin-inhibiting actives, which would validate South Korean R&D cycle investments.| Strategic Initiative | Industry Significance |
|---|---|
| Fermented Peptide Patent Licensing | Secures freedom-to-operate for palmitoyl tripeptide complexes amid overlapping university claims. |
| ISO 22716 Facility Certification | Unlocks professional dermatology channel access requiring GMP-validated manufacturing documentation. |
| Direct-to-Consumer Subscription Launch | Captures millennial repeat purchase loyalty displacing North American department store counter economics. |
| REACH-Compliant Preservative Reformulation | Eliminates regulatory risk from ECHA SVHC candidate list expansions targeting eye-area sensitizers. |
| India Pharmacy Channel Expansion | Establishes first-mover positioning in Apollo and MedPlus organized retail eye-care sections. |
Research Methodology
A standing panel of dermatology clinic procurement managers, cosmetic formulators, pharmacy retail category buyers, and regulatory affairs specialists provided ongoing calibration against shifting peptide patent landscapes and REACH compliance timelines. Primary fieldwork combined structured interviews with these stakeholders and secondary validation through MFDS functional cosmetic claim databases, ECHA SVHC candidate list publications, FDA cosmetic labeling guidance documents, and South Korean customs export statistics for fermented ingredient categories. Bottom-up volume modeling across delivery formats and ingredient types triangulated against top-down market sizing from trade flow analysis.
Consistency checks validated projected expansion rates against historical K-beauty R&D cycle compression patterns and professional channel adoption curves in United States medical spa clusters. The analytical framework segmented demand across cream, serum, roll-on, and gel product types; peptide, retinol, vitamin C, and caffeine ingredient categories; pump, jar, tube, and sachet packaging formats; and women, professional, men, and unisex end-user archetypes throughout the projection horizon. CAGR derivation incorporated patent expiration timelines for copper peptide complexes, NMPA regulatory pathway efficiency assumptions, and cold-chain infrastructure penetration rates for stabilized vitamin C distribution.
Underlying assumptions cover sustained K-beauty innovation investment, stable REACH enforcement intensity, and gradual India pharmacy channel liberalization, with deviation risk concentrated in retinol feedstock supply disruptions or abrupt NMPA animal-testing policy shifts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Makeup Setting Powder Market
Cosmetics & Skincare
Global Cosmetic Applicator Foam Market
Cosmetics & Skincare
Eyeliner Market
Cosmetics & Skincare
Italy Lip Care Products Market
Cosmetics & Skincare
Canada Cosmetic Products Market
Cosmetics & Skincare
Herbal Soap Market
Cosmetics & Skincare
Halal Cosmetic Products Market
Cosmetics & Skincare
Halal Cosmetics Market
Cosmetics & Skincare
UK Eyelash Serum Market
Cosmetics & Skincare
Essential Oil Soap Market
Cosmetics & Skincare
Russia Lip Care Products Market
Cosmetics & Skincare
Tea Based Face Masks Market
Cosmetics & Skincare
Sports Sun Care Market
Cosmetics & Skincare
Bangladesh Face Wash Market
Cosmetics & Skincare
Lipstick Market
Cosmetics & Skincare
Japan Organic Cosmetics Market