
 Beauty Facial Mask Market | 2026-2036
Beauty Facial Mask Market Size, Share, and Industry Trends Forecast 2026-2036
Beauty Facial Mask Market Analysis
Subscription-based replenishment programs is realigning how consumers purchase beauty facial masks, shifting transactions from episodic retail buying toward recurring revenue models. L'Oréal S.A. leverages its multi-brand portfolio to anchor subscription services across mass and prestige tiers. Estée Lauder Companies differentiates through high-touch digital consultation tools bundled with recurring mask deliveries. Shiseido Company, Ltd. competes via localized subscription formats tailored to Asian skin care rituals.
A beauty facial mask is a topical skin treatment product, typically pre-soaked in serum or formulated as a spreadable substrate, designed for timed dermal contact to deliver hydrating, clarifying, or anti-aging actives. The product type dimension shows sheet masks dominating volume due to convenience and travel-friendly formats, while clay masks command higher per-unit margins through spa-positioned detoxification claims. Gel masks represent the fastest-growing structural category, propelled by cooling sensory positioning and compatibility with sensitive skin segments.
FDA cosmetic labeling requirements and the EU Cosmetics Regulation govern ingredient disclosure and safety substantiation, compelling manufacturers to reformulate around restricted preservative systems. ECHA REACH compliance adds testing burdens for European market entry, favoring larger players with dedicated regulatory affairs capacity. ISO 22716 Good Manufacturing Practices certification increasingly functions as a baseline qualifier for professional channel distribution. Stakeholders must monitor evolving microplastic restrictions and biodegradability mandates as these frameworks extend to rinse-off cosmetic products.
Market Dynamics
Subscription-based replenishment programs are restructuring purchase patterns across the beauty facial mask sector, converting episodic retail transactions into predictable recurring revenue streams that alter inventory planning and customer lifetime value calculations for manufacturers.
Growth Catalysts
- K-Beauty Innovation Cycles:Seoul metropolitan cluster laboratories compress product development timelines from concept to shelf, accelerating format and ingredient iteration that keeps consumer engagement high.
- Clean Beauty Certification:ECHA REACH compliance requirements in Europe are reformulating ingredient standards, eliminating restricted preservative systems and creating premium positioning for compliant formulations.
- Professional Channel Expansion:Premium spa and salon adoption among licensed aestheticians is elevating mask treatments from home-use commodities to service-anchored experiences with higher per-session economics.
Market Restraints
- Biodegradability Mandates:Evolving microplastic restrictions targeting rinse-off cosmetic products are forcing structural substrate redesigns for sheet and hydrogel formats, raising R&D costs.
- Regulatory Testing Burden:ECHA REACH compliance adds substantial safety substantiation requirements for European market entry, favoring larger players with dedicated regulatory affairs capacity over mid-tier competitors.
- Input Cost Volatility:Specialized bio-cellulose and bioceramic substrate materials face supply concentration among Korean and Japanese specialty fiber producers, creating margin pressure during currency fluctuations.
Strategic Opportunities
- Men's Grooming Penetration:Underdeveloped male facial care segments in North American and European markets present white-space expansion for detoxifying clay and cooling gel formats positioned outside traditional feminine coding.
- ISO 22716 Certification Arbitrage:Good Manufacturing Practices certification increasingly functions as a baseline qualifier for professional channel distribution, creating competitive moats for early certifiers.
- Digital Consultation Integration:High-touch virtual skin assessment tools bundled with recurring mask deliveries are redefining customer acquisition economics and reducing churn in direct-to-consumer channels.
Industry Challenges
- Formulation Talent Scarcity:Cosmetic chemists with dual expertise in clean ingredient compliance and sensory engineering command premium compensation, constraining mid-cap R&D expansion.
- Legacy System Integration:Subscription platform implementation requires reconfiguring ERP and fulfillment infrastructure originally architected for wholesale batch distribution, creating operational friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beauty Facial Mask Market |
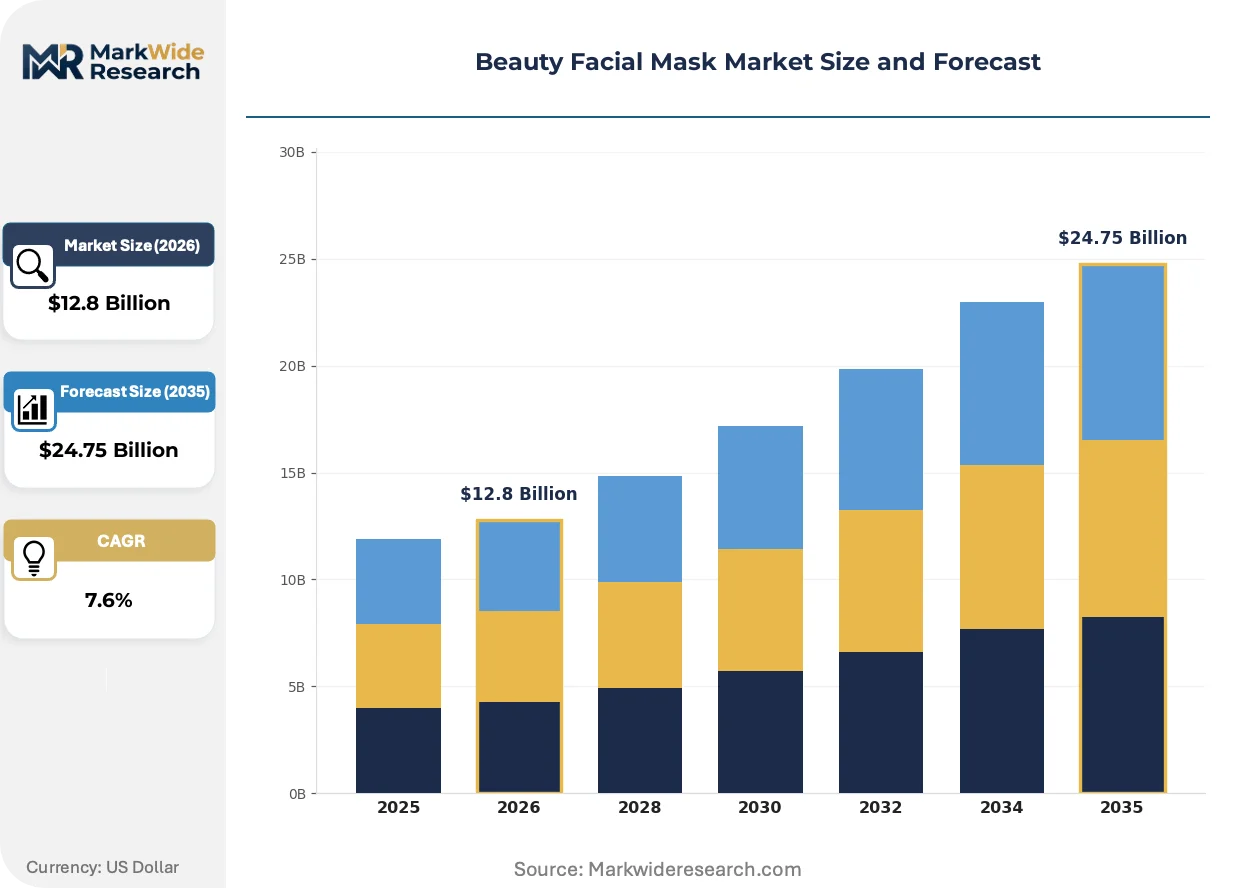
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $24.75 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet Mask, Gel Mask, Cream Mask, Clay Mask Ingredient Type: Natural, Organic, Synthetic, Hydrating Application: Daily Use, Spa Treatment, Special Occasion, Professional Use Customer Type: Men, Women, Teenagers, Seniors |
| Companies Covered | L'Oréal S.A, Estée Lauder Companies, Procter & Gamble Company, Shiseido Company, Ltd., Johnson & Johnson, Unilever Plc, Clarins S.A., Kao Corporation, Amorepacific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beauty Facial Mask Market Emerging Trajectories
Active ingredient delivery systems and substrate engineering are converging to redefine efficacy claims, while regulatory frameworks and consumption patterns simultaneously reshape how masks are formulated, certified, and purchased across mass and prestige tiers.
Bio-cellulose fermentation-derived substrates are overtaking traditional cotton and rayon sheet materials in premium positioning. Dermatology clinics and medi-spa channels are adopting these formats at accelerated pace due to superior serum retention and occlusive properties. This substrate shift is overtaking established supply relationships with textile converters and compressing margin structures for legacy material suppliers.
EU Cosmetics Regulation amendments governing ingredient disclosure are tightening safety substantiation requirements for preservative systems and fragrance allergens. Manufacturers are reformulating around restricted compounds and investing in alternative stabilization technologies. Professional-grade mask lines targeting European spa distribution are most affected, with many accelerating ISO 22716 certification timelines to maintain channel access.
Replenishment automation through subscription platforms is displacing traditional retail replenishment triggers. Direct-to-consumer brands and multi-brand portfolios alike are capturing predictable revenue streams that reduce customer acquisition cost amortization periods. This behavioral shift concentrates in South Korea and Japan, where mobile-first commerce infrastructure supports seamless recurring payment integration with skin analysis app ecosystems.
Beauty Facial Mask Market Segmentation
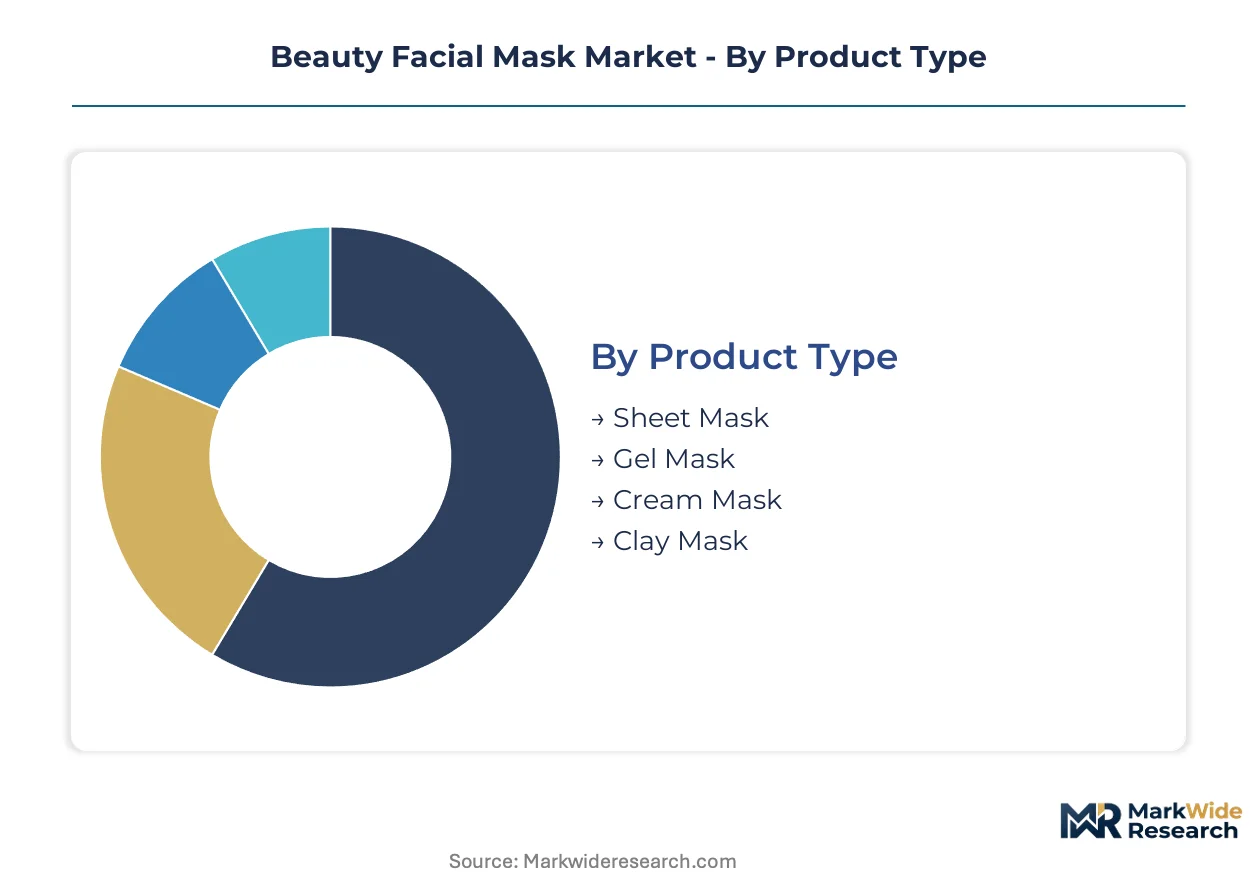
Product architecture in the beauty facial mask market determines capital allocation across substrate manufacturing, serum formulation, and distribution infrastructure. Segment boundaries increasingly blur as hybrid formats emerge, yet each category retains distinct margin profiles and regulatory exposure that shape manufacturer portfolio strategy.
Product Type:
Capital intensity peaks with bio-cellulose fermentation facilities and specialized hydrogel casting equipment, while clay extraction and sheet material sourcing require lower fixed-asset deployment.
- Sheet Mask:Pre-cut fiber substrates pre-soaked in serum dominate volume throughput. Demand concentrates in South Korea's Seoul metropolitan cluster, where K-beauty innovation cycles compress development timelines and sustain consumer engagement through rapid format iteration.
- Gel Mask:Hydrogel matrices deliver cooling sensory positioning and compatibility with sensitive skin segments. Professional medi-spa channels in Japan and South Korea are adopting these formats at accelerated pace due to superior occlusive properties and extended wear comfort.
- Cream Mask:Spreadable emulsion substrates support richer occlusive delivery for overnight protocols. European spa distribution favors these formats for service-anchored experiences.
- Clay Mask:Mineral-rich spreadable substrates command premium per-unit margins through detoxification claims. Manufacturing scales through contract processors with existing cosmetic emulsion capacity.
Most installed capacity flows through Sheet Mask. Expansion is steepest in Gel Mask.
Ingredient Type:
Formulation cost structures diverge sharply between certified organic supply chains and synthetic active production, with natural positioning occupying a mid-tier pricing band.
- Natural:Botanically derived actives without synthetic chemical processing. ECHA REACH compliance requirements in Europe are eliminating restricted preservative systems and creating premium positioning for compliant natural formulations.
- Organic:Certified cultivation and extraction protocols with full traceability documentation. Professional channel penetration in Germany and France requires third-party certification investment that smaller formulators struggle to absorb.
- Synthetic:Laboratory-engineered molecules with precise concentration control and batch consistency. Manufacturing scales efficiently through established chemical suppliers.
- Hydrating:Hyaluronic acid and glycerin-forward formulations targeting transdermal moisture retention. Asian direct-to-consumer brands bundle these with subscription replenishment programs.
Organic commands the highest per-unit pricing. Natural is gaining share fastest in European professional distribution.
Application:
Channel economics separate high-frequency replenishment models from episodic service-anchored purchases, with inventory velocity varying tenfold across use cases.
- Daily Use:Single-serve formats designed for at-home integration into morning or evening rituals. Subscription platforms in South Korea and Japan capture predictable revenue through mobile-first recurring payment integration.
- Spa Treatment:Professional-grade formulations with elevated active concentrations for licensed aesthetician application. Premium spa and salon channels in the United States and United Kingdom are elevating mask treatments from commodities to experience-anchored services.
- Special Occasion:Prestige-positioned formats for event preparation and gifting. Seasonal demand spikes concentrate around holiday periods and wedding seasons.
- Professional Use:Dermatology clinic and medi-spa protocols requiring ISO 22716 Good Manufacturing Practices certification. This baseline qualifier increasingly functions as a competitive moat for early certifiers.
Daily Use generates the highest absolute volume. Professional Use carries the steepest margin expansion trajectory.
Customer Type:
Demographic targeting determines packaging design, fragrance profiles, and retail placement, with male-oriented formats requiring substantial repositioning investment.
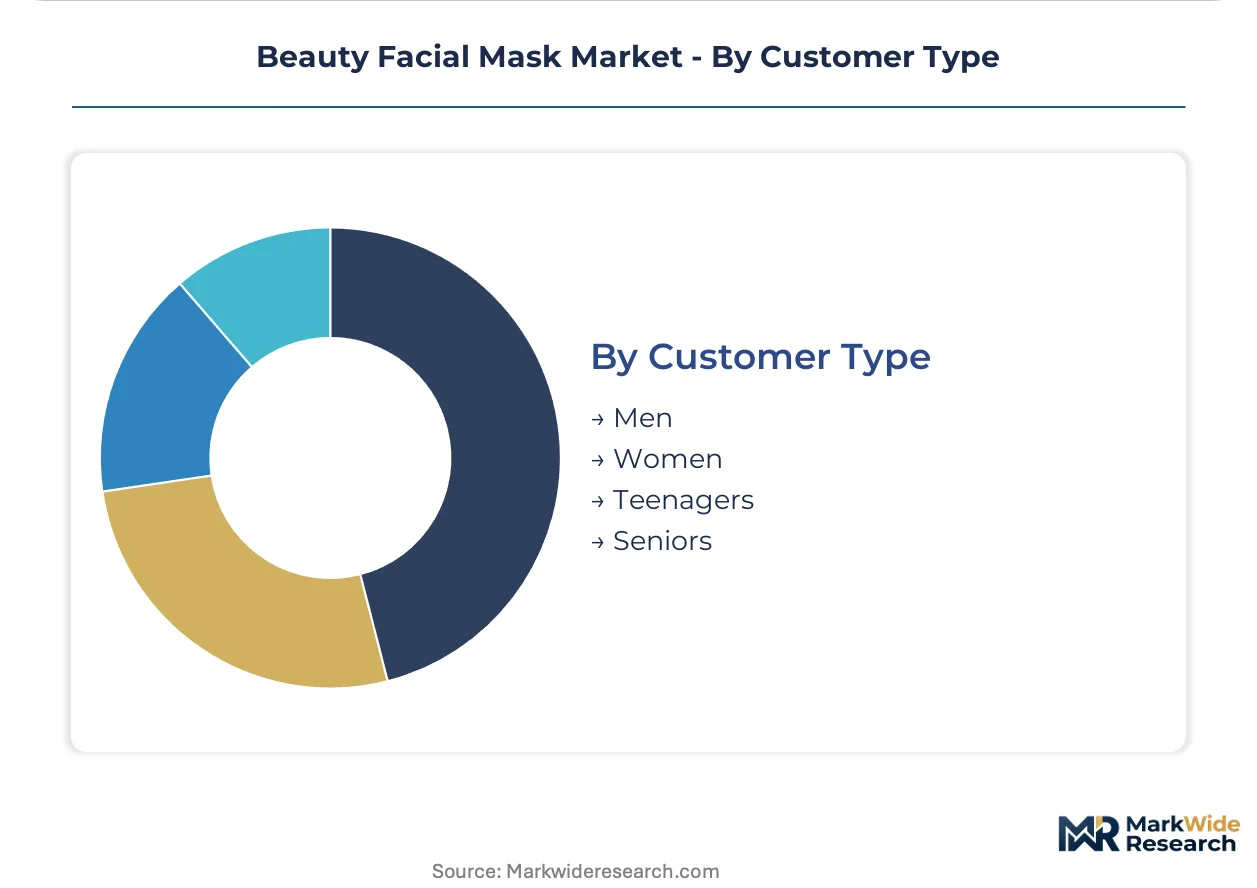
- Women:Core category demand with established purchase rituals across mass and prestige tiers. Subscription services from multi-brand portfolios anchor recurring revenue across life-stage segments.
- Men:Underdeveloped facial care segments in North American and European markets present white-space expansion. Detoxifying clay and cooling gel formats positioned outside traditional feminine coding are gaining trial.
- Teenagers:Acne-focused formulations with accessible price points and social media-native marketing. K-beauty brands leverage compressed innovation cycles to maintain relevance with this cohort.
- Seniors:Anti-aging actives with barrier repair and collagen-support claims. Professional consultation channels in Japan support premium positioning for this segment.
Women retain the largest installed base. Men represent the steepest expansion opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's Seoul metropolitan cluster compresses product development timelines faster than Germany's regulatory-heavy approval pathways, creating divergent innovation velocities across major beauty facial mask markets.
United States
Premium spa and salon channels elevate mask treatments from home-use commodities to service-anchored experiences with higher per-session economics. FDA cosmetic labeling requirements govern ingredient disclosure and safety substantiation for domestic manufacturers. Professional-grade distribution concentrates in Los Angeles and New York City metro areas, where licensed aesthetician density supports premium positioning.
South Korea
K-beauty innovation cycles sustain consumer engagement through rapid format iteration and compressed concept-to-shelf timelines. MFDS regulates cosmetic safety and efficacy claims under the Cosmetics Act, with Seoul-based laboratories driving substrate engineering advances. The Seoul Capital Area hosts dense clusters of bio-cellulose fermentation facilities and hydrogel casting operations serving regional export demand.
Germany
Clean beauty certification from ECHA REACH compliance creates premium positioning for reformulated preservative-free formulations. The EU Cosmetics Regulation mandates strict safety substantiation for professional channel distribution. Industrial activity clusters in North Rhine-Westphalia and Bavaria, where contract manufacturers serve European spa and salon networks with ISO 22716-certified production.
Japan
Subscription replenishment programs capture predictable revenue through mobile-first recurring payment integration with skin analysis app ecosystems. METI oversees cosmetic manufacturing standards and market surveillance under the Pharmaceutical and Medical Device Act. The Kanto region around Tokyo anchors gel mask adoption in professional medi-spa channels seeking superior occlusive properties.
France
Prestige-positioned formats for event preparation and gifting sustain seasonal demand spikes around holiday periods. ANSM enforces cosmetic safety regulations alongside EU-level REACH compliance requirements. The Île-de-France region, particularly Paris and its cosmetics industry corridor, concentrates headquarters operations for heritage beauty houses with professional mask portfolios.
Beauty Facial Mask Market Vendor Landscape
Top-tier vendors anchor multi-brand portfolios spanning mass and prestige tiers, while mid-cap specialists concentrate on substrate engineering and clean formulation certification. The vendor base organizes around three strategic archetypes: integrated beauty conglomerates with subscription platform infrastructure, regional champions leveraging compressed innovation cycles, and contract manufacturers with ISO 22716 certification moats. Dominant competitive moves include portfolio diversification across product type segments and strategic partnerships with professional channel distributors.
Within the integrated conglomerate tier, L'Oréal S.A. and Estée Lauder Companies exemplify scale-driven players with recurring revenue platform infrastructure, while Shiseido Company, Ltd. occupies a position bridging Eastern and Western market architectures through localized subscription formats.
| Leading Market Players |
|---|
| L'Oréal S.A |
| Estée Lauder Companies |
| Procter & Gamble Company |
| Shiseido Company, Ltd. |
| Johnson & Johnson |
| Unilever Plc |
| Clarins S.A. |
| Kao Corporation |
| Amorepacific Corporation |
| Others |
Supply Flow & Price Mechanics
Bio-cellulose fiber spot prices in South Korea cascade through substrate manufacturing tiers, compressing margins for sheet mask converters while elevating premium positioning for hydrogel formats with superior serum retention economics.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard cotton and rayon sheet substrates. Three-tier pricing structure across premium bio-cellulose, standard fiber, and economy non-woven levels separates dermatology clinic-grade formulations from mass retail alternatives. Price differentiation hinges on ISO 22716 certification status and substrate fermentation origin. Cost compression in economy tiers is intensifying because Chinese converters are absorbing currency fluctuation impacts to maintain volume contracts. Daily-use subscription buyers exhibit highest price sensitivity, while professional spa channels remain least elastic due to service-anchored markup structures.
Supply Chain Analysis
Bio-cellulose fermentation feedstock rests on South Korean and Japanese specialty fiber producers with concentrated casting operations in Seoul and Osaka metropolitan clusters. Raw material dependencies span nata de coco substrate precursors, bioceramic mineral additives, and pharmaceutical-grade hyaluronic acid active stocks. Supply chain risk centers on single-source vulnerability for premium hydrogel matrices, where Japanese producers control proprietary cross-linking chemistry. Distribution runs through professional spa networks in Germany and France, direct-to-consumer platforms in South Korea and Japan, and mass retail consolidation in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Cosmetics Regulation amendments function as a regulatory compounder, with ECHA REACH compliance timelines accelerating demand for certified clean formulations across professional European distribution.
For Market Incumbents: Acquire ISO 22716-certified contract manufacturing capacity to preempt channel access restrictions. Consolidate substrate fermentation assets in Seoul metropolitan cluster to secure bio-cellulose supply continuity against Korean Won volatility. L'Oréal S.A. and Estée Lauder Companies anchor defensive positioning through multi-brand subscription infrastructure that raises customer switching costs. For New Entrants and Emerging Players: Capture underdeveloped male facial care segments in North American markets through detoxifying clay formats positioned outside traditional feminine coding. Target white-space expansion in professional medi-spa channels seeking cooling gel alternatives with sensitive skin compatibility claims. Launch through bundled digital consultation tools that reduce customer acquisition friction in direct-to-consumer channels. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap formulators possessing dual expertise in clean ingredient compliance and sensory engineering. Long-term viability favors acquisition targets with established ECHA REACH documentation and Korean substrate sourcing relationships. Watch subscription platform integration rates as the inflection signal for recurring revenue durability.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Cellulose Substrate Scale-Up | Fermentation facility investment secures premium positioning against cotton and rayon alternatives. |
| ECHA REACH Certification Pathway | Regulatory compliance investment unlocks professional spa distribution across Germany and France. |
| Subscription Platform Integration | Recurring revenue infrastructure reduces customer acquisition cost amortization in South Korea. |
| Men's Grooming Line Extension | Detoxifying clay formats penetrate underdeveloped North American male facial care segments. |
| Digital Consultation Partnership | Virtual skin assessment tools bundled with mask deliveries redefine acquisition economics. |
Methodological Framework
Direct dialogue with cosmetic chemists, professional aesthetician network heads, regulatory affairs directors at ECHA, and subscription platform operations managers grounds qualitative findings. Secondary validation draws from MFDS cosmetic safety filings, EU Cosmetics Regulation amendment trackers, Seoul-based bio-cellulose production databases, and customs trade records for substrate fiber imports. Bottom-up volume modeling triangulates against top-down market sizing from prestige and mass channel revenue aggregation.
Bottom-up demand modeling segments across product type, ingredient certification tier, application frequency, and customer demographic dimensions throughout the forecast period. CAGRs derive from growth rate convergence analysis across segment-level volume trajectories. Industry-specific forecast inputs incorporate K-beauty innovation cycle compression rates and professional channel certification penetration curves.
Regulatory enforcement intensity, raw material currency fluctuation, and subscription churn rate volatility are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about clean beauty certification adoption timelines and substrate technology substitution elasticities. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Bath Soap Market
Cosmetics & Skincare
Face Bronzer Market
Cosmetics & Skincare
Eye Shadow Market
Cosmetics & Skincare
Organic Soaps Market
Cosmetics & Skincare
Sun Care Market
Cosmetics & Skincare
Herbal Soap Market
Cosmetics & Skincare
Matte Lipstick Market
Cosmetics & Skincare
Mushroom Beauty Products Market
Cosmetics & Skincare
Probiotic Skin Care Cosmetic Product Market
Cosmetics & Skincare
Asia-Pacific Face Compact Market
Cosmetics & Skincare
Waterproof Eyebrow Liner Market
Cosmetics & Skincare
Sports Sun Care Market
Cosmetics & Skincare
Face Compact Market
Cosmetics & Skincare
Canada Cosmetic Products Market
Cosmetics & Skincare
Eyeliner Pen Market
Cosmetics & Skincare
Magnetic Fake Eyelashes Market