
 Mascara Applicators Market | 2026-2036
Mascara Applicators Market Size, Share, and Industry Trends Forecast 2026-2036
Mascara Applicators Market Foresight
Chinese injection-molding capacity for cosmetic-grade polymers is restructuring supply availability for mascara wands and brush assemblies. Albéa leverages integrated manufacturing across European and Asian facilities to sustain consistent output for luxury brand clients. Anisa International specializes in custom brush architecture, while L'Oréal anchors significant captive demand through in-house applicator specification and volume procurement.
Mascara applicators are precision-formed cosmetic tools, typically injection-molded from polypropylene or assembled with nylon or polyester filament bristles in helical or straight-cut configurations, designed to deposit, distribute, and separate lash-coating formulations with controlled loading and release. Silicone-tipped variants now compete with traditional fiber brushes in premium positioning, with plastic retaining dominant unit volume across mass-market channels. Professional use applications command higher per-unit margins than personal use segments, while eco-friendly material development is reshaping procurement specifications among Western beauty brands.
FDA cosmetic labeling requirements and EU REACH substance restrictions govern material composition and migration limits for applicators contacting ocular-adjacent formulations. ECHA evaluations of microplastic additives further pressure converters toward bio-based or recyclable polymer alternatives. Stakeholders must monitor evolving extended producer responsibility frameworks and material certification standards to preempt compliance-driven sourcing disruptions.
Market Dynamics
REACH substance restrictions and ECHA microplastic evaluations are forcing immediate material transitions across European cosmetic packaging supply chains, compressing converter lead times and accelerating bio-based polymer qualification programs.
Growth Catalysts
- EU Green Deal packaging mandates:Extended producer responsibility frameworks in France and Germany now require post-consumer recycled content thresholds, pulling demand toward certified sustainable applicator sources.
- Professional service expansion:Beauty salons and freelance makeup artists in South Korea and the United Arab Emirates are upgrading tool inventories, driving premium brush architecture specifications.
- Silicone-tip technology maturation:Precision molding advances enable complex helical geometries previously exclusive to fiber brushes, opening premium positioning for synthetic alternatives.
Market Restraints
- Polypropylene feedstock volatility:Propylene monomer supply disruptions in Chinese petrochemical corridors transmit directly to injection-molding cost structures.
- Single-supplier filament concentration:Nylon 6.6 bristle sourcing clusters heavily in Zhejiang province, creating geographic concentration risk for Western brand owners.
- Migration testing bottlenecks:FDA ocular irritation protocols and EU cosmetics regulation safety assessments extend new material approval timelines by 8-14 months.
Strategic Opportunities
- Indian prestige retail underpenetration:Organized beauty specialty stores in Mumbai and Delhi remain underserved by branded applicator assortments, presenting first-mover channel potential.
- Direct-to-consumer customization:Subscription beauty boxes and personalized mascara formulations create demand for bespoke wand geometries matched to individual lash profiles.
- Bio-based polymer regulatory tailwinds:Italy and Spain now offer green procurement certification premiums for packaging converters demonstrating carbon footprint reductions.
Industry Challenges
- Tooling engineer scarcity:Precision mold design for micro-feature cosmetic components requires specialized expertise concentrated in German and Japanese technical institutes.
- Multi-material disassembly compliance:EU single-use plastics directive recyclability targets conflict with fiber brush metal ferrule bonding techniques, forcing redesign cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mascara Applicators Market |
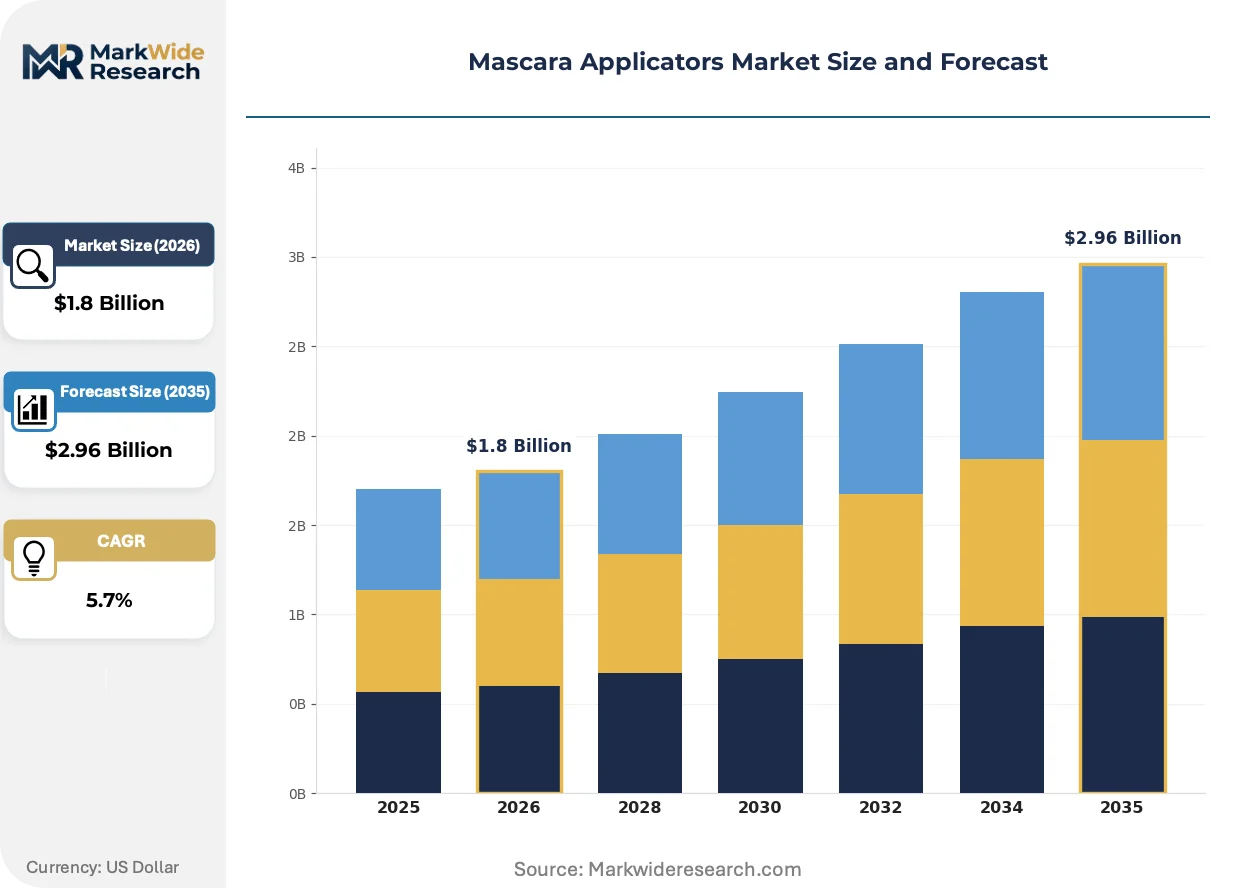
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
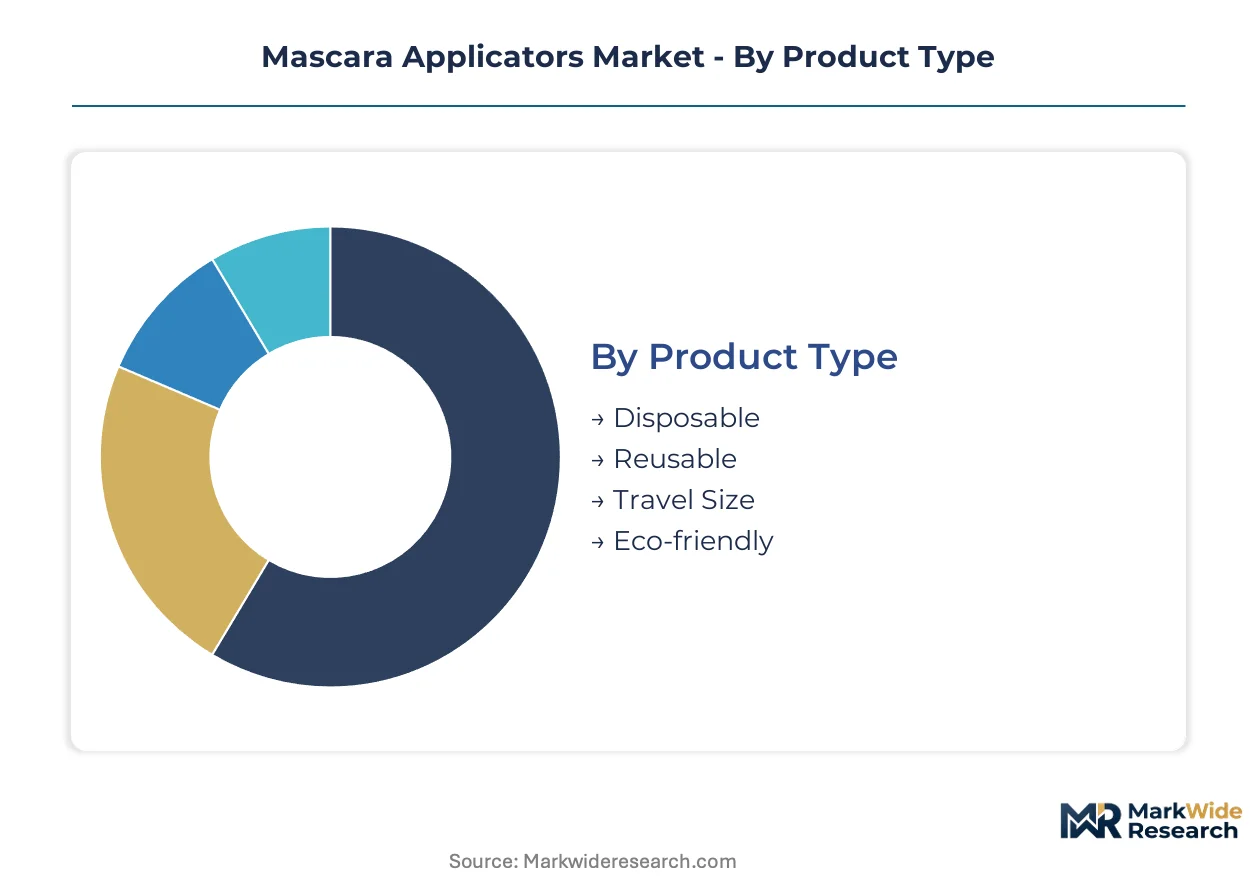
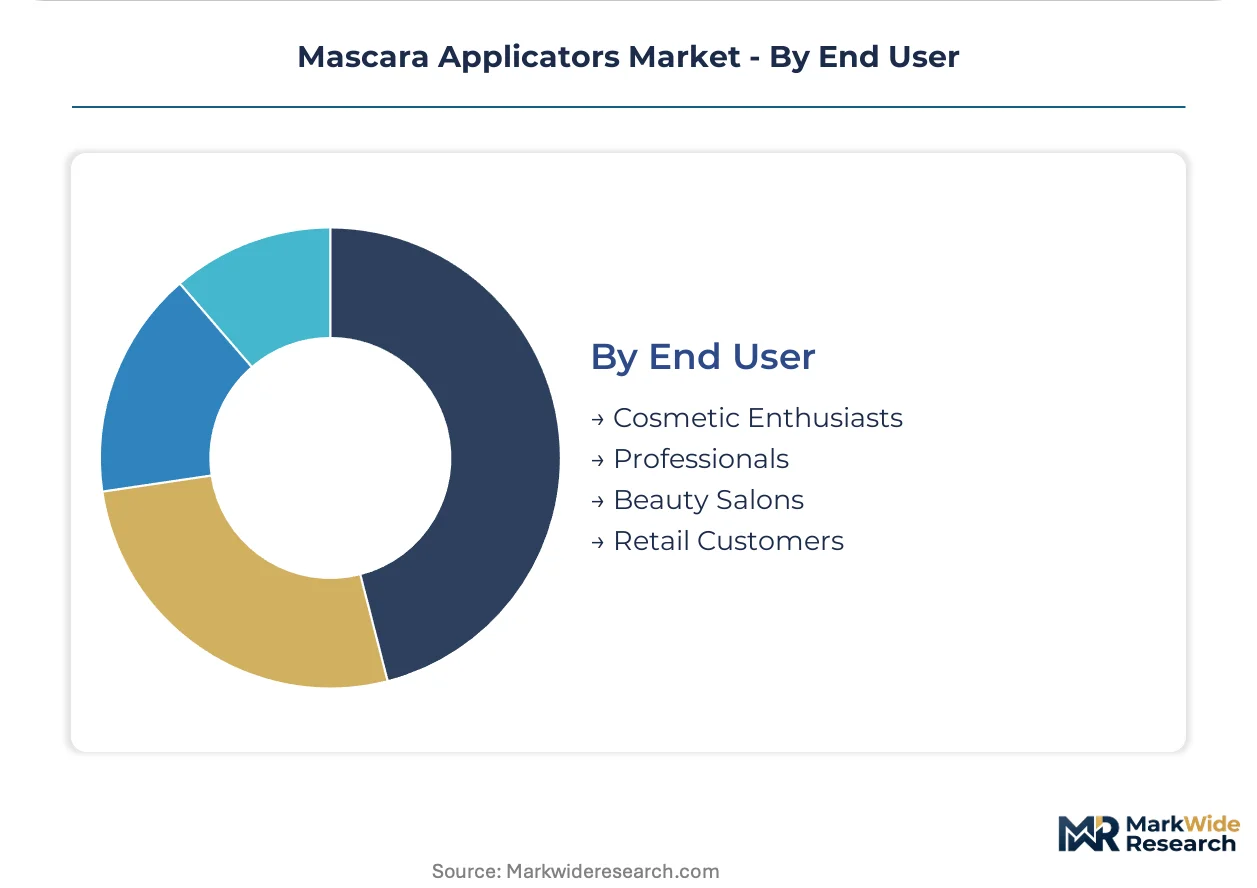
| Segmentation | Product Type: Disposable, Reusable, Travel Size, Eco-friendly Application: Personal Use, Professional Use, Retail Sales, Online Sales Material: Plastic, Silicone, Natural Fibers, Metal End User: Cosmetic Enthusiasts, Professionals, Beauty Salons, Retail Customers |
| Companies Covered | L'Oréal, Estée Lauder Companies, Markwins International, Shiseido, Chanel, Albéa, Cospack America Corporation, Anisa International, International Cosmetic Suppliers Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mascara Applicators Market Shifts & Advancements
Applicator architecture is fragmenting into application-specific geometries as lash cosmetic formulations diversify in viscosity and fiber-loading characteristics. This specialization pressures standardized brush portfolios.
Silicone injection molding is modularizing production economics for complex tip geometries. Korean beauty brands and professional makeup houses are adopting these platforms fastest. The technology is modularizing what were previously discrete fiber brush and metal ferrule supply chains into single-component molding operations.
REACH Annex XVII restrictions on intentionally added microplastics are tightening migration thresholds for polymer additives in ocular-adjacent products. German converters face immediate reformulation deadlines. Premium brand portfolios with EU manufacturing exposure are accelerating bio-based polypropylene pilot programs to preempt enforcement actions.
Beauty retailers are unbundling applicator replacement from mascara repurchase, selling standalone brushes through specialty channels. Sephora and Ulta have expanded dedicated tool sections. This pattern concentrates in the United States where premium beauty retail formats support higher-margin accessory positioning independent of core cosmetic sales.
Mascara Applicators Market Segmentation
Mascara applicator procurement splits sharply between standalone tool purchases and embedded systems bundled with formulation sales. Understanding these integration patterns reveals where margin capture concentrates and where specification control shifts between brand owners and contract manufacturers.
Product Type:
Disposable applicators dominate embedded mascara systems, while reusable and eco-friendly variants command standalone retail positioning with higher per-unit economics.
- Disposable:Single-use polypropylene wands and fiber brushes ship pre-loaded in mascara tubes. Mass-market brands in the United States specify these for cost-controlled volume production.
- Reusable:Precision-engineered silicone tips and metal-core brushes withstand repeated cleaning cycles. Sephora and Ulta channel expansion drives demand for these premium standalone tools.
- Travel Size:Compact dual-ended designs with shortened handles target airline retail and subscription box formats.
- Eco-friendly:Bio-based polypropylene and cellulose-derived filaments respond to EU Green Deal procurement mandates in France and Germany.
Disposable leads volumes today; eco-friendly is gaining share fastest.
Application:
Channel structure determines specification authority, with professional use segments demanding custom geometries that personal use mass production cannot accommodate.
- Personal Use:Standardized helical and straight-cut fiber brushes serve individual consumers through drugstore and supermarket channels.
- Professional Use:Freelance makeup artists and beauty salons in South Korea and the United Arab Emirates specify precision-molded silicone tips with complex lash-separating geometries.
- Retail Sales:Dedicated tool sections at beauty specialty stores unbundle applicator replacement from core cosmetic purchases.
- Online Sales:Direct-to-consumer subscriptions enable bespoke wand-matching to individual lash profiles.
Personal use anchors volume scale; professional use expands most quickly.
Material:
Material selection governs regulatory compliance burden, with REACH and FDA migration thresholds creating divergent qualification timelines across polymer categories.
- Plastic:Injection-molded polypropylene retains dominant unit volume across mass-market channels despite ECHA microplastic evaluation pressures.
- Silicone:Liquid silicone rubber enables single-component molding of complex tip geometries previously requiring fiber-ferrule assembly.
- Natural Fibers:Tapered animal hair and plant-derived filaments serve prestige positioning in Japanese and French luxury houses.
- Metal:Stainless steel ferrules and aluminum handle cores concentrate in professional-grade tool manufacturing.
Plastic commands absolute volume; silicone shows the steepest expansion trajectory.
End User:
User sophistication determines willingness to pay for specification precision, segmenting the market between price-sensitive routine purchasers and performance-driven professionals.
- Cosmetic Enthusiasts:Informed consumers seeking specific lash effects drive standalone tool purchases through specialty retail.
- Professionals:Freelance makeup artists maintain diverse tool inventories with application-specific geometries for editorial and bridal work.
- Beauty Salons:Service-oriented cosmetics consumption in South Korea and the United Arab Emirates upgrades institutional tool procurement standards.
- Retail Customers:Impulse-driven mass-market purchasers accept bundled applicators as part of core mascara transactions.
Retail customers generate the highest transaction volumes; beauty salons are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between jurisdictions is redirecting manufacturing investment toward compliance-advantaged locations. EU REACH substance restrictions and extended producer responsibility mandates elevate operational costs for European converters, while Asian production clusters capture volume through integrated supply chains and lower qualification overhead.
United States
Premium beauty retail expansion at Sephora and Ulta drives standalone applicator demand through dedicated tool sections. FDA ocular irritation protocols govern material approval timelines for new polymer introductions. New York and Los Angeles anchor brand headquarters procurement decisions, with direct-to-consumer channels commanding disproportionate specification authority.
Germany
REACH Annex XVII enforcement pressures immediate reformulation of polymer additives in ocular-adjacent products. ECHA microplastic evaluations compress converter lead times for bio-based alternatives. Stuttgart and Hamburg host precision mold engineering expertise concentrated in technical institutes serving cosmetic component fabricators.
China
Zhejiang province clusters nylon 6.6 bristle sourcing for global brush assembly supply chains. SAMR cosmetic packaging standards intersect with provincial environmental compliance frameworks. Guangdong and Jiangsu injection-molding corridors restructure polypropylene availability for mascara wand production.
France
EU Green Deal packaging mandates require post-consumer recycled content thresholds for beauty sector procurement. ANSM cosmetic safety assessments overlay REACH migration limits for polymer-based applicators. Paris luxury houses anchor prestige positioning for natural fiber and metal-ferrule tool specifications.
South Korea
Beauty salon service expansion and freelance makeup artist networks upgrade professional tool inventory standards. MFDS cosmetic ingredient regulations align with broader Asia-Pacific harmonization initiatives. Seoul-based brands pioneer silicone-tip technology adoption for complex helical geometries previously exclusive to fiber brushes.
Mascara Applicators Market Competitive Landscape
European integrated manufacturers anchor one tier; Asian specialists hold cost-optimized volume production. The market structures around three tiers: captive brand-owned operations, independent luxury suppliers, and contract converters serving mass-market channels. Two dominant competitive moves define current positioning: strategic partnerships between material suppliers and mold engineering houses, and geographic expansion of silicone injection-molding platforms into Korean and Chinese facilities.
Among diversified beauty conglomerates, L'Oréal and Estée Lauder Companies occupy positions reflecting captive demand through in-house applicator specification and volume procurement. Albéa represents the integrated manufacturing archetype with cross-continental facility networks sustaining consistent output for luxury brand clients. Anisa International exemplifies the custom architecture specialist segment, focusing on precision brush design distinct from standardized mass-market offerings.
| Leading Market Players |
|---|
| L'Oréal |
| Estée Lauder Companies |
| Markwins International |
| Shiseido |
| Chanel |
| Albéa |
| Cospack America Corporation |
| Anisa International |
| International Cosmetic Suppliers Ltd. |
| Others |
Supply & Pricing Matrix
Precision mold engineering expertise concentrated in Stuttgart and Hamburg technical institutes creates labor-cost differentials that widen pricing-tier spreads between German-engineered premium applicators and Asian mass-market alternatives. This workforce geography forces brand owners to arbitrage specification authority against landed cost targets.
Pricing Analysis
Retailer markup layers at Sephora and Ulta compress manufacturer margins while direct-to-OEM channels preserve pricing power for volume commitments. Three-tier pricing structure across premium silicone-tip, standard fiber-brush, and economy polypropylene levels separates professional-grade tools from mass-market disposables. Cost compression in the embedded-applicator tier intensifies because propylene monomer volatility transmits directly to injection-molding economics. Cosmetic enthusiasts show least price sensitivity for standalone precision tools; retail customers accepting bundled applicators drive hardest bargain.
Supply Chain Analysis
Single-source vulnerability sits with Zhejiang province nylon 6.6 bristle concentration, which feeds global brush assembly operations. Manufacturing gravity centers on China, South Korea, and Germany for distinct process stages: Chinese injection-molding for polypropylene wands, Korean silicone-tip precision molding, German mold engineering. Raw material dependencies span propylene monomer, liquid silicone rubber, and cellulose-derived filaments. Tariff exposure on Chinese cosmetic packaging imports creates structural risk for Western brand owners. Distribution runs through beauty specialty retail, direct-to-consumer subscription platforms, and professional salon supply houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mascara applicator margins are expanding through silicone-tip technology maturation, which collapses fiber-ferrule assembly costs into single-component molding while commanding premium positioning. Bio-based polymer regulatory tailwinds in Italy and Spain further shift procurement toward certified sustainable sources with pricing power.
For Market Incumbents: Cement specification control by deepening backward integration into precision mold engineering capabilities at Stuttgart technical institutes. Accelerate bio-based polypropylene pilot programs to preempt REACH Annex XVII enforcement deadlines. Channel control through dedicated tool sections at Sephora and Ulta defends against unbundling pressure from standalone brush competitors.
For New Entrants and Emerging Players: Subscription beauty box partners offer lowest-friction customer acquisition for bespoke wand-matching services. Indian prestige retail in Mumbai and Delhi presents the most penetrable geography, with organized beauty specialty stores currently underserved by branded applicator assortments. Direct-to-consumer customization platforms enable bypass of incumbent retail markup layers entirely.
For Investors and Strategic Acquirers: Beauty conglomerates with captive demand are the most active acquirer in this space, seeking custom brush architecture specialists to internalize specification authority. Target acquisition archetypes include precision silicone-molding houses with Korean facility footprints and bio-based polymer qualification capabilities. Watch ECHA microplastic evaluation enforcement timelines as inflection indicator for material substitution investment windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Injection Molding Platform Expansion | Korean brands pioneer complex helical geometries previously exclusive to fiber brushes. |
| Bio-based Polymer Qualification Programs | German converters face immediate REACH Annex XVII reformulation deadlines. |
| Direct-to-Consumer Customization Launch | Subscription boxes enable bespoke wand-matching to individual lash profiles. |
| Professional Salon Channel Penetration | South Korean and UAE beauty salons upgrade institutional tool procurement standards. |
| Precision Mold Engineering Acquisition | Stuttgart technical institutes concentrate expertise for micro-feature cosmetic components. |
Research Methodology
Direct dialogue with cosmetic packaging procurement managers, precision mold engineers at German technical institutes, regulatory affairs specialists at ECHA, and beauty salon operators in Seoul anchored qualitative grounding. Secondary validation drew from FDA cosmetic labeling guidance documents, REACH Annex XVII substance restriction updates, EU Green Deal packaging mandate texts, and customs records for polypropylene and nylon filament trade flows. Bottom-up applicator volume estimates triangulated against top-down beauty sector expenditure models.
Segment-level outputs across the projection horizon reflect modeling of product type tiers, application channels, material categories, and end-user sophistication levels. CAGRs were derived from regression analysis of historical procurement patterns against regulatory enforcement timelines and technology adoption curves. Silicone-tip technology maturation rates and bio-based polymer qualification pipelines served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA microplastic evaluation enforcement timing and propylene monomer supply disruptions in Chinese petrochemical corridors. Forecasts reflect documented assumptions about regulatory harmonization and material substitution cost curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Lip Scrub Market
Cosmetics & Skincare
Myanmar Skin Care Products Market
Cosmetics & Skincare
Silicone Makeup Sponge Market
Cosmetics & Skincare
K-Beauty Products Market
Cosmetics & Skincare
Eye Shadow Market
Cosmetics & Skincare
Medicated Shampoo Market
Cosmetics & Skincare
Bath Soap Market
Cosmetics & Skincare
Temporary Tattoo Market
Cosmetics & Skincare
Tinted Cosmetics Market
Cosmetics & Skincare
Face Bronzer Market
Cosmetics & Skincare
Hyaluronic Acid Beauty Products Market
Cosmetics & Skincare
Makeup Remover Product Market
Cosmetics & Skincare
UK Eyelash Serum Market
Cosmetics & Skincare
Waterproof Eyebrow Liner Market
Cosmetics & Skincare
Deodorant Stick Market
Cosmetics & Skincare
Global Cosmetic Applicator Foam Market