
 Asia-Pacific Face Compact Market | 2026-2036
Asia-Pacific Face Compact Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Face Compact Market Insights
Buyer concentration across Asia-Pacific beauty retail is rebalancing as specialty beauty stores and online retail platforms fragment purchasing power away from traditional department store channels. Shiseido Company anchors its position through premium powder compact lines distributed heavily in Japanese department stores. Amorepacific Corporation leverages K-beauty brand strength to dominate online retail channels across South Korea and expanding into Southeast Asian markets. L'Oréal SA competes through localized R&D centers in China that adapt cream and liquid compact formulations for humidity-resistant wear in tropical climates.
Asia-Pacific face compacts are pressed or molded cosmetic formulations containing pigments, binders, and fillers designed for portable facial coverage, typically housed in mirror-equipped cases with application sponges. Manufacturing employs high-pressure compression at specific density thresholds to prevent crumbling while ensuring even pigment dispersion across powder and cream variants. Powder compacts occupy the largest volume share across luxury and mid-range price tiers, though liquid formats are gaining traction among professional artists seeking buildable coverage. Specialty beauty stores capture the highest margin pools in South Korea and Japan, while online retail channels in China and India are expanding fastest among budget and mid-range segments.
China's NMPA enforces GB standards for cosmetic safety testing, including mandatory heavy metal screening for talc-based powder compacts before market authorization. South Korea's MFDS and Japan's MHLW maintain parallel but divergent ingredient disclosure requirements that fragment compliance pathways for multinational brands. India's BIS certification for imported cosmetics adds procedural delays that constrain rapid scaling for newer entrants. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple Asia-Pacific jurisdictions, as these compounds appear in long-wear compact formulations and face prospective phase-out timelines.
Market Dynamics
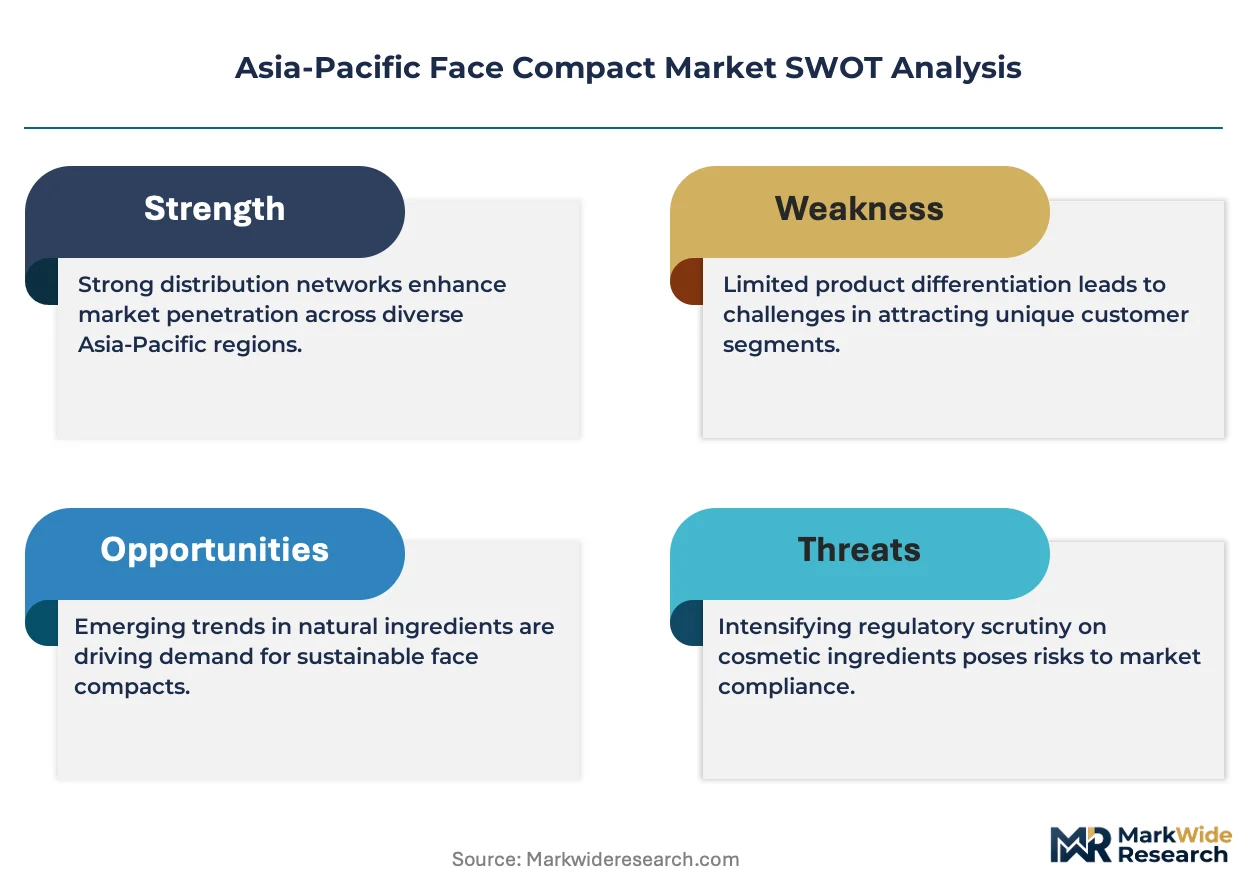
China's NMPA enforcement of GB cosmetic safety standards is compressing formulation flexibility across powder and cream compact variants, forcing manufacturers to requalify talc and synthetic dye suppliers under heavy metal screening mandates.
Growth Catalysts
- Urban professional demand:Young professional women in Seoul, Tokyo, and Shanghai are expanding purchases through specialty beauty stores and online retail platforms, concentrating volume in metropolitan clusters with established K-beauty infrastructure.
- K-beauty brand extension:South Korean beauty brands are leveraging cultural influence to penetrate Southeast Asian markets through localized digital marketing and influencer partnerships.
- Humidity-resistant formulations:Cream and liquid compact variants adapted for tropical climates are capturing professional artist segments in Singapore, Bangkok, and Jakarta.
Market Restraints
- Ingredient compliance costs:China's NMPA tightening of talc and synthetic dye standards elevates testing expenditures and extends product registration timelines.
- Supply concentration risk:Premium mica and talc processing capacity clusters in specific Chinese provinces, creating vulnerability to regional environmental enforcement actions.
- Per- and polyfluoroalkyl substance phase-out:Prospective restrictions across South Korea's MFDS and Japan's MHLW threaten long-wear compact formulations dependent on these compounds.
Strategic Opportunities
- India's underpenetrated tier-two cities:Compact consumption in secondary Indian urban centers remains below saturation, offering first-mover positioning for mid-range powder formats.
- Clean beauty regulatory alignment:India's BIS certification delays create windows for brands pre-positioned with EU REACH-compliant ingredient portfolios to accelerate market entry.
- Cross-channel integration:Specialty beauty stores in South Korea and Japan are deploying augmented reality try-on technologies to bridge physical and digital purchase journeys.
Industry Challenges
- Formulation chemist scarcity:Shortage of specialists capable of reformulating talc-dependent powders under NMPA heavy metal limits is compressing R&D throughput.
- Multi-jurisdiction disclosure divergence:Parallel but non-harmonized ingredient reporting requirements across China's NMPA, South Korea's MFDS, and Japan's MHLW fragment compliance staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Face Compact Market |
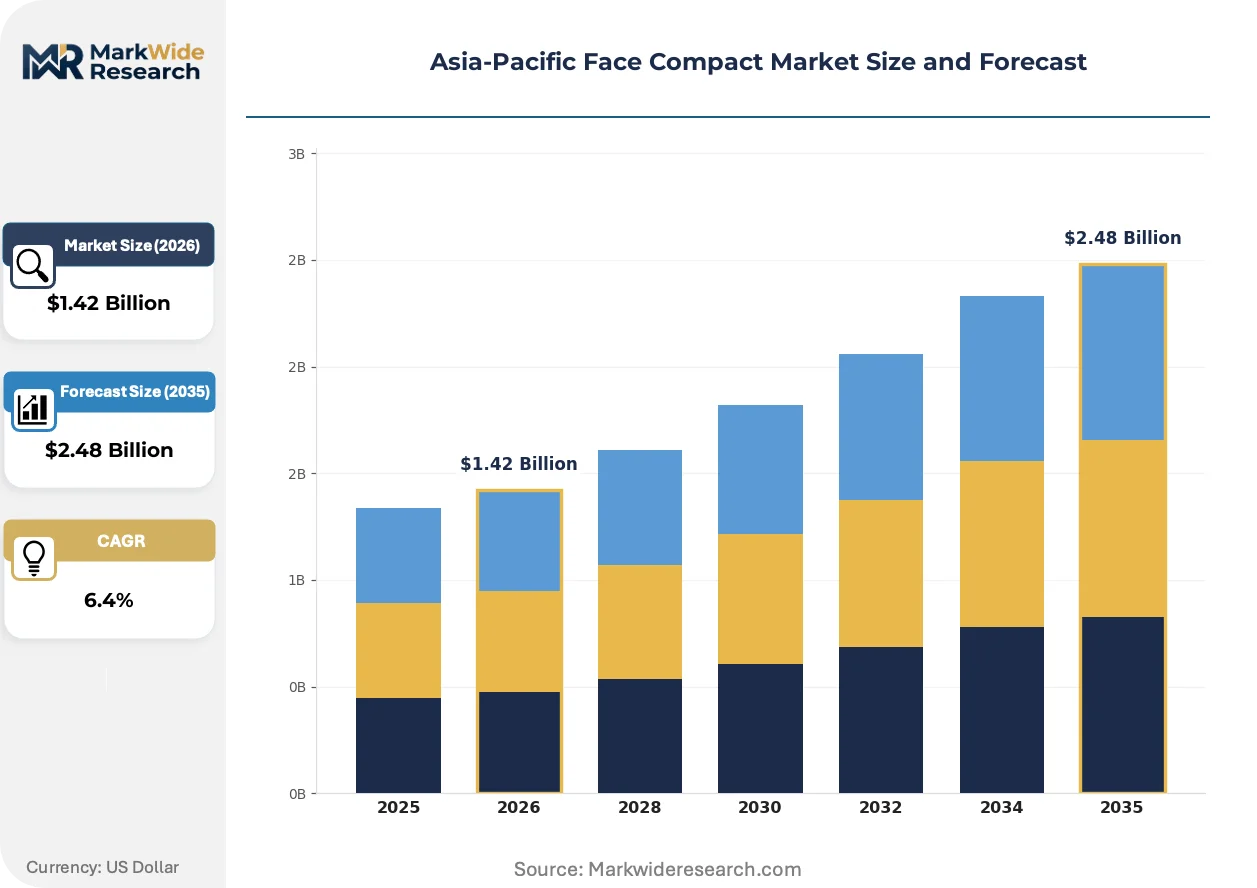
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Cream, Stick, Liquid End User: Professional Artists, Regular Consumers, Beauty Enthusiasts, Retail Chains Distribution Channel: Online Retail, Department Stores, Specialty Beauty Stores, Pharmacies Price Tier: Luxury, Mid-Range, Budget, Discount |
| Companies Covered | L'Oréal SA, Shiseido Company, Estée Lauder Companies Inc., Kao Corporation, Procter & Gamble, Unilever PLC, Amorepacific Corporation, Cosmax, Johnson & Johnson Services, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Face Compact Market Trends and Innovations
Formulation science and retail infrastructure are converging to reshape how face compacts are developed, certified, and distributed across Asia-Pacific metropolitan markets.
Microbiome-friendly preservation systems are decentralizing traditional paraben-dependent stabilization in cream compact formulations. Premium and professional-grade manufacturers in Japan and South Korea are adopting these systems fastest, compressing the historical dominance of conventional preservative portfolios. This shift is decentralizing supply relationships away from established chemical suppliers toward biotechnology ingredient specialists.
China's NMPA is tightening mandatory heavy metal screening protocols for talc-based powder compacts under evolving GB standards. This regulatory pressure is elevating testing infrastructure requirements and extending pre-market authorization timelines. Multinational brands with centralized regional labs are responding by relocating analytical capacity to Shanghai and Guangzhou to reduce submission cycle times.
Social commerce livestreaming is fragmenting traditional e-commerce purchase patterns among Chinese consumers under thirty-five. Beauty influencers on Douyin and Xiaohongshu are displacing conventional product page discovery with real-time demonstration and limited-release drops. This behavioral pivot is most visible in tier-one Chinese cities where impulse purchase conversion rates through livestream channels now exceed standard marketplace listings.
Asia-Pacific Face Compact Market Segmentation
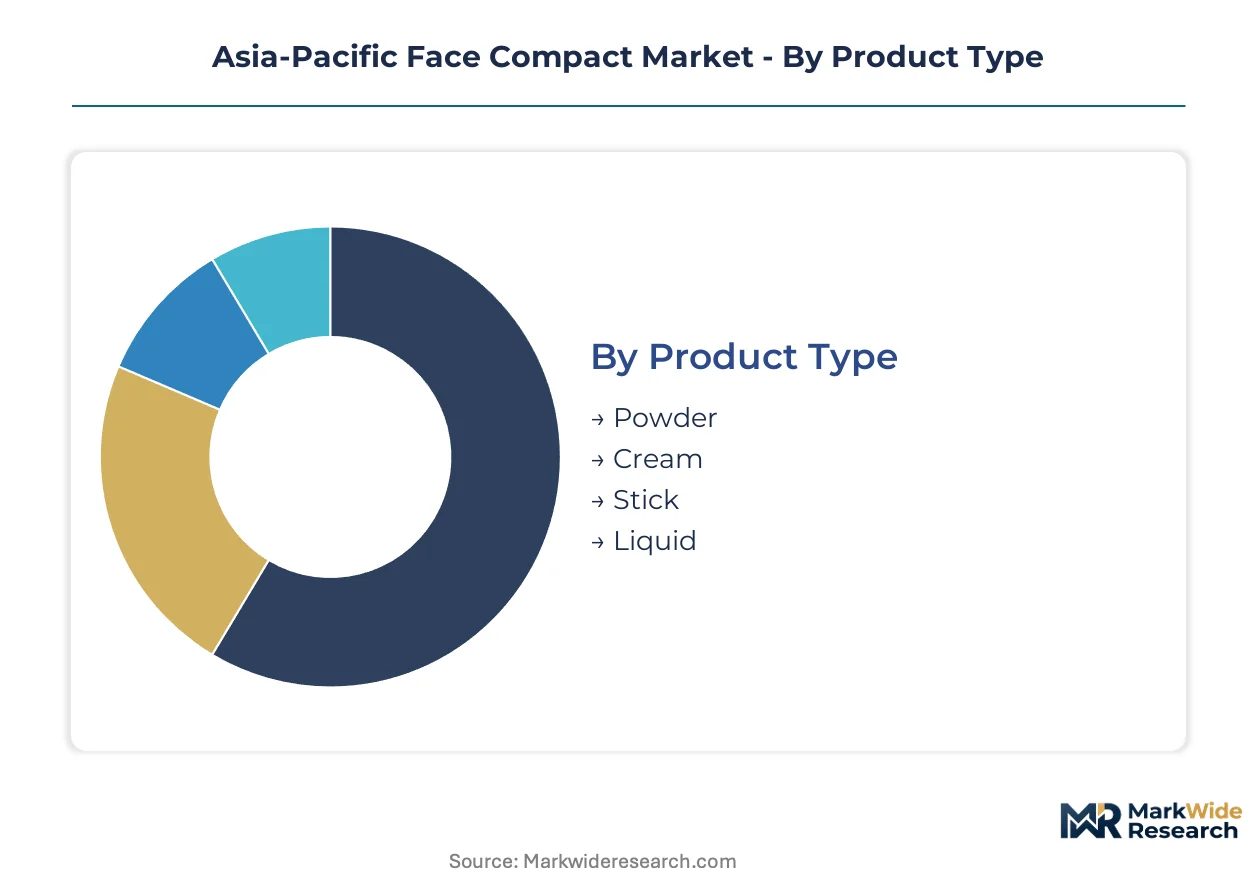
Product formulation chemistry and distribution channel economics fragment the Asia-Pacific face compact landscape into distinct competitive arenas. Each segmentation axis reveals where margin pools concentrate and where regulatory compliance burdens fall most heavily.
Product Type:
Powder compression density and emulsion stability define the technical differentiation across portable facial coverage formats.
- Powder:Pressed mineral formulations with talc, mica, and binding agents deliver portable matte coverage. Demand concentrates in Seoul and Tokyo department stores where K-beauty prestige brands anchor premium positioning despite NMPA heavy metal screening mandates elevating supplier qualification costs.
- Cream:Emulsion-based compacts with wax and oil phases provide buildable hydration for dry climate zones. Professional artists in Singapore and Bangkok drive volume for humidity-resistant variants that resist meltdown in tropical conditions.
- Stick:Solid balm formats with high wax content enable precise application for contouring and touch-ups. Japanese consumers favor stick compacts for commuting convenience in dense urban transit corridors.
- Liquid:Fluid foundations in compact reservoirs with sponge applicators merge coverage with portability. South Korean online retail channels expand fastest for liquid formats targeting younger demographics seeking TikTok-viral finish effects.
Mature deployment sits with Powder. Newer deployment is concentrated in Liquid.
End User:
Application expertise and purchase frequency separate customer segments with radically different channel preferences and price sensitivity profiles.
- Professional Artists:Makeup artists and salon operators require high-pigment, long-wear formulations for client durability under studio lighting. Beauty schools in Shanghai and Mumbai generate concentrated procurement volume for professional-grade cream and liquid compacts.
- Regular Consumers:Daily users seeking natural coverage represent the volume base across all price tiers. India's tier-two cities show underpenetrated expansion potential as disposable income rises in secondary urban centers.
- Beauty Enthusiasts:Collectors and trend-followers purchase multiple formats for occasion-specific use. South Korean specialty beauty stores capture highest margins from this segment through limited-edition packaging and influencer collaboration drops.
- Retail Chains:Private-label buyers and merchandise planners source compacts for house brand portfolios. China's domestic pharmacy chains are expanding mid-range powder compact selections to compete with online retail price pressure.
Volume concentration favors Regular Consumers. Margin expansion is climbing the fastest with Beauty Enthusiasts.
Distribution Channel:
Physical retail infrastructure and digital platform economics are rebalancing customer acquisition costs and inventory risk across the region.
- Online Retail:Marketplace platforms and brand direct-to-consumer sites enable rapid format testing with minimal inventory commitment. Douyin livestreaming in Chinese tier-one cities now converts impulse purchases faster than standard product pages for compact color cosmetics.
- Department Stores:Flagship counters with trained beauty advisors sustain premium positioning through experiential service. Japanese department stores anchor Shiseido's powder compact dominance despite share erosion to specialty channels.
- Specialty Beauty Stores:Curated assortment retailers like Olive Young and Watsons capture trend-sensitive demand with rapid SKU rotation. South Korea's specialty channel maintains highest compact category margins through exclusive brand partnerships and membership programs.
- Pharmacies:Drugstore and apothecary channels emphasize dermatologist-tested and sensitive-skin positioned formulations. India's pharmacy distribution faces BIS certification delays that constrain multinational brand scaling.
Established infrastructure sits with Department Stores. Channel expansion is gaining share fastest through Online Retail.
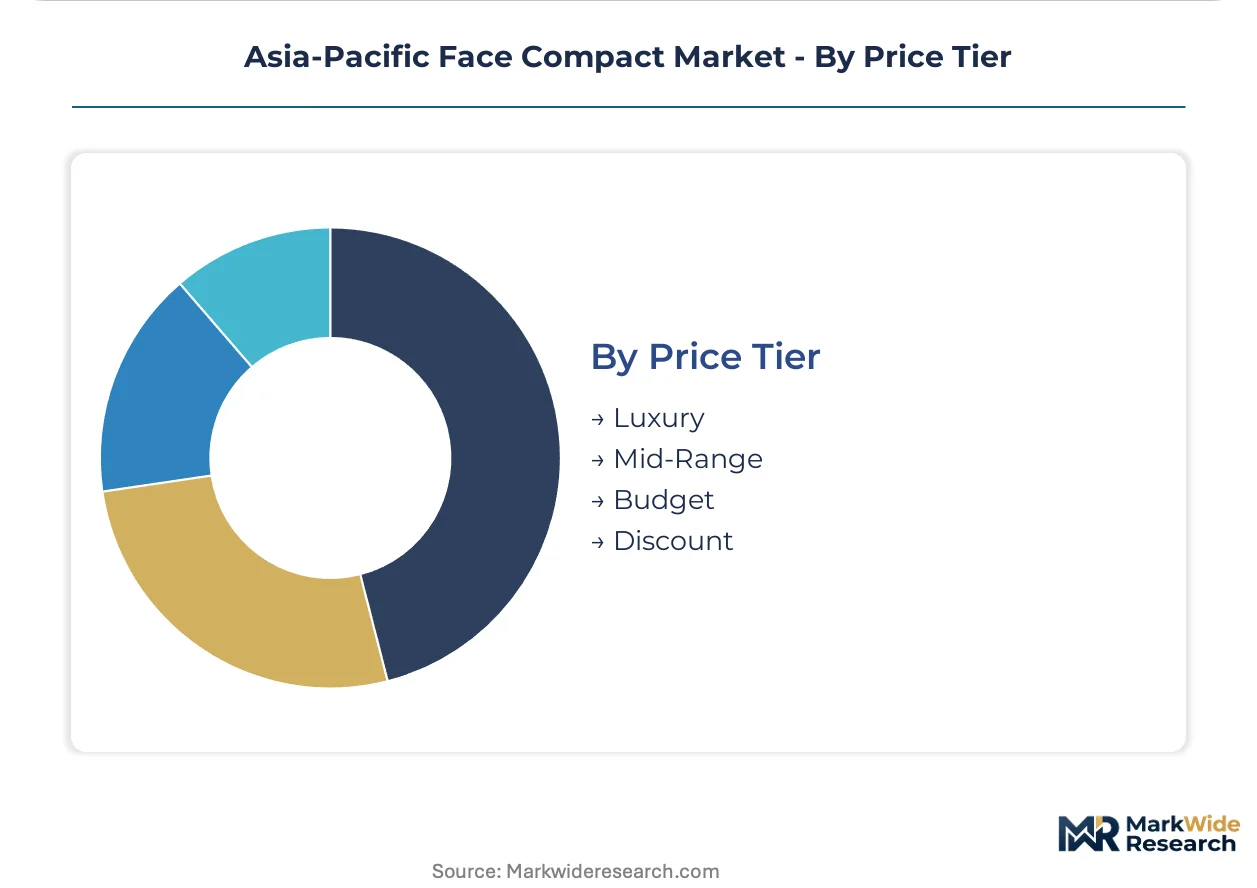
Price Tier:
Raw material grade, packaging investment, and marketing spend stratify the market into distinct profitability bands with different regulatory exposure.
- Luxury:Precious metal packaging, rare botanical extracts, and artisanal pressing techniques justify premium positioning. Japanese consumers in Tokyo and Osaka sustain luxury compact demand despite demographic headwinds through gift-giving culture.
- Mid-Range:Balanced ingredient quality and accessible pricing targets urban professionals seeking performance without status markup. Amorepacific and L'Oréal compete intensely in this band across South Korea and China's tier-one cities.
- Budget:Functional formulations with standardized packaging prioritize unit economics for mass distribution. India's domestic brands dominate budget tier through localized shade ranges and pharmacy channel penetration.
- Discount:Promotional and grey-market imports capture price-sensitive trial purchases with minimal brand loyalty. Southeast Asian border trade and parallel import channels fragment pricing discipline in Vietnam and Indonesia.
Margin stability sits with Luxury. Volume acceleration is expanding most quickly in Mid-Range.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in metropolitan clusters where K-beauty infrastructure and premium retail density overlap. Seoul, Tokyo, and Shanghai generate disproportionate compact volume through specialty beauty stores and livestream commerce channels.
China
Urban professional women in Shanghai and Beijing drive premium powder compact purchases through Douyin livestreaming and Xiaohongshu discovery. NMPA enforcement of GB cosmetic safety standards mandates heavy metal screening for talc-based formulations, compressing supplier qualification timelines. Manufacturing and testing infrastructure clusters in Shanghai and Guangzhou as multinational brands relocate analytical capacity to reduce submission cycles.
South Korea
Seoul's metropolitan area anchors K-beauty brand dominance through Olive Young and specialized digital marketing. MFDS maintains ingredient disclosure requirements that diverge from neighboring jurisdictions, fragmenting compliance pathways for regional expansion. Beauty schools in Seoul generate concentrated procurement volume for professional-grade cream and liquid compacts targeting makeup artists.
Japan
Department stores in Tokyo and Osaka sustain Shiseido's powder compact positioning despite share erosion to specialty channels. MHLW preservative regulations accelerate adoption of microbiome-friendly stabilization systems among premium manufacturers. Commuting culture in dense urban transit corridors drives stick compact formats for touch-up convenience.
India
Tier-two cities including Pune, Ahmedabad, and Jaipur present underpenetrated expansion potential as disposable income rises in secondary urban centers. BIS certification for imported cosmetics adds procedural delays that constrain rapid scaling for newer entrants. Domestic brands dominate budget tier through localized shade ranges and pharmacy channel penetration in Maharashtra and Gujarat.
Singapore
Professional artists and beauty enthusiasts in Singapore drive demand for humidity-resistant cream compact formulations adapted to tropical climates. The city-state's regulatory alignment with EU REACH standards creates entry pathways for clean beauty brands with pre-qualified ingredient portfolios. Sephora and local specialty retailers capture high margins through exclusive Southeast Asian product launches.
Asia-Pacific Face Compact Market Competitive Landscape
Japanese producers anchor premium-tier positioning through department store infrastructure and heritage brand equity; South Korean specialists hold digital-native and K-beauty influence vectors. The vendor base stratifies into three tiers: multinational conglomerates with centralized R&D, regional champions leveraging cultural export power, and domestic mass-market formulators. Archetypes include heritage luxury houses, K-beauty platform brands, and contract manufacturers with vertical formulation capabilities. Competitive moves center on M&A to secure biotech ingredient pipelines and capacity expansion in China to compress NMPA registration timelines.
Among France-based conglomerates, L'Oréal SA exemplifies the multinational archetype with localized R&D adaptation for tropical climate formulations. Japanese heritage houses Shiseido Company and Kao Corporation occupy positions bridging prestige department store anchoring with preservative system innovation. South Korean platform specialist Amorepacific Corporation represents the K-beauty export model, leveraging cultural influence across Southeast Asian digital channels. These three entities collectively illustrate how geographic origin and channel strategy determine competitive positioning in fragmented Asia-Pacific beauty retail.
| Leading Market Players |
|---|
| L'Oréal SA |
| Shiseido Company |
| Estée Lauder Companies Inc. |
| Kao Corporation |
| Procter & Gamble |
| Unilever PLC |
| Amorepacific Corporation |
| Cosmax |
| Johnson & Johnson Services, Inc. |
| Others |
Pricing and Supply Chain Analysis
Luxury-to-budget tier divergence in Asia-Pacific face compacts manifests through talc sourcing certification costs and channel-controlled margin capture, with premium formulations absorbing NMPA heavy metal testing expenses while budget tiers compress supplier margins through pharmacy channel volume aggregation.
Pricing Analysis
Volume concentration in India's budget tier runs through domestic pharmacy chains, while margin stability clusters in Japanese department store luxury positioning. Three-tier pricing structure across premium, standard, and economy levels differentiates by packaging investment and preservative system grade, with microbiome-friendly stabilization commanding brand premiums. Pricing pressure stems from NMPA compliance cost pass-through requirements in China's mid-range segment. Professional artists in Singapore show lowest price sensitivity; India's tier-two regular consumers exhibit highest elasticity.
Supply Chain Analysis
Freight cost differentials between premium mica shipments from Indian Jharkhand mines and talc processing clusters in China's Liaoning province elevate landed costs for multinational formulators. Raw material dependencies center on talc, mica, and synthetic pigment binders, with South Korean biotech preservative specialists displacing conventional chemical suppliers. Single-source vulnerability concentrates in Liaoning's environmental enforcement exposure. Distribution runs through Shanghai and Guangzhou testing hubs for NMPA pre-market authorization, then fragments to specialty beauty stores in Seoul and Tokyo or livestream commerce channels in Chinese tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Talc processing capacity constraints under tightening NMPA environmental enforcement prop pricing power for qualified suppliers, compressing formulation flexibility while elevating compliance-tier premiums.
For Market Incumbents: Anticipate MFDS and MHLW per- and polyfluoroalkyl substance phase-out timelines by accelerating microbiome-friendly preservation R&D partnerships with South Korean biotech specialists. Defend channel position through exclusive Olive Young and Sephora Southeast Asia distribution agreements before clean beauty regulatory alignment windows close. Vertical integration into Jharkhand mica sourcing reduces single-origin exposure.
For New Entrants and Emerging Players: India's tier-two beauty enthusiasts represent the most penetrable buyer archetype, with Pune and Ahmedabad showing compact consumption gaps against Mumbai and Delhi benchmarks. Pre-position EU REACH-compliant ingredient portfolios to exploit BIS certification acceleration pathways. Launch through pharmacy channel private-label partnerships with domestic retail chains to bypass multinational brand recognition deficits.
For Investors and Strategic Acquirers: Re-rating potential sits with contract manufacturers possessing vertical formulation capabilities given K-beauty brand extension demand across Southeast Asian markets. Long-term viability favors entities with captive talc qualification infrastructure under NMPA GB standards. Monitor South Korea's MFDS disclosure harmonization proposals as inflection signal for regional compliance cost compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean Beauty Regulatory Alignment | EU REACH-compliant portfolios accelerate India's BIS certification timelines for multinational entrants. |
| Biotech Preservative Partnership | Microbiome-friendly stabilization R&D displaces paraben-dependent systems in premium Japanese formulations. |
| Livestream Commerce Integration | Douyin and Xiaohongshu channel control captures impulse conversion in Chinese tier-one cities. |
| Tier-Two City Distribution Buildout | Pharmacy channel penetration in Pune and Ahmedabad addresses India's underpenetrated secondary urban centers. |
| Testing Infrastructure Relocation | Shanghai and Guangzhou analytical capacity reduces NMPA submission cycle times for talc-based powders. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with cosmetic formulation chemists, NMPA regulatory consultants, Olive Young category buyers, and Indian pharmacy procurement managers. NMPA GB standard documentation, MFDS ingredient disclosure guidelines, Japan MHLW preservative regulations, and BIS certification procedural records provided compliance pathway validation. Bottom-up SKU-level volume aggregation triangulated against top-down category spend estimates from beauty retail audit databases.
Data-stream reconciliation across product type, price tier, distribution channel, and metropolitan cluster dimensions generated volume and value outputs across the analysis window. CAGRs derived from regression modeling of historical regulatory event impacts on category growth rates, with humidity-resistant formulation adoption curves and livestream commerce penetration trajectories as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NMPA environmental enforcement intensity and per- and polyfluoroalkyl substance restriction timelines across South Korea and Japan. Forecasts reflect documented assumptions regarding K-beauty cultural export sustainability and Indian disposable income trajectory in secondary urban centers. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Makeup Remover Product Market
Cosmetics & Skincare
Snail Beauty Products Market
Cosmetics & Skincare
Liquid Lipstick Market
Cosmetics & Skincare
Organic Color Cosmetics Products Market
Cosmetics & Skincare
Body Cream Jars Market
Cosmetics & Skincare
Bangladesh Face Wash Market
Cosmetics & Skincare
Massaging Cosmetic Applicators Market
Cosmetics & Skincare
Face Bronzer Market
Cosmetics & Skincare
Natural Cosmetic Color Market
Cosmetics & Skincare
Pillow Spray Market
Cosmetics & Skincare
Anti-Pollution Skin Care Products Market
Cosmetics & Skincare
Japan Bath Soap Market
Cosmetics & Skincare
Makeup Setting Powder Market
Cosmetics & Skincare
Sweden Cosmetics Products Market
Cosmetics & Skincare
GCC Bath Soap Market
Cosmetics & Skincare
UK Lip Care Products Market