
 Scalp Scrub Market | 2026-2036
Scalp Scrub Market Size, Share, and Industry Trends Forecast 2026-2036
Scalp Scrub Market Analytics
REACH compliance is restructuring the cost-of-entry calculus for scalp scrub manufacturers targeting European distribution. L'Oréal leverages its integrated R&D pipeline to preempt regulatory thresholds for preservative systems and microplastic restrictions. Unilever anchors its mass-market position through scaled procurement of certified sustainable surfactants across multiple continents.
A scalp scrub is a mechanically or chemically active treatment product designed to remove sebum buildup, dead skin cells, and environmental residues from the scalp surface, typically incorporating abrasive particles such as sugar, salt, or jojoba esters at concentrations between two and ten percent by weight, with primary commercial purpose centered on improving follicular health and optimizing conditions for hair growth. Exfoliating scrub formats dominate unit volume due to consumer familiarity with granular tactile feedback, while botanical extract ingredient categories command premium shelf positioning as clean beauty positioning intensifies across retail channels. Jar packaging occupies the professional salon segment where portion control and resealability support backbar efficiency, though pump bottle configurations compete aggressively in home-use channels through dispensing convenience and perceived hygiene.
The FDA maintains oversight of cosmetic safety through the Federal Food, Drug, and Cosmetic Act, while the EPA evaluates environmental release profiles for rinse-off personal care ingredients under the Toxic Substances Control Act framework. ECHA's ongoing microplastic restriction proposals threaten conventional polyethylene bead formulations, forcing reformulation toward biodegradable alternatives. Stakeholders must monitor evolving state-level ingredient disclosure laws in California and New York, as these jurisdictions typically prefigure broader federal mandates that will reshape labeling requirements and supply chain documentation burdens.
Market Dynamics
The EU Green Deal's chemical transparency mandates are forcing scalp scrub manufacturers to restructure formulation pipelines and supplier documentation systems before products reach European distribution channels.
Growth Catalysts
- REACH compliance deadlines:European distributors now require granular ingredient disclosure that accelerates clean-label product development across the personal care supply chain.
- Professional salon channel expansion:Stylists in the United States increasingly incorporate scalp treatments into standard service protocols, driving backbar volume and retail attachment rates.
- Biodegradable abrasive materials:Sugar and jojoba ester formulations are capturing shelf space as polyethylene bead alternatives satisfy emerging microplastic restrictions.
Market Restraints
- Surfactant cost volatility:Certified sustainable palm-derived and coconut-derived feedstocks face price pressure from competing biofuel demand and weather-related supply disruptions in Southeast Asia.
- Regulatory fragmentation:California's Safer Consumer Products regulations and New York's ingredient disclosure laws create compliance patchwork that fragments packaging and labeling runs.
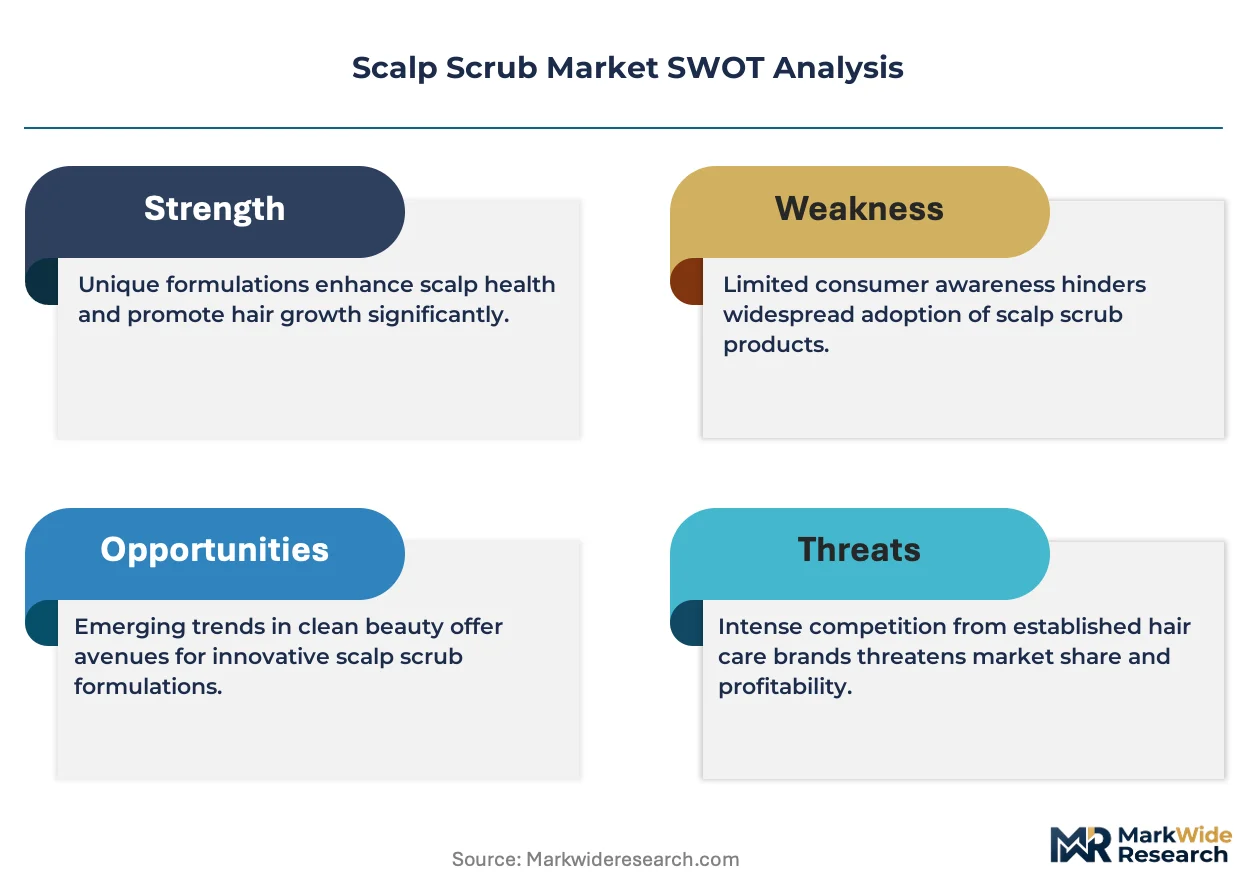
- Technical formulation limits:Natural preservative systems struggle to match synthetic alternatives for shelf stability in high-moisture jar formats preferred by salon professionals.
Strategic Opportunities
- Direct-to-consumer subscription models:Pump bottle configurations with automated replenishment capture recurring revenue from home-use segments in the United States.
- Scalp microbiome positioning:Prebiotic and postbiotic ingredient claims open premium pricing tiers as dermatological credibility becomes a purchase trigger.
- Waterless and solid formats:Concentrated balm and bar formulations reduce shipping weights and align with plastic-reduction commitments from major retailers.
Industry Challenges
- Formulation chemist scarcity:The specialized expertise required to balance exfoliation efficacy with scalp sensitivity limits new product pipeline velocity.
- Supply chain reconfiguration costs:Shifting from conventional to biodegradable abrasives demands equipment recalibration and supplier qualification timelines that compress margin recovery windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scalp Scrub Market |
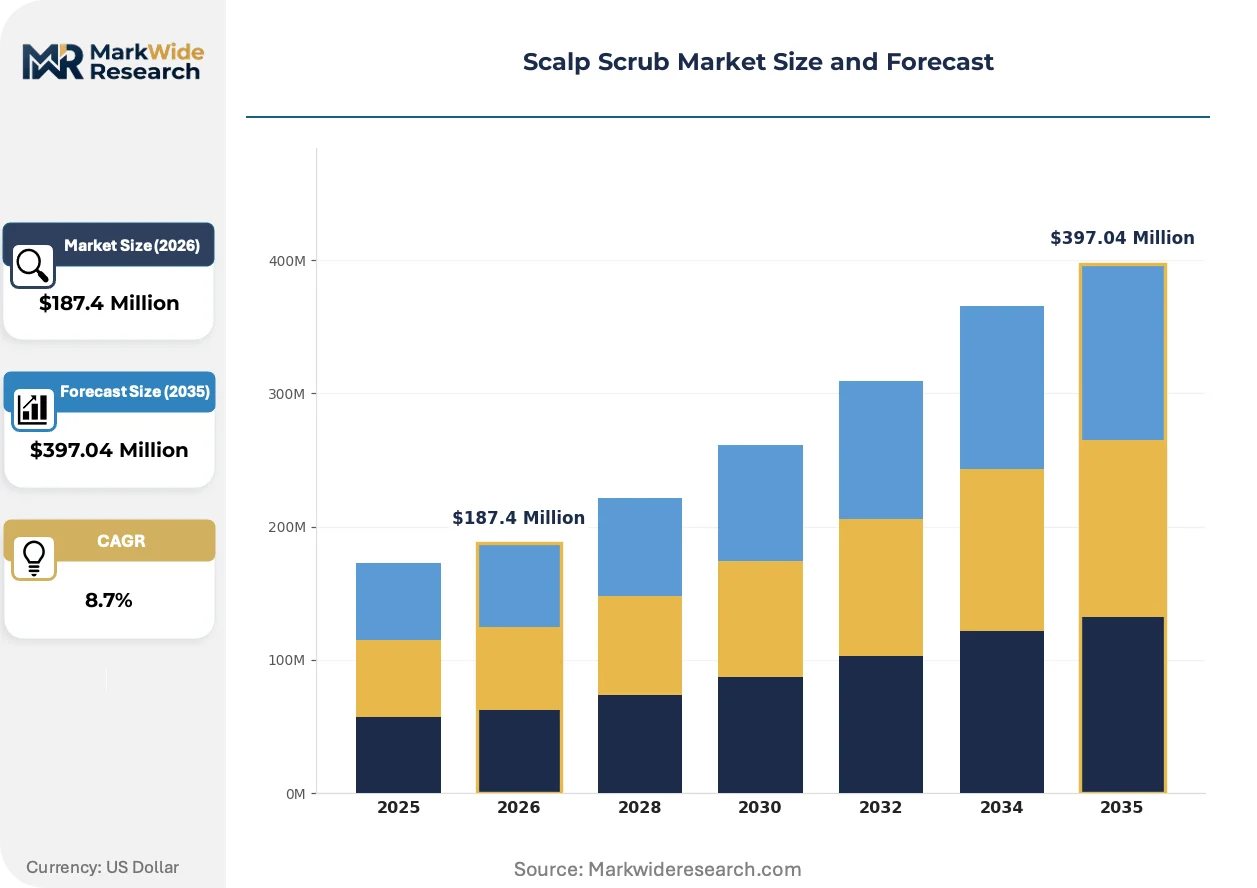
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exfoliating Scrub, Cleansing Gel, Foam Treatment, Paste Formula Ingredient Type: Natural, Organic, Chemical, Botanical Extracts End User: Men, Women, Salons, Home Users Packaging Type: Jar, Tube, Pump Bottle, Sachet |
| Companies Covered | Ouai, Procter & Gamble, L'Oréal, Himalaya Drug Company, Beiersdorf, Unilever, Christophe Robin, dpHUE, Briogeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scalp Scrub Market Evolving Landscape
Formulation science and distribution infrastructure are converging to reshape how scalp treatments reach end users, with sustainability mandates and channel fragmentation driving parallel innovation tracks.
Encapsulated active delivery systems are integrating time-release mechanisms for salicylic acid and botanical extracts, extending treatment efficacy between applications. Premium salon brands in the United States and Germany are adopting these technologies to differentiate professional-grade protocols from mass-market alternatives. The structural result is a widening performance gap that justifies tiered pricing and locks in stylist loyalty through measurable client outcomes.
REACH microplastic restriction proposals are compelling manufacturers to eliminate polyethylene beads from rinse-off cosmetics entirely. ECHA's draft measures classify conventional scrub particles as restricted substances, forcing reformulation toward cellulose, silica, or seed-based alternatives. European contract manufacturers are absorbing the largest compliance burden, with smaller brands outsourcing reformulation to specialized R&D houses to meet accelerated phase-out timelines.
Home-use buyers are fragmenting across channel preferences that bypass traditional retail gatekeepers. Direct-to-consumer beauty brands in the United States now dedicate entire site sections to scalp health, displacing generalist hair care positioning. This behavioral shift concentrates marketing spend on digital education content and influencer partnerships rather than shelf placement fees, compressing the role of conventional distributors in category development.
Scalp Scrub Market Segmentation
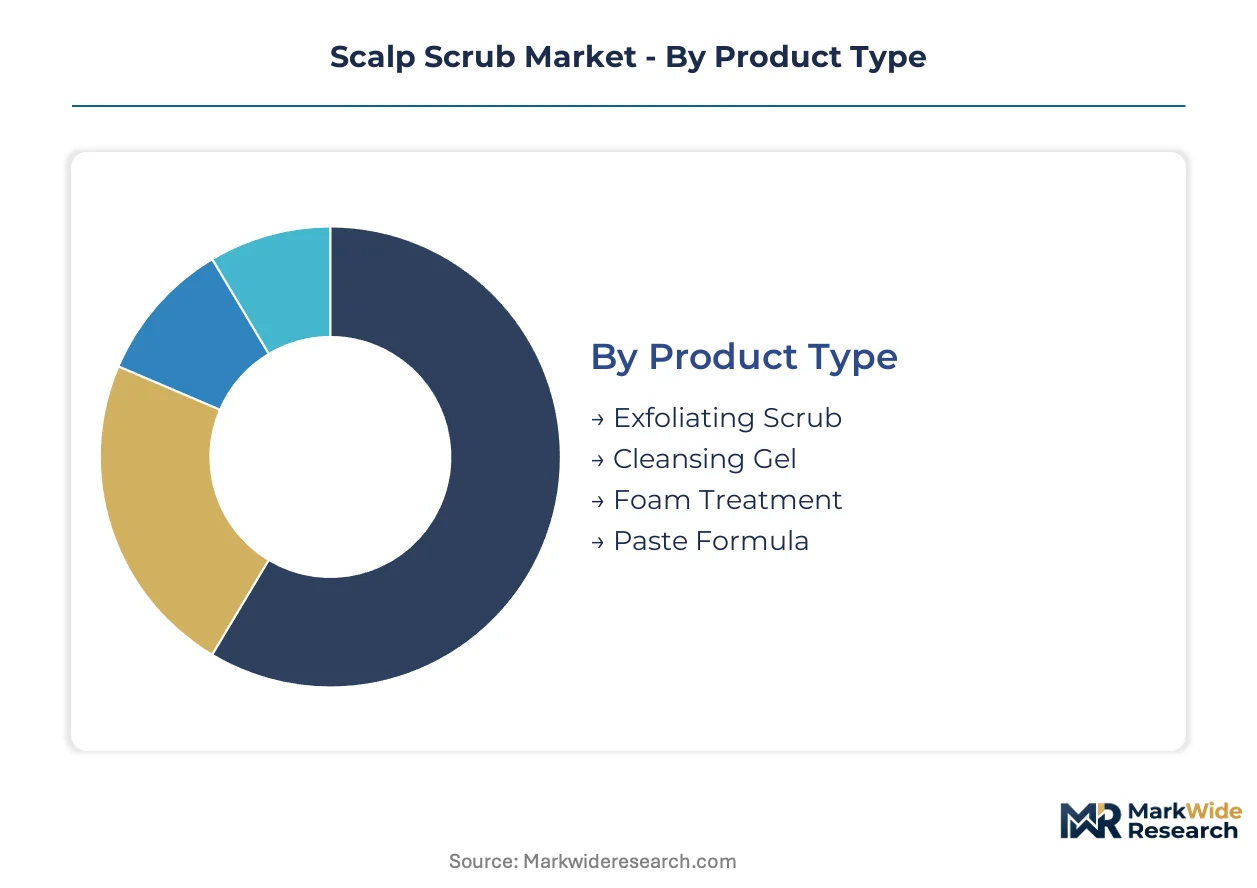
Scalp scrub segmentation reflects divergent channel economics between professional service environments and at-home consumption rituals. Product formats and packaging configurations align with distinct usage contexts, while ingredient positioning stratifies across clean-label credibility tiers. Understanding these splits enables targeted formulation and distribution decisions.
Product Type:
Exfoliating scrub formats dominate unit volume through tactile familiarity, while foam treatments command premium positioning in specialized channels.
- Exfoliating Scrub:Granular formulations incorporating sugar, salt, or jojoba esters at two to ten percent concentration deliver mechanical exfoliation with immediate sensory feedback. Demand concentrates in United States home-use channels where consumers associate granular texture with efficacy, though polyethylene bead reformulation pressures are accelerating biodegradable abrasive adoption.
- Cleansing Gel:Lower-viscosity formulations with suspended micro-exfoliants target daily-use protocols and sensitive scalp positioning. Salons in Germany and France increasingly specify gel formats for backbar efficiency due to easier rinse-out and reduced residue concerns during color service intervals.
- Foam Treatment:Aerosol or pump-dispensed aerated formats distribute active ingredients across dense hair with minimal mechanical agitation.
- Paste Formula:High-viscosity concentrated treatments with extended contact time for intensive weekly protocols.
Today's leader: Exfoliating Scrub. Tomorrow's challenger: Foam Treatment.
Ingredient Type:
Botanical positioning separates premium shelf placement from mass-market surfactant chemistry, with certification requirements fragmenting supplier qualification.
- Natural:Formulations excluding synthetic preservatives and petrochemical-derived surfactants, typically relying on sugar-based abrasives and plant-derived emulsifiers. United States direct-to-consumer brands dedicate site navigation to natural scalp care, capturing subscription revenue through clean-label loyalty.
- Botanical Extracts:Standardized plant actives including tea tree, peppermint, and rosemary with claimed follicular stimulation properties. Professional salons in California specify botanical-forward protocols to differentiate service menus and justify premium treatment pricing.
- Organic:Certified feedstock supply chains with USDA or COSMOS documentation requirements.
- Chemical:Synthetic surfactant and preservative systems optimized for shelf stability and cost efficiency.
Botanical Extracts hold current premium positioning. Natural formulations are climbing the fastest as disclosure mandates intensify.
End User:
Professional channel concentration creates backbar volume anchors, while gendered marketing fragments retail assortment planning.
- Salons:Licensed professionals performing scalp treatments as standalone services or color preparation protocols, driving bulk procurement of jar formats with portion-control requirements. United States salon chains negotiate direct supply agreements that bypass traditional distributor markups.
- Women:Primary retail purchasers across all channels, with marketing emphasizing hair growth optimization and scalp health as beauty regimen extension.
- Home Users:Non-professional consumers purchasing through retail or direct-to-consumer channels for self-administered treatment.
- Men:Emerging segment targeted through grooming brand extensions and hair loss prevention positioning.
Salons anchor professional credibility. Direct-to-consumer home users are gaining share fastest as digital education displaces retail discovery.
Packaging Type:
Format selection trades dispensing hygiene against product preservation and shipping economics.
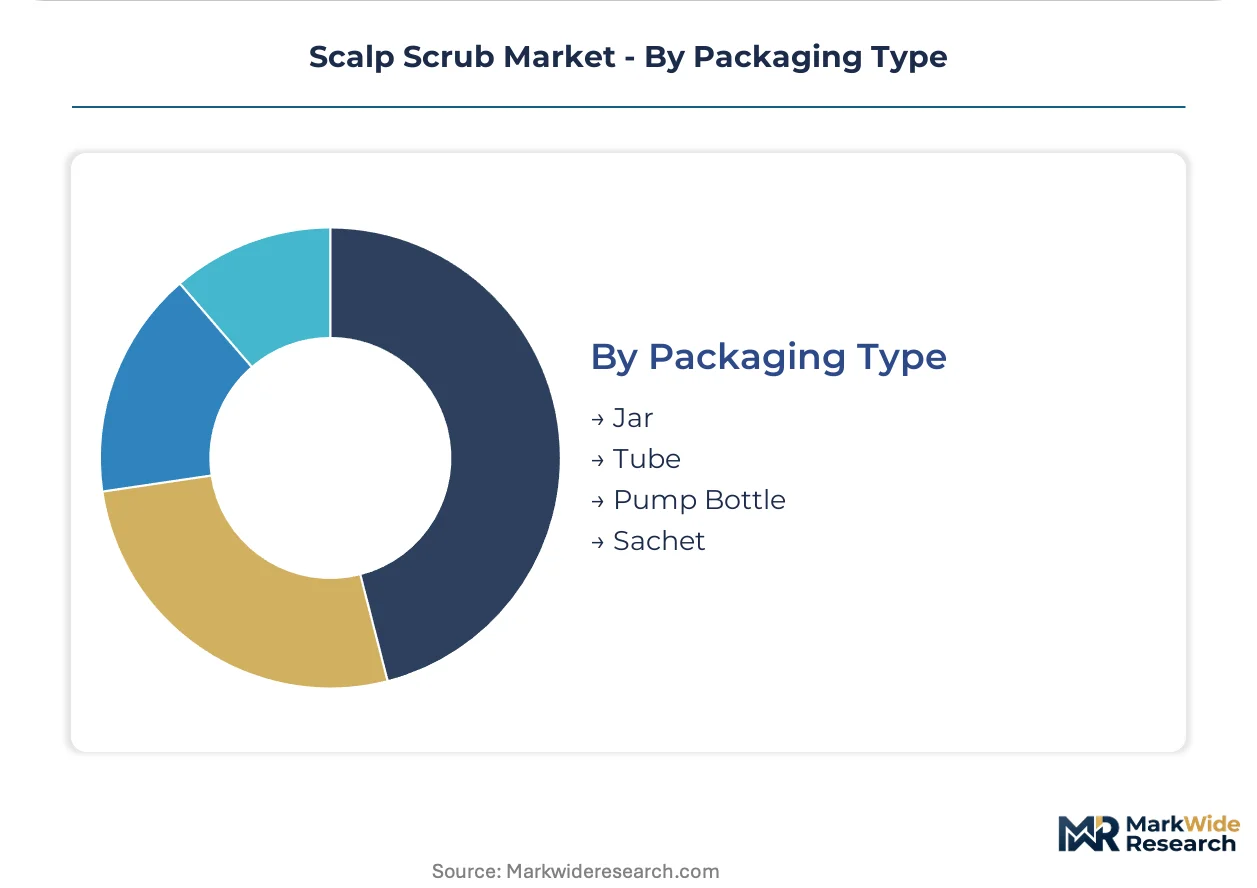
- Jar:Wide-mouth configurations supporting spatula portioning and resealability, preferred by United States salon professionals for backbar visibility and inventory management. High moisture exposure challenges natural preservative systems in this format.
- Pump Bottle:Airless or standard pump configurations reducing contamination risk and supporting automated replenishment subscription models. Direct-to-consumer brands in the United States standardize on pump formats for perceived hygiene and dispensing convenience.
- Tube:Collapsible aluminum or laminate structures for travel and trial-size distribution.
- Sachet:Single-use foil or film pouches for sample distribution and salon trial protocols.
Pump Bottle configurations dominate home-use growth. Jar formats defend salon channel loyalty through professional ritual alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The scalp scrub category traces its commercial origins to professional salon protocols in France and the United States, where stylists first incorporated granular scalp treatments into hair care services during the early 2000s. This professional heritage continues to shape regional demand patterns and regulatory responses across major markets.
United States
Direct-to-consumer beauty brands have built dedicated scalp care categories that displace generalist hair care positioning, with subscription models capturing recurring revenue from home-use segments. The FDA maintains cosmetic safety oversight through the Federal Food, Drug, and Cosmetic Act, while California's Safer Consumer Products regulations and New York's ingredient disclosure laws create compliance patchwork. Los Angeles and New York City anchor innovation clusters where digital-native brands concentrate marketing spend on influencer partnerships rather than traditional retail placement.
Germany
Professional salons specify gel formats for backbar efficiency due to easier rinse-out and reduced residue concerns during color service intervals. ECHA's REACH compliance deadlines force granular ingredient disclosure that accelerates clean-label product development across the personal care supply chain. Berlin and Hamburg host contract manufacturers absorbing the largest reformulation burden as microplastic restriction proposals compel polyethylene bead phase-outs.
France
Luxury positioning and professional heritage sustain premium pricing tiers, with botanical extract formulations commanding shelf space as clean beauty positioning intensifies. The EU Green Deal's chemical transparency mandates restructure formulation requirements across the personal care supply chain. Paris anchors the professional salon segment where scalp treatments originated as standalone services, with regional formulators leading biodegradable abrasive adoption.
United Kingdom
Retail channel fragmentation drives assortment planning complexity, with gendered marketing and microbiome positioning opening premium pricing tiers. ECHA's ongoing microplastic restriction proposals threaten conventional polyethylene bead formulations, forcing reformulation toward biodegradable alternatives. London concentrates direct-to-consumer brand headquarters and digital education content production that displaces retail discovery.
India
Mass-market penetration accelerates through affordable natural formulations relying on sugar-based abrasives and plant-derived emulsifiers, with Ayurvedic positioning differentiating local offerings. The country's national cosmetic regulator evaluates safety profiles for rinse-off personal care ingredients under evolving framework standards. Mumbai and Bangalore host emerging domestic brands capturing subscription revenue through clean-label loyalty in the home-use segment.
Scalp Scrub Market Competitive Landscape
The competitive structure tilts toward multinational consumer goods conglomerates with integrated R&D pipelines and scaled procurement networks. Two distinct tiers have emerged: mass-market players leveraging global distribution infrastructure, and premium specialists commanding stylist loyalty through professional-grade protocols. Three strategic archetypes dominate—multinational conglomerates with portfolio breadth, digital-native direct-to-consumer brands, and salon-centric professional specialists. Competitive moves concentrate on supply chain reconfiguration toward biodegradable abrasives and preemptive regulatory compliance for preservative systems.
Among multinational conglomerates, L'Oréal and Unilever occupy positions that exemplify divergent strategic paths—L'Oréal leveraging integrated R&D to preempt regulatory thresholds, Unilever anchoring mass-market positioning through scaled sustainable surfactant procurement. Within the specialist tier, Ouai represents the digital-native archetype that built category presence through direct-to-consumer channels before retail expansion. These three companies illustrate how competitive positioning fragments across scale-driven efficiency and premium credibility vectors.
| Leading Market Players |
|---|
| Ouai |
| Procter & Gamble |
| L'Oréal |
| Himalaya Drug Company |
| Beiersdorf |
| Unilever |
| Christophe Robin |
| dpHUE |
| Briogeo |
| Others |
Value Network & Pricing Analysis
Captive integration into certified sustainable surfactant production anchors both supply security and pricing power for scalp scrub manufacturers navigating REACH compliance deadlines and California disclosure mandates.
Pricing Analysis
Bundled salon service protocols command premium attachment rates against unbundled retail SKUs where direct-to-consumer brands compete on subscription convenience. Three-tier pricing structure across professional-grade, masstige, and economy levels separates botanical-certified formulations from synthetic alternatives, with certification tier as the primary price differentiation driver. Pricing pressure stems from surfactant feedstock competition with biofuel demand, compressing margins in natural-positioned tiers. Home-use direct-to-consumer segments show highest price sensitivity, while professional salons absorb premium markups for backbar efficiency and client outcome credibility.
Supply Chain Analysis
Regional distribution centers in Germany, France, and the United States coordinate hub-and-spoke patterns that position contract manufacturers near professional salon clusters and direct-to-consumer fulfillment nodes. Raw material dependencies center on Southeast Asian coconut-derived and palm-derived feedstocks, biodegradable cellulose abrasives from European suppliers, and preservative systems qualified under REACH and FDA frameworks. Single-source vulnerability concentrates in certified organic botanical extract supply, where COSMOS and USDA documentation requirements limit supplier pools. Distribution runs through professional beauty distributors in salon channels, while home-use segments increasingly bypass traditional retail through brand-direct e-commerce infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scalp scrub demand has shifted toward microbiome-positioned and prebiotic-infused formulations, signaling a late-cycle quality story where premium specifications displace basic exfoliation claims.
For Market Incumbents: Cement stylist loyalty through encapsulated active delivery systems that extend treatment efficacy and lock in professional-grade differentiation. Defend against digital-native entrants by tightening direct supply agreements with United States salon chains, bypassing distributor markups that erode margin recovery windows. Prioritize backward integration into biodegradable abrasive production to preempt ECHA microplastic restriction compliance costs. For New Entrants and Emerging Players: Capture white-space in men's grooming extensions where hair loss prevention positioning remains underdeveloped relative to female-targeted scalp health marketing. Target waterless and solid format innovation for premium-mid-economy pricing differentiation, as concentrated balm formulations reduce shipping weights and align with retailer plastic-reduction commitments. Deploy influencer-driven digital education as the primary go-to-market angle, displacing shelf placement fees that concentrate incumbent marketing spend. For Investors and Strategic Acquirers: Consolidation pressure builds where formulation chemist scarcity limits new product pipeline velocity and specialized R&D expertise commands premium acquisition multiples. Long-term viability favors mid-cap specialists with captive supply of certified sustainable surfactants and proven regulatory compliance infrastructure across REACH and FDA jurisdictions. Watch ECHA's final microplastic restriction implementation timeline as the signal for accelerated reformulation capex cycles and distressed asset opportunities among polyethylene bead-dependent manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Abrasive Reformulation | ECHA microplastic restrictions force polyethylene bead phase-out toward cellulose and seed-based alternatives. |
| Direct-to-Consumer Subscription Launch | Pump bottle configurations with automated replenishment capture recurring revenue from United States home-use segments. |
| Scalp Microbiome Certification Investment | Prebiotic and postbiotic ingredient claims open premium pricing tiers through dermatological credibility positioning. |
| Professional Salon Channel Expansion | Direct supply agreements with United States salon chains bypass distributor markups and anchor backbar volume. |
| Waterless Format Development | Concentrated balm and bar formulations reduce shipping weights and align with major retailer plastic-reduction commitments. |
Research Methodology
Bottom-up salon and home-use channel modeling reconciled against top-down surfactant and abrasive ingredient supply tracking forms the analytical core. Primary interviews with formulation chemists, professional salon owners, direct-to-consumer brand executives, and contract manufacturing procurement leads combined with secondary validation from ECHA regulatory filings, FDA cosmetic ingredient databases, Nielsen retail audit data, and customs trade records. Triangulation across stakeholder perspectives and documentary sources ensures segment-level precision without reliance on single-source estimates.
Historical trendline analysis of professional service attachment rates and retail SKU velocity established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include product format, ingredient certification tier, end-user channel, and packaging configuration, with CAGRs derived from regression analysis against macroeconomic indicators and regulatory implementation timelines. Forecast inputs incorporate REACH compliance deadline acceleration, microplastic restriction phase-out schedules, and direct-to-consumer subscription adoption curves.
Underlying measurement precision varies by segment; professional salon channel data carries tighter precision than emerging direct-to-consumer subsegments where disclosure practices remain inconsistent. Forecasts reflect assumptions about regulatory implementation timing, feedstock price stability, and consumer preference shifts that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Sun Care Products Market
Cosmetics & Skincare
Massaging Cosmetic Applicators Market
Cosmetics & Skincare
Hand Cream Market
Cosmetics & Skincare
Tea Based Face Masks Market
Cosmetics & Skincare
Eye Shadow Stick Market
Cosmetics & Skincare
Eye Makeup Market
Cosmetics & Skincare
Period Balm Market
Cosmetics & Skincare
Global Cosmetic Shea Butter Market
Cosmetics & Skincare
Moisturizing Spray Market
Cosmetics & Skincare
Epigenetic Cosmetic Products Market
Cosmetics & Skincare
Cosmetics Private Label and Contract Manufacturing Market
Cosmetics & Skincare
Global Facial Cleanser Market
Cosmetics & Skincare
Matte Lipstick Market
Cosmetics & Skincare
Natural Cosmetic Color Market
Cosmetics & Skincare
J-Beauty Products Market
Cosmetics & Skincare
Lipstick Market