
 Canada Cosmetic Products Market | 2026-2036
Canada Cosmetic Products Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Cosmetic Products Market Outlook
Cosmetic chemist talent is rotating toward natural formulation expertise as Canadian brands scramble to meet clean-label expectations. L'Oréal leverages its established Montreal R&D footprint to develop region-specific skincare lines. Estée Lauder anchors its prestige positioning through controlled distribution in Holt Renfrew and select specialty retail. Beiersdorf competes aggressively in the dermocosmetic channel with its Eucerin brand, while Shiseido extends its reach through Toronto-based digital marketing operations targeting multicultural consumers.
Cosmetic products encompass chemically formulated preparations applied to the human body for cleansing, beautifying, or altering appearance, typically containing emulsifiers, active ingredients, and preservatives at specified pH levels and stability thresholds. These products serve personal care and aesthetic enhancement purposes across consumer and professional settings. Skincare dominates value contribution as Canadian consumers prioritize preventive aging and barrier-repair formulations, while online retail captures the fastest volume growth through direct-to-consumer subscription models. Cruelty-free and vegan segments attract disproportionate margin pools as certification requirements elevate pricing power and reduce price elasticity among ethically motivated buyers.
Health Canada enforces the Cosmetic Regulations under the Food and Drugs Act, mandating ingredient disclosure, safety substantiation, and notification prior to sale. The Canadian Environmental Protection Act and related frameworks restrict certain preservatives and microplastics, compelling reformulation across haircare and makeup categories. Provincial regulators in Quebec supplement federal rules with stricter labeling requirements under the Charter of the French Language. Stakeholders must monitor pending amendments to the Cosmetic Ingredient Hotlist and assess whether domestic manufacturing investments or U.S. import dependencies better serve compliance timelines.
Market Dynamics
Health Canada's tightening Cosmetic Ingredient Hotlist revisions are forcing systemic reformulation across preservative-dependent categories, compressing product development timelines while elevating compliance costs for domestic manufacturers and importers alike.
Growth Catalysts
- Clean-label certification frameworks:Health Canada's evolving safety substantiation requirements under the Cosmetic Regulations are accelerating R&D investment in plant-derived emulsifiers and fermentation-based actives among Ontario-based formulators.
- Quebec's Charter of the French Language amendments:Stricter bilingual labeling mandates are creating competitive moats for domestic producers with established compliance infrastructure versus cross-border competitors facing localization delays.
- Digital-first distribution infrastructure:Direct-to-consumer subscription platforms operating from Toronto and Vancouver are capturing recurring revenue pools in personalized skincare, bypassing traditional retail margin structures.
Market Restraints
- Petrochemical-derived emollient volatility:Price instability in squalane and silicone feedstocks is compressing gross margins for mass-market haircare and color cosmetics manufacturers dependent on imported raw materials.
- Single-source preservative dependencies:Concentration of phenoxyethanol and paraben alternatives among German and Swiss specialty chemical suppliers exposes Canadian brands to supply continuity risks during regulatory transition periods.
- Biodegradability performance gaps:Technical limitations in achieving equivalent shelf stability for fully biodegradable surfactant systems are restricting formulation options within Health Canada's microplastic restriction timelines.
Strategic Opportunities
- Atlantic Canada manufacturing corridors:Underutilized production capacity in Halifax and Moncton offers cost-competitive expansion options for brands seeking proximity to European export markets without U.S. tariff exposure.
- Indigenous botanical ingredient partnerships:Collaborative sourcing agreements with First Nations communities in British Columbia are unlocking novel active ingredient pipelines with distinctive geographic indication potential.
- Provincial green procurement mandates:Ontario's sustainable purchasing guidelines for institutional buyers are creating preferential access channels for cruelty-free and vegan-certified professional product lines.
Industry Challenges
- Cosmetic chemist specialization gaps:Shortages in natural formulation expertise and preservative-free stability engineering are extending product development cycles beyond competitive windows.
- Dual regulatory compliance burdens:Simultaneous adherence to Health Canada's notification requirements and U.S. FDA labeling standards is fragmenting packaging runs and inventory management for cross-border brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Cosmetic Products Market |
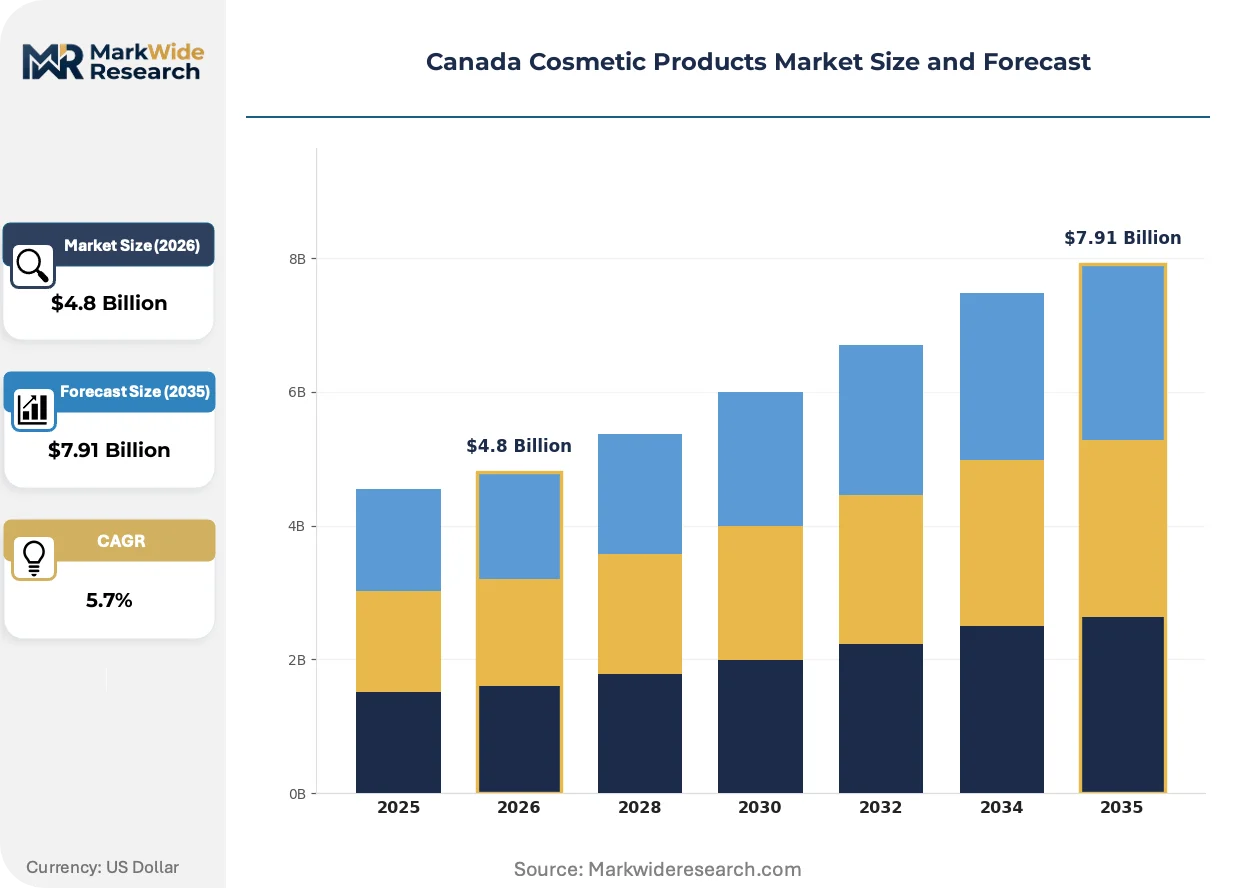
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Makeup, Haircare, Fragrance Distribution Channel: Online Retail, Department Stores, Specialty Stores, Pharmacies Consumer Age Group: Teenagers, Millennials, Gen X, Baby Boomers Formulation Type: Cruelty-Free, Organic, Vegan, Mineral |
| Companies Covered | L'Oréal, Unilever, Procter & Gamble, Estée Lauder, Coty, Shiseido, Revlon, Beiersdorf, Chanel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Cosmetic Products Market Strategic Shifts
Biotechnology-derived actives and precision fermentation processes are restructuring ingredient sourcing strategies, while regulatory pressure on synthetic preservatives accelerates investment in microbiome-compatible preservation systems across Canadian formulation labs.
Precision fermentation-derived squalane and ceramide analogues are achieving cost parity with plant-extracted alternatives. Mid-tier skincare brands in Toronto and Vancouver are adopting these inputs at scale for barrier-repair serums. Synthetic petrochemical emollients is supplanting bio-identical lipids as the default functional base in premium facial moisturizers.
Health Canada's pending amendments to the Cosmetic Ingredient Hotlist are expanding prohibited and restricted substance categories. Domestic manufacturers are pre-emptively reformulating hair dye and sunscreen portfolios to avoid discontinuation risks. Quebec's provincial regulators are advancing parallel restrictions on certain UV filters, compressing formulation flexibility for national product lines.
Subscription-based replenishment models are displacing traditional retail replenishment cycles in facial skincare. Urban millennial consumers in Montreal and Calgary are consolidating purchases through direct-to-consumer platforms offering algorithmic personalization. British Columbia's dense metropolitan corridors are exhibiting the highest concentration of these switching behaviors, with specialty retail foot traffic declining proportionally.
Canada Cosmetic Products Market Segmentation
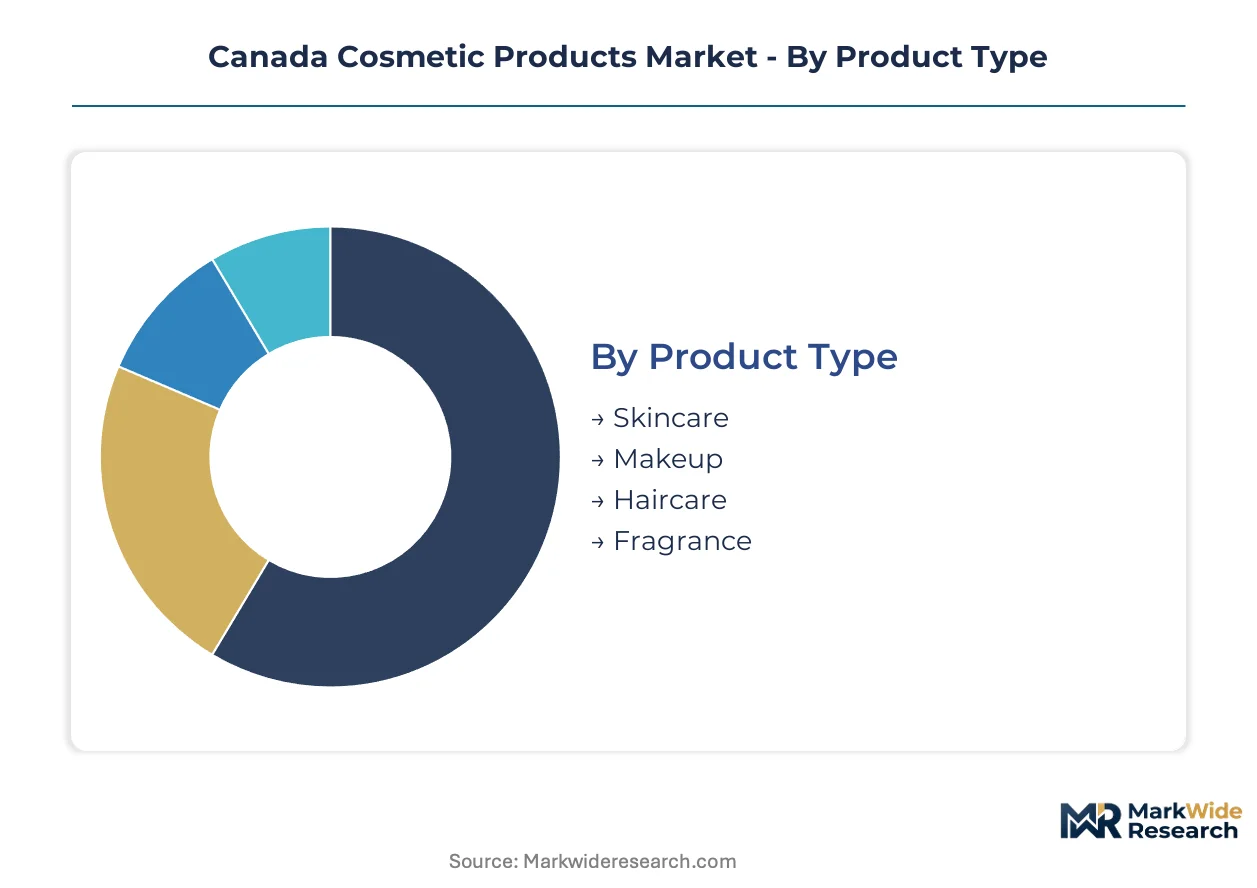
Segmentation reveals how Health Canada's regulatory pressure and regional consumer preferences fragment demand across distinct product and channel configurations. Understanding these divisions exposes where compliance costs concentrate and where margin expansion remains feasible.
Product Type:
Domestic manufacturing capacity concentrates in Ontario and Quebec for mass-market categories, while premium segments rely heavily on European and Asian imports through Vancouver and Toronto distribution hubs.
- Skincare:Emulsifier-rich formulations with ceramide complexes and peptide actives dominate R&D expenditure. Demand clusters in Toronto and Vancouver urban centers among millennial consumers pursuing preventive aging regimens, with Health Canada's preservative restrictions accelerating microbiome-compatible preservation investment.
- Makeup:Color cosmetics incorporating silicone-derived emollients and mineral pigments face reformulation pressure under pending microplastic restrictions. British Columbia and Ontario account for disproportionate volume given higher per-capita spending on prestige color products.
- Haircare:Sulfate-free surfactant systems with plant-derived conditioning agents serve the mass-market channel. Atlantic Canada manufacturing corridors supply private-label volume for drugstore distribution.
- Fragrance:Alcohol-based formulations with synthetic and natural aromatic compounds face Quebec's stricter VOC disclosure requirements. Import dependency runs high for niche and luxury fragrance.
Skincare holds the largest share; momentum sits with haircare as clean-label reformulation accelerates across mass and prestige tiers.
Distribution Channel:
Channel selection determines compliance burden intensity, with direct-to-consumer platforms avoiding Quebec's bilingual labeling mandates that constrain cross-border inventory management.
- Online Retail:Subscription-based replenishment platforms with algorithmic personalization engines capture recurring revenue in facial skincare. Toronto and Vancouver operations bypass traditional retail margin structures while navigating Health Canada's notification requirements for each SKU variant.
- Department Stores:Prestige brand counters in Holt Renfrew and Hudson's Bay anchor luxury positioning through controlled experiential retail. Inventory localization costs elevate for national product lines facing Quebec's Charter of the French Language amendments.
- Specialty Stores:Sephora and independent beauty boutiques concentrate cruelty-free and vegan-certified assortment. Foot traffic declines proportionally as British Columbia consumers shift to digital replenishment.
- Pharmacies:Shoppers Drug Mart and Jean Coutu dermocosmetic bays emphasize pharmacist-curated skincare with therapeutic positioning. Eucerin and La Roche-Posay maintain shelf dominance through clinical endorsement.
Pharmacies retain the highest transaction frequency; online retail gains share fastest through subscription conversion.
Consumer Age Group:
Generational purchasing patterns split between digital-native replenishment behaviors and traditional retail loyalty, with age cohorts clustering geographically across Canadian metropolitan corridors.
- Millennials:Algorithmic personalization and clean-label certification drive purchasing decisions. Urban concentrations in Montreal and Calgary consolidate spending through direct-to-consumer platforms.
- Gen X:Prestige department store counters and professional salon channels retain loyalty. Higher per-transaction value supports specialty retail footprint in Toronto and Vancouver.
- Teenagers:Social commerce and influencer-driven discovery dominate acquisition. TikTok-native brands bypass traditional distribution entirely.
- Baby Boomers:Pharmacist consultation and clinical efficacy claims guide selection. Shoppers Drug Mart dermocosmetic bays capture disproportionate volume.
Millennials command the largest addressable spend; teenagers expand most quickly through social commerce penetration.
Formulation Type:
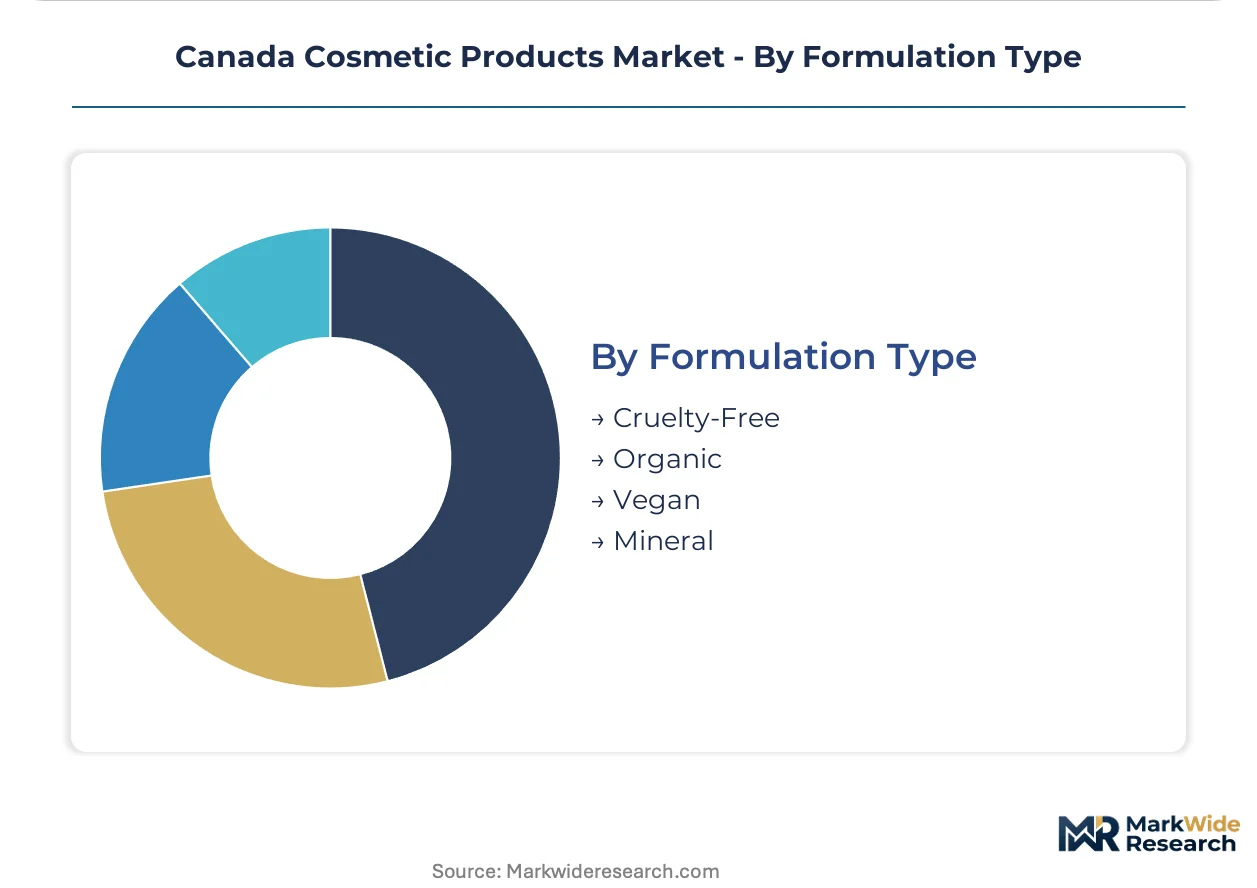
Certification requirements create tiered pricing architecture, with vegan and organic segments attracting disproportionate margin pools through reduced price elasticity among ethically motivated buyers.
- Cruelty-Free:Leaping Bunny and PETA certification frameworks mandate supply chain audit trails. Domestic brands leverage Canadian manufacturing to satisfy transparency demands.
- Organic:ECOCERT and COSMOS standards restrict synthetic preservative options, compressing formulation flexibility. British Columbia consumers exhibit highest willingness-to-pay premiums.
- Vegan:Elimination of animal-derived ingredients including honey, lanolin, and carmine expands addressable market among ethically motivated segments. Certification costs elevate pricing power.
- Mineral:Titanium dioxide and zinc oxide-based sunscreens and color cosmetics face Quebec's parallel UV filter restrictions. Reformulation timelines compress as Health Canada Hotlist amendments advance.
Cruelty-free captures the broadest adoption; vegan formulations climb fastest as certification infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health Canada anchors regulatory oversight across provincial markets, with compliance requirements tightening formulation standards from Vancouver to Halifax. Provincial regulators in Quebec layer additional mandates atop federal rules. Metropolitan demand clusters concentrate where millennial consumers drive clean-label purchasing.
Ontario
Toronto's millennial population fuels preventive aging skincare demand through direct-to-consumer subscription platforms. Health Canada's Cosmetic Regulations enforcement concentrates inspection resources in the province's manufacturing corridors. The Greater Toronto Area hosts domestic formulation labs serving national distribution networks.
Quebec
Montreal consumers exhibit strong preference for cruelty-free and vegan-certified product lines across prestige and mass tiers. The Charter of the French Language mandates stricter bilingual labeling than federal requirements alone. Laval and Quebec City manufacturing facilities specialize in haircare and fragrance production for eastern Canadian markets.
British Columbia
Vancouver's urban density supports the highest per-capita spending on premium organic skincare formulations. Health Canada coordinates with provincial environmental regulators on microplastic restriction timelines affecting coastal manufacturing. Indigenous botanical ingredient partnerships with First Nations communities unlock novel active sourcing pipelines in the Pacific Northwest.
Alberta
Calgary's younger demographic profile accelerates digital-first purchasing behaviors in personalized skincare subscriptions. Provincial procurement guidelines for institutional buyers create preferential access channels for certified sustainable product lines. Edmonton distribution hubs serve prairie markets with compressed logistics costs versus coastal import routes.
Atlantic Canada
Halifax and Moncton offer underutilized production capacity for brands seeking European export proximity without U.S. tariff exposure. Health Canada's notification requirements apply uniformly, though provincial enforcement resources remain thinner than in central Canada. The region's lower operating costs attract private-label manufacturing for drugstore distribution chains.
Canada Cosmetic Products Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with multinational conglomerates controlling prestige distribution through department store anchors while mid-tier domestic brands compete on clean-label certification speed. Three archetypes dominate: global beauty conglomerates with established R&D footprints, regional specialists leveraging proximity compliance advantages, and digital-native direct-to-consumer brands bypassing traditional retail margin structures. Competitive moves concentrate on portfolio diversification into dermocosmetic positioning and strategic partnerships with biotechnology ingredient suppliers.
Within the global conglomerate tier, L'Oréal and Estée Lauder exemplify integrated leaders with established Canadian market presence, while Beiersdorf represents the dermocosmetic specialist archetype competing through clinical endorsement channels. These entities occupy positions that reflect divergent strategic bets on regulatory compliance infrastructure versus digital distribution agility.
| Leading Market Players |
|---|
| L'Oréal |
| Unilever |
| Procter & Gamble |
| Estée Lauder |
| Coty |
| Shiseido |
| Revlon |
| Beiersdorf |
| Chanel |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles for phenoxyethanol and paraben alternatives concentrate pricing power among German and Swiss specialty chemical suppliers serving Canadian formulators. This lead-time compression amplifies margin pressure on domestic brands navigating Health Canada's Cosmetic Ingredient Hotlist revisions while elevating cost pass-through capability for upstream preservative manufacturers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates vegan-certified organic formulations in Vancouver and Toronto from mass-market haircare distributed through Atlantic Canada drugstore channels. Price differentiation stems from certification grade complexity and geographic delivery cost asymmetries between European import routes and domestic manufacturing. Pricing pressure stems from petrochemical-derived emollient feedstock volatility compressing gross margins in color cosmetics. Mass-market consumers exhibit highest price sensitivity, while ethically motivated millennials purchasing through direct-to-consumer platforms demonstrate reduced elasticity for cruelty-free certified SKUs.
Supply Chain Analysis
Sixty-day safety stock requirements for fermentation-based actives and plant-derived emulsifiers reflect just-in-time dependencies on Ontario-based formulators serving national distribution networks. Raw material sourcing draws from German preservative suppliers, Swiss specialty chemical manufacturers, and British Columbia First Nations botanical partnerships. Single-source vulnerability concentrates in phenoxyethanol alternatives during regulatory transition periods. Distribution runs through Toronto and Vancouver direct-to-consumer fulfillment centers bypassing traditional retail margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Health Canada's pending Cosmetic Ingredient Hotlist amendments constitute a regulatory inflection accelerating biotechnology-derived active adoption and compressing reformulation timelines for preservative-dependent categories.
For Market Incumbents: Consolidate formulation expertise through captive hiring of natural preservation engineers and microbiome-compatible stability specialists. Acquire Ontario-based manufacturing assets to satisfy Health Canada notification requirements while reducing cross-border compliance fragmentation. Deepen backward integration into precision fermentation-derived ceramide analogues to offset petrochemical emollient price volatility threatening mass-market haircare margins. For New Entrants and Emerging Players: Anchor in Atlantic Canada manufacturing corridors where underutilized Halifax and Moncton capacity offers European export proximity without U.S. tariff exposure. Target Indigenous botanical ingredient partnerships with First Nations communities in British Columbia to unlock geographic indication potential and differentiated active pipelines. Deploy algorithmic personalization engines through subscription-based replenishment models capturing recurring revenue from Montreal and Calgary millennial consumers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision fermentation infrastructure and clean-label certification compliance systems. Long-term viability favors acquisition targets with established Health Canada notification track records and scalable direct-to-consumer fulfillment architectures. Monitor Health Canada Hotlist amendment timing as the critical signal for portfolio reformulation risk exposure and stranded asset vulnerability in preservative-heavy product lines.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Certification Investment | Leaping Bunny and ECOCERT compliance accelerates pricing power among ethically motivated Ontario and British Columbia consumers. |
| Precision Fermentation Partnership | Biotechnology-derived squalane and ceramide sourcing reduces petrochemical feedstock dependency for Toronto formulators. |
| Direct-to-Consumer Platform Launch | Algorithmic personalization engines bypass Quebec bilingual labeling mandates while capturing recurring skincare revenue. |
| Atlantic Canada Manufacturing Expansion | Halifax and Moncten capacity accesses European export markets without U.S. tariff exposure for national brands. |
| Indigenous Botanical Sourcing Agreement | First Nations partnerships in British Columbia unlock novel active ingredients with geographic indication protection potential. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cosmetic chemists, brand formulation directors, Health Canada regulatory affairs specialists, Shoppers Drug Mart category buyers, and direct-to-consumer platform operators. Secondary validation drew from Health Canada Cosmetic Ingredient Hotlist amendments, Quebec Charter of the French Language regulatory filings, Nielsen retail audit data, and customs import records tracking European preservative shipments. Bottom-up SKU-level volume builds were triangulated against top-down category expenditure models.
Across the analysis window, projections incorporate segmentation by product type, distribution channel, consumer age cohort, and formulation certification tier. CAGRs were derived from regression analysis of historical volume trajectories and elasticity-adjusted price evolution. Forecast inputs include Health Canada regulatory amendment timelines, Quebec labeling mandate implementation schedules, and millennial cohort purchasing pattern shifts in Toronto and Vancouver metropolitan corridors.
Material uncertainties — Health Canada Hotlist revision scope, Quebec provincial regulatory parallel actions, and biotechnology ingredient cost parity achievement — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and consumer certification preference stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Global Cosmetic Shea Butter Market
Cosmetics & Skincare
Facial Serum Market
Cosmetics & Skincare
Microbiome Cosmetic Products Market
Cosmetics & Skincare
GCC Bath Soap Market
Cosmetics & Skincare
Scalp Scrub Market
Cosmetics & Skincare
Waterproof Temporary Tattoo Sticker Market
Cosmetics & Skincare
Herbal Soap Market
Cosmetics & Skincare
Organic Color Cosmetics Products Market
Cosmetics & Skincare
Asia-Pacific Halal Cosmetics Market
Cosmetics & Skincare
Israel Cosmetics Market
Cosmetics & Skincare
Matte Lipstick Market
Cosmetics & Skincare
Epigenetic Cosmetic Products Market
Cosmetics & Skincare
Period Balm Market
Cosmetics & Skincare
Thailand Skin Care Products Market
Cosmetics & Skincare
China Skincare Market
Cosmetics & Skincare
Body Cream Jars Market