
 North America Bath Soap Market | 2026-2036
North America Bath Soap Market Size, Share, and Industry Trends Forecast 2026-2036
North America Bath Soap Market Intelligence
Capital-intensity divergence between mass-market and artisanal manufacturers is collapsing as mid-tier players automate batch production and direct-to-consumer fulfillment. Procter & Gamble leverages its North American manufacturing footprint to sustain shelf-space dominance across conventional retail channels. Dr. Bronner's anchors the organic segment through certified fair trade supply chains and radical transparency labeling. Unilever competes via dual-brand architecture, operating mass-market and premium soap lines through separate channel strategies.
North America bath soap encompasses surfactant-based cleansing bars and liquid formulations, typically combining fatty acid salts with glycerin, fragrance compounds, and functional additives at pH ranges of 9-10, manufactured through continuous saponification or batch cold-process methods for personal hygiene and skin conditioning applications. The liquid soap category captures expanding share in commercial end-user settings such as hotels and gyms, where pump-dispenser formats reduce cross-contamination risk and labor costs associated with bar replacement. Specialty soap, spanning exfoliating, medicated, and fragrance-free dermatological variants, commands disproportionate margin pools as ingredient transparency and clean-label positioning displace synthetic antibacterial formulations in premium channels.
The EPA's Safer Choice program and California's Proposition 65 chemical warning requirements constrain synthetic preservative and fragrance compound selection, while the FDA's cosmetic labeling regulations mandate ingredient disclosure that shapes consumer trust and retail access decisions. State-level extended producer responsibility frameworks emerging in Oregon and Maine will impose packaging recovery obligations on bottles, bar wrappers, and pump dispensers, altering cost structures across the packaging type dimension. Stakeholders must monitor regulatory fragmentation between U.S. federal baseline standards and accelerating state-level chemical restriction regimes to anticipate compliance-driven product reformulation cycles and channel redistribution.
Market Dynamics
Clean-label ingredient mandates from California's Proposition 65 and the EPA's Safer Choice program are forcing simultaneous reformulation across mass-market and premium soap portfolios, collapsing the historical regulatory gap between tiered positioning strategies.
Growth Catalysts
- Gen Z and millennial health consciousness:Younger cohorts prioritize dermatologically tested, fragrance-free formulations, expanding the specialty soap segment beyond traditional medicated applications.
- Extended producer responsibility frameworks:Oregon and Maine are imposing packaging recovery obligations that accelerate recyclable pump-dispenser and bar-wrapper innovation.
- Commercial hygiene protocols:Hotels and gyms are standardizing liquid soap pump formats to reduce cross-contamination risk and labor costs associated with bar replacement cycles.
Market Restraints
- Palm oil and coconut fatty acid volatility:Tropical supply disruptions transmit directly into surfactant input costs, compressing margin pools for batch-process manufacturers.
- Fragrance compound restrictions:California's Proposition 65 warning requirements constrain synthetic scent portfolios, limiting product differentiation in conventional retail channels.
- Bar soap substitution pressure:Body wash and shower gel formats capture bathroom counter space, particularly in urban households with limited storage.
Strategic Opportunities
- Underserved dermatological segments:Eczema and psoriasis-specific formulations show penetration gaps in the U.S. Midwest and Southeast corridors where specialty retail density remains low.
- Direct-to-consumer subscription models:Automated replenishment platforms bypass shelf-space competition and capture lifetime value through personalized scent profiling.
- Biodegradable surfactant convergence:Cold-process methods integrating enzymatic catalysts reduce energy intensity while satisfying EPA Safer Choice biodegradability thresholds.
Industry Challenges
- Formulation chemist scarcity:pH-balanced, preservative-free stability engineering requires specialized expertise that outpaces North American university pipeline output.
- Cold-process scale-up capital:Artisanal manufacturers face equipment-intensive transitions from batch to semi-continuous production without sacrificing clean-label positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Bath Soap Market |
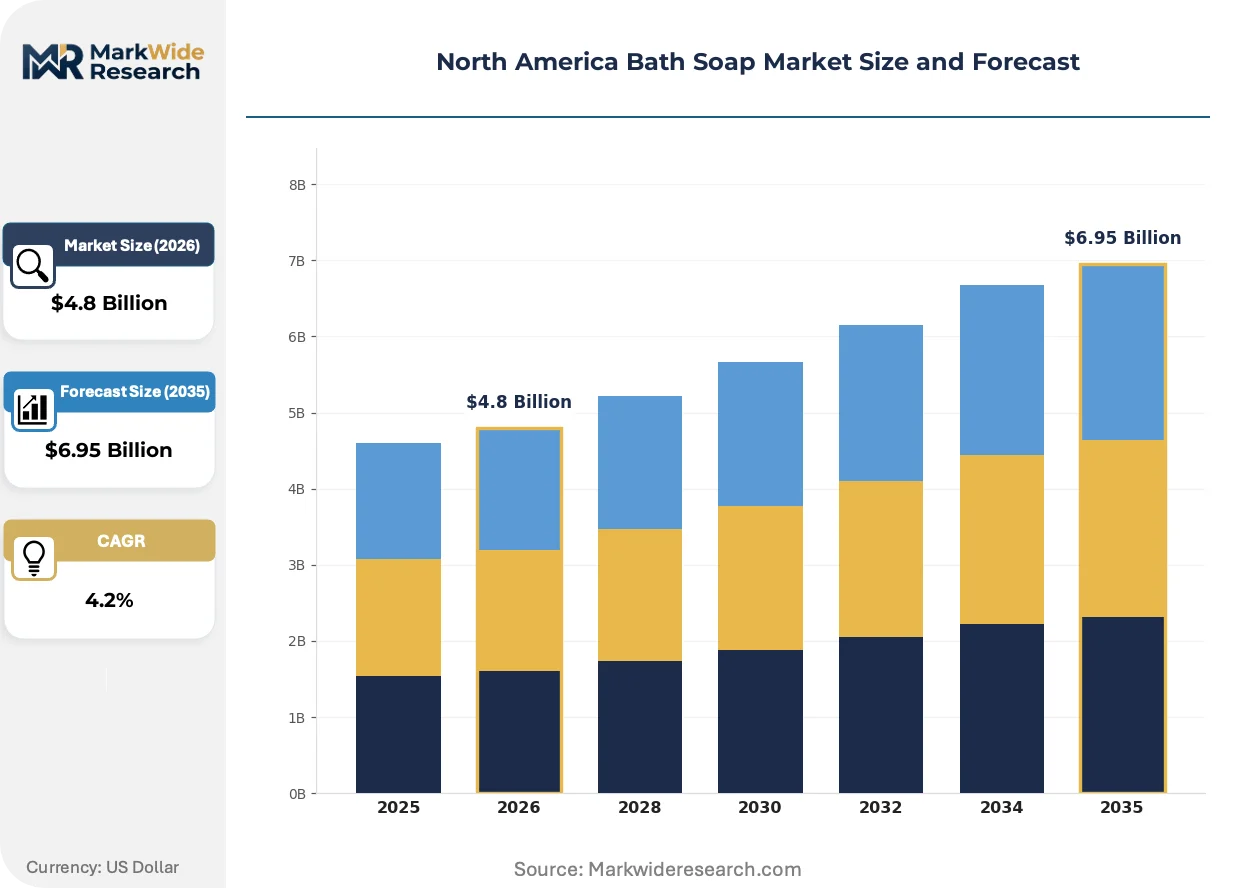
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bar Soap, Liquid Soap, Foaming Soap, Specialty Soap Ingredient: Natural, Organic, Synthetic, Antibacterial Packaging Type: Bottles, Bar Wrappers, Pump Dispensers, Sachets End User: Households, Hotels, Gyms, Spas |
| Companies Covered | Henkel, GOJO Industries, Procter & Gamble, Dr. Bronner's, Dove, Colgate-Palmolive Company, Reckitt Benckiser, Burt's Bees, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Bath Soap Market Strategic Shifts & Innovations
Surfactant chemistry and distribution architecture are undergoing parallel transformation as regulatory pressure and channel fragmentation force simultaneous innovation across formulation science and fulfillment logistics.
Solid bar formulations with waterless concentrate cores are bifurcating the liquid-versus-bar taxonomy that has defined category segmentation for decades. Health-conscious millennials in the U.S. Northeast and West Coast corridors are adopting these hybrid formats at accelerating velocity. This technology is bifurcating shelf-space negotiations, forcing retailers to allocate dedicated fixtures for concentrate refills separate from conventional bar and liquid displays.
The EPA's Safer Choice program and California's Proposition 65 chemical warning requirements are constraining synthetic preservative and fragrance compound selection across all price tiers. Manufacturers must now maintain parallel formulation libraries: one compliant with federal baseline standards, another with state-level chemical restriction regimes. Premium and mass-market soap lines are both affected, though premium channels absorb compliance costs through pricing power while mass-market players face margin compression.
Health system procurement departments and hospitality purchasing consortia are consolidating vendor relationships around single-source soap contracts with embedded sustainability reporting. Large hospital networks and national hotel chains are displacing fragmented supplier bases with preferred partnerships that bundle liquid soap, bar soap, and sanitizer SKUs under unified ESG compliance documentation. This consolidation is most visible in the U.S. Northeast corridor where integrated delivery networks and hospitality REITs concentrate purchasing volume.
North America Bath Soap Market Segmentation
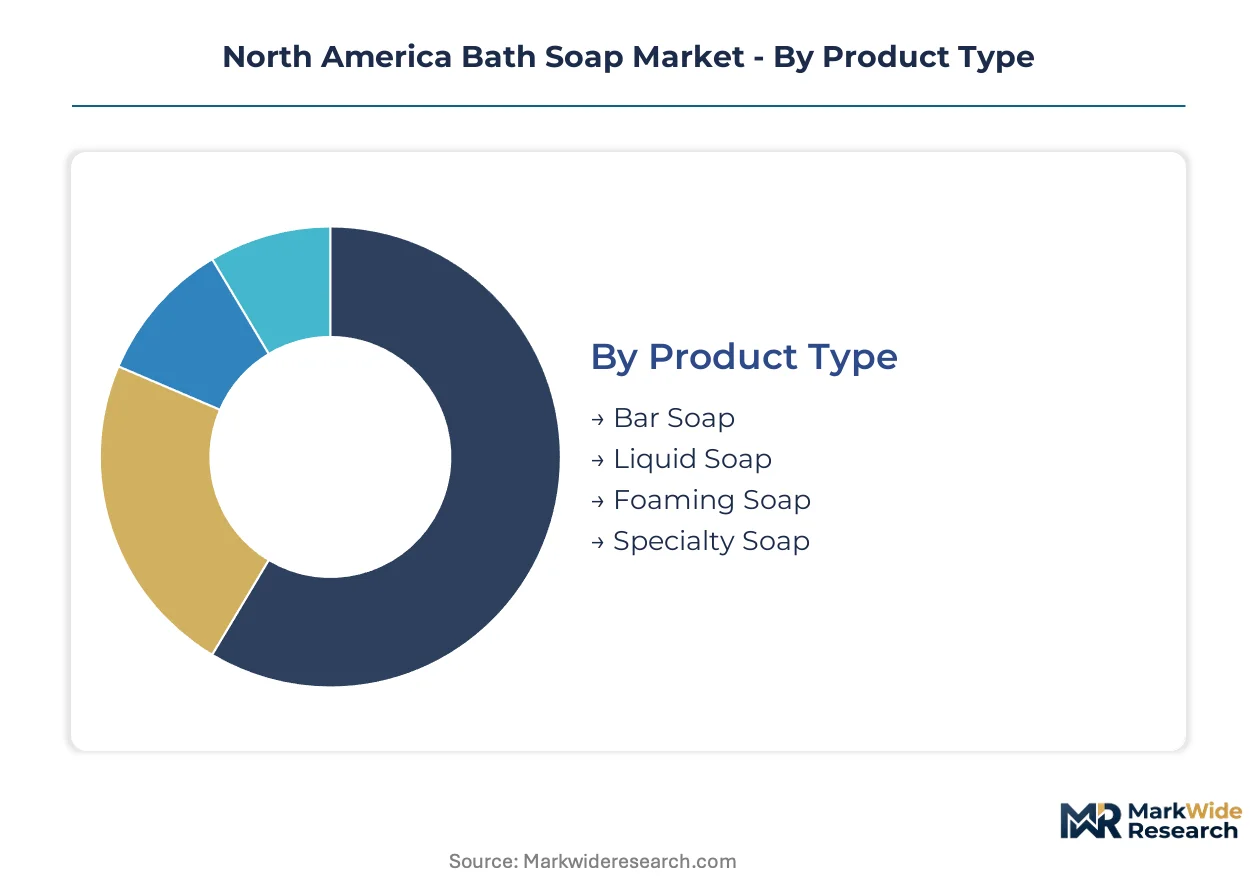
Segmentation in North American bath soap markets reveals how regulatory pressure and channel fragmentation create divergent compliance burdens across product formats. Each dimension exposes distinct margin structures and reformulation cycles that reshape competitive positioning.
Product Type:
EPA Safer Choice biodegradability thresholds and California Proposition 65 warning requirements apply unevenly across solid and liquid formats, with surfactant chemistry determining compliance pathway costs.
- Bar Soap:Continuous saponification produces fatty acid salt matrices at pH 9-10, with glycerin retention varying by cold-process versus hot-process method. Northeast and West Coast retail corridors concentrate demand for palm-oil-free and coconut-oil variants as ESG sourcing transparency intensifies.
- Liquid Soap:Potassium-based surfactant solutions require preservative systems that face tighter scrutiny under state-level chemical disclosure laws. Hotel and gym procurement consortia in the U.S. Northeast standardize pump-dispenser formats to reduce cross-contamination risk and labor replacement cycles.
- Foaming Soap:Diluted surfactant concentrates with specialized aeration mechanisms command premium positioning in institutional hygiene contracts.
- Specialty Soap:Exfoliating, medicated, and dermatological variants integrate functional additives for eczema and psoriasis applications.
Bar soap handles the majority of throughput; liquid soap is the fastest mover on share.
Ingredient:
Cost tier differentiation separates mass-market synthetic formulations from premium certified supply chains, with mid-tier players straddling both positioning strategies.
- Natural:Plant-derived surfactants and unrefined oils satisfy clean-label positioning without full organic certification overhead. Midwest and Southeast retail penetration lags coastal corridors where ingredient transparency commands shelf-space allocation.
- Organic:USDA NOP certification and fair trade supply chain documentation anchor premium channel access. West Coast natural product retailers and direct-to-consumer subscription platforms concentrate demand for radical transparency labeling.
- Synthetic:Petrochemical-derived surfactants and fragrance compounds face reformulation pressure under state-level chemical restriction regimes.
- Antibacterial:Triclosan-free alternatives using benzalkonium chloride or essential oil systems replace legacy formulations banned from consumer markets.
Synthetic ingredients still dominate volume throughput; organic certification claims are expanding most quickly in premium channels.
Packaging Type:
Extended producer responsibility frameworks in Oregon and Maine impose recovery obligations that alter cost structures across rigid and flexible formats.
- Bottles:HDPE and PET containers face recycled content mandates under emerging state-level circular economy regulations. Hotel chains and gym operators in the Northeast prioritize bulk refill systems to minimize single-use packaging liability exposure.
- Bar Wrappers:Paper-based and compostable films replace multilayer plastic laminates as shelf-ready sustainability signaling intensifies. Mass-market retail channels in California absorb higher unit costs to maintain Proposition 65 compliant supply chains.
- Pump Dispensers:Mechanical closure systems complicate material separation for recycling streams, driving innovation in mono-material designs.
- Sachets:Single-use flexible packaging concentrates in travel and hospitality amenity applications with limited collection infrastructure.
Bottles handle the majority of throughput; bar wrappers are climbing the fastest on sustainability-driven substitution.
End User:
Procurement consolidation across health systems and hospitality REITs collapses fragmented supplier relationships into unified vendor contracts with embedded ESG reporting.
- Households:Urban consumers with limited bathroom storage favor liquid and concentrate formats over traditional bar configurations. Direct-to-consumer subscription models capture replenishment automation and personalized scent profiling data.
- Hotels:National chain consolidation around preferred vendor partnerships bundles soap, sanitizer, and amenity SKUs under single-source contracts. Northeast corridor hospitality REITs concentrate purchasing volume with sustainability documentation requirements.
- Gyms:High-frequency touchpoint protocols prioritize pump-dispenser liquid formats with antimicrobial claims.
- Spas:Premium positioning demands certified organic and aromatherapy-grade formulations with batch traceability.
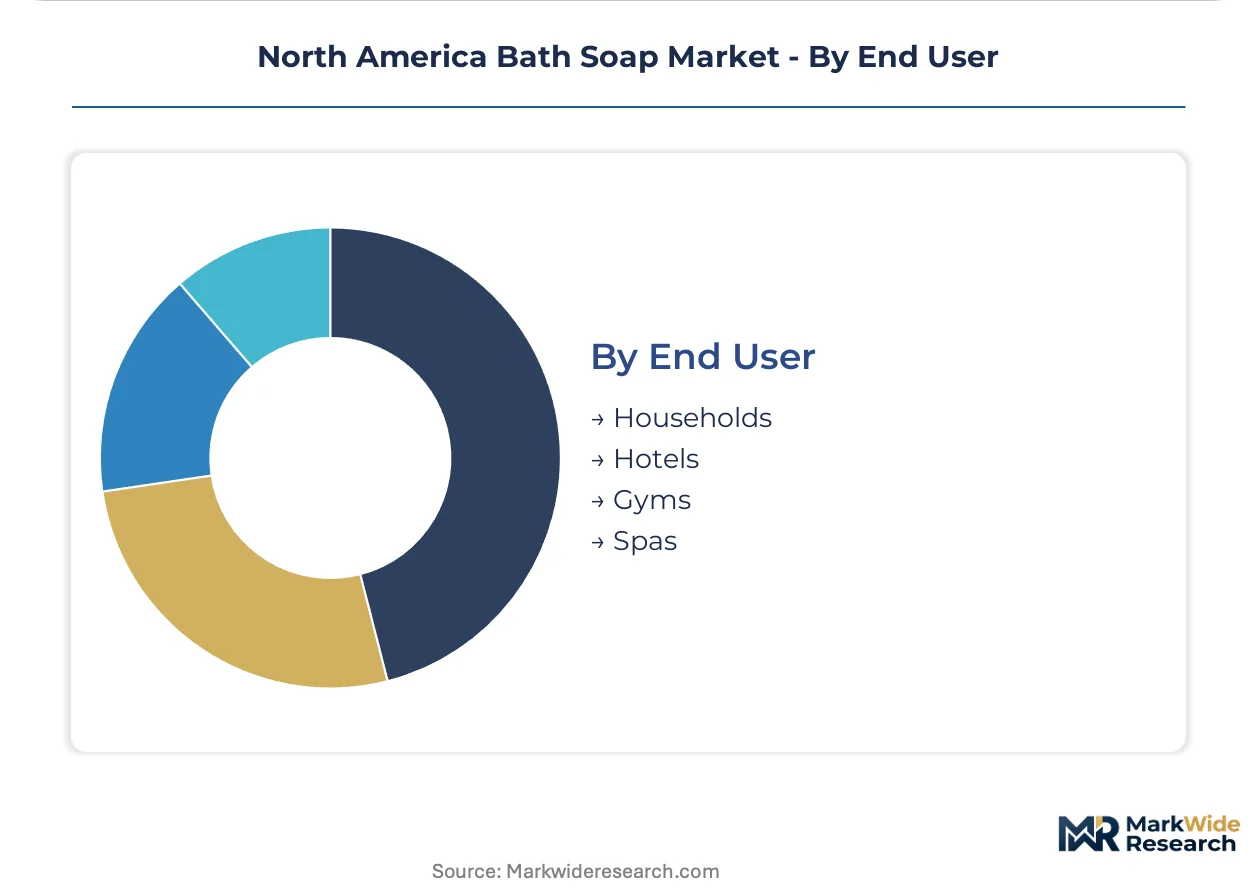
Households handle the majority of throughput; hotel procurement consolidation is gaining share fastest on contract standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates along the U.S. Northeast and West Coast corridors, where clean-label retail penetration commands shelf-space premiums unavailable to Midwest mass-market distributors. Canadian specialty channels absorb comparable ESG compliance costs with narrower volume bases. Mexican manufacturing clusters exploit tariff-advantaged export positioning toward U.S. border states.
United States
Millennial and Gen Z dermatological demand drives specialty soap growth in coastal urban corridors. The EPA's Safer Choice program and California's Proposition 65 constrain synthetic preservative selection nationwide. Northeast hospitality REITs and integrated health networks consolidate procurement around single-source contracts with embedded sustainability documentation.
Canada
Health-conscious consumers in Toronto and Vancouver metro areas mirror U.S. West Coast clean-label preferences with smaller absolute volumes. Health Canada and PMRA cosmetic regulations align with FDA disclosure standards while maintaining distinct ingredient approval pathways. Quebec's personal care manufacturing base serves francophone retail channels with localized formulation variants.
Mexico
Export-oriented surfactant production clusters in Nuevo León and Jalisco supply U.S. border state distributors. Mexican regulatory frameworks under COFEPRIS coordinate with FDA cosmetic standards for cross-border commerce. Bajío Region chemical processing infrastructure supports toll manufacturing contracts for North American brand owners seeking cost-advantaged production.
North America Bath Soap Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the North America bath soap market. Mass-market shelf-space dominance concentrates among diversified consumer goods conglomerates with integrated manufacturing footprints. Mid-tier automation investments collapse historical capital-intensity gaps between artisanal and industrial producers. Strategic moves center on direct-to-consumer fulfillment infrastructure and certified supply chain documentation for ESG procurement requirements.
Within the mass-market tier, Procter & Gamble and Unilever occupy positions defined by retail channel breadth and dual-brand architecture separating premium from standard positioning. Dr. Bronner's anchors the organic segment through radical transparency labeling and fair trade supply chain verification. These three exemplify how divergent archetypes—scale-driven conglomerates versus mission-certified specialists—coexist under converging regulatory pressure from EPA Safer Choice and state-level chemical disclosure mandates.
| Leading Market Players |
|---|
| Henkel |
| GOJO Industries |
| Procter & Gamble |
| Dr. Bronner's |
| Dove |
| Colgate-Palmolive Company |
| Reckitt Benckiser |
| Burt's Bees |
| Unilever |
| Others |
Cost & Logistics Intelligence
Palm oil substitution by coconut and shea butter alternatives in premium formulations simultaneously shifts sourcing geography toward West African and Southeast Asian cooperatives while compressing margin structures for manufacturers locked into long-term tropical commodity contracts.
Pricing Analysis
The customization-premium spread between configured-to-order organic lines and standard synthetic formulations runs wide, with three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on USDA organic certification tier and volume scale commitments from hospitality procurement consortia. Cost compression in mass-market tiers is intensifying because surfactant input volatility transmits directly into finished goods economics. Household consumers in the U.S. Midwest exhibit highest price sensitivity, while Northeast hospitality REITs absorb premiums for embedded sustainability documentation.
Supply Chain Analysis
Malaysia and Indonesia anchor global palm oil production, while the Philippines and India concentrate coconut fatty acid refining capacity for North American surfactant manufacturers. Raw material portfolios draw from tropical oleochemical clusters, petroleum-derived feedstocks, and certified organic oilseeds. Single-source vulnerability in Indonesian palm supply chains exposes formulators to El Niño-driven production shocks. Distribution runs through diversified retail, direct-to-consumer subscription platforms, and consolidated institutional procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation chemistry expertise for pH-balanced, preservative-free stability engineering has outpaced North American university pipeline output, creating persistent capability gaps that advantage incumbents with captive R&D infrastructure.
For Market Incumbents: Consolidate procurement relationships with certified organic supply cooperatives to preempt raw material access constraints from emerging clean-label competitors. Deepen backward integration into surfactant manufacturing to capture margin pools currently held by Malaysian and Indonesian oleochemical processors. Defend against direct-to-consumer subscription entrants by locking hospitality REITs into multi-year single-source contracts with embedded ESG reporting.
For New Entrants and Emerging Players: Differentiate on dermatological specialization for eczema and psoriasis applications in the underserved U.S. Southeast and Midwest corridors where specialty retail density remains low. Target white-space opportunity in biodegradable surfactant cold-process methods integrating enzymatic catalysts that satisfy EPA Safer Choice thresholds. Pursue automated replenishment platforms with personalized scent profiling as the primary go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier manufacturers that have automated batch production but lack direct-to-consumer fulfillment infrastructure. Long-term viability over the coming decade rests on capturing ESG procurement mandates from consolidated health system and hospitality buyers. Watch for inflection signals in state-level extended producer responsibility enforcement that would accelerate packaging recovery cost burdens and trigger distressed divestitures.
| Strategic Initiative | Industry Significance |
|---|---|
| Certified Organic Supply Chain Integration | Fair trade verification unlocks premium channel access in West Coast natural product retail corridors. |
| Direct-to-Consumer Subscription Launch | Automated replenishment captures lifetime value through scent profiling data and bypasses shelf-space competition. |
| Biodegradable Surfactant R&D Investment | Enzymatic cold-process methods satisfy EPA Safer Choice biodegradability thresholds for institutional procurement. |
| Hospital System Partnership Consolidation | Unified vendor contracts bundle soap, sanitizer, and amenity SKUs under single-source ESG documentation. |
| Mono-Material Pump Dispenser Redesign | Material separation simplification addresses Oregon and Maine extended producer responsibility compliance obligations. |
Research Approach
Desk research of FDA cosmetic labeling regulations, EPA Safer Choice certified product listings, California Proposition 65 chemical databases, and Nielsen retail audit data preceded structured interviews with formulation chemists, hospitality procurement directors, natural products category buyers, and surfactant manufacturing plant managers. Primary fieldwork combined with secondary validation from trade customs records and SEC 10-K disclosures enabled bottom-up and top-down triangulation across the analysis window.
Variance decomposition across product type, ingredient certification tier, packaging format, and end-user channel shaped the analytical framework throughout the forecast period. CAGRs were derived from segment-level volume and value modeling incorporating surfactant input cost trajectories and regulatory compliance cycle timing. Industry-specific forecast inputs included EPA Safer Choice program expansion scenarios and state-level extended producer responsibility adoption patterns.
The analysis sits within stated boundaries; outcomes outside prevailing regulatory enforcement intensity and tropical commodity supply stability would require recalibration. Forecasts reflect assumptions regarding Proposition 65 warning requirement stringency and palm oil price volatility transmission mechanisms. Recalibration cycles align with material shifts in EPA program scope and state-level chemical restriction regime adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Cosmetics OEM and ODM Services Market
Cosmetics & Skincare
South America Cosmetics Products Market
Cosmetics & Skincare
Canada Cosmetic Products Market
Cosmetics & Skincare
Tea Based Face Masks Market
Cosmetics & Skincare
Mushroom Beauty Products Market
Cosmetics & Skincare
UK Eyelash Serum Market
Cosmetics & Skincare
Halal Cosmetic Products Market
Cosmetics & Skincare
Herbal Soap Market
Cosmetics & Skincare
Body Blurring Cosmetics Market
Cosmetics & Skincare
Magnetic Fake Eyelashes Market
Cosmetics & Skincare
Global Cosmetic Shea Butter Market
Cosmetics & Skincare
Global Cosmetic Antioxidant Market
Cosmetics & Skincare
Italy Lip Care Products Market
Cosmetics & Skincare
Waterproof Eyebrow Liner Market
Cosmetics & Skincare
Face Cream Market
Cosmetics & Skincare
Bangladesh Face Wash Market