
 Camellia Skincare and Cosmetics Market | 2026-2036
Camellia Skincare and Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Camellia Skincare and Cosmetics Market Outlook
Clean beauty enthusiasts are rotating toward clinical-grade natural formulations, pulling demand from conventional prestige buyers. True Botanicals leverages its vertically integrated supply chain to control camellia oil quality from cultivation to bottling. Vintners Daughter sustains premium positioning through small-batch fermentation processes. Pai Skin Care anchors its European presence with Soil Association-certified organic camellia formulations.
Camellia skincare and cosmetics encompass topical products formulated with Camellia oleifera or Camellia japonica seed oil, typically cold-pressed to preserve triterpene saponins and polyphenol concentrations exceeding 80% in refined grades. These formulations function primarily as occlusive moisturizers and oxidative stress inhibitors in facial care protocols. Moisturizers occupy the largest revenue pool due to daily-use frequency and premium pricing elasticity among aging demographics. Serums compete on active ingredient density, with brands differentiating through camellia oleifera versus rarer japonica cultivar sourcing. The natural formulation segment leads volume while organic certification commands the widest margin spread across distribution channels.
Japan's Ministry of Health, Labour and Welfare enforces Quasi-Drug standards that mandate substantiation for anti-aging botanical claims, directly shaping product development timelines for camellia-infused lines. The EU REACH framework and ECHA's microplastic restrictions constrain synthetic carrier formulations, indirectly advantaging pure plant-oil delivery systems. South Korea's MFDS cosmetic safety assessments require heavy metal screening for Jeju-sourced agricultural inputs. Stakeholders must monitor evolving biodegradability mandates in the EU Green Deal's chemical strategy, as these will determine which camellia extraction solvents retain market access.
Market Dynamics
Clean beauty certification requirements are compressing formulation timelines and forcing brands to consolidate supplier relationships around traceable camellia cultivation networks.
Growth Catalysts
- Quasi-Drug substantiation mandates:Japan's Ministry of Health, Labour and Welfare requires clinical evidence for anti-aging botanical claims, elevating camellia's research-backed positioning above generic natural alternatives.
- Jeju Island agricultural clustering:South Korea's MFDS cosmetic safety assessments for heavy metal screening have professionalized cultivation practices, creating export-grade quality tiers that command premium positioning.
- Cold-press extraction automation:Supercritical CO2 systems preserve triterpene saponin concentrations above 80%, enabling brands to market measurable bioactive potency rather than vague natural origin.
Market Restraints
- Input cost volatility:Camellia oleifera seed prices fluctuate with harvest yields in China's Hunan and Jiangxi provinces, compressing margin predictability for mid-tier formulators.
- Supply concentration risk:Over 60% of global camellia oil refining capacity sits with three Japanese and South Korean processors, creating bottleneck vulnerability during peak demand cycles.
- Regulatory friction:EU REACH framework constraints on synthetic carrier formulations force reformulation investments, disadvantaging smaller brands lacking dedicated compliance infrastructure.
Strategic Opportunities
- Underpenetrated Nordic markets:Sweden and Finland's cold-climate skincare routines remain dominated by petroleum-derived occlusives, creating white space for camellia's oxidative stability credentials.
- EU Green Deal biodegradability mandates:The chemical strategy's solvent restrictions favor cold-pressed camellia extraction over hexane-based alternatives, advantaging early adopters of green chemistry.
- Men's grooming channel expansion:Sephora's dedicated male skincare sections and direct-to-consumer subscription boxes are normalizing facial oil protocols beyond traditional female demographics.
Industry Challenges
- Certification timeline compression:Soil Association and COSMOS organic audits require 18-24 month supplier verification cycles, delaying product launches and freezing working capital.
- Formulation talent scarcity:Cosmetic chemists with dual expertise in natural extraction science and clinical efficacy testing command salary premiums that strain mid-cap R&D budgets.
- IP complexity in cultivar sourcing:Disputes over Camellia japonica varietal rights between Japanese agricultural cooperatives and commercial breeders threaten exclusive supply agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camellia Skincare and Cosmetics Market |
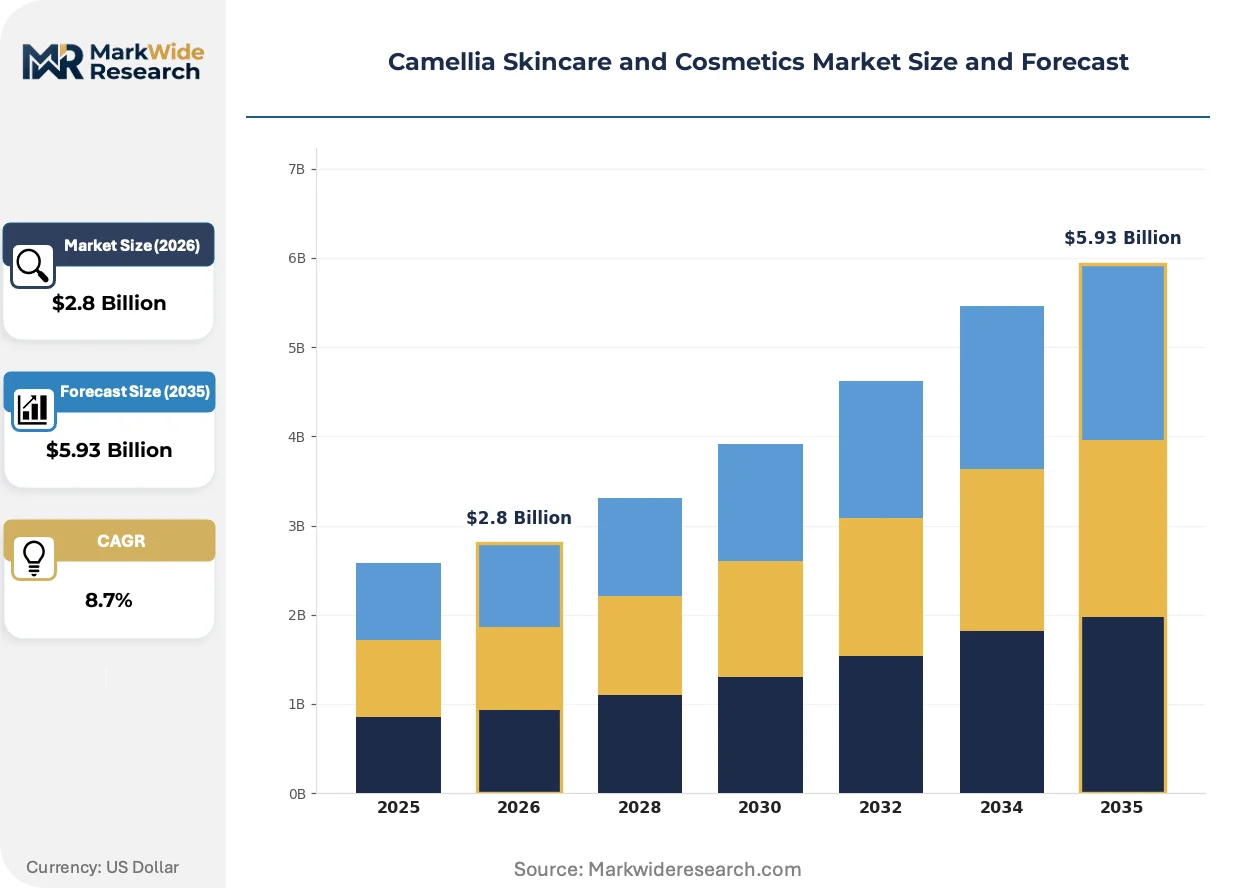
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Serums, Cleansers, Sunscreens End User: Individual Consumers, Salons, Spas, Retailers Formulation: Natural, Organic, Chemical-Based, Vegan Distribution Channel: Online Stores, Retail Outlets, Direct Sales, Distributors |
| Companies Covered | Vintners Daughter, True Botanicals, Pai Skin Care, French Farmacie, Juice Beauty, Dr. Alkaitis, Osima Organics, Nüssa Cosmetics, Laurel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camellia Skincare and Cosmetics Market Strategic Shifts
Formulation science is pivoting from marketing-driven natural claims to measurable bioactive delivery, with extraction technology and regulatory compliance emerging as the primary competitive differentiators.
Supercritical CO2 extraction is supplanting traditional cold-press methods for high-grade camellia oleifera oil production. Premium spa chains and clinical skincare lines specify CO2-processed grades for guaranteed saponin retention. This shift is compressing margins for artisanal producers lacking capital-intensive equipment, consolidating supply relationships around technology-capable processors.
EU REACH microplastic restrictions are forcing elimination of synthetic microbead carriers in exfoliating formulations. Camellia seed powder and jojoba ester blends replace polyethylene spheres in facial scrubs. South Korean MFDS pre-market safety assessments now require biodegradability documentation, accelerating reformulation investments ahead of 2027 enforcement deadlines.
Subscription-based replenishment models are displacing traditional retail discovery for core skincare protocols. Direct-to-consumer brands capture recurring revenue through personalized serum regimens featuring camellia-based moisturizers. Seoul's metropolitan beauty cluster demonstrates this shift most visibly, where K-beauty platforms integrate AI skin analysis with auto-ship camellia oil formulations.
Camellia Skincare and Cosmetics Market Segmentation
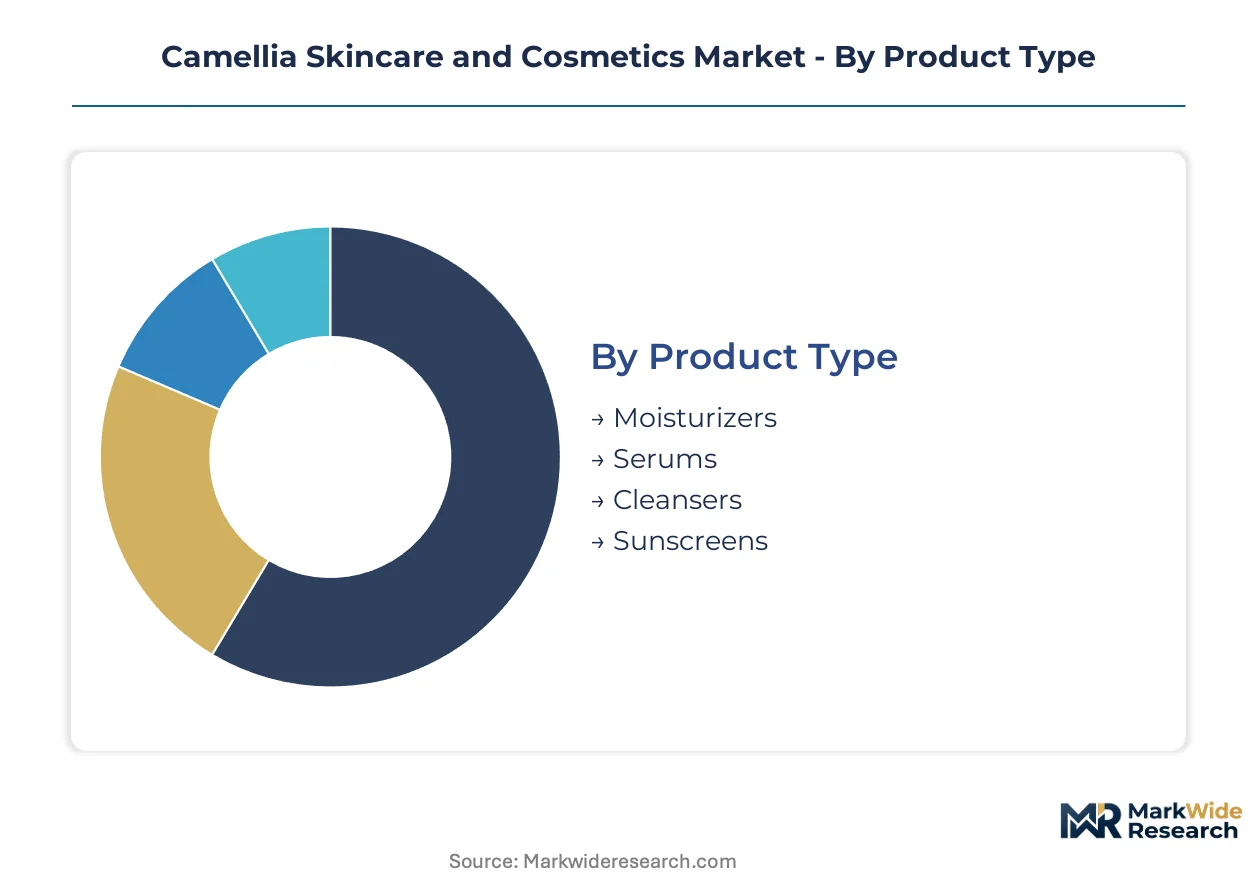
Segmentation in camellia skincare reflects divergent regulatory compliance burdens and extraction technology thresholds. Brands configure product lines around certification tiers that determine market access in Japan, South Korea, and the EU.
Product Type:
Japan's Quasi-Drug substantiation mandates under the Ministry of Health, Labour and Welfare create divergent development timelines across topical formats.
- Moisturizers:Daily-use occlusive formulations leverage cold-pressed camellia oleifera oil with triterpene saponin concentrations preserved above 80%. Aging demographics in Seoul's metropolitan beauty cluster drive premium pricing elasticity for facial creams with Jeju Island-sourced extracts.
- Serums:High-density active delivery systems differentiate through cultivar sourcing—camellia japonica versus oleifera—with brands marketing measurable bioactive potency. South Korean MFDS cosmetic safety assessments for heavy metal screening professionalize serum-grade agricultural inputs.
- Cleansers:Oil-based and emulsion formats use camellia seed derivatives for lipid-compatible makeup removal.
- Sunscreens:Botanical carriers replace synthetic emollients under EU REACH microplastic restrictions.
Moisturizers handle the majority of throughput; serums are expanding most quickly on share.
End User:
Procurement patterns split between direct consumer acquisition and institutional volume contracts with divergent quality specifications.
- Individual Consumers:Subscription-based replenishment models displace traditional retail discovery, with Seoul's K-beauty platforms integrating AI skin analysis for personalized camellia oil regimens.
- Salons:Professional treatment menus specify supercritical CO2-extracted grades for guaranteed saponin retention in facial protocols.
- Spas:Premium wellness chains expand camellia oil-based service offerings, sourcing through consolidated supplier relationships with traceable cultivation networks.
- Retailers:Sephora's dedicated male skincare sections normalize facial oil protocols beyond traditional demographics, creating white space for camellia's oxidative stability credentials.
Individual consumers drive absolute volume; spas gain share fastest through service premiumization.
Formulation:
Margin spreads widen dramatically across certification tiers, with organic audits freezing working capital for 18-24 month supplier verification cycles.
- Natural:Cold-pressed extraction without synthetic additives dominates volume production, though brands face compressed margins from artisanal producers lacking CO2 equipment.
- Organic:Soil Association and COSMOS certifications command the widest margin spread across distribution channels, with Pai Skin Care anchoring European presence through certified formulations.
- Chemical-Based:Synthetic carrier systems face EU REACH framework constraints and ECHA microplastic restrictions, forcing reformulation investments.
- Vegan:Plant-only protocols exclude animal-derived emulsifiers, aligning with clean beauty rotation toward clinical-grade natural formulations.
Natural formulations handle the majority of throughput; organic certification climbs the fastest on margin contribution.
Distribution Channel:
Channel selection determines working capital intensity and regulatory documentation burdens for botanical origin claims.
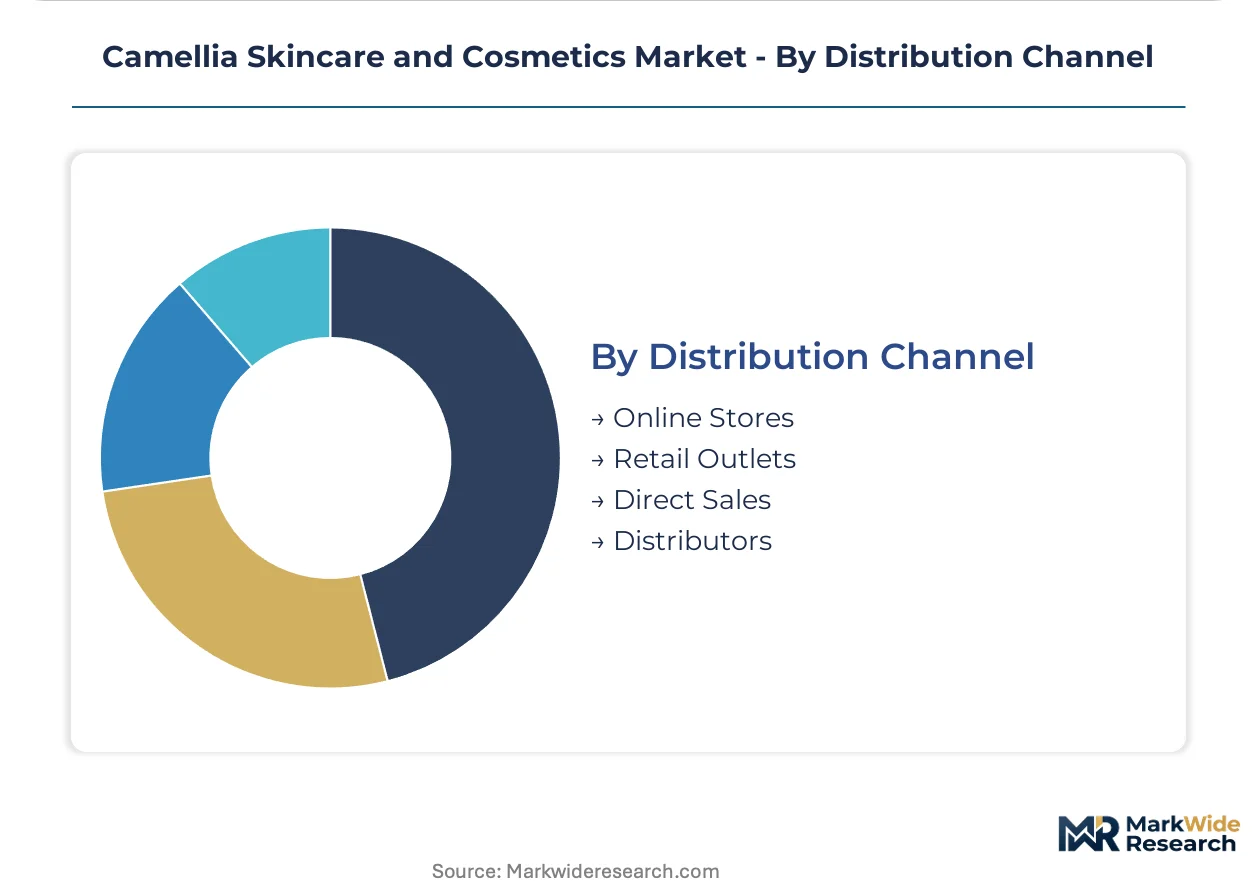
- Online Stores:Direct-to-consumer brands capture recurring revenue through auto-ship camellia oil formulations, with AI-driven personalization reducing customer acquisition costs.
- Retail Outlets:Physical discovery remains critical for prestige positioning, though clean beauty certification requirements compress formulation timelines for shelf placement.
- Direct Sales:Consultant networks emphasize education-heavy protocols for facial oil application, building loyalty in underpenetrated Nordic markets.
- Distributors:Bulk procurement for spa and salon channels concentrates around three Japanese and South Korean processors controlling over 60% of global refining capacity.
Online stores handle the majority of throughput; direct sales channels show the steepest expansion trajectory in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Busan anchors Northeast Asia's camellia oil distribution network, connecting Jeju Island cultivators to Seoul's metropolitan beauty cluster and onward to Japanese and Chinese processing facilities.
Japan
Tokyo's premium spa chains drive demand for Quasi-Drug certified camellia formulations. The Ministry of Health, Labour and Welfare enforces clinical substantiation requirements for anti-aging botanical claims. Kansai's Osaka-Kobe corridor hosts concentrated refining capacity for supercritical CO2 extraction.
South Korea
Seoul's AI-integrated beauty platforms normalize subscription-based camellia oil replenishment. The MFDS mandates heavy metal screening for Jeju-sourced agricultural inputs. The Seoul Capital Area concentrates K-beauty brand headquarters formulating with island-derived extracts.
United States
Clean beauty rotation pulls prestige buyers toward clinical-grade natural formulations. The FDA oversees cosmetic safety while California's Proposition 65 drives ingredient disclosure beyond federal minimums. Sephora's dedicated male skincare sections in Los Angeles and New York Metro expand facial oil demographics.
France
Paris-based luxury houses anchor European demand for high-margin organic camellia serums. ANSM enforces strict botanical claim substantiation under EU cosmetics regulation. The Île-de-France region concentrates formulation R&D laboratories serving premium export markets.
Sweden
Cold-climate skincare routines in Stockholm remain underpenetrated by botanical occlusives. The EU REACH framework and ECHA microplastic restrictions indirectly advantage pure plant-oil delivery systems. Nordic direct sales networks emphasize education-heavy protocols for facial oil adoption.
Camellia Skincare and Cosmetics Market Competitive Environment
Concentration sits with vertically integrated specialists and premium-positioned clean beauty brands. The competitive structure splits between technology-capable processors controlling refining capacity and formulation-focused brands building direct consumer relationships. Three strategic archetypes dominate: cultivator-integrated oil suppliers, clinical-grade natural formulators, and subscription-native digital brands. Capacity consolidation and certification-driven supplier consolidation represent the dominant competitive moves.
Among California-based clean beauty specialists, Vintners Daughter and True Botanicals exemplify the premium-tier archetype through small-batch processing claims and vertically controlled supply chains. Pai Skin Care anchors the European organic certification vector with Soil Association-accredited formulations. These three occupy positions that bridge cultivation transparency and clinical credibility.
| Leading Market Players |
|---|
| Vintners Daughter |
| True Botanicals |
| Pai Skin Care |
| French Farmacie |
| Juice Beauty |
| Dr. Alkaitis |
| Osima Organics |
| Nüssa Cosmetics |
| Laurel |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-twenty-four month Soil Association and COSMOS certification cycles freeze working capital for brands sourcing Jeju Island camellia extracts, compressing margin predictability for mid-tier formulators while concentrating pricing power with vertically integrated processors holding supercritical CO2 extraction capacity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Quasi-Drug certified serums from natural-formulation moisturizers and unbranded bulk camellia oleifera oil. Price differentiation rests on certification grade and cultivar provenance, with Jeju-sourced japonica extracts commanding widest margin spreads. Cost compression in mid-tier natural formulations is intensifying because artisanal producers lack capital-intensive CO2 equipment. Individual consumers through subscription channels show lowest price sensitivity; bulk distributors for salon procurement exhibit highest.
Supply Chain Analysis
China's Hunan and Jiangxi provinces anchor raw camellia oleifera seed cultivation, while Japan and South Korea concentrate over sixty percent of global refining capacity for cosmetic-grade oil extraction. Downstream formulation draws from cold-pressed seed stock, supercritical CO2 processing equipment, and Soil Association-certified organic certification infrastructure. Single-source vulnerability sits with three Japanese and South Korean processors during peak harvest-to-production cycles. Distribution runs through Seoul's metropolitan beauty cluster for K-beauty brand formulation, with Busan port handling Jeju Island agricultural consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Camellia skincare market fragmentation creates entry niches as clean beauty certification requirements compress formulation timelines and force supplier consolidation around traceable cultivation networks.
For Market Incumbents: Compound defensive positioning through exclusive cultivar rights agreements with Japanese agricultural cooperatives and captive supercritical CO2 processing capacity additions in Osaka-Kobe corridor. Threat from emerging subscription-native digital brands with AI-driven personalization demands accelerated direct-to-consumer channel control and Soil Association certification investment to lock shelf placement. For New Entrants and Emerging Players: Differentiate on clinical-grade natural formulations targeting underpenetrated Nordic markets, specifically Sweden and Finland cold-climate skincare routines currently dominated by petroleum-derived occlusives. White space sits with men's grooming channel expansion through Sephora's dedicated male skincare sections. Go-to-market angle: education-heavy direct sales protocols emphasizing oxidative stability credentials for facial oil adoption. For Investors and Strategic Acquirers: Long-term, this sits as a vertical integration play because certification-driven supplier consolidation and extraction technology thresholds favor backward-integrated cultivator-processors over pure-formulation brands. Acquisition target archetype: mid-cap specialists with Jeju Island sourcing relationships and existing Soil Association or COSMOS organic audits. Signal to watch: EU Green Deal biodegradability mandate enforcement accelerating green chemistry extraction adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Secures Jeju Island camellia japonica varietal rights against Japanese cooperative disputes. |
| Supercritical CO2 Capacity Expansion | Guarantees triterpene saponin retention above eighty percent for Quasi-Drug substantiation. |
| Soil Association Certification Investment | Unlocks premium margin spreads across European distribution channels and retail placement. |
| Direct-to-Consumer Subscription Launch | Captures recurring revenue through AI-integrated personalization in Seoul's beauty cluster. |
| Men's Grooming Channel Entry | Normalizes camellia facial oil protocols beyond traditional female demographics via Sephora. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and certification body disclosures through structured interviews with cosmetic brand managers, Jeju Island agricultural cooperative representatives, South Korean MFDS regulatory affairs leads, supercritical CO2 equipment suppliers, and European Soil Association certification auditors. Secondary validation sources include Japan Ministry of Health, Labour and Welfare Quasi-Drug registration databases, EU ECHA REACH restriction documentation, and Seoul metropolitan beauty cluster platform analytics. Bottom-up demand modeling triangulates against top-down value chain analysis across extraction, formulation, and distribution tiers.
Segmentation dimensions modeled span product type, end user, formulation certification tier, and distribution channel across the projection horizon. Analytical framework incorporates Jeju Island agricultural input quality grading, supercritical CO2 extraction yield differentials, and regional regulatory compliance burden indices. CAGRs derive from volume-throughput assumptions tied to subscription channel penetration rates and spa service menu expansion trajectories.
Material uncertainties — harvest yield volatility in China's Hunan province, EU Green Deal solvent restriction timing, and Quasi-Drug claim substantiation standard revisions — sit outside the modeled envelope. Forecasts reflect assumptions regarding certification audit cycle durations and K-beauty platform AI integration adoption curves. Recalibration cycles align with material shifts in Japan's Ministry of Health, Labour and Welfare regulatory guidance and EU biodegradability mandate enforcement schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Natural Baby Skin Care Products Market
Cosmetics & Skincare
Reusable Makeup Remover Pad Market
Cosmetics & Skincare
Magnetic Fake Eyelashes Market
Cosmetics & Skincare
Silicone Makeup Sponge Market
Cosmetics & Skincare
Anti-Pollution Skin Care Products Market
Cosmetics & Skincare
Botanical Skin Care Ingredients Market
Cosmetics & Skincare
Tea Based Face Masks Market
Cosmetics & Skincare
Sun Care Products Market
Cosmetics & Skincare
Liquid Makeup Market
Cosmetics & Skincare
Eye Cream Market
Cosmetics & Skincare
North America Deodorants Market
Cosmetics & Skincare
Makeup Remover Pen Market
Cosmetics & Skincare
Body Blurring Cosmetics Market
Cosmetics & Skincare
Beauty Facial Mask Market
Cosmetics & Skincare
Cosmetic Pencil and Pen Market
Cosmetics & Skincare
Italy Lip Care Products Market