
 Barcode Label Market | 2026-2036
Barcode Label Market Size, Share, and Industry Trends Forecast 2026-2036
Barcode Label Market Outlook
Multi-source procurement is expanding across the barcode label supply chain as end-users diversify away from single-vendor dependencies. Zebra Technologies Corporation anchors North American hardware-integrated label ecosystems through its printer and media bundling strategy. Avery Dennison Corporation sustains global material science leadership with proprietary adhesive formulations and film substrates. SATO Holdings Corporation dominates precision label manufacturing for automotive and pharmaceutical track-and-trace applications in Asia.
A barcode label is a machine-readable printed substrate combining symbology patterns with adhesive backing, typically manufactured through thermal transfer or direct thermal processes at resolutions between 203 and 600 dots per inch for automated data capture. Its primary commercial purpose is to encode product identity, lot numbers, and logistics data for scanning at retail points, warehouse gates, and shipping docks. Thermal transfer labels command premium positioning in asset-tagging and cold-chain logistics where permanence and chemical resistance justify higher unit costs. Direct thermal labels occupy high-volume, short-lifecycle applications such as shipping receipts and patient wristbands where imaging fades acceptably within weeks. Pressure-sensitive adhesives represent the fastest-growing adhesive category as peel-and-stick application speed becomes critical in automated fulfillment lines.
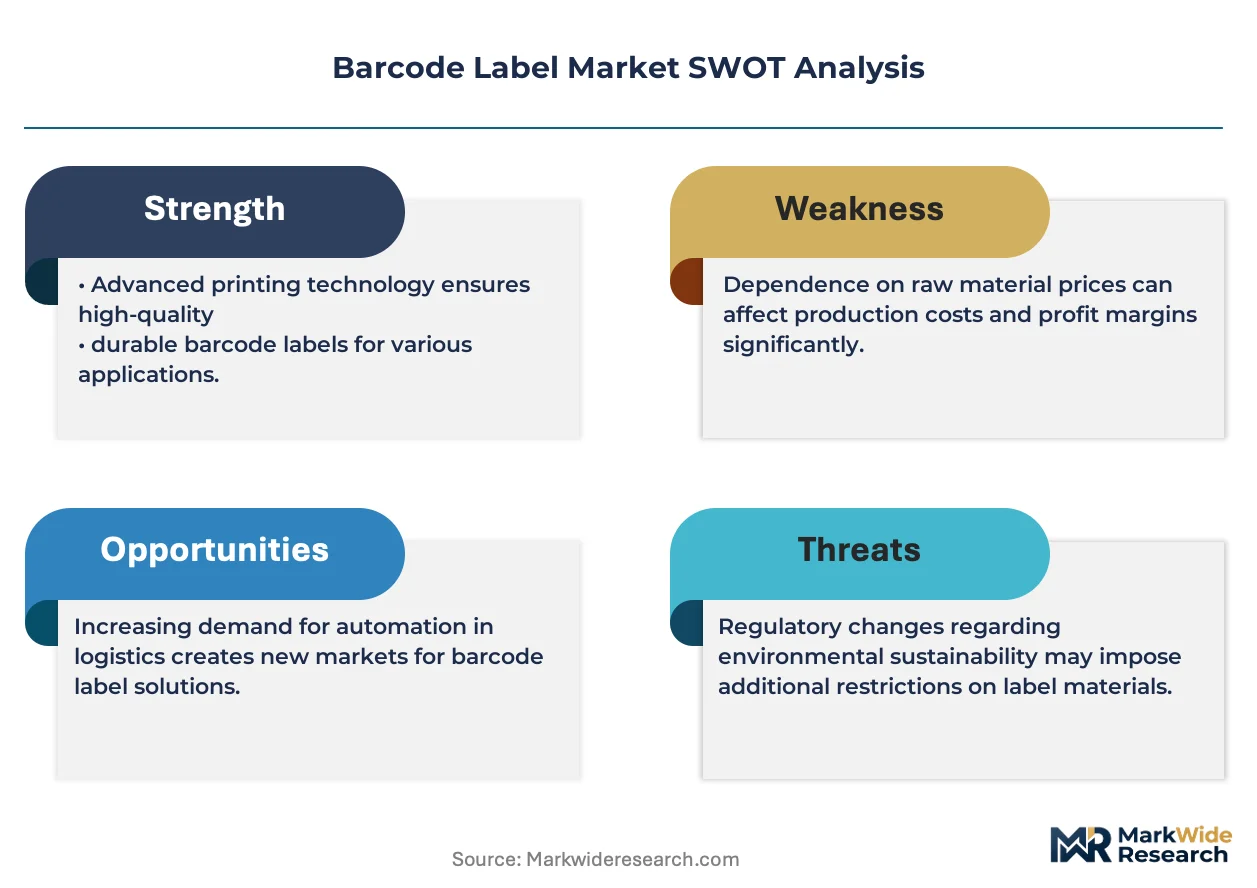
FDA track-and-trace mandates for pharmaceuticals and FDA food safety modernization requirements are elevating label durability and data-integrity standards in regulated supply chains. EPA and OSHA frameworks govern volatile organic compound emissions from adhesive solvents and worker exposure limits in label converting facilities. ECHA REACH compliance in Europe restricts certain phthalate plasticizers and heavy metal pigments, forcing reformulation of legacy vinyl and polyester face stocks. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and qualify new material platforms ahead of compliance deadlines.
Market Dynamics
E-commerce fulfillment velocity demands are compressing label procurement cycles from quarterly to weekly replenishment, forcing converters to hold regional inventory buffers and adopt digital print-on-demand workflows.
Growth Catalysts
- FDA track-and-trace mandates:Pharmaceutical serialization requirements in the United States mandate durable two-dimensional barcodes on unit-level packaging, expanding thermal transfer label specifications.
- EU Green Deal chemical restrictions:REACH compliance deadlines are accelerating reformulation of solvent-based adhesives toward bio-based alternatives in European converting operations.
- Warehouse automation density:Automated storage and retrieval systems in Germany and China require machine-readable labels with enhanced scan reliability at high conveyor speeds.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and silicone release liner prices fluctuate with crude oil indices, squeezing converter margins on long-term customer contracts.
- Adhesive supply concentration:Specialty hot-melt formulations depend on a limited supplier base in the Rhine-Ruhr industrial cluster, creating single-source vulnerability.
- Direct thermal fade limitation:Image degradation under heat and light restricts use in outdoor asset tracking and archival applications, capping addressable market scope.
Strategic Opportunities
- Indian pharmaceutical export labeling:CDSCO alignment with international serialization standards creates demand for high-durability labels in Mumbai and Hyderabad manufacturing corridors.
- RFID-barcode hybrid integration:Convergence of printed electronics with traditional thermal transfer substrates enables dual-technology tracking in luxury goods and electronics.
- California SB 54 extended producer responsibility:Plastic packaging mandates incentivize recyclable linerless label formats in West Coast food and beverage distribution.
Industry Challenges
- Color management specialist scarcity:Digital inkjet label production requires operators trained in ICC profiling and variable-data workflows, creating hiring bottlenecks in Midwest converting hubs.
- Multi-jurisdiction compliance synchronization:Divergent FDA, EMA, and NMPA label content requirements force SKU proliferation and inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barcode Label Market |
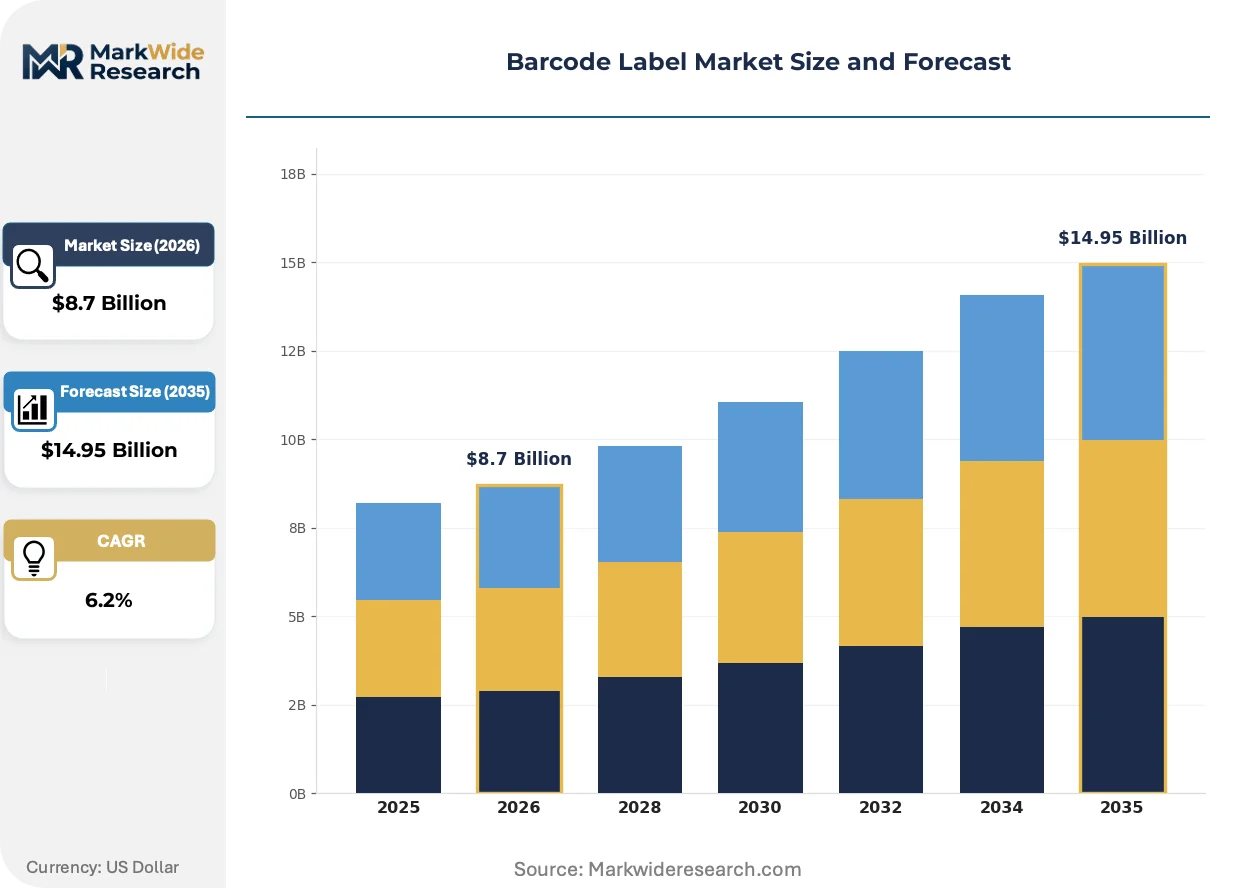
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.95 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Label Type: Avery, Direct Thermal, Thermal Transfer, Waterproof Adhesive Type: Permanent, Removable, Repositionable, Pressure Sensitive Application: Retail, Manufacturing, Shipping, Inventory Management Material: Paper, Plastic, Polyester, Vinyl |
| Companies Covered | Zebra Technologies Corporation, Avery Dennison Corporation, Honeywell International Inc., SATO Holdings Corporation, Toshiba TEC Corporation, TSC Auto ID Technology Co. Ltd., Seiko Epson Corporation, Canon Inc., Printronix Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barcode Label Market Strategic Shifts
Digital print technologies and sustainable material platforms are converging to redefine converter economics and brand-owner specifications across high-mix, short-run label production environments.
Water-based inkjet printing systems for label webs is modularizing converter capital deployment, allowing mid-tier players in Ohio and Ontario to enter pharmaceutical and nutraceutical segments without rotary press investments. Brand owners in organic food and craft beverage verticals are adopting these systems for versioned packaging with two-week lead times. The technology is modularizing the traditional economies-of-scale barrier that concentrated premium label supply among large-format rotogravure operators.
ECHA REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are compelling face-stock suppliers to eliminate fluorinated coatings used for grease resistance in food contact labels. Industrial consequence includes accelerated qualification of plasma-treated polyethylene alternatives and silicone-free release liners. The chilled and frozen food segment across France, Italy, and Poland is most affected, with reformulation timelines compressed to avoid stranded inventory ahead of enforcement windows.
Consolidated buying desks at third-party logistics providers are compressing supplier qualification cycles and unbundling hardware-software-media bundles that historically locked in label specifications. Regional distributors in Texas and Georgia are gaining share by offering vendor-agnostic substrate portfolios with same-day shipping. This pattern is most visible in parcel and less-than-truckload shipping verticals where carrier-agnostic scan compliance has replaced proprietary Zebra or Honeywell ecosystem requirements.
Barcode Label Market Segmentation
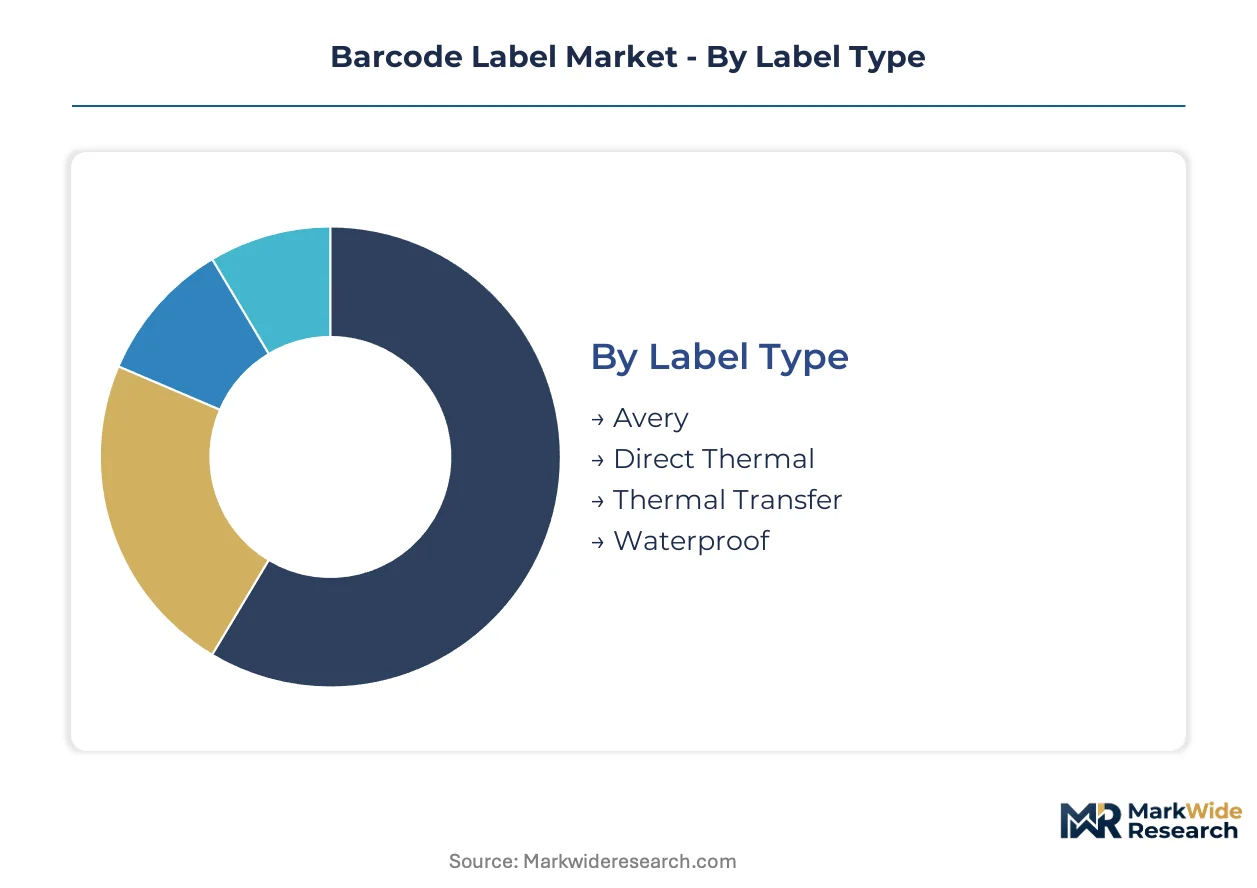
Barcode label procurement decisions cascade through multiple technical dimensions that determine print compatibility, environmental durability, and regulatory compliance. Converters and end-users must align specifications across material substrates, imaging chemistries, and adhesive platforms to avoid scanning failures in automated handling systems.
Label Type:
Capital intensity varies sharply across imaging platforms, with thermal transfer requiring ribbon inventory and precision printhead investments while direct thermal minimizes consumable complexity.
- Avery:Pre-die-cut label formats with standardized dimensions streamline deployment in desktop printer fleets. Demand concentrates in small-to-medium retail operations across Germany and the United States where SKU variety outstrips custom converting economics.
- Direct Thermal:Heat-activated imaging layers eliminate ribbon costs and simplify operator training. E-commerce fulfillment centers in China deploy these labels for outbound parcel tracking where image permanence requirements span days rather than years.
- Thermal Transfer:Wax-resin or full-resin ribbon systems deposit durable codes resistant to solvents and abrasion. Pharmaceutical manufacturers in India specify these labels for cold-chain vial tracking under CDSCO serialization mandates.
- Waterproof:Synthetic face stocks with specialized topcoats withstand submersion and humidity exposure. Marine logistics operators and outdoor asset managers in coastal United States markets specify these for container and equipment tagging.
Most installed capacity flows through Direct Thermal. Expansion is steepest in Thermal Transfer.
Adhesive Type:
Application speed and surface compatibility drive adhesive selection, with permanent formulations dominating high-throughput automated lines.
- Permanent:Aggressive acrylic or rubber-based chemistries form irreversible bonds with corrugated, plastic, and metal substrates. Warehouse automation in Germany relies on permanent adhesives for pallet and tote identification that must survive multi-year facility lifecycles.
- Removable:Controlled-tack formulations enable clean removal from glass, electronics housings, and painted surfaces without residue. Consumer electronics manufacturers in China specify removable labels for device packaging and warranty activation stickers.
- Repositionable:Low initial tack allows alignment correction during manual application. Retail signage and promotional labeling in France utilize these adhesives for temporary shelf-edge and window displays.
- Pressure Sensitive:Instant bond formation without heat or moisture activation accelerates automated dispensing. Amazon fulfillment centers and DHL hubs across the United States specify pressure-sensitive constructions for print-and-apply systems operating at 40+ packages per minute.
Permanent adhesives anchor the installed base. Pressure Sensitive formulations are gaining share fastest in automated environments.
Application:
End-use requirements dictate durability specifications, with regulated pharmaceutical and food segments imposing the most stringent material qualifications.
- Retail:Point-of-sale scanning demands crisp edge definition and contrast ratios for laser scanner compatibility. Grocery chains in the United States specify these labels for produce and packaged goods price lookup.
- Manufacturing:Work-in-process tracking requires resistance to cutting fluids, dust, and mechanical abrasion. Automotive suppliers in Germany apply durable polyester labels to engine components and subassemblies for full lifecycle traceability.
- Shipping:Carrier-compliant formats with routing barcodes and human-readable zone indicators. FedEx and UPS volume in North America drives specification for 4x6 inch thermal labels with zone and service level encoding.
- Inventory Management:Location and lot-level identification for warehouse slotting and cycle counting. Third-party logistics providers in China deploy these labels for bonded warehouse operations under customs supervision requirements.
Shipping applications command the largest label volumes. Manufacturing specifications are climbing fastest as serialization mandates expand.
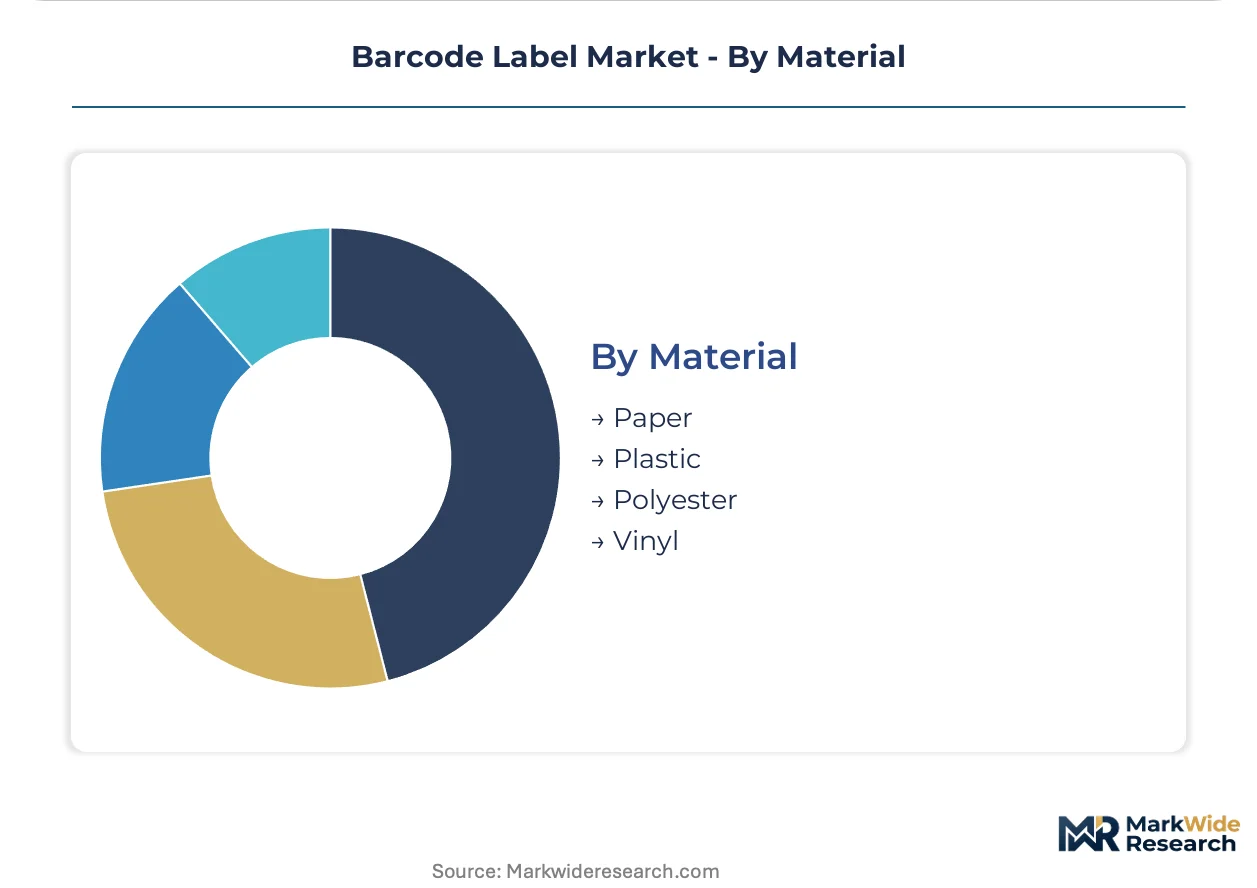
Material:
Substrate selection balances cost, durability, and regulatory compliance, with paper dominating disposable applications and synthetics penetrating asset-tracking use cases.
- Paper:Uncoated or topcoated facestocks provide economical printing surfaces for short-lifecycle applications. Direct thermal paper labels serve pharmacy prescription vials and food service date coding across India and the United States.
- Plastic:Polypropylene and polyethylene films offer tear resistance and moisture protection at moderate cost premiums. Beverage bottlers in Italy specify plastic labels for refrigerated distribution where condensation degrades paper alternatives.
- Polyester:High tensile strength and dimensional stability under temperature extremes. Electronics manufacturers in China apply polyester labels to circuit boards and components for RoHS-compliant identification.
- Vinyl:Conformable films that adhere to curved surfaces and withstand outdoor exposure. Utility infrastructure and fleet vehicle marking in the United States utilizes vinyl for pole tags and DOT compliance labeling.
Paper substrates carry the majority of installed volume. Polyester is expanding most quickly in electronics and industrial asset applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between jurisdictions is creating cost-of-compliance arbitrage, pushing label converting capacity toward regions with streamlined chemical registration pathways while demand concentrates in markets with dense logistics infrastructure.
United States
Third-party logistics providers and e-commerce fulfillment networks drive label consumption across Texas and Georgia distribution corridors. FDA track-and-trace mandates for pharmaceuticals elevate durability specifications for cold-chain applications. The Midwest converting hub around Ohio faces hiring bottlenecks for digital inkjet color management specialists.
Germany
Automotive suppliers and warehouse automation deployers anchor demand for high-reliability thermal transfer labels in Bavaria and Baden-Württemberg. ECHA REACH Annex XVII restrictions on fluorinated coatings force reformulation of food-contact labels ahead of enforcement windows. The Rhine-Ruhr industrial cluster concentrates specialty hot-melt adhesive production, creating single-source vulnerability.
China
E-commerce fulfillment centers and consumer electronics manufacturers consume direct thermal labels at massive scale in Yangtze River Delta and Pearl River Delta regions. NMPA serialization requirements for pharmaceuticals expand thermal transfer specifications in Mumbai and Hyderabad manufacturing corridors. Shenzhen and Shanghai host dense printer hardware and media bundling ecosystems.
India
Pharmaceutical export labeling demand surges as CDSCO aligns with international serialization standards in Mumbai and Hyderabad manufacturing corridors. FSSAI food safety modernization elevates label durability requirements for domestic distribution. Regional distributors gain share by offering vendor-agnostic substrate portfolios with shortened lead times.
Japan
Precision manufacturing and automotive track-and-trace applications sustain demand for high-resolution thermal transfer labels in Aichi Prefecture and Kanto region. METI industrial standards govern chemical emissions from adhesive solvents in converting facilities. Tokyo-based logistics providers compress procurement cycles toward weekly replenishment rhythms.
Barcode Label Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue digital print-on-demand workflows and sustainable material platforms. The vendor base organizes around three strategic archetypes: hardware-integrated ecosystem builders, material science specialists with proprietary adhesive formulations, and regional converters offering vendor-agnostic substrate portfolios. Consolidation pressure operates through strategic partnerships between printer manufacturers and media suppliers, while capacity expansion concentrates in Asian converting hubs.
Within the hardware-integrated tier, Zebra Technologies Corporation and Honeywell International Inc. exemplify ecosystem bundling strategies that historically locked in label specifications. Avery Dennison Corporation occupies a position representing material science leadership through proprietary adhesive and film substrate capabilities. SATO Holdings Corporation anchors the precision manufacturing archetype for regulated track-and-trace applications. TSC Auto ID Technology Co. Ltd. sits within the emerging tier of Asia-based specialists challenging incumbent hardware-media bundles.
| Leading Market Players |
|---|
| Zebra Technologies Corporation |
| Avery Dennison Corporation |
| Honeywell International Inc. |
| SATO Holdings Corporation |
| Toshiba TEC Corporation |
| TSC Auto ID Technology Co. Ltd. |
| Seiko Epson Corporation |
| Canon Inc. |
| Printronix Inc. |
| Others |
Value Chain & Pricing Dynamics
Performance-grade bifurcation between thermal transfer durability specifications and direct thermal commodity volumes manifests in divergent margin structures and sourcing footprints across the barcode label supply chain. Premium thermal transfer formulations command resin ribbon inventories and precision coating assets in Germany and Japan, while high-velocity direct thermal procurement in China compresses converter margins through weekly replenishment cycles and regional buffer requirements.
Pricing Analysis
Distributor margin layering in North American label markets typically captures 15-25 point spreads between converter gate pricing and end-user landed costs. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FDA-validated pharmaceutical labels commanding substantial premiums over uncertified shipping formats. Cost compression in direct thermal grades is intensifying because e-commerce fulfillment centers negotiate volume-based rebates that erode legacy price schedules. Third-party logistics providers exhibit highest price sensitivity due to unbundled hardware-software-media procurement, while pharmaceutical manufacturers prioritize scan reliability over unit cost.
Supply Chain Analysis
Silicone release liner supply rests on petrochemical feedstock producers in the United States, Germany, and South Korea, with polypropylene face stock drawing from polymer resin complexes in China and the Middle East. Specialty hot-melt adhesive formulations hinge on concentrated production in the Rhine-Ruhr industrial cluster, creating single-source vulnerability for European converters. Tariff exposure on Chinese-sourced thermal paper substrates threatens cost stability for North American direct thermal label assemblers. Distribution runs through regional converter networks with same-day shipping capabilities in Texas, Georgia, and Ontario fulfillment corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The barcode label market functions as a regulatory compounder where FDA pharmaceutical serialization mandates and ECHA REACH chemical restrictions continuously elevate compliance-driven replacement demand.
For Market Incumbents: Anchor ecosystem lock-in through hardware-media bundling investments that resist unbundling pressure from third-party logistics buying desks. Defensive consolidation moves include acquiring regional converters in Texas and Georgia to secure same-day distribution reach, and qualifying bio-based adhesive platforms ahead of EU Green Deal enforcement windows. Threat substitution from RFID-barcode hybrid technologies demands accelerated R&D in printed electronics integration. For New Entrants and Emerging Players: Launch via vendor-agnostic substrate portfolios targeting carrier-agnostic scan compliance requirements in parcel and less-than-truckload shipping verticals. White-space targets include Indian pharmaceutical export corridors where CDSCO serialization alignment creates demand for high-durability thermal transfer specifications, and California SB 54 recyclable linerless formats for West Coast food distribution. Go-to-market angle emphasizes digital print-on-demand workflows with two-week lead times for organic food and craft beverage brand owners. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier converters lack capital to qualify sustainable material platforms ahead of regulatory deadlines. Long-term viability favors material science specialists with proprietary adhesive formulations and film substrate capabilities over pure-play hardware distributors. Acquisition target archetype includes regional converters with established pharmaceutical certification and same-day shipping infrastructure. Signal to watch is divergence between FDA, EMA, and NMPA label content requirements forcing SKU proliferation and inventory segmentation stress.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-based Adhesive Qualification | REACH Annex XVII compliance secures European food-contact label market access ahead of enforcement windows. |
| Digital Print-on-Demand Deployment | Modular inkjet systems enable mid-tier converters to enter pharmaceutical segments without rotary press investments. |
| RFID-Barcode Hybrid Integration | Dual-technology substrates capture luxury goods and electronics tracking demand from brand owners. |
| Regional Inventory Buffer Expansion | Weekly replenishment rhythms in e-commerce fulfillment require Texas and Georgia distribution node density. |
| Pharmaceutical Certification Investment | FDA track-and-trace mandate compliance opens cold-chain vial tracking specifications in regulated supply chains. |
Study Parameters
Coverage spans the United States, Germany, China, and India, with primary inputs from each market cluster obtained through converter operations directors, pharmaceutical packaging engineers, third-party logistics procurement leads, and adhesive formulation chemists. Secondary validation drew from FDA drug labeling guidance documents, ECHA REACH substance restriction databases, customs trade flow records, and SEC filings from publicly traded label converters. Bottom-up volume estimates triangulated against top-down market sizing from equipment installation bases and ribbon media consumption proxies.
Granularity-level modeling deployed separate forecast tracks for thermal transfer versus direct thermal imaging platforms, permanent versus pressure-sensitive adhesive chemistries, and paper versus synthetic face stock substrates across the projection horizon. Segment-level CAGRs derived from equipment replacement cycles, regulatory mandate implementation schedules, and e-commerce fulfillment center buildout pipelines. Industry-specific forecast inputs included pharmaceutical serialization compliance deadlines and warehouse automation density metrics in Germany and China.
Forecast precision tightens around the base case; tail outcomes carry wider variance under petrochemical feedstock volatility and adhesive supply concentration disruptions. Forecasts reflect assumptions regarding regulatory timeline adherence and substitution elasticity between imaging technologies. A small set of named triggers warrants ongoing watch: REACH enforcement acceleration, NMPA serialization expansion, and Amazon fulfillment network regionalization pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Pre-Gummed Labels Market
Labels
Direct Thermal Labels Market
Labels
Booklet Labels Market
Labels
Coated Wet Glue Label Market
Labels
ESD Protective Signage Labels Market
Labels
Global Metal Detectable Tags and Labels Market
Labels
Europe Self Adhesives Label Market
Labels
Wet Glue Labeling Machines Market
Labels
Label Applicator Market
Labels
Global Thermal Transfer Label Market
Labels
Global Tamper Evident Labels Market
Labels
Global Pressure Labels Market
Labels
In-Mold Labeling (IML) Market
Labels
Global in-Mold Labels Market
Labels
Inspection and Inventory Labels Market
Labels
BOPP Labels Market