
 Global in-Mold Labels Market | 2026-2036
Global in-Mold Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Global in-Mold Labels Market Foresight
REACH compliance is decoupling European converters from legacy multi-layer label stocks. Multi-Color Corporation leverages backward integration into pre-distortion software and cylinder engraving to sustain margin control across high-volume beverage programs. CCL Industries anchors its position through captive film extrusion assets in North America and Asia. Constantia Flexibles specializes in thin-gauge polypropylene structures that navigate EFSA food-contact thresholds while competing on total applied cost.
In-mold labels are pre-printed decorative films fused to plastic containers during the injection or blow molding cycle, typically constructed from polypropylene, polyethylene, or PET with thickness ranging from 40 to 80 microns and requiring precise thermal stability to withstand melt temperatures above 200°C without distortion or ink migration. Their primary purpose is to deliver permanent, scratch-resistant branding that eliminates post-mold labeling steps and enables complex contour adhesion impossible with pressure-sensitive alternatives. Polypropylene dominates material selection due to its compatibility with standard container resins and established recycling sortation protocols, while digital printing represents the fastest-expanding technology segment as brands demand shorter run lengths and versioning flexibility for regional marketing campaigns. Beverage packaging occupies the largest application share by volume, though pharmaceutical packaging commands superior unit margins driven by serialization mandates and tamper-evident requirements.
FDA food-contact regulations, EU REACH substance restrictions, and China's GB standards for plastic packaging collectively shape formulation choices, migration testing protocols, and market access documentation burdens for label suppliers operating across multiple jurisdictions. EMA and EFSA guidelines on indirect food additives further constrain adhesive and ink chemistries, particularly for dairy and infant nutrition containers where consumer safety scrutiny intensifies. Stakeholders must monitor regulatory divergence between recycling-friendly mono-material mandates and performance requirements for barrier labels, as the resolution of this tension will determine which material platforms and printing investments retain strategic value through the forecast horizon.
Market Dynamics
EU REACH substance restrictions are forcing converters to abandon multi-layer label constructions in favor of mono-material polypropylene solutions that simplify recycling compliance without sacrificing heat resistance during injection molding cycles.
Growth Catalysts
- EU Green Deal packaging mandates:Circular economy targets require mono-material compatibility, positioning polypropylene in-mold labels as the default choice for beverage brands seeking recyclability certification.
- Pharmaceutical serialization requirements:EMA guidelines on tamper-evident packaging push drug manufacturers toward permanent label fusion that eliminates delamination risks during distribution.
- Injection molding cluster concentration in Germany, China, and the United States:Proximity between label converters and container manufacturers reduces logistics costs and enables just-in-time production coordination.
Market Restraints
- Pre-distortion software and cylinder engraving capex:High-volume beverage programs require specialized pre-press infrastructure that locks out smaller converters lacking backward integration capabilities.
- Petroleum-based resin price volatility:Polypropylene feedstock costs fluctuate with crude oil markets, compressing margins for converters without captive film extrusion assets.
- Pressure-sensitive label substitution in short runs:Digital print-on-demand alternatives capture versioning flexibility for regional marketing campaigns below minimum efficient scale for in-mold production.
Strategic Opportunities
- India's FSSAI food-contact compliance pathway:Emerging domestic beverage and dairy brands seek permanent decoration solutions as packaging quality standards converge with global norms.
- Digital printing convergence with thermal stability engineering:Ink formulations that withstand 200°C melt temperatures enable versioning flexibility previously restricted to pressure-sensitive alternatives.
- Extended producer responsibility schemes:France's Citeo and Germany's DSD systems create financial incentives for mono-material label adoption through modulated packaging fees.
Industry Challenges
- Pre-press distortion compensation expertise:Container curvature variations demand specialized cylinder engraving skills that concentrate among legacy European and Japanese equipment operators.
- Migration testing documentation burdens:EFSA food-contact thresholds require extensive substance migration data for each ink-adhesive-substrate combination, extending certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global in-Mold Labels Market |
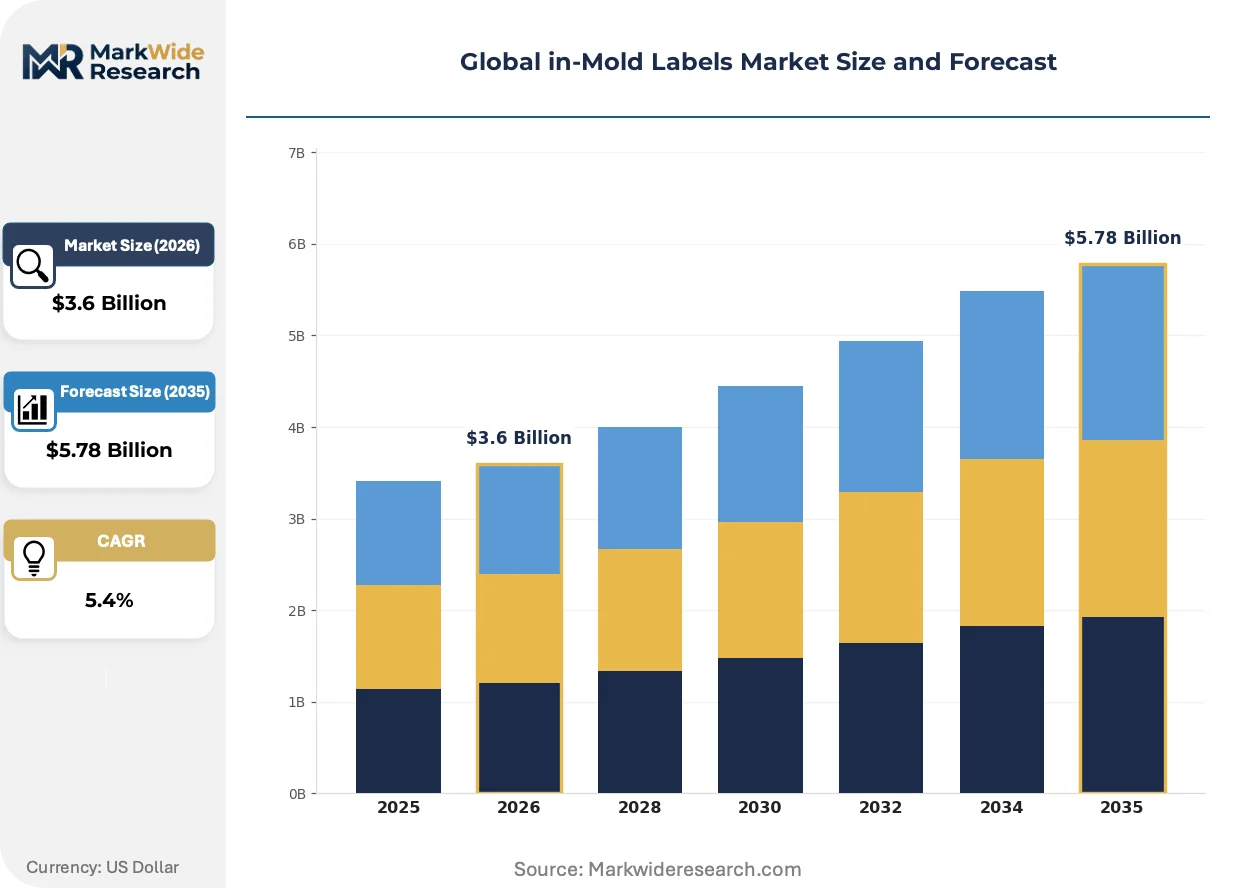
| Market Size in 2026 | $3.6 Billion |
| Market Size in 2035 | $5.78 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polypropylene, Polyethylene, PET, PVC, Polystyrene, Polycarbonate Application: Beverage Packaging, Personal Care Packaging, Food Containers, Pharmaceutical Packaging, Household Chemicals, Electronic Goods End User Industry: Consumer Goods Manufacturers, Packaging Companies, Printing Firms, Cosmetic Producers, Pharmaceutical Manufacturers, Electronics Producers Printing Technology: Flexography, Digital Printing, Offset Printing, Gravure Printing, Screen Printing, Letterpress |
| Companies Covered | Multi-Color Corporation, CCL Industries Inc., Huhtamaki Group, Constantia Flexibles GmbH, Coveris Holdings, Avery Dennison Corporation, Fuji Seal International Inc., Fort Dearborn Company, Inland Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global in-Mold Labels Market Shifts & Advancements
Digital printing architectures are disrupting traditional gravure-dominated production economics while regulatory pressure on recycling compatibility accelerates material platform consolidation toward polypropylene dominance.
Thin-gauge polypropylene structures are modularizing production workflows across high-volume beverage lines. These 40-60 micron films reduce material consumption per label while maintaining dimensional stability above 200°C melt temperatures. Premium cosmetic brands in France and Germany are adopting these structures fastest, compressing total applied cost gaps versus pressure-sensitive alternatives and enabling shorter run lengths without cylinder changeover penalties.
REACH substance restrictions are eliminating legacy adhesive chemistries from European supply chains. ECHA candidate list updates target phthalate plasticizers and certain epoxy-based curing agents common in multi-layer constructions. Dairy and infant nutrition packaging segments face the tightest compliance windows, with converters accelerating migration to polyolefin-based adhesive platforms that satisfy both EFSA food-contact thresholds and EU Green Deal recyclability mandates.
Brand procurement patterns are compressing supplier qualification cycles as multinational beverage and personal care companies consolidate vendor bases. Regional marketing teams demand versioning flexibility that previously required multiple regional converters, but digital printing investments by integrated suppliers now capture these requirements within single-source relationships. China and the United States exhibit this concentration most visibly, where injection molding clusters serve global accounts through coordinated label supply agreements.
Global in-Mold Labels Market Segmentation
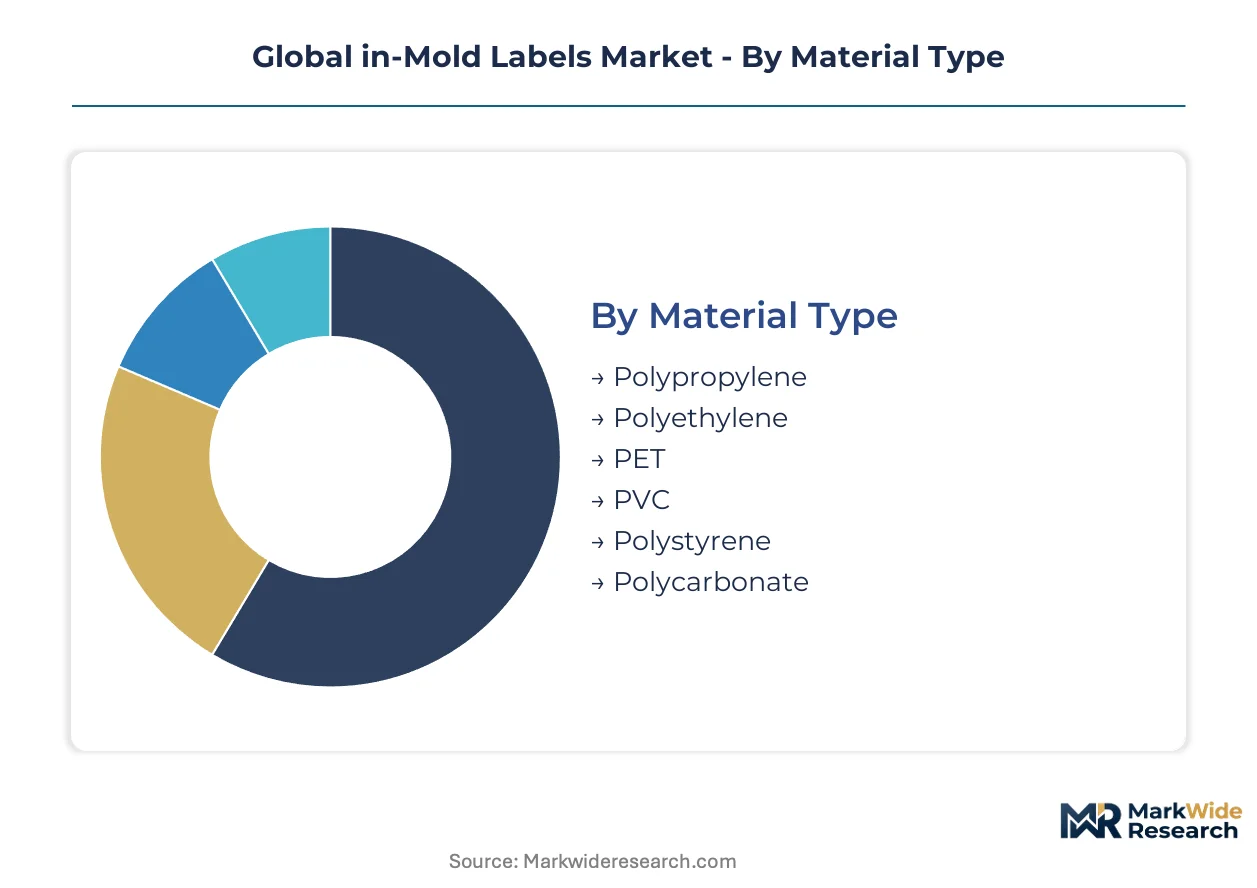
Segmentation in the in-mold labels market reveals how regulatory compliance burdens, material thermal requirements, and end-use performance specifications fragment supplier capabilities across distinct certification pathways. Each dimension carries unique approval hierarchies that determine market access and margin structures.
Material Type:
Polypropylene dominates certification pathways due to EFSA food-contact pre-approvals and REACH mono-material recyclability alignment, while alternative polymers navigate divergent regulatory thresholds.
- Polypropylene:Standard 40-80 micron films withstand injection molding temperatures above 200°C without dimensional distortion. Demand concentrates in German beverage packaging lines where EU Green Deal recyclability mandates favor mono-material compatibility.
- Polyethylene:Lower melt temperature tolerance restricts deployment to blow-molding applications, though FDA food-contact pathway documentation is more established versus newer substrate alternatives.
- PET:Crystal clarity suits premium cosmetic containers in France and Germany requiring visual shelf differentiation.
- PVC:REACH substance restrictions are phasing out legacy constructions across European dairy packaging.
- Polystyrene:Limited thermal stability confines usage to low-temperature household chemical applications.
- Polycarbonate:High-temperature resistance serves specialized pharmaceutical serialization programs requiring autoclave sterilization compatibility.
Leading the category by volume: Polypropylene. Growing fastest: PET.
Application:
Application segments diverge sharply on serialization mandates, barrier performance requirements, and regional regulatory enforcement intensity.
- Beverage Packaging:High-volume injection molding programs in China and the United States demand just-in-time label supply coordination with container manufacturers. EMA tamper-evident guidelines are pushing carbonated soft drink producers toward permanent fusion labels that eliminate delamination risks during cold-chain distribution.
- Pharmaceutical Packaging:Unit margins exceed other segments due to EMA serialization mandates and multi-layer tamper-evidence requirements. Swissmedic and FDA 21 CFR compliance documentation extends qualification cycles.
- Personal Care Packaging:Premium cosmetic brands in France adopt thin-gauge polypropylene for complex contour adhesion on ergonomic bottle designs.
- Food Containers:EFSA migration thresholds constrain ink-adhesive combinations for dairy and infant nutrition segments.
- Household Chemicals:Chemical resistance specifications favor polypropylene over polyethylene for bleach and solvent containers.
- Electronic Goods:Static-dissipative formulations serve semiconductor cleanroom packaging requirements in South Korea and Japan.
Volume leadership sits with beverage packaging. Steepest expansion trajectory: pharmaceutical packaging.
End User Industry:
End user categories separate by backward integration depth, with captive film extrusion assets determining procurement leverage.
- Consumer Goods Manufacturers:Multinational beverage and personal care brands consolidate vendor bases to capture versioning flexibility within single-source relationships.
- Packaging Companies:Injection molding clusters in Germany, China, and the United States coordinate just-in-time label supply through captive printing investments or long-term converter agreements.
- Printing Firms:Specialized pre-distortion software and cylinder engraving capabilities concentrate among legacy European and Japanese equipment operators.
- Cosmetic Producers:Premium French and German brands drive thin-gauge polypropylene adoption for total applied cost compression.
- Pharmaceutical Manufacturers:Serialization mandates require permanent label fusion with migration testing documentation for each ink-substrate combination.
- Electronics Producers:Cleanroom packaging specifications in South Korea and Japan demand static-controlled label formulations.
Procurement concentration: packaging companies. Fastest-growing demand source: pharmaceutical manufacturers.
Printing Technology:
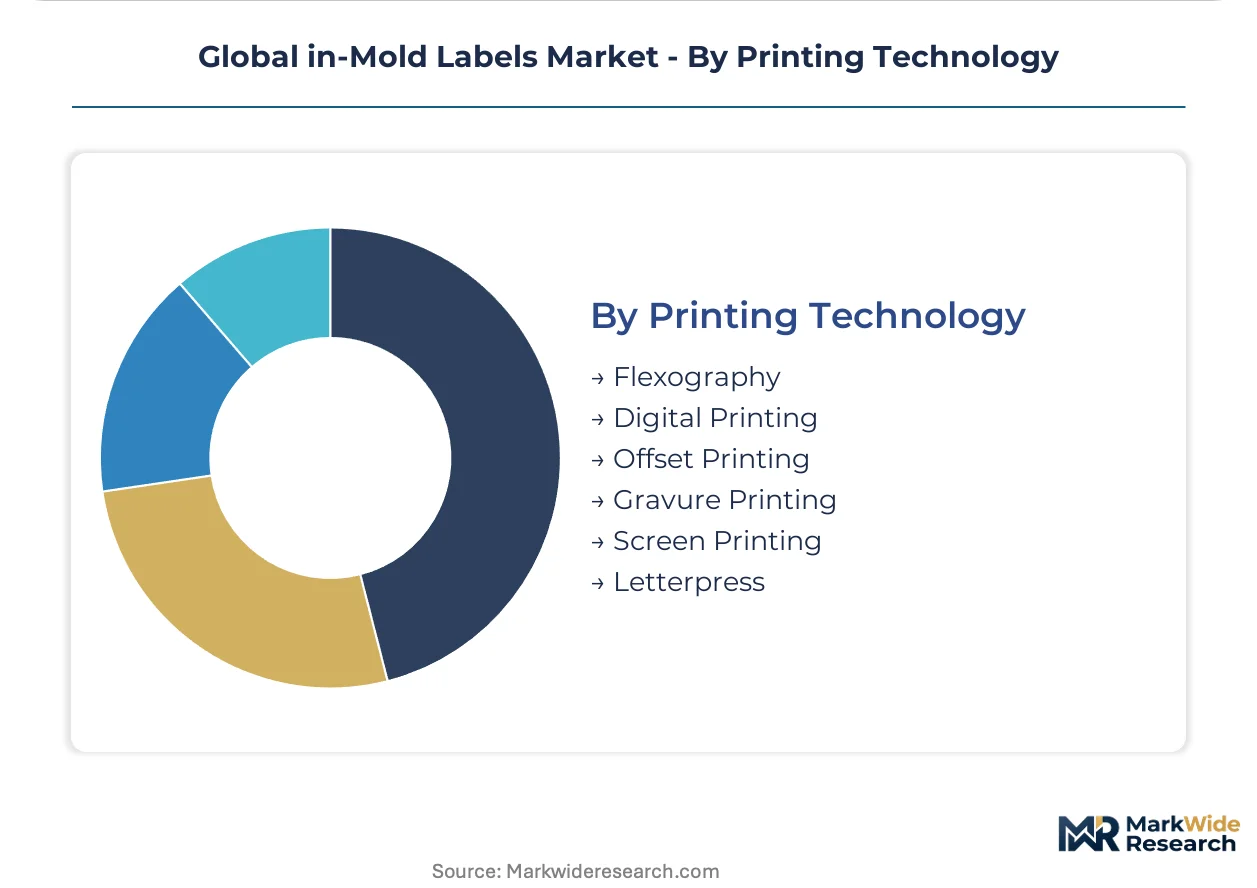
Technology selection hinges on run length economics, thermal stability engineering, and pre-press infrastructure amortization.
- Gravure Printing:Cylinder engraving investments lock in high-volume beverage programs with unit cost advantages at scale. Pre-distortion compensation expertise concentrates among European and Japanese equipment operators serving German and Chinese injection molding clusters.
- Digital Printing:Ink formulations that withstand 200°C melt temperatures are enabling versioning flexibility previously restricted to pressure-sensitive alternatives. Regional marketing teams at multinational brands now demand shorter run lengths without cylinder changeover penalties.
- Flexography:Mid-volume economics serve food container segments with moderate regulatory documentation burdens.
- Offset Printing:Limited thermal stability restricts deployment to low-temperature applications.
- Screen Printing:Thick ink deposits suit specialty cosmetic effects with limited run requirements.
- Letterpress:Legacy infrastructure persists in narrow-format pharmaceutical serialization applications.
Volume dominance: gravure printing. Technology climbing fastest: digital printing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate injection molding capacity serving multinational beverage brands. Germany's Ruhr industrial corridor hosts dense converter clusters. The United States' Great Lakes manufacturing belt anchors North American label demand.
China
Injection molding clusters in Guangdong and Zhejiang provinces process high-volume beverage container programs for domestic and export markets. GB standards for plastic packaging migration testing constrain ink-adhesive formulations entering food-contact applications. The Yangtze River Delta region coordinates just-in-time label supply between Shanghai-based converters and Suzhou container manufacturers.
Germany
EU Green Deal circular economy targets mandate mono-material polypropylene compatibility across beverage packaging lines. REACH substance restrictions phase out phthalate plasticizers from legacy adhesive chemistries. The Ruhr industrial corridor hosts specialized pre-distortion software operators serving injection molding clusters in North Rhine-Westphalia.
United States
FDA food-contact regulations shape formulation choices for dairy and infant nutrition container labels. The Great Lakes manufacturing belt concentrates blow-molding operations for household chemical packaging. Midwestern injection molding clusters coordinate with captive film extrusion assets to reduce petroleum-based resin price volatility exposure.
India
FSSAI food-contact compliance pathways attract investment as domestic beverage brands upgrade packaging quality standards. The PLI scheme for manufacturing incentivizes label converter capacity expansion near Mumbai and Pune. Maharashtra's industrial corridors develop just-in-time supply relationships with emerging dairy and personal care brands.
Japan
METI circular economy guidelines accelerate mono-material adoption in premium cosmetic packaging. JIS standards for plastic recycling sortation favor polypropylene label structures. The Kansai region around Osaka maintains specialized cylinder engraving expertise for complex contour adhesion applications.
Global in-Mold Labels Market Competitive Landscape
North American producers anchor one tier; European specialists hold advanced pre-press capabilities. The vendor base concentrates among integrated converters with captive film extrusion and backward integration into pre-distortion software. Three archetypes dominate: scale-driven beverage program operators, premium pharmaceutical serialization specialists, and thin-gauge cosmetic-focused innovators. Competitive moves center on digital printing technology licensing and strategic partnerships with injection molding clusters.
Among North American fabricators, Multi-Color Corporation and Fort Dearborn Company exemplify scale-driven archetypes serving high-volume beverage programs. CCL Industries Inc. occupies a position bridging North American and Asian production networks through integrated film extrusion assets. Constantia Flexibles GmbH represents the European specialist tier with concentration in thin-gauge polypropylene structures for premium applications.
| Leading Market Players |
|---|
| Multi-Color Corporation |
| CCL Industries Inc. |
| Huhtamaki Group |
| Constantia Flexibles GmbH |
| Coveris Holdings |
| Avery Dennison Corporation |
| Fuji Seal International Inc. |
| Fort Dearborn Company |
| Inland Packaging |
| Others |
Supply & Pricing Matrix
Cylinder engraving specialists in Germany and Japan command wage premiums that widen spreads between premium gravure-run labels and economy digital-print alternatives. Labor-cost differentials between these legacy skill centers and emerging converter hubs in India compress margins on standardized beverage programs while preserving pricing power for complex pharmaceutical serialization work.
Pricing Analysis
Lead-time premiums structure pricing tiers, with beverage brands paying substantial markups for sub-48-hour turnaround on rush orders versus standard 2-week cylinder engraving cycles. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with EFSA food-contact compliant labels commanding substantial premiums over industrial-grade alternatives. Pricing pressure stems from petroleum-based resin volatility, which squeezes converters lacking captive film extrusion. Small-batch cosmetic brands exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize compliance assurance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Japanese cylinder engraving equipment operators, whose specialized pre-distortion compensation expertise concentrates in the Kansai region. Raw material flows draw from Saudi Arabian polypropylene feedstock, German adhesive chemical precursors, and Chinese digital printing ink formulations. Tariff exposure on photopolymer plate imports from the European Union threatens North American digital converter margins. Distribution runs through just-in-time coordination between Ruhr Valley label converters and North Rhine-Westphalia injection molding clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over pre-distortion software and captive film extrusion determines margin capture across high-volume beverage programs.
For Market Incumbents: Lock in pre-distortion software capabilities through strategic hiring of legacy Japanese cylinder engraving specialists before retirement waves erode the talent pool. Deepen backward integration into polypropylene film extrusion to insulate margins from petroleum feedstock volatility threatening converters with merchant supply dependence. Pressure-sensitive label substitution in short-run versioning represents the most immediate displacement threat requiring digital printing counterinvestment. For New Entrants and Emerging Players: EU Green Deal circular economy mandates in Germany open a window for mono-material polypropylene specialists to capture share from legacy multi-layer converters facing REACH compliance deadlines. India's FSSAI food-contact compliance pathway offers the most penetrable white-space target, with domestic dairy brands upgrading from basic pressure-sensitive decoration. A licensing partnership with established injection molding clusters provides the fastest credible market entry without cylinder engraving infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with thin-gauge polypropylene innovators given EFSA threshold tightening on food-contact migration limits favoring their technical capabilities. Long-term viability hinges on digital printing thermal stability engineering that enables versioning flexibility without sacrificing heat resistance. The signal to monitor is consolidation velocity among German beverage label converters, which indicates whether scale economies or specialized expertise wins competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captive polypropylene supply insulates margins from crude-linked resin volatility affecting merchant-dependent rivals. |
| Digital Printing Thermal Stability Investment | Ink formulations withstand 200°C melt temperatures, enabling versioning flexibility previously restricted to pressure-sensitive alternatives. |
| Pre-Distortion Software Acquisition | Control over cylinder engraving compensation expertise concentrates among legacy European and Japanese operators. |
| Extended Producer Responsibility Partnership | France's Citeo and Germany's DSD systems reward mono-material adoption through modulated packaging fee structures. |
| Pharmaceutical Serialization Certification | EMA tamper-evident guidelines push drug manufacturers toward permanent fusion labels with superior unit margins. |
Research Methodology
Trade association filings, customs import-export databases, and SEC 10-K disclosures formed the secondary backbone for capacity and revenue estimation. Primary interviews with injection molding plant managers, label converter procurement leads, beverage brand packaging directors, and EFSA regulatory affairs specialists validated secondary findings and informed competitive positioning assessments. Bottom-up triangulation across converter capacity utilization and top-down cross-check against end-use demand volumes ensured analytical consistency.
Historical trendline analysis established baseline growth patterns across material type, application segment, printing technology, and end-user industry dimensions. CAGRs were derived through regression analysis of shipment volumes and value realizations across the projection horizon. Forecast inputs incorporated EU Green Deal implementation timelines, REACH substance restriction phase-out schedules, and injection molding cluster expansion plans in China and India.
Caveats apply where petroleum price shocks, regulatory enforcement delays, or digital printing thermal stability breakthroughs could materially shift the outlook. Forecasts reflect assumptions about mono-material adoption velocity and pre-distortion software talent availability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Healthcare and Laboratory Labels Market
Labels
High Gloss Labels Market
Labels
Shrink Sleeve Labels Market
Labels
Oxygen Indicator Labels Market
Labels
Pre-Gummed Labels Market
Labels
HAZMAT Labels Market
Labels
Sustainable Labels Market
Labels
Holographic Labels Market
Labels
Asia-Pacific Self-Adhesive Labels Market
Labels
Direct Thermal Labels Market
Labels
Multi-Part Labels Market
Labels
Inventory Tags Market
Labels
Self-Adhesive Labels Market
Labels
Linerless Labels Market
Labels
Wire Marking Labels Market
Labels
Ripeness Indicator Labels Market