
 Performance Testing Tools Market | 2026-2036
Performance Testing Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Performance Testing Tools Market Analysis
Capital-intensity divergence between cloud-native challengers and legacy incumbents is unwinding traditional competitive moats in performance testing. LoadRunner (OpenText) anchors its position through deep enterprise channel control and decades of mainframe-to-cloud migration expertise. Grafana Cloud K6 leverages open-source community velocity to compete on developer-native pricing and Kubernetes-aligned workflows.
Performance testing tools are software platforms that simulate user traffic, system load, and failure conditions to validate application responsiveness, stability, and throughput under defined concurrency thresholds. These tools execute scripted transaction sequences across distributed infrastructure to isolate latency bottlenecks, memory leaks, and thread contention before production deployment. Cloud-based deployment models now capture the fastest expansion as organizations abandon fixed-capacity data center commitments for elastic consumption tied to release cadence. Automated testing solutions command disproportionate R&D investment from vendors because CI/CD embedding creates recurring subscription pull-through across DevOps toolchains. Open-source solutions sustain price pressure on commercial tiers while simultaneously expanding total addressable market awareness among mid-market engineering teams.
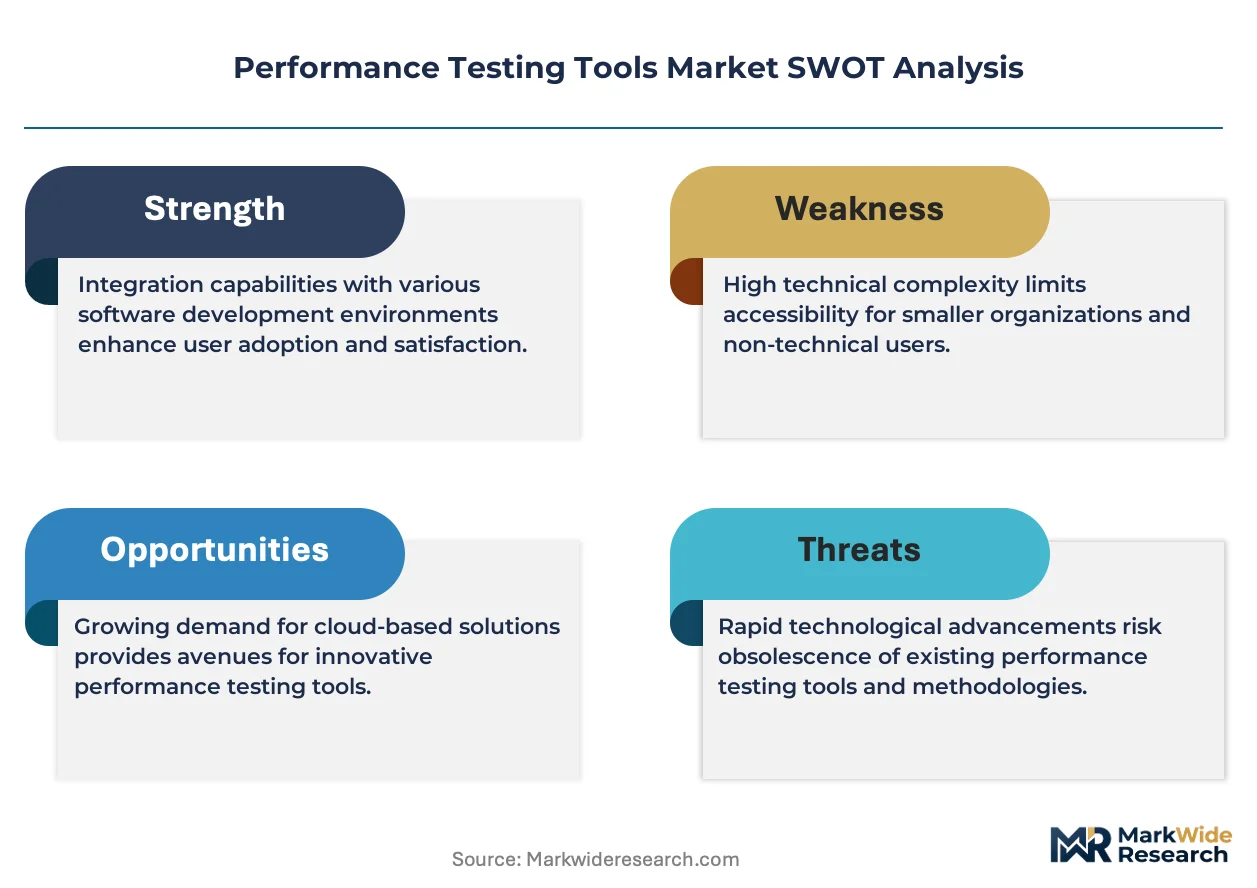
FDA software validation guidelines for healthcare IT systems, SEC operational resilience expectations for trading infrastructure, and ISO 25010 software quality standards collectively elevate mandatory testing rigor across regulated verticals. The EU AI Act's risk-based system classification will extend performance verification requirements to inference latency and model serving throughput benchmarks. Stakeholders must weigh compliance-driven testing depth against cloud infrastructure cost trajectories when selecting platform architectures.
Market Dynamics
DevOps pipeline automation is compressing release cycles and forcing performance testing tools to embed directly into CI/CD workflows, eliminating standalone testing phases that previously buffered production deployments.
Growth Catalysts
- CI/CD Integration Mandates:Engineering standards bodies now require automated performance gates in deployment pipelines, pulling testing tools into subscription bundles across DevOps toolchains.
- Fintech Regulatory Stress-Testing:SEC operational resilience expectations for trading infrastructure mandate throughput validation before system go-live, expanding mandatory procurement in financial services.
- Cloud-Native Application Rollouts:BFSI platforms migrating to distributed microservices architectures require elastic load simulation that fixed-capacity data center tools cannot deliver.
Market Restraints
- Cloud Infrastructure Cost Volatility:Elastic consumption pricing tied to release cadence creates unpredictable operational expenditure spikes that finance teams resist approving.
- Open-Source Price Compression:Community-driven tools like K6 sustain zero-license alternatives that commercial vendors must differentiate against through managed service overlays.
- Skill Specialization Bottlenecks:Shortage of engineers proficient in both distributed systems architecture and performance engineering limits enterprise adoption velocity.
Strategic Opportunities
- EU AI Act Compliance Services:Risk-based system classification extends performance verification to inference latency benchmarks, creating new verification modules for ML serving infrastructure.
- Kubernetes-Native Testing Workflows:Container orchestration alignment enables testing-as-code paradigms that embed directly into platform engineering teams' existing GitOps practices.
- Healthcare IT Validation:FDA software validation guidelines for connected medical devices create recurring compliance-driven testing engagements with specialized documentation requirements.
Industry Challenges
- Legacy System Integration Complexity:Mainframe-to-cloud migration paths require hybrid testing environments that span decades of technical debt, complicating tool configuration.
- ISO 25010 Certification Timelines:Software quality standard compliance demands extensive documentation cycles that delay product launch windows and strain engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Performance Testing Tools Market |
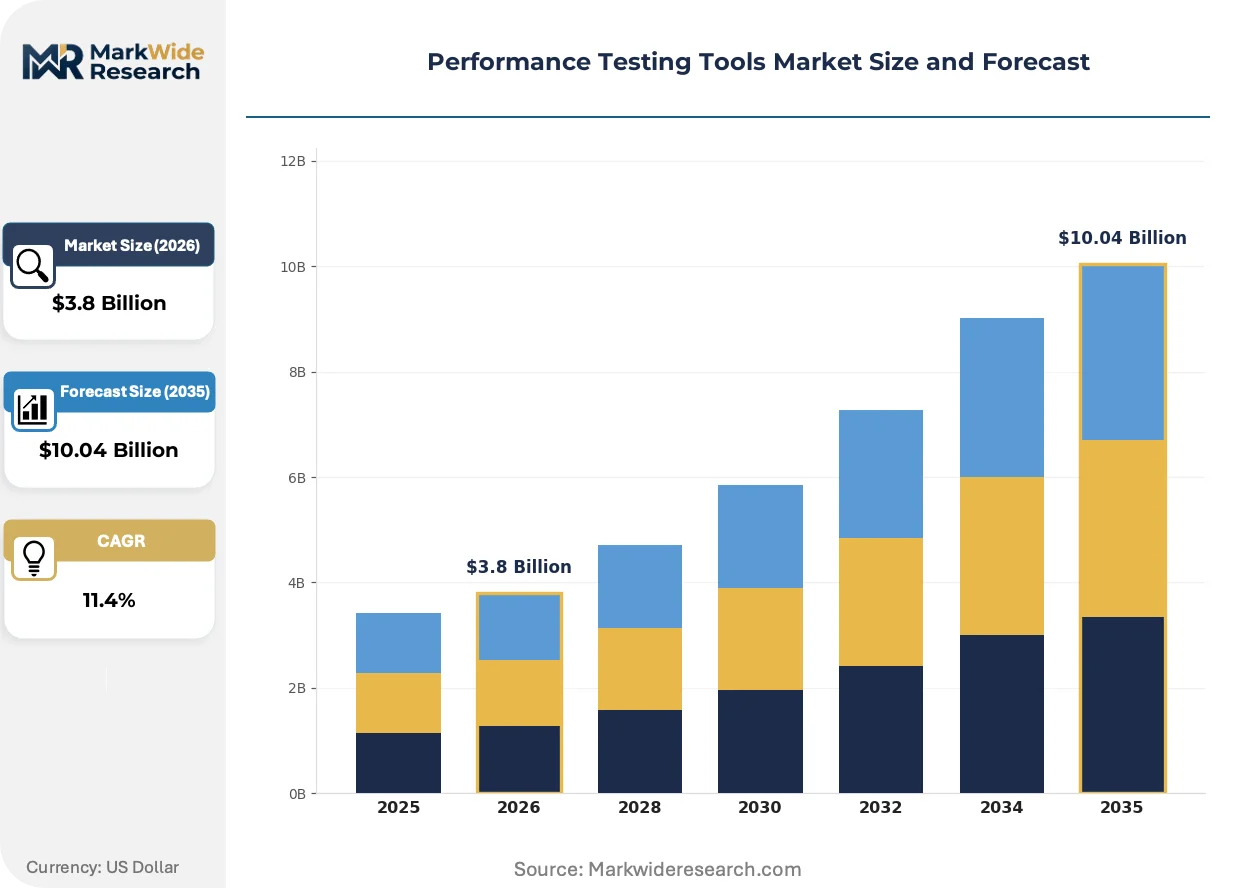
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Load Testing, Stress Testing, Functional Testing, Automated Testing Deployment Model: On-Premises, Cloud-Based, Hybrid, Local End User: IT Services, Telecom, BFSI, E-Commerce Solution: Open Source, Commercial, SaaS, Consulting |
| Companies Covered | OctoPerf, Apache JMeter, PFLB, LoadRunner (OpenText), Gatling, BlazeMeter, Loadium, LoadNinja, Grafana Cloud K6, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Performance Testing Tools Market Emerging Trajectories
Performance testing architectures are fragmenting between developer-native open-source stacks and enterprise-managed commercial platforms, with workflow embedding rather than feature depth becoming the primary competitive differentiator.
Chaos engineering is bifurcating traditional load testing by introducing failure injection as a core validation layer. Platform engineering teams at hyperscale retailers and streaming services now mandate combined load-and-fault simulations before production release. This convergence is compressing vendor roadmaps that previously treated reliability and performance as separate tool categories.
The EU AI Act's risk-based classification system imposes inference latency documentation requirements on high-risk AI deployments. Medical imaging and credit scoring platforms must now benchmark model serving throughput under concurrent request loads. European healthcare IT vendors are responding by integrating performance verification into MDR technical documentation workflows.
Engineering procurement patterns are consolidating around bundled DevOps platforms rather than standalone testing licenses. Mid-market software teams now acquire performance capabilities as embedded modules within CI/CD suites, bypassing dedicated vendor relationships. This concentration is most visible in United States fintech clusters where procurement authority has shifted from QA directors to platform engineering leads.
Performance Testing Tools Market Segmentation
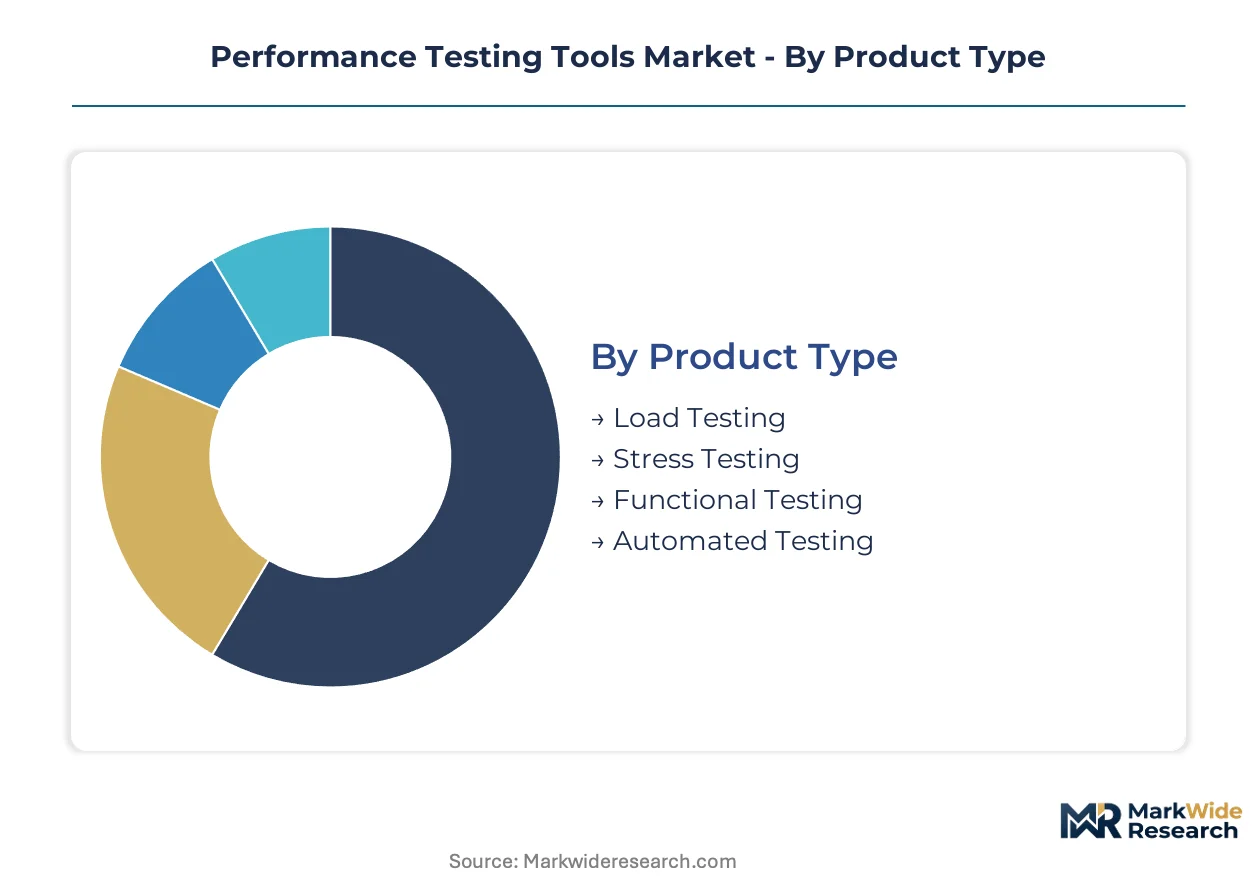
Performance testing tools fragment across four critical dimensions that determine procurement authority and pricing power. Product architecture and deployment economics drive substitution risk most acutely, while end-user verticals and solution delivery models reshape competitive boundaries.
Product Type:
Load testing faces acute substitution pressure from developer-native open-source stacks that embed directly into CI/CD pipelines.
- Load Testing:Simulates concurrent user traffic to measure application response times and throughput under defined volume thresholds. Demand concentrates in United States fintech clusters where SEC operational resilience mandates require throughput validation before system go-live.
- Stress Testing:Pushes systems beyond normal operational capacity to identify breaking points and failure modes. European healthcare IT vendors integrate stress validation into MDR technical documentation workflows for connected medical devices.
- Functional Testing:Validates individual software functions operate correctly under expected conditions.
- Automated Testing:Executes scripted test sequences without manual intervention across release pipelines.
Load testing anchors the volume base while automated testing gains share at the steepest rate.
Deployment Model:
Cost tier stratification separates enterprise retention spending from mid-market elastic consumption patterns.
- Cloud-Based:Delivers elastic load simulation capacity through consumption-based pricing tied to release cadence. United States hyperscaler data center buildouts and fintech regulatory stress-testing requirements are converging to accelerate procurement.
- Hybrid:Combines on-premises control with cloud burst capacity for variable demand spikes. BFSI platforms migrating to distributed microservices architectures require this flexibility for compliance-sensitive workloads.
- On-Premises:Maintains fixed-capacity infrastructure within organizational data centers.
- Local:Deploys testing environments on individual developer workstations or isolated subnets.
On-premises deployments retain the largest installed base while cloud-based solutions expand most quickly.
End User:
Application intensity varies sharply across verticals with divergent compliance burdens and release velocity requirements.
- BFSI:Banking, financial services, and insurance platforms face mandatory throughput validation under SEC operational resilience expectations and EU AI Act risk classification for algorithmic trading systems.
- IT Services:Outsourced development shops and system integrators embed testing tools across client DevOps toolchains.
- Telecom:Network operators validate signaling infrastructure and customer-facing application performance.
- E-Commerce:Retail platforms simulate flash sale traffic and seasonal demand spikes.
BFSI commands the deepest testing spend per deployment while IT services drives the broadest tool proliferation.
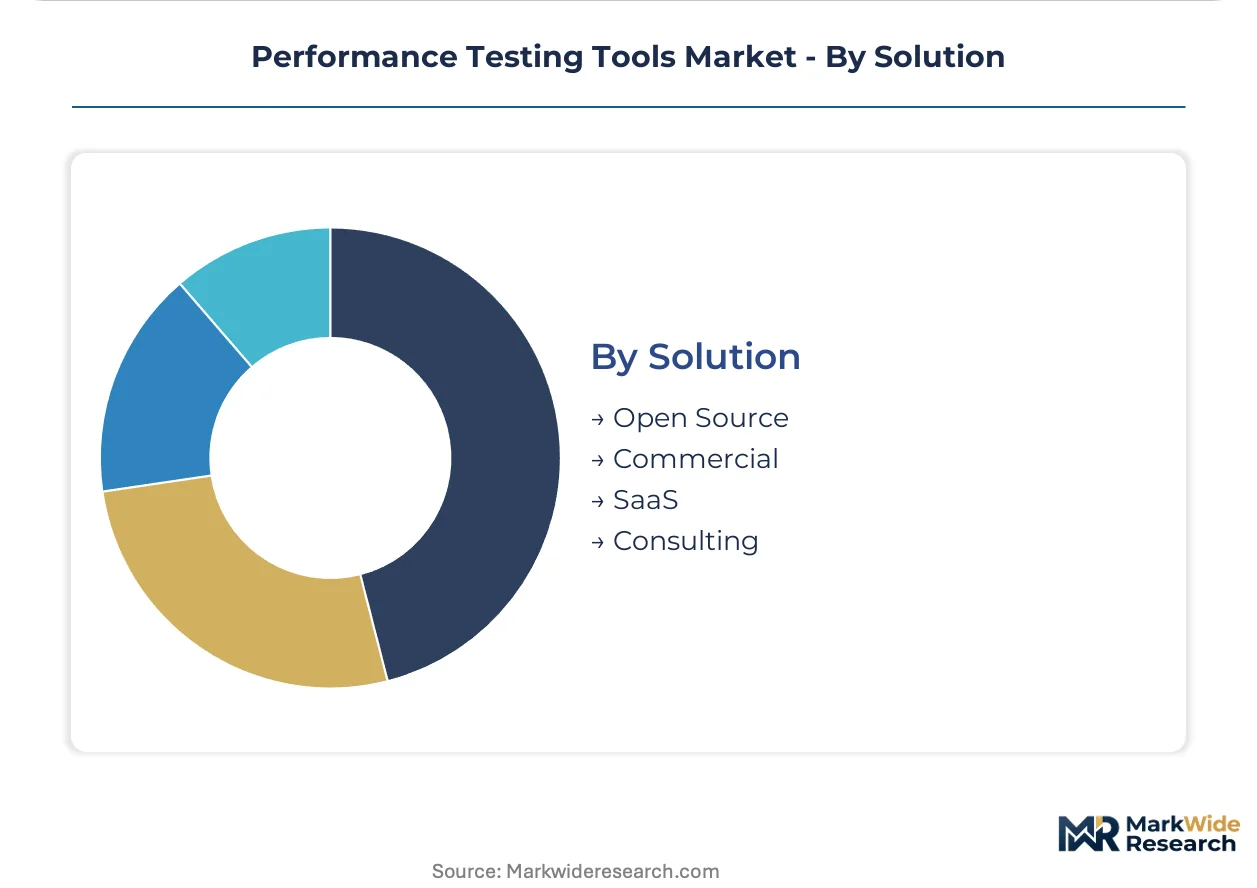
Solution:
Customer type and procurement maturity determine whether organizations acquire capabilities through subscription, license, or professional services.
- SaaS:Managed testing platforms eliminate infrastructure provisioning overhead through browser-based configuration. Mid-market software teams acquire performance capabilities as embedded modules within CI/CD suites.
- Open Source:Community-driven tools like K6 sustain zero-license alternatives that commercial vendors must differentiate against.
- Commercial:Perpetual or subscription licenses for proprietary testing platforms with enterprise support.
- Consulting:Professional services engagements for test design, execution, and compliance documentation.
Commercial solutions capture the highest revenue per account while SaaS delivery climbs the fastest among new deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. United States buyers absorb premium pricing for compliance-integrated suites, while Indian and Brazilian procurement teams prioritize open-source alternatives with managed service overlays.
United States
SEC operational resilience mandates for trading infrastructure and hyperscaler data center expansion drive procurement intensity. FDA software validation guidelines for healthcare IT systems create recurring compliance engagements. Fintech clusters in New York and San Francisco embed performance testing directly into CI/CD pipelines.
Germany
Automotive OEMs and industrial automation suppliers validate embedded software under ISO 25010 quality standards. The EU AI Act's risk-based classification imposes inference latency documentation on manufacturing AI deployments. Bavaria's Munich-Stuttgart corridor concentrates DevOps platform engineering teams.
United Kingdom
Financial services regulators enforce operational resilience expectations for payment infrastructure and algorithmic trading systems. GDPR-aligned data sovereignty requirements shape hybrid deployment preferences. London's fintech density sustains dedicated testing tool procurement budgets.
India
IT services exporters and domestic fintech unicorns scale engineering headcount faster than specialized performance engineers. RBI guidelines for digital payment infrastructure stress-testing expand mandatory validation scope. Bengaluru and Hyderabad clusters drive SaaS-based testing adoption.
Japan
Manufacturing software vendors and telecom operators maintain conservative procurement cycles with heavy on-premises retention. METI industrial standards for connected device reliability extend testing documentation requirements. Tokyo-Osaka corridor concentrates enterprise platform engineering investment.
Performance Testing Tools Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier that fragments across open-source communities and vertical-specific boutiques. The upper tier commands enterprise retention through bundled DevOps platform relationships and compliance documentation services. Specialist competitors compete on Kubernetes-native workflows and developer-native pricing. M&A activity concentrates on CI/CD toolchain integration, while organic R&D prioritizes AI inference benchmarking modules.
Within the open-source-native tier, Apache JMeter and Grafana Cloud K6 exemplify community-driven velocity that commercial vendors must differentiate against through managed overlays. LoadRunner (OpenText) occupies a position representing decades of enterprise channel control and mainframe-to-cloud migration expertise. These three anchors illustrate the competitive tension between zero-license alternatives and premium compliance-integrated suites.
| Leading Market Players |
|---|
| OctoPerf |
| Apache JMeter |
| PFLB |
| LoadRunner (OpenText) |
| Gatling |
| BlazeMeter |
| Loadium |
| LoadNinja |
| Grafana Cloud K6 |
| Others |
Supply Flow & Price Mechanics
Elastic consumption capacity at hyperscale data centers generates scale economies that compress unit economics for cloud-native testing vendors while establishing price floors for on-premises retention plays. This concentration of compute infrastructure in United States hyperscaler regions simultaneously enables SaaS-tiered subscription models and pressures commercial vendors to differentiate through managed service overlays rather than license premiums.
Pricing Analysis
Professional services and extended compliance documentation contracts drive lifetime value for enterprise-grade testing platforms. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated healthcare suites from mid-market SaaS modules and open-source community editions. Cost compression in the standard tier intensifies because K6 and Apache JMeter sustain zero-license alternatives that commercial vendors must offset through Kubernetes-native workflow integration. Mid-market platform engineering teams exhibit acute price sensitivity, while BFSI compliance officers absorb premium pricing for SEC-validated throughput benchmarking.
Supply Chain Analysis
The United States and Germany anchor enterprise software development and automotive embedded systems validation, respectively. Cloud infrastructure provisioning draws from hyperscaler data center buildouts in Virginia, Oregon, and Frankfurt, while CI/CD toolchain integration rests on GitHub, GitLab, and Atlassian platform engineering. Single-source vulnerability concentrates in hyperscaler compute dependencies, as AWS, Azure, and GCP capacity constraints can throttle elastic load simulation during peak release windows. Distribution runs through DevOps platform bundles that embed testing capabilities as subscription modules rather than standalone procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has consolidated around platform engineering leads who control CI/CD procurement budgets, fragmenting traditional QA director authority and compressing standalone testing vendor margins.
For Market Incumbents: Fortify enterprise retention through deep ISO 25010 certification investment and mainframe-to-cloud migration expertise that open-source challengers cannot replicate. Channel control over system integrator relationships and compliance documentation services defends against Grafana Cloud K6's developer-native pricing. Prioritize R&D in AI inference benchmarking modules to capture EU AI Act verification requirements.
For New Entrants and Emerging Players: Lead with Kubernetes-native testing-as-code paradigms that embed directly into platform engineering teams' existing GitOps practices. European healthcare IT vendors present the most penetrable segment, as MDR technical documentation workflows create recurring compliance-driven engagements. Target managed service overlays on Apache JMeter open-source cores to bypass zero-license price resistance.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors CI/CD toolchain integration specialists over standalone testing pure-plays. Long-term viability hinges on workflow embedding depth rather than feature breadth, with hyperscaler partnership density serving as the critical inflection signal. Acquisition targets should demonstrate existing GitHub Marketplace or GitLab integration presence alongside healthcare or fintech vertical penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| CI/CD Platform Integration | Embedding into GitHub Actions and GitLab pipelines captures platform engineering procurement authority. |
| AI Inference Benchmarking Module Launch | EU AI Act latency documentation requirements create new verification revenue streams for ML serving infrastructure. |
| Healthcare Compliance Services Expansion | FDA software validation guidelines for connected medical devices generate recurring documentation engagements. |
| Hyperscaler Partnership Deepening | AWS Marketplace and Azure DevOps integration reduces customer acquisition friction for cloud-native deployments. |
| Open-Source Commercial Overlay Acquisition | Managed service packaging around K6 or JMeter communities defends against zero-license price compression. |
Methodological Framework
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in this study. Platform engineering leads, DevOps directors, QA managers at BFSI institutions, and compliance officers at healthcare IT vendors provided operational perspectives. These insights were triangulated against SEC operational resilience guidance, FDA software validation guidelines, EU AI Act risk classification frameworks, and ISO 25010 quality standard documentation. Bottom-up deployment model analysis and top-down vertical spending estimates were reconciled to establish market sizing boundaries.
Sensitivity analysis around cloud infrastructure cost trajectories and open-source adoption velocity informs the projection framework. Segmentation dimensions span product type, deployment model, end-user vertical, and solution delivery approach, with regional adoption patterns and CI/CD maturity serving as cross-cutting variables. CAGRs were derived from elasticity modeling across these dimensions, incorporating hyperscaler capex disclosures and DevOps toolchain penetration benchmarks as industry-specific inputs.
Forecasts assume regulatory continuity in SEC operational resilience expectations, FDA software validation protocols, and EU AI Act implementation timelines; material policy shifts would require re-modeling. Specific risks include open-source price compression acceleration, hyperscaler capacity constraints, and skill specialization bottlenecks that could constrain enterprise adoption velocity. Recalibration cycles align with material shifts in CI/CD platform consolidation and compliance mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Interference Mitigation Filters Market
Others
Africa Smart Card Market
Others
Pickup Truck Market
Others
Construction Wearables Market
Others
Global Cryogenic Tanks Market
Others
Asia Pacific Video Conferencing Hardware Market
Others
Italy 3D Printing Construction Market
Others
Asia-Pacific B2B Legal Services Market
Others
Tripod Market
Others
Asia-Pacific Programmatic Display Advertising Market
Others
Port Replicator Market
Others
Europe Military 4D Printing Market
Others
Global Thermally Conductive Grease Market
Others
AI in Home Automation Market
Others
Industrial Gauges Market
Others
Global Active Speaker Market