
 Cellulose Paints Market | 2026-2036
Cellulose Paints Market Size, Share, and Industry Trends Forecast 2026-2036
Cellulose Paints Market Analysis
Asset-light leasing models for cellulose ester production equipment are narrowing the capital barrier for mid-tier paint manufacturers. PPG Industries leverages captive supply chains for nitrocellulose feedstock to sustain margin stability across automotive coating lines. AkzoNobel anchors its European position through specialized water-based cellulose formulations that meet industrial VOC thresholds. BASF competes on R&D intensity in cellulose derivative chemistry for furniture finishing applications.
Cellulose paints are coatings formulated with nitrocellulose or cellulose acetate binders dissolved in organic solvents, typically yielding films that dry through solvent evaporation rather than chemical curing, with coating thicknesses ranging from 15 to 40 micrometers for decorative and protective applications. Their primary commercial purpose centers on delivering rapid-drying, high-gloss finishes for wood furniture, automotive components, and consumer goods where production throughput outweighs durability demands. Solvent-based formulations still occupy the largest value share due to their superior flow and leveling in automotive refinishing, though water-based alternatives are gaining share where environmental compliance tightens. Industrial coatings applications generate the deepest margin pools because batch consistency requirements and technical service demands limit price-based competition. Spray paint formats lead volume in craft and hobbyist channels where convenience overrides per-unit cost sensitivity.
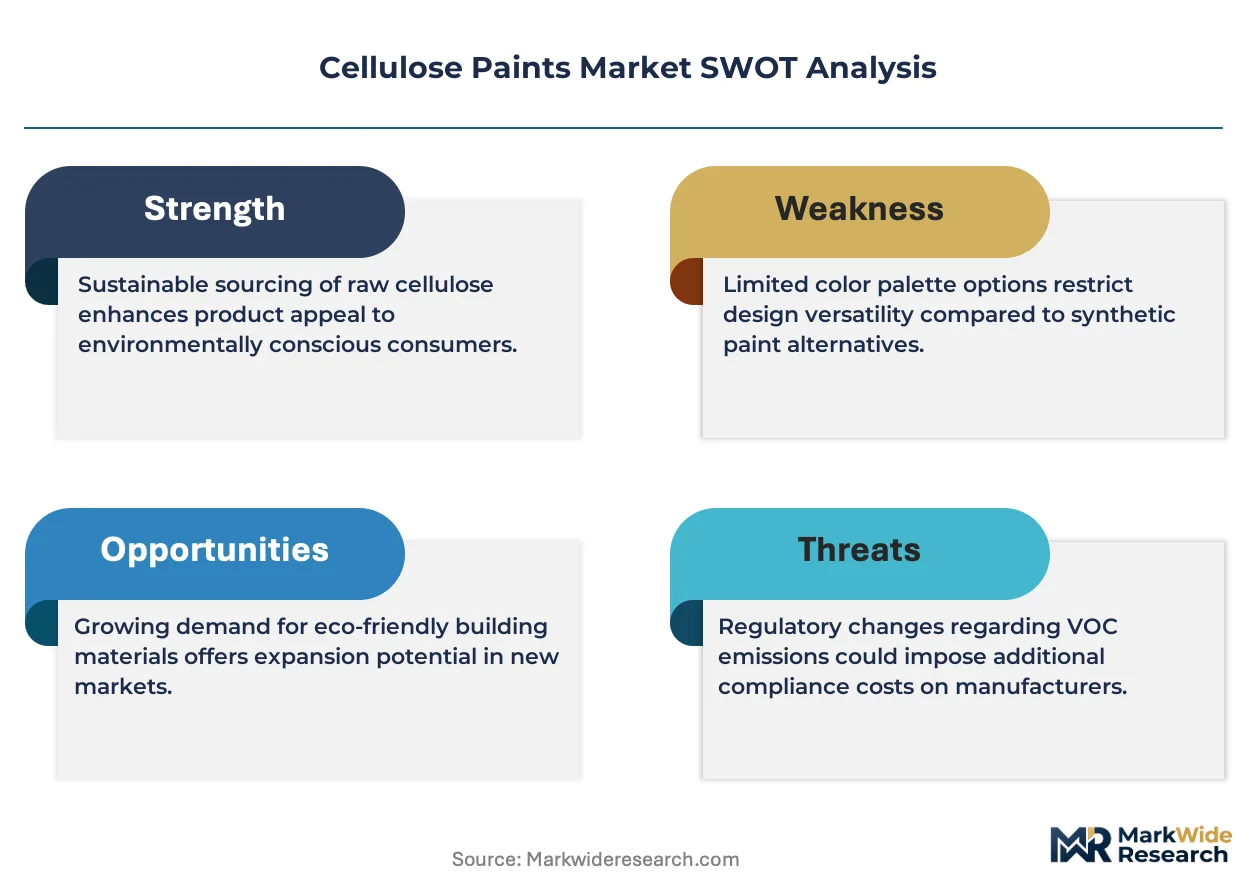
EPA regulations on hazardous air pollutants and OSHA permissible exposure limits for n-hexane in coating operations constrain solvent-based formulation strategies in the United States. REACH registration requirements and the EU F-Gas Regulation indirectly pressure manufacturers toward lower-VOC cellulose paint systems by altering solvent availability and cost structures. China's MEE enforcement of GB standards on industrial emissions is accelerating domestic reformulation investments. Stakeholders must monitor evolving solvent substitution pathways and regional enforcement intensity to align product portfolios with compliance timelines.
Market Dynamics
Automotive OEMs in Germany and Japan are accelerating solvent-based cellulose paint consumption for faster-drying finishes, while REACH and China's GB standards force simultaneous reformulation investments that compress margin structures for mid-tier suppliers.
Growth Catalysts
- Automotive Refinishing Throughput:German and Japanese OEMs specify nitrocellulose lacquers for assembly-line speed, creating pull for high-gloss, rapid-cure formulations in Chennai and Pune automotive hubs.
- REACH Registration Thresholds:ECHA's evolving substance restrictions are forcing solvent substitutions that favor specialized cellulose ester producers with compliant feedstock chains.
- Wood Furniture Export Certification:India's BIS standards alignment with EU decorative coating specifications is opening bonded warehouse demand for VOC-compliant cellulose finishes.
Market Restraints
- Cotton Linters Supply Concentration:Nitrocellulose feedstock depends on cotton byproduct availability concentrated in South Asian and Chinese textile processing regions.
- n-Hexane Exposure Limits:OSHA permissible exposure thresholds in US coating operations add ventilation capital burdens that solvent-based cellulose lines struggle to absorb.
- Polyurethane Substitution:Two-component polyurethane clears are capturing share in premium automotive refinish segments where durability outweighs speed.
Strategic Opportunities
- Water-Based Formulation Gaps:India's domestic paint manufacturers lack captive cellulose ester technology, creating licensing windows for European water-based IP holders.
- MEE Enforcement Acceleration:China's Ministry of Ecology and Environment is tightening GB emissions inspections, mandating solvent recovery systems that favor reformulated cellulose alternatives.
- Furniture E-Commerce Finishing:Direct-to-consumer wood furniture platforms in Germany require batch-flexible, quick-turn coating services that cellulose spray systems uniquely provide.
Industry Challenges
- Reformulation Chemist Scarcity:Cellulose derivative solvent substitution expertise sits concentrated with legacy European and Japanese technical service teams, constraining Indian and Chinese manufacturer autonomy.
- Legacy Equipment Stranding:Mid-tier paint producers face stranded asset risk on conventional solvent-based cellulose lines as regional VOC timelines compress.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellulose Paints Market |
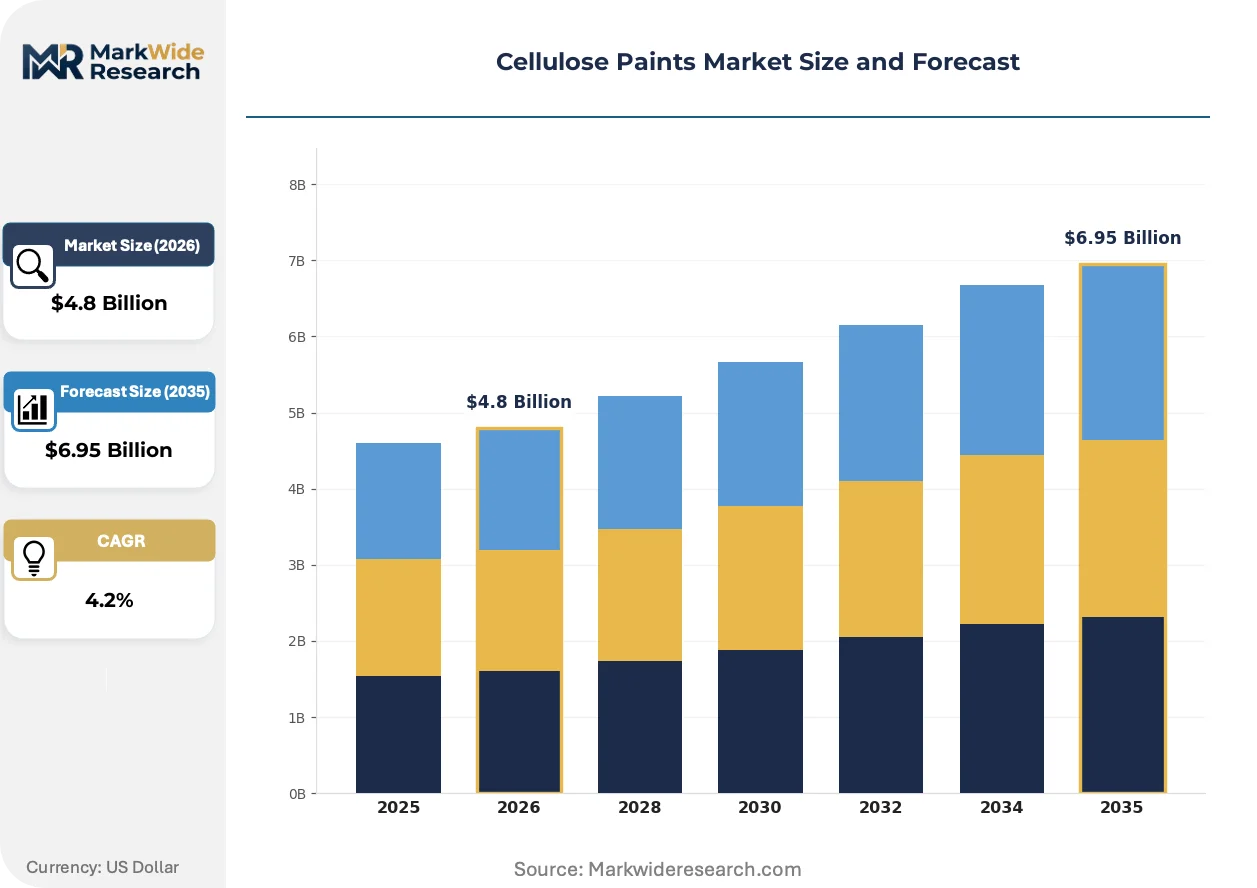
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent-Based, Water-Based, Spray Paint, Primers Application: Automotive Coating, Furniture Finishing, Industrial Coatings, Craft Projects End User: Manufacturers, Hobbyists, Construction, Automotive Distribution Channel: Retail Stores, Online Platforms, Wholesale, Direct Sales |
| Companies Covered | PPG Industries, AkzoNobel, BASF, Eastman Chemical Company, The Sherwin-Williams Company, RPM International, Nippon Paint Holdings, The Dow Chemical Company, Asian Paints, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellulose Paints Market Emerging Trajectories
Formulation chemistry is bifurcating between legacy solvent systems serving speed-critical automotive segments and water-based cellulose esters capturing regulatory-compliant furniture and industrial coatings demand.
Water-reducible cellulose acetate butyrate dispersions are migrating from specialty architectural touch-up applications into mainstream industrial maintenance coatings. German furniture manufacturers are piloting these systems for kitchen cabinet production where EU F-Gas Regulation solvent availability constraints bite hardest. The technology is compressing the traditional solvent-based cellulose advantage window in decorative applications where throughput requirements moderate.
REACH's 2023-2025 substance evaluation wave is eliminating several ketone and ester solvents historically standard in nitrocellulose lacquers. ECHA's restriction proposals on N-methyl-2-pyrrolidone and specific glycol ethers are forcing reformulation toward higher-cost cellulose ester alternatives. Automotive refinish shops in France and Italy are absorbing price premiums for compliant pre-mixed systems rather than blending in-house.
Indian automotive component suppliers are consolidating coating procurement through integrated paint-and-application service contracts with German and Japanese technical partners. Tier-2 stamping and injection molding shops around Pune and Chennai are outsourcing finishing entirely, abandoning in-house cellulose spray booths. This behavior concentrates demand with captive applicators possessing ECHA-compliant formulation libraries and MEE-aligned solvent handling infrastructure.
Cellulose Paints Market Segmentation
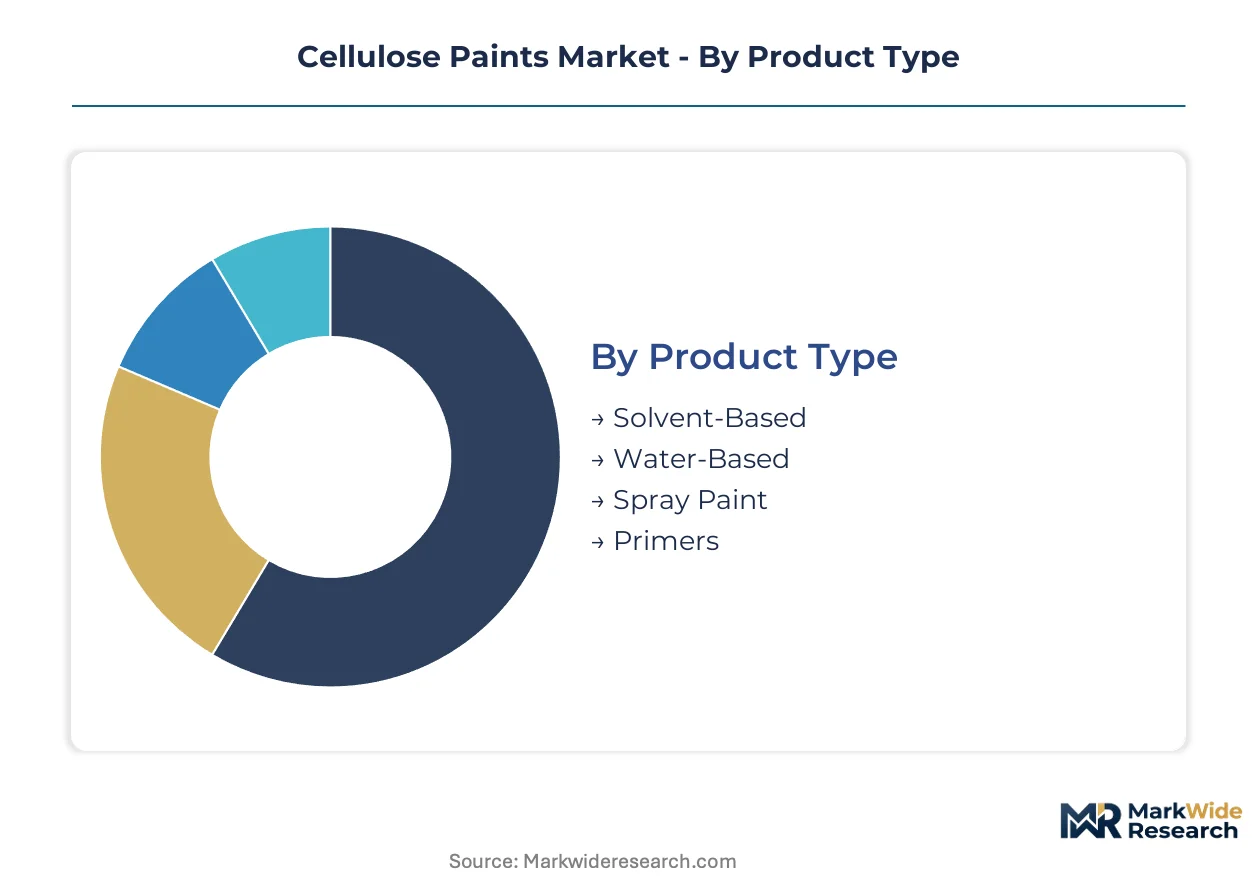
Cellulose paints fragment across formulation chemistry, application environment, and procurement behavior. Each dimension carries distinct margin profiles and regulatory exposure that determine competitive positioning.
Product Type:
Mature solvent systems dominate volume while water-based alternatives emerge fastest on regulatory pressure.
- Solvent-Based:Nitrocellulose and cellulose acetate binders dissolved in organic solvents deliver 15-40 micrometer films through rapid solvent evaporation. German and Japanese automotive OEMs specify these for assembly-line throughput where drying speed outweighs VOC exposure. REACH ketone restrictions and China's GB standards are compressing formulation flexibility.
- Water-Based:Cellulose acetate butyrate dispersions reduce solvent content while maintaining flow characteristics for furniture finishing. German kitchen cabinet manufacturers pilot these systems where EU F-Gas Regulation constrains traditional solvent availability. MEE enforcement in China accelerates domestic reformulation investment.
- Spray Paint:Aerosol formats target craft and hobbyist channels where convenience commands premium pricing over per-unit cost.
- Primers:Undercoat formulations establish adhesion layers for wood furniture and automotive substrates in industrial coating lines.
Solvent-based formulations handle the majority of throughput; water-based alternatives are gaining share fastest on compliance timelines.
Application:
Cost tiers separate speed-critical automotive segments from batch-flexible decorative finishing.
- Automotive Coating:Nitrocellulose lacquers specified by German and Japanese OEMs for rapid-cure assembly lines. Tier-2 suppliers around Pune and Chennai outsource finishing to captive applicators with ECHA-compliant libraries.
- Furniture Finishing:High-gloss cellulose systems serve export certification requirements where India's BIS standards align with EU decorative specifications. Direct-to-consumer e-commerce platforms in Germany demand quick-turn batch flexibility.
- Industrial Coatings:Maintenance and protective applications generate margin pools where technical service demands limit price competition.
- Craft Projects:Hobbyist consumption concentrates in spray formats through retail and online channels.
Automotive coating commands premium pricing; furniture finishing is expanding most quickly on export certification alignment.
End User:
Customer type determines volume scale versus specification intensity.
- Manufacturers:Integrated production lines in automotive and furniture sectors procure through paint-and-application service contracts with German and Japanese technical partners.
- Hobbyists:Individual consumers purchase spray formats through retail and online platforms where convenience overrides per-unit economics.
- Construction:Maintenance and touch-up applications for architectural woodwork and trim.
- Automotive:Refinish shops and OEM assembly operations with specialized VOC handling infrastructure.
Manufacturers concentrate procurement volume; hobbyist channels sustain the steepest expansion trajectory on e-commerce penetration.
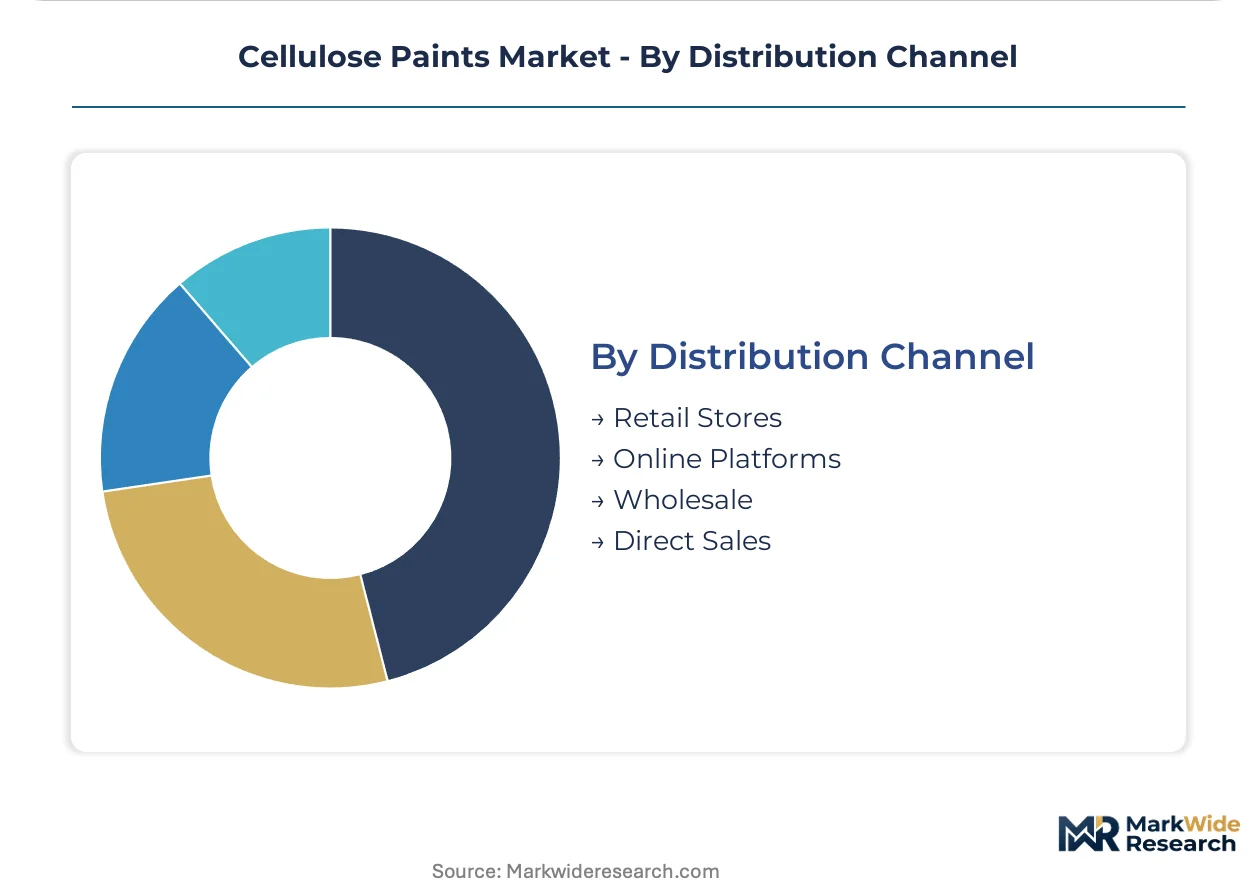
Distribution Channel:
Supply concentration varies by customer scale and technical service requirements.
- Retail Stores:Bricks-and-mortar outlets serve hobbyist and small contractor demand for immediate product access.
- Online Platforms:E-commerce channels capture craft and DIY segments with expanded SKU availability.
- Wholesale:Bulk distribution to industrial applicators and coating service providers.
- Direct Sales:Technical service-intensive relationships with automotive OEMs and furniture manufacturers requiring formulation customization.
Direct sales anchor industrial value capture; online platforms are climbing the fastest on consumer channel shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH registration timelines and China's GB emissions standards are reshaping formulation requirements across major manufacturing centers. Automotive OEMs in Germany and Japan specify nitrocellulose lacquers for assembly-line throughput. Furniture exporters in India align with EU decorative coating specifications to access bonded warehouse demand.
Germany
Automotive OEMs specify nitrocellulose lacquers for assembly-line speed at plants in Bavaria and Baden-Württemberg. ECHA's 2023-2025 substance evaluation wave eliminates ketone solvents historically standard in these formulations. Tier-1 suppliers around Stuttgart outsource finishing to captive applicators with compliant solvent handling infrastructure.
China
MEE enforcement of GB standards on industrial emissions accelerates domestic reformulation investment in the Yangtze River Delta. The Ministry of Ecology and Environment mandates solvent recovery systems that favor water-based cellulose alternatives. Paint manufacturers in Shanghai and Jiangsu province consolidate procurement through integrated service contracts with technical partners.
India
Automotive component suppliers around Chennai and Pune scale coating procurement through paint-and-application service contracts. BIS standards alignment with EU decorative specifications opens bonded warehouse demand for VOC-compliant cellulose finishes. Domestic manufacturers lack captive cellulose ester technology, creating licensing windows for European IP holders.
Japan
METI guidelines on chemical substance management influence solvent substitution pathways for automotive refinishing. Japanese OEMs specify rapid-cure cellulose systems for high-gloss assembly-line finishes. Technical service teams in the Kanto and Kansai regions concentrate expertise in cellulose derivative chemistry that constrains manufacturer autonomy elsewhere.
United States
EPA regulations on hazardous air pollutants and OSHA permissible exposure limits for n-hexane constrain solvent-based formulation strategies. Refinish shops absorb ventilation capital burdens that mid-tier producers struggle to accommodate. Industrial coating lines in the Midwest and Southeast face stranded asset risk as regional VOC timelines compress.
Cellulose Paints Market Vendor Landscape
Channel-controlling players compete with product-specialist players across divergent margin pools in automotive and furniture segments. The vendor base separates into consolidated multinational suppliers with captive feedstock chains and regional formulators serving compliance-driven niches. Three archetypes dominate: integrated chemical conglomerates with nitrocellulose backward integration, water-based formulation specialists, and application-service integrators. Competitive moves concentrate on technology licensing for VOC-compliant systems and geographic expansion into Indian and Chinese automotive hubs.
Within the integrated chemical tier, PPG Industries and BASF occupy positions anchored by captive supply chain control over nitrocellulose feedstock. AkzoNobel exemplifies the water-based formulation specialist archetype, with its European positioning built on compliant cellulose ester technology. Among Asia-Pacific coating groups, Nippon Paint Holdings and Asian Paints represent scale-driven regional players expanding through technical partnerships in automotive clusters. These named entities illustrate how competitive advantage separates between feedstock security, regulatory compliance IP, and application-service integration.
| Leading Market Players |
|---|
| PPG Industries |
| AkzoNobel |
| BASF |
| Eastman Chemical Company |
| The Sherwin-Williams Company |
| RPM International |
| Nippon Paint Holdings |
| The Dow Chemical Company |
| Asian Paints |
| Others |
Supply Flow & Price Mechanics
Overcapacity in South Asian cotton linter processing facilities is compressing nitrocellulose feedstock margins and forcing solvent-based cellulose paint suppliers toward volume-driven pricing postures that sacrifice margin for line utilization. This utilization squeeze cascades into buyer negotiations, where automotive OEM procurement teams in Germany and Japan extract price concessions in exchange for long-term offtake commitments.
Pricing Analysis
Certification level creates the primary spread between REACH-compliant formulations and legacy solvent systems. Three-tier pricing structure across premium, standard, and economy levels reflects ECHA registration status, with automotive refinish shops in France and Italy absorbing premiums for pre-mixed compliant systems. Price compression in mid-tier furniture finishing intensifies as Indian domestic manufacturers license European water-based IP. Hobbyist spray formats sustain the least price sensitivity due to convenience premiums.
Supply Chain Analysis
Export-control restrictions on dual-use chemical processing technology limit nitrocellulose production equipment flows from Germany and Japan into South Asian markets. Supply concentrates in China, India, and Pakistan for cotton linter feedstock, while cellulose ester derivative production clusters in Germany, the United States, and Japan. The chain rests on n-hexane solvent availability and specialized reformulation chemist pools concentrated in European technical service teams. Single-source vulnerability runs through South Asian textile byproduct processing. Distribution runs through direct technical service relationships with automotive OEMs and wholesale channels to industrial applicators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks automotive production cycles, with German and Japanese OEM assembly-line throughput serving as the primary cyclical driver. Recovery positioning favors suppliers with captive compliant formulation libraries.
For Market Incumbents: Entrench position through backward integration into nitrocellulose feedstock and accelerated water-based cellulose ester R&D to offset polyurethane substitution threats in premium automotive refinish. Prioritize certification investment for REACH-compliant pre-mixed systems that command pricing premiums. Channel control through paint-and-application service contracts in Indian automotive hubs around Chennai and Pune locks out mid-tier competitors lacking technical service depth.
For New Entrants and Emerging Players: India's domestic paint manufacturers lack captive cellulose ester technology, creating licensing windows for European water-based IP holders seeking geographic expansion. Water-based formulation gaps in furniture finishing for direct-to-consumer German e-commerce platforms offer the most penetrable white space. Target bonded warehouse demand for VOC-compliant cellulose finishes aligned with BIS standards. Go-to-market through technical partnership structures with established applicators rather than greenfield production investment.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory compliance play because REACH substance evaluation waves and China's GB emissions standards permanently elevate formulation expertise barriers. Acquisition targets should center on European and Japanese technical service teams with cellulose derivative solvent substitution capabilities. Watch MEE enforcement intensity in the Yangtze River Delta as the inflection signal for domestic Chinese reformulation investment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitrocellulose Feedstock | PPG Industries and BASF sustain margin stability through captive cotton linter supply chains. |
| Water-Based Formulation Licensing | AkzoNobel's European IP creates entry pathways for Indian domestic manufacturers lacking captive technology. |
| Paint-and-Application Service Contracts | German and Japanese technical partners consolidate Tier-2 supplier demand in Chennai and Pune automotive hubs. |
| Solvent Recovery System Deployment | MEE-mandated infrastructure investments in Shanghai and Jiangsu favor reformulated cellulose alternatives. |
| REACH-Compliant Pre-Mixed System Development | ECHA ketone restrictions force automotive refinish shops toward specialized suppliers with compliant libraries. |
Methodological Framework
Operator-level perspectives from coating plant managers, automotive OEM procurement leads, furniture manufacturer technical directors, and distribution channel partners anchored the qualitative base. Secondary validation drew from ECHA substance restriction proposals, MEE enforcement bulletins, BIS certification databases, and SEC filings from listed coating suppliers. Bottom-up volume modeling triangulated against top-down value estimates across formulation chemistry, application environment, and procurement behavior segments.
Scenario-bracketing around REACH registration timelines and MEE enforcement intensity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include solvent-based versus water-based chemistry, automotive versus furniture versus industrial application, and direct sales versus wholesale distribution. CAGRs derived from production capacity utilization rates in German and Japanese automotive plants and bonded warehouse throughput for Indian furniture exports. Industry-specific inputs incorporated cotton linter price volatility and reformulation chemist availability constraints.
Practitioners should monitor ECHA substance evaluation waves, MEE inspection intensity, and automotive OEM assembly-line speed specifications for early signals of forecast deviation. Forecasts reflect assumptions about regulatory enforcement continuity and solvent substitution pathway economics. Material shifts in REACH ketone restriction implementation or cotton linter supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Fluorescent Paint Market
Paints & Coatings
Core Plate Varnishes Market
Paints & Coatings
South America Paints and Coatings Additives Market
Paints & Coatings
Polyurethane Resins Paints and Coatings Market
Paints & Coatings
Global Exterior Architectural Coatings Market
Paints & Coatings
Bituminous Paints Market
Paints & Coatings
US Paints and Coatings Market
Paints & Coatings
Paint Sprayer Market
Paints & Coatings
Global Primer Market
Paints & Coatings
Saudi Arabia Architectural Paints Market
Paints & Coatings
Middle East & Africa Corrosion Protection Coating Market
Paints & Coatings
Asia-Pacific Paint Spray Guns Market
Paints & Coatings
India Automotive Paints and Coatings Market
Paints & Coatings
Low VOC Paint Market
Paints & Coatings
Decorative Paints Market
Paints & Coatings
Low VOC Paints and Coatings Market