
 Europe Automotive Paints and Coatings Market | 2026-2036
Europe Automotive Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Paints and Coatings Market Foresight
Skilled applicator labor availability is bifurcating the Europe automotive paints and coatings landscape into high-automation OEM lines and labor-dependent aftermarket channels. PPG Industries leverages its centralized European R&D hub in the Netherlands to sustain water-based technology leadership. Akzo Nobel anchors its position through deep relationships with German premium OEMs. BASF competes via backward integration into specialty resin production for automotive clearcoats.
Europe automotive paints and coatings comprise layered polymer systems—typically 15-25 micrometers per coat—engineered to deliver corrosion resistance, UV stability, and aesthetic finish on metal, plastic, and composite substrates. Water-based technology dominates new OEM installations, while solvent-based formulations retain share in commercial vehicle refinishing where drying speed outweighs emissions compliance costs. Powder coating extends its position in wheel and underbody applications, capitalizing on zero-VOC profiles and material utilization rates above 95 percent. The OEM application segment commands the largest value pool, though aftermarket channels offer higher per-liter margins through distributor-controlled pricing.
REACH restricts aromatic solvent content, while the EU Green Deal mandates lifecycle emissions reductions that cascade into coating formulation requirements. ECHA substance evaluations are forcing reformulation of certain isocyanate hardeners, compressing product development cycles. Germany's national implementation of EU Industrial Emissions Directive adds plant-level compliance costs that favor larger integrated suppliers. Stakeholders must monitor the interplay between Ecodesign requirements for vehicles and the carbon footprint accounting boundaries assigned to coating operations.
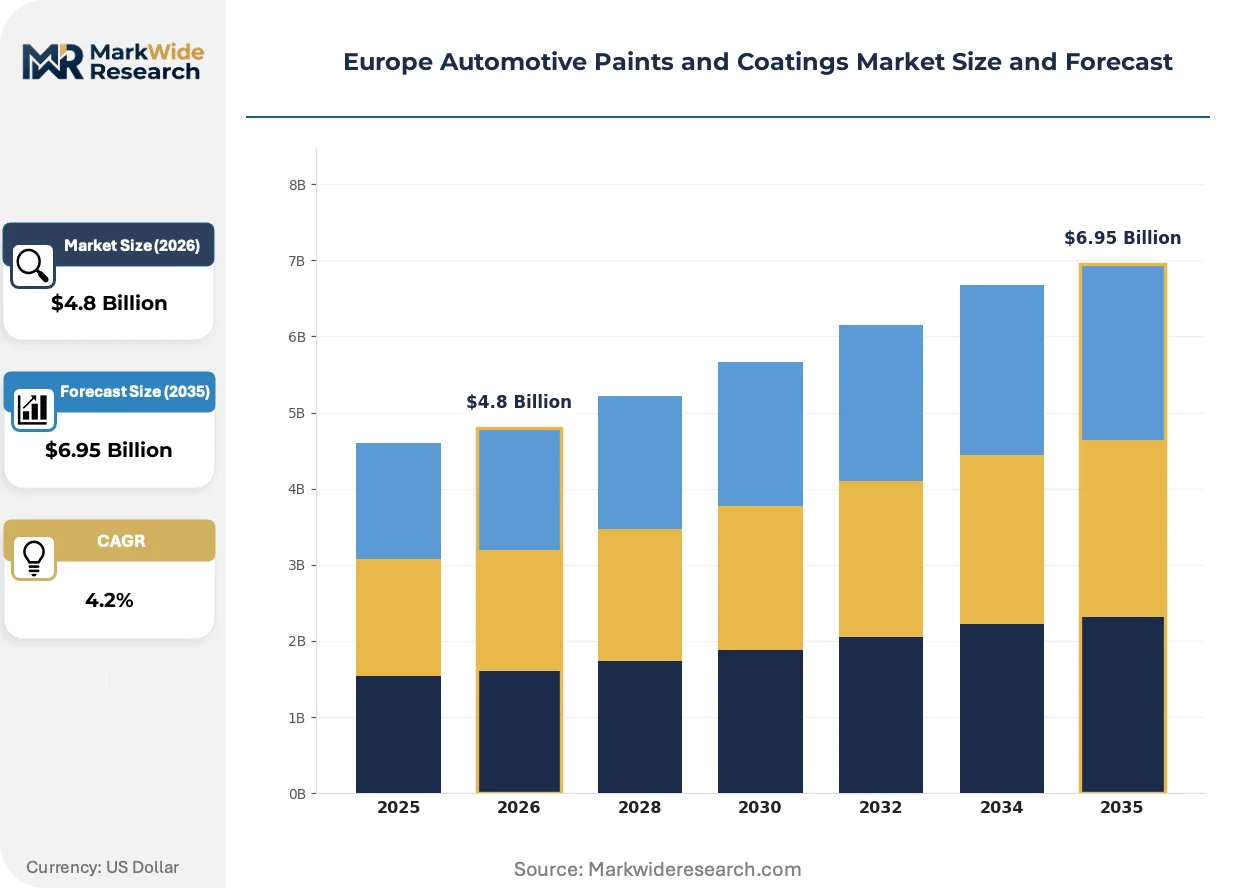
Market Dynamics
REACH substance restrictions and the EU Green Deal are compressing product development cycles while forcing wholesale reformulation of solvent-based systems across European coating operations.
Growth Catalysts
- EU Green Deal lifecycle mandates:Carbon footprint accounting boundaries now extend to coating operations, accelerating water-based system adoption in German and French OEM facilities.
- Battery enclosure specifications:Electric vehicle manufacturers in Bavaria and Baden-Württemberg are expanding coating requirements for thermal management and corrosion protection on aluminum battery housings.
- Powder coating technology:Zero-VOC profiles and material utilization rates above 95 percent are extending powder systems into wheel and underbody applications previously served by liquid coatings.
Market Restraints
- Isocyanate hardener reformulation:ECHA substance evaluations are forcing rapid product redevelopment, compressing R&D timelines and raising compliance costs for integrated suppliers.
- Specialty resin supply concentration:Backward integration into captive resin production favors larger chemical conglomerates, raising barriers for mid-tier coating formulators.
- Drying speed limitations:Water-based formulations cannot match solvent-based cure rates in commercial vehicle refinishing, preserving VOC-intensive systems in aftermarket channels.
Strategic Opportunities
- Lightweight composite substrates:CFRP and thermoplastic body panels in premium electric vehicles require adhesion-promoting primer systems absent from current OEM specifications.
- Industrial Emissions Directive implementation:Germany's national plant-level compliance rules favor larger integrated suppliers with centralized emission control infrastructure.
- Aftermarket channel consolidation:Distributor-controlled pricing in refinishing creates margin capture opportunities for formulators with direct body-shop relationships.
Industry Challenges
- Skilled applicator scarcity:Labor availability bifurcation between automated OEM lines and labor-dependent refinishing channels constrains capacity expansion in aftermarket operations.
- Interplay monitoring burden:Ecodesign requirements for finished vehicles must be reconciled with carbon footprint boundaries assigned to coating operations, complicating compliance architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Paints and Coatings Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basecoats, Clearcoats, Primers, Sealers Technology: Water-based, Solvent-based, Powder Coating, UV Curable Application: OEMs, Aftermarket, Commercial Vehicles, Passenger Vehicles End User: Automobile Manufacturers, Repair Shops, Distributors, Exporters |
| Companies Covered | Axalta Coating Systems, Jotun, Akzo Nobel, Nippon Paint, Beckers Group, PPG Industries, The Sherwin-Williams Company, Covestro, BASF, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Paints and Coatings Market Shifts & Advancements
Formulation chemistry and application methods are evolving under regulatory compression, with sustainability mandates now dictating technical roadmaps rather than merely constraining them.
High-solids and UV-curable clearcoat systems are displacing conventional two-component polyurethane finishes in premium OEM lines. German luxury manufacturers have specified these technologies for 2026 model year production. The shift is compressing incumbent coating suppliers' revenue per vehicle while demanding capital-intensive application line modifications.
REACH authorization procedures for aromatic solvents are tightening permissible exposure limits across coating operations. The restriction cascades into reformulation of basecoat and primer systems used in high-volume assembly plants. French and Spanish OEM facilities face accelerated transition timelines compared to German counterparts with earlier water-based investments.
Direct procurement relationships between OEM coating engineers and specialty resin producers are shortening traditional distributor channels. Tier-1 suppliers now specify raw material grades rather than accepting formulator recommendations. This pattern concentrates most visibly in Bavaria, where BMW and Audi operate centralized technical purchasing functions.
Europe Automotive Paints and Coatings Market Segmentation
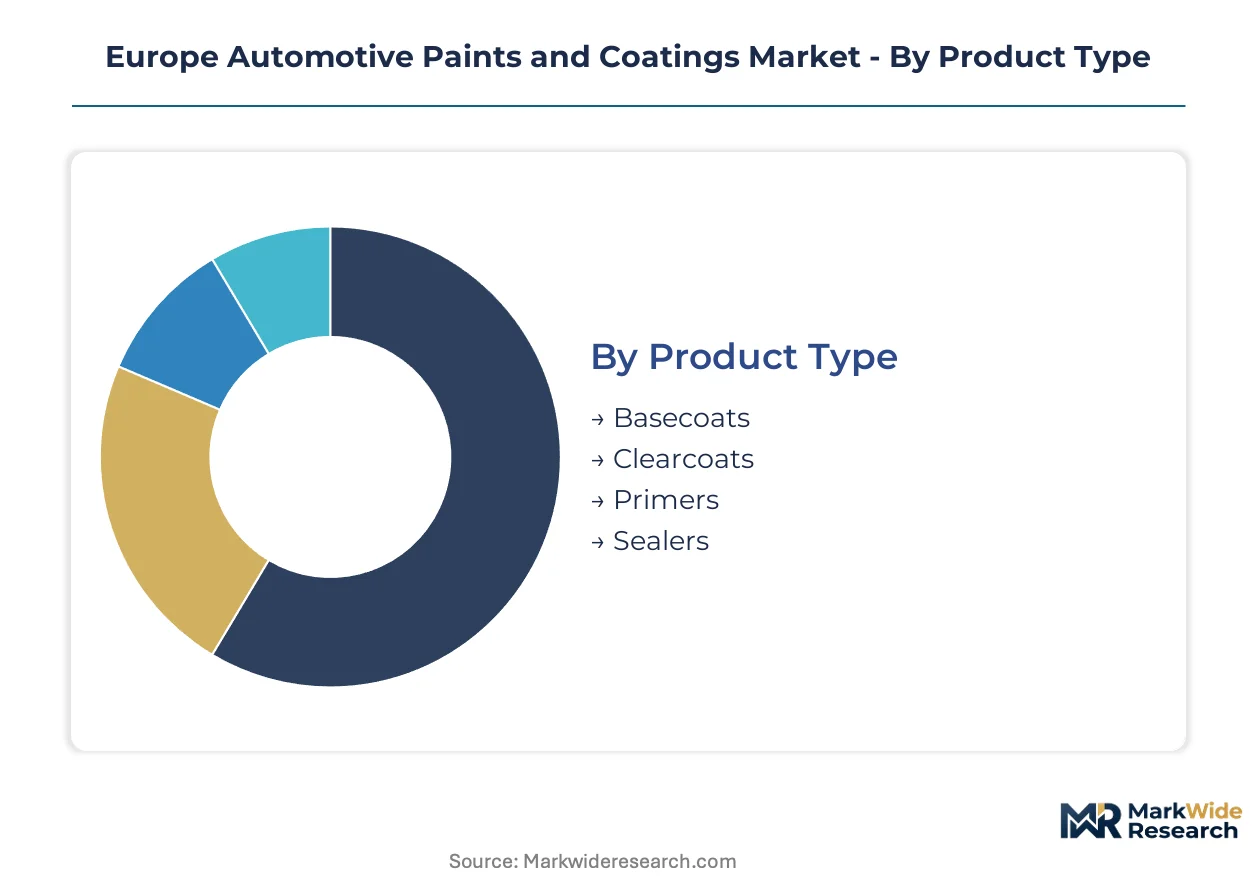
Segmentation in Europe automotive paints and coatings reveals how regulatory pressure and application requirements split value capture across formulation technologies and channel structures. Understanding these divisions exposes where integrated suppliers command premium positioning versus where distributor relationships dominate margin extraction.
Product Type:
Clearcoats and basecoats concentrate margin pools through technical complexity and specification control by German premium OEMs.
- Clearcoats:These 15-25 micrometer top layers deliver UV stability, gloss retention, and scratch resistance through polyurethane or ceramic-enhanced formulations. Bavarian OEM technical centers specify high-solids and UV-curable clearcoats for 2026 model year production, compressing revenue per vehicle while demanding capital-intensive application line modifications. German luxury manufacturers anchor demand concentration here.
- Basecoats:Pigmented layers providing color and metallic effects now operate under REACH aromatic solvent restrictions forcing water-based system adoption. French and Spanish OEM facilities face accelerated transition timelines compared to German counterparts with earlier water-based investments. ECHA substance evaluations cascade directly into basecoat reformulation cycles.
- Primers:Adhesion-promoting underlayers for corrosion protection on aluminum and composite substrates are gaining specification complexity with electric vehicle battery enclosure requirements.
- Sealers:Cavity wax and seam sealant products serve corrosion protection in underbody and structural applications with lower per-liter margins than decorative coating layers.
Clearcoats hold installed capacity. Basecoats are rotating up the share rankings.
Technology:
Water-based systems concentrate new OEM specification wins while solvent-based formulations retain defensive positions in aftermarket channels where drying speed commands priority.
- Water-based:These formulations dominate new OEM installations across Germany and France under EU Green Deal lifecycle mandates extending carbon footprint accounting to coating operations. REACH compliance accelerates adoption in high-volume assembly plants, though drying limitations constrain penetration in commercial vehicle refinishing.
- Solvent-based:Conventional systems preserve share in aftermarket refinishing where cure rate requirements outweigh emissions compliance costs. VOC-intensive formulations face tightening ECHA authorization procedures for aromatic solvents.
- Powder Coating:Zero-VOC profiles and material utilization above 95 percent extend these systems into wheel and underbody applications previously served by liquid coatings.
- UV Curable:Rapid cure through ultraviolet radiation enables premium OEM lines to reduce energy consumption and footprint, with German luxury manufacturers specifying these technologies for production ramp-up.
Water-based systems command new specification volume. Powder coating is climbing the fastest in wheel and underbody conversion.
Application:
OEM channels concentrate absolute value pools while aftermarket operations offer higher per-liter margins through distributor-controlled pricing and labor-dependent service delivery.
- OEMs:Original equipment manufacturing absorbs the largest coating volume through automated application lines in German production clusters. Bavaria and Baden-Württemberg drive premium coating consumption with centralized technical purchasing functions specifying raw material grades directly.
- Aftermarket:Refinishing channels yield superior per-liter margins through body-shop relationships and distributor pricing control, though skilled applicator scarcity constrains capacity expansion.
- Commercial Vehicles:Truck and bus manufacturing in France and Eastern Europe maintains solvent-based preference where production speed dominates regulatory compliance priorities.
- Passenger Vehicles:Light vehicle production across German, French, and Spanish facilities generates the foundational demand base for coating system development and specification.
OEMs anchor volume scale. Aftermarket is gaining share fastest in margin contribution.
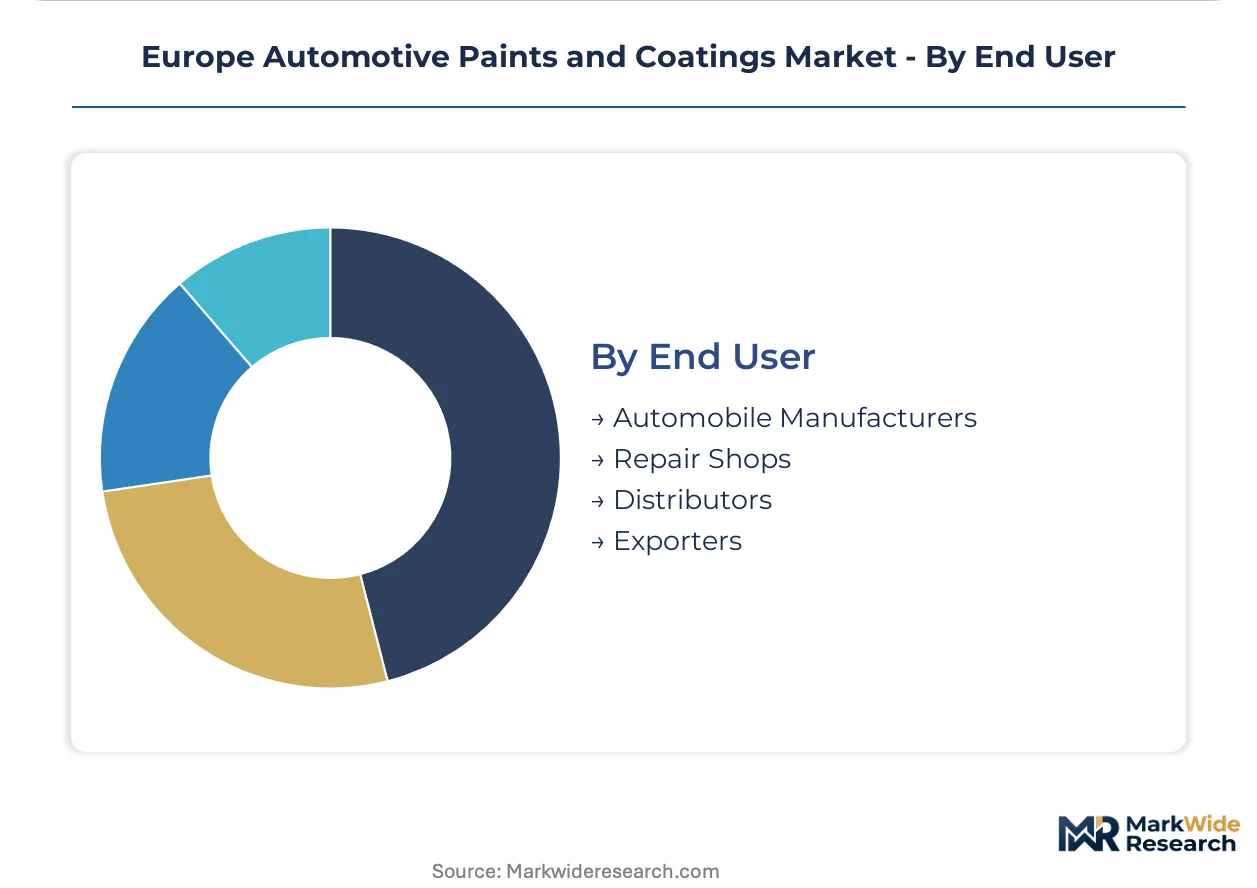
End User:
Automobile manufacturers concentrate specification authority while repair shops and distributors compete for margin capture in fragmented service channels.
- Automobile Manufacturers:BMW, Audi, Mercedes-Benz, and Volkswagen operate centralized technical purchasing in Bavaria and Baden-Württemberg, specifying resin grades and coating chemistries that bypass traditional formulator recommendations. Direct procurement relationships with specialty resin producers shorten distributor channels.
- Repair Shops:Independent and franchise body shops in France, Spain, and Italy depend on distributor networks for product access and technical support, creating margin capture opportunities for formulators with direct relationships.
- Distributors:Regional coating distributors control pricing and inventory in aftermarket channels across Southern and Eastern Europe where OEM specification influence weakens.
- Exporters:Cross-border coating suppliers serving Eastern European vehicle assembly plants from German and Benelux production bases navigate REACH compliance for intra-EU trade.
Automobile manufacturers hold specification authority. Repair shops are expanding their share of aftermarket value capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA substance restrictions and REACH authorization procedures anchor regulatory pressure across the region, with national implementations of EU directives creating differentiated compliance burdens that reshape coating demand patterns.
Germany
Bavarian OEM technical centers in Munich and Ingolstadt specify high-solids clearcoats for 2026 model year production, compressing supplier margins while demanding capital-intensive line modifications. The national implementation of the EU Industrial Emissions Directive adds plant-level compliance costs that favor larger integrated suppliers with centralized emission control infrastructure. Baden-Württemberg production clusters around Stuttgart drive premium coating consumption through BMW and Mercedes-Benz centralized purchasing functions.
France
Paris-based OEM engineering centers are expanding coating specifications for electric vehicle battery enclosures requiring thermal management properties on aluminum substrates. ANSM workplace exposure guidelines complement REACH restrictions on aromatic solvents, accelerating water-based system adoption in high-volume assembly plants. French OEM facilities face compressed transition timelines compared to German counterparts with earlier water-based investments.
Spain
Barcelona and Valencia automotive assembly plants maintain solvent-based preferences in commercial vehicle production where drying speed outweighs emissions compliance costs. Spanish regulatory authorities enforce REACH aromatic solvent restrictions with accelerated timelines that strain mid-tier formulator capabilities. Catalan coating distributors control aftermarket pricing in Southern European refinishing channels.
Italy
Turin and Milan automotive engineering hubs specify adhesion-promoting primer systems for lightweight composite substrates in premium electric vehicle platforms. Italian coating formulators navigate ECHA substance evaluations on isocyanate hardeners that compress product development cycles. Northern Italian industrial districts concentrate specialty resin production that supplies automotive clearcoat manufacturers.
United Kingdom
Midlands-based vehicle assembly operations source coatings through cross-border supply chains from German and Benelux production bases. UK REACH retains substance restriction frameworks that mirror EU authorization procedures, maintaining regulatory alignment for coating trade. British aftermarket refinishing channels depend on distributor networks with direct body-shop relationships for margin capture.
Europe Automotive Paints and Coatings Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Europe automotive paints and coatings market. The upper tier commands specification authority through direct OEM relationships and captive resin production, while mid-tier formulators compete on distributor channel access and regional service density. Strategic archetypes include integrated chemical conglomerates with backward integration into specialty resins, water-based technology specialists with centralized R&D hubs, and regional coating distributors controlling aftermarket pricing. Dominant competitive moves center on M&A to secure resin supply security and capacity expansion in automated OEM application line partnerships.
Among integrated chemical conglomerates, BASF SE and Covestro AG exemplify archetypes with upstream control over specialty resin production for automotive clearcoats. PPG Industries occupies a position within the water-based technology leadership tier through its centralized European R&D hub in the Netherlands. Akzo Nobel N.V. represents the premium OEM relationship archetype with deep specification ties to German luxury manufacturers. These three companies anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Axalta Coating Systems |
| Jotun |
| Akzo Nobel |
| Nippon Paint |
| Beckers Group |
| PPG Industries |
| The Sherwin-Williams Company |
| Covestro |
| BASF |
| Others |
Supply & Pricing Matrix
Water-based resin substitution for solvent-based aromatic systems is redrawing procurement geography from German chemical clusters toward Benelux specialty producers, simultaneously compressing formulator margins while elevating raw material cost transparency through direct OEM-resin relationships.
Pricing Analysis
Per-liter spreads between Bavarian OEM supply contracts and Southern European aftermarket channels exceed 40 percent, reflecting specification-controlled premium tiers versus distributor-negotiated volume discounts. Three-tier pricing structure across premium, standard, and economy levels separates high-solids clearcoat specifications from conventional basecoat formulations and commodity primer systems. Pricing pressure stems from REACH-driven reformulation costs that suppliers cannot fully pass through to German OEMs with consolidated purchasing leverage. Aftermarket refinishing channels exhibit highest price sensitivity due to fragmented body-shop buyer bases, while premium OEM technical centers demonstrate lowest sensitivity given performance-specification lock-in.
Supply Chain Analysis
Just-in-time resin delivery dominates German OEM corridors, though strategic stockpiling of isocyanate hardeners is spreading among formulators facing ECHA substance evaluation uncertainty. Geographic supply concentration centers on Germany, the Netherlands, and Belgium for specialty resin production, with Italy contributing adhesion-promoter chemical intermediates. Raw material dependencies include aliphatic isocyanates, acrylic polyols, and UV photoinitiators for emerging clearcoat technologies. Single-source vulnerability concentrates in ECHA-authorized aromatic solvent substitutes where patent-protected alternatives limit supplier switching. Distribution runs through integrated chemical conglomerates for OEM channels and regional coating distributors for aftermarket refinishing across France, Spain, and Italy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through German OEM technical purchasing centralization, with BMW, Audi, and Mercedes-Benz specification authority compressing formulator margins while fragmenting aftermarket channel control across Southern European distributor networks.
For Market Incumbents: Consolidate backward integration into captive resin production for automotive clearcoats, securing supply security against specialty resin concentration risks while building emission-control infrastructure to capture Industrial Emissions Directive compliance advantages in German production clusters. Deepen direct OEM engineering relationships in Bavaria and Baden-Württemberg to defend specification control against emerging water-based technology specialists. For New Entrants and Emerging Players: Differentiate on UV-curable and powder coating technology platforms where incumbent liquid formulation investments create capability gaps. Target Italian and Spanish aftermarket refinishing channels where distributor relationships remain fragmented and skilled applicator scarcity constrains incumbent capacity expansion. Pursue body-shop direct technical service models to bypass established distributor pricing control. For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors integrated chemical conglomerates with captive resin production and centralized emission infrastructure over mid-tier formulators facing reformulation cost spirals. Long-term viability over the next decade hinges on water-based technology leadership positions and direct OEM specification relationships. Monitor ECHA authorization timelines for isocyanate hardener substitutes as the critical inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resins | Captive supply of acrylic polyols and aliphatic isocyanates insulates against ECHA-driven raw material scarcity. |
| Water-Based Technology Capacity Expansion | New installation lines in German OEM facilities capture EU Green Deal lifecycle mandate compliance premiums. |
| Powder Coating Technology Partnerships | Zero-VOC wheel and underbody applications displace liquid coatings in high-utilization automotive segments. |
| Direct Body-Shop Distribution Networks | Aftermarket channel control in France and Italy captures margin pools beyond fragmented distributor pricing. |
| UV-Curable Clearcoat R&D Investment | German luxury OEM specifications for 2026 production cycles demand capital-intensive application line partnerships. |
Research Methodology
The analysis maps water-based, solvent-based, powder, and UV-curable coating technologies, each validated through coating formulator R&D directors, OEM platform engineers, aftermarket distributor procurement managers, and ECHA regulatory affairs specialists. Primary interview intelligence combined with secondary validation from REACH substance registration databases, EU Industrial Emissions Directive implementation records, and vehicle production registration data. Bottom-up volume modeling across formulation technologies triangulates against top-down value estimates derived from chemical industry trade flows.
Consistency checks against external benchmarks validated projection outputs through cross-reference with customs trade data and automotive OEM supplier disclosure patterns. Segmentation dimensions span product type, technology platform, application channel, and end-user category across the projection horizon. CAGRs derived from regression analysis of historical volume trends adjusted for regulatory inflection points including ECHA authorization timelines and EU Green Deal implementation phases. Industry-specific inputs include coating content per vehicle by propulsion architecture and OEM tier classification.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement intensity or accelerated EU Green Deal carbon accounting expansion would require recalibration. Forecasts reflect documented assumptions regarding ECHA substance evaluation timelines and German OEM production cluster stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Canvas Primer Market
Paints & Coatings
Water Color Market
Paints & Coatings
Middle-East Paints and Coatings Market
Paints & Coatings
Global Aerosol Paints Market
Paints & Coatings
Global Exterior Architectural Coatings Market
Paints & Coatings
Global Texture Paint Market
Paints & Coatings
Mexico Paints and Coatings Market
Paints & Coatings
Paint Buckets Market
Paints & Coatings
Faux Paints and Coatings Market
Paints & Coatings
Global Decorative Paints and Coatings Market
Paints & Coatings
Paint and Coating Stripper Market
Paints & Coatings
Asia-Pacific Paint Thinner Market
Paints & Coatings
Polyurethane Resins Paints and Coatings Market
Paints & Coatings
Morocco Paints and Coatings Market
Paints & Coatings
Europe Paints and Coatings Additives Market
Paints & Coatings
Core Plate Varnishes Market