
 Global Anti-Formaldehyde Paint Market | 2026-2036
Global Anti-Formaldehyde Paint Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anti-Formaldehyde Paint Market Foresight
Buyer concentration among large construction firms and healthcare facility operators is realigning procurement standards toward certified zero-formaldehyde systems. AkzoNobel leverages its European distribution network to supply hospital renovation programs with low-emission coating systems. PPG Industries anchors North American demand through specialized furniture coating lines that meet LEED v4.1 interior air quality thresholds. SKSHU Paint dominates China's premium residential segment with water-based formulations engineered for humid subtropical climates.
Anti-formaldehyde paint denotes architectural and industrial coating systems formulated without formaldehyde-releasing preservatives or binders, typically achieving less than 0.01 ppm free formaldehyde content through modified acrylic-urethane hybrid chemistries. These coatings serve spaces demanding stringent indoor air quality, including pediatric wards, senior living facilities, and net-zero residential buildings. Water-based formulations lead volume shipments due to regulatory pressure on solvent-borne VOC emissions, while nano-technology enabled variants capture expanding margin pools in healthcare and cleanroom applications. Furniture manufacturers represent the fastest-growing end user industry as export compliance with REACH and California Air Resources Board standards becomes non-negotiable for market access.
EPA's TSCA Title VI formaldehyde emission standards for composite wood products have cascaded into coating adjacency requirements, while REACH's candidate list restrictions and the EU Green Deal's 2030 renovation wave targets are tightening permissible thresholds across member states. China's MEE enforces GB standards for indoor air pollutants that now explicitly reference coating contributions to formaldehyde loading. Stakeholders must monitor regulatory divergence between jurisdictions where mutual recognition agreements remain absent, as dual certification costs will determine competitive viability in cross-border project bidding.
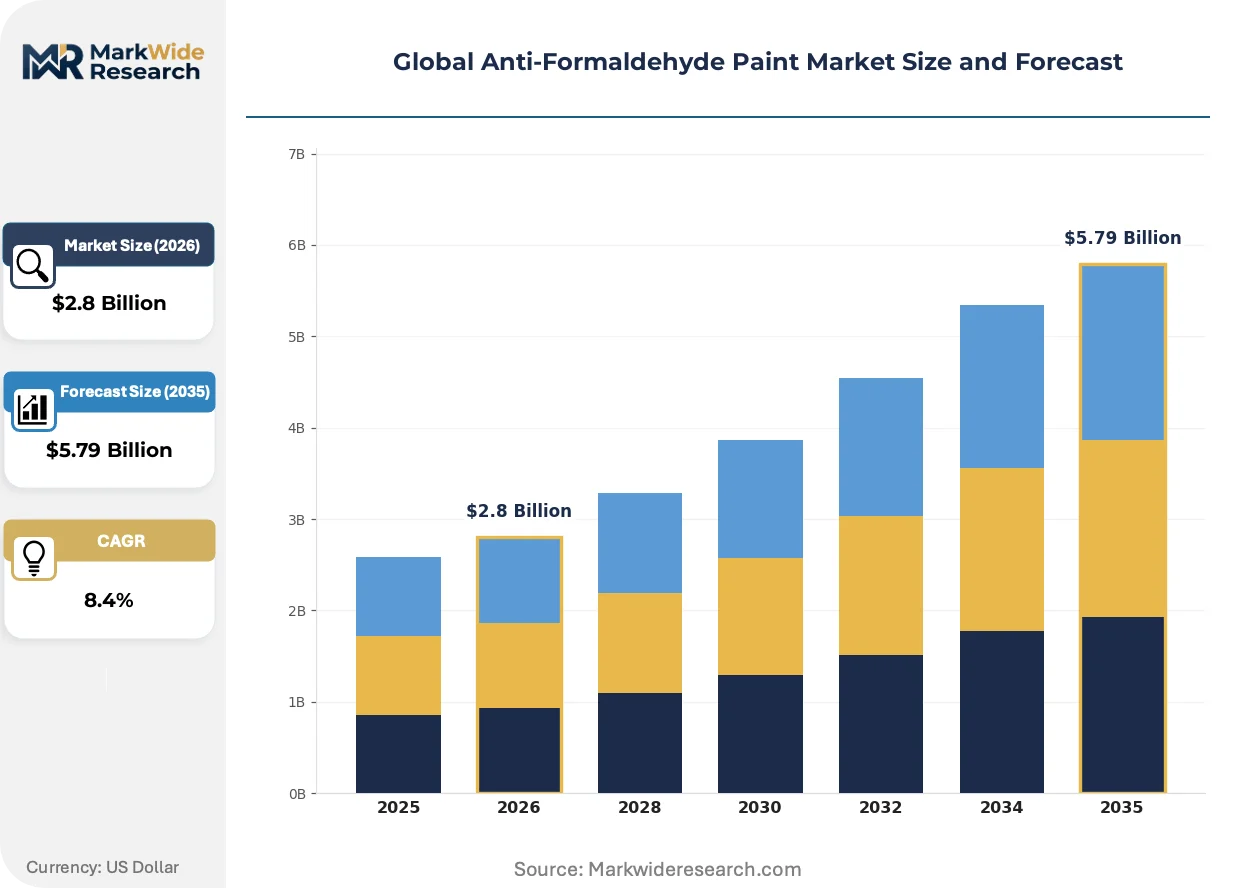
Market Dynamics
Regulatory divergence between the EPA's TSCA Title VI cascading requirements and the EU Green Deal's renovation wave targets is fragmenting formulation standards and forcing dual certification investments from manufacturers seeking cross-border project access.
Growth Catalysts
- EU Green Deal renovation mandates:The 2030 targets for building stock decarbonization are accelerating zero-emission coating specifications across German, French, and Dutch public procurement frameworks.
- Pediatric healthcare construction:Hospital operators in China's tier-one cities now specify sub-0.01 ppm formaldehyde thresholds for interior ward coatings as standard procurement language.
- Water-based acrylic-urethane hybrids:Modified polymer chemistries achieving equivalent durability to solvent-borne systems without formaldehyde-releasing preservatives are capturing specification share in humid subtropical climates.
Market Restraints
- Petrochemical feedstock volatility:Acrylic acid and isocyanate input costs swing formulation economics unpredictably, compressing margin visibility for water-based hybrid producers.
- Titanium dioxide supply concentration:Pigment sourcing dependence on Chinese sulfate-process capacity creates exposure to export licensing disruptions and environmental compliance shutdowns.
- Performance gaps in extreme climates:Zero-formaldehyde water-based systems exhibit accelerated chalking and adhesion failure in high-UV desert environments, limiting addressable geography.
Strategic Opportunities
- India's green building acceleration:GRIHA and IGBC certification penetration in Bengaluru and Hyderabad commercial towers remains below 15 percent, opening specification windows for compliant coating systems.
- Nano-silica antimicrobial convergence:Integration of photocatalytic surface treatments with zero-formaldehyde binders creates premium positioning for cleanroom and pharmaceutical manufacturing environments.
- Direct-to-furniture-manufacturer channels:Bypassing traditional distributor networks to serve export-oriented wood product fabricators in Vietnam and Indonesia reduces certification documentation friction.
Industry Challenges
- Formulation chemist scarcity:Expertise in hybrid polymer architecture and preservative-free stabilization sits concentrated with retiring specialists at European and Japanese coating majors.
- Dual certification timeline compression:Simultaneous EPA TSCA Title VI adjacency compliance and REACH candidate list navigation extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anti-Formaldehyde Paint Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Epoxy, Acrylic, Polyurethane Formulation Technology: Nano-Technology, Polymer Emulsion, UV Curable, Bio-Based, Silicone Modified Application: Interior Walls, Ceilings, Furniture Coatings, Automotive Finishes, Marine Coatings End User Industry: Construction Firms, Furniture Manufacturers, Vehicle Assemblers, Shipbuilders, Industrial Equipment Makers |
| Companies Covered | AkzoNobel, RPM International, Nippon Paint Holdings, Hempel, Axalta Coating Systems, Sherwin Williams, Jotun, SKSHU Paint, PPG Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anti-Formaldehyde Paint Market Shifts & Advancements
Active reformulation toward preservative-free binders and the convergence of air quality certification with digital building passports are compressing traditional specification cycles and elevating technical service intensity.
Photocatalytic nano-titanium dioxide integration is electrifying surface functionality in healthcare and cleanroom segments. Pediatric ward operators in Germany and the Netherlands now specify self-sanitizing wall systems as standard. This capability compression is forcing traditional zero-VOC suppliers to accelerate R&D partnerships or cede premium specification tiers.
REACH candidate list expansion into formaldehyde-releasing preservatives is triggering cascade reformulations across European manufacturing footprints. Coating producers serving IKEA supply chains and hospital renovation programs face immediate substitution deadlines. Furniture export certification to California Air Resources Board standards now requires explicit preservative disclosure documentation previously absent from technical data sheets.
Building information modeling integration with material passport databases is altering specification workflows for large construction consortia. Skanska and Hochtief procurement platforms now auto-reject coating submissions lacking third-party formaldehyde emission test reports. This digitization is most visible in Nordic markets where municipal clients mandate open-source material traceability for public building contracts.
Global Anti-Formaldehyde Paint Market Segmentation
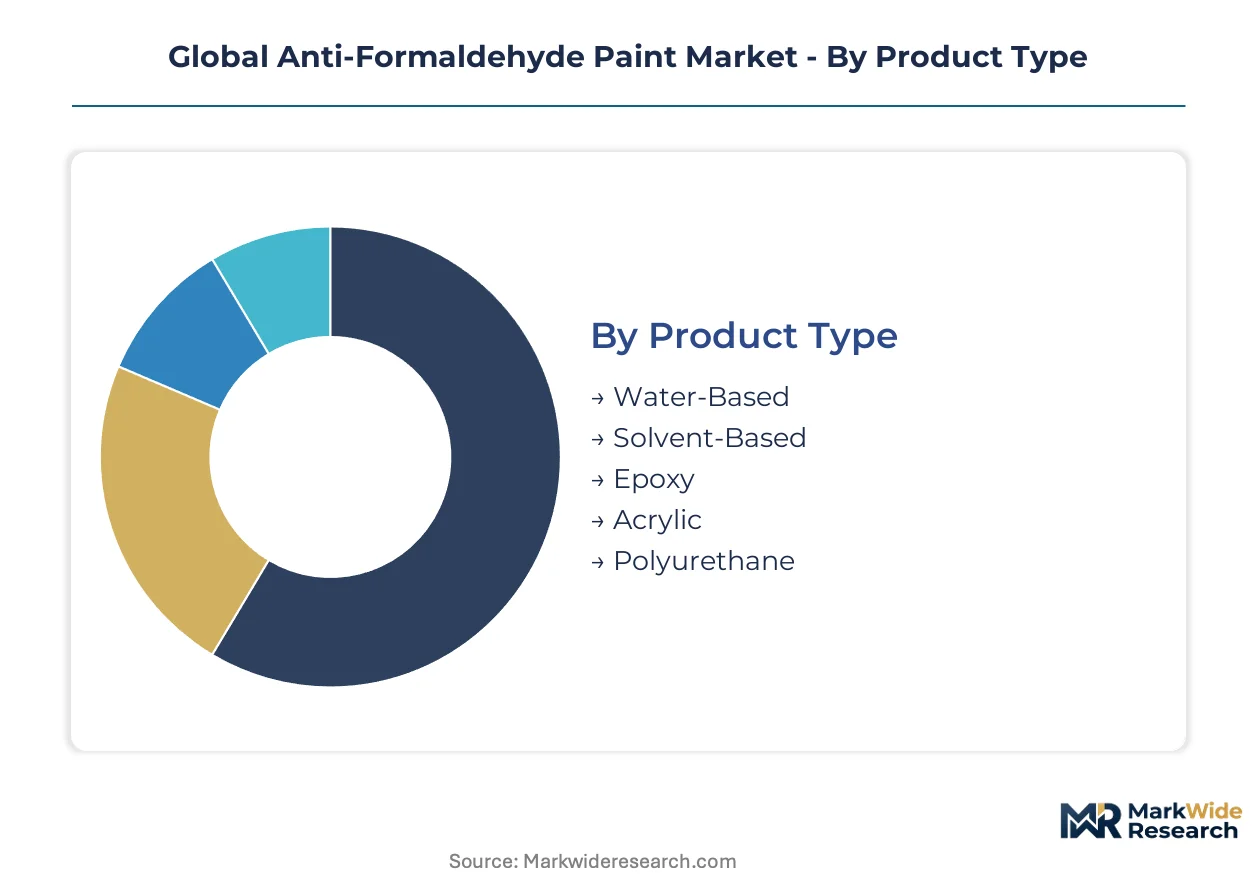
Formulation chemistry and certification thresholds fragment procurement specifications across end-use verticals. Buyers prioritize emission documentation, climate durability, and application efficiency when selecting coating systems for sensitive environments.
Product Type:
Application environment dictates binder selection, with humidity exposure and substrate compatibility driving technical requirements.
- Water-Based:Acrylic-urethane hybrid dispersions achieve sub-0.01 ppm formaldehyde content through preservative-free stabilization. Demand concentrates in China's tier-one cities where GB standards mandate coating contributions to indoor air quality, and in German hospital renovation programs specifying LEED v4.1 compliance.
- Solvent-Based:Alkyd and urethane systems modified with formaldehyde-free crosslinkers retain application in marine and industrial settings where water-based alternatives fail on corrosion resistance. Regulatory pressure from EPA VOC ceilings and EU solvent emission directives is compressing specification share in residential and commercial interiors.
- Epoxy:Two-component amine-cured systems serve pharmaceutical cleanrooms and food processing facilities requiring chemical resistance without formaldehyde-releasing hardeners.
- Acrylic:Pure acrylic emulsions dominate furniture coating lines serving California Air Resources Board export compliance.
- Polyurethane:Aliphatic urethane topcoats protect high-traffic healthcare corridors from abrasion and sterilization chemical exposure.
Volume sits with Water-Based systems; growth tilts toward Epoxy as pharmaceutical manufacturing expands in India and Southeast Asia.
Formulation Technology:
Performance tier and price positioning separate across technology platforms, with premium functionality commanding specification in regulated environments.
- Nano-Technology:Photocatalytic titanium dioxide integration enables self-sanitizing surfaces for pediatric wards in Germany and the Netherlands. These systems capture margin pools in healthcare where infection control documentation determines procurement awards.
- Polymer Emulsion:Core water-based platform serving volume residential construction across humid subtropical climates where modified acrylic-urethane hybrids prevent adhesion failure.
- UV Curable:Instant-cure systems reduce line downtime for furniture manufacturers in Vietnam and Indonesia facing export certification deadlines.
- Bio-Based:Plant-derived binders from soybean and castor oil feedstocks address Scope 3 emission targets for Nordic municipal construction contracts.
- Silicone Modified:Enhanced weatherability coatings protect exterior substrates in high-UV desert environments where standard water-based systems exhibit accelerated chalking.
Polymer Emulsion dominates shipment volumes; Nano-Technology is climbing the fastest as cleanroom and hospital specifications harden.
Application:
Substrate geometry and exposure conditions determine film thickness requirements, cure protocols, and recoating windows.
- Interior Walls:Flat and eggshell finishes for residential and commercial spaces where air quality certification drives specification toward zero-formaldehyde systems with third-party test documentation.
- Ceilings:High-hide formulations with sag resistance for healthcare and educational facilities requiring mold-resistant surface treatments without formaldehyde-releasing biocides.
- Furniture Coatings:The steepest expansion trajectory as export-oriented wood product fabricators in Vietnam and Indonesia face dual REACH and California Air Resources Board compliance mandates.
- Automotive Finishes:Basecoat-clearcoat systems for interior trim components where OEMs enforce material passport traceability.
- Marine Coatings:Anti-corrosive primers and topcoats for ship interiors where IMO guidelines on indoor air quality converge with flag state regulations.
Interior Walls command the largest addressable base; Furniture Coatings is gaining share fastest on export compliance pressure.
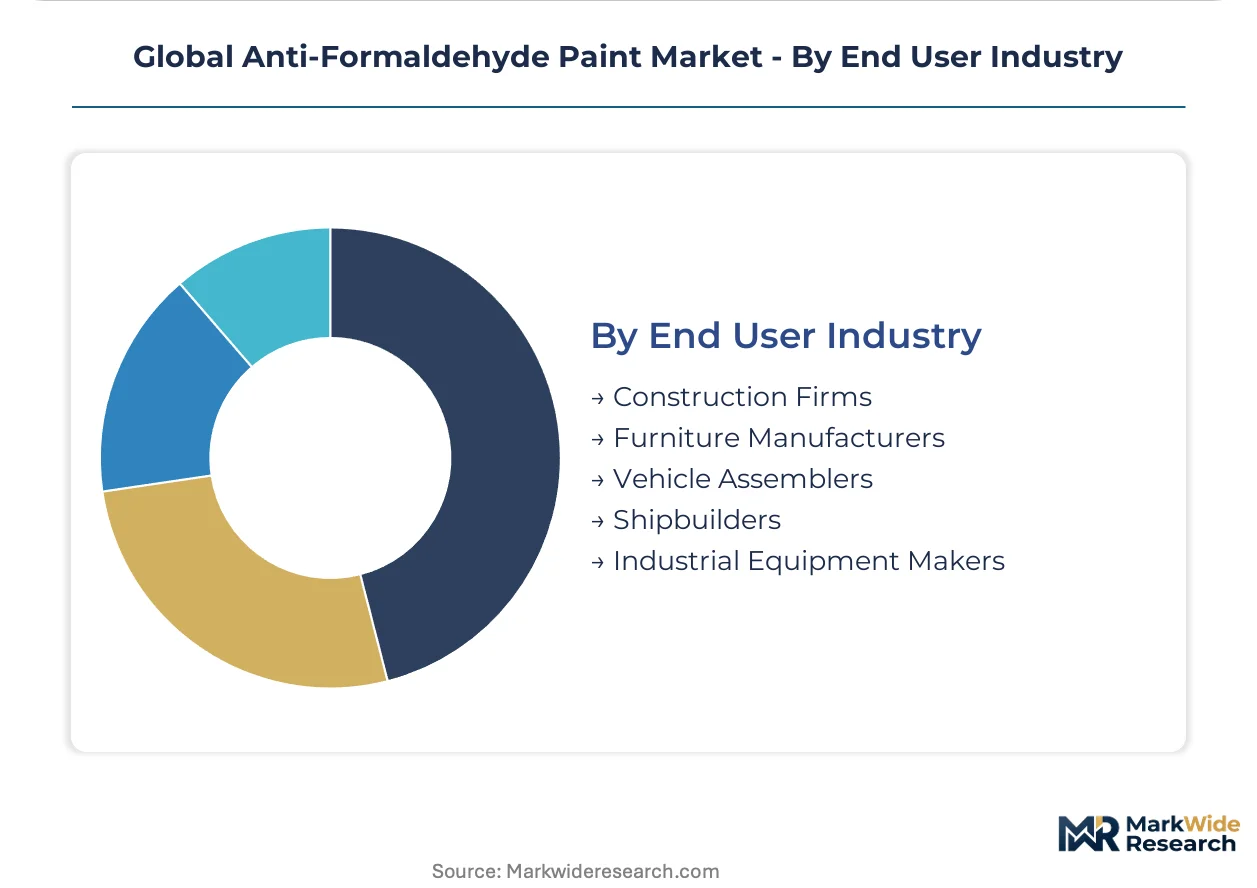
End User Industry:
Procurement sophistication varies sharply, with specification authority resting at different organizational levels across verticals.
- Construction Firms:Large consortia like Skanska and Hochtief mandate digital material passports with formaldehyde emission test reports, auto-rejecting non-compliant submissions.
- Furniture Manufacturers:Export-dependent fabricators prioritize dual certification documentation to maintain IKEA supply chain access and California market entry.
- Vehicle Assemblers:OEM material compliance teams enforce IMDS reporting for interior coating systems.
- Shipbuilders:Classification society approval processes for coating systems used in accommodation spaces.
- Industrial Equipment Makers:Food processing and pharmaceutical machinery requiring FDA-compliant surface finishes.
Construction Firms anchor current procurement volume; Furniture Manufacturers show the steepest specification growth on regulatory compliance timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the steepest demand trajectory for zero-formaldehyde coatings. Tier-one cities enforce GB standards mandating sub-0.01 ppm formaldehyde contributions from interior finishes. Shanghai and Beijing construction consortia now auto-reject coating submissions lacking third-party emission documentation.
China
GB standards from MEE explicitly reference coating contributions to indoor air pollutant loading. Pediatric ward operators in Shanghai and Beijing specify sub-0.01 ppm thresholds as standard procurement language. SKSHU Paint anchors premium residential demand through water-based formulations engineered for humid subtropical climates.
Germany
Residential construction firms expand procurement of zero-emission interior coatings for hospital renovation programs. EU Green Deal renovation wave targets accelerate reformulation investments across manufacturing footprints. Hochtief procurement platforms auto-reject submissions lacking formaldehyde emission test reports.
United States
Furniture manufacturers face California Air Resources Board compliance mandates for export market access. EPA TSCA Title VI formaldehyde emission standards cascade into coating adjacency requirements for composite wood products. LEED v4.1 interior air quality thresholds drive specification in commercial construction clusters.
Netherlands
Skanska mandates digital material passports with open-source traceability for municipal building contracts. Pediatric ward operators specify self-sanitizing wall systems as standard procurement language. Municipal clients enforce documentation requirements that compress traditional specification cycles.
India
GRIHA and IGBC certification penetration in Bengaluru and Hyderabad commercial towers remains below 15 percent. Central pollution control directives tighten permissible emission thresholds for interior finishes. Export-oriented wood product fabricators face dual compliance timelines for European and North American market access.
Global Anti-Formaldehyde Paint Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue nano-technology enabled variants and bio-based formulations. The vendor base clusters around three strategic archetypes: European coating majors with hospital renovation specialization, Asia-Pacific water-based hybrid suppliers, and North American furniture coating specialists. Dominant competitive moves include dual certification investments for cross-border project access and direct-to-manufacturer channel development in Southeast Asian export hubs.
Among European coating majors, AkzoNobel leverages distribution infrastructure for healthcare facility programs. PPG Industries anchors North American demand through furniture coating lines. SKSHU Paint occupies the premium residential position in China's tier-one cities. These three exemplify the geographic specialization that fragments competitive positioning across regulatory jurisdictions.
| Leading Market Players |
|---|
| AkzoNobel |
| RPM International |
| Nippon Paint Holdings |
| Hempel |
| Axalta Coating Systems |
| Sherwin Williams |
| Jotun |
| SKSHU Paint |
| PPG Industries |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap coating specialists across Germany and Japan anchor supply discipline through generational capital allocation patterns that resist short-term pricing volatility. Their concentrated ownership structures enable decade-long formulation investments that commodity traders cannot replicate, compressing margin recovery timelines for private-equity-rolled competitors.
Pricing Analysis
Volume shipments cluster in standard water-based acrylic-urethane hybrids where price differentiation hinges on certification grade and volume scale. Premium nano-technology enabled variants command specification in German and Dutch pediatric wards where infection control documentation determines procurement awards. Cost compression in standard tiers intensifies because titanium dioxide sourcing dependence on Chinese sulfate-process capacity exposes producers to export licensing disruptions. Furniture manufacturers in Vietnam and Indonesia show the highest price sensitivity, while hospital operators in China's tier-one cities prioritize emission documentation over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Skanska and Hochtief procurement platforms mandate multi-supplier qualification for formaldehyde emission test documentation. Manufacturing concentrates in China, Germany, and the Netherlands where REACH candidate list compliance and EPA TSCA Title VI adjacency standards converge. Acrylic acid, isocyanate, and nano-titanium dioxide feedstocks draw from petrochemical complexes and specialty chemical producers. Single-source vulnerability in Chinese titanium dioxide sulfate-process capacity threatens pigment availability. Distribution runs through regional coating distributors serving construction consortia and direct-to-manufacturer channels for export-oriented furniture fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anti-formaldehyde paint market operates as a vertical-integration race where upstream control over preservative-free binder chemistries and downstream digital material passport capabilities determine competitive viability.
For Market Incumbents: Deepen captive supply of modified acrylic-urethane hybrid dispersions to offset petrochemical feedstock volatility. Expand technical service teams in China's tier-one cities where GB standard compliance documentation determines specification outcomes. Acquire nano-technology specialists before photocatalytic self-sanitizing surfaces displace standard zero-VOC offerings in European healthcare procurement. For New Entrants and Emerging Players: The price-point gap between premium nano-technology systems and economy water-based hybrids opens specification windows in India's green building acceleration. Target Bengaluru and Hyderabad commercial towers where GRIHA and IGBC certification penetration remains below fifteen percent. Pursue direct-to-furniture-manufacturer channel development in Vietnam and Indonesia to bypass distributor margin extraction. For Investors and Strategic Acquirers: Distressed-cycle entries favor European coating majors with hospital renovation specialization and stranded REACH compliance investments. Five-to-ten year viability hinges on dual certification asset bases that bridge EPA and EU regulatory divergence. Watch for MEE enforcement intensity in Shanghai and Beijing as the inflection indicator for Chinese demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Preservative-Free Binder Production | AkzoNobel and SKSHU Paint secure supply continuity against REACH candidate list expansion. |
| Nano-Technology R&D Partnership | Photocatalytic titanium dioxide integration captures premium specification in German pediatric wards. |
| Dual Certification Investment | Simultaneous EPA TSCA Title VI and REACH compliance enables cross-border project bidding. |
| Direct-to-Manufacturer Channel Development | Bypassing distributors reduces documentation friction for Vietnam furniture export compliance. |
| Digital Material Passport Integration | Skanska and Hochtief procurement platforms auto-reject submissions lacking emission test reports. |
Research Methodology
Trade association filings from the American Coatings Association, Cefic sector reports, and SEC 10-K disclosures from listed chemical producers formed the secondary backbone. Primary interviews with formulation chemists, procurement leads at German construction consortia, and technical directors at Asia-Pacific water-based hybrid suppliers combined with bottom-up and top-down triangulation across shipment data and regulatory filing analysis.
Historical trendline analysis of water-based versus solvent-borne specification share informed the projection framework across the analysis window. Segmentation dimensions modeled include formulation chemistry, certification threshold, end-use vertical, and regional regulatory cluster. CAGRs derived from regression analysis of construction spend correlation and green building certification penetration rates. Forecast inputs incorporated MEE enforcement intensity projections and EU Green Deal renovation wave target implementation timelines.
Inputs from construction consortia procurement platforms were available through the study window; gaps in real-time titanium dioxide export licensing data introduce uncertainty bands around pigment cost assumptions. Deviation in REACH candidate list expansion timing or EPA TSCA Title VI adjacency rulemaking would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Food Grade Epoxy Paint Market
Paints & Coatings
Sri Lanka Paints and Coatings Market
Paints & Coatings
United Arab Emirates (UAE) Paints and Coatings Market
Paints & Coatings
Water-Borne Latex Paints Market
Paints & Coatings
Furniture Wood Coatings Market
Paints & Coatings
Paints and Coatings Additives Market
Paints & Coatings
Low VOC Paint Market
Paints & Coatings
Polyolefin Resin Paints Market
Paints & Coatings
Bituminous Paints Market
Paints & Coatings
India Floor Coatings Market
Paints & Coatings
Aircraft Paint Market
Paints & Coatings
Solar Paint Market
Paints & Coatings
Asia-Pacific Paint Spray Guns Market
Paints & Coatings
Floor Paints Market
Paints & Coatings
Cellulose Paints Market
Paints & Coatings
India Automotive OEM Coatings Market