
 Leno Bags Market | 2026-2036
Leno Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Leno Bags Market Foresight
Asset-light leasing models for woven bag manufacturing equipment are tilting competitive dynamics toward mid-scale regional producers. Singhal Industries leverages its Gujarat-based vertical integration to control polypropylene resin sourcing costs. Mondi Group sustains European demand through certified recyclable leno bag lines aligned with EU Green Deal targets. Commercial Syn Bags Ltd. anchors South Asian export volumes with specialized UV-resistant formulations for tropical agriculture.
Leno bags are woven polyolefin containers characterized by their open-mesh construction, typically manufactured with 8×8 to 10×10 weave density per square inch to enable airflow while containing bulk solids. The primary purpose spans agricultural commodity storage, retail produce display, and industrial parts handling where ventilation prevents moisture accumulation. Gusseted bags lead volume share due to their expanded cubic capacity for root vegetables, while biodegradable material variants represent the fastest-expanding margin pool as European retailers enforce packaging waste directives. Flat bags occupy a mature position in basic grain handling where price sensitivity limits feature differentiation.
BIS certification requirements in India and REACH compliance obligations across Europe are reshaping resin additive formulations and recyclability claims. FDA food-contact standards in the United States govern export-bound leno bags entering North American produce distribution channels. Stakeholders must monitor evolving extended producer responsibility frameworks in key importing jurisdictions to anticipate material specification shifts before they disrupt supply qualifications.
Market Dynamics
Asset-light leasing models for woven bag manufacturing equipment are tilting competitive dynamics toward mid-scale regional producers who can bypass capital-intensive greenfield investments.
Growth Catalysts
- EU Green Deal packaging waste directives:European retailers are mandating certified recyclable leno bag lines, creating pull-through demand for polypropylene formulations with verified recyclability credentials.
- Perishable crop storage modernization:Agricultural buyers across India and Southeast Asia are shifting toward ventilated woven packaging to reduce post-harvest losses in onion and potato supply chains.
- BIS certification tightening:India's Bureau of Indian Standards is enforcing stricter material specifications for food-contact plastics, disqualifying non-compliant imports and protecting domestic qualified suppliers.
Market Restraints
- Polypropylene resin price volatility:Feedstock costs tied to crude oil derivatives expose converters to margin compression when naphtha prices spike.
- Gujarat-Maharashtra supply concentration:India's onion and potato processing clusters concentrate bulk procurement in two states, creating regional demand vulnerability during monsoon disruptions.
- Biodegradable material performance gaps:Starch-based alternatives lack the tensile strength and UV resistance of polypropylene, limiting substitution in tropical agriculture applications.
Strategic Opportunities
- Extended producer responsibility frameworks:France's AGEC law and similar EU packaging regulations are creating premium pricing tiers for closed-loop recyclable leno bag systems.
- Industrial parts handling expansion:Automotive component manufacturers are adopting ventilated woven containers for moisture-sensitive metal parts in Just-in-Sequence logistics.
- Equipment leasing channel innovation:Pay-per-output manufacturing contracts are enabling mid-scale entrants to serve fragmented agricultural co-operatives without balance-sheet strain.
Industry Challenges
- REACH compliance timeline compression:European Chemicals Agency substance-of-very-high-concern listings are forcing rapid reformulation of UV stabilizers and slip agents.
- Weave density calibration expertise:Optimizing 8×8 to 10×10 mesh configurations for specific crop aeration requirements demands specialized textile engineering talent in short supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leno Bags Market |
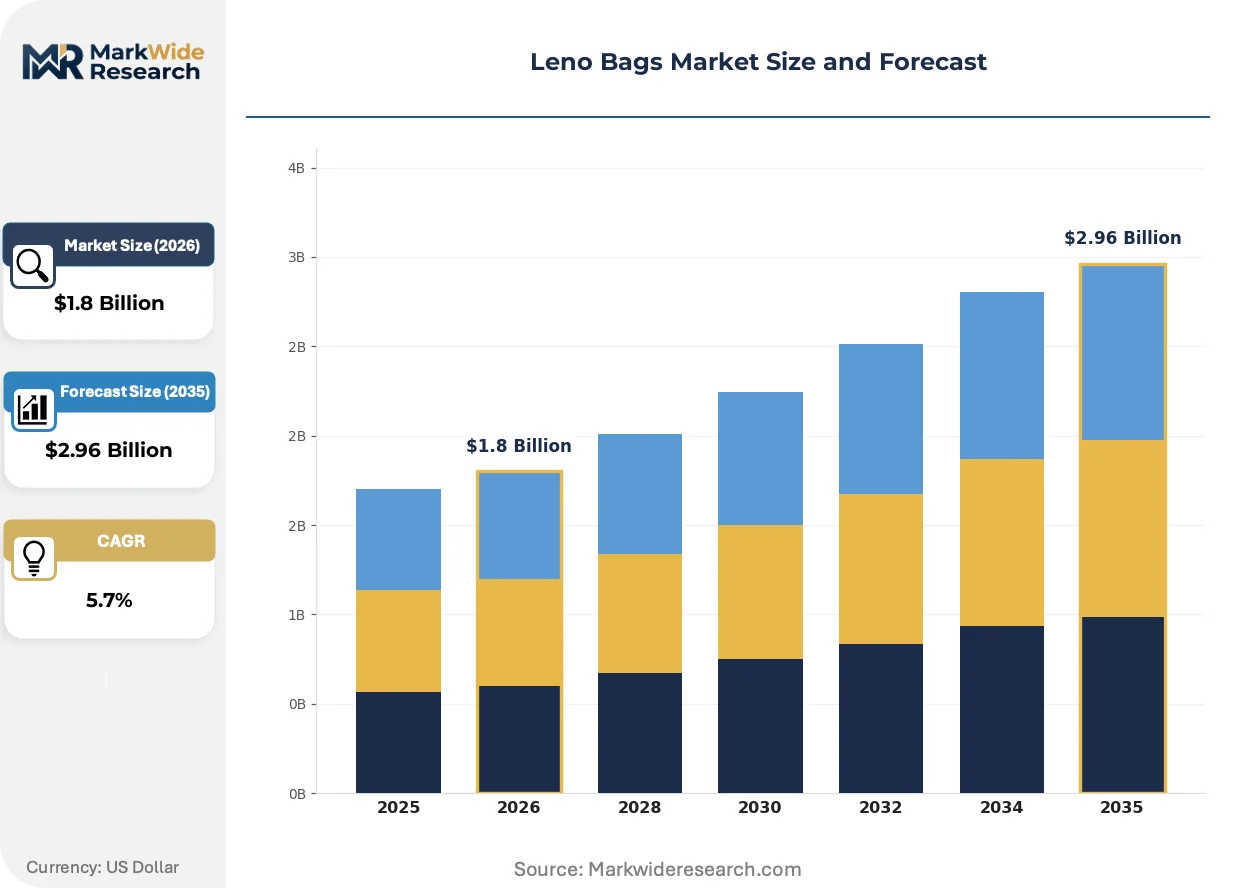
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Gusseted Bags, Drawstring Bags, Mesh Bags Material: Polyethylene, Polypropylene, Nylon, Jute End User: Agriculture, Retail, Packaging, Transportation Feature: Recyclable, Biodegradable, Durable, UV Resistant |
| Companies Covered | Singhal Industries, Muscat Polymers Pvt. Ltd., Commercial Syn Bags Ltd., Volm Companies, Rathi Packaging, LC Packaging, Starlinger Group, Mondi Group, Shree Tirupati Balajee FIBC Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leno Bags Market Shifts & Advancements
Three intersecting developments are restructuring how leno bags are specified, procured, and valued across agricultural and industrial supply chains.
Co-extruded multilayer polypropylene films with integrated anti-fog and anti-static properties are collapsing the performance gap between conventional leno mesh and laminated alternatives. Dutch greenhouse operators and German food distributors are specifying these hybrid constructions for high-value produce display where condensation control matters. The technology is collapsing premium pricing for basic laminated bags by delivering equivalent functionality at woven-bag cost structures.
India's BIS certification mandates for food-contact plastics are forcing additive package disclosures from resin suppliers. Formulators must now document compliance with migration limits for heavy metals and primary aromatic amines. Export-oriented converters in Gujarat are responding by qualifying captive resin streams rather than relying on spot market polypropylene with uncertain certification trails.
Co-operative procurement consortia are aggregating smallholder agricultural demand into specification-grade volume blocks. Maharashtra onion growers and Bangladesh jute processors are bypassing traditional distributor markups through direct mill relationships. This consolidation is most visible in India's western states where farmer producer organizations have achieved sufficient scale to negotiate custom gusset dimensions and printed branding.
Leno Bags Market Segmentation
Leno bag specifications diverge sharply between commodity agriculture and premium retail channels, with weave density, material grade, and certification status determining procurement decisions across each vertical. Understanding these segment boundaries clarifies where margin pools concentrate versus where price competition erodes returns.
Product Type:
Use-case spectrum spans basic grain containment through branded retail display, with cubic capacity and handling convenience driving specification choices.
- Flat Bags:Simple two-dimensional construction with sealed bottom and open top, optimized for basic grain and seed handling where minimal aeration suffices. India's Punjab wheat cooperatives specify flat configurations for direct combine-to-storage workflows, accepting lower ventilation in exchange for unit cost minimization.
- Gusseted Bags:Side-folding panels expand cubic capacity by 30-40% for irregular root vegetables, with reinforced corners supporting palletized stacking. Gujarat onion processors and Maharashtra potato packers drive bulk procurement of 50kg gusseted polypropylene leno bags, prioritizing dimensional stability during monsoon-season transport.
- Drawstring Bags:Integrated closure mechanisms eliminate manual tying for retail produce display and consumer convenience applications.
- Mesh Bags:Maximum openness configurations for high-moisture crops requiring rapid evaporation, common in Southeast Asian tropical vegetable supply chains.
The dominant share belongs to Gusseted Bags, while Biodegradable material variants are closing the gap fastest.
Material:
Cost tier stratification separates commodity polyolefins from performance-engineered alternatives, with resin certification trails increasingly gatekeeping market access.
- Polyethylene:Lower-density formulations offer flexibility and moisture resistance for short-cycle retail applications. European fresh-produce distributors specify certified recyclable polyethylene leno constructions to satisfy France's AGEC law and extended producer responsibility frameworks.
- Polypropylene:Superior tensile strength and UV stability dominate agricultural bulk handling, with homopolymer grades preferred for tropical exposure. India's BIS certification mandates for food-contact plastics are forcing additive package disclosures from polypropylene resin suppliers, advantaging converters with captive supply chains.
- Nylon:High-abrasion resistance for industrial parts handling and repeated-use logistics applications.
- Jute:Natural fiber alternatives for biodegradable claims and specific export market preferences, limited by moisture susceptibility.
Polypropylene commands volume leadership, though polyethylene is gaining fastest in European retail channels.
End User:
Customer type fragmentation concentrates procurement power in agricultural co-operatives while retail chains drive specification innovation.
- Agriculture:Post-harvest storage and field-to-market transport for onions, potatoes, garlic, and tropical vegetables, with ventilation preventing sprouting and rot. India's Gujarat and Maharashtra processing clusters aggregate demand through farmer producer organizations negotiating custom dimensions.
- Retail:Branded produce display and consumer-facing packaging where aesthetics and sustainability credentials influence specification. German food distributors and Dutch greenhouse operators prioritize anti-fog hybrid constructions for high-value produce presentation.
- Packaging:Industrial and commercial protective containment for moisture-sensitive goods.
- Transportation:Logistics-sector applications for bulk commodity movement and intermodal handling.
Agriculture retains the largest procurement volumes, yet Retail specifications are climbing fastest as sustainability mandates tighten.
Feature:
Margin differentiation increasingly attaches to certification-backed performance claims rather than base material functionality.
- Recyclable:Verified polypropylene formulations with established reprocessing pathways, essential for EU Green Deal compliance. Mondi Group and comparable European converters maintain certified recyclable leno bag lines aligned with retailer sustainability procurement criteria.
- Biodegradable:Starch-based and bio-polymer alternatives for single-use applications with composting infrastructure, though tropical agriculture limits substitution due to tensile strength and UV resistance gaps.
- Durable:Reinforced weave densities and additive packages for multi-season reuse and harsh handling conditions.
- UV Resistant:Stabilized formulations preventing polymer degradation during extended outdoor storage, critical for Commercial Syn Bags Ltd.'s Southeast Asian export volumes.
Durable specifications dominate current procurement, while Recyclable certifications are expanding most quickly under regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agricultural co-operatives and industrial packers concentrate procurement across distinct regional clusters, with regulatory frameworks and crop processing infrastructure determining specification requirements. Buyer archetypes shift from smallholder aggregators in South Asia to certified-sustainability retailers in Western Europe.
India
Gujarat and Maharashtra onion-potato processors drive bulk procurement of gusseted polypropylene leno bags through farmer producer organizations. BIS certification mandates for food-contact plastics tighten material specifications and additive disclosures. Ahmedabad and Nashik processing clusters negotiate custom dimensions and printed branding directly with converters.
Germany
Food distributors and greenhouse operators specify anti-fog hybrid constructions for high-value produce display where condensation control matters. EU Green Deal packaging waste directives mandate certified recyclable leno bag lines with verified reprocessing pathways. Hamburg logistics hubs aggregate demand for industrial parts handling applications in automotive Just-in-Sequence supply chains.
United States
Produce distribution channels require FDA food-contact compliance for import-bound leno bags entering North American markets. California Central Valley agricultural packers and Florida vegetable shippers source ventilated woven containers for perishable crop storage. Midwest grain cooperatives specify flat bag configurations for cost-minimized bulk handling.
Netherlands
Dutch greenhouse operators and flower bulb exporters prioritize co-extruded multilayer films with integrated anti-fog properties. Extended producer responsibility frameworks under France's AGEC law create premium pricing tiers for closed-loop recyclable systems. Rotterdam port logistics integrate leno containers into intermodal bulk commodity movements.
Vietnam
Tropical vegetable supply chains in the Mekong Delta specify maximum-openness mesh configurations for rapid moisture evaporation. Commercial Syn Bags Ltd. anchors Southeast Asian export volumes with UV-resistant formulations for extended outdoor storage. Ho Chi Minh City processing clusters aggregate demand from regional agricultural exporters.
Leno Bags Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement channels. The vendor base spans integrated resin-to-bag converters, regional weaving specialists, and equipment-leasing intermediaries. Three archetypes dominate: vertically integrated resin controllers, certification-focused sustainability specialists, and asset-light regional fabricators. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure additive-compliant resin streams and co-operative procurement relationships.
Among India-based integrated producers, Singhal Industries exemplifies the captive resin supply archetype with Gujarat-based vertical control over polypropylene sourcing. Commercial Syn Bags Ltd. represents the tropical-export specialist segment, while Mondi Group occupies the certified-sustainability tier aligned with EU Green Deal procurement criteria. These three anchors illustrate how geographic positioning and regulatory compliance capabilities determine competitive access across distinct buyer segments.
| Leading Market Players |
|---|
| Singhal Industries |
| Muscat Polymers Pvt. Ltd. |
| Commercial Syn Bags Ltd. |
| Volm Companies |
| Rathi Packaging |
| LC Packaging |
| Starlinger Group |
| Mondi Group |
| Shree Tirupati Balajee FIBC Ltd. |
| Others |
Supply & Pricing Matrix
Mundra Port freight corridors connecting Gujarat to European distribution hubs transmit polypropylene resin cost volatility directly into downstream leno bag pricing tiers. This logistics channel concentrates supply-side leverage among converters with captive resin streams while fragmenting price negotiation power across agricultural co-operative buyers.
Pricing Analysis
Cost-plus contracts indexed to naphtha derivatives dominate procurement between resin suppliers and woven bag converters. Three-tier pricing structure across premium, standard, and economy levels separates EU Green Deal certified recyclable lines from basic agricultural grades. Cost compression in standard-tier polypropylene gusseted bags is intensifying because of feedstock price swings and mid-scale regional entrant competition. India's farmer producer organizations exhibit highest price sensitivity, while Dutch greenhouse operators prioritize condensation-control specifications over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Ahmedabad-based resin distributors are compressing working capital cycles for Maharashtra weaving clusters. Manufacturing concentrates in India, China, and Turkey, with polypropylene resin, UV stabilizer additives, and loom equipment as critical inputs. Single-source vulnerability in homopolymer polypropylene qualification for BIS certification creates supply disruption exposure. Distribution runs through agricultural co-operative procurement consortia and European retail sustainability procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward agricultural co-operatives as Maharashtra and Gujarat farmer producer organizations consolidate fragmented smallholder demand into specification-grade volume blocks.
For Market Incumbents: Harden certification-backed supply positions by qualifying captive polypropylene resin streams for BIS food-contact compliance. Deepen channel control through direct mill relationships with onion and potato processing clusters to offset equipment-leasing entrant competition. For New Entrants and Emerging Players: Establish a beachhead in biodegradable leno bag segments serving European retail sustainability mandates where starch-based alternatives face performance gaps. Target Maharashtra farmer producer organizations with pay-per-output manufacturing contracts to bypass capital-intensive greenfield investments. For Investors and Strategic Acquirers: Regional weaving specialists with BIS-qualified captive resin supply represent the most defensible acquisition archetype for long-term viability. Watch for inflection signals in EU extended producer responsibility enforcement timelines that would accelerate premium pricing for closed-loop recyclable systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene Resin | Singhal Industries controls feedstock costs through Gujarat-based captive supply. |
| EU Green Deal Certification Investment | Mondi Group maintains recyclable leno bag lines aligned with retailer procurement criteria. |
| Equipment Leasing Channel Partnership | Mid-scale regional producers serve agricultural co-operatives without balance-sheet strain. |
| Co-operative Procurement Consortium Development | Maharashtra farmer producer organizations negotiate custom gusset dimensions directly. |
| Anti-Fog Hybrid Construction Launch | Dutch greenhouse operators specify co-extruded multilayer films for condensation control. |
Research Methodology
Cross-validation between primary interviews and secondary trade data anchors the qualitative findings in this study. Conversations with plant managers at Gujarat weaving facilities, procurement leads at Maharashtra agricultural co-operatives, distribution channel partners in European fresh-produce networks, and technical R&D directors at resin formulators informed demand-side dynamics. Secondary sources include customs and trade flow databases, BIS certification registries, EU packaging waste directive implementation reports, and SEC filings from listed packaging converters. Bottom-up volume estimates from regional processing clusters were triangulated against top-down market sizing from trade association aggregates.
Calibration against historical price elasticity and substitution patterns across agricultural packaging categories shaped the analytical framework. Segmentation dimensions modeled include product type, material grade, end-use vertical, certification status, and regional regulatory cluster. CAGRs were derived from fitted growth curves anchored to observed penetration rates and announced capacity additions. Industry-specific forecast inputs incorporate monsoon seasonality effects on Indian agricultural demand and EU extended producer responsibility implementation timelines.
Stress conditions across polypropylene resin price bands, BIS certification enforcement intensity, and EU Green Deal compliance acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about co-operative procurement consolidation trajectories and equipment-leasing model adoption. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Conical Bags Packaging Market
Bags and Containers
Freezing Bags Market
Bags and Containers
Dome Shrink Basket Bags Market
Bags and Containers
Lawn and Leaf Bags Market
Bags and Containers
Inclusion Bags Market
Bags and Containers
Conical Top Bulk Bag Market
Bags and Containers
Pasted Valve Bags Market
Bags and Containers
Anti-Static Polyethylene Bag Market
Bags and Containers
Child Resistant Bags Market
Bags and Containers
Side Gusset/Quad Seal Bag Market
Bags and Containers
Insulated Delivery Bag Market
Bags and Containers
Commodity Liners Market
Bags and Containers
Flip Lip Bags Market
Bags and Containers
Self-Sealing Bags Market
Bags and Containers
Bags and Containers Market
Bags and Containers
Bag-In-Box Filler Market