
 Back to College Market | 2026-2036
Back to College Market Size, Share, and Industry Trends Forecast 2026-2036
Back to College Market Intelligence
The capital-intensity gap between integrated e-commerce giants and traditional brick-and-mortar retailers is redrawing competitive positioning. Amazon.com, Inc. leverages its vast logistics infrastructure to offer a wide product assortment and rapid delivery services. In contrast, The ODP Corporation, through its Office Depot brand, focuses on a curated selection of school and office supplies via its physical store network. Technology firms like Apple Inc. differentiate by controlling a premium product ecosystem and utilizing direct-to-student sales channels.
The back to college market comprises the seasonal retail of products and services for students preparing for a new academic term in higher education. This includes technology products such as laptops featuring multi-core processors for demanding software, and essentials like dorm furniture that must adhere to campus-specific fire safety codes. The market's primary commercial purpose is to equip students for both their academic coursework and residential life. Laptops and other personal electronics represent the highest-value product type, while online retail has solidified its position as the dominant distribution channel.
Online retailers operate under strict data privacy frameworks, including the EU's GDPR, which governs the processing of student personal information. In the United States, the Federal Trade Commission (FTC) monitors truth-in-advertising laws related to promotional sales events. Product safety standards, such as CE marking for electronics sold in Europe, also dictate market access for hardware vendors. Retailers must now decide how to balance investments in digital personalization against the increasing cost of global regulatory compliance.
Market Dynamics
The digitalization of higher education is the central force shaping the back to college market. This shift dictates demand for high-performance computing hardware for coursework and simultaneously accelerates the channel migration toward integrated e-commerce platforms for procurement.
Growth Catalysts
- International Student Enrollment:Sustained growth in international student populations, particularly in the United States and the United Kingdom, creates a recurring, high-value demand segment requiring a complete initial outfitting of academic and residential goods.
- Curriculum-Mandated Technology:Universities increasingly require students in STEM and creative fields to own laptops with specific multi-core processors and graphics capabilities to run demanding software, making these high-cost purchases non-discretionary.
- Sustainable Product Demand:A rising preference among student consumers for products made from recycled materials and with minimal packaging is compelling retailers to expand their eco-friendly product lines, creating a new basis for brand differentiation.
Market Restraints
- Campus-Specific Product Codes:Restrictive and non-standardized campus housing regulations, such as unique fire safety codes for furniture and electronics, complicate inventory management and limit the product assortment retailers can offer nationally.
- High Cost of Core Technology:The significant upfront cost of essential electronics like laptops and tablets acts as a primary budget constraint for students and their families, leading to purchasing delays or a search for second-hand alternatives.
- Intense Demand Seasonality:Market demand is heavily concentrated in the two months preceding the fall academic term, creating immense inventory and logistical pressures for retailers and raising the financial risk of unsold seasonal stock.
Strategic Opportunities
- Product-as-a-Service Models:Retailers can develop subscription or rental services for high-cost items like premium dorm furniture, micro-fridges, and specialized electronics, converting large one-time sales into recurring revenue streams throughout the academic year.
- Expansion in Emerging Education Hubs:The rapid expansion of higher education infrastructure in countries like India presents an underpenetrated market for organized retail tailored to student needs, offering significant first-mover advantages.
- Circular Economy Initiatives:Formalized trade-in and certified refurbishment programs for electronics and other durable goods can capture value from the secondary market while appealing to environmentally conscious and budget-sensitive students.
Industry Challenges
- Global Regulatory Overhead:Online retailers face rising operational costs to simultaneously comply with the EU's GDPR on student data privacy and the US FTC's truth-in-advertising laws for promotional events.
- Supply Chain Fragility:The market's dependence on consumer electronics sourced from Asia exposes retailers to significant disruption risk from component shortages and shipping delays, jeopardizing peak season product availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Back to College Market |
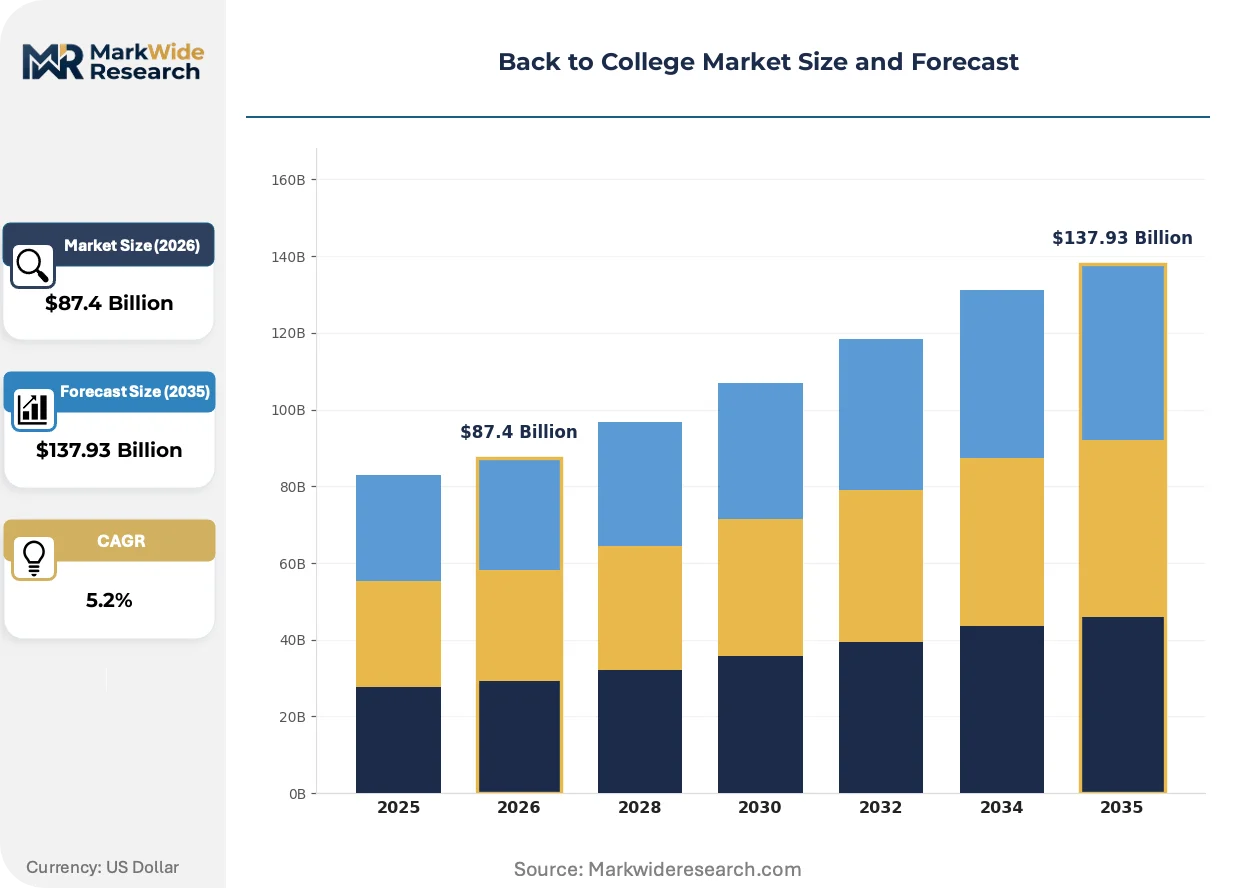
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $137.93 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laptops, Textbooks, Dorm Furniture, School Supplies End User: Undergraduate Students, Graduate Students, International Students, Adult Learners Distribution Channel: Online Retail, Campus Bookstores, Big Box Stores, Specialty Retailers Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Amazon.com, Inc., The ODP Corporation, Walmart Inc., Apple Inc., Staples Inc., HP Inc., Acco Brands Corporation, Dell Technologies, Lenovo Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Back to College Market Strategic Shifts & Innovations
The market's evolution is defined by the fusion of the digital and physical aspects of student life. This integration is changing not only the products students buy but also the fundamental models through which they access and use them for their academic careers.
AI-driven software provides students with personalized study aids, automated research assistance, and dynamic content generation. Students across all academic disciplines are adopting these tools, often through university-provided licenses or accessible freemium platforms. This technology is decomposing the monolithic, high-cost physical textbook into a fluid collection of on-demand digital content modules and interactive learning services.
Europe's Corporate Sustainability Reporting Directive (CSRD) is compelling large retailers to provide extensive disclosures on their supply chain's environmental and social impacts. This regulation forces greater transparency in the sourcing of electronics, textiles, and furniture sold to the student market. Retailers targeting the EU must now invest in sophisticated auditing and reporting systems to verify compliance, especially for their private-label brands.
Students are increasingly favoring access over ownership for high-cost, short-term-use items. This behavioral shift supports the growth of rental services for dorm furniture and subscription platforms for digital textbooks and software. This unbundling of ownership from usage disrupts traditional retail models that depend on large, one-time transactional sales, creating openings for new service-based competitors.
Back to College Market Segmentation
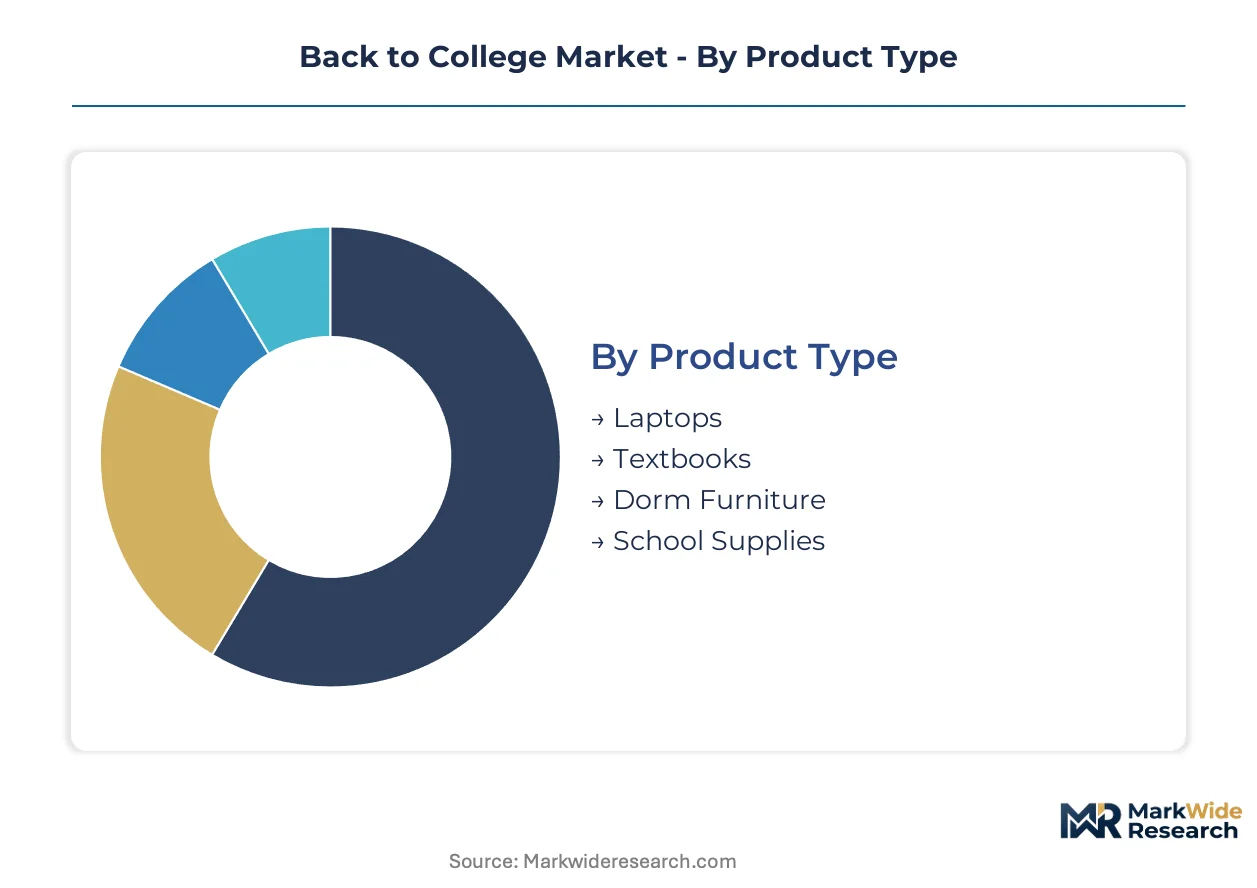
The Back to College market serves a diverse student population with varied academic and residential needs. Effective segmentation allows retailers and manufacturers to tailor product offerings, marketing strategies, and distribution channels, addressing specific demand patterns across different student demographics and product categories. Understanding these distinct segments is critical for optimizing inventory and achieving targeted market penetration.
Product Type:
The demand for specific product types varies significantly by geographic location, with some items being domestic staples while others are high-value imports.
- Laptops:These high-value technology products feature multi-core processors for demanding software applications in STEM fields. Demand concentrates heavily in the United States and European markets, driven by university-mandated technology requirements.
- Dorm Furniture:This segment includes beds, desks, and storage units, often requiring adherence to campus-specific fire safety codes. Procurement patterns shift towards rental models in densely populated urban university centers like the United Kingdom.
- Textbooks:Academic learning materials, increasingly accessed through digital subscriptions or online content modules, are essential for coursework.
- School Supplies:Basic academic necessities like notebooks, pens, and binders represent high-volume, low-margin purchases for students.
Laptops holds the largest share; momentum sits with Textbooks.
End User:
Different end-user segments exhibit distinct purchasing behaviors and product requirements, influencing retailer offerings and marketing efforts.
- International Students:This segment comprises individuals studying outside their home country, often requiring a complete initial outfitting of academic and residential goods. Demand is particularly strong in the United States and Australia, driving electronics and dorm essential sales.
- Undergraduate Students:The largest demographic in higher education, these students purchase a broad range of products from basic school supplies to entry-level laptops. Their decisions are influenced by budget constraints and peer recommendations in large university systems like India.
- Graduate Students:These learners require specialized software and high-performance computing, leading to demand for premium technology and advanced research tools.
- Adult Learners:Returning to education, this segment prioritizes convenience and value, often opting for flexible online learning tools and ergonomic study equipment.
Undergraduate Students represent the largest volume segment; International Students are expanding most quickly.
Distribution Channel:
The choice of distribution channel reflects student preferences for convenience, product assortment, and immediate access to goods, shaping procurement patterns.
- Online Retail:E-commerce platforms offer extensive product assortments, competitive pricing, and direct-to-door delivery, solidifying their dominant position. This channel is particularly strong in the United States, leveraging vast logistics networks and digital personalization tools.
- Campus Bookstores:These physical outlets offer curated selections of textbooks, branded merchandise, and essential school supplies, providing immediate access. Competitive positioning depends on convenience and direct integration with academic departments.
- Big Box Stores:Large retailers provide a wide array of general merchandise and seasonal promotions, attracting budget-conscious families during peak periods.
- Specialty Retailers:These stores focus on niche products like high-end electronics or ergonomic furniture, catering to specific academic needs or premium preferences.
Online Retail commands the largest share of transactions; Specialty Retailers are climbing the fastest in niche segments.
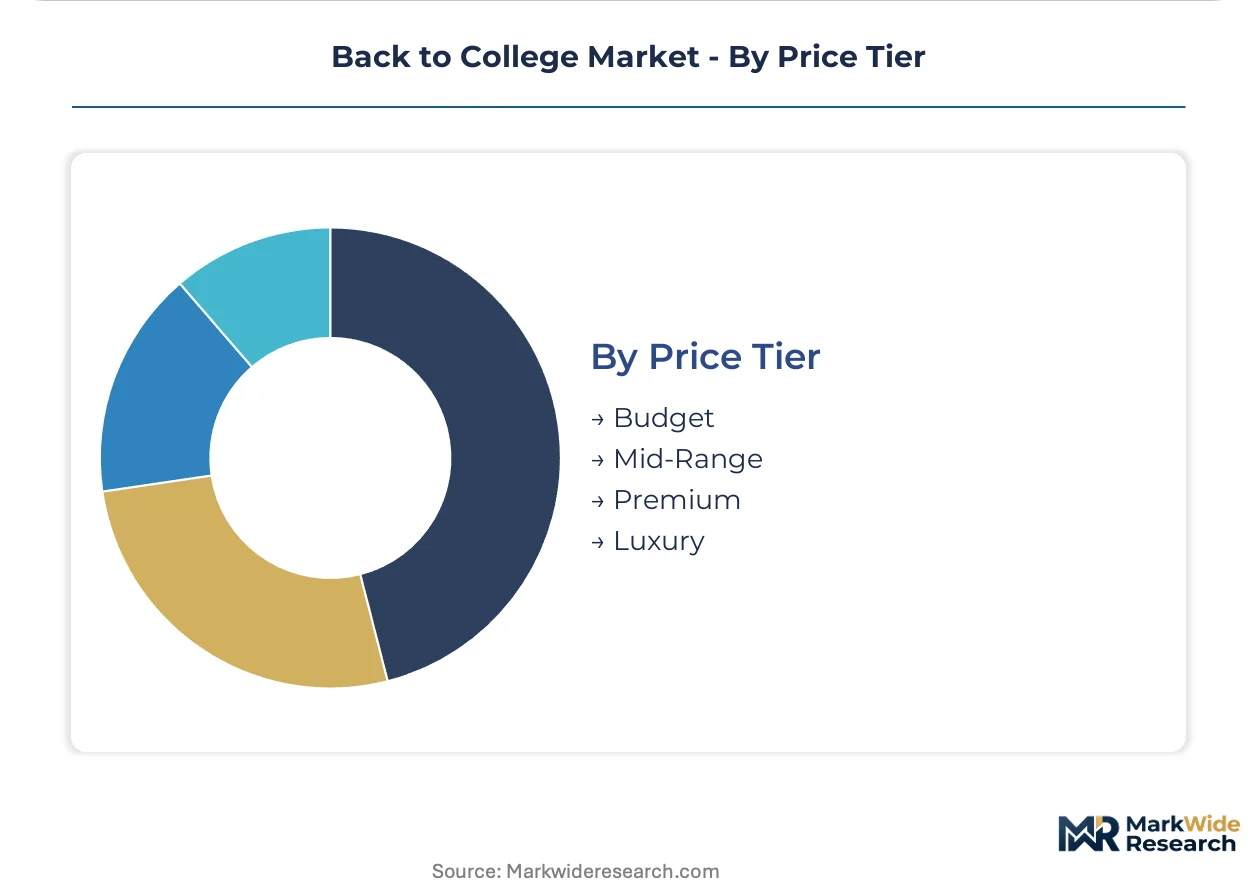
Price Tier:
Pricing strategies reflect product quality, brand perception, and student purchasing power, directly impacting retailer margins and market accessibility.
- Mid-Range:Products in this tier balance quality and affordability, appealing to the broadest segment of students seeking durable and functional items. This tier captures significant transaction volume, particularly in markets with large middle-class student populations like Germany and Canada.
- Premium:This segment includes high-performance electronics, designer dorm accessories, and specialized academic tools, targeting students with higher disposable incomes or professional requirements. Brands like Apple Inc. differentiate through a premium product ecosystem and direct-to-student sales channels.
- Budget:This tier focuses on essential, cost-effective items, often favored by students with tight financial constraints or seeking temporary dorm solutions.
- Luxury:Characterized by exclusive brands and bespoke services, this niche tier caters to a very small segment of affluent students seeking highly differentiated products.
Mid-Range products generate the highest sales volume; the Premium tier exhibits the steepest expansion trajectory for specialized goods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The regional pricing-power asymmetry between the United States and India shapes global back-to-college procurement patterns. Developed markets often command premium pricing for specialized electronics, while emerging hubs prioritize cost-effective solutions for a vast student base. This dynamic influences product availability and distribution strategies across continents.
United States
Demand for high-performance laptops and dorm essentials drives US market activity. The Federal Trade Commission (FTC) monitors truth-in-advertising laws for promotional sales events. University towns like Boston and Austin see concentrated demand for academic and residential goods.
United Kingdom
Sustained international student enrollment fuels demand for complete outfitting in the UK. Strict campus-specific fire safety codes dictate dorm furniture offerings. Densely populated urban university centers like London increasingly adopt rental models for high-cost items.
India
Undergraduate students in India drive high-volume, low-margin purchases for basic school supplies. The Indian government's emphasis on digital education boosts demand for entry-level computing devices. Large university systems in Bangalore and Pune experience significant seasonal retail peaks.
Germany
Mid-range products balancing quality and affordability appeal to Germany's large student population. Europe's Corporate Sustainability Reporting Directive (CSRD) compels retailers to disclose supply chain impacts. Major university cities like Munich and Berlin are hubs for durable and functional student items.
Australia
International students in Australia create strong demand for electronics and dorm essentials. Consumer protection laws ensure product safety and fair trading practices for student purchases. Educational centers in Sydney and Melbourne witness recurring, high-value demand for initial student setups.
Back to College Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the back to college market. The market exhibits a tiered structure, with integrated e-commerce giants competing against specialized retailers and traditional brick-and-mortar stores. Strategic archetypes include online platforms leveraging vast logistics, curated physical suppliers, and premium product ecosystem providers. Companies primarily engage in portfolio diversification and geographic expansion, alongside strategic partnerships, to capture student spending segments.
Among integrated e-commerce platforms, Amazon.com, Inc. exemplifies a player leveraging extensive logistics infrastructure for wide product assortment and rapid delivery services. Apple Inc. represents a premium product ecosystem provider, utilizing direct-to-student sales channels for high-value technology items and differentiating through controlled product ecosystems. The ODP Corporation, through its Office Depot brand, anchors the curated selection of school and office supplies available via physical store networks, focusing on specific regional demand and immediate access. These distinct approaches highlight the varied strategies for market penetration and customer engagement across different student segments.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| The ODP Corporation |
| Walmart Inc. |
| Apple Inc. |
| Staples Inc. |
| HP Inc. |
| Acco Brands Corporation |
| Dell Technologies |
| Lenovo Group Limited |
| Others |
Cost & Logistics Intelligence
Peak season inventory cycles for back-to-college essentials create immense logistical pressures for retailers, directly influencing pricing power through the risk of unsold seasonal stock and the need for rapid fulfillment.
Pricing Analysis
The customization-premium spread differentiates pricing across the market, with high-performance laptops and specialized electronics commanding higher prices. This market employs a hybrid pricing model, combining per-unit transactional sales for most goods with subscription or rental services for high-cost items like dorm furniture and software. Brand premium and technology specifications are key price differentiation drivers. Pricing pressure stems from the significant upfront cost of core technology, leading to budget-conscious purchasing. Undergraduate students exhibit the highest price sensitivity, while graduate students and premium segment buyers prioritize specialized features.
Supply Chain Analysis
Long lead times for electronics components, primarily sourced from Asia, expose retailers to significant disruption risks. Geographic supply concentration for consumer electronics, textiles, and furniture centers heavily in Asian manufacturing hubs, including China and other Southeast Asian nations. The market relies on multi-core processors and specialized raw materials for technology products. Supply chain fragility, particularly from component shortages and shipping delays, represents a critical structural risk. Distribution runs predominantly through online retail platforms, leveraging vast logistics networks for direct-to-student delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Back to College market represents a defensive-moat story, driven by the regulatory entrenchment of e-commerce platforms and the recurring demand from a large, growing student population.
For Market Incumbents: Fortify existing e-commerce dominance through advanced digital personalization features and seamless integration of university-specific requirements. Integrate circular economy initiatives like certified refurbishment programs to capture value from secondary markets. This counters the threat of new service-based competitors disrupting traditional transactional sales. Invest in sophisticated auditing and reporting systems for global regulatory compliance, leveraging this as a competitive lever.
For New Entrants and Emerging Players: Anchor in underserved product-as-a-service models for high-cost items like premium dorm furniture and specialized electronics. Target underpenetrated emerging education hubs, particularly in India, with tailored, organized retail solutions. The most penetrable segment consists of budget-conscious students seeking access over ownership. A strong go-to-market angle involves offering flexible subscription platforms for specialized electronics and dorm essentials.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring revenue model play because of sustained enrollment growth and the digitalization of higher education. Acquisition targets should focus on specialized service providers offering subscription or rental solutions for student needs, or technology firms developing AI-driven educational tools. The signal to watch is sustained growth in international student enrollment figures and the adoption rate of product-as-a-service models.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Product-as-a-Service Models | This converts large one-time sales into recurring revenue streams, appealing to budget-sensitive students. |
| Expand into Emerging Education Hubs | This captures significant first-mover advantages in underpenetrated markets like India. |
| Implement Circular Economy Programs | This appeals to environmentally conscious students and captures value from secondary markets. |
| Invest in AI-Driven Study Aids | This enhances student academic performance and aligns with higher education digitalization trends. |
| Strengthen Global Regulatory Compliance | This ensures market access and builds consumer trust, especially for online retailers. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews, complemented by extensive secondary data validation. Stakeholders included university procurement officers, e-commerce platform managers, retail logistics specialists, and student consumer groups. Secondary sources comprised US Federal Trade Commission (FTC) advisories, EU's GDPR guidelines, corporate sustainability reports (CSRD), and higher education enrollment statistics. A bottom-up and top-down triangulation process ensured data accuracy and consistency.
The forecast boundary for this analysis spans across the projection horizon, utilizing a robust analytical framework to model market dynamics. Segmentation dimensions modeled included product type, end user, distribution channel, price tier, and regional educational policy. Compound annual growth rates were calculated through econometric modeling. Key industry-specific forecast inputs included international student enrollment projections and university technology mandates for coursework.
Decision-makers should treat outputs as directional under current international student enrollment trends and regulatory stability; material deviation would warrant model refresh. Forecasts reflect assumptions regarding economic conditions and technological adoption. Geopolitical shifts impacting international student mobility or unforeseen changes in global regulatory frameworks represent specific risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Education & Training
Asia-Pacific Learning Management Systems Market
Education & Training
Global Mechatronics and Robotics Courses Market
Education & Training
Higher Education Learning Systems Market
Education & Training
Europe MOOC Market
Education & Training
Educational Content Development Service Market
Education & Training
Global K-12 Software Market
Education & Training
Higher Education Technology Market
Education & Training
AI in K-12 Education Market
Education & Training
HSE Consulting Training Services Market
Education & Training
Competency-Based Education Spending Market
Education & Training
Remote Learning Technology Spending Market
Education & Training
Corporate Training Market
Education & Training
Educational Consulting and Training Market
Education & Training
Asia Big Data Analytics in Education Market
Education & Training
Europe K12 Education Market
Education & Training
MBA Education Market