
 North America K-12 Furniture Market | 2026-2036
North America K-12 Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
North America K-12 Furniture Market Analytics
Single-source procurement for K-12 furniture is decoupling from long-standing district habits as budget pressures and supply chain volatility push buyers toward diversified vendor pools. Steelcase Inc. leverages its established dealer network to maintain institutional relationships across Midwest school districts. Virco Manufacturing Corporation anchors its position through captive domestic production of metal seating and activity tables. HNI Corporation competes via vertical integration into wood component fabrication, insulating margins from raw material volatility.
North America K-12 furniture encompasses desks, chairs, shelving, tables, and ancillary equipment engineered to student anthropometric standards, typically fabricated from wood, metal, plastic, or laminate substrates and finished for durability against institutional wear cycles. The category serves primary and secondary educational facilities requiring flexible spatial configurations for individual study, group collaboration, and technology integration. Ergonomic and collaborative type segments are capturing disproportionate attention as districts phase out fixed-row classroom layouts; plastic material formulations lead volume due to cost scalability, though laminate surfaces command premium positioning in high-visibility administrative and STEM lab environments. Modular product architecture is expanding fastest where districts prioritize reconfigurable footprints to accommodate fluctuating enrollment and hybrid instructional models.
The U.S. Consumer Product Safety Commission and California Air Resources Board shape compliance obligations through flammability standards and formaldehyde emission thresholds, respectively, while EPA guidelines on volatile organic compounds influence adhesive and finish selection across manufacturing operations. Health Canada and the U.S. Green Building Council's LEED criteria further filter market access for suppliers targeting publicly funded projects with sustainability mandates. Stakeholders must track evolving procurement aggregation patterns, as regional purchasing cooperatives gain leverage to standardize specifications and compress supplier margins.
Market Dynamics
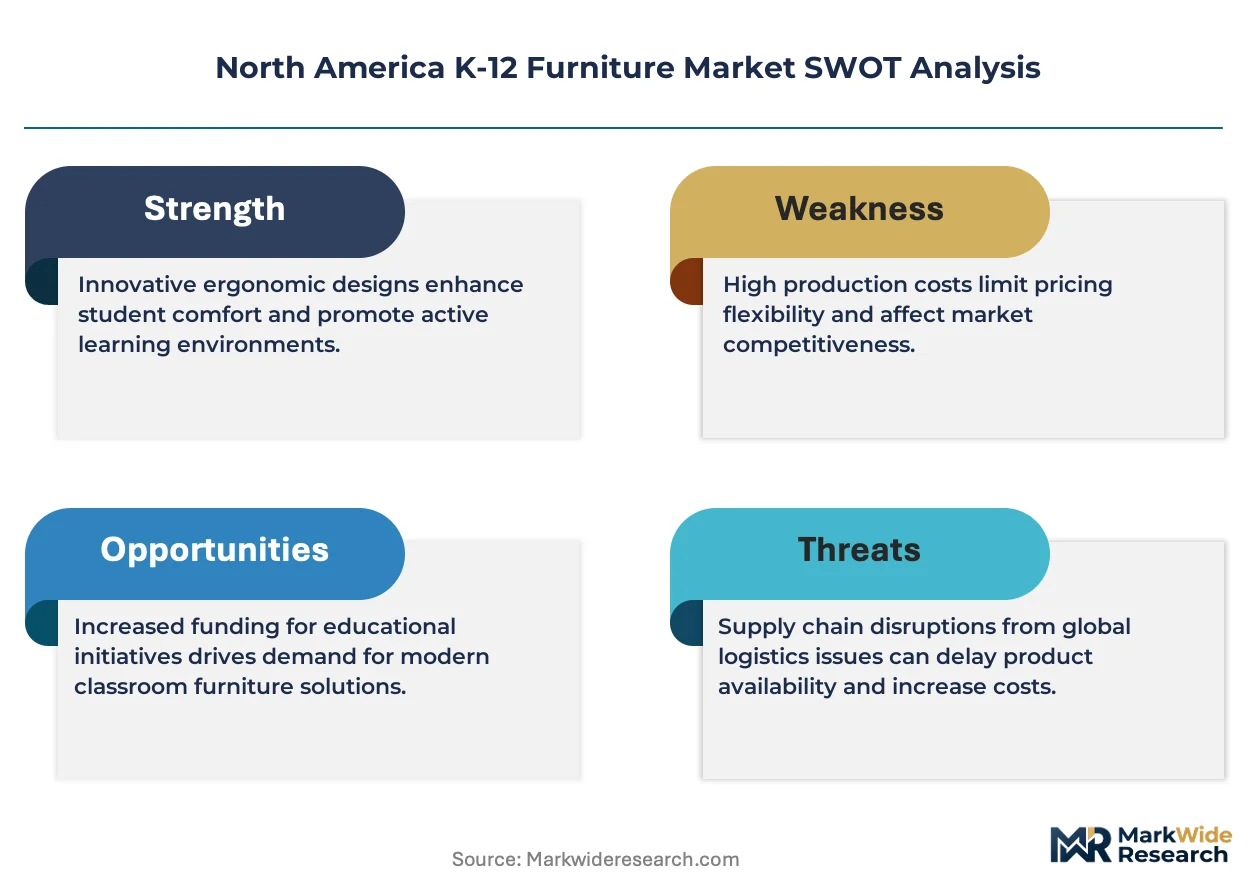
District-level bond funding cycles and classroom modernization mandates are compressing replacement timelines for fixed-row furniture configurations across U.S. and Canadian school systems.
Growth Catalysts
- California Air Resources Board formaldehyde emission standards:Districts in high-compliance states accelerate furniture turnover to meet indoor air quality thresholds, creating replacement pull for low-emission laminate and engineered wood products.
- Collaborative seating configurations:Elementary schools in Ontario and Texas expand procurement of modular desks and mobile seating pods to support group-based instructional models.
- U.S. Southeast bond funding concentration:District-level capital programs in Florida, Georgia, and North Carolina channel investment into reconfigurable furniture systems for enrollment-flexible buildings.
Market Restraints
- Steel and aluminum input volatility:Metal seating manufacturers face margin compression from commodity price swings, with domestic mills operating at capacity constraints.
- Canadian softwood lumber supply concentration:British Columbia and Quebec sawmill capacity limitations restrict engineered substrate availability for wood-component fabricators.
- Legacy fixed-desk infrastructure:Decades of sunk investment in bolted-down seating creates physical and budgetary friction against rapid reconfiguration adoption.
Strategic Opportunities
- Mexico underpenetrated procurement modernization:Federal education infrastructure programs create entry points for suppliers offering durable plastic and metal seating at public-sector price points.
- Hybrid instructional technology convergence:Furniture integrating cable management, device charging, and acoustic dampening captures premium positioning in STEM lab and media center deployments.
- U.S. Green Building Council LEED v4.1 schools rating:Sustainability-mandated projects in California, Washington, and New York filter vendor pools toward certified low-VOC and recycled-content products.
Industry Challenges
- Ergonomic certification timeline compression:BIFMA and ANSI/BIFMA e3 documentation requirements extend product development cycles for collaborative and active seating lines.
- Dealer network reconfiguration friction:Districts diversifying vendor pools strain established distribution relationships, requiring manufacturers to support direct specification and shortened fulfillment windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America K-12 Furniture Market |
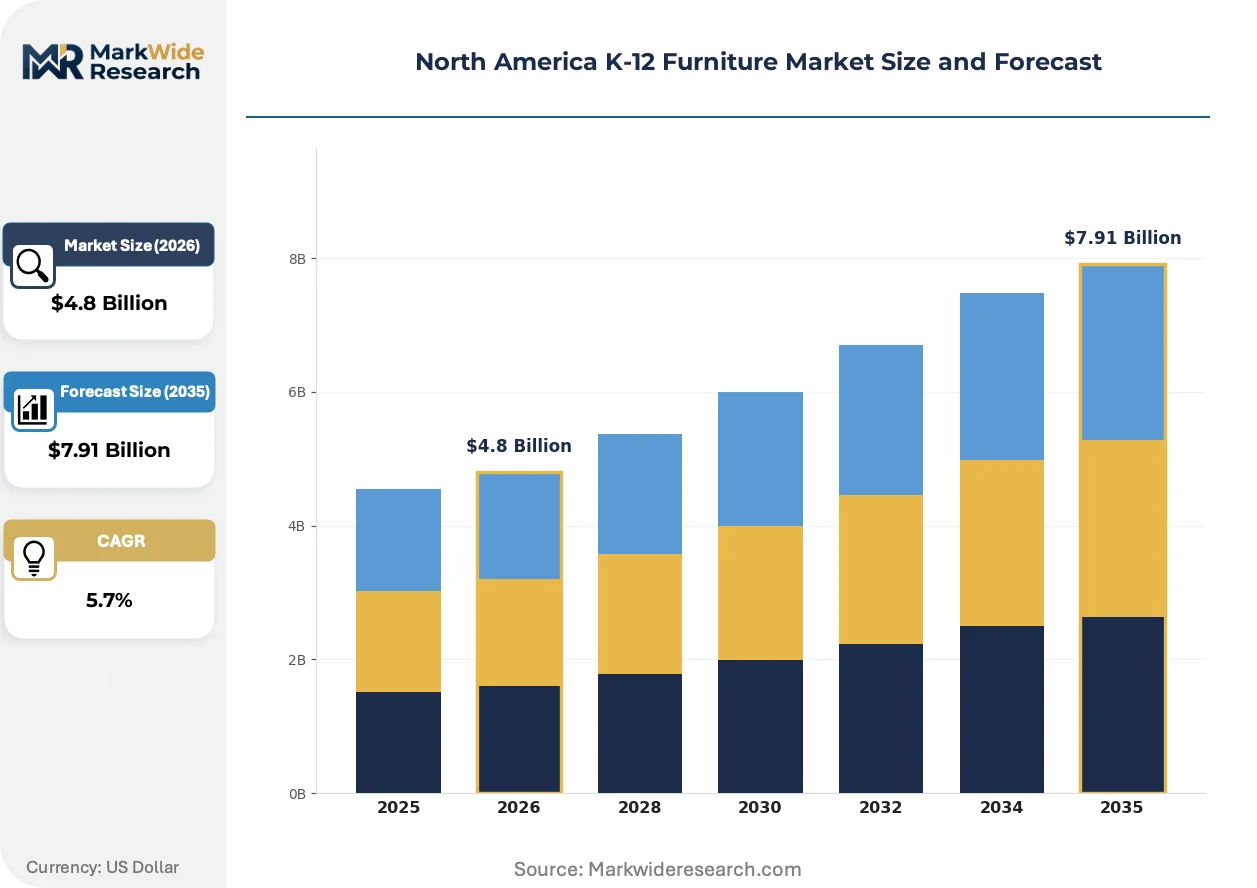
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desks, Chairs, Shelving, Tables Material: Wood, Metal, Plastic, Laminate End User: Elementary Schools, Middle Schools, High Schools, Educational Institutions Type: Traditional, Ergonomic, Modular, Collaborative |
| Companies Covered | KI Furniture, Smith System, Steelcase Inc., Knoll Inc., Krueger International Inc., Herman Miller Inc., Virco Manufacturing Corporation, VS America Inc., HNI Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America K-12 Furniture Market Evolving Landscape
Active learning pedagogies and hybrid classroom models are reshaping furniture specification criteria, with buyers prioritizing mobility, durability, and technology integration over traditional fixed-installation economics.
Modular furniture architecture is overtaking fixed-row classroom layouts as the default specification for new construction and renovation projects. District facilities planners in Texas and Florida specify caster-mounted tables and nesting chairs to enable rapid room reconfiguration. This mobility is compressing replacement cycles for traditional bolted desks while expanding addressable spend per square foot.
The U.S. Consumer Product Safety Commission flammability standards and California Air Resources Board formaldehyde thresholds are tightening substrate and finish selection across manufacturing operations. Suppliers reformulate adhesives and specify low-emission laminates to maintain eligibility for publicly funded projects. Wood-component fabricators in the U.S. Midwest and Quebec face the steepest compliance adaptation costs.
Buyer aggregation through regional purchasing cooperatives is consolidating specification authority away from individual districts. Cooperatives in the U.S. Southeast and Ontario standardize furniture requirements across dozens of member districts, compressing supplier margins while rewarding scale-capable manufacturers with multi-year contract visibility. This concentration is most advanced in states with centralized procurement statutes.
North America K-12 Furniture Market Segmentation
K-12 furniture procurement in North America operates through specification tiers that filter vendor eligibility based on compliance burden, application environment, and lifecycle economics. District purchasing cooperatives increasingly weight certification documentation over unit price in competitive evaluations.
Product Type:
BIFMA e3 and ANSI/BIFMA certification requirements vary sharply by product category, with seating lines carrying heavier ergonomic documentation loads than storage systems.
- Desks:Fixed pedestal and height-adjustable work surfaces fabricated from laminate, solid wood, or steel substrates. Demand concentrates in California and Texas elementary renovations where districts replace bolted-down rows with mobile, reconfigurable units to support collaborative pedagogies.
- Chairs:Shell seating, task chairs, and active stools engineered to student anthropometric ranges with polypropylene, steel, or upholstered construction. Ontario and U.S. Southeast districts prioritize ergonomic certification for extended sitting durations in STEM lab environments.
- Shelving:Fixed and mobile storage systems for library, classroom, and administrative use.
- Tables:Activity, cafeteria, and conference tables spanning rectangular to kidney configurations.
Leading the category by volume: Chairs. Growing fastest: Desks.
Material:
Raw material selection determines compliance pathway and landed cost tier, with engineered substrates facing stricter California Air Resources Board scrutiny than monolithic plastics.
- Wood:Solid hardwood and engineered particleboard for premium institutional applications. Canadian softwood supply constraints from British Columbia sawmill limitations restrict substrate availability for U.S. Midwest fabricators serving publicly funded projects.
- Metal:Steel and aluminum tubing, stampings, and castings for seating frames and desk supports. Domestic mill capacity constraints in the U.S. Southeast create procurement bottlenecks for district-level bond-funded modernization programs.
- Plastic:Injection-molded polypropylene and polyethylene shells, legs, and glides dominating high-volume procurement.
- Laminate:High-pressure and low-pressure decorative surfaces bonded to composite cores for durability and cleanability.
Plastic commands the greatest procurement volume. Laminate carries the steepest price premium and compliance documentation burden.
End User:
Facility type shapes specification complexity, with secondary environments demanding technology integration and primary settings prioritizing durability and safety certification.
- Elementary Schools:K-5 facilities requiring scaled furniture for ages 5-11 with rounded edges, stable bases, and bright color palettes. Texas and Ontario districts lead procurement of collaborative pods and mobile storage for flexible classroom layouts.
- Middle Schools:Grades 6-8 environments transitioning students between self-contained and departmentalized instruction. U.S. Southeast bond funding channels investment into reconfigurable furniture systems for enrollment-flexible buildings.
- High Schools:Grades 9-12 facilities with specialized lab, vocational, and performing arts spaces.
- Educational Institutions:Administrative, library, cafeteria, and auxiliary spaces across district portfolios.
Elementary Schools generate the highest unit volume. Middle Schools are expanding most quickly as districts modernize aging 1960s-1970s facilities.
Type:
Product architecture determines replacement cycle timing, with fixed traditional installations carrying decades-long depreciation schedules against modular alternatives suited to annual reconfiguration.
- Traditional:Fixed-row desks and bolted seating configurations inherited from mid-20th century classroom design. Legacy sunk investment in California and Midwest districts creates physical and budgetary friction against rapid modernization.
- Ergonomic:Height-adjustable, active, and posture-supporting seating engineered to ANSI/HFES standards. Health Canada and EPA guidelines on volatile organic compounds influence adhesive and finish selection for upholstered and wood-component lines.
- Modular:Caster-mounted, nesting, and reconfigurable systems enabling rapid spatial transformation.
- Collaborative:Team-oriented tables, whiteboard surfaces, and mobile seating pods supporting group-based instruction.
Traditional installations still dominate installed base. Modular and Collaborative types are climbing the fastest as active learning pedagogies displace fixed-row layouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian softwood lumber from British Columbia sawmills and U.S. Great Lakes metal fabrication clusters anchor North American K-12 furniture supply. District procurement patterns vary sharply across national and sub-regional boundaries.
United States
District-level bond funding in Florida, Georgia, and North Carolina accelerates reconfigurable furniture procurement for enrollment-flexible buildings. The U.S. Consumer Product Safety Commission flammability standards filter vendor eligibility for publicly funded projects. Texas elementary districts specify collaborative seating pods from Dallas-Fort Worth fabrication clusters.
Canada
Ontario school boards expand modular desk procurement to support active learning pedagogies. Health Canada indoor air quality guidelines influence laminate and engineered wood selection for publicly funded renovations. Quebec sawmill capacity constraints limit substrate availability for wood-component fabricators serving cross-border demand.
Mexico
Federal education infrastructure programs create procurement entry points for durable plastic and metal seating suppliers. The Secretariat of Public Education modernization initiatives channel investment into basic furniture for rural and urban schools alike. Mexico City metropolitan area distributors serve as consolidation points for imported component assembly.
North America K-12 Furniture Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers balance dealer network maintenance against direct specification capabilities. The vendor base clusters around three tiers: scale-driven domestic producers, vertically integrated wood specialists, and European-import positioning players. Strategic archetypes include captive manufacturing, specification-led design houses, and cooperative purchasing network anchors. M&A activity and capacity expansion in Mexico represent the dominant competitive moves.
Among Midwest-based institutional furniture specialists, Steelcase Inc. and Virco Manufacturing Corporation exemplify divergent scale strategies. HNI Corporation occupies a position within the vertically integrated wood fabrication tier. These three anchors represent distinct responses to procurement aggregation pressure from regional purchasing cooperatives.
| Leading Market Players |
|---|
| KI Furniture |
| Smith System |
| Steelcase Inc. |
| Knoll Inc. |
| Krueger International Inc. |
| Herman Miller Inc. |
| Virco Manufacturing Corporation |
| VS America Inc. |
| HNI Corporation |
| Others |
Value Network & Pricing Analysis
Regional purchasing cooperative consolidation across the U.S. Southeast and Ontario is compressing supplier margins while rewarding scale-capable manufacturers with multi-year contract visibility, forcing smaller fabricators to absorb cost volatility or exit procurement eligibility. This buyer-side concentration is reshaping how domestic producers structure warranty bundling and service tiers to defend positioning.
Pricing Analysis
Warranty and installation-service bundling separates premium laminate and ergonomic seating lines from unbundled economy plastic shells. Three-tier pricing structure across premium, standard, and economy levels tracks certification burden, with BIFMA e3 documentation adding documentation costs that flow through to district cooperative bids. Pricing pressure stems from Canadian softwood lumber supply constraints elevating engineered substrate costs for wood-component fabricators. High-volume plastic seating procurement by Texas and Florida districts exhibits greatest price sensitivity, while LEED-mandated California projects tolerate premium positioning for low-VOC certified products.
Supply Chain Analysis
Single-source vulnerability sits with British Columbia sawmill capacity for engineered wood substrates and U.S. Southeast domestic steel mill output for metal seating frames. Raw material flows draw from Quebec particleboard producers, Midwest Great Lakes metal fabrication clusters, and Dallas-Fort Worth plastic injection molding operations. Tariff exposure on Canadian softwood imports creates margin risk for cross-border substrate sourcing. Distribution runs through established dealer networks anchored by Steelcase and Virco, with direct specification capability emerging as a competitive requirement for shortened fulfillment windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement aggregation through regional purchasing cooperatives is consolidating vendor pools, forcing sub-scale manufacturers toward exit or acquisition as margin compression eliminates standalone viability.
For Market Incumbents: Cement dealer network loyalty through captive installation and warranty service bundling while accelerating backward integration into wood component fabrication to insulate margins from Canadian lumber volatility. Invest in BIFMA e3 certification documentation to maintain eligibility for cooperative purchasing networks standardizing specifications across Ontario and U.S. Southeast member districts. For New Entrants and Emerging Players: Launch via direct specification relationships with individual Texas and Florida districts bypassing cooperative procurement aggregation, targeting middle school modernization projects where bond funding channels investment into reconfigurable systems. Prioritize durable plastic and metal seating at public-sector price points for Mexico's federal education infrastructure programs, leveraging Mexico City metropolitan distributors for component assembly consolidation. For Investors and Strategic Acquirers: The window for entry favors vertically integrated wood specialists with captive Quebec or British Columbia substrate access and established BIFMA documentation capabilities. Monitor U.S. Green Building Council LEED v4.1 adoption velocity across California, Washington, and New York as the inflection signal for sustainability-mandated project filtering toward certified low-VOC product lines.| Strategic Initiative | Industry Significance |
|---|---|
| Dealer Network Reconfiguration | Direct specification capability shortens fulfillment windows for cooperative procurement. |
| Backward Integration into Wood Fabrication | Captive substrate production insulates margins from British Columbia sawmill constraints. |
| BIFMA e3 Certification Investment | Documentation burden filters vendor eligibility for aggregated cooperative bids. |
| Geographic Capacity Expansion in Mexico | Federal education infrastructure programs create procurement entry points for durable seating. |
| Low-VOC Product Line Repositioning | LEED-mandated projects in California filter vendor pools toward certified finishes. |
Research Methodology
Document review covered U.S. Consumer Product Safety Commission flammability standards, California Air Resources Board formaldehyde emission thresholds, Health Canada indoor air quality guidelines, and EPA volatile organic compound directives, complemented by interviews with district facilities planners, regional purchasing cooperative procurement directors, furniture dealer network managers, and wood-component fabrication plant engineers. Secondary validation drew from U.S. school district bond funding disclosures, Canadian provincial education infrastructure budgets, SEC 10-K filings of publicly traded furniture manufacturers, and BIFMA industry shipment data. Bottom-up unit demand estimates and top-down market sizing were triangulated for convergence.
Segmentation outputs across product type, material substrate, end-user facility tier, and furniture architecture type were modeled across the projection horizon. CAGRs were derived from enrollment trend projections, replacement cycle compression factors, and bond funding allocation patterns. Forecast inputs incorporated California classroom space standard updates, Ontario active learning pedagogy adoption curves, and U.S. Southeast district-level capital program prioritization matrices.
Commodity price volatility in steel and aluminum, Canadian softwood lumber supply disruptions, and shifts in cooperative purchasing cooperative specification authority are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about pedagogical transition timelines and regulatory compliance threshold evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Primary and Secondary Education
Saudi Arabia Private K12 Education Market
Primary and Secondary Education
Qatar Private K12 Education Market
Primary and Secondary Education
UAE Private K12 Education Market
Primary and Secondary Education
Oman Private K12 Education Market
Primary and Secondary Education
K-12 Education Market
Primary and Secondary Education
Asia-Pacific School Furniture Market
Primary and Secondary Education
In-Person Learning Market
Primary and Secondary Education
GCC Private K12 Education Market
Primary and Secondary Education
North America K12 Education Market
Primary and Secondary Education
Oman Private K-12 Market
Primary and Secondary Education
Europe K12 Education Market
Primary and Secondary Education
Back to School Market