
 Corporate Training Market | 2026-2036
Corporate Training Market Size, Share, and Industry Trends Forecast 2026-2036
Corporate Training Market Analysis
India is fragmenting as a delivery hub for corporate training, with Bangalore and Hyderabad drawing content development centers from global providers. Simplilearn anchors its position through certification-aligned technical curricula in cloud computing and data science. FranklinCovey differentiates via behavioral methodology licensing to enterprise HR departments. Dale Carnegie Training sustains its footprint through instructor-led soft skills programs that command premium pricing in executive education.
Corporate training encompasses structured learning interventions designed to upgrade employee capabilities, typically delivered through modular curricula with measurable competency outcomes and post-assessment validation. Programs integrate synchronous instruction, asynchronous content libraries, and applied simulations to close identified performance gaps against role-specific competency frameworks. Online delivery mode leads volume expansion as learning management systems embed AI-driven personalization engines, while compliance training retains the most predictable budget allocation due to regulatory refresh mandates. Leadership development claims the highest per-learner spend, though technical skills training generates the largest aggregate revenue pool across IT and finance verticals.
OSHA workplace safety standards, the EU GDPR certification requirements, and India's PLI scheme workforce clauses collectively shape mandatory training budgets and content specifications across jurisdictions. FDA good manufacturing practice training mandates in pharmaceutical and medical device operations create recurring compliance revenue streams for specialized providers. Stakeholders must evaluate whether platform investments in generative AI tutoring will compress margins for standardized content or unlock premium pricing for hyper-personalized competency pathways.
Market Dynamics
Generative AI tutoring engines are compressing content development cycles and forcing providers to reprice standardized modules against hyper-personalized competency pathways. The shift from instructor-led delivery to AI-augmented asynchronous platforms is redistributing margin pools across the value chain.
Growth Catalysts
- EU AI Act algorithmic literacy mandates:European employers must certify workforce competency in AI risk management, creating mandatory procurement of compliance modules.
- India PLI scheme workforce clauses:Manufacturing incentives tie subsidy eligibility to documented training completion, channeling public funds into private provider ecosystems.
- Healthcare clinical competency gaps:Hospital systems facing nursing shortages and specialized technician deficits are expanding dedicated learning budgets for simulation-based credentialing.
Market Restraints
- Content development cost concentration:High-fidelity simulations and VR-based safety training require capital-intensive production studios concentrated in Bangalore and Hyderabad.
- Regulatory fragmentation:Divergent OSHA workplace safety standards, EU GDPR certification refresh cycles, and India's DGFT skill certification requirements force multi-jurisdictional content versioning.
- Substitution by open-source libraries:Free technical certification prep resources on platforms like Coursera and edX erode pricing power for entry-level IT skills modules.
Strategic Opportunities
- Saudi Arabia and UAE national transformation programs:Vision 2030 and similar initiatives mandate massive workforce localization, creating demand for Arabic-language leadership development curricula.
- FDA good manufacturing practice training mandates:Pharmaceutical and medical device operations require recurring compliance certification, generating predictable recurring revenue for specialized providers.
- Convergence of generative AI and learning analytics:Real-time competency gap detection paired with automated content generation enables dynamic pathway customization at scale.
Industry Challenges
- Instructional designer talent scarcity:The shift to AI-augmented content creation demands professionals who blend pedagogy expertise with prompt engineering and data analytics fluency.
- LMS integration complexity:Enterprise clients require seamless API connectivity with legacy HRIS platforms, extending sales cycles and inflating implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corporate Training Market |
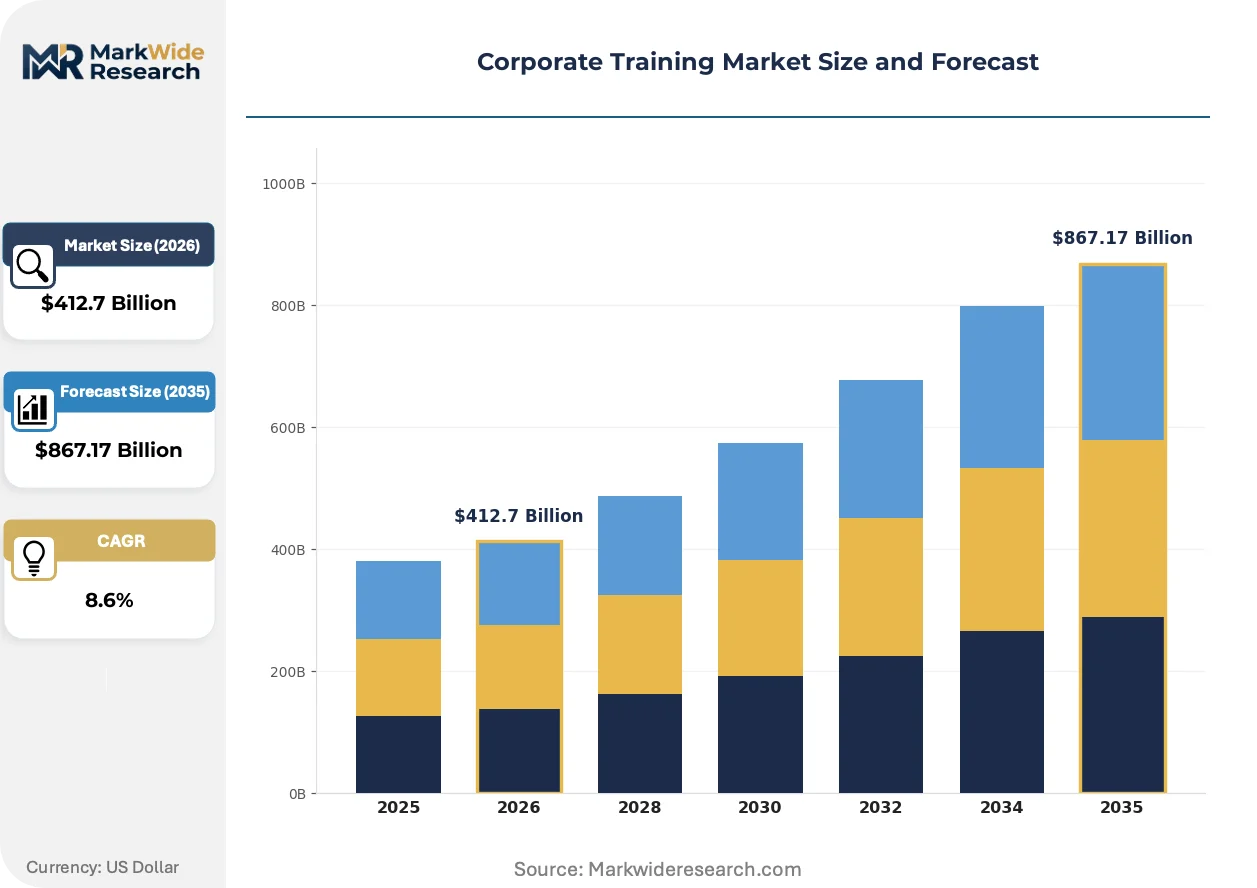
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $867.17 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Mode: In-Person, Online, Hybrid, Blended Training Type: Technical Skills, Soft Skills, Compliance Training, Leadership Development End User: Corporates, SMEs, Startups, Government Agencies Industry Vertical: IT, Healthcare, Finance, Manufacturing |
| Companies Covered | Global Knowledge, Dale Carnegie Training, Edstellar, Nomadic Learning, FranklinCovey, Microtek Learning, Simplilearn, ELB Learning, AllenComm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corporate Training Market Emerging Trajectories
Adaptive learning algorithms are replacing static course catalogs as the primary interface between employers and workforce development. The technology stack is bifurcating into commodity content delivery infrastructure and premium intelligence layers that predict individual competency trajectories.
Generative AI tutoring systems are collapsing the cost structure of personalized instruction. These engines synthesize role-specific scenarios from enterprise data repositories and deliver adaptive feedback without human instructor intervention. Fortune 500 HR departments in financial services and technology verticals are piloting these systems at scale, compressing the traditional 12-week leadership development cycle into continuous micro-learning touchpoints.
The EU AI Act's workforce literacy requirements are mandating algorithmic risk assessment training across regulated industries. Employers in banking, healthcare, and public administration must document employee comprehension of automated decision-making systems. German automotive manufacturers and French pharmaceutical groups are accelerating procurement of compliance modules ahead of enforcement deadlines.
Buyer concentration among large employers is consolidating vendor relationships and demanding outcome-based contracting. Enterprise procurement teams now require training providers to tie fees to measurable competency gains verified through third-party assessment. This shift is most pronounced in India's IT services sector, where campus-to-corporate programs face pressure to demonstrate placement rates and role-readiness scores rather than completion certificates.
Corporate Training Market Segmentation
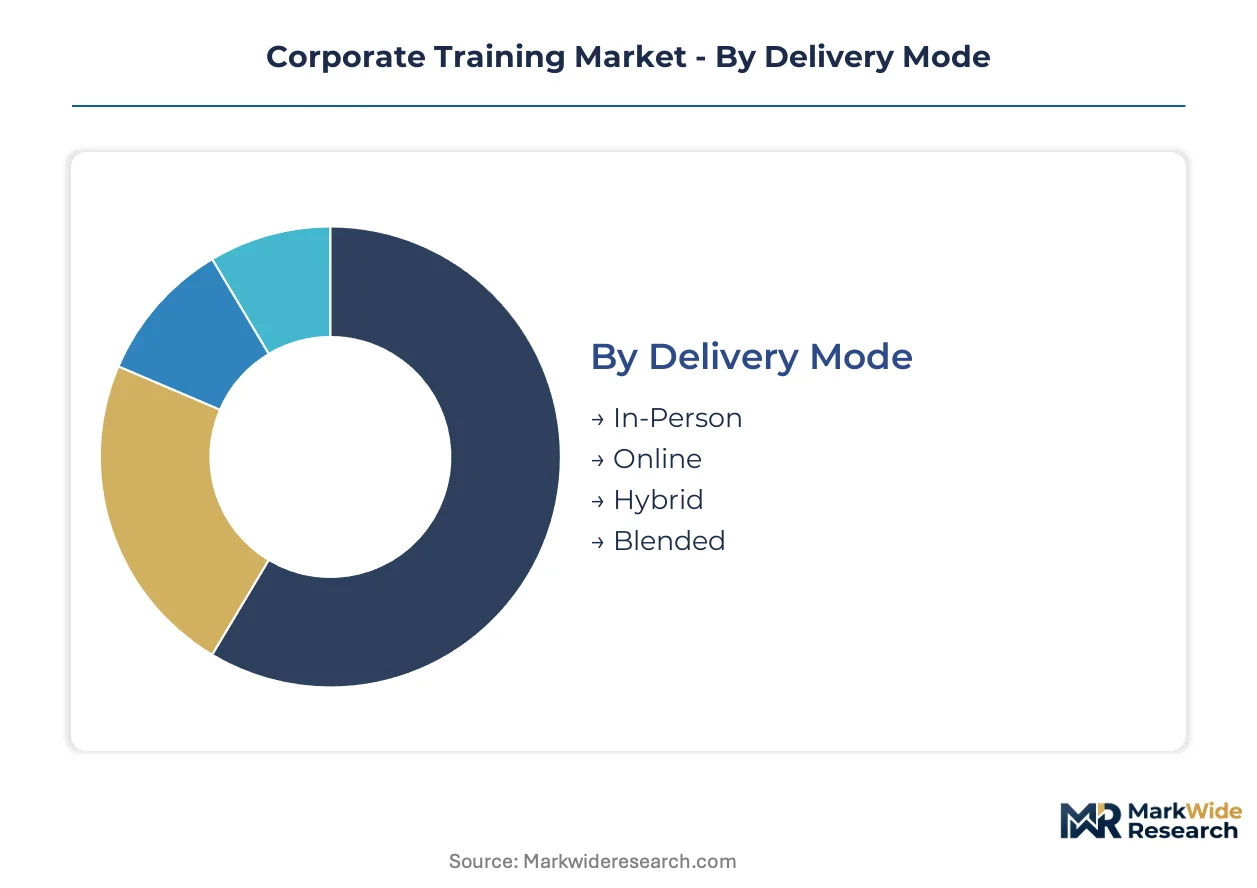
Corporate training procurement patterns diverge sharply across delivery modalities, competency domains, and organizational scale. Buyers segment investments by regulatory exposure, workforce technical intensity, and measurable outcome requirements rather than uniform curriculum adoption.
Delivery Mode:
Mature synchronous formats coexist with emerging AI-augmented asynchronous platforms, creating a bifurcated infrastructure landscape where legacy providers defend installed base while cloud-native entrants capture expansion budgets.
- In-Person:Instructor-led classroom delivery maintains dominance in executive education and high-stakes certification programs where peer interaction and real-time feedback prove non-substitutable. German automotive manufacturers and Saudi national oil companies continue mandating residential leadership modules despite higher per-learner costs.
- Online:Self-paced digital curricula with embedded assessments scale across distributed workforces without geographic constraint. India's IT services firms deploy these modules for campus-to-corporate conversion at volume, though completion rates vary without managerial accountability mechanisms.
- Hybrid:Scheduled virtual sessions supplemented by in-person intensives balance flexibility with relationship formation. Healthcare systems in the US and UK favor this model for clinical competency credentialing where simulation labs require physical presence.
- Blended:Algorithmically sequenced content pathways interweave synchronous touchpoints based on individual proficiency trajectories. Early adopters in financial services report compressed time-to-competency against traditional linear curricula.
Online delivery captures volume leadership; blended architectures hold the steepest expansion curve as AI personalization engines mature.
Training Type:
Cost tier stratification separates commoditized compliance refresh from premium leadership development, with technical skills occupying the contested middle ground where open-source alternatives pressure pricing.
- Technical Skills:Cloud architecture, data science, and cybersecurity certifications dominate procurement in technology and financial verticals. India's PLI scheme workforce clauses channel public subsidy into documented completion of manufacturing automation curricula.
- Soft Skills:Communication, negotiation, and team dynamics training persists in instructor-dependent formats that resist full automation. Dale Carnegie Training and similar providers defend premium positioning through facilitator certification networks.
- Compliance Training:Mandatory modules tied to OSHA workplace safety standards, EU GDPR certification refresh cycles, and FDA good manufacturing practice mandates generate predictable recurring revenue with limited pricing power.
- Leadership Development:C-suite and high-potential programs command the highest per-learner investment, with outcomes increasingly tied to promotion velocity and retention metrics rather than completion certificates.
Compliance training retains budget predictability; leadership development claims the steepest per-capita spend escalation as outcome-based contracting spreads.
End User:
Customer type determines procurement sophistication, with large corporates consolidating vendor relationships while SMEs and startups access modular solutions through platform marketplaces.
- Corporates:Fortune 500 enterprises demand API-integrated learning management systems with HRIS connectivity, extending sales cycles but locking in multi-year contracts. Buyer concentration pressures providers toward outcome-based fee structures.
- SMEs:Mid-market employers prioritize off-the-shelf content libraries with minimal implementation overhead, accepting standardized curricula over customization to contain administrative burden.
- Startups:Venture-backed technology firms favor accelerated bootcamp formats and micro-credential stacking for rapid role readiness, often bypassing traditional providers for specialized academies.
- Government Agencies:Public sector procurement in the EU and India ties training eligibility to subsidy compliance, creating captive demand for accredited providers meeting documented outcome requirements.
Corporates anchor aggregate revenue; government agencies provide the most expansion velocity as workforce localization mandates proliferate across Saudi Arabia and UAE national transformation programs.
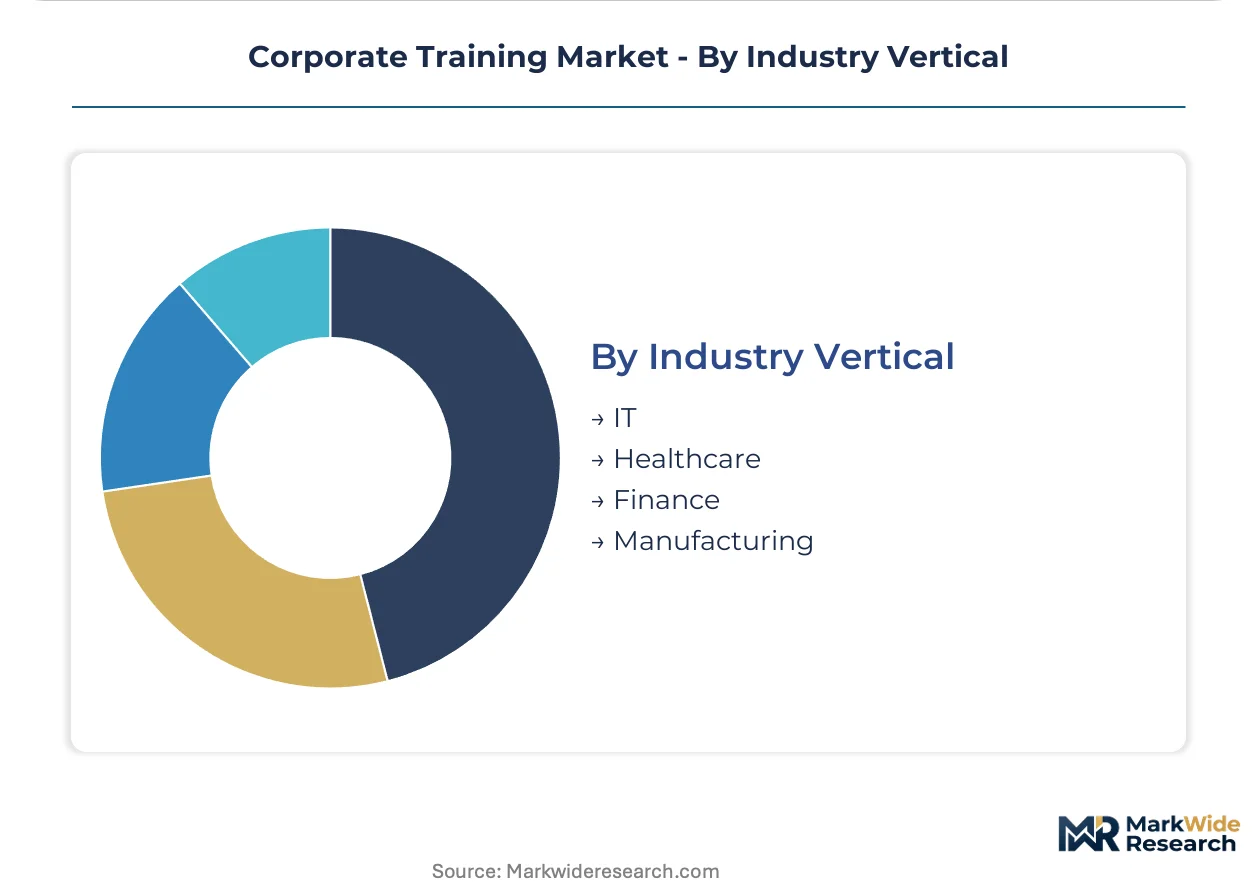
Industry Vertical:
Application intensity varies by sector regulatory exposure and technical talent scarcity, with IT and healthcare diverging in delivery modality preferences despite comparable training budget growth.
- IT:Continuous reskilling requirements around generative AI tooling and cloud infrastructure drive the largest aggregate spending pool, with Bangalore and Hyderabad content development centers serving global demand.
- Healthcare:Nursing shortages and specialized technician deficits expand simulation-based credentialing budgets, with US hospital systems and UK's NHS investing in VR-enabled clinical scenarios.
- Finance:EU AI Act algorithmic literacy mandates and SEC disclosure requirements create overlapping compliance obligations, with banking consortia negotiating collective procurement of risk management modules.
- Manufacturing:India's PLI scheme workforce clauses and Germany's Industrie 4.0 competency frameworks channel investment into automation and quality systems training for operator-level personnel.
IT verticals dominate aggregate revenue capture; healthcare demonstrates the steepest per-learner investment growth as clinical simulation technologies proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Content development studios cluster in Bangalore and Hyderabad, channeling technical curriculum production for global IT services firms. The EU AI Act and India's PLI scheme workforce clauses are redirecting training procurement across three continents. Regulatory divergence between OSHA, GDPR, and DGFT mandates forces multi-jurisdictional content versioning.
United States
Hospital systems facing nursing shortages are expanding simulation-based credentialing budgets for clinical competency gaps. FDA good manufacturing practice training mandates create recurring compliance revenue streams for pharmaceutical and medical device operations. Dallas and Atlanta host concentrated corporate learning headquarters serving Fortune 500 HR departments.
Germany
Automotive manufacturers are accelerating procurement of EU AI Act compliance modules ahead of enforcement deadlines. Industrie 4.0 competency frameworks channel investment into automation training for operator-level personnel. Stuttgart and Munich anchor leadership development programs commanding premium per-learner spend in executive education.
India
IT services firms are scaling campus-to-corporate programs at unprecedented rates under PLI scheme workforce clauses tying subsidy eligibility to documented training completion. DGFT skill certification requirements shape content specifications for manufacturing automation curricula. Bangalore and Hyderabad fragment as delivery hubs drawing content development centers from global providers.
Saudi Arabia
Vision 2030 national transformation programs mandate massive workforce localization, creating demand for Arabic-language leadership development curricula. SFDA pharmaceutical training requirements overlap with corporate competency frameworks in healthcare verticals. Riyadh concentrates procurement of premium instructor-led executive education modules.
United Kingdom
NHS investment in VR-enabled clinical scenarios is expanding healthcare simulation budgets for nursing and specialized technician deficits. GDPR certification refresh cycles generate predictable recurring revenue for compliance module providers. London anchors financial services procurement of algorithmic risk assessment training under overlapping regulatory obligations.
Corporate Training Market Vendor Landscape
Certification-aligned specialists and behavioral methodology licensors split the market between technical competency verification and executive soft skills development. The vendor base organizes around three strategic archetypes: cloud-native platform operators, instructor-network defenders, and enterprise methodology licensors. Consolidation pressures concentrate among Fortune 500 procurement teams demanding outcome-based contracting with HRIS integration. Dominant competitive moves include geographic expansion into Saudi Arabia and UAE workforce localization programs, plus technology licensing partnerships for AI-driven personalization engines.
Within the methodology licensing tier, FranklinCovey and Dale Carnegie Training exemplify divergent approaches to premium positioning—one through enterprise HR department partnerships, the other through facilitator certification networks commanding residential program pricing. Simplilearn anchors the certification-aligned technical curriculum segment, occupying a position shaped by cloud computing and data science alignment with vendor-neutral credentialing bodies. These three players represent the structural fault lines between asynchronous platform scale and instructor-dependent relationship economics.
| Leading Market Players |
|---|
| Global Knowledge |
| Dale Carnegie Training |
| Edstellar |
| Nomadic Learning |
| FranklinCovey |
| Microtek Learning |
| Simplilearn |
| ELB Learning |
| AllenComm |
| Others |
Supply Flow & Price Mechanics
Freight corridors connecting Bangalore and Hyderabad to Dubai and Frankfurt transmit cost volatility directly into content development pricing, compressing margins for standardized modules while amplifying premiums for instructor-certified pathways that resist geographic arbitrage.
Pricing Analysis
The EU AI Act dictates the pricing tier structure across European procurement, with algorithmic risk assessment modules commanding premium fees against commoditized GDPR refresh content. Three-tier pricing structure across premium, standard, and economy levels separates certified facilitator-led programs from self-paced digital libraries and open-source alternatives. Price erosion runs through entry-level technical skills as Coursera and edX substitute free certification prep. SMEs exhibit acute price sensitivity, while Fortune 500 enterprises accept outcome-based fee premiums tied to measurable competency verification.
Supply Chain Analysis
Content development studios in Bangalore, Hyderabad, and Chennai hold concentrated production capacity for technical curriculum and VR-enabled simulation assets. Raw material dependencies center on instructional designer talent pools, cloud rendering infrastructure, and licensed certification body content rights. Single-source vulnerability concentrates in prompt-engineering specialists who bridge pedagogy and AI tooling. Distribution runs through enterprise learning management system APIs and direct HR department licensing agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, where mandated compliance refresh cycles and certification body partnerships create high switching costs for enterprise buyers.
For Market Incumbents: Pre-empt open-source substitution by deepening API integration with legacy HRIS platforms, extending contract lock-in. Fortify facilitator certification networks against generative AI tutoring commoditization. Invest in Bangalore and Hyderabad content studios to capture PLI scheme workforce clause subsidies before competitors consolidate accreditation relationships.
For New Entrants and Emerging Players: Establish a beachhead in Arabic-language leadership development for Saudi Vision 2030 localization mandates, where incumbent coverage remains thin. Target healthcare simulation credentialing in US hospital systems facing nursing shortages. Lead with VR-enabled clinical scenarios differentiated from flat video libraries.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive training divisions lacking standalone scale. Long-term viability hinges on outcome-based contracting capabilities and AI personalization engine ownership. Monitor enforcement timelines for EU AI Act algorithmic literacy mandates as procurement acceleration signal.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Personalization Engine Development | Compresses time-to-competency for financial services clients piloting continuous micro-learning. |
| Certification Body Partnership Expansion | Locks in exclusive content licensing with vendor-neutral credentialing authorities in cloud computing. |
| Arabic Curriculum Localization | Captures Saudi and UAE national transformation program budgets ahead of European competitor entry. |
| VR Simulation Studio Buildout | Addresses FDA good manufacturing practice training mandates with recurring compliance revenue streams. |
| Outcome-Based Contracting Infrastructure | Aligns fee structures with third-party verified competency gains demanded by India's IT services sector. |
Methodological Framework
A spread of perspectives from chief learning officers, HRIS integration specialists, instructional designers, and certification body partnership managers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings from publicly traded training providers, EU regulatory enforcement notices, and India's DGFT skill certification documentation. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers across delivery modes and competency domains.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeled by delivery modality, training type, organizational scale, and industry vertical. CAGRs derived from trend extrapolation of documented procurement volumes and regulatory mandate enforcement schedules. Forecast inputs incorporated PLI scheme workforce clause implementation velocity and EU AI Act compliance deadline clustering.
Sensitivities concentrate around generative AI tutoring adoption curves, regulatory enforcement delay risks, and open-source platform substitution thresholds. Quarterly review of certification body partnership announcements and enterprise LMS procurement RFPs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Corporate Training and Talent Development
Talent As a Service Market
Corporate Training and Talent Development
Corporate Leadership Training Market
Corporate Training and Talent Development
Frontline Workers Training Market
Corporate Training and Talent Development
Executive Coaching Certification Market
Corporate Training and Talent Development
Global Sales Training Market
Corporate Training and Talent Development
Competency-Based Education Spending Market
Corporate Training and Talent Development
Corporate Workforce Development Training Market
Corporate Training and Talent Development
Europe Executive Search (Headhunting) Market
Corporate Training and Talent Development
Asia Pacific Strategic Consulting Services Market
Corporate Training and Talent Development
Asia Pacific HR Professional Services Market
Corporate Training and Talent Development
Middle East and Africa Management Consulting Services Market
Corporate Training and Talent Development
Europe Management Consulting Services Market
Corporate Training and Talent Development
Corporate Training Software Market
Corporate Training and Talent Development
United States HR Professional Service Market
Corporate Training and Talent Development
Integrated Talent Management Market
Corporate Training and Talent Development
Corporate eLearning Market