
 Educational Content Development Service Market | 2026-2036
Educational Content Development Service Market Size, Share, and Industry Trends Forecast 2026-2036
Educational Content Development Service Market Insights
GDPR's extraterritorial reach is consolidating data sovereignty requirements for educational content hosting across European learner management systems. Blue Carrot leverages its animation production scale to anchor premium video tutorial creation for institutional clients. SweetRush sustains competitive positioning through specialized gamification design capabilities that differentiate its corporate training modules. AllenComm dominates compliance-driven curriculum design for regulated industries navigating OSHA and HIPAA training mandates.
Educational content development service encompasses the systematic design, production, and validation of structured learning materials spanning multimedia assets, competency-aligned assessments, and pedagogical frameworks calibrated to measurable outcome criteria. These services transform subject matter expertise into scaffolded instruction sequences deployable across synchronous and asynchronous delivery infrastructures. Course development and e-learning modules command the largest share of current service revenue as institutions prioritize scalable digital credential pathways. Assessment design represents the fastest-expanding segment as employers demand verified skill demonstrations rather than completion certificates, while curriculum design retains mature margin pools in K-12 and higher education accreditation cycles.
The U.S. Department of Education's Title IV eligibility standards shape demand for accredited content formats, while the EU AI Act imposes algorithmic audit requirements on adaptive learning systems deployed across member states. India's BIS certification framework for digital educational materials creates market access barriers for unstandardized imports. Stakeholders must monitor divergent national AI governance trajectories to determine where localization investments preserve platform eligibility versus where partnership models reduce compliance burden.
Market Dynamics
AI-assisted authoring tools are compressing production timelines for educational content studios while simultaneously elevating buyer expectations for personalized learning pathways at scale.
Growth Catalysts
- EU AI Act:Algorithmic transparency mandates for adaptive learning platforms are accelerating investment in compliance-ready content architectures across European institutional procurement.
- Federal workforce development grants:US Department of Education Title IV eligibility standards sustain premium service demand from accredited vocational training providers.
- Corporate L&D budget expansion:Enterprise reskilling initiatives prioritize verified skill demonstrations over completion certificates, expanding assessment design contracts.
Market Restraints
- Specialized instructional designer scarcity:Talent pipelines for competency-aligned assessment architecture lag behind platform deployment timelines.
- Data sovereignty fragmentation:GDPR extraterritorial reach forces redundant hosting infrastructure across European learner management systems.
- Algorithmic audit costs:EU AI Act compliance investments consume 15-25% of adaptive platform development budgets before content production begins.
Strategic Opportunities
- India's BIS certification framework:Standardized digital educational material requirements create first-mover advantages for localized production partnerships.
- Immersive technology convergence:AR/VR training modules for hazardous environment simulation open premium pricing tiers in energy and manufacturing verticals.
- Skills-based hiring mandates:Employer verification demands shift procurement toward outcome-validated micro-credential pathways.
Industry Challenges
- Legacy LMS integration friction:SCORM and xAPI interoperability gaps delay deployment of next-generation adaptive content in established institutional accounts.
- Multimodal IP licensing complexity:Rights clearance for third-party media assets in video tutorial production extends project timelines unpredictably.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Educational Content Development Service Market |
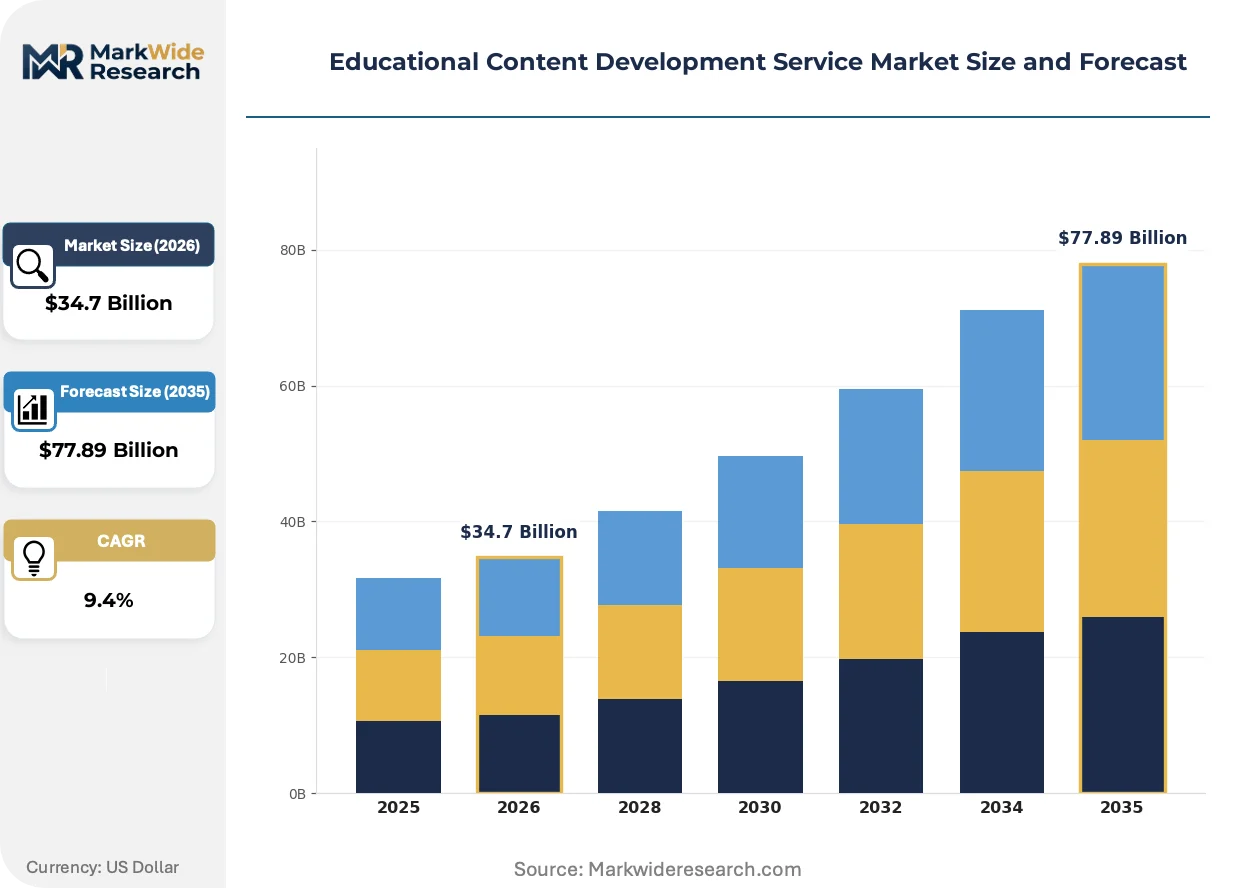
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $77.89 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Course Development, E-Learning Modules, Assessment Design, Curriculum Design Delivery Mode: Online Learning, Blended Learning, Virtual Classrooms, Instructor-Led Training Target Audience: Students, Corporates, Educators, Institutions Content Type: Video Tutorials, Interactive Quizzes, Textual Resources, Simulation Exercises |
| Companies Covered | Blue Carrot, SweetRush, AllenComm, ELB Learning, CommLab India, Learning Pool, MindSpring, EI Design, Udemy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Educational Content Development Service Market Trends and Innovations
Generative AI is fragmenting traditional studio production models while enabling real-time content personalization that was technically infeasible three years ago.
Multimodal large language models are decentralizing instructional design workflows by enabling subject matter experts to generate scaffolded lesson sequences without intermediary content architects. Corporate training departments in regulated industries are adopting these tools fastest, compressing vendor dependency for routine compliance module updates. This capability shift is decentralizing revenue concentration away from full-service studios toward hybrid human-AI production models.
The EU AI Act's algorithmic audit requirements are forcing transparency documentation into adaptive learning platform architectures. Content developers must now embed explainability features that trace personalization decisions to specific learner data inputs. European higher education institutions deploying adaptive systems face the steepest compliance retrofit costs, driving consolidation toward vendors with pre-certified transparency frameworks.
Enterprise buyers are unbundling assessment design from full-course development, contracting specialized vendors for verified skill demonstration architectures. This purchasing pattern displaces bundled service relationships that dominated corporate L&D procurement for the past decade. The shift is most visible in US healthcare and financial services verticals where regulatory scrutiny of training effectiveness has intensified.
Educational Content Development Service Market Segmentation
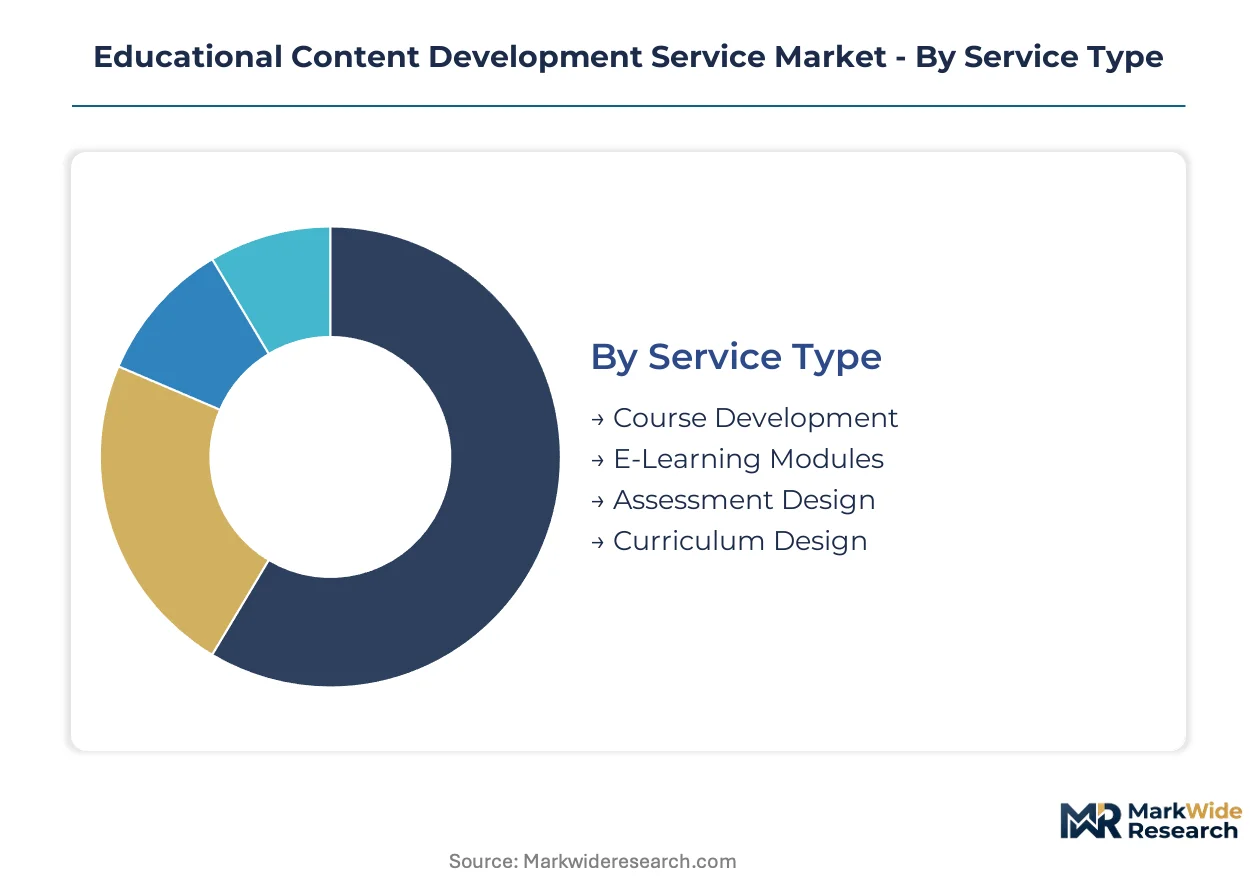
Educational content development services fragment across four distinct dimensions that determine production economics and buyer procurement patterns. Service type and delivery mode configurations directly shape staffing requirements and technology infrastructure investments. Target audience and content type selections govern royalty structures and platform integration complexity.
Service Type:
Upgrade cycles for learning management systems are compressing from five-year to eighteen-month refresh intervals, forcing content architecture decisions that anticipate platform migration.
- Course Development:Comprehensive instructional design encompassing learning objectives, module sequencing, and outcome mapping for credential-bearing programs. US community colleges and German vocational academies drive procurement as federal workforce grants expand eligibility requirements.
- E-Learning Modules:Self-contained digital learning units deployable across SCORM and xAPI standards with embedded progress tracking. Corporate L&D departments in healthcare and financial services verticals prioritize these for compliance training refresh cycles.
- Assessment Design:Competency-aligned evaluation architectures with psychometric validation for high-stakes certification.
- Curriculum Design:Multi-year instructional frameworks aligned to accreditation standards and regulatory mandates.
E-Learning Modules sits at the top of the volume ranking, with Assessment Design climbing the fastest.
Delivery Mode:
Cost tier differentiation separates premium synchronous offerings from economy asynchronous deployments, with mid-market blended configurations capturing procurement flexibility.
- Online Learning:Fully asynchronous digital delivery through web-based platforms with automated progress tracking and adaptive personalization engines. India's BIS certification framework and EU AI Act algorithmic audit requirements are reshaping platform eligibility standards.
- Blended Learning:Integrated synchronous and asynchronous components combining scheduled live sessions with self-paced digital resources. US higher education institutions deploying Title IV-eligible programs favor this model for retention optimization.
- Virtual Classrooms:Real-time video-conference instruction with breakout rooms and collaborative whiteboards.
- Instructor-Led Training:Face-to-face delivery with printed materials and physical equipment for hands-on skill demonstration.
Online Learning captures the largest revenue pool, while Blended Learning gains share fastest among accredited institutional buyers.
Target Audience:
Application-specific requirements diverge sharply between compliance-driven corporate procurement and pedagogical-outcome-focused institutional purchasing.
- Corporates:Enterprise training departments procuring reskilling and compliance modules with verified skill demonstration requirements. OSHA and HIPAA mandates in US regulated industries sustain premium pricing for audit-ready content architectures.
- Institutions:Universities, colleges, and K-12 systems requiring accreditation-aligned curriculum with measurable learning outcome documentation. European higher education faces steepest EU AI Act compliance retrofit costs.
- Students:Direct-to-learner supplemental education and test preparation services.
- Educators:Teacher professional development and instructional methodology certification programs.
Corporates anchor current revenue concentration, with Institutions expanding most quickly as federal workforce development grants amplify.
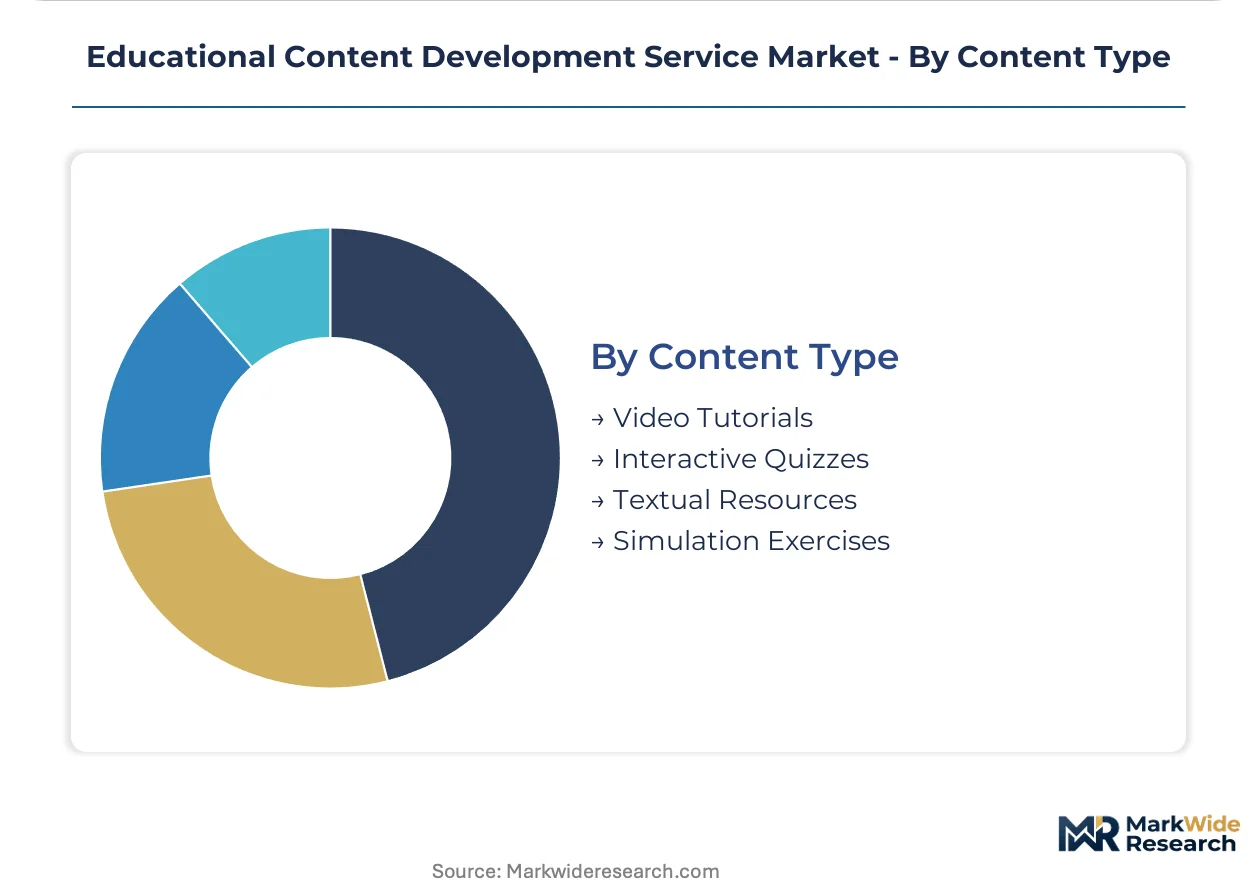
Content Type:
Customer type segmentation separates enterprise buyers demanding immersive simulation capabilities from individual learners prioritizing mobile-accessible microlearning formats.
- Video Tutorials:Scripted visual instruction with professional voiceover and motion graphics production for procedural skill demonstration. Animation studios leverage production scale to anchor premium institutional contracts.
- Simulation Exercises:Interactive scenario-based learning environments for hazardous condition rehearsal without physical risk. Energy and manufacturing verticals in Germany and the United States open premium pricing tiers for AR/VR-enabled safety training.
- Interactive Quizzes:Gamified assessment elements with immediate feedback loops and spaced repetition algorithms.
- Textual Resources:Downloadable documents, case studies, and reference materials for offline consumption.
Video Tutorials commands the highest production volume, with Simulation Exercises showing steepest expansion trajectory as immersive technology costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Workforce development specialists cluster in federal grant corridors across the United States, while algorithmic compliance architects concentrate in European regulatory hubs. India's certification engineers and China's platform developers anchor Asia-Pacific production capacity.
United States
Community college systems and corporate L&D departments drive procurement volume through Title IV workforce development grants. OSHA and HIPAA training mandates sustain premium pricing for audit-ready compliance architectures. Austin and Raleigh-Durham clusters host adaptive learning platform developers serving healthcare and financial services verticals.
Germany
Vocational academies and industrial consortiums demand competency-aligned assessment frameworks for dual education pathways. EU AI Act algorithmic transparency requirements force retrofit investments into existing adaptive platforms. Munich and Stuttgart engineering clusters specialize in AR/VR safety simulation modules for manufacturing and energy sectors.
India
BIS certification requirements for digital educational materials create localization barriers for imported content platforms. Corporate training outsourcing and K-12 supplemental education segments expand procurement from domestic studios. Bengaluru and Hyderabad technology corridors concentrate e-learning module production for North American and European clients.
United Kingdom
Higher education institutions prioritize blended learning architectures to optimize Title IV-equivalent international student retention. GDPR data sovereignty requirements force redundant hosting infrastructure across learner management systems. London and Manchester edtech clusters develop assessment design capabilities for skills-based hiring verification.
China
Provincial education bureaus and corporate training departments scale procurement for credential-bearing microlearning pathways. National standards for digital educational content create compliance thresholds for platform market access. Beijing and Shanghai technology districts concentrate AI-assisted authoring tool development for domestic and export markets.
Educational Content Development Service Market Competitive Landscape
The competitive structure tilts toward specialized service boutiques rather than integrated platform conglomerates. Full-service studios compete with modular specialists across assessment design, gamification architecture, and immersive simulation development. Two archetypes dominate: compliance-focused curriculum architects serving regulated industries, and production-scale animation studios anchoring video tutorial contracts. Strategic moves concentrate on technology licensing partnerships for AI-assisted authoring tools and geographic expansion through localized certification compliance.
Within the full-service studio tier, Blue Carrot and SweetRush occupy differentiated positions. Blue Carrot exemplifies production-scale animation capabilities that anchor premium institutional video contracts. SweetRush represents specialized gamification design expertise that differentiates corporate training module procurement. AllenComm sits within the compliance-architect archetype, with positioning shaped by regulated industry curriculum mandates.
| Leading Market Players |
|---|
| Blue Carrot |
| SweetRush |
| AllenComm |
| ELB Learning |
| CommLab India |
| Learning Pool |
| MindSpring |
| EI Design |
| Udemy |
| Others |
Pricing and Supply Chain Analysis
Instructional designer talent pools in Bengaluru and Hyderabad anchor labor-cost differentials that separate premium compliance-grade content from economy-tier module production. EU AI Act algorithmic audit requirements widen these spreads as transparency documentation adds fixed-cost layers to European delivery.
Pricing Analysis
The bundled-vs-unbundled service split is fragmenting procurement relationships across corporate L&D departments. Project-based pricing dominates full-course development while subscription SaaS tiers capture recurring assessment design contracts. Price differentiation hinges on psychometric validation depth and OSHA or HIPAA certification alignment. Cost compression in economy-tier e-learning modules intensifies as AI-assisted authoring tools enable client self-production. Healthcare and financial services buyers show lowest price sensitivity due to regulatory audit requirements.
Supply Chain Analysis
Freight costs for physical training equipment and AR/VR hardware tether margin performance to logistics corridors serving German manufacturing and US energy verticals. Content production concentrates in India, the United States, and Germany. Raw material dependencies include cloud compute capacity, motion capture studios, and third-party media licensing. Single-source vulnerability sits with specialized instructional design talent pipelines. Distribution runs through direct enterprise sales teams and learning management system vendor marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as employer verification demands shift procurement toward outcome-validated micro-credential pathways with premium pricing power.
For Market Incumbents: Anticipate margin compression from generative AI decentralization by deepening proprietary assessment psychometric libraries and securing EU AI Act pre-certification for adaptive platforms. Talent scarcity for competency-aligned architects threatens service delivery timelines. Backward integration into animation production preserves video tutorial margin pools. For New Entrants and Emerging Players: India's BIS certification framework opens a window for localized production partnerships serving North American and European clients seeking cost-advantaged compliance-grade content. White-space targets include AR/VR safety simulation for German manufacturing and skills-based hiring verification tools for US healthcare. A channel partnership with established LMS vendors accelerates enterprise access. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap assessment design boutiques with psychometric validation capabilities and healthcare vertical concentration. Long-term viability hinges on AI-human hybrid production models that preserve quality differentiation. The signal to watch is corporate procurement unbundling velocity in regulated industries.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification Investment | Algorithmic transparency frameworks preserve platform eligibility across German and French institutional procurement. |
| Assessment Design Capability Acquisition | Psychometric validation expertise captures enterprise contracts shifting toward verified skill demonstrations. |
| India Localization Partnership | BIS compliance and labor-cost advantages anchor cost-competitive delivery for North American clients. |
| AR/VR Safety Simulation Development | Immersive training modules open premium pricing tiers in German energy and US manufacturing verticals. |
| AI-Assisted Authoring Tool Licensing | Technology partnerships compress production timelines while maintaining human quality oversight. |
Research Methodology
Multiple input streams — executive interviews with corporate L&D directors, procurement discussions with higher education technology officers, and validation sessions with instructional design studio heads — were reconciled against secondary sources including US Department of Education Title IV eligibility documentation, EU AI Act regulatory filings, and India BIS certification standards. Bottom-up service revenue estimates and top-down market sizing approaches were cross-checked for convergence.
Data-stream reconciliation across service type, delivery mode, target audience, and content format dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectories weighted by procurement pattern shifts toward assessment design and immersive simulation. Forecast inputs incorporated federal workforce development grant allocations and algorithmic audit cost assumptions for European adaptive platform deployment.
Revisions become necessary when EU AI Act enforcement intensity, India BIS certification timeline delays, or generative AI capability breakthroughs materially alter production economics. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Education & Training
Global IoT in Education Market
Education & Training
Executive Education Program Market
Education & Training
Competency-Based Education Spending Market
Education & Training
M-Education Market
Education & Training
Europe Leadership Development Program Market
Education & Training
General Medicine Education Publishing Market
Education & Training
Cloud-Based Training Software Market
Education & Training
Kindergarten Books Market
Education & Training
Virtual Reality in Education Market
Education & Training
Global Mobile Learning Market
Education & Training
Online Language Learning Market
Education & Training
Global Edutainment Centers Market
Education & Training
Poland Higher Education Market
Education & Training
Vocational English Course Counselling Solution Market
Education & Training
Europe Management Consulting Services Market
Education & Training
Africa E-Learning Market