
 Europe K12 Education Market | 2026-2036
Europe K12 Education Market Size, Share, and Industry Trends Forecast 2026-2036
Europe K12 Education Market Analytics
Private school operators across France and Spain are realigning curriculum delivery around hybrid instruction models. Pearson PLC leverages its century-old assessment infrastructure to dominate standardized testing content across British and Irish jurisdictions. Nord Anglia Education anchors its premium positioning through proprietary global curricula delivered at campuses in Switzerland, the Netherlands, and Portugal. Cognita competes on scale, operating more than one hundred schools from the United Kingdom through Italy and Germany.
Europe K12 education encompasses structured primary and secondary instruction delivered through state-funded, independent, and international school systems, integrating physical learning materials with cloud-hosted platforms, interactive displays, and adaptive assessment engines to develop student competencies through age-graded progression. E-learning platforms and digital tools command expanding budget share as ministries in Denmark and Sweden mandate one-to-one device programs. Blended learning and hybrid models attract capital fastest where broadband penetration exceeds national averages, while traditional classroom delivery retains volume leadership across Eastern European markets where infrastructure gaps persist. Learning management systems and educational apps capture disproportionate margin pools relative to hardware categories facing commoditization.
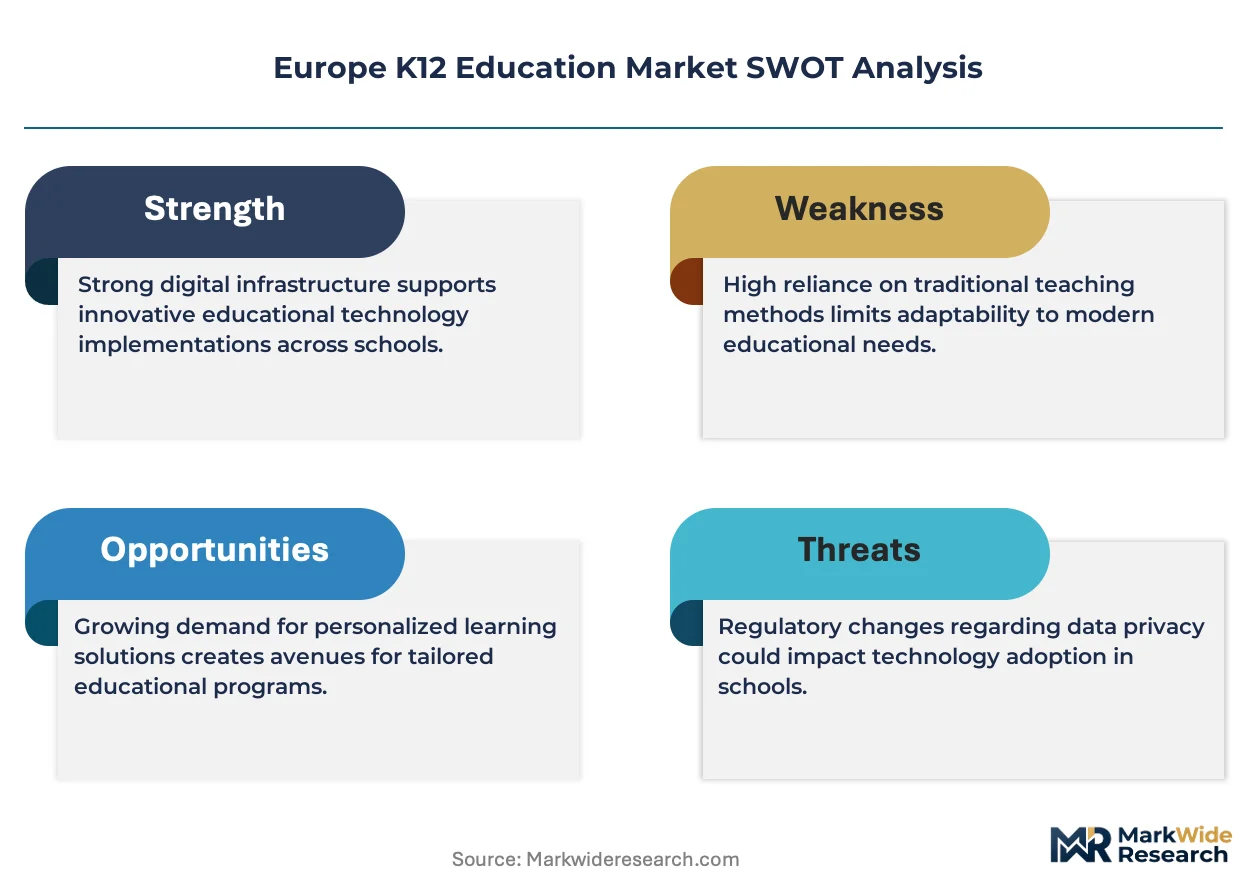
The EU AI Act imposes risk-tiered obligations on automated tutoring and student analytics deployed across member states, while GDPR constrains how platforms process pupil biometric and behavioral data. ECHA guidelines on electronic waste and REACH substance restrictions affect hardware refresh cycles for interactive whiteboards and tablets procured under national education tenders. Stakeholders must track how national interpretations of the AI Act's high-risk system definitions reshape procurement specifications and vendor qualification criteria.
Market Dynamics
The EU AI Act's risk-tiered compliance obligations are restructuring how European schools procure automated tutoring systems and student analytics platforms. Vendors must now navigate divergent national interpretations of high-risk system definitions while maintaining cross-border service continuity.
Growth Catalysts
- GDPR-mandated data sovereignty:Schools across Germany and France prioritize EU-hosted learning management systems. Cloud localization requirements accelerate replacement of non-compliant legacy platforms.
- One-to-one device mandates:Danish and Swedish ministries now require universal student tablet access. Procurement volumes for ruggedized hardware and MDM software surge accordingly.
- Hybrid instruction permanence:Private school networks in Spain and Portugal have institutionalized blended delivery models. Sustained investment flows toward synchronous virtual classroom infrastructure.
Market Restraints
- REACH substance restrictions:ECHA guidelines on restricted chemicals in electronics complicate tablet and interactive display manufacturing. Supply chains face reformulation costs and extended certification timelines.
- Broadband infrastructure gaps:Rural districts in Eastern Europe lack fiber connectivity for cloud-dependent learning platforms. Digital divide constraints limit addressable market expansion.
- Teacher digital literacy deficits:Workforce readiness for adaptive assessment engines and AI-assisted tutoring tools lags hardware deployment. Training burdens extend implementation cycles.
Strategic Opportunities
- Portugal's EdTech subsidy schemes:National recovery funds allocate dedicated capital for classroom digitization. Vendors with localized compliance documentation capture preferential tender status.
- Immersive technology convergence:AR/VR content layers integrate with existing LMS architectures. Early movers in vocational STEM curricula establish platform stickiness.
- Outcome-based procurement pilots:British academy trusts experiment with literacy improvement guarantees rather than seat licenses. Performance contracting restructures vendor-client risk allocation.
Industry Challenges
- Interoperability fragmentation:Proprietary data formats from dominant LMS providers obstruct seamless content migration. Schools face vendor lock-in despite regulatory pressure for portability.
- Biometric consent complexity:GDPR Article 8 restrictions on processing children's biometric data for attendance or proctoring create jurisdictional uncertainty. Platform developers must engineer region-specific feature sets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe K12 Education Market |
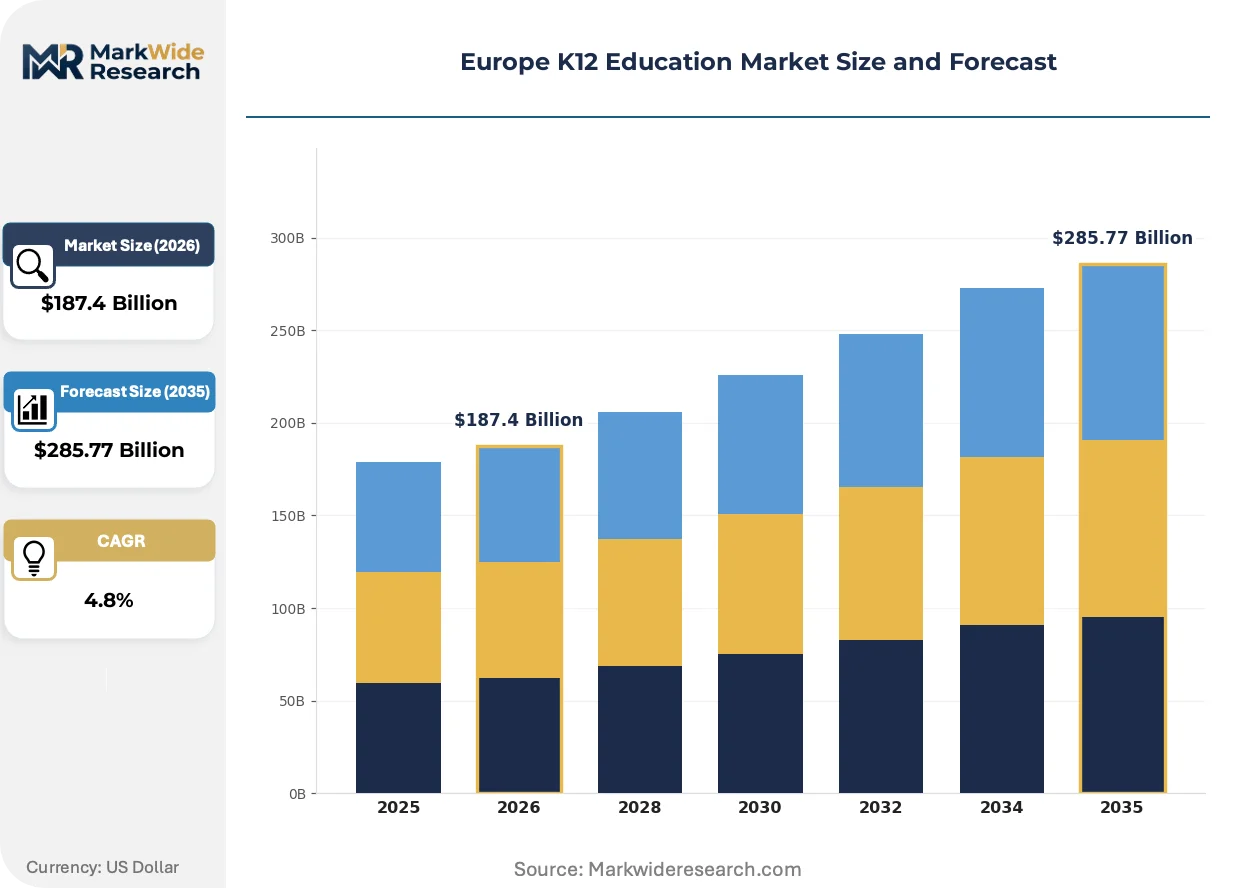
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textbooks, E-learning Platforms, Classroom Supplies, Digital Tools Delivery Mode: Online Learning, Blended Learning, Traditional Classroom, Hybrid Models End User: Primary Schools, Secondary Schools, Special Education Institutions, Tutoring Centers Technology: Learning Management Systems, Assessment Tools, Interactive Whiteboards, Educational Apps |
| Companies Covered | Pearson PLC, Nord Anglia Education, Cognita, International Schools Partnership, Inspired Education Group, Globeducate, Oracle Corporation, Samsung Electronics, Blackboard, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe K12 Education Market Evolving Landscape
European K12 technology procurement is pivoting from hardware-centric refresh cycles toward integrated platform ecosystems. Regulatory pressure and pedagogical evolution are converging to reshape vendor competitive dynamics.
Adaptive learning engines are unifying diagnostic assessment, personalized content sequencing, and progress analytics into single-platform architectures. British multi-academy trusts deploy these systems at scale across federated school networks. The technology is unifying previously siloed data streams into actionable instructional workflows, compressing vendor consolidation timelines.
The EU AI Act's high-risk system classification for educational scoring algorithms imposes conformity assessment obligations on automated grading platforms. German Länder education ministries now require documented algorithmic transparency for statewide tender eligibility. Assessment technology suppliers are reengineering scoring models to satisfy explainability mandates, prioritizing interpretable rule-based systems over opaque neural architectures.
Parental data rights activism is reshaping platform selection criteria beyond institutional IT preferences. Dutch school boards face organized pressure for granular consent mechanisms and deletion guarantees. Procurement committees in Flanders and Wallonia now weight privacy architecture as heavily as pedagogical features, elevating vendors with built-in data minimization protocols.
Europe K12 Education Market Segmentation
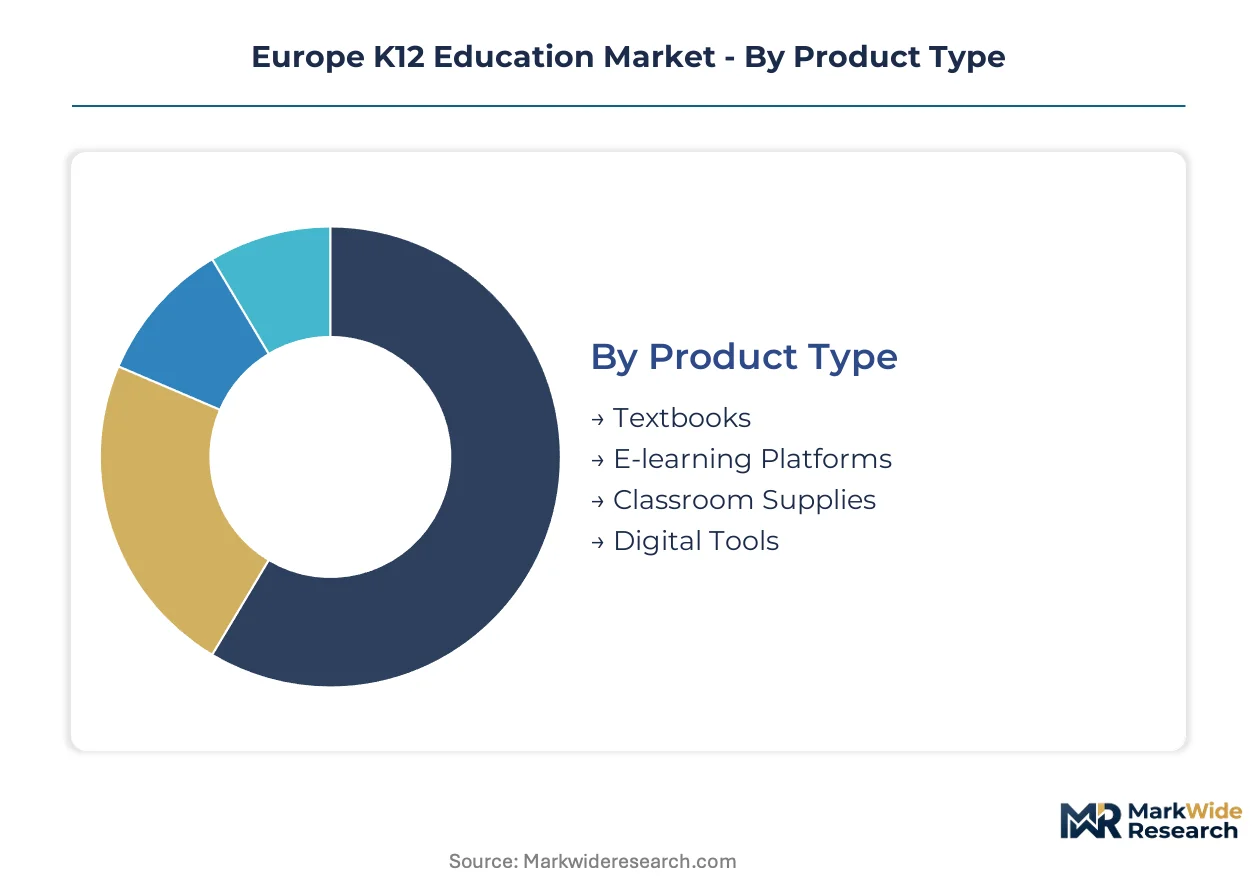
Segmentation in European K12 education reveals how procurement priorities diverge across institutional budgets, regulatory environments, and infrastructure maturity. Understanding these fault lines enables vendors to align product development with the specific compliance and pedagogical requirements of each buyer category.
Product Type:
Budget allocation patterns separate ministries funding core instructional materials from private operators investing in digital transformation.
- E-learning Platforms:Cloud-hosted learning environments integrate content libraries, progress tracking, and parental communication portals. German and French procurement specifications now mandate GDPR-compliant EU data residency, displacing legacy platforms hosted outside the bloc.
- Digital Tools:Adaptive assessment engines, AI tutoring modules, and collaboration software command premium pricing where the EU AI Act imposes conformity assessment obligations. Danish one-to-one device mandates accelerate district-level procurement of bundled software licenses.
- Textbooks:Physical instructional materials retain volume leadership across Eastern European markets where per-pupil spending constraints limit digital migration.
- Classroom Supplies:Consumables and physical equipment face margin compression from REACH substance compliance costs and ECHA electronic waste guidelines affecting refresh cycles.
Volume sits with Textbooks; growth tilts toward E-learning Platforms.
Delivery Mode:
Infrastructure readiness and teacher workforce capabilities determine which delivery models achieve institutional adoption.
- Blended Learning:Hybrid architectures combining synchronous virtual instruction with face-to-face sessions now dominate private school network strategies in Spain and Portugal. These models require integrated LMS-CRM systems that track attendance across physical and digital touchpoints.
- Hybrid Models:Flexible scheduling systems enabling rapid pivots between remote and in-person delivery gained permanent institutional status post-pandemic. British multi-academy trusts deploy these at scale across federated networks.
- Traditional Classroom:Conventional instructor-led delivery persists where broadband gaps in rural Eastern Europe constrain cloud-dependent alternatives.
- Online Learning:Fully remote instruction remains concentrated in supplementary tutoring segments and specialized curricula rather than mainstream state systems.
Traditional Classroom retains the largest installed base; Blended Learning captures the steepest expansion trajectory.
End User:
Institutional type shapes procurement authority, budget scale, and regulatory exposure.
- Secondary Schools:Upper-grade institutions drive demand for career-oriented STEM platforms and examination preparation systems. British academy trusts and German Gymnasien represent concentrated procurement volume for assessment technology.
- Primary Schools:Foundational literacy and numeracy platforms prioritize intuitive interfaces for early learners. Swedish municipalities mandate device access starting at age six, expanding addressable market for ruggedized hardware.
- Tutoring Centers:Supplementary instruction providers compete on outcome metrics, creating demand for granular progress analytics and parent-facing dashboards.
- Special Education Institutions:Accessibility-compliant platforms serving diverse learning needs face specialized procurement requirements under national disability frameworks.
Secondary Schools command the largest technology budgets; Primary Schools are expanding most quickly under national digitization mandates.
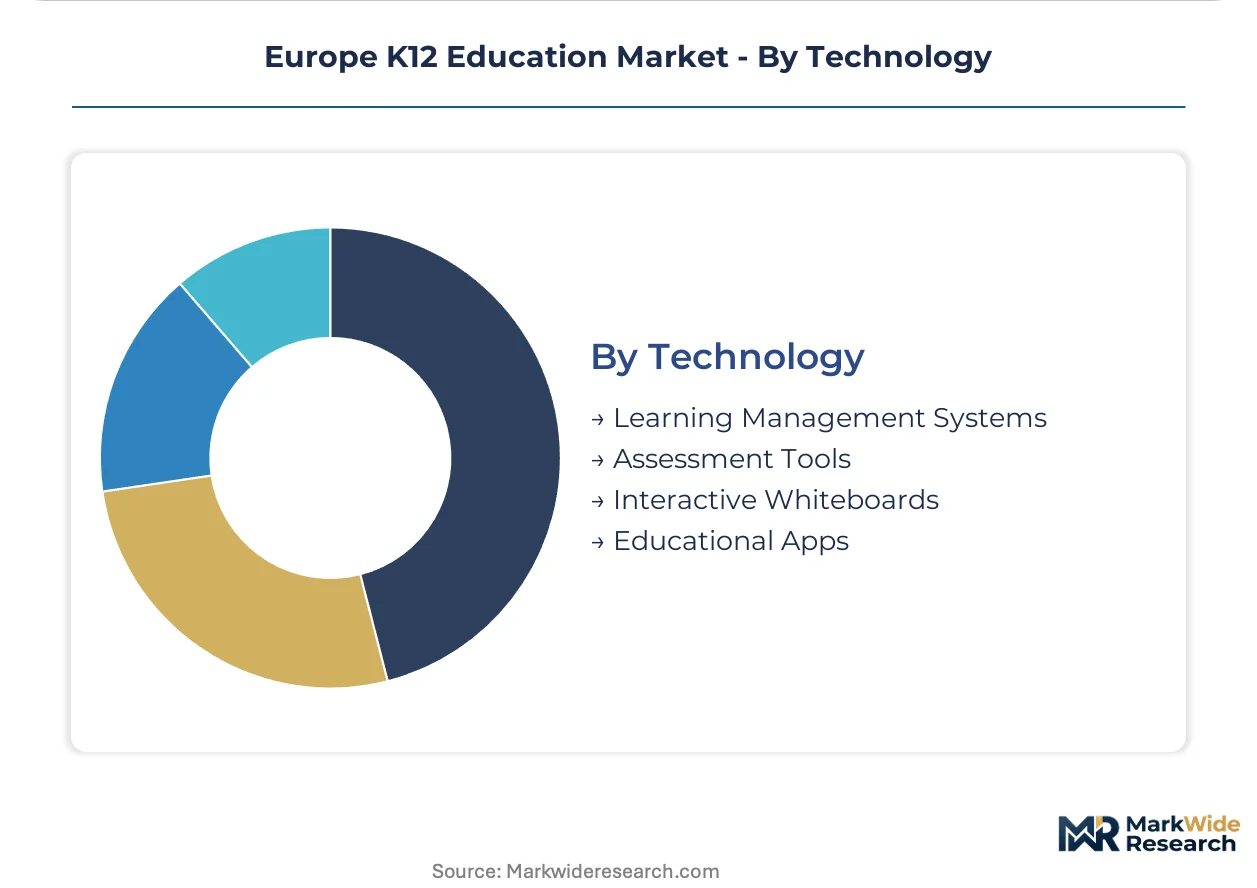
Technology:
Vendor competitive dynamics concentrate in software categories where data architecture determines regulatory compliance.
- Learning Management Systems:Centralized platforms for content delivery, assignment management, and gradebook integration now function as institutional operating systems. GDPR Article 8 restrictions on children's biometric data force region-specific feature engineering.
- Assessment Tools:Automated scoring and diagnostic engines face EU AI Act high-risk system classification, requiring algorithmic transparency documentation for German Länder tender eligibility.
- Educational Apps:Mobile-first supplementary content targets parent-funded segments outside core institutional procurement, facing fragmented distribution through app store channels.
- Interactive Whiteboards:Display hardware faces commoditization pressure and REACH substance compliance costs, with margin pools shifting to embedded software and content subscriptions.
Interactive Whiteboards represent the mature volume category; Learning Management Systems are gaining share fastest as institutional platform consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German federalism anchors education technology procurement across the continent. Länder-level budget autonomy fragments tender specifications while creating concentrated demand pockets in industrialized western states.
Germany
Bavarian and North Rhine-Westphalian ministries drive procurement volume for GDPR-compliant learning management systems. The EU AI Act's high-risk system classification forces algorithmic transparency documentation for statewide assessment tenders. Berlin-Brandenburg clusters host ed-tech vendors engineering explainable scoring models for Gymnasium examination platforms.
United Kingdom
Multi-academy trusts in England consolidate technology spending across federated school networks. British procurement frameworks emphasize outcome-based contracting for literacy improvement guarantees rather than traditional seat licenses. Greater London and the Southeast concentrate vendor headquarters serving academy chains with integrated platform ecosystems.
France
Grand Est and Île-de-France regions prioritize hybrid instruction infrastructure for private school networks. CNIL guidance on children's biometric data processing shapes attendance system specifications. Parisian ed-tech clusters develop region-specific feature sets satisfying Article 8 consent requirements for facial recognition proctoring tools.
Sweden
Municipal digitization mandates expand one-to-one device programs starting at primary level. National procurement specifications favor ruggedized hardware meeting REACH substance restrictions for classroom durability. Stockholm and Gothenburg metropolitan areas concentrate systems integrators bundling tablets with mobile device management software.
Spain
Andalusian and Catalan private operators institutionalize blended learning models post-pandemic. National recovery funds allocate dedicated capital for classroom digitization through localized compliance documentation requirements. Madrid clusters host vendors capturing preferential tender status under Portugal-adjacent subsidy schemes.
Europe K12 Education Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adaptive assessment specialization and AI-assisted tutoring modules. The vendor base stratifies across three maturity tiers: century-old assessment infrastructure providers, premium international school network operators, and scale-driven multi-campus consolidators. Two dominant competitive moves define current positioning: proprietary curriculum differentiation through global campus networks and outcome-based procurement pilots restructuring vendor-client risk allocation.
Within the premium network tier, Nord Anglia Education and Cognita exemplify contrasting scale strategies. Pearson PLC anchors the assessment infrastructure segment through its established presence across British and Irish jurisdictions. These three entities represent the primary competitive archetypes: curriculum-integrated campus operators, multi-campus scale consolidators, and legacy assessment content providers.
| Leading Market Players |
|---|
| Pearson PLC |
| Nord Anglia Education |
| Cognita |
| International Schools Partnership |
| Inspired Education Group |
| Globeducate |
| Oracle Corporation |
| Samsung Electronics |
| Blackboard |
| Others |
Value Network & Pricing Analysis
Software engineering talent clusters in Berlin and Paris drive labor-cost differentials that separate premium adaptive learning platforms from economy-tier content libraries. GDPR compliance engineering and EU AI Act conformity assessment capabilities command wage premiums that propagate through SaaS subscription tiers.
Pricing Analysis
Warranty and service bundling separates enterprise LMS contracts from stripped-down software licenses. Three-tier pricing structure across premium, standard, and economy levels reflects algorithmic transparency certification status under German Länder tender rules. Price differentiation hinges on data residency guarantees and embedded professional development hours. Pricing pressure stems from REACH substance compliance costs compressing hardware margins. Private tutoring centers exhibit highest price sensitivity; British multi-academy trusts accept premium pricing for outcome-based literacy guarantees.
Supply Chain Analysis
Dual-sourcing requirements in German and French ministry tenders mandate multi-supplier qualification for cloud infrastructure and device procurement. Manufacturing concentrates in China, Taiwan, and South Korea for tablet components and interactive display panels. Supply chains draw from rare earth elements, lithium-ion cells, and specialized semiconductor foundry capacity. Single-source vulnerability in EU-based data center hosting creates geopolitical exposure for GDPR-compliant platform delivery. Distribution runs through national systems integrators and direct ministry contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in EU-hosted cloud infrastructure prop pricing power for vendors with certified data residency capabilities. Capacity bottlenecks in algorithmic transparency engineering limit rapid scaling of AI-assisted tutoring platforms.
For Market Incumbents: Extend platform consolidation timelines by acquiring specialized assessment engine developers before EU AI Act high-risk system documentation requirements harden. Secure backward integration into cloud infrastructure through partnerships with EU-based hyperscaler regions. Certification investment in explainable AI scoring models represents the critical defensive lever against emerging adaptive learning specialists. For New Entrants and Emerging Players: Enter via Portugal's national recovery fund subsidy schemes where localized compliance documentation creates preferential tender access. Rural Eastern European districts with broadband infrastructure gaps present the most penetrable white-space for offline-capable blended learning platforms. Direct-to-school pilot programs with literacy improvement guarantees bypass incumbent LMS lock-in. For Investors and Strategic Acquirers: Re-rating potential sits with vocational STEM platform specialists given immersive technology convergence in German and Swedish curricula. Long-term viability favors vendors with proprietary content libraries and federated school network relationships. Acquisition target archetype: adaptive assessment engine developers with documented algorithmic transparency. The signal to watch is British academy trust outcome-based procurement adoption rates as inflection indicator for performance contracting normalization.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Algorithmic transparency documentation unlocks German Länder statewide tender eligibility. |
| Cloud Infrastructure Localization | GDPR-mandated EU data residency displaces non-compliant legacy platform providers. |
| Immersive Technology Integration | AR/VR content layers establish platform stickiness in vocational STEM curricula. |
| Outcome-Based Contracting Pilots | Literacy improvement guarantees restructure vendor-client risk allocation in British trusts. |
| Dual-Sourcing Partnership Development | Multi-supplier qualification satisfies French and German ministry procurement mandates. |
Research Methodology
Multi-period observation of device deployment ratios, cloud procurement volumes, and regulatory filing patterns anchored the trend analysis, supplemented by interviews with European education ministry procurement officers, LMS platform product managers, school IT directors, and special education curriculum coordinators. Secondary validation drew from EU AI Act implementation guidance, CNIL biometric data processing opinions, ECHA REACH substance restriction updates, and national education budget appropriations. Bottom-up school-level spending estimates triangulated against top-down ministry expenditure projections.
Segment-weighting approaches distributed total market value across product type, delivery mode, end user, and technology dimensions. CAGRs were derived from enrollment projections, device refresh cycles, and software subscription renewal rates across the analysis window. Forecast inputs incorporated broadband infrastructure rollout timelines, EU AI Act enforcement phase-in schedules, and national recovery fund allocation trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under delayed EU AI Act national interpretation harmonization or accelerated REACH substance restriction expansion. Deviation in German Länder education budget federalism would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Primary and Secondary Education
Qatar Private K12 Education Market
Primary and Secondary Education
North America K-12 Furniture Market
Primary and Secondary Education
UAE Private K12 Education Market
Primary and Secondary Education
In-Person Learning Market
Primary and Secondary Education
Oman Private K-12 Market
Primary and Secondary Education
K-12 Education Market
Primary and Secondary Education
Saudi Arabia Private K12 Education Market
Primary and Secondary Education
North America K12 Education Market
Primary and Secondary Education
GCC Private K12 Education Market
Primary and Secondary Education
Asia-Pacific School Furniture Market
Primary and Secondary Education
Back to School Market
Primary and Secondary Education
Oman Private K12 Education Market