
 Remote Learning Technology Spending Market | 2026-2036
Remote Learning Technology Spending Market Size, Share, and Industry Trends Forecast 2026-2036
Remote Learning Technology Spending Market Analytics
GDPR compliance is shifting the cost-of-entry calculus for European edtech deployments, forcing vendors to architect data sovereignty into platform foundations. Coursera leverages its institutional partnerships to sustain premium credentialing revenue streams across accredited university networks. Blackboard anchors its position through deep LMS integration with legacy student information systems in North American higher education. PowerSchool competes by extending its K-12 administrative software stack into adjacent classroom analytics and formative assessment tools.
Remote Learning Technology Spending encompasses institutional and enterprise procurement of software, hardware, and connectivity infrastructure enabling synchronous and asynchronous instruction outside traditional physical classrooms. Core functional parameters include sub-150 millisecond latency thresholds for real-time video, SCORM or xAPI interoperability standards for content portability, and AES-256 encryption for student data protection. Learning Management Systems dominate procurement volumes among higher education institutions, where multi-year enterprise licenses generate predictable recurring revenue pools. Video Conferencing Tools represent the fastest-expanding segment within corporate training environments, where hybrid workforce models require persistent virtual classroom capacity. Cloud-Based deployment leads across all end-user categories, though on-premises configurations persist in defense and financial services sectors with stringent data residency requirements.
The U.S. Department of Education enforces FERPA compliance for any platform processing student education records, while the EU AI Act imposes risk-classification obligations on adaptive learning algorithms deployed in European institutions. India's BIS certification requirements for educational hardware and the country's data localization directives under proposed digital privacy legislation are reshaping vendor market access strategies. Stakeholders must monitor how fragmented national AI governance frameworks will fragment platform development roadmaps and inflate compliance engineering costs.
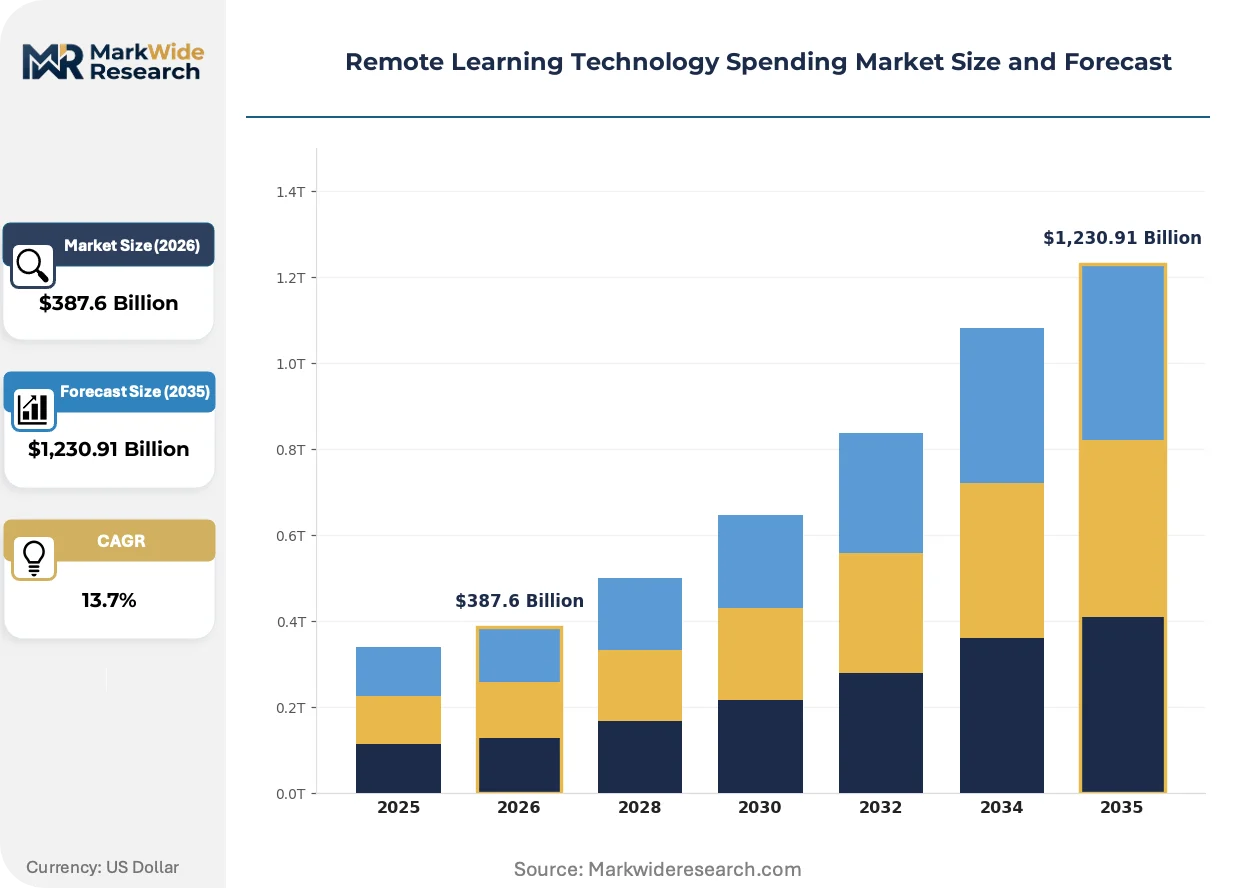
Market Dynamics
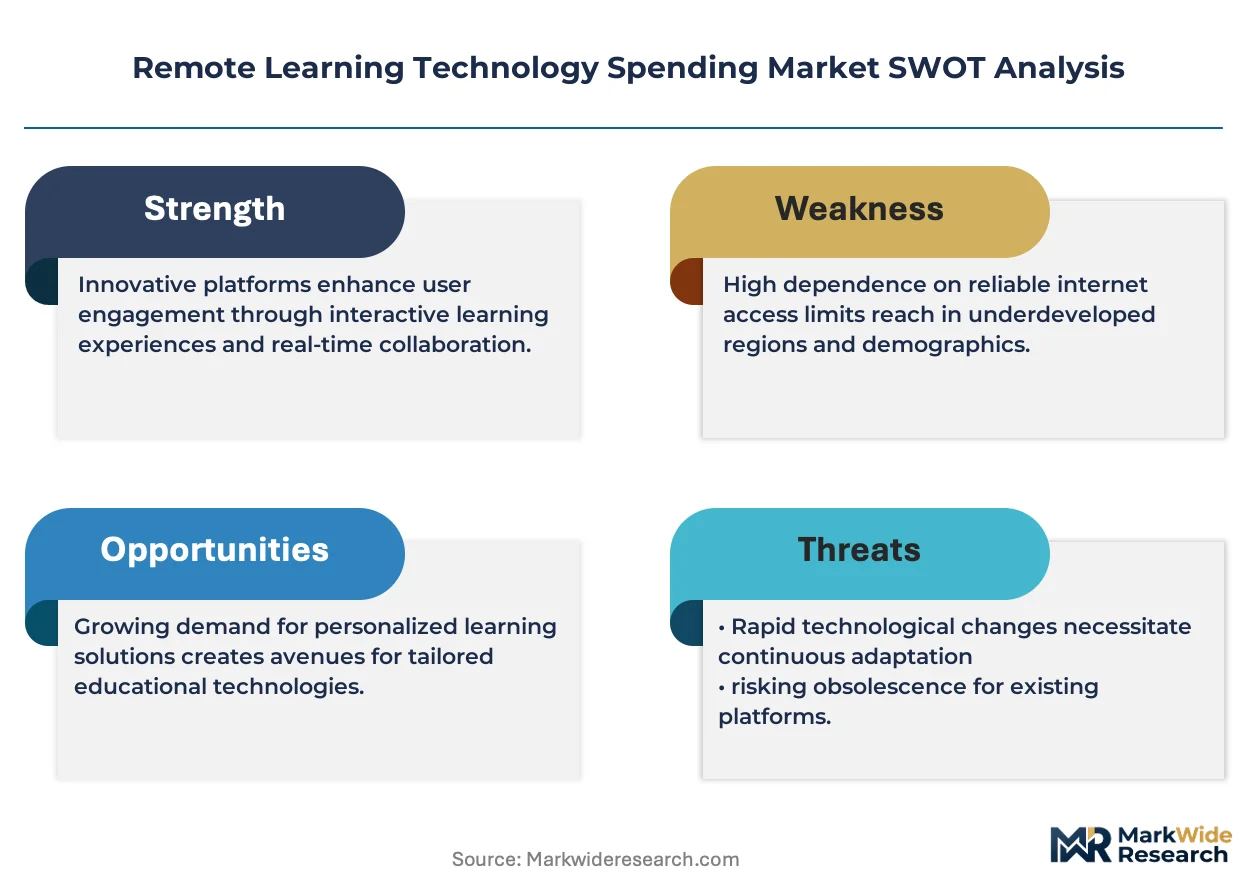
Cloud migration mandates from K-12 districts and higher education procurement offices are compressing on-premise infrastructure replacement cycles while redirecting capital toward subscription-based learning platforms.
Growth Catalysts
- ESSA Accountability Mandates:US school districts must demonstrate measurable student outcomes, forcing investment in analytics-integrated LMS platforms that track proficiency metrics in real time.
- Adaptive Learning Engines:AI-powered personalization algorithms are redirecting institutional R&D budgets toward architectures that customize content sequencing based on individual learner performance data.
- India:The National Education Policy and Digital India infrastructure investments are generating government tenders for integrated LMS and digital content ecosystems at scale.
Market Restraints
- GDPR Compliance Engineering:European deployments require data sovereignty architecture from platform foundations, inflating upfront development costs and extending sales cycles.
- Latency Infrastructure:Sub-150 millisecond thresholds for synchronous video demand fiber-optic backbone investments that rural and emerging-market districts cannot finance.
- Legacy SIS Integration:Deep entrenchment of student information systems in North American higher education creates switching friction that locks institutions into incumbent vendors.
Strategic Opportunities
- Corporate Training Hybridization:Persistent virtual classroom capacity requirements from distributed workforce models are expanding addressable market beyond traditional education verticals.
- xAPI Interoperability:Next-generation learning record stores capturing experience data outside formal courses enable credential portability across institutional boundaries.
- India's Data Localization:Proposed digital privacy legislation requiring domestic data storage creates first-mover advantage for vendors architecting compliant infrastructure.
Industry Challenges
- AI Governance Fragmentation:Divergent national frameworks for algorithmic risk classification force platform vendors to maintain multiple development roadmaps simultaneously.
- SCORM-to-xAPI Migration:Content portability standard transitions require costly re-authoring of legacy courseware libraries that institutions resist funding.
- FERPA-AI Act Overlap:Concurrent US and EU compliance obligations for student data protection and algorithmic transparency create engineering conflicts in feature design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remote Learning Technology Spending Market |
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,230.91 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Learning Management Systems, Video Conferencing Tools, Digital Courseware, Assessment Software End User: K-12 Schools, Higher Education Institutions, Corporations, Training Providers Deployment Model: Cloud-Based, On-Premises, Hybrid, Mobile Pricing Model: Subscription, One-Time License, Freemium, Pay-Per-Use |
| Companies Covered | D2L, 360Learning, Coursera, Blackboard, PowerSchool, Udemy, Docebo, Absorb LMS, Duolingo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remote Learning Technology Spending Market Evolving Landscape
Generative AI integration is compressing content production timelines while forcing vendors to renegotiate intellectual property frameworks with institutional publishers.
Natural language processing engines embedded in tutoring platforms are automating formative assessment generation, enabling real-time misconception identification without instructor intervention. Community colleges and vocational programs are adopting these tools fastest due to staffing constraints. This capability is automating the labor-intensive feedback loops that previously limited course scalability.
The EU AI Act's risk-classification obligations for educational algorithms are forcing European deployments to document training data provenance and bias mitigation protocols. Vendors must now maintain algorithmic impact assessments as auditable artifacts. Higher education institutions in Germany and France are delaying procurement until compliance pathways clarify, compressing near-term revenue recognition.
Enterprise learning buyers are unbundling perpetual licenses into modular component subscriptions, separating content libraries from delivery platforms from analytics dashboards. Corporate training departments now procure best-of-breed point solutions rather than monolithic suites. This pattern is most visible in US financial services and technology sectors where internal learning operations teams possess integration expertise.
Remote Learning Technology Spending Market Segmentation
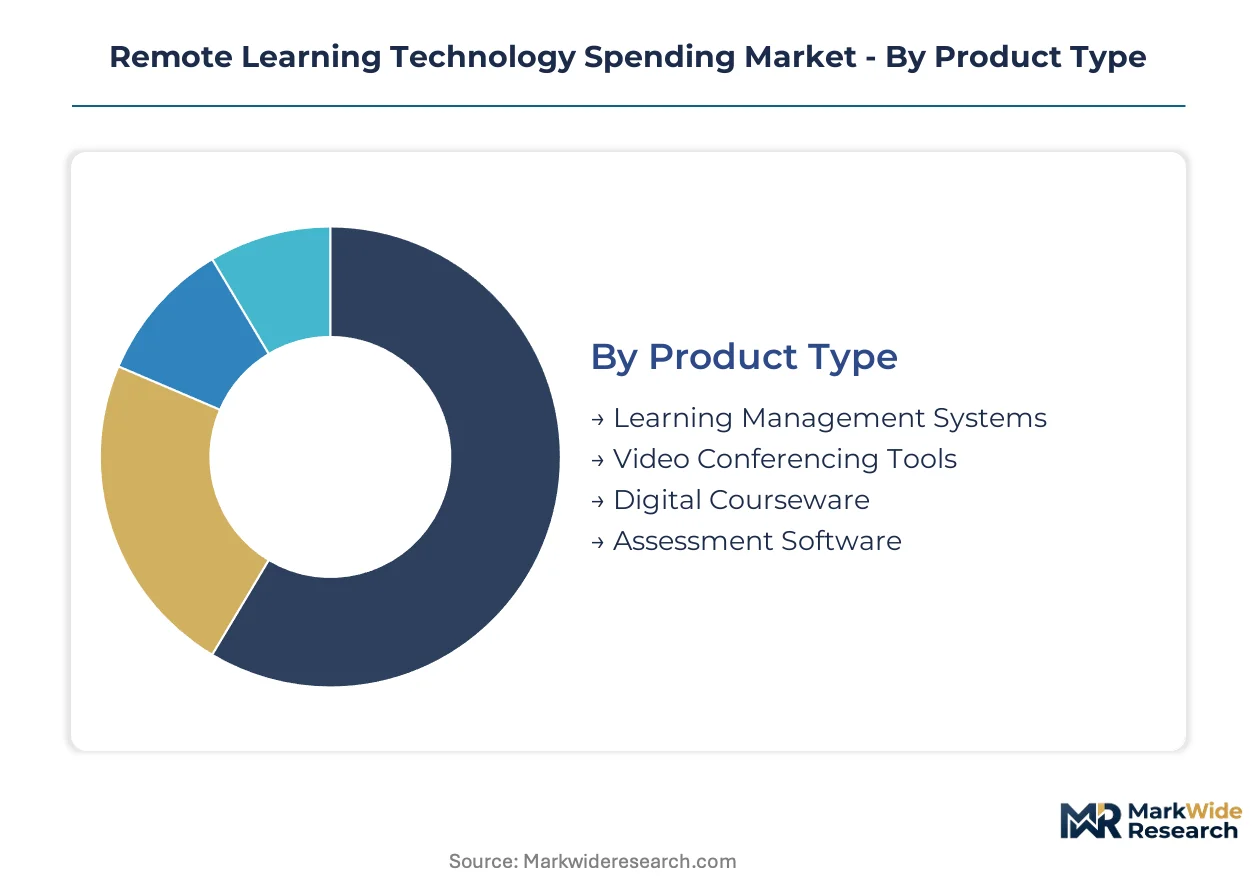
Procurement patterns in remote learning technology diverge sharply across institutional contexts, with latency requirements, compliance obligations, and legacy system entrenchment creating distinct demand profiles. Vendors must architect platform variants that reconcile these divergent specifications without fragmenting development roadmaps beyond recovery.
Product Type:
Functional architecture determines integration complexity and renewal economics across institutional procurement cycles.
- Learning Management Systems:Multi-tenant platforms with SCORM/xAPI interoperability and gradebook synchronization anchor enterprise licensing in higher education. North American universities concentrate demand here, driven by ESSA accountability mandates requiring real-time proficiency tracking and longitudinal analytics.
- Video Conferencing Tools:Sub-150 millisecond latency engines with AES-256 encryption and breakout room orchestration dominate synchronous instruction infrastructure. Corporate training environments in US financial services and technology sectors are expanding procurement fastest, compelled by persistent hybrid workforce models requiring scheduled virtual classroom capacity.
- Digital Courseware:Interactive content libraries with adaptive sequencing algorithms and embedded formative assessments.
- Assessment Software:Proctoring engines with biometric identity verification and plagiarism detection protocols.
Learning Management Systems lead on scale; Video Conferencing Tools lead on momentum.
End User:
Budget authority and procurement velocity vary dramatically across institutional buyer categories.
- K-12 Schools:District-level purchasing consortia with ESSA-mandated outcome accountability and Title I funding eligibility requirements. US school districts are accelerating cloud migration, compressing on-premise replacement cycles while redirecting capital toward subscription-based analytics-integrated platforms.
- Corporations:Enterprise learning operations teams with modular procurement authority and internal integration expertise. US financial services and technology sectors are unbundling perpetual licenses into component subscriptions, separating content libraries from delivery platforms from analytics dashboards.
- Higher Education Institutions:Multi-year enterprise license negotiators with deep legacy SIS entrenchment creating vendor lock-in friction.
- Training Providers:Agile buyers with rapid deployment needs and credential portability requirements across institutional boundaries.
K-12 Schools anchor procurement volume; Corporations are expanding most quickly.
Deployment Model:
Data residency requirements and infrastructure maturity dictate architecture selection across geographies.
- Cloud-Based:Multi-tenant SaaS with automatic scaling, disaster recovery, and API-first integration architectures. This deployment mode dominates across all end-user categories, though defense and financial services sectors with stringent data residency requirements maintain exceptions.
- On-Premises:Air-gapped installations with local data sovereignty and custom security hardening. India's proposed digital privacy legislation requiring domestic data storage is reshaping vendor market access strategies and creating first-mover advantage for compliant infrastructure architects.
- Hybrid:Split architectures with sensitive data on-premise and compute workloads in cloud.
- Mobile:Native applications with offline content synchronization and low-bandwidth optimization.
Cloud-Based deployment commands installed base; On-Premises configurations are gaining share fastest in regulated verticals.
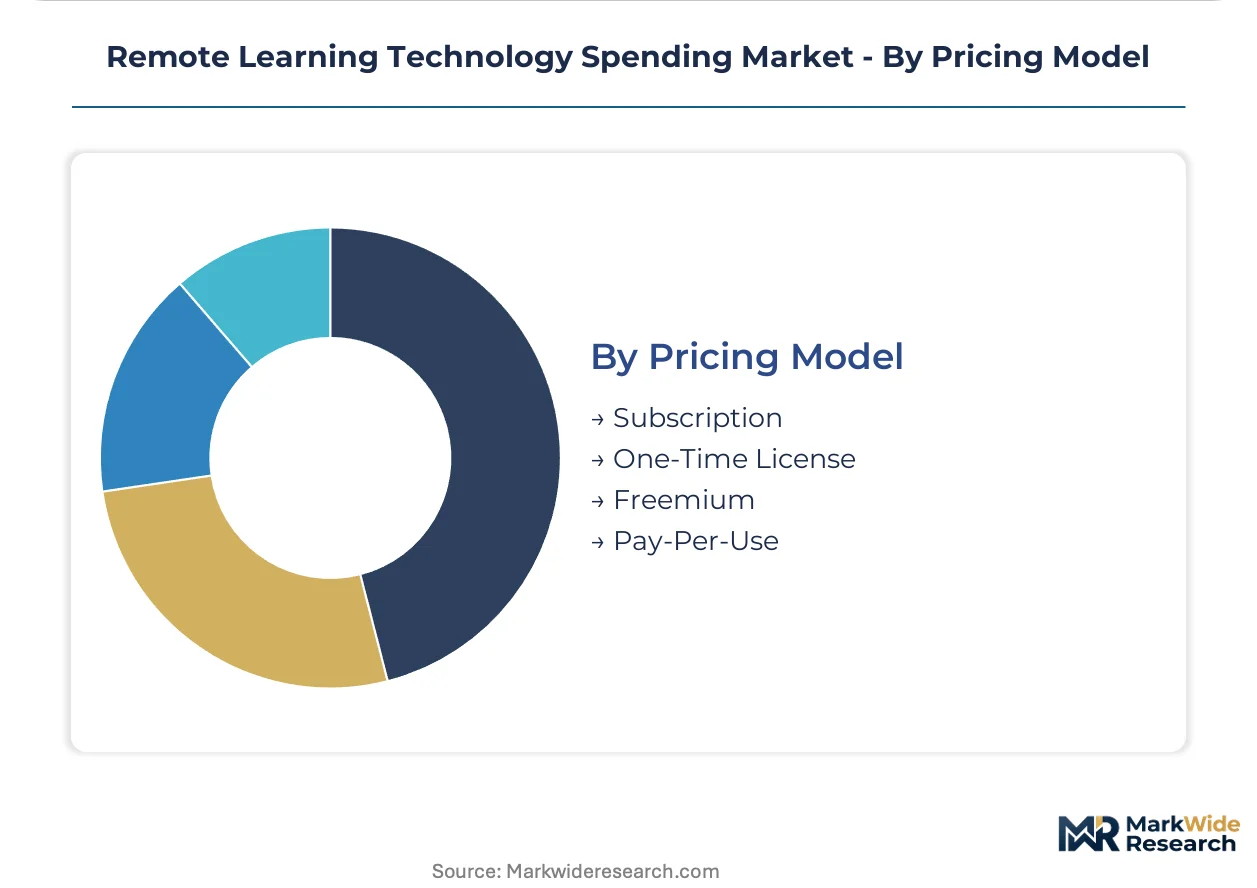
Pricing Model:
Revenue recognition timing and customer lifetime value calculations shift substantially across commercial structures.
- Subscription:Recurring annual or multi-year licenses with tiered feature access and usage-based overage provisions. Higher education institutions generate predictable revenue pools through enterprise agreements, while corporate training departments favor modular component subscriptions enabling best-of-breed procurement.
- Freemium:Base functionality at no cost with premium features, support, and analytics unlocked through paid tiers. Community colleges and vocational programs with staffing constraints adopt automated assessment tools through this model, enabling real-time misconception identification without instructor intervention.
- One-Time License:Perpetual software ownership with annual maintenance fees.
- Pay-Per-Use:Consumption-based billing tied to active learner hours or content access events.
Subscription pricing leads on revenue concentration; Freemium is climbing the fastest in resource-constrained institutional segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software engineering talent pools in Bangalore, Boston, and Berlin anchor platform development clusters, while procurement demand concentrates in jurisdictions with active education reform agendas and infrastructure investment programs.
United States
K-12 district cloud migration and corporate hybrid training models drive procurement velocity. FERPA compliance requirements enforce AES-256 encryption standards for any platform processing student education records. Greater Boston anchors higher education LMS enterprise licensing negotiations, with Massachusetts Institute of Technology and Harvard generating multi-year subscription renewals.
India
National Education Policy implementation and Digital India infrastructure tenders create large-scale government procurement windows. BIS certification requirements for educational hardware reshape vendor market access strategies. Bangalore's technology corridor concentrates adaptive learning engine development, with local startups securing integrated LMS contracts from state education departments.
Germany
Vocational training digitization and corporate apprenticeship platforms expand addressable market beyond traditional academic institutions. EU AI Act risk-classification obligations force algorithmic impact assessments for adaptive learning deployments. Munich and Berlin clusters delay procurement decisions until compliance pathways clarify, compressing near-term vendor revenue recognition.
United Kingdom
Corporate training unbundling and modular subscription procurement accelerate among financial services learning operations teams. GDPR data sovereignty architecture inflates upfront platform development costs for European deployments. London's EdTech cluster concentrates credential portability and xAPI interoperability development, with startups targeting cross-institutional learning record stores.
Japan
Corporate workforce reskilling mandates and aging population education needs diversify demand beyond K-12 and higher education verticals. METI standards for educational technology procurement influence platform feature requirements in enterprise segments. Tokyo-Osaka corridor concentrates video conferencing infrastructure investment, with fiber-optic backbone upgrades addressing sub-150 millisecond latency thresholds.
Remote Learning Technology Spending Market Competitive Landscape
The competitive structure tilts toward platform consolidators with deep SIS integration capabilities and point-solution specialists with rapid deployment agility. Incumbent vendors anchor positions through multi-year enterprise licenses and legacy system entrenchment. Emerging players compete on modular subscription models and AI-powered personalization architectures. Dominant competitive moves include strategic partnerships with institutional publishers and geographic expansion into data-localization-compliant infrastructure.
Among North American platform providers, Coursera and Blackboard exemplify divergent archetypes within the competitive set. Coursera occupies a position representing institutional partnership models with premium credentialing revenue streams. Blackboard anchors the legacy integration tier, exemplifying vendors with deep LMS entrenchment in higher education student information systems. PowerSchool sits within the K-12 administrative software expansion archetype, representing platform vendors extending into adjacent classroom analytics.
| Leading Market Players |
|---|
| D2L |
| 360Learning |
| Coursera |
| Blackboard |
| PowerSchool |
| Udemy |
| Docebo |
| Absorb LMS |
| Duolingo |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up platform specialists have consolidated the mid-tier LMS vendor landscape, concentrating pricing power among three dominant holding companies while compressing procurement leverage for K-12 districts locked into multi-year enterprise agreements. This ownership concentration reshapes supply behavior by prioritizing recurring revenue predictability over feature innovation, while pricing discipline tightens as districts face ESSA-mandated outcome accountability without commensurate budget expansion.
Pricing Analysis
Bundled-vs-unbundled service splits now define procurement economics across institutional buyer categories. Three-tier pricing structure across premium, standard, and economy levels segments the market by integration depth and analytics sophistication, with premium tiers commanding substantial uplifts for AI-powered adaptive engines and real-time proficiency dashboards. Pricing pressure stems from corporate training departments unbundling perpetual licenses into modular component subscriptions, forcing legacy vendors to defend maintenance revenue against best-of-breed point solutions. K-12 schools exhibit highest price sensitivity due to Title I funding constraints and compressed capital cycles, while financial services learning operations teams demonstrate lowest sensitivity given internal integration expertise and workforce reskilling mandates.
Supply Chain Analysis
India's data localization mandates and BIS certification requirements for educational hardware are reshaping sourcing patterns, compelling vendors to establish domestic cloud infrastructure and hardware assembly partnerships. Software engineering talent concentrates in Bangalore, Boston, and Berlin, with platform development drawing from specialized labor pools in each corridor. Fiber-optic backbone investments for sub-150 millisecond latency thresholds rest on equipment sourcing from Japan, South Korea, and the United States. Single-source vulnerability in AI training data pipelines poses structural risk as adaptive learning algorithms require continuous refresh of proprietary assessment item banks. Distribution runs through direct enterprise sales teams for higher education institutions and channel partners for K-12 district consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in AI-powered personalization tiers and India-compliant infrastructure deployments, with cloud migration compressing on-premise support costs while redirecting capital toward high-attach-rate analytics modules.
For Market Incumbents: Lock in multi-year enterprise renewals through deep SIS integration that elevates switching costs for North American higher education institutions. Consolidate adjacent classroom analytics capabilities through targeted capability acquisitions, while investing in FERPA-AI Act compliance engineering to preempt regulatory displacement by nimbler cloud-native competitors. For New Entrants and Emerging Players: Begin with modular subscription offerings targeting corporate training departments in US financial services and technology sectors, where internal learning operations teams possess integration expertise and procurement authority for best-of-breed point solutions. India's government tender windows for integrated LMS and digital content ecosystems represent the most penetrable geography, with first-mover advantage accruing to vendors architecting BIS-compliant hardware and domestic data storage infrastructure. For Investors and Strategic Acquirers: Valuations sit cheapest among point-solution specialists with rapid deployment agility and AI-powered personalization architectures, as platform consolidators trade at premiums reflecting SIS integration moats. The acquisition target archetype combines adaptive learning engine capabilities with xAPI interoperability credentials enabling credential portability across institutional boundaries. Watch procurement velocity in German vocational training digitization as an inflection indicator, with Munich and Berlin cluster delays resolving into compressed vendor selection windows once EU AI Act compliance pathways clarify.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep SIS synchronization locks higher education institutions into renewal cycles with elevated switching friction. |
| Geographic Expansion | India-compliant infrastructure deployment captures government tender windows under National Education Policy implementation. |
| Strategic Partnership | Institutional publisher alliances secure premium content libraries that differentiate credentialing revenue streams. |
| Acquisition of Specialist Firm | Classroom analytics capabilities extend K-12 administrative software stacks into adjacent formative assessment tools. |
| Product Launch | AI-powered adaptive engines redirect R&D budgets toward personalized instruction architectures with measurable outcome metrics. |
Research Methodology
Bottom-up institutional procurement modeling reconciled against top-down vendor revenue tracking forms the analytical core of this study. Primary interviews with K-12 district technology directors, higher education CIOs, corporate learning operations leaders, and platform engineering executives combined with secondary validation from SEC filings, hyperscaler capex disclosures, and government tender databases. Trade association publications from EDUCAUSE and industry-specific procurement records triangulate against bottom-up segmentation outputs.
Historical trendline analysis across deployment model transitions and pricing model shifts informs the projection framework. Segmentation dimensions modeled include product type, end-user category, deployment architecture, and regional regulatory cluster, with CAGRs derived from elasticity-adjusted adoption curves and infrastructure investment pipelines. AI governance fragmentation scenarios and latency threshold compliance costs factor as industry-specific inputs shaping trajectory boundaries.
Several conditions sit outside the modeled scope, including sudden shifts in national data localization legislation, disruptive generative AI capabilities rendering current adaptive engines obsolete, and fiber-optic infrastructure buildout delays in rural districts. Forecasts reflect documented assumptions regarding ESSA accountability mandate enforcement continuity and EU AI Act implementation timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Distance Learning and Online Education
Europe E-Learning Market
Distance Learning and Online Education
GCC Massive Open Online Course (MOOC) Market
Distance Learning and Online Education
United States E-Learning Market
Distance Learning and Online Education
Global Virtual Classroom Market
Distance Learning and Online Education
E-Learning Market
Distance Learning and Online Education
Europe Digital Education Market
Distance Learning and Online Education
Homeschooling Market
Distance Learning and Online Education
GCC E-Learning Market
Distance Learning and Online Education
Digital Course Recorder Market
Distance Learning and Online Education
Global Self-Paced E-Learning Market
Distance Learning and Online Education
Saudi Arabia E-Learning Market
Distance Learning and Online Education
Online Tutoring Services Market
Distance Learning and Online Education
Digital Marketing Courses Market
Distance Learning and Online Education
E-Learning Services Market
Distance Learning and Online Education
Online Tutoring Market
Distance Learning and Online Education
Cloud-Based Training Software Market