
 Europe MOOC Market | 2026-2036
Europe MOOC Market Size, Share, and Industry Trends Forecast 2026-2036
Europe MOOC Market Foresight
The EU AI Act is restructuring compliance costs for automated grading and personalized learning algorithms deployed by European MOOC providers. Coursera Inc. leverages its institutional partnerships to sustain credit-bearing pathway programs across multiple EU member states. FutureLearn Limited anchors its competitive position through Open University affiliation and UK degree-integrated offerings. Miriadax specializes in Spanish and Portuguese-language professional development content, occupying a distinct linguistic niche with limited direct competition.
Massive Open Online Courses (MOOCs) are web-based learning environments designed to support unlimited enrollment through cloud-hosted learning management systems, typically incorporating video lectures, automated assessments, and peer interaction forums for knowledge dissemination at scale. Their primary commercial purpose centers on delivering affordable, accessible education and workforce training outside traditional degree-granting institutions. Professional Development courses within the Course Type dimension generate the strongest margin pools as employers fund certified upskilling for existing staff. Self-Paced delivery through the Delivery Mode dimension captures the largest enrollment base by eliminating scheduling barriers for working professionals across time zones. Corporate Training within the End User dimension exhibits the fastest structural expansion as enterprises replace in-person seminars with scalable digital alternatives.
GDPR enforcement by national data protection authorities shapes platform architecture for learner data storage and cross-border transfer across EU operations. The EU Green Deal and Digital Education Action Plan together channel public funding toward digital credentialing infrastructure and green skills curricula. ECTS credit recognition frameworks governed by the European Higher Education Area determine which MOOC completions transfer into formal degree pathways. Stakeholders must monitor evolving AI Act implementing acts for specific transparency and human-oversight obligations affecting adaptive learning systems.
Market Dynamics
The EU AI Act is forcing European MOOC providers to restructure automated grading systems and adaptive learning algorithms around mandatory human oversight requirements, compressing deployment timelines for AI-driven personalization features.
Growth Catalysts
- Digital Education Action Plan:EU funding channels accelerate interoperable credentialing infrastructure across member states, enabling seamless credit transfer for cross-border learners.
- Germany:Federal-state coordination on digital credentialing standards accelerates employer recognition of MOOC-based qualifications, expanding corporate training contracts.
- Cloud-hosted LMS architectures:Scalable delivery infrastructure eliminates enrollment caps, allowing platforms to absorb surging enterprise reskilling demand without proportional cost expansion.
Market Restraints
- GDPR compliance costs:National data protection authorities enforce strict learner data localization requirements, fragmenting platform architecture across member states.
- ECTS recognition barriers:European Higher Education Area frameworks limit which MOOC completions transfer into formal degree pathways, constraining credit-bearing program expansion.
- Substitute threat from corporate LMS vendors:In-house learning management systems at large enterprises capture internal training budgets that might otherwise flow to external MOOC platforms.
Strategic Opportunities
- Spain and Portugal:Portuguese-language professional development content remains underpenetrated, with limited platform competition for Iberian and Latin American corporate learners.
- EU Green Deal curricula:Public funding mandates for green skills training create dedicated revenue streams for sustainability-focused course development.
- Blockchain-verified credentials:Integration of distributed ledger technology with existing digital badge systems enables portable, tamper-proof qualification verification for mobile workforces.
Industry Challenges
- AI Act implementing acts:Evolving transparency obligations for adaptive learning systems create compliance timeline uncertainty, delaying product roadmap execution.
- Cross-border data transfer protocols:Reconciling GDPR localization requirements with cloud infrastructure economics demands complex architectural reengineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe MOOC Market |
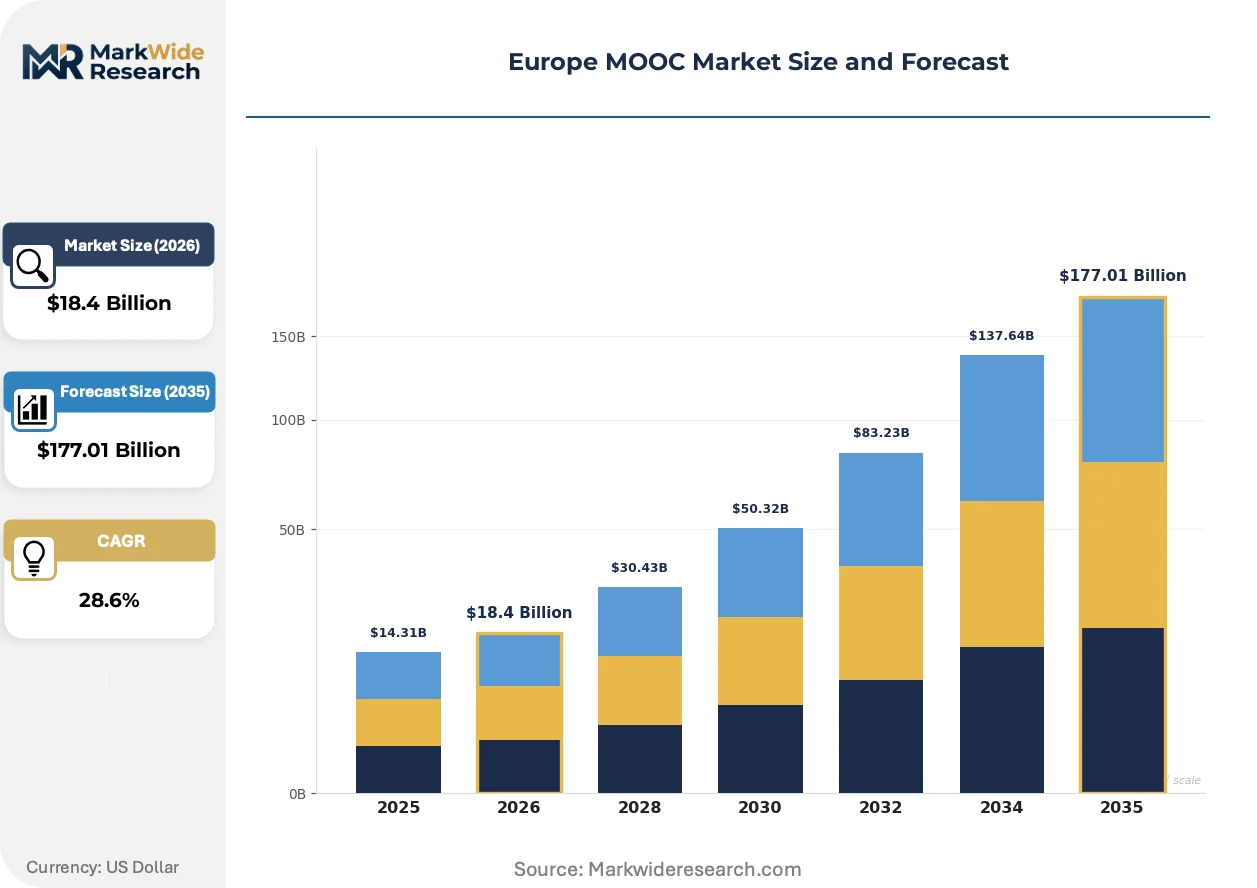
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $177.01 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Course Type: Professional Development, Academic Courses, Skill Development, Corporate Training Delivery Mode: Self-Paced, Instructor-Led, Hybrid, Blended Learning End User: Individuals, Corporates, Educational Institutions, Government Agencies Technology: Learning Management Systems, Mobile Learning, Video Conferencing, Gamification |
| Companies Covered | Coursera Inc., FutureLearn Limited, OpenupEd, Miriadax, Udemy, Inc., edX Inc., Federica Web Learning, Alison, Udacity, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe MOOC Market Shifts & Advancements
Generative AI tools are compressing content production cycles while blockchain credentialing infrastructure enables portable qualification verification across European labor markets.
Adaptive learning algorithms are decentralizing personalized education pathways by enabling real-time curriculum adjustment based on individual learner performance data. Corporate training departments across Germany and France are deploying these systems at accelerating pace, replacing static course catalogs with dynamic skill-building journeys. This technology is decentralizing platform competitive advantage away from content libraries toward data-driven personalization engines.
The EU AI Act imposes mandatory human oversight requirements on automated grading systems, forcing providers to restructure algorithmic decision-making workflows. Industrial consequence includes elevated compliance costs and delayed deployment timelines for fully autonomous tutoring features. Professional certification programs in regulated sectors such as healthcare and finance face the most acute adaptation pressure, with providers redesigning assessment architectures to maintain audit trails.
Employer-funded upskilling is displacing individual learner payments as the dominant revenue model across European MOOC platforms. Enterprise procurement teams now negotiate volume-based training contracts directly with platforms, bypassing traditional individual enrollment channels. This shift is most visible in Germany, where federal reskilling subsidies channel public funds through corporate HR departments rather than direct-to-consumer subsidies.
Europe MOOC Market Segmentation
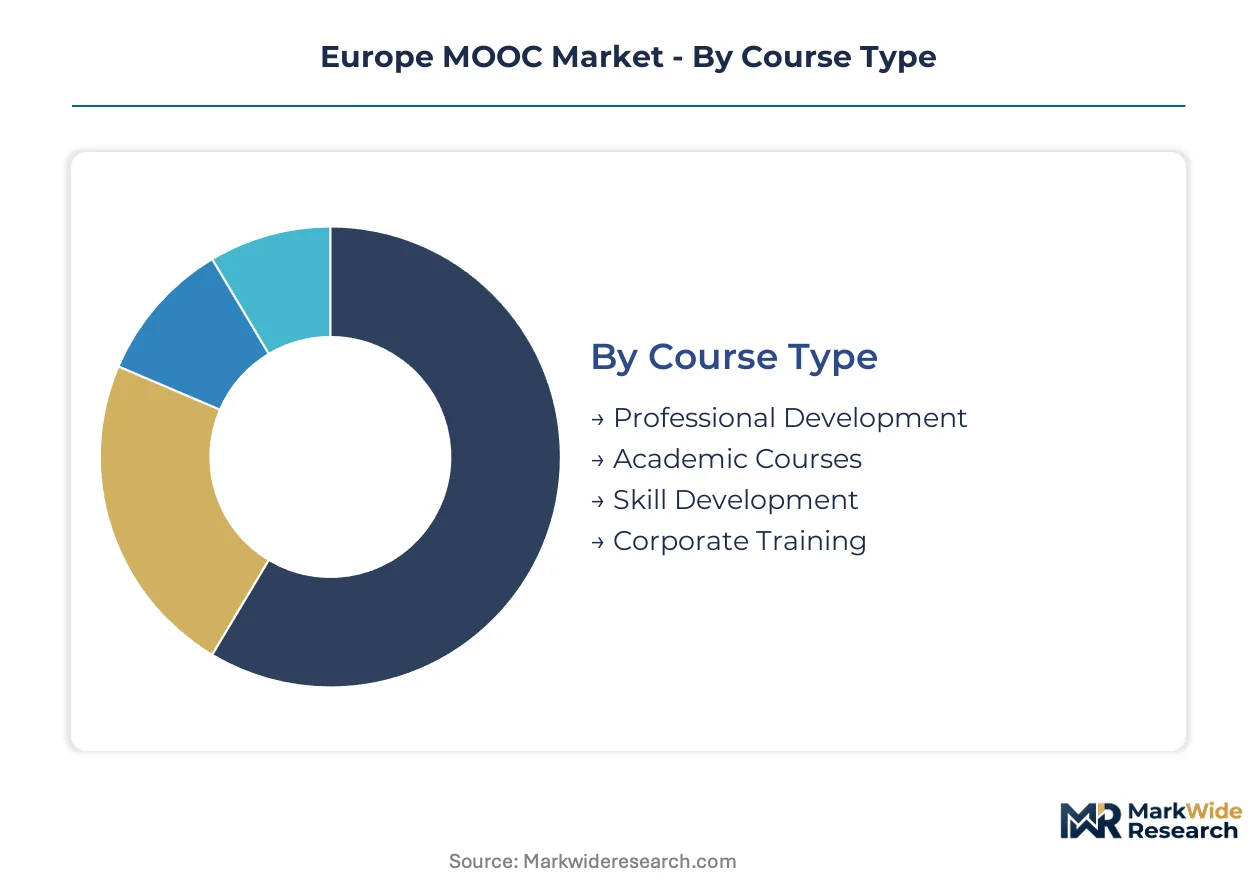
Segmentation in the Europe MOOC market reveals divergent margin profiles across learner cohorts and delivery architectures. Course type and end user dimensions determine pricing power, while delivery mode selection shapes platform infrastructure economics and scalability constraints.
Course Type:
Professional Development commands premium pricing through employer-funded contracts, while Academic Courses trade volume for lower per-seat revenue in degree pathway programs.
- Professional Development:Certification-bearing curricula target regulated sectors including healthcare, finance, and data privacy compliance. German corporate training subsidies and French professional development accounts (CPF) channel substantial public funding into this segment, compressing price sensitivity among enterprise buyers.
- Corporate Training:Customized learning paths integrate with enterprise HR systems and skills taxonomies. Spanish banking and automotive sectors deploy these programs at scale, replacing in-person seminars with measurable digital alternatives that reduce per-employee training costs.
- Academic Courses:University-affiliated content stacks toward ECTS credit recognition under Bologna Process frameworks.
- Skill Development:Short-form modules address immediate competency gaps without formal credentialing overhead.
Today's leader: Professional Development. Tomorrow's challenger: Corporate Training.
Delivery Mode:
Self-Paced architectures dominate enrollment volumes by eliminating scheduling friction, while Instructor-Led formats capture premium positioning through scarce expert access.
- Self-Paced:Asynchronous video libraries and automated assessments enable unlimited concurrent learners without proportional instructor cost expansion. Cloud-hosted LMS infrastructure across Ireland and Netherlands data centers supports this model's scalability across time zones.
- Hybrid:Combines on-demand content with scheduled live sessions for cohort-based progression. Italian professional associations and Dutch trade federations favor this structure for regulated continuing education where peer interaction satisfies accreditation requirements.
- Instructor-Led:Synchronous delivery demands real-time instructor presence and caps enrollment per session.
- Blended Learning:Integrates physical classroom components with digital pre-work and reinforcement.
Self-Paced captures volume leadership. Hybrid gains fastest as accreditation bodies relax synchronous requirements.
End User:
Corporates now outspend Individuals on a per-learner basis, shifting platform revenue models toward B2B contract structures.
- Corporates:Enterprise procurement teams negotiate multi-year training agreements with volume-based pricing and skills analytics dashboards. German automotive manufacturers and French energy utilities deploy these contracts across tens of thousands of employees.
- Educational Institutions:Universities license platform content for credit-bearing degree supplements and summer bridge programs. Spanish public universities integrate MOOCs into formal curricula through Miriadax partnerships, reducing content development costs.
- Individuals:Direct-to-consumer enrollment persists in career transition and hobbyist learning categories.
- Government Agencies:Public sector reskilling initiatives channel EU Social Fund resources into platform contracts.
Corporates anchor current revenue. Educational Institutions present the steepest expansion trajectory as credit transfer frameworks mature.
Technology:
Learning Management Systems constitute the foundational infrastructure layer, while emerging interfaces compete for differentiation.
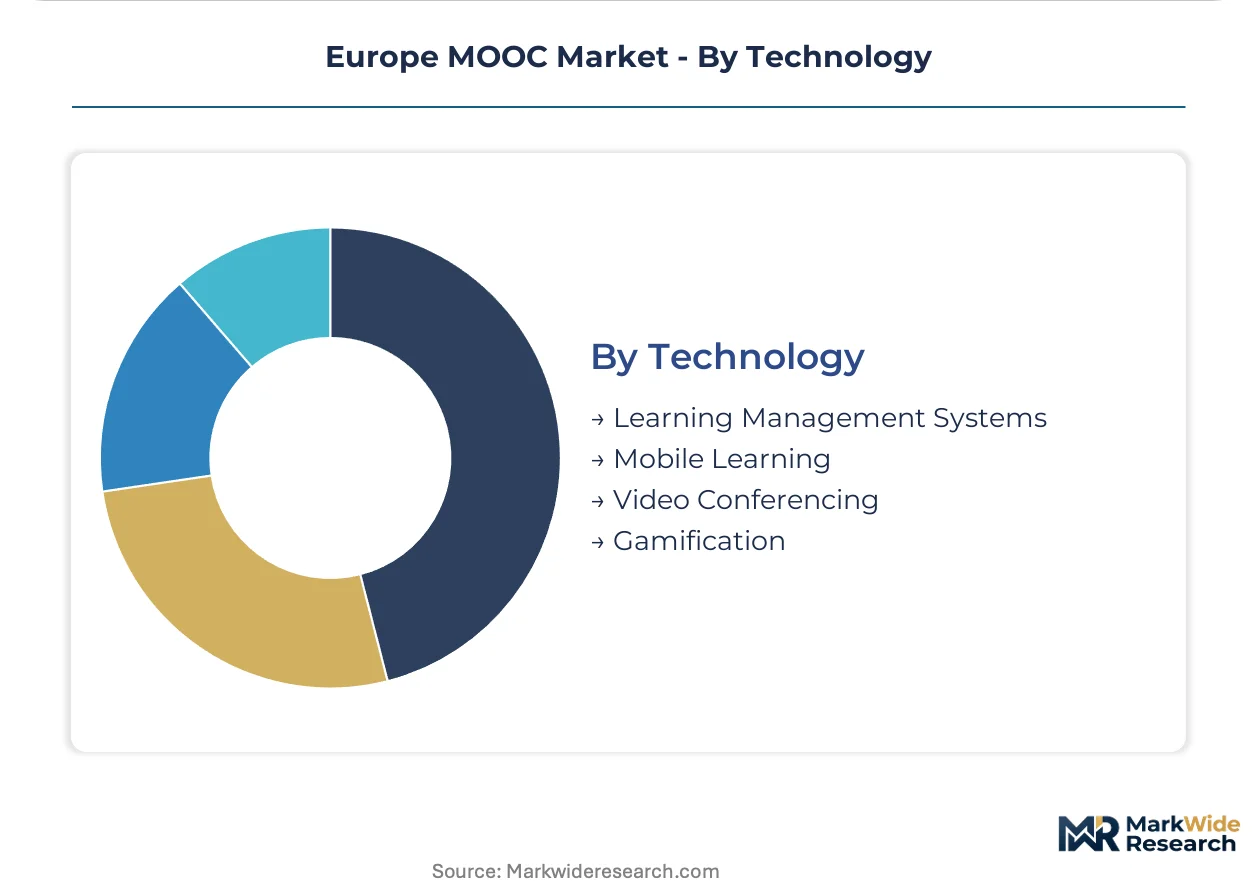
- Learning Management Systems:Cloud-native platforms with SCORM/xAPI compliance manage content delivery, progress tracking, and credential issuance. GDPR-compliant data residency configurations across Frankfurt, Amsterdam, and Dublin regions satisfy cross-border operational requirements.
- Mobile Learning:Smartphone-optimized interfaces with offline content caching address commuter learning patterns in high-public-transit European cities.
- Video Conferencing:Real-time session infrastructure enables instructor-led and hybrid delivery modes.
- Gamification:Badge systems, leaderboards, and progress visualization drive completion rate improvements in self-paced environments.
Learning Management Systems dominate infrastructure spend. Mobile Learning climbs fastest as commuter cohorts expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering talent and French digital infrastructure anchor European MOOC platform operations, while Spanish linguistic networks and Dutch cloud hosting extend continental reach.
Germany
Automotive and industrial machinery workforces drive enterprise reskilling demand through federal-state digital credentialing initiatives. The Federal Employment Agency channels reskilling subsidies through corporate HR departments rather than individual learners. Munich and Stuttgart host concentrated platform partnerships with automotive manufacturers deploying AI compliance training.
United Kingdom
Financial services professionals and public sector workers generate sustained demand for certified professional development pathways. The UK Information Commissioner's Office enforces GDPR-aligned data localization requirements for learner records. London anchors credit-bearing degree integrations through Open University-affiliated platform operations.
France
Energy utility and healthcare workforces absorb substantial corporate training volumes through Compte Personnel de Formation (CPF) funding mechanisms. The CNIL shapes platform data governance architectures for automated assessment systems. Paris and Lyon cluster regulated sector training programs with mandatory continuing education requirements.
Spain
Iberian and Latin American corporate learners create demand for Portuguese and Spanish-language professional development content. The Spanish Data Protection Agency enforces cross-border data transfer protocols affecting platform cloud configurations. Madrid and Barcelona concentrate banking and automotive sector deployments replacing in-person seminars.
Netherlands
Logistics and technology sector workforces drive demand for self-paced skill development through employer-funded contracts. The Dutch Data Protection Authority mandates strict learner data residency configurations for cloud-hosted LMS operations. Amsterdam hosts primary data center infrastructure supporting scalable delivery across European time zones.
Europe MOOC Market Competitive Landscape
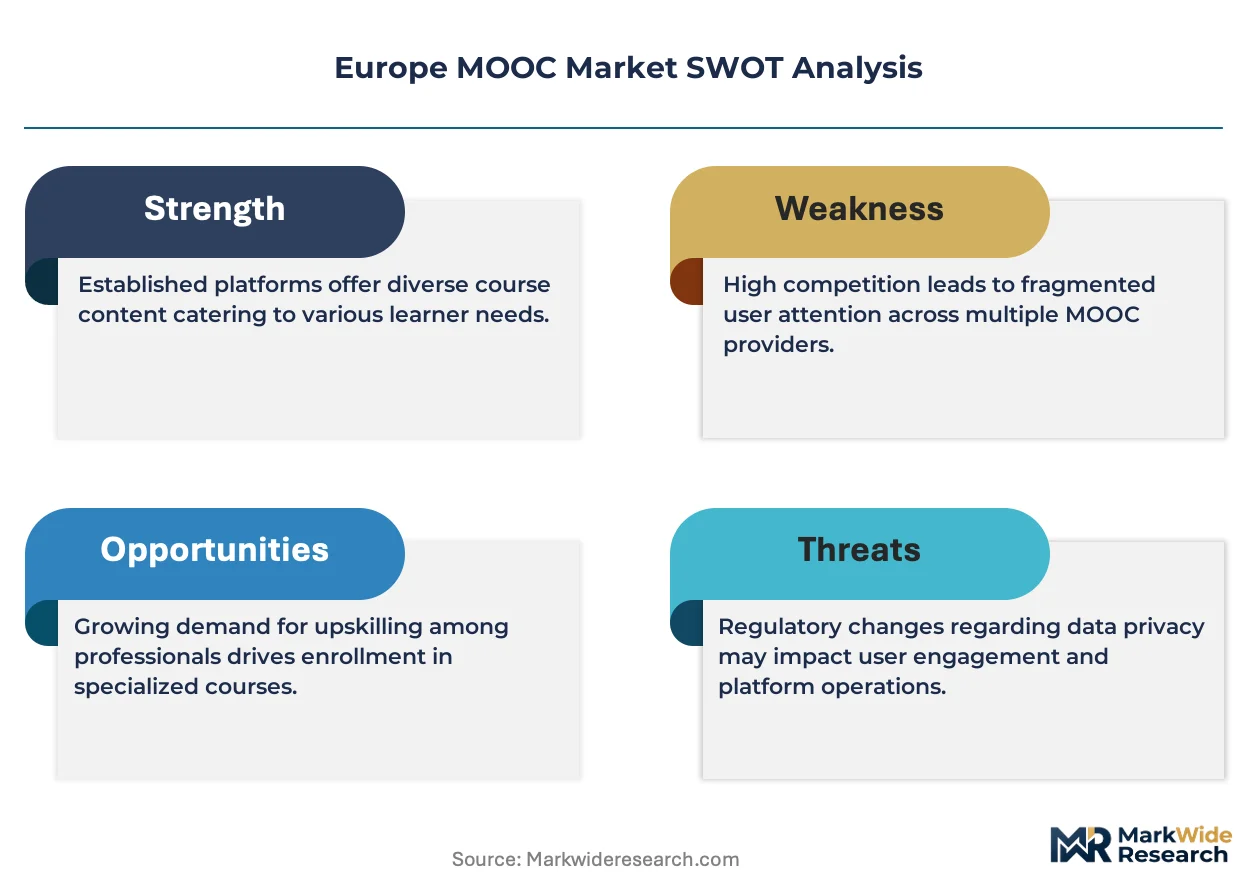
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. US-based global platforms with institutional university partnerships occupy premium credit-bearing segments, while European regional specialists capture linguistic and regulatory niches. Three archetypes dominate: global platform operators with degree-integrated offerings, regional language specialists with corporate training focus, and open-access providers with freemium monetization. Competitive moves center on ECTS credit recognition expansion and GDPR-compliant cloud infrastructure deployment.
Within the global platform tier, Coursera Inc. and edX Inc. exemplify degree-integrated positioning through university partnership networks spanning multiple EU member states. Among European regional specialists, Miriadax occupies a distinct Iberian and Latin American linguistic niche with limited direct competition for Portuguese-language professional development. FutureLearn Limited anchors UK market positioning through Open University affiliation and domestic degree-integrated offerings. These three represent divergent strategic archetypes: global scale with institutional partnerships, regional linguistic focus, and national degree system integration.
| Leading Market Players |
|---|
| Coursera Inc. |
| FutureLearn Limited |
| OpenupEd |
| Miriadax |
| Udemy, Inc. |
| edX Inc. |
| Federica Web Learning |
| Alison |
| Udacity, Inc. |
| Others |
Supply & Pricing Matrix
Cloud infrastructure cost indices cascade through European MOOC platform economics, compressing margins on self-paced delivery while amplifying pricing power for instructor-led certification tiers that absorb compliance overhead.
Pricing Analysis
Course bundling versus à-la-carte module sales splits the European MOOC market into distinct revenue architectures. Subscription-based corporate training contracts dominate B2B segments, while individual learners face per-course transactional pricing. Price differentiation hinges on ECTS credit eligibility and GDPR compliance certification tier. Cost compression in self-paced video delivery intensifies as cloud storage fees escalate across Frankfurt and Amsterdam data centers. Enterprise procurement teams exhibit lowest price sensitivity due to federal reskilling subsidy absorption, whereas individual career-changers face acute budget constraints.
Supply Chain Analysis
ECTS accreditation and AI Act compliance certification gate platform access to credit-bearing revenue streams, forcing supply chain restructuring around audited assessment workflows. Content production concentrates in Germany, the United Kingdom, and Spain, with cloud hosting anchored in Ireland and the Netherlands. Platform operations draw from video production studios, learning management system licenses, and AI tutoring engine APIs. Single-source vulnerability runs through hyperscaler cloud dependencies for scalable delivery. Distribution runs through direct enterprise sales teams and university partnership channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European MOOC market functions as a geographic-arbitrage play, with German federal reskilling subsidies offering cost-advantaged customer acquisition unavailable in markets lacking comparable public training budgets.
For Market Incumbents: Deploy ECTS credit pathway expansion as the primary defensive lever. Deepen university partnership networks in France and Spain to preempt emerging platform competition. Counter the substitute threat from corporate LMS vendors by embedding skills analytics dashboards that demonstrate measurable training ROI to enterprise procurement teams. For New Entrants and Emerging Players: Portuguese-language corporate training partnerships offer the most penetrable white-space entry point, with Iberian and Brazilian enterprise demand substantially underserved. Target mid-sized Spanish automotive suppliers replacing in-person compliance seminars. Pursue white-label platform licensing to established professional associations with captive member bases. For Investors and Strategic Acquirers: Asymmetric upside sits with regional language specialists possessing GDPR-compliant infrastructure and existing corporate training contracts. Long-term viability favors platforms with durable university affiliations enabling credit transfer. Monitor German federal-state digital credentialing standardization as the critical inflection signal for cross-border scalability.| Strategic Initiative | Industry Significance |
|---|---|
| ECTS Credit Pathway Expansion | Unlocks formal degree integration through Bologna Process frameworks across German and French universities. |
| GDPR-Compliant Cloud Migration | Positions platforms for German and Dutch enterprise contracts under strict national data protection authority enforcement. |
| AI Tutoring Engine Deployment | Enables personalized learning at scale while navigating EU AI Act human-oversight requirements for automated assessment. |
| Corporate Training Partnership | Captures French CPF and German federal reskilling subsidy flows through direct HR department procurement channels. |
| Blockchain Credential Integration | Supports portable qualification verification for mobile workforces across European labor markets. |
Research Methodology
Direct dialogue with platform product managers, corporate learning officers at German automotive manufacturers, French CNIL compliance consultants, and Spanish university partnership directors grounded qualitative findings. Secondary validation drew from EU Digital Education Action Plan progress reports, GDPR enforcement decisions by national data protection authorities, ECTS credit transfer statistics, and cloud infrastructure capex disclosures by hyperscalers. Bottom-up enrollment modeling triangulated against top-down corporate training spend estimates.
Market size outputs segment across course type, delivery mode, end user, and technology infrastructure dimensions throughout the projection horizon. CAGRs derived from historical enrollment velocity, corporate training contract renewal rates, and public funding allocation trajectories. Forecast inputs incorporated AI Act implementation timelines and ECTS recognition framework expansion assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act implementing act finalization and German federal-state credentialing coordination pace. Forecasts reflect documented assumptions regarding subsidy continuity and cross-border data transfer protocol stability. A model refresh is warranted upon material change in AI Act transparency obligation enforcement or ECTS automatic recognition directive adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Distance Learning and Online Education
Digital Marketing Courses Market
Distance Learning and Online Education
United States E-Learning Market
Distance Learning and Online Education
Global Digital Education Market
Distance Learning and Online Education
Global Virtual Classroom Market
Distance Learning and Online Education
Europe E-Learning Market
Distance Learning and Online Education
MOOC Market
Distance Learning and Online Education
E-Learning Services Market
Distance Learning and Online Education
GCC Massive Open Online Course (MOOC) Market
Distance Learning and Online Education
Online Tutoring Market
Distance Learning and Online Education
Digital Course Recorder Market
Distance Learning and Online Education
Online Tutoring Services Market
Distance Learning and Online Education
Global Online Tutoring Software Market
Distance Learning and Online Education
Europe Digital Education Market
Distance Learning and Online Education
Massive Open Online Courses Market
Distance Learning and Online Education
GCC E-Learning Market
Distance Learning and Online Education
Saudi Arabia E-Learning Market