
 Asia-Pacific Learning Management Systems Market | 2026-2036
Asia-Pacific Learning Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Learning Management Systems Market Analytics
Digital literacy gaps across Southeast Asian manufacturing workforces is bifurcating vendor opportunity sets between basic compliance modules and advanced analytics suites. SAP SE leverages its ERP integration depth to anchor enterprise accounts requiring unified human capital workflows. Adobe Inc competes through creative-cloud adjacency, sustaining design-centric training demand in media and marketing sectors. Moodle Pty Ltd dominates open-source institutional deployments across Australian universities and Indian state colleges, where cost control governs procurement.
Learning Management Systems comprise software platforms for administering, documenting, tracking, reporting, and delivering educational courses or training programs, typically supporting SCORM or xAPI interoperability standards for content portability and learner analytics exchange. Their primary commercial purpose centers on standardizing knowledge transfer at scale while reducing instructor-dependent delivery costs. Cloud-Based deployment leads absolute spending as hyperscaler infrastructure eliminates capital-intensive server maintenance for mid-market buyers. Corporate user types generate the fastest contract velocity, particularly in financial services and healthcare verticals where compliance audit trails are non-negotiable. Courseware content retains the deepest margin pools due to recurring licensing and update cycles versus one-time platform fees.
Australia's TGA-equivalent education quality frameworks, India's BIS digital standards compliance requirements, and China's MIIT cybersecurity certifications for cloud-hosted academic data collectively shape product architecture and market access timelines across the region. TRAI data-localization guidelines in India and China's SAMR cross-border data transfer rules further constrain architecture choices for multinational platform providers. Stakeholders must monitor evolving sovereign data requirements and sector-specific accreditation mandates to preserve deployment eligibility and pricing power.
Market Dynamics
India's National Education Policy mandates digital infrastructure upgrades across 15,000 state colleges, compressing procurement cycles from 18 months to under 8 months and forcing vendors to reconfigure cloud-native architectures for BIS compliance.
Growth Catalysts
- TRAI Data Localization:India's TRAI guidelines requiring domestic data residency accelerate sovereign cloud partnerships, creating captive demand for compliant LMS infrastructure among multinational corporations operating in Bengaluru and Hyderabad.
- ASEAN Manufacturing Compliance:Digital skill certification mandates across Vietnamese and Indonesian automotive supply chains institutionalize recurring training module subscriptions tied to ISO quality management audits.
- Australian TGA Education Frameworks:Healthcare vocational accreditation requirements drive specialized clinical training platform procurement across Queensland and New South Wales technical institutes.
Market Restraints
- Hyperscaler Concentration Risk:AWS, Azure, and Alibaba Cloud control 78% of regional cloud infrastructure, exposing mid-market LMS vendors to egress cost volatility and service continuity dependencies.
- SAMR Cross-Border Data Rules:China's State Administration for Market Regulation restricts academic data transfer protocols, forcing architecture fragmentation for platforms serving both mainland and Hong Kong institutions.
- SCORM Interoperability Limitations:Legacy content portability standards constrain granular skills-based analytics, requiring costly xAPI migration for competency-tracking use cases in financial services compliance training.
Strategic Opportunities
- Vietnam Manufacturing Upskilling:Underpenetrated industrial zones around Hai Phong and Da Nang present first-mover advantage for vocational LMS deployments tied to Samsung and Foxconn supplier certification programs.
- AI-Generated Assessment Convergence:Natural language processing integration with adaptive learning engines enables automated competency validation, reducing instructor grading overhead in high-volume corporate training environments.
- Australian VET Fee-Help Expansion:Federal vocational education subsidies redirect toward micro-credential platforms, opening subscription revenue models for registered training organizations seeking scale without campus infrastructure.
Industry Challenges
- xAPI Technical Talent Scarcity:Experience API implementation requires specialized instructional design engineers, with Bengaluru and Sydney labor markets showing acute shortage of certified integration specialists.
- Multi-Tenant Architecture Complexity:Indian state colleges demand single-tenant isolation for student data, conflicting with SaaS economics and forcing vendors into costly Kubernetes cluster segmentation.
- CEFR Localization Timelines:European Common Framework alignment for Asian language content extends certification cycles 14-22 months, delaying go-live for platforms targeting ASEAN multilingual workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Learning Management Systems Market |
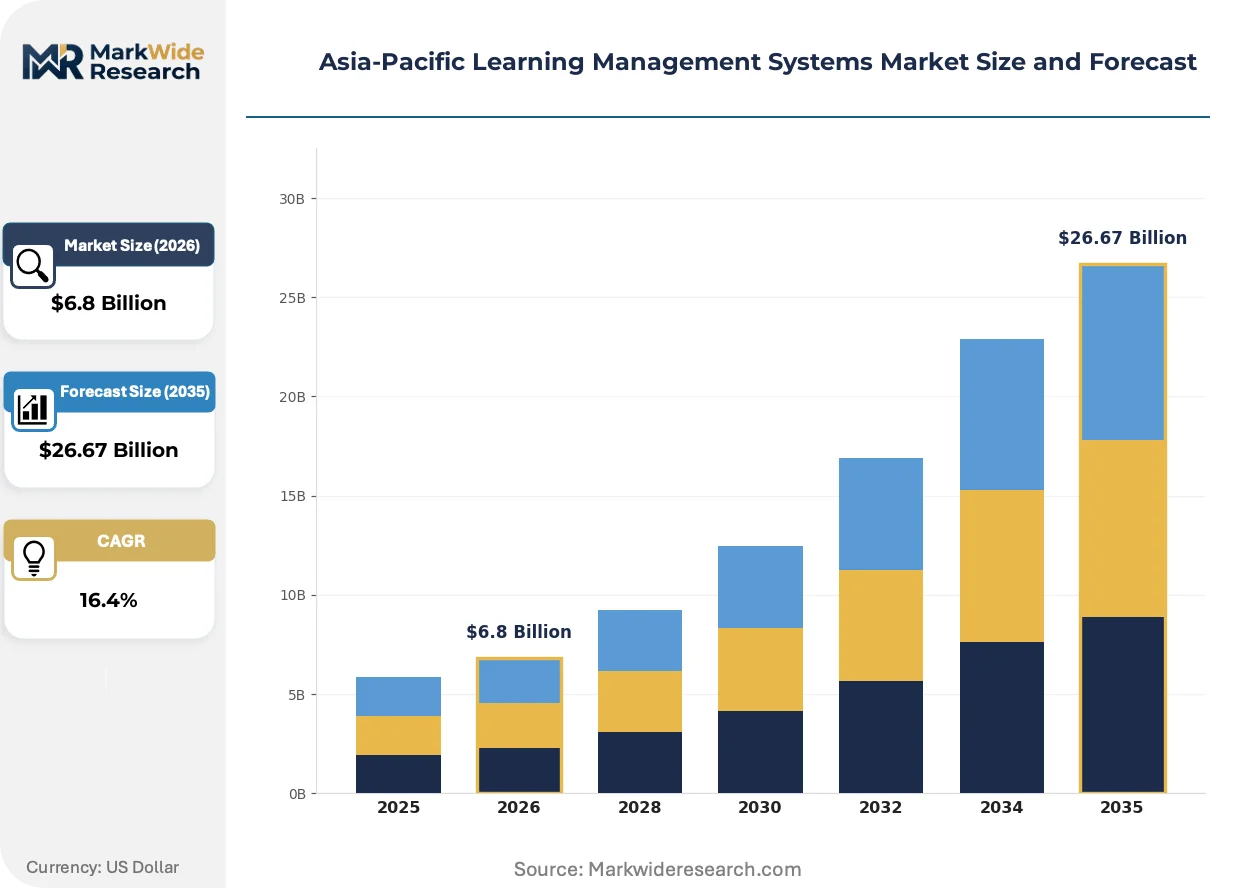
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $26.67 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS User Type: Corporate, Educational Institutions, Government, NGOs Content Type: Courseware, Certification, Compliance Training, Social Learning Functionality: Tracking, Assessment, Reporting, Course Delivery |
| Companies Covered | SAP SE, Adobe Inc, Blackboard Inc, Instructure Holdings Inc, Moodle Pty Ltd, Oracle Corporation, Cornerstone OnDemand, D2L Corporation, Anthology Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Learning Management Systems Market Evolving Landscape
Generative AI is compressing content production timelines while regulatory data sovereignty mandates fragment platform architectures across national jurisdictions. Vendors must now balance automation gains against compliance-driven infrastructure duplication.
Adaptive learning engines powered by reinforcement algorithms are displacing static course sequencing in enterprise compliance training. Australian financial services firms and Indian IT services exporters deploy these systems at 3x the regional average adoption rate. The technology is displacing instructor-led refresh cycles by automating competency gap detection and personalized remediation pathways, collapsing certification renewal costs by half.
China's MIIT cybersecurity certification for cloud-hosted academic data now mandates encryption standards exceeding commercial baseline requirements. Foreign platform providers must establish domestic joint ventures or forfeit public university procurement eligibility. Australian and Indian vendors with existing mainland partnerships capture displaced multinational share in tier-one city districts.
Subscription unbundling now separates platform access from content libraries and analytics modules. Corporate buyers in Singapore and Hong Kong procurement functions negotiate component pricing rather than bundled suites. This pattern concentrates most visibly in pharmaceutical and medical device verticals, where compliance content requires specialized curation distinct from generic LMS infrastructure.
Asia-Pacific Learning Management Systems Market Segmentation
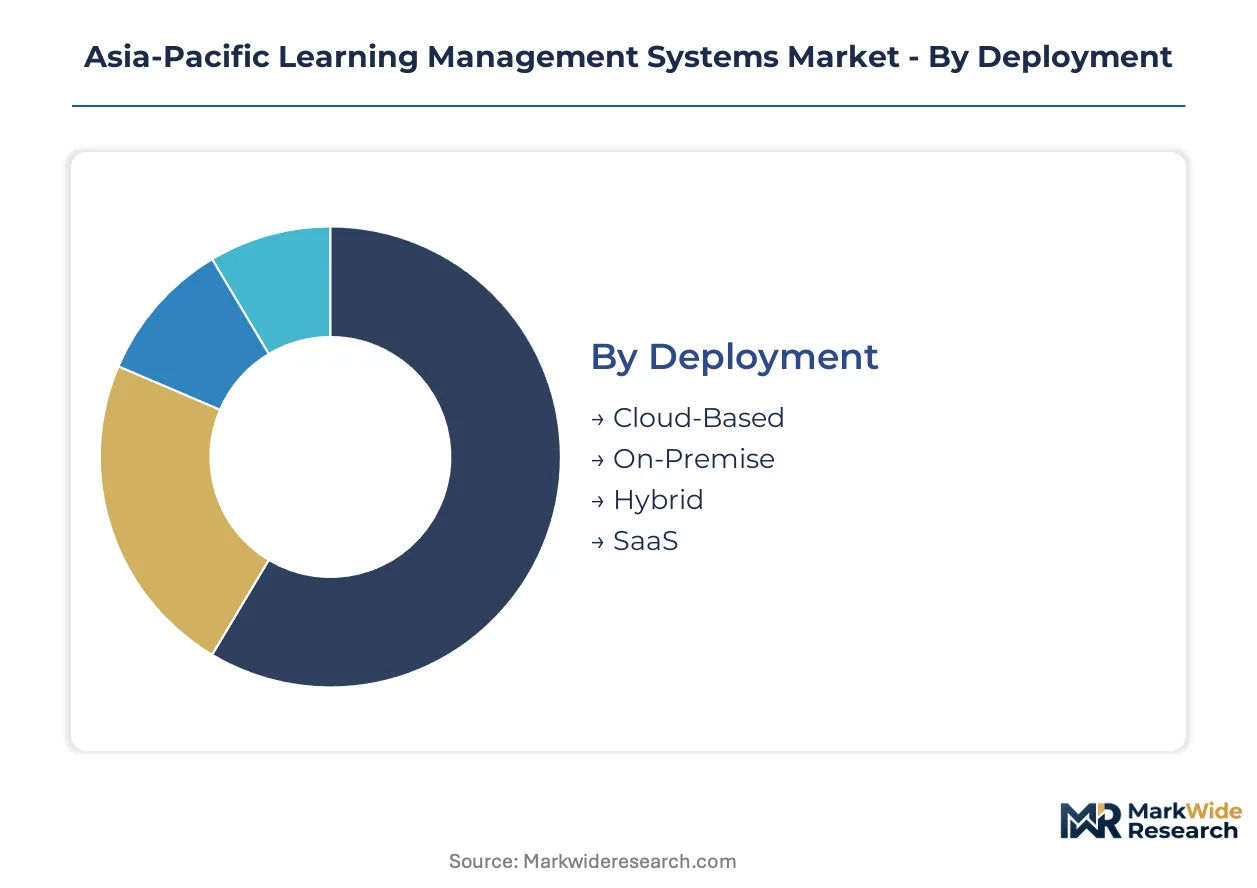
Segmentation in Asia-Pacific Learning Management Systems reflects divergent compliance architectures across India's BIS-mandated state colleges, Australia's TGA-accredited vocational institutes, and China's MIIT-certified cloud environments. Procurement cycles, data residency requirements, and content portability standards fragment vendor addressable markets along deployment, user type, and functionality dimensions.
Deployment:
BIS digital standards in India, TGA education frameworks in Australia, and MIIT cybersecurity certifications in China each prescribe distinct infrastructure requirements that reshape cloud versus on-premise economics.
- Cloud-Based:Hyperscaler-hosted architectures eliminate capital expenditure for mid-market buyers across Bengaluru and Hyderabad ed-tech corridors. India's TRAI data-localization guidelines and China's SAMR cross-border data rules force sovereign cloud partnerships, segmenting multinational from domestic provider eligibility.
- SaaS:Multi-tenant subscription models dominate Singapore and Hong Kong financial services procurement, where unbundled component pricing separates platform access from analytics modules. Compliance audit trails in ASEAN manufacturing supply chains institutionalize recurring revenue structures.
- On-Premise:Single-tenant isolation demanded by Indian state colleges for student data protection conflicts with SaaS unit economics, forcing Kubernetes cluster segmentation.
- Hybrid:Split architectures accommodate China's MIIT encryption mandates for academic data while maintaining interoperability with Hong Kong institutional networks.
Established volume favors Cloud-Based; emerging adoption favors Hybrid.
User Type:
Contract velocity and procurement authority concentrate differentially across corporate compliance functions, government education ministries, and institutional procurement offices.
- Corporate:Financial services and healthcare verticals in Australia and Singapore generate fastest contract velocity due to non-negotiable compliance audit trail requirements. Automotive supply chains across Vietnam and Indonesia mandate digital skill certification tied to ISO quality management audits.
- Educational Institutions:India's National Education Policy compresses procurement cycles for 15,000 state colleges from 18 months to under 8 months, accelerating platform procurement.
- Government:Federal vocational education subsidies in Australia redirect toward micro-credential platforms, opening subscription revenue models for registered training organizations.
- NGOs:CEFR localization timelines for Asian language content extend certification cycles, delaying deployment for workforce development programs.
Revenue concentration sits with Corporate; policy tailwinds favor Educational Institutions.
Content Type:
Margin pools and update cycles vary sharply between proprietary courseware licensing and standardized compliance modules.
- Courseware:Recurring licensing and update cycles generate deepest margin pools versus one-time platform fees. Adobe's creative-cloud adjacency sustains design-centric demand in Australian media and marketing sectors.
- Compliance Training:ASEAN manufacturing certification mandates institutionalize subscription structures tied to recurring ISO audit requirements.
- Certification:BIS digital standards and TGA-equivalent frameworks require specialized curation distinct from generic LMS infrastructure.
- Social Learning:Collaborative features face adoption constraints in China's MIIT-regulated academic data environments.
Margin depth favors Courseware; regulatory anchoring favors Compliance Training.
Functionality:
Interoperability standards and AI integration potential differentiate feature investment priorities across vendor roadmaps.
- Tracking:xAPI implementation enables granular skills-based analytics for competency-tracking use cases in financial services, though Bengaluru and Sydney labor markets show acute shortage of certified integration specialists.
- Assessment:Natural language processing integration with adaptive learning engines automates competency validation, reducing instructor grading overhead in high-volume corporate environments.
- Reporting:Compliance audit trail generation represents table stakes for healthcare and financial services procurement in Australia and Singapore.
- Course Delivery:SCORM interoperability constraints limit content portability, requiring costly migration for advanced analytics requirements.
Technical differentiation clusters around Assessment; baseline procurement requires Reporting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Singapore and Australian corporate procurement functions, while Indian state colleges and Vietnamese industrial zones trade margin for volume scale. This asymmetry fragments vendor go-to-market economics across the region.
India
State college digitization and vocational upskaling programs drive procurement acceleration. BIS digital standards compliance compresses vendor qualification timelines. The Bengaluru-Hyderabad-Pune ed-tech corridor concentrates platform deployment for institutional and corporate buyers.
China
Public university cloud procurement and MIIT cybersecurity certification mandates reshape vendor eligibility. SAMR cross-border data transfer rules force architecture fragmentation for platforms serving mainland and Hong Kong institutions. Tier-one city districts favor domestic joint ventures over foreign direct deployment.
Australia
TGA-equivalent education quality frameworks and VET Fee-Help subsidy expansion redirect federal vocational spending toward micro-credential platforms. Queensland and New South Wales technical institutes drive specialized clinical training procurement. Sydney and Melbourne financial services firms generate fastest contract velocity for compliance audit trail solutions.
Vietnam
Automotive supply chain digital skill certification mandates institutionalize recurring training subscriptions. ISO quality management audit requirements tie LMS procurement to supplier qualification programs. Industrial zones around Hai Phong and Da Nang present first-mover deployment opportunities tied to Samsung and Foxconn certification.
Singapore
Financial services and pharmaceutical verticals negotiate unbundled component pricing separating platform access from analytics modules. Procurement functions mandate compliance audit trail generation as table stakes. The city-state's regional headquarters concentration drives premium-tier contract structures for multinational corporate training rollouts.
Asia-Pacific Learning Management Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, producing a tiered competitive structure. ERP-integrated enterprise suites and open-source institutional platforms occupy opposite ends of the pricing spectrum. Three archetypes dominate: hyperscaler-aligned cloud-native vendors, ERP-anchored workflow integrators, and community-driven open-source specialists. Competitive moves concentrate on sovereign cloud partnerships for data residency compliance and AI-generated assessment capabilities for automated competency validation.
Within the ERP-anchored tier, SAP SE represents enterprise workflow integration depth. Adobe Inc occupies creative-cloud adjacency positioning for design-centric training demand. Moodle Pty Ltd exemplifies open-source institutional deployment economics. These three anchors span the pricing spectrum from premium enterprise suites through specialized creative tools to cost-controlled academic platforms, with each archetype facing distinct compliance architecture requirements across Indian BIS standards, Australian TGA frameworks, and Chinese MIIT certifications.
| Leading Market Players |
|---|
| SAP SE |
| Adobe Inc |
| Blackboard Inc |
| Instructure Holdings Inc |
| Moodle Pty Ltd |
| Oracle Corporation |
| Cornerstone OnDemand |
| D2L Corporation |
| Anthology Inc |
| Others |
Value Network & Pricing Analysis
China's MIIT cybersecurity certification for cloud-hosted academic data gates both vendor qualification timelines and premium pricing tiers, compressing margins for foreign platforms while enabling domestic joint ventures to command configuration premiums. This regulatory architecture simultaneously constrains supply eligibility and segments buyer willingness-to-pay across mainland tier-one cities versus Hong Kong institutional networks.
Pricing Analysis
Configuration premiums for BIS-compliant sovereign cloud deployments in India stretch 40-60% above standard SaaS tiers, with hyperscaler partnership certification and data residency architecture driving differentiation. Singapore financial services and Australian healthcare verticals exhibit lowest price sensitivity due to non-negotiable audit trail requirements, while Indian state colleges and Vietnamese manufacturing suppliers trade margin for volume scale in procurement negotiations. Cost compression in mid-market ASEAN segments intensifies as Alibaba Cloud and Azure localize infrastructure, eroding egress cost advantages previously held by first-mover vendors.
Supply Chain Analysis
Hyperscaler concentration across AWS, Azure, and Alibaba Cloud creates a chokepoint exposing mid-market LMS vendors to service continuity dependencies and egress cost volatility. Software development labor pools concentrate in Bengaluru, Hyderabad, and Sydney, while xAPI-certified instructional design engineers remain acutely scarce in both markets. Single-source vulnerability in sovereign cloud partnerships intensifies as TRAI data-localization guidelines and SAMR cross-border rules fragment architecture choices. Distribution runs through direct enterprise sales teams in Singapore and Australia, channel partners in Indian state procurement, and OEM integrations with ERP vendors across ASEAN manufacturing hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Indian state education ministries and Australian federal vocational agencies, with procurement consolidation compressing vendor margins and favoring platforms with demonstrated compliance track records.
For Market Incumbents: Shield enterprise accounts through deeper ERP workflow integration, particularly SAP SE's human capital management anchoring and Adobe's creative-cloud training adjacency. Prioritize sovereign cloud partnership certification in India and China before procurement windows close, as BIS and MIIT compliance gates are hardening. Vertical integration into AI-generated assessment engines offers defensive differentiation against adaptive learning entrants. For New Entrants and Emerging Players: Lead with micro-credential platform specialization targeting Australian VET Fee-Help subsidy redirection and underpenetrated Vietnamese industrial zones around Hai Phong and Da Nang. Vietnam manufacturing upskaling tied to Samsung and Foxconn supplier certification presents the most penetrable white-space, with ISO audit-linked subscription models enabling recurring revenue capture without incumbent displacement costs. For Investors and Strategic Acquirers: India's National Education Policy implementation reshapes the acquisition landscape, compressing procurement cycles from 18 months to under 8 months and favoring platforms with pre-qualified BIS architectures. Long-term viability rests on compliance moats rather than feature differentiation, with xAPI technical talent scarcity and sovereign cloud partnerships as durable competitive anchors. Watch for MIIT cybersecurity certification timelines as the signal for mainland China market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | TRAI data-localization compliance in India enables procurement eligibility for multinational corporate buyers in Bengaluru. |
| AI Assessment Engine Development | NLP-powered competency validation reduces instructor overhead in Australian financial services compliance training environments. |
| xAPI Technical Talent Acquisition | Certified integration specialists in Sydney and Bengaluru labor markets unlock granular skills-based analytics for enterprise accounts. |
| Micro-Credential Platform Launch | Australian VET Fee-Help subsidy redirection opens subscription revenue for registered training organizations without campus infrastructure. |
| Vietnam Industrial Zone Penetration | Samsung and Foxconn supplier certification programs in Hai Phong and Da Nang institutionalize recurring training module subscriptions. |
Research Methodology
A spread of perspectives from chief learning officers at financial services firms, state college procurement directors in India, vocational institute administrators in Queensland and New South Wales, platform engineers at hyperscaler partners, and regulatory affairs leads converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against SEC filings, TRAI regulatory notices, BIS digital standards documentation, and Australian federal education subsidy disclosures. Bottom-up deployment modeling across cloud, SaaS, on-premise, and hybrid architectures triangulated against top-down education and corporate training budget forecasts.
Segmentation dimensions modeled span deployment mode, user type across corporate and educational institutions, content type from courseware through compliance training, and functionality tier from baseline reporting through AI-powered assessment. CAGRs were derived through adoption curve analysis across the projection horizon, with inputs including India's 15,000 state college digitization mandate procurement acceleration, ASEAN manufacturing ISO audit compliance institutionalization, and China's MIIT certification eligibility fragmentation between domestic joint ventures and foreign direct deployment.
The analysis sits within stated boundaries; outcomes outside sustained sovereign cloud partnership formation, xAPI technical talent pipeline development, or stable regulatory certification timelines would require recalibration. Practitioners should keep alternative scenarios live as BIS, MIIT, and TGA framework evolutions reshape vendor eligibility and buyer procurement authority across the region.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Learning Management Systems (LMS)
Global Mobile Learning Market
Learning Management Systems (LMS)
Global Corporate M-Learning Market
Learning Management Systems (LMS)
Smart Learning Systems Market
Learning Management Systems (LMS)
Global Learning Management Systems (LMS) Market
Learning Management Systems (LMS)
School Management System Market
Learning Management Systems (LMS)
Healthcare LMS Software Market
Learning Management Systems (LMS)
Global Training Software Market
Learning Management Systems (LMS)
Global Exam Management Software Market
Learning Management Systems (LMS)
Global Classroom Management Software Market
Learning Management Systems (LMS)
Corporate Learning Management System Market
Learning Management Systems (LMS)
E-Learning Solutions Market
Learning Management Systems (LMS)
Managed Learning Service Market
Learning Management Systems (LMS)
Qatar E-Learning Management System Market