
 Competency-Based Education Spending Market | 2026-2036
Competency-Based Education Spending Market Size, Share, and Industry Trends Forecast 2026-2036
Competency-Based Education Spending Market Analysis
Platform licensing revenue is reconfiguring margin pools away from traditional seat-time tuition toward subscription-based competency verification systems. Pearson plc leverages its established assessment infrastructure to dominate psychometric certification delivery across North American community college networks. D2L Corporation anchors its position through proprietary analytics engines that map learner proficiency against employer-defined skill taxonomies. Coursera Inc. competes by extending enterprise contracts that bundle competency verification with Fortune 500 talent pipeline guarantees.
Competency-based education spending encompasses institutional and consumer expenditures on outcomes-verified learning models where student advancement depends on demonstrated mastery rather than instructional hours, typically employing adaptive algorithms, psychometric item banks, and employer-validated rubrics to certify discrete capabilities. The delivery method dimension shows online learning capturing the fastest expansion as asynchronous assessment protocols reduce proctoring overhead, while blended learning sustains premium pricing through embedded face-to-face skills validation. Within technology utilization, learning management systems remain the mature infrastructure layer, whereas assessment platforms attract disproportionate R&D investment as vendors race to automate authentic performance evaluation.
The US Department of Education shapes market access through experimental site agreements that determine Title IV eligibility for direct assessment programs, while regional accreditors like the Higher Learning Commission enforce quality standards for competency definition and evidence requirements. State authorization reciprocity agreements further fragment market entry, forcing providers to navigate fifty distinct regulatory postures for online program delivery. Stakeholders must monitor pending revisions to the federal educational assistance framework, as any restriction on aid disbursement for non-term-based enrollment would immediately compress addressable demand across the vendor ecosystem.
Market Dynamics
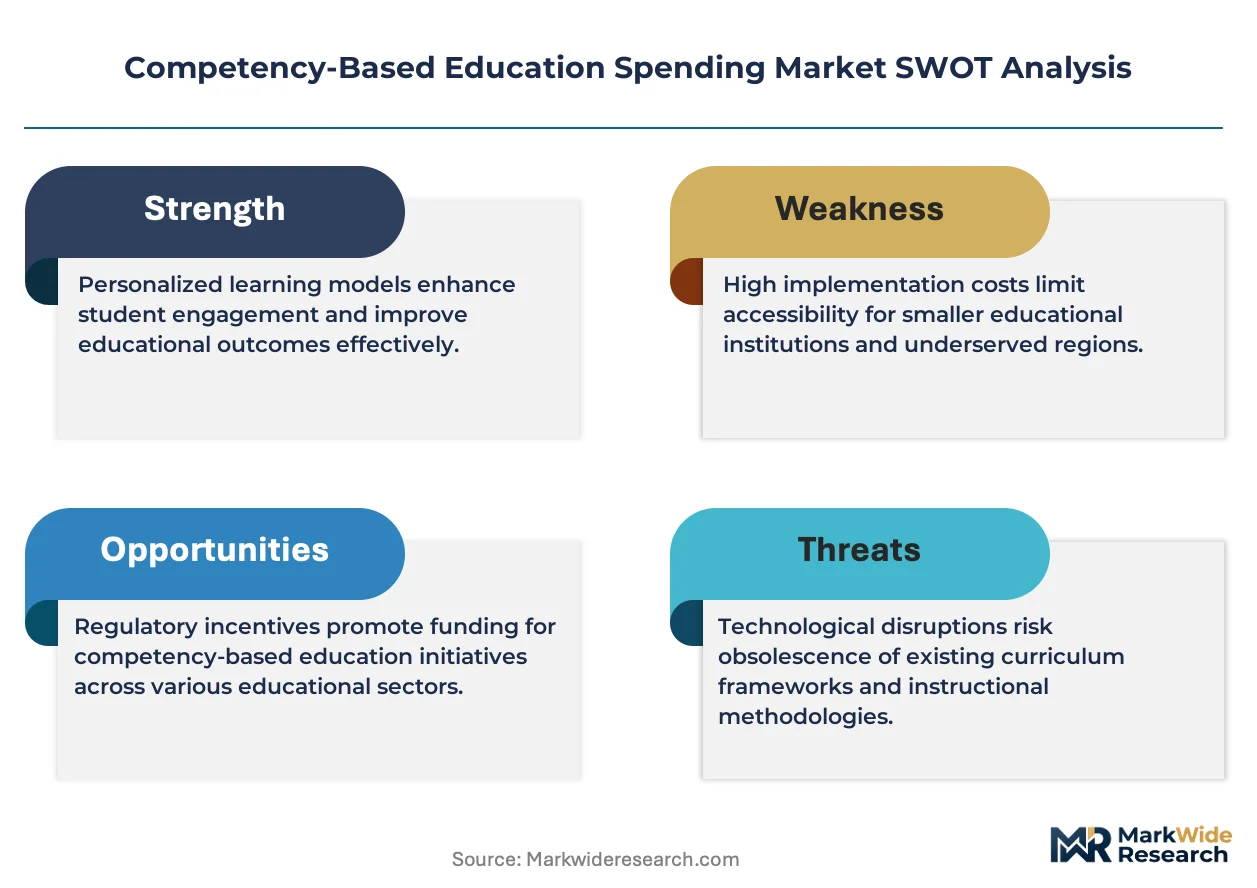
Federal financial aid eligibility for direct assessment programs is compressing enrollment timelines and forcing legacy institutions to restructure degree pathways around demonstrated mastery rather than seat-time accumulation.
Growth Catalysts
- US Department of Education Experimental Sites:Title IV eligibility expansion for non-credit-hour models removes the primary barrier to scale for competency-based programs.
- Fortune 500 Talent Pipelines:Manufacturing and technology employers now mandate verified skill credentials for advancement, creating institutional procurement pull.
- Psychometric Automation:Adaptive algorithms reduce assessment proctoring costs by enabling asynchronous, AI-proctored evaluation of authentic performance tasks.
Market Restraints
- Regional Accreditor Fragmentation:The Higher Learning Commission and peer bodies enforce divergent evidence requirements for competency definition, raising compliance overhead for multi-state providers.
- State Authorization Reciprocity Gaps:Fifty distinct regulatory postures for online program delivery force redundant administrative infrastructure.
- Legacy LMS Technical Debt:Seat-time-based student information systems resist integration with mastery-tracking analytics engines.
Strategic Opportunities
- US Community College Networks:Underpenetrated two-year institutions seek turnkey competency verification platforms to replace developmental education sequences.
- Employer-Defined Skill Taxonomies:Convergence of learning analytics with human capital management systems enables real-time credential alignment to labor market demand.
- Asynchronous Assessment Protocols:Proctoring overhead reduction opens subscription pricing models previously uneconomical at small enrollment scale.
Industry Challenges
- Instructional Designer Scarcity:Competency rubric development and authentic assessment creation require specialized psychometric expertise absent in traditional faculty pipelines.
- Federal Aid Framework Uncertainty:Pending restrictions on non-term-based enrollment eligibility would compress addressable demand across the vendor ecosystem.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Competency-Based Education Spending Market |
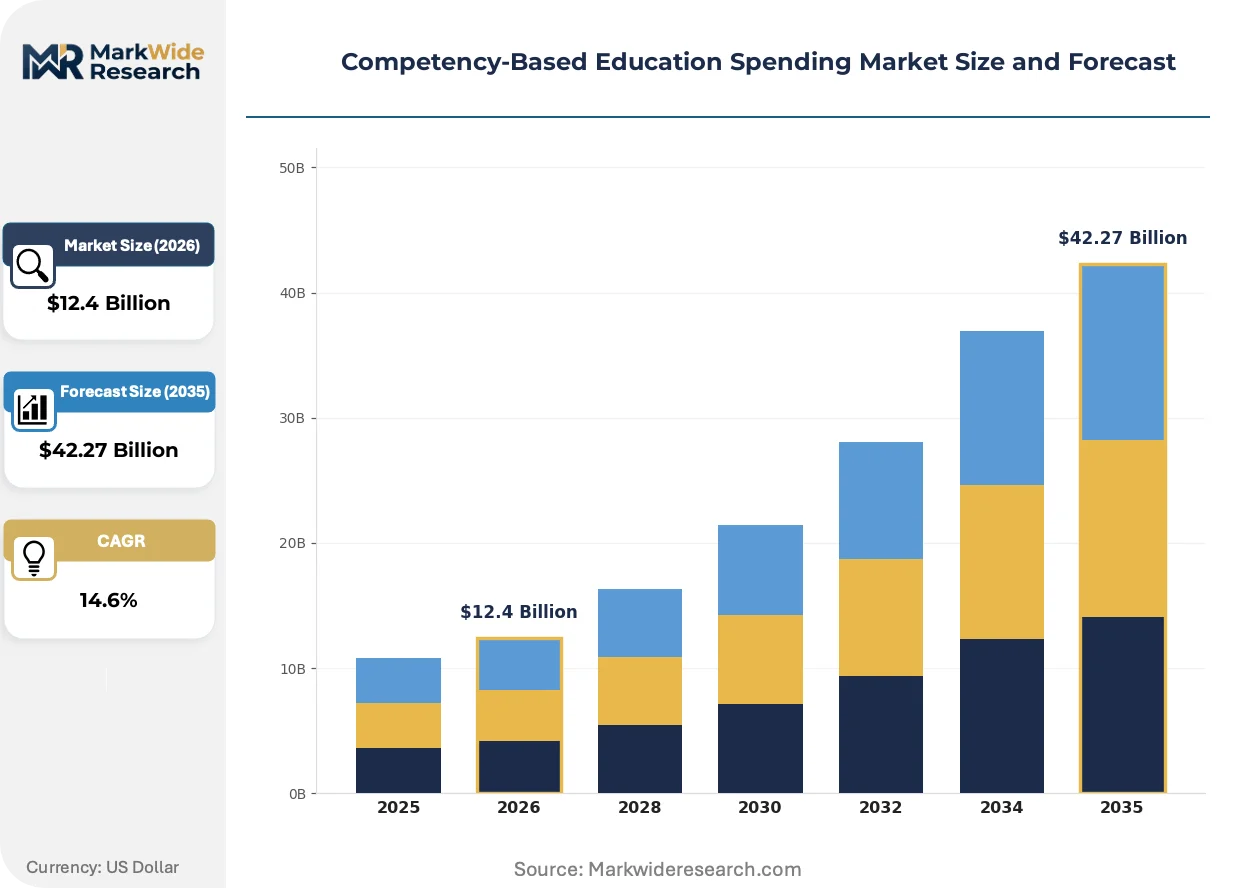
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $42.27 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Funding Source: Government Grants, Institutional Funding, Private Investments, Tuition Fees Delivery Method: Online Learning, Blended Learning, Face-to-Face Instruction, Self-Paced Courses Target Audience: Adult Learners, College Students, Corporate Employees, Educators Technology Utilization: Learning Management Systems, Analytics Tools, Virtual Classrooms, Assessment Platforms |
| Companies Covered | D2L Corporation, Instructure Holdings Inc., Blackboard Inc., Pearson plc, Coursera Inc., Western Governors University, Southern New Hampshire University, Udacity Inc., Ellucian, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Competency-Based Education Spending Market Emerging Trajectories
Assessment infrastructure is fragmenting from monolithic learning management systems toward specialized competency verification stacks that embed directly into employer talent workflows.
AI-proctored performance evaluation is hybridizing authentic skills demonstration with scalable delivery. These systems capture video evidence of hands-on tasks for remote review by employer-validated assessors. Community college workforce divisions are adopting fastest where nursing and manufacturing labs require practical verification. The technology is hybridizing previously incompatible goals of academic integrity and workforce relevance into unified credentialing workflows.
The US Department of Education's experimental sites initiative for direct assessment programs is reshaping federal aid disbursement mechanics. Title IV eligibility now attaches to demonstrated learning rather than instructional hours enrolled. Direct assessment programs at Western Governors University and Southern New Hampshire University are most affected, having built scalable infrastructure now eligible for expansion capital.
Employer consortium purchasing is consolidating procurement authority for competency verification. Manufacturing sector employers in the US Midwest now contract directly with platform vendors for credential guarantees rather than routing through individual institutional procurement offices. This shift is most visible in automotive and aerospace supply chains where skill standardization across suppliers reduces training redundancy.
Competency-Based Education Spending Market Segmentation
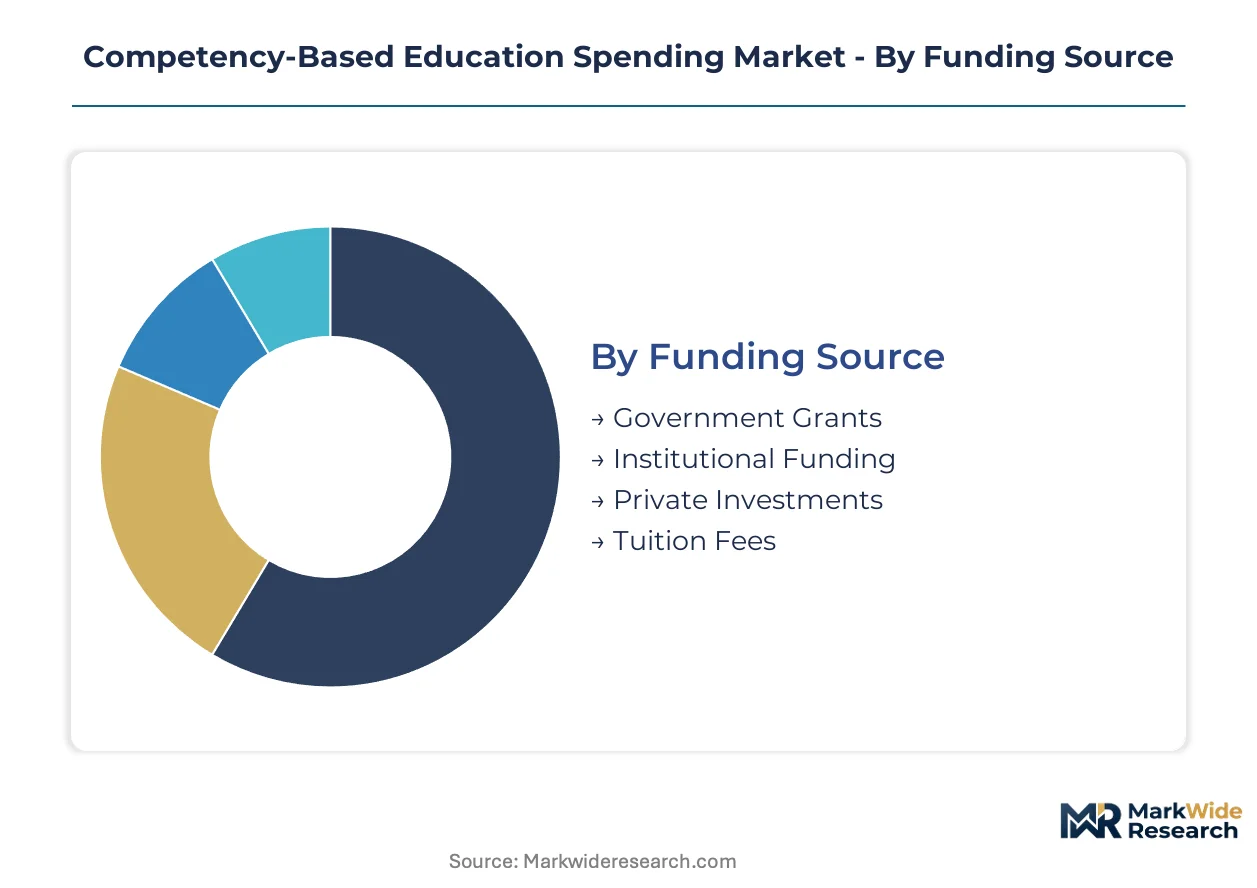
Competency-based education spending fragments across four intersecting dimensions that determine procurement authority, delivery infrastructure, and technology stack requirements. Each segmentation axis reveals distinct margin structures and vendor positioning strategies.
Funding Source:
Government grants concentrate procurement decisions at federal and state education agencies, while tuition-driven models empower individual learner choice.
- Government Grants:Federal experimental sites funding through the US Department of Education removes credit-hour constraints for direct assessment programs. State workforce development boards in the US Midwest channel Title IV disbursements toward manufacturing credential pathways.
- Institutional Funding:University operating budgets reallocate from seat-time instruction toward competency verification infrastructure. Community college networks prioritize turnkey platform licensing over custom development.
- Private Investments:Venture capital flows toward assessment automation vendors with employer-validated rubrics.
- Tuition Fees:Self-paying adult learners drive subscription pricing models for asynchronous credential programs.
Established volume favors institutional funding; emerging adoption favors government grants.
Delivery Method:
Cost tier structures separate premium face-to-face validation from scalable online delivery.
- Online Learning:Asynchronous assessment protocols eliminate proctoring overhead and enable AI-proctored performance evaluation. Western Governors University and Southern New Hampshire University anchor scalable infrastructure for direct assessment at volume.
- Blended Learning:Embedded face-to-face skills validation sustains premium pricing through hands-on lab verification. Nursing and manufacturing programs at US community colleges adopt hybrid formats fastest where practical demonstration is mandatory.
- Face-to-Face Instruction:Traditional seat-time models resist restructuring around demonstrated mastery.
- Self-Paced Courses:Fortune 500 manufacturers mandate self-paced credential programs for internal advancement pathways.
Scale economics favor online learning; skills fidelity favors blended learning.
Target Audience:
Customer type determines rubric complexity and employer integration depth.
- Adult Learners:Working professionals require credential portability across employer boundaries. Prior learning assessment credits reduce time-to-completion for non-traditional students.
- Corporate Employees:Talent pipeline guarantees from Fortune 500 manufacturers create institutional procurement pull for verified skill credentials.
- College Students:Traditional-age learners transition from credit-hour accumulation toward mastery-based advancement.
- Educators:Faculty development programs demand psychometric training for competency rubric design.
Procurement authority favors corporate employees; volume concentration favors adult learners.
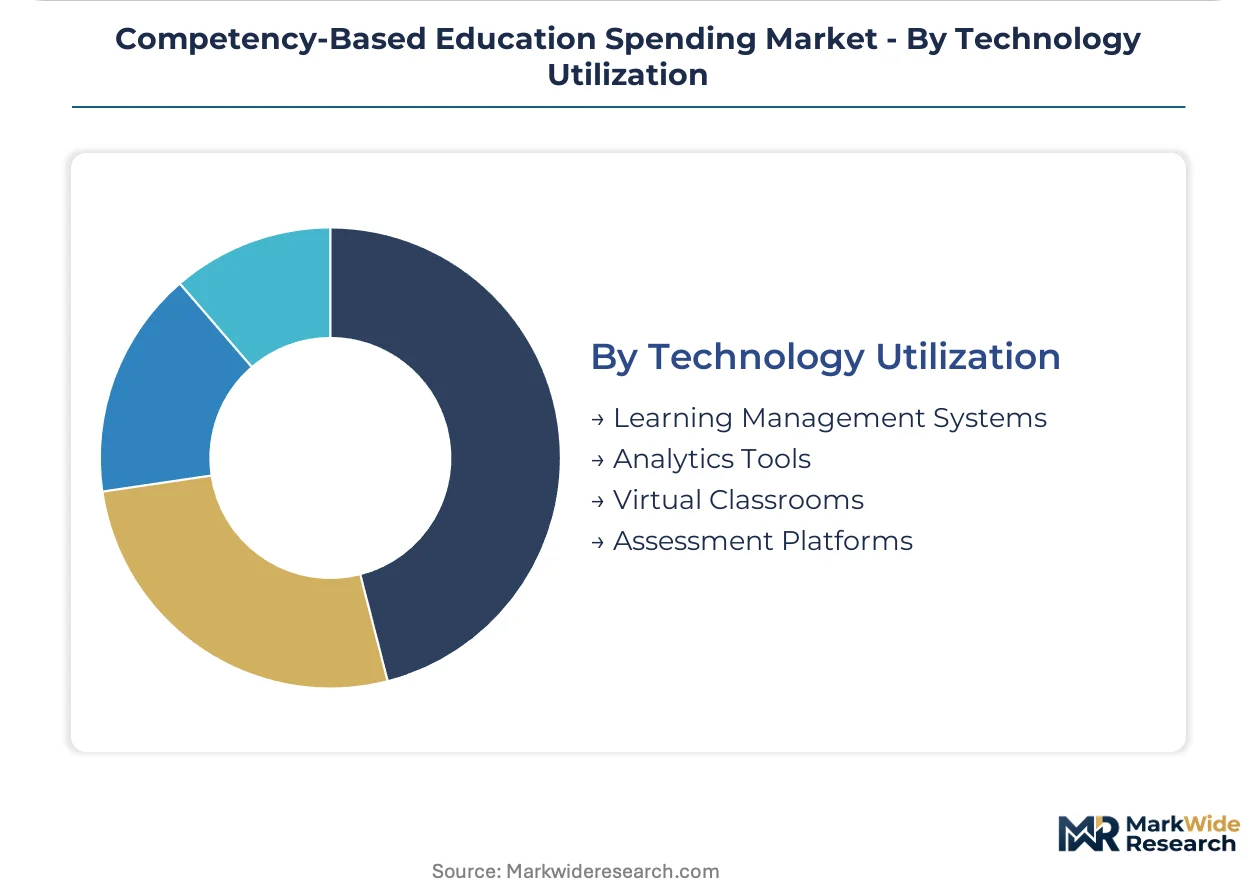
Technology Utilization:
Supply concentration clusters around assessment automation versus legacy learning management infrastructure.
- Assessment Platforms:Psychometric item banks and adaptive algorithms attract disproportionate R&D investment as vendors automate authentic performance evaluation. Analytics engines map learner proficiency against employer-defined skill taxonomies.
- Learning Management Systems:Mature infrastructure layer resists integration with mastery-tracking engines due to seat-time technical debt.
- Analytics Tools:Proprietary proficiency mapping enables real-time credential alignment to labor market demand.
- Virtual Classrooms:Synchronous delivery protocols retain niche positioning for high-stakes skills demonstration.
Investment intensity favors assessment platforms; installed base favors learning management systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys competency-based education primarily through direct assessment degree programs, while other markets emphasize employer-validated microcredentials and corporate training procurement. Federal financial aid eligibility for non-credit-hour models accelerates institutional adoption uniquely in the US. Corporate training budgets in Germany and Japan drive alternative funding flows for skills verification platforms.
United States
Western Governors University and Southern New Hampshire University anchor scalable infrastructure for direct assessment at volume, enrolling hundreds of thousands of students in self-paced credential programs. The US Department of Education's experimental sites initiative removes Title IV eligibility barriers for non-term-based enrollment, channeling federal aid toward demonstrated mastery models. Manufacturing employers in the Midwest now contract directly with platform vendors for skill standardization across automotive and aerospace supply chains.
Germany
Dual vocational training systems integrate competency verification into federal employment frameworks, with manufacturing employers mandating verified credentials for advancement pathways. The Federal Institute for Vocational Education and Training (BIBB) accredits competency rubrics aligned to national qualification frameworks. Industrial clusters in Bavaria and Baden-Württemberg deploy assessment platforms for precision manufacturing and automation skills validation.
United Kingdom
Degree apprenticeship programs drive employer procurement of competency verification systems, with levy-funded training reshaping institutional-provider relationships. The Office for Students monitors quality standards for alternative provider programs, including non-traditional assessment models. London-based edtech vendors and university extension programs concentrate delivery infrastructure for professional credentialing.
Canada
Provincial workforce development boards channel public funding toward competency-based microcredentials for displaced workers and career transitioners. Employment and Social Development Canada supports pilot programs linking prior learning assessment to portable credential frameworks. Ontario and British Columbia community college networks expand adoption of turnkey assessment platforms for nursing and technology workforce pipelines.
Australia
The Australian Skills Quality Authority regulates competency-based training packages within the vocational education and training sector, embedding employer-defined skill standards into national qualifications. State training authorities in New South Wales and Victoria procure assessment platforms for apprenticeships and traineeships. Mining and healthcare employers in Western Australia drive demand for practical skills verification through remote delivery protocols.
Competency-Based Education Spending Market Vendor Landscape
Capability concentration sits with specialized assessment platform vendors; scale advantage sits with established learning management incumbents with installed base penetration. The market structures around three tiers: psychometric certification specialists, enterprise analytics platform providers, and legacy institutional software vendors. Strategic moves center on assessment automation R&D investment and employer consortium partnership formation to secure talent pipeline guarantees.
Within the assessment-specialist tier, Pearson plc exemplifies psychometric infrastructure dominance through established certification delivery networks. D2L Corporation and Coursera Inc. occupy positions bridging enterprise analytics with direct-to-employer contract structures. These three anchors represent divergent competitive vectors: established assessment heritage, proprietary proficiency-mapping engines, and bundled talent-pipeline guarantees respectively.
| Leading Market Players |
|---|
| D2L Corporation |
| Instructure Holdings Inc. |
| Blackboard Inc. |
| Pearson plc |
| Coursera Inc. |
| Western Governors University |
| Southern New Hampshire University |
| Udacity Inc. |
| Ellucian |
| Others |
Supply Flow & Price Mechanics
Salt Lake City anchors the most concentrated assessment platform development cluster, where Western Governors University and adjacent edtech infrastructure providers shape downstream pricing power through scalable direct assessment delivery. Capacity expansion in this hub feeds subscription pricing models that undercut traditional seat-time tuition across North American community college networks.
Pricing Analysis
Long-term enterprise licensing contracts dominate procurement, with Fortune 500 manufacturers negotiating multi-year platform subscriptions that bundle competency verification with talent pipeline guarantees. Price differentiation stems from psychometric certification tier and embedded analytics depth, with premium tiers commanding higher fees for employer-validated rubric customization. Cost compression in mid-market institutional segments is intensifying because community college networks demand turnkey solutions at scale. Self-paying adult learners exhibit highest price sensitivity, while corporate training departments prioritize credential portability over unit cost.
Supply Chain Analysis
Psychometric item bank development draws from specialized content providers concentrated in the United States, the United Kingdom, and Australia, where regulatory familiarity with federal qualification frameworks creates competitive moats. Raw material inputs include adaptive algorithm licensing, cloud compute infrastructure, and employer skill taxonomy databases. Single-source vulnerability sits with proprietary analytics engines that resist interoperability with legacy student information systems. Distribution runs through direct institutional sales teams for large university contracts and channel partnerships for community college network penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competency-based education vendors face acute instructional designer scarcity, with psychometric expertise for authentic assessment creation outstripping traditional faculty pipeline output. This capability gap constrains rubric development velocity and limits program launch timelines across the vendor ecosystem.
For Market Incumbents: Build assessment automation moats through AI-proctored performance evaluation R&D that hybridizes academic integrity with workforce relevance. Invest in employer consortium partnerships to secure talent pipeline guarantees that lock out competing platforms. Address the threat from specialized assessment startups by acquiring psychometric certification specialists with established community college network penetration.
For New Entrants and Emerging Players: Pursue underpenetrated US community college workforce divisions where nursing and manufacturing labs require practical verification infrastructure. Target two-year institutions in the Midwest automotive and aerospace supply chain corridors seeking turnkey competency verification platforms. Lead with asynchronous assessment protocols that eliminate proctoring overhead and enable subscription pricing previously uneconomical at small enrollment scale.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-dependent infrastructure play because Title IV eligibility expansion for direct assessment programs determines addressable market size. Prioritize assessment platform vendors with experimental site agreements and employer-validated rubric libraries. Watch federal educational assistance framework revisions as the critical inflection signal, as restrictions on non-term-based enrollment eligibility would compress demand across the vendor ecosystem.
| Strategic Initiative | Industry Significance |
|---|---|
| Assessment Platform Integration | Embedding competency verification directly into Fortune 500 human capital management systems creates sticky enterprise relationships. |
| Employer Consortium Partnership | Manufacturing sector purchasing consolidation in the US Midwest reduces customer acquisition costs through multi-employer contracts. |
| Psychometric Automation Investment | AI-proctored performance evaluation reduces assessment delivery costs while maintaining academic integrity standards for federal aid eligibility. |
| Community College Network Expansion | Turnkey platform licensing to underpenetrated two-year institutions replaces developmental education sequences with verified credential pathways. |
| Regulatory Compliance Certification | Higher Learning Commission accreditation for competency definition and evidence requirements secures Title IV disbursement eligibility. |
Methodological Framework
Operator-level perspectives from chief learning officers, institutional procurement directors, assessment platform product managers, and workforce development board executives anchored the qualitative base for this analysis. Primary interviews with these stakeholders combined with secondary validation from US Department of Education experimental site filings, regional accreditor standards documentation, and employer skill taxonomy publications. Bottom-up enrollment data triangulated against top-down federal financial aid disbursement patterns to establish market sizing boundaries.
Scenario-bracketing around Title IV policy trajectories shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include funding source, delivery method, target audience, and technology utilization, with particular attention to direct assessment program scale economics and employer consortium procurement patterns. CAGRs derived from enrollment velocity projections and platform licensing revenue trajectories, incorporating psychometric automation cost curves and community college network adoption rates as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in federal education funding levels and workforce development appropriations would shift the trajectory materially. Forecasts reflect assumptions about experimental site agreement expansion and employer credential mandate adoption that remain subject to policy and labor market evolution. Cross-checking against US Department of Education disbursement data and Bureau of Labor Statistics credential demand indicators is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Corporate Training and Talent Development
Canada Outplacement Services Market
Corporate Training and Talent Development
Educational Consulting and Training Market
Corporate Training and Talent Development
Global Sales Training Market
Corporate Training and Talent Development
Corporate Workforce Development Training Market
Corporate Training and Talent Development
Private Tutoring Market
Corporate Training and Talent Development
Middle East and Africa Management Consulting Services Market
Corporate Training and Talent Development
Corporate Training Market
Corporate Training and Talent Development
Corporate Training Services Market
Corporate Training and Talent Development
Europe Consulting Services Market
Corporate Training and Talent Development
Asia-Pacific Management Consulting Services Market
Corporate Training and Talent Development
IT Training Market
Corporate Training and Talent Development
Asia Pacific HR Professional Services Market
Corporate Training and Talent Development
Corporate Leadership Training Market
Corporate Training and Talent Development
Corporate eLearning Market
Corporate Training and Talent Development
Executive Coaching Certification Market
Corporate Training and Talent Development
Corporate Training Software Market